
Market Overview:
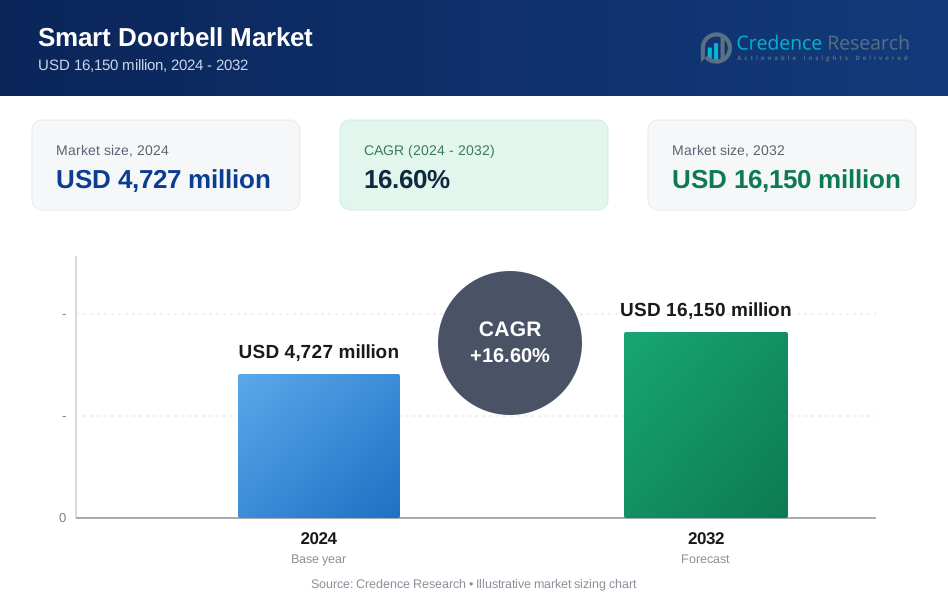
The Smart Doorbell Market size was valued at USD 4727 million in 2024 and is anticipated to reach USD 16150 million by 2032, at a CAGR of 16.6% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Smart Doorbell Market Size 2024 | USD 4727 million |
| Smart Doorbell Market, CAGR | 16.6% |
| Smart Doorbell Market Size 2032 | USD 16150 million |
Several key drivers are contributing to the expansion of the smart doorbell market. The primary factor is the rising need for advanced security systems, as homeowners and businesses seek reliable solutions to monitor and manage visitor access remotely. Additionally, the proliferation of IoT-enabled devices and smart home systems is enhancing the functionality and appeal of smart doorbells, enabling features such as video streaming, two-way communication, and motion detection. Furthermore, the growing trend of integrating artificial intelligence (AI) for facial recognition and voice assistant compatibility is adding value to smart doorbells, increasing their adoption in various applications.
Regionally, North America holds a dominant share of the smart doorbell market, primarily driven by the high rate of smart home adoption in the United States and Canada. The region's well-established infrastructure for connected home devices, coupled with rising consumer awareness of home security, has led to substantial market penetration. Europe follows closely, with increasing investments in smart security solutions. Meanwhile, the Asia Pacific region is expected to witness the highest growth rate due to rising disposable income, expanding urbanization, and the growing demand for advanced home automation systems in emerging markets such as China and India.
Market Insights:
- The Smart Doorbell Market is projected to grow from USD 4,727 million in 2024 to USD 16,150 million by 2032, at a CAGR of 16.6%.
- Key drivers of growth include the rising need for advanced security systems and the increasing adoption of IoT-enabled devices in smart homes.
- Smart doorbells offer features like video streaming, motion detection, and real-time alerts, enhancing security and convenience for homeowners and businesses.
- AI-powered capabilities, such as facial recognition and voice assistant compatibility, are adding significant value to smart doorbells, increasing their market adoption.
- North America holds the largest market share (38%) due to high smart home adoption rates and strong consumer demand for advanced security solutions.
- Europe follows closely, accounting for 29% of the market, with increasing investments in smart security technologies and growing safety concerns.
- Asia Pacific is expected to experience the highest growth, driven by urbanization, rising disposable incomes, and increasing awareness of smart home technologies.
Market Drivers:
Growing Consumer Demand for Enhanced Home Security Solutions
The increasing concerns about home security and safety are major factors driving the Smart Doorbell Market. Homeowners are seeking more reliable and advanced solutions to monitor their properties and interact with visitors remotely. Traditional doorbell systems no longer meet the evolving security needs, prompting a shift towards smart doorbells that offer features such as video streaming, motion detection, and real-time alerts. The ability to monitor a property from anywhere via a smartphone or tablet enhances convenience and peace of mind, making these devices a highly preferred option.
- For instance, Speco Technologies’ video doorbell enables remote live video access and real-time communication through its dedicated app, supporting both Wi-Fi and Power over Ethernet (PoE) connectivity for consistent and reliable service.
Advancements in Smart Home Ecosystems and IoT Integration
Smart doorbells are becoming essential components of broader smart home ecosystems, fueled by the rapid growth of Internet of Things (IoT) technologies. These devices integrate seamlessly with other smart home products like security cameras, lights, and voice assistants, creating an interconnected network that offers enhanced control and automation. The continuous development of IoT solutions is improving the functionality of smart doorbells, enabling more sophisticated features such as voice recognition and automated actions, which, in turn, drive market adoption.
Technological Innovations in Smart Doorbell Features
The Smart Doorbell Market is benefiting from ongoing innovations in product features and capabilities. The introduction of AI-powered features like facial recognition, advanced motion detection, and voice assistants are increasing the appeal of these devices. These technologies improve user experience by providing higher levels of convenience and security. By integrating artificial intelligence, smart doorbells are becoming smarter, offering users the ability to distinguish between familiar visitors and potential threats, thus enhancing security and automation.
- For instance, the Google Nest Hello is equipped with advanced AI, enabling accurate facial recognition and package detection; it delivers familiar face alerts and distinguishes people, packages, and general motion through its neural network-based detection, with a 160° field of view and 24/7 video recording (1600 x 1200 HD resolution).
Growing Popularity of Remote Monitoring and Communication Capabilities
The demand for remote monitoring and two-way communication has contributed significantly to the growth of the Smart Doorbell Market. Homeowners value the ability to see and communicate with visitors in real-time, even when they are away. This feature is particularly appealing to people who frequently travel or work remotely. Smart doorbells allow users to interact with delivery personnel, guests, or service providers without being physically present, improving both convenience and security.
Market Trends:
Increasing Integration of Artificial Intelligence and Advanced Technologies
The Smart Doorbell Market is experiencing a trend towards integrating artificial intelligence (AI) and machine learning to enhance the functionality of these devices. AI-powered features, such as facial recognition and voice identification, are becoming standard offerings. These technologies allow smart doorbells to recognize familiar faces and distinguish between potential threats and regular visitors, improving security. By using machine learning algorithms, these devices can continuously improve their performance, such as reducing false alerts and adapting to changes in the environment. The growing reliance on AI not only elevates the user experience but also positions smart doorbells as an essential tool for modern home security.
- For instance, the Ring Video Doorbell Pro 2 features a 150-degree horizontal and 150-degree vertical field of view for its 1536p HD+ camera, allowing users to see visitors from head to toe and enabling precise 3D motion detection using radar technology.
Expansion of Subscription-Based Services and Cloud Storage Solutions
A noticeable trend in the Smart Doorbell Market is the increasing adoption of subscription-based services, particularly for cloud storage. Many smart doorbells offer cloud storage options that allow users to store video footage and receive access to historical data. This trend provides customers with more flexibility and security, as they can review video footage remotely at any time. Subscription models also allow manufacturers to offer additional services such as enhanced video quality, longer storage durations, and advanced analytics. This shift toward cloud-based storage solutions is making smart doorbells more accessible and attractive, especially for consumers seeking seamless integration and enhanced features.
- For instance, Ring offers up to 180 days of video event history for its cloud storage subscribers, providing extended access and review capability for recorded footage.
Market Challenges Analysis:
Privacy and Data Security Concerns
One of the primary challenges facing the Smart Doorbell Market is the growing concern about privacy and data security. With smart doorbells continuously capturing video footage and transmitting it to the cloud, there are potential risks related to unauthorized access to sensitive information. Hackers targeting connected devices can pose a threat to user privacy, as stored footage or personal data could be compromised. These concerns have led to increasing scrutiny and regulations surrounding data protection. Manufacturers need to prioritize strong encryption and secure data handling practices to mitigate these risks and maintain consumer trust.
High Installation and Maintenance Costs
Another challenge for the Smart Doorbell Market is the relatively high cost of installation and maintenance. While the devices themselves have become more affordable, the installation process can be complex, especially in homes lacking existing infrastructure for smart devices. Professional installation services, required for optimal performance, add to the overall cost. Ongoing maintenance, software updates, and subscription fees for cloud storage further contribute to the long-term expenses. These factors may discourage some consumers from adopting smart doorbells, particularly in price-sensitive markets or for individuals who are less familiar with technology.
Market Opportunities:
Expansion in Emerging Markets and Urbanization
The Smart Doorbell Market holds significant opportunities for growth in emerging markets, driven by increasing urbanization and rising disposable incomes. As cities expand and new residential areas are developed, the demand for advanced security systems is rising. Homeowners in these regions are becoming more aware of the benefits of smart home technologies, including enhanced security and convenience. With a growing middle class and improved access to technology, these markets present untapped potential for smart doorbell adoption. Manufacturers can leverage this opportunity by offering cost-effective, easy-to-install solutions that cater to the specific needs of emerging markets.
Integration with Broader Smart Home Ecosystems
Another major opportunity lies in the further integration of smart doorbells with broader smart home ecosystems. As consumers increasingly adopt interconnected smart home devices, there is a growing demand for products that offer seamless compatibility with other devices like security cameras, locks, and lighting systems. The Smart Doorbell Market can benefit from this trend by expanding its product offerings to include enhanced compatibility with various smart home platforms. By providing consumers with a unified, easy-to-manage system, manufacturers can increase the appeal and adoption of smart doorbells across diverse market segments.
Market Segmentation Analysis:
By Product Type
The Smart Doorbell Market is segmented by product type into wired and wireless categories. Wireless smart doorbells dominate the market due to their easy installation and convenience. They are increasingly preferred by consumers who seek hassle-free setup and greater flexibility in device placement. Wired smart doorbells, while offering a more stable connection, are less popular due to their complex installation requirements. However, they are still favored in some residential and commercial settings where consistent performance is critical.
- For instance, the Arlo Essential Wireless Video Doorbell features a 180-degree diagonal field of view and operates wire-free with a rechargeable battery that lasts up to 4 months.
By End-User
The Smart Doorbell Market is segmented by end-user into residential, commercial, and industrial sectors. The residential segment holds the largest market share, driven by growing demand for enhanced security in homes. Consumers are increasingly adopting smart doorbells for improved safety and convenience. The commercial sector follows closely, with businesses installing smart doorbells for better monitoring and access control. The industrial sector, though smaller in comparison, is gradually growing as more industrial sites integrate security systems to protect valuable assets.
By Distribution Channel
The Smart Doorbell Market is divided into online and offline distribution channels. Online channels are experiencing rapid growth, driven by the increasing preference for e-commerce and the convenience of direct-to-consumer sales. Consumers appreciate the ability to compare products, read reviews, and benefit from home delivery. Offline channels, including retail stores and specialized distributors, remain significant but are slowly losing ground to online platforms. This shift reflects broader consumer behavior trends favoring online shopping and greater access to information.
- For instance, in December 2020, Amazon sold over 400,000 Ring smart doorbell devices and accessories to homeowners worldwide through its online platform, showcasing the power of e-commerce in this market.
Segmentations:
By Product Type- Wired
- Wireless
- Residential
- Commercial
- Industrial
- Online
- Offline
- US.
- Canada
- Mexico
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Brazil
- Argentina
- Rest of Latin America
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America: Leading Market Share and Technological Advancements
North America holds 38% of the global Smart Doorbell Market share, driven by the high adoption rate of smart home technologies in the United States and Canada. The region’s demand for advanced security solutions has positioned smart doorbells as a critical element of connected home ecosystems. With features such as AI-powered facial recognition and seamless integration with other IoT devices, the popularity of these devices continues to rise. The presence of major manufacturers in North America promotes continuous innovation, boosting market growth through product advancements and extensive marketing.
Europe: Steady Growth in Demand for Security Solutions
Europe accounts for 29% of the Smart Doorbell Market share, with significant growth driven by increasing concerns over safety and the rising demand for home security solutions. Countries like the UK, Germany, and France are seeing rising adoption rates as consumers integrate smart doorbells into their home automation systems. The region's well-developed infrastructure for connected devices enhances market growth, as consumers increasingly seek secure, reliable smart home technologies. Regulations focused on digital security further stimulate demand, making smart doorbells a preferred option in the European market.
Asia Pacific: Rapid Growth and Expanding Market Potential
Asia Pacific represents 23% of the global Smart Doorbell Market share, and the region is expected to witness the highest growth rate during the forecast period. Urbanization, rising disposable incomes, and growing awareness of smart home technologies are driving demand in countries such as China, India, and Japan. The expanding middle class and urban population play a pivotal role in market expansion. As demand for advanced security features rises, local manufacturers are introducing cost-effective solutions to meet the needs of a diverse and rapidly growing market.
Key Player Analysis:
- Smart wares Group
- Arlo Technologies Inc.
- Ring Inc.
- Eques Inc.
- iseeBell Inc.
- Vivint, Inc.
- August Home Inc.
- Intelligent Technology Co. Ltd.
- Sky Bell Technologies Inc.
- Aeotec Technology (Shenzhen) Co. Ltd.
Competitive Analysis:
The Smart Doorbell Market is highly competitive, with key players focusing on innovation and product differentiation to maintain their market positions. Major companies like Ring (Amazon), Nest (Google), and Arlo Technologies lead the market, leveraging advanced features such as AI-based facial recognition, video streaming, and integration with other smart home devices. These players invest heavily in research and development to enhance user experience and provide more secure, user-friendly products. Smaller companies also contribute to the market, often targeting niche segments with affordable or specialized solutions. Competitive strategies include aggressive marketing, partnerships with home security providers, and expanding product offerings. The presence of new entrants with advanced technological features is increasing competition, driving down prices while simultaneously elevating the overall quality of devices in the market. The focus on seamless integration with existing home automation systems is another critical factor in differentiating products in this highly dynamic market.
Recent Developments:
- In January 2025, Ring and Kidde announced the launch of Smart Smoke and Combination Smoke & CO Alarms at CES 2025.
- In June 2025, SkyBell Technologies entered a definitive agreement to be acquired by Klotho Neurosciences, Inc., with Klotho issuing shares representing 90% of its post-deal common stock to SkyBell.
- In October 2024, August Home Inc. partnered with Yale and ecobee to integrate their smart locks with the ecobee Smart Security service, creating a seamless security and home automation platform for U.S. and Canadian consumers.
Market Concentration & Characteristics:
The Smart Doorbell Market exhibits moderate concentration, with a few dominant players such as Ring, Nest, and Arlo Technologies leading the industry. These companies command a significant share of the market due to their brand recognition, advanced features, and strong distribution networks. Smaller players and new entrants are also present, offering affordable alternatives or specialized products, but they face challenges in competing with the technological advancements of larger firms. The market is characterized by rapid innovation, with an emphasis on integrating AI, IoT, and cloud-based solutions. As consumer demand for security and convenience grows, companies are focusing on developing seamless, user-friendly products that can easily integrate with broader smart home ecosystems. Competitive dynamics are shaped by continuous product improvement, pricing strategies, and partnerships with other smart home device manufacturers.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, End-User, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Integration of AI-powered features such as facial recognition and motion detection to enhance security.
- Adoption of cloud-based storage solutions for seamless video access and data management.
- Expansion of wireless models, offering easier installation and flexibility for homeowners.
- Development of energy-efficient devices with longer battery life and lower power consumption.
- Incorporation of voice assistant compatibility, allowing hands-free control and integration with other smart home devices.
- Focus on user-friendly mobile applications for remote monitoring and management.
- Customization options for users to personalize settings and notifications according to their preferences.
- Enhanced privacy features, including encrypted data transmission and secure user authentication.
- Collaboration with home security systems to provide comprehensive protection solutions.
- Expansion into emerging markets, driven by increasing urbanization and demand for smart home technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Smart Doorbell Market?
What factors are driving the growth of the Smart Doorbell Market?
What are the key segments within the Smart Doorbell Market?
What are some challenges faced by the Smart Doorbell Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Smart Doorbell Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Smart Doorbell Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 4,727 million → 2032: USD 16,150 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Smart Doorbell Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Smart Doorbell Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Smart Doorbell Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Smart Doorbell Market Drivers
- 3.3 Smart Doorbell Market Restraints & Challenges
- 3.4 Smart Doorbell Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Smart Doorbell Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Smart Doorbell Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Smart Doorbell category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Smart Doorbell Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Smart Doorbell Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Smart Doorbell market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Smart Doorbell Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Smart Doorbell Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Smart Doorbell Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Smart Doorbell (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Smart Doorbell Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Smart Doorbell Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Smart Doorbell Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Smart Doorbell Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Smart Doorbell Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Smart Doorbell Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Smart Doorbell Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Smart Doorbell Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Smart Doorbell Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
