
Market Overview
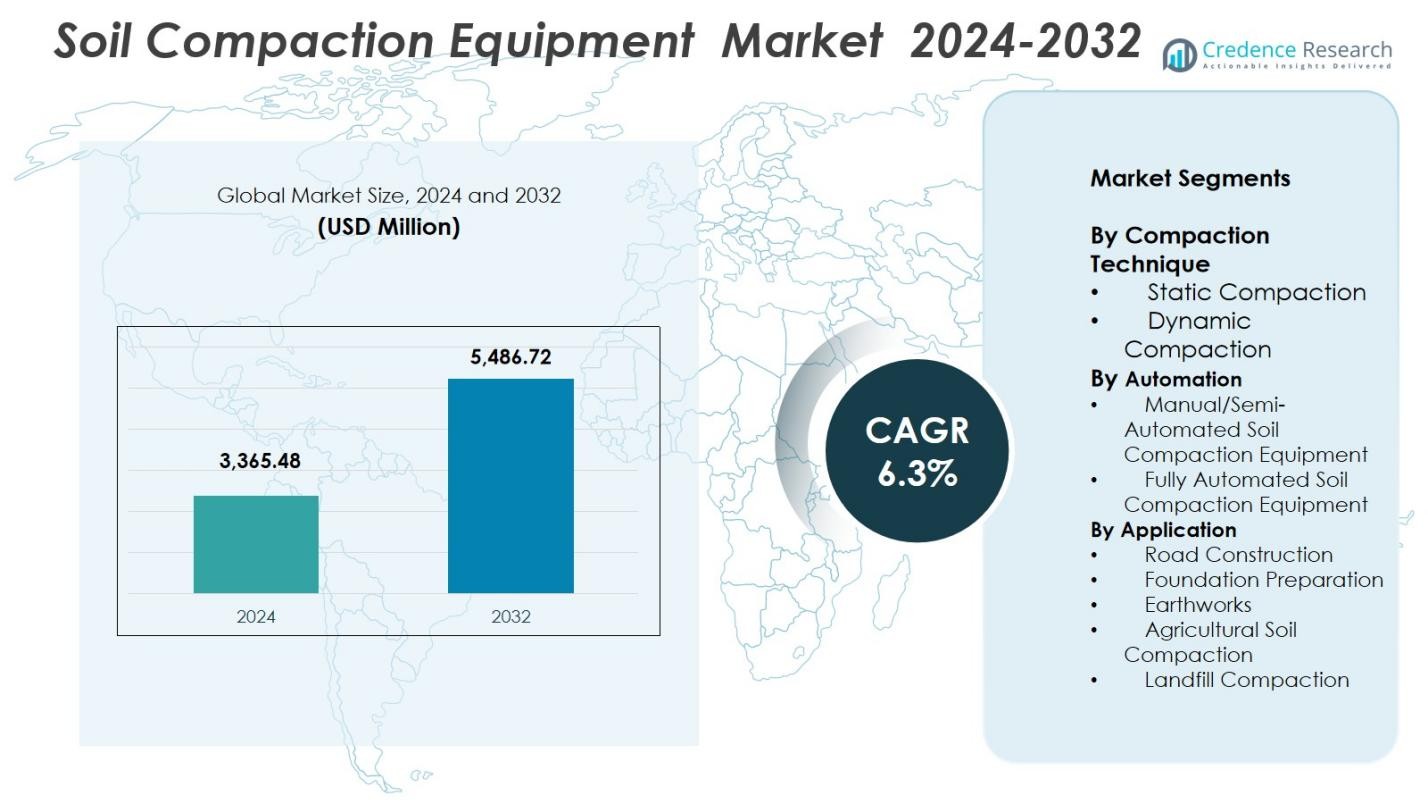
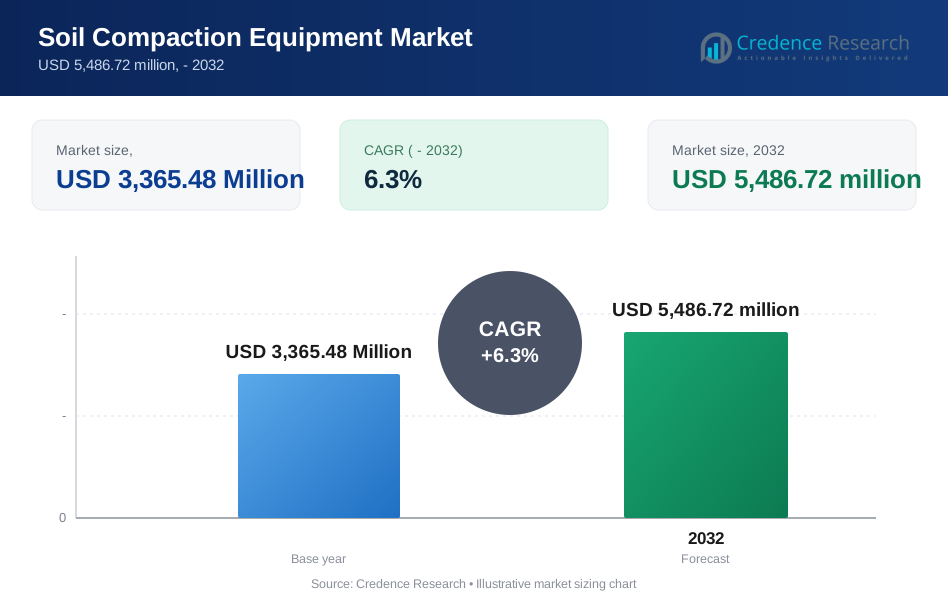
Soil Compaction Equipment Market size was valued at USD 3,365.48 Million in 2024 and is anticipated to reach USD 5,486.72 Million by 2032, at a CAGR of 6.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Soil Compaction Equipment Market Size 2024 | USD 3,365.48 Million |
| Soil Compaction Equipment Market , CAGR | 6.3% |
| Soil Compaction Equipment Market Size 2032 | USD 5,486.72 Million |
Soil Compaction Equipment Market features strong participation from global manufacturers offering advanced rollers, rammers, and plate compactors tailored for infrastructure and earthwork applications. Leading players such as Caterpillar, BOMAG, Wirtgen Group, Dynapac, JCB, Volvo Construction Equipment, Hitachi Construction Machinery, XCMG, and Wacker Neuson focus on intelligent compaction, telematics integration, and high-efficiency engines to strengthen their market presence. Asia-Pacific leads the market with a 34.8% share, driven by extensive roadbuilding and urban development projects, followed by North America at 29.4% and Europe at 27.1%. Continuous investment in digital compaction technologies and sustainable equipment platforms further enhances the competitive positioning of these companies.
Market Insights
- The Soil Compaction Equipment Market was valued at USD 3,365.48 million in 2024 and is projected to reach USD 5,486.72 million by 2032, growing at a CAGR of 6.3%.
- Market growth is driven by expanding road construction, infrastructure modernization, and increasing mechanization across construction and agriculture, boosting demand for rollers, rammers, and plate compactors.
- Key trends include the adoption of intelligent compaction, telematics-enabled equipment, electric compactors, and rental-based models that offer cost-efficient access to advanced machinery.
- Leading players such as Caterpillar, BOMAG, Wirtgen Group, Dynapac, JCB, and XCMG strengthen market competitiveness through product innovation, automation, and expanded rental partnerships, while high equipment costs remain a restraint.
- Asia-Pacific dominates with a 34.8% share, followed by North America at 29.4% and Europe at 27.1%, while dynamic compaction leads the technique segment with a 62.4% share, reflecting strong demand for high-performance equipment.
Market Segmentation Analysis
By Compaction Technique
In the Soil Compaction Equipment market, dynamic compaction holds the dominant position with a 62.4% share in 2024, driven by its higher efficiency, deeper soil penetration, and suitability for large-scale civil engineering projects. Dynamic systems offer superior densification for highways, runways, and heavy-load foundations, making them the preferred choice in infrastructure-intensive economies. Static compaction continues to support landscaping, small-scale construction, and agriculture, but rising global investments in transportation corridors, urban expansion, and industrial zones reinforce the strong adoption of dynamic compaction across both developed and emerging regions.
- For Instance, the Hamm HC series from Wirtgen incorporated advanced vibration systems achieving deeper compaction layers, enabling contractors to meet stringent density requirements in expressway and airport runway projects.
By Automation
Manual and semi-automated soil compaction equipment leads this segment with a 71.8% market share in 2024, supported by affordability, ease of operation, and extensive use across small to medium-scale construction projects. Contractors prioritize these systems for their flexibility, lower maintenance costs, and compatibility with varied soil conditions. Fully automated equipment is gaining traction due to advancements in telematics, GPS-guided rollers, and real-time compaction mapping; however, high upfront costs and limited operator familiarity slow widespread adoption. Growth in digital construction technologies and smart jobsite integration is expected to accelerate automated equipment penetration over the forecast period.
- For instance, Wirtgen Group enhanced its Hamm Compaction Navigator (HCN) system, enabling real-time compaction documentation and GPS-based guidance for rollers, improving uniformity on large road projects.
By Application
Road construction emerges as the dominant application segment, capturing a 48.6% share in 2024, driven by massive investments in national highway programs, rural road expansion, airport runways, and freight corridor development. The segment benefits from stringent compaction quality standards that require high-performance rollers and advanced monitoring technologies. Foundation preparation and earthworks also contribute significantly, supported by ongoing commercial and residential construction. Agricultural soil compaction and landfill compaction remain niche but steadily expanding applications, particularly in regions modernizing their farming practices or enhancing waste management infrastructure.
Key Growth Drivers
Expanding Global Infrastructure and Road Development Programs
The Soil Compaction Equipment market benefits significantly from massive global infrastructure investments, particularly in highways, railways, airports, industrial corridors, and urban development projects. Government-backed programs such as rural road connectivity schemes, smart city missions, and logistics network expansion drive consistent demand for high-performance rollers and compactors. Developing economies in Asia-Pacific and Africa are witnessing large-scale public sector spending to improve transportation efficiency, reduce congestion, and enhance regional connectivity, further accelerating equipment procurement. Additionally, private construction companies and EPC contractors increasingly require reliable compaction machinery that ensures uniform soil density and long-term structural stability. The surge in mega-projects including industrial parks, warehousing hubs, and renewable energy installations reinforces the adoption of advanced compaction systems. Strict regulatory standards for pavement quality and compaction uniformity also push the industry toward technologically superior machines capable of delivering higher precision and productivity.
- For instance, India’s Bharatmala highway development program deployed advanced vibratory rollers from Wirtgen across multiple corridors, improving compaction efficiency under strict pavement quality specifications.
Mechanization of Construction and Agricultural Operations
Increasing mechanization across construction, mining, and agricultural sectors acts as a strong growth catalyst for the Soil Compaction Equipment market. As labor shortages rise and project timelines tighten, contractors prioritize efficient equipment that reduces manual effort and accelerates site preparation activities. Mechanized compaction enhances structural durability, supports foundation stability, and minimizes long-term maintenance costs. In agriculture, modern farming practices such as precision soil conditioning and controlled compaction encourage the adoption of walk-behind rollers and tractor-mounted compactors. Developing countries are witnessing rapid mechanization as small and mid-sized contractors upgrade from manual methods to mechanized soil preparation solutions. Government subsidies, training programs, and equipment financing schemes further support the transition by making compactors more accessible. The emphasis on productivity, safety, and consistent compaction outcomes continues to fuel the shift toward mechanized solutions across diverse end-use industries.
- For instance, in mining and earth-works applications, studies on Rolling Dynamic Compaction (RDC) a mechanized method using heavy non-circular impact rollers show that RDC can compact thicker soil layers and improve shear strength and stiffness, making it a more efficient alternative to manual or static methods especially for large-scale projects.
Advancements in Automation, Telematics, and Intelligent Compaction
Technological innovation stands as a major driver, with automation and telematics transforming how compaction equipment operates on modern job sites. Intelligent compaction systems equipped with real-time sensors, GPS mapping, and accelerometer-based feedback provide operators with continuous data on soil stiffness, compaction depth, and coverage uniformity. This enhances accuracy, reduces operational errors, and ensures compliance with quality standards. Contractors increasingly adopt fleet management platforms that track fuel consumption, machine health, utilization rate, and location to optimize deployment and maintenance schedules. Automated control features reduce operator dependency and improve productivity in large infrastructure projects. Integration with drones, BIM systems, and remote diagnostics further strengthens equipment efficiency. As construction becomes more data-driven, the demand for smart, connected compactors continues to grow, positioning technologically advanced equipment as a pivotal growth engine for the industry.
Key Trends & Opportunities
Increasing Adoption of Electric and Hybrid Compaction Equipment
A growing focus on sustainability, emissions reduction, and noise control is accelerating the adoption of electric and hybrid soil compaction machines. Urban infrastructure projects, tunnels, and environmentally sensitive zones increasingly prefer low-emission rollers that comply with stringent environmental regulations. Manufacturers are developing battery-powered rammers, plate compactors, and small rollers that offer quieter operation, lower operating costs, and reduced maintenance compared to diesel-powered models. Advancements in lithium-ion battery technology also extend machine runtime and charging efficiency, improving the feasibility of electric alternatives. Governments promoting green construction and carbon-neutral public works provide further incentives for transitioning to clean-energy equipment. This trend presents strong opportunities for OEMs to expand their eco-friendly portfolios and cater to municipalities, contractors, and rental companies seeking sustainable compaction solutions.
- For instance, Wacker Neuson expanded its zero-emission lineup with the Battery Rammer AS50e and AP1840e electric plate compactor, offering reduced vibration, low noise, and no onsite emissions for inner-city and indoor applications.
Rising Demand for Rental and Leasing Services Across Emerging Markets
The expansion of equipment rental and leasing services represents a significant opportunity for the Soil Compaction Equipment market, especially in regions where small and mid-sized contractors prefer cost-effective procurement models. High upfront purchase costs and maintenance expenses make rental solutions attractive for short-duration and specialized compaction tasks. Rental fleets increasingly include advanced rollers with telematics, automated control systems, and efficient engines, enabling widespread access to premium technology at lower cost. Companies operating in emerging economies leverage rentals to participate in large infrastructure projects without long-term capital commitments. This shifts market dynamics toward flexible ownership models, encouraging OEMs to strengthen rental partnerships and invest in durable, high-utilization equipment designed specifically for fleet operators.
- For instance, United Rentals expanded its compaction equipment offerings with advanced vibratory rollers and plate compactors featuring telematics-enabled monitoring, allowing contractors to track performance and utilization without purchasing the machines.
Key Challenges
High Equipment Costs and Limited Adoption of Advanced Technologies
The Soil Compaction Equipment market faces challenges stemming from high procurement costs, which limit adoption among small contractors and cost-sensitive markets. Modern rollers equipped with intelligent compaction, automation, and telematics often require substantial upfront investment, restricting penetration in developing regions. Additionally, many contractors lack the technical expertise required to operate advanced systems, resulting in slower adoption of automated compaction technologies. Training gaps, high maintenance costs, and limited availability of skilled operators further hinder widespread implementation. Economic fluctuations and budget constraints in public infrastructure projects also delay equipment upgrades. These factors collectively challenge market expansion, particularly for premium and technologically advanced models.
Operational Bottlenecks, Regulatory Compliance, and Environmental Constraints
Soil compaction activities often face operational constraints due to varying soil conditions, adverse weather, and regulatory restrictions on noise and emissions. In regions with strict environmental controls, diesel-powered equipment may require additional compliance measures, increasing operating costs. Unpredictable soil behavior in certain terrains demands multiple passes and higher fuel consumption, reducing efficiency and increasing wear on machinery. Additionally, contractors must adhere to stringent compaction quality standards, requiring meticulous monitoring and documentation. Delays caused by equipment breakdowns, supply chain disruptions, or lack of standardized testing protocols can further impact project timelines. These operational and regulatory challenges create substantial barriers for both manufacturers and end users.
Regional Analysis
North America
North America holds a 29.4% share of the Soil Compaction Equipment market in 2024, supported by extensive investments in highway rehabilitation, airport expansions, and commercial infrastructure. The U.S. leads demand due to strict compaction quality standards and rapid adoption of telematics-enabled rollers for large-scale projects. Canada’s growing focus on sustainable construction and remote jobsite automation further boosts equipment uptake. High labor costs and advanced construction practices accelerate the transition toward mechanized and semi-automated compactors. Strong rental penetration and continuous equipment upgrades by contractors also reinforce North America’s position as a technologically advanced market.
Europe
Europe accounts for a 27.1% market share, driven by robust construction activity, modernization of transportation corridors, and stringent environmental regulations. Countries such as Germany, France, and the U.K. adopt electric and hybrid compaction equipment to meet emission compliance targets. The region benefits from mature infrastructure development cycles that emphasize soil stability, pavement durability, and precision compaction. Public investments in rail networks, renewable energy installations, and urban redevelopment drive steady demand. Europe’s strong presence of global OEMs and rapid adoption of intelligent compaction technologies reinforce its leadership in sustainability-focused equipment innovation.
Asia-Pacific
Asia-Pacific dominates the Soil Compaction Equipment market with a 34.8% share, making it the largest regional contributor in 2024. Massive infrastructure development programs in China, India, and Southeast Asia including national highways, metro rail networks, industrial corridors, and airport expansions drive substantial equipment demand. Rapid urbanization and government-backed construction initiatives encourage widespread adoption of both mechanical and automated compactors. The region also benefits from growing construction equipment manufacturing hubs and increasing mechanization in agriculture. Expanding rental fleets, rising labor shortages, and a shift toward technologically advanced rollers further accelerate market growth across emerging economies.
Latin America
Latin America represents a 5.6% share of the market, with demand influenced by ongoing road-building programs, mining activities, and urban infrastructure upgrades. Brazil, Mexico, and Chile lead adoption as governments emphasize logistics development and improved rural connectivity. Economic fluctuations slow long-term investments but create opportunities for rental-based equipment solutions. Contractors increasingly prefer versatile, fuel-efficient compactors suited to mixed soil conditions across large work zones. Growth in residential construction and land redevelopment projects supports consistent demand, while modernization of waste management sites drives adoption of landfill compactors.
Middle East & Africa (MEA)
The Middle East & Africa region holds a 3.1% share, supported by infrastructure diversification, oil-funded construction programs, and large-scale urban development initiatives. Countries such as the UAE, Saudi Arabia, and Qatar invest heavily in roads, industrial parks, and smart city projects, boosting demand for high-performance compaction equipment. Africa’s adoption is rising due to expansion of road networks, mining operations, and agricultural land preparation. However, budget constraints and limited access to advanced machinery slow penetration of automated compactors. Rental services and durable mechanical compactors remain highly preferred across the region.
Market Segmentations
By Compaction Technique
- Static Compaction
- Dynamic Compaction
By Automation
- Manual/Semi-Automated Soil Compaction Equipment
- Fully Automated Soil Compaction Equipment
By Application
- Road Construction
- Foundation Preparation
- Earthworks
- Agricultural Soil Compaction
- Landfill Compaction
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Soil Compaction Equipment market features a diverse and well-established competitive landscape, driven by global manufacturers expanding their portfolios with technologically advanced and fuel-efficient rollers, rammers, and plate compactors. Key players such as Caterpillar, Wirtgen Group, JCB, BOMAG, Dynapac, Volvo Construction Equipment, Hitachi Construction Machinery, XCMG, Sany Heavy Industries, and Wacker Neuson focus on intelligent compaction systems, telematics integration, and automation to strengthen their market presence. Companies increasingly emphasize electric and hybrid compactors to meet emission regulations and urban construction requirements. Strategic initiatives including product launches, rental fleet partnerships, and regional manufacturing expansions enhance competitiveness. Many OEMs also invest in digital platforms for real-time machine monitoring and predictive maintenance, improving fleet efficiency for contractors. With rising demand across infrastructure, agriculture, and waste management projects, competition intensifies as manufacturers innovate toward compact, high-performance, and cost-efficient equipment tailored to diverse soil and project conditions.
Key Player Analysis
- Wirtgen Group
- J C Bamford Excavators Ltd. (JCB)
- Sany Heavy Industries
- MBW, Inc.
- XCMG
- Weber Maschinentechnik GmbH
- Terex
- Caterpillar
- Zoomlion Heavy Industries
- Dynapac
Recent Developments
- In September 2025, SANY India introduced the SSR110C-10 PRO an 11-ton vibratory soil compactor built at its Pune facility, aimed at boosting infrastructure and road-building projects in India.
- In July 2025, JCB launched the 12-tonne VM118D soil compactor the world’s first soil compactor over 10 tonnes to meet EU Stage V emissions standards without requiring Diesel Exhaust Fluid (DEF).
- In December 2024, CASE Construction Equipment launched a “rental-ready” compactor lineup with simplified controls and telematics support, aimed at rental firms and small contractors.
Report Coverage
The research report offers an in-depth analysis based on Compaction Technique, Automation, Application, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will witness strong adoption of intelligent compaction systems as digital construction practices become standard across major infrastructure projects.
- Automation and telematics integration will expand, enabling real-time performance monitoring and higher compaction accuracy.
- Electric and hybrid compactors will gain momentum as governments tighten emission norms and urban projects demand low-noise equipment.
- Rental and leasing services will grow significantly, especially in emerging markets where contractors prefer flexible ownership models.
- Demand for high-frequency and high-impact compactors will rise with the expansion of highways, airports, and industrial corridors.
- Manufacturers will focus on compact, fuel-efficient, and multifunctional equipment suited for diverse soil and terrain conditions.
- Predictive maintenance technology will enhance fleet reliability and reduce downtime for construction contractors.
- Growing mechanization in agriculture will drive demand for small and mid-sized compactors tailored for soil conditioning.
- Emerging economies will prioritize large-scale road connectivity programs, strengthening regional market expansion.
- Competitive intensity will increase as global and regional players introduce advanced, cost-efficient models for both construction and waste management applications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Soil Compaction Equipment market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Soil Compaction Equipment market projected to grow between 2024 and 2032?
Which Soil Compaction Equipment market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Soil Compaction Equipment market?
Who are the leading companies in the Soil Compaction Equipment market?
Which region commanded the largest share of the Soil Compaction Equipment market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,365.48 Million → 2032: USD 5,486.72 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Soil Compaction Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Soil Compaction Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Soil Compaction Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Soil Compaction Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Soil Compaction Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Soil Compaction Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Soil Compaction Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Soil Compaction Equipment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,365.48 Million → 2032: USD 5,486.72 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Soil Compaction Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Soil Compaction Equipment Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Soil Compaction Equipment Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Soil Compaction Equipment Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

