
Market Overview
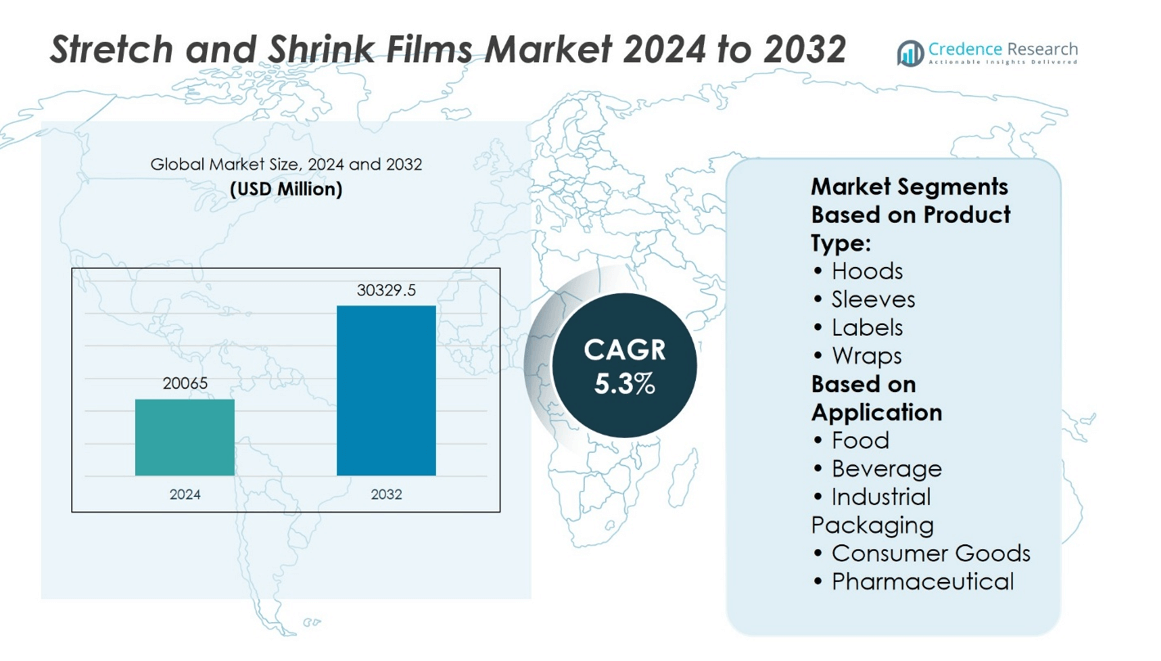
Stretch and Shrink Films Market size was valued at USD 20065 million in 2024 and is anticipated to reach USD 30329.5 million by 2032, at a CAGR of 5.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Stretch and Shrink Films Market Size 2024 | USD 20065 million |
| Stretch and Shrink Films Market, CAGR | 5.3% |
| Stretch and Shrink Films Market Size 2032 | USD 30329.5 million |
The stretch and shrink films market grows steadily due to rising demand for secure and tamper-evident packaging across food, beverage, and logistics sectors. It benefits from strong adoption in e-commerce and retail supply chains where durability and product visibility matter. The market trends highlight a shift toward sustainable, recyclable films and innovations in multi-layer extrusion technologies that improve performance and reduce material use. Manufacturers focus on downgauging film thickness without compromising strength. Demand for automated packaging solutions also influences product development, prompting investments in high-efficiency films that support faster processing and reduced operational costs across various end-use industries.
The stretch and shrink films market shows strong regional presence across North America, Europe, and Asia-Pacific, with Asia-Pacific holding the largest market share due to its expanding manufacturing base and packaging demand. North America and Europe follow, driven by sustainability regulations and advanced packaging infrastructure. Key players such as Berry Global Inc., Sigma Plastics Group, Amcor plc, Sealed Air, Bollore Inc, Paragon Films, and HIPAC Spa compete through product innovation, regional expansion, and strategic acquisitions to strengthen their global market position.
Market Insights
- The stretch and shrink films market reached USD 20065 million in 2024 and is projected to grow at a CAGR of 5.3% through the forecast period.
- Increasing demand for efficient packaging in food, beverage, and logistics sectors drives market expansion.
- Rising focus on lightweight, cost-effective, and sustainable packaging solutions supports steady adoption.
- Key players focus on innovation, such as multi-layer film technologies and recyclable materials, to gain competitive advantage.
- Fluctuating raw material prices and environmental regulations challenge consistent profit margins.
- Asia-Pacific holds the largest regional share due to strong manufacturing activity and high demand for consumer goods.
- North America and Europe show moderate growth with emphasis on sustainable practices and automation in packaging lines.
Market Drivers
E-commerce Expansion Increases Packaging Demand Across Distribution Channels
The rapid growth of e-commerce has created significant demand for efficient and secure packaging solutions, driving adoption of stretch and shrink films. These films ensure product stability and protection during transportation across complex distribution networks. With retailers shipping millions of parcels daily, manufacturers rely on these films to safeguard items from dust, moisture, and tampering. Stretch and shrink films enhance operational efficiency by minimizing packaging time and reducing material waste. Warehouses and fulfillment centers implement automated packaging lines that depend on these films for consistent wrapping and bundling. It supports the need for lightweight and cost-effective packaging that withstands long-distance shipment and high handling frequency.
- For instance, Berry Global reported an increase of 4,500 metric tons in its North American stretch film production capacity in 2023 to meet rising demand from online retail packaging applications.
Food and Beverage Sector Drives Adoption for Shelf-Life Extension and Hygiene
The food and beverage industry remains a key consumer of stretch and shrink films due to their role in product preservation and hygiene. These films create tight seals around packaged goods, preventing contamination and extending shelf life. Manufacturers of perishable products use it to maintain visual appeal and freshness throughout retail display. The films accommodate various shapes and sizes, making them suitable for multipacks and irregularly shaped containers. Fast-moving consumer goods rely on clear visibility and tamper evidence that these films provide. It also reduces packaging bulk while supporting compliance with food safety regulations.
- For instance, Amcor developed its shrink film solution for dairy products that extended shelf life by 15 days and reduced oxygen transmission to below 0.1 cc/m²/day, resulting in enhanced product safety and reduced food waste.
Industrial and Consumer Goods Manufacturers Focus on Cost-Efficient Load Stabilization
Stretch and shrink films contribute to secure palletization and load containment in industrial settings, supporting high-speed logistics and warehouse safety. Industries such as construction materials, electronics, and personal care products employ it to stabilize large or irregular shipments. The films offer high tensile strength and puncture resistance, minimizing the risk of damage during handling. Manufacturers choose these materials to lower packaging costs and streamline transportation. Integration with automated stretch wrapping machines improves throughput and reduces labor dependency. It plays a vital role in maintaining consistent packaging standards across diverse product lines.
Sustainability Requirements Influence Material Innovation and Recycling Efforts
Growing environmental awareness and stricter regulations have prompted producers to invest in recyclable and downgauged variants of stretch and shrink films. It now features higher performance with less material usage, supporting waste reduction targets. Many companies shift toward mono-material solutions to enhance recyclability and meet sustainability commitments. Development of bio-based and post-consumer recycled content films continues to gain traction across industries. Packaging teams evaluate it not only for strength and clarity but also for life cycle impact. This shift aligns with broader circular economy goals and reinforces brand accountability.
Market Trends
Growth in Flexible Packaging Adoption Influences Material Preference
Flexible packaging formats continue to replace rigid alternatives across various industries, prompting a shift in material selection within the stretch and shrink films market. Brands seek lightweight, durable solutions that improve shelf appeal and reduce shipping costs. It supports efficient space utilization during transportation and storage. The versatility of these films allows for their application across diverse shapes and sizes, from individual retail units to bulk shipments. Consumer goods and food sectors favor them for their tamper-resistance and transparency. Their compatibility with high-speed packaging lines further encourages widespread integration.
- For instance, Coveris increased its production of polyethylene-based shrink films by 2,800 metric tons in 2023 to support demand for lightweight, flexible packaging in the food and medical sectors.
Focus on Downgauging and High-Performance Film Formulations
Manufacturers emphasize downgauging to reduce film thickness while maintaining strength, improving material efficiency and sustainability. The stretch and shrink films market sees growing interest in multi-layered, high-performance films that offer superior load containment and clarity. It supports sustainability goals without compromising functionality. These developments help reduce resin consumption and lower operational costs for end-users. Companies invest in advanced extrusion technologies to produce films that meet evolving performance demands. The trend also supports compliance with emerging environmental standards.
- For instance, Sealed Air launched its Cryovac OptiDure 2050 shrink film with a down gauge thickness of 25 microns, offering puncture resistance of over 2.5 kg
Integration of Automation Technologies in Packaging Operations
The transition to automated packaging solutions in manufacturing and distribution sectors increases reliance on films compatible with machine applications. The stretch and shrink films market adapts to this trend by offering materials with uniform stretchability, consistent gauge, and smooth unwind characteristics. It improves wrapping speed and reduces material waste. Automated lines require films that deliver optimal tension control and minimize film breaks. Machine-grade films help optimize throughput in high-volume environments. The demand for compatibility with robotics and smart packaging systems continues to rise.
Circular Economy Principles Guide Innovation and Material Recovery Efforts
Sustainability trends influence product innovation, with brands adopting recyclable, compostable, and post-consumer recycled films. The stretch and shrink films market reflects this shift with expanded offerings that align with closed-loop systems and regulatory pressures. It promotes the use of mono-material structures to support recycling stream compatibility. Governments and industry groups advocate for greater traceability and responsible sourcing of raw materials. Brands prioritize environmental transparency and incorporate life-cycle assessments into packaging decisions. The trend encourages collaboration across the supply chain to reduce ecological impact.
Market Challenges Analysis
Rising Environmental Scrutiny and Regulatory Pressures Limit Material Use
The stretch and shrink films market faces challenges from mounting environmental concerns and tightening global regulations. Government agencies continue to impose restrictions on single-use plastics, urging companies to reduce polymer-based packaging. It complicates raw material sourcing and forces a shift toward recyclable or biodegradable alternatives, many of which lack equivalent performance or scalability. Compliance with extended producer responsibility (EPR) frameworks adds cost and operational complexity. Brands must reevaluate film compositions to meet recycling requirements without compromising product protection. These pressures reduce flexibility in design and often delay product innovation cycles.
Volatility in Raw Material Prices Disrupts Supply Chain Stability
Price fluctuations in petrochemical-derived resins, such as polyethylene and polypropylene, present a major obstacle for producers. The stretch and shrink films market depends heavily on stable feedstock supplies to maintain consistent pricing and profit margins. It suffers when geopolitical tensions, trade restrictions, or refinery disruptions limit resin availability. Procurement teams must manage cost unpredictability while meeting delivery schedules for high-volume applications. Smaller manufacturers face particular difficulty in absorbing price shocks, reducing their competitiveness. These supply-side constraints frequently hinder long-term planning and investment in new technologies.
Market Opportunities
Expansion of E-Commerce and Retail Logistics Opens New Avenues for Film Usage
The growth of online retail and direct-to-consumer distribution creates strong demand for secure and efficient packaging. The stretch and shrink films market benefits from increased use of pallet wraps and unit load protection across e-commerce supply chains. It enables retailers and fulfillment centers to reduce product damage during high-volume shipping operations. Film manufacturers can develop specialized formats tailored to automated wrapping systems, ensuring fast throughput and minimal waste. Custom films that support branding or tamper-evidence also find growing acceptance. These applications offer scalable, high-frequency use cases that reinforce recurring sales.
Shift Toward Bio-Based and Recyclable Films Spurs Innovation
Sustainability-driven innovation in materials presents a clear opportunity for forward-looking producers. The stretch and shrink films market gains momentum from growing investments in bio-based polymers and circular packaging solutions. It allows manufacturers to align with corporate ESG goals and regulatory expectations while offering performance-aligned alternatives. Advances in multilayer technology and post-consumer resin integration help maintain strength and flexibility in eco-friendly formats. Partnerships with recyclers and resin developers support the creation of closed-loop systems. These initiatives position film makers as responsible suppliers in a packaging landscape that prioritizes resource efficiency.
Market Segmentation Analysis:
By Product Type:
The stretch and shrink films market includes products such as hoods, sleeves and labels, wraps, and others. Wraps are widely used in securing pallet loads across warehouses and distribution centers, offering reliable load stability and minimizing movement during transit. It supports fast packaging speeds and cost efficiency in logistics. Sleeves and labels are important in industries like beverages and pharmaceuticals, where high-quality branding and tamper-evident packaging are essential. Shrink sleeves conform to complex container shapes and enable 360-degree design coverage, enhancing shelf appeal. Hoods, especially stretch hoods, have replaced traditional shrink covers in many industrial applications due to their strength and energy-saving characteristics. It eliminates the need for heat application while offering strong puncture resistance and waterproof sealing.
- For instance, Berry Global’s Stratos Stretch Film achieved a pre-stretch capability of 325%, allowing a single roll to wrap up to 15,000 linear feet of pallets, reducing film consumption by 1.2 kg per pallet load
By Application:
The stretch and shrink films market caters to applications in food and beverage, industrial packaging, consumer goods, and pharmaceuticals. Food and beverage lead in adoption due to the sector’s demand for hygienic, durable, and visually appealing packaging. It helps extend shelf life, protect against contamination, and support retail display readiness. Industrial packaging relies on stretch and shrink films to bundle large and heavy products like appliances, machinery, and construction materials. It ensures product stability and ease of transportation without needing additional protective layers. Consumer goods use these films for bundling and retail presentation, helping manufacturers reduce individual packaging costs while enhancing visual impact on shelves. In pharmaceuticals, the use of shrink labels and tamper-evident films ensures regulatory compliance and product integrity throughout the supply chain.
- For instance, according to the USDA Agricultural Research Service, the use of high-barrier shrinks films in beef packaging-maintained oxygen transmission rates at 0.04 cc/m²/day, extending product shelf life from 21 days to 42 days when stored at 1.7°C
Segments:
Based on Product Type:
- Hoods
- Sleeves
- Labels
- Wraps
Based on Application
- Food
- Beverage
- Industrial Packaging
- Consumer Goods
- Pharmaceutical
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America accounted for 28.5% of the global stretch and shrink films market share in 2024. The region benefits from mature packaging industries in the U.S. and Canada, where demand for flexible and sustainable packaging solutions remains consistent. High consumption of packaged food, beverages, and pharmaceuticals drives the uptake of shrink and stretch film packaging. The U.S. leads in demand due to its expansive retail and logistics sectors, which prioritize damage-free delivery and shelf-ready packaging formats. Growth in e-commerce and warehouse automation encourages the use of high-performance stretch films for pallet unitization. It supports operational efficiency while meeting sustainability goals with thinner films that use less plastic. North American manufacturers also invest in downgauged films and recyclable materials to align with government initiatives aimed at reducing plastic waste.
Europe
Europe captured a 24.2% share of the stretch and shrink films market in 2024. Strict environmental regulations and consumer demand for eco-friendly packaging solutions shape market trends across the region. Countries such as Germany, France, and the U.K. lead innovation in bio-based and recyclable film formulations. Stretch films with high tensile strength and lower material usage remain in focus among European packaging companies. The beverage and personal care sectors demand high-clarity shrink sleeves for premium branding and tamper-evident sealing. Automated packaging lines and integration of recyclable mono-materials continue to influence purchasing decisions across industrial users. It reflects the European Union’s sustainability goals and increasing demand for circular packaging solutions. Local players collaborate with retailers and recyclers to improve film recovery and reduce landfill dependency.
Asia Pacific
Asia Pacific led the global market with a 33.1% share in 2024. The region’s dominance stems from rapid industrialization, growth in manufacturing, and expanding retail sectors across China, India, Japan, and Southeast Asia. China alone contributes a major portion of regional revenue due to its role as a global manufacturing hub and exporter of packaged goods. Stretch and shrink films find widespread application in logistics, agriculture, electronics, and FMCG sectors. It supports efficient load containment and reduces product damage during long-distance transportation. Rising disposable income and urbanization drive consumption of packaged food and consumer goods, further accelerating packaging demand. Asia Pacific also sees increasing local investments in extrusion technologies, improving the availability of cost-effective, high-performance films tailored for varied climates and supply chain conditions.
Latin America
Latin America held a 7.8% share of the global stretch and shrink films market in 2024. Brazil and Mexico drive demand in the region through their growing beverage, dairy, and consumer goods industries. Local producers adopt stretch hoods and shrink wraps for both retail and industrial packaging applications. It enhances product stability during transport and meets branding requirements with custom-printed shrink sleeves. Growing logistics networks, particularly in urban areas, push manufacturers to adopt automated packaging technologies. Local challenges like limited recycling infrastructure create demand for biodegradable alternatives and thinner gauge films. Market players in Latin America also benefit from trade integration and manufacturing relocation from North America, expanding regional production capabilities.
Middle East and Africa (MEA)
The Middle East and Africa contributed 6.4% to the global market in 2024. Gulf countries, especially the UAE and Saudi Arabia, continue to invest in advanced retail and logistics infrastructure, creating sustained demand for high-performance stretch films. It plays a key role in food security by extending the shelf life of perishables through barrier shrink wraps. Industrial sectors in South Africa and the GCC utilize stretch films to secure machinery and heavy equipment for export and internal distribution. MEA faces challenges with film recycling, prompting efforts toward localizing biodegradable film production. Imports still dominate the market, but investments in flexible packaging plants are expected to strengthen regional supply. The region’s young consumer base and growing retail sector support long-term demand for visually appealing, protective shrink packaging.
Key Player Analysis
- HIPAC Spa
- Millennium Packaging, Inc
- LUBAN PACK
- Amcor plc
- Paragon Films
- A-Z Packaging
- Italdibipack SpA
- Sigma Plastics Group
- Berry Global Inc.
- Sealed Air
- Bollore Inc
Competitive Analysis
The stretch and shrink films market include HIPAC Spa, Millennium Packaging, Inc, LUBAN PACK, Amcor plc, Paragon Films, A-Z Packaging. The stretch and shrink films market remains highly competitive, driven by rapid innovation in materials and packaging technologies. Companies are focusing on enhancing film strength, clarity, and sustainability to meet evolving industry requirements. Strategic investments in advanced extrusion technologies and multilayer film development help firms deliver high-performance solutions across diverse applications. Market participants prioritize strong supply chain integration and regional manufacturing footprints to ensure consistent product availability. Sustainability goals continue to influence operations, with players accelerating adoption of recyclable and bio-based films. Firms also emphasize tailored product offerings to meet sector-specific demands in food, pharmaceuticals, and consumer goods. The market's dynamic nature demands continual innovation and operational efficiency to maintain competitive positioning.
Recent Developments
- In March 2024, Paragon launched "Beyond PCR," the world’s first ultra-high performance, thin-gauge machine film with certified-pending, post-consumer recycled content, available nationwide in the United States.
- In February, 2024, Innovia Films launched floatable polyolefin shrink films. RayoFloat white APO is a low-density white polyolefin that maintains floatability when printed. Its opacity enhances light blocking, suitable for shrink sleeves for light-sensitive industries such as dairy, food supplements, nutritional products and cosmetics.
- In July 2023, Amcor invested in a new production line in Swansea, enabling the company to produce a new series of thinner, PVdC-free shrink bags and films that maintain high optical and protective qualities while reducing plastic usage.
- In May 2023, Innovia Films introduced APO 45, a floatable and sustainable shrink sleeve material developed to boost PET recycling rates and support a circular economy for packaging. The product is suitable for use in all shrink sleeve applications in the household, laundry, personal care, food, dairy, and beverage markets, states the company.
Market Concentration & Characteristics
The shrink films market exhibits moderate to high market concentration, with a mix of global manufacturers and regional players competing across application verticals. It operates in a technologically driven environment where product differentiation centers on film clarity, shrink ratio, and material composition. The market emphasizes cost efficiency, high-speed application compatibility, and consistent sealing performance to meet industrial packaging demands. It displays characteristics of scalability, with manufacturers expanding capacity through multilayer co-extrusion lines and automation. Regulatory compliance, especially regarding food contact safety and recyclability, influences product development and procurement strategies. The shrink films market shows a strong inclination toward sustainability, driving innovation in biodegradable and recyclable polyolefin formulations. Competitive intensity continues to shape market structure, supported by integrated value chains and growing end-user expectations for durability and aesthetics.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The stretch and shrink films market will experience rising demand due to increasing adoption of flexible packaging solutions across industries.
- Manufacturers will invest more in recyclable and biodegradable film technologies to meet sustainability regulations.
- E-commerce growth will push the need for strong, tamper-evident, and secure packaging formats.
- The market will benefit from automation in packaging lines, requiring consistent film thickness and high-speed compatibility.
- Demand for food-grade shrink films will grow, driven by increased consumption of packaged food and beverages.
- Stretch hood films will gain traction in industrial packaging due to their high load stability and moisture resistance.
- North America and Asia-Pacific will remain key contributors, supported by strong manufacturing and logistics sectors.
- Innovation in multilayer co-extruded films will continue, improving mechanical strength and visual appeal.
- Regulatory focus on plastic waste reduction will influence product development and raw material sourcing.
- The market will see increased consolidation, with key players expanding production capacity and geographic reach.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
E-commerce Expansion and Automated Logistics
The rapid growth of e-commerce and the adoption of automated packaging lines in warehouses and fulfillment centers are driving demand for stretch and shrink films. These films provide secure, tamper-evident packaging that protects goods during high-frequency, long-distance shipments, supporting operational efficiency and reducing material waste.
Food and Beverage Shelf-Life and Hygiene Requirements
The food and beverage sector relies heavily on stretch and shrink films to extend product shelf life, maintain hygiene, and ensure visual appeal. These films offer tight seals that prevent contamination and spoilage, supporting compliance with food safety regulations and meeting consumer expectations for fresh, safe products.
Sustainability and Regulatory Pressures
Increasing environmental awareness and stricter regulations on single-use plastics are pushing manufacturers to innovate with recyclable, downgauged, and bio-based film solutions. This shift supports waste reduction targets and aligns with corporate ESG commitments, driving the adoption of new materials and technologies in the market.
Industrial Load Stabilization and Cost Efficiency
Industrial and consumer goods manufacturers use stretch and shrink films for secure palletization and load containment, reducing product damage during handling and transit. The films' high tensile strength and compatibility with automated wrapping machines help lower packaging costs and improve throughput in logistics operations.
Growth in Flexible Packaging Adoption
The ongoing shift from rigid to flexible packaging formats across industries is increasing the use of stretch and shrink films. Their lightweight, durable, and versatile nature supports efficient transportation, storage, and retail display, making them a preferred choice for brands seeking cost-effective and visually appealing packaging solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the stretch and shrink films market and what is its projected size in 2032?
At what Compound Annual Growth Rate is the stretch and shrink films market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the stretch and shrink filmsmarket?
Which region commanded the largest share of the stretch and shrink films market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Food
- 1.2.2 Beverage
- 1.2.3 Industrial Packaging
- 1.2.4 Consumer Goods
- 1.2.5 Pharmaceutical
- 1.3 By Product Type
- 1.3.1 Hoods
- 1.3.2 Sleeves
- 1.3.3 Labels
- 1.3.4 Wraps
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 20065 million → 2032: USD 30329.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Stretch and Shrink Films Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Stretch and Shrink Films Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Stretch and Shrink Films Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Stretch and Shrink Films Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Stretch and Shrink Films Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Stretch and Shrink Films Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Stretch and Shrink Films Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Stretch and Shrink Films Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 20065 million → 2032: USD 30329.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Stretch and Shrink Films Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Food
- 12.3.7.2 Beverage
- 12.3.7.3 Industrial Packaging
- 12.3.7.4 Consumer Goods
- 12.3.7.5 Pharmaceutical
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hoods
- 12.4.7.2 Sleeves
- 12.4.7.3 Labels
- 12.4.7.4 Wraps
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Stretch and Shrink Films End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Stretch and Shrink Films Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Stretch and Shrink Films Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Stretch and Shrink Films Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Berry Global Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Sigma Plastics Group
- 18.4 Amcor plc
- 18.5 Sealed Air
- 18.6 Bollore Inc
- 18.7 Paragon Films
- 18.8 HIPAC Spa
- 18.9 Millennium Packaging, Inc
- 18.10 LUBAN PACK
- 18.11 Italdibipack SpA
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

