
Market Overview:
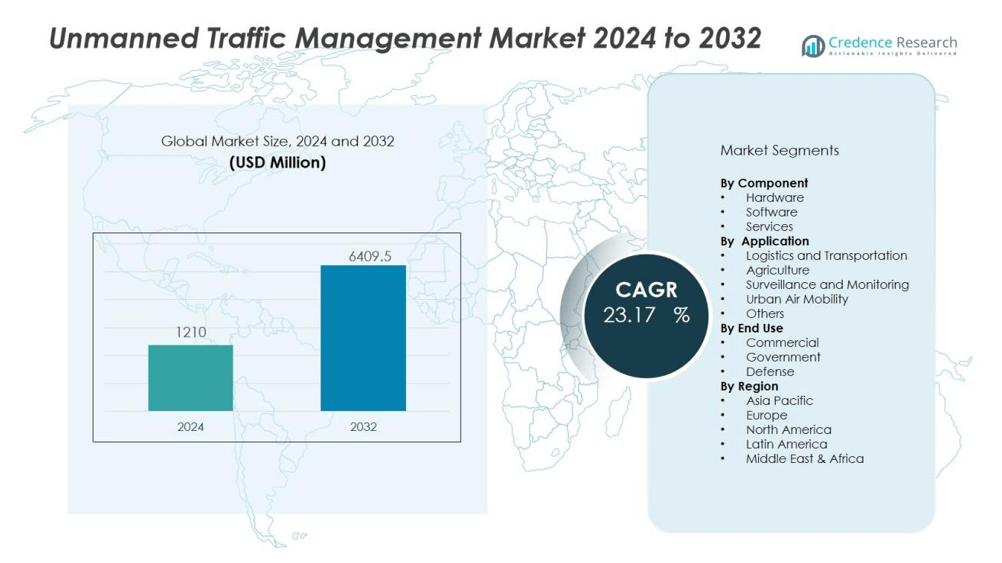
The unmanned traffic management market size was valued at USD 1210 million in 2024 and is anticipated to reach USD 6409.5 million by 2032, at a CAGR of 23.17% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Unmanned Traffic Management Market Size 2024 | USD 1210 million |
| Unmanned Traffic Management Market, CAGR | 23.17% |
| Unmanned Traffic Management Market Size 2032 | USD 6409.5 million |
The market is driven by the increasing deployment of drones in critical sectors such as e-commerce delivery, disaster management, and infrastructure monitoring. Growing government support through drone regulations and airspace modernization initiatives is further accelerating UTM adoption. The rising emphasis on beyond-visual-line-of-sight (BVLOS) operations and the development of advanced communication and navigation technologies also strengthen market expansion. Strategic collaborations between drone operators, technology providers, and regulatory bodies are shaping standardized frameworks for large-scale implementation.
Regionally, North America dominates the UTM market, supported by favorable regulatory frameworks from the Federal Aviation Administration (FAA) and strong participation from technology companies. Europe follows closely, driven by the European Union’s U-space initiative and robust investment in urban air mobility projects. Asia-Pacific is emerging as the fastest-growing region, propelled by high drone adoption in China, Japan, and India for logistics and agriculture, making it a critical growth hub in the global landscape.
Market Insights:
- The unmanned traffic management market was valued at USD 1210 million in 2024 and is projected to reach USD 6409.5 million by 2032, growing at a CAGR of 23.17% during 2024–2032.
- Rising drone adoption in logistics, agriculture, surveillance, and infrastructure inspection is creating strong demand for scalable UTM systems that ensure safe and efficient fleet coordination.
- Supportive regulatory frameworks such as the FAA’s Remote ID in the U.S. and the EU’s U-space initiative are accelerating large-scale implementation of UTM solutions worldwide.
- Advances in 5G connectivity, satellite navigation, and AI are enhancing real-time communication, enabling beyond-visual-line-of-sight operations and reducing risks of mid-air conflicts.
- North America leads with a share exceeding 35%, Europe follows with nearly 30%, and Asia-Pacific emerges as the fastest-growing region driven by adoption in China, Japan, and India.
Market Drivers:
Rising Adoption of Drones Across Commercial and Industrial Applications:
The unmanned traffic management market is gaining momentum due to the increasing use of drones in sectors such as logistics, agriculture, surveillance, and infrastructure monitoring. Companies are deploying drones for last-mile deliveries, precision farming, and inspection of critical assets like power lines and pipelines. The surge in commercial adoption creates significant demand for efficient UTM systems to manage large-scale operations. It ensures safe coordination of growing drone fleets in both urban and rural environments.
- For instance, DJI Agriculture has deployed over 400,000 agricultural drones globally by 2024, covering more than 500 million hectares of farmland and achieving water savings of 222 million tons.
Government Regulations and Supportive Policy Frameworks:
Governments across the globe are introducing clear regulatory frameworks to support drone integration into national airspace. The Federal Aviation Administration in the U.S. and the European Union’s U-space initiative highlight structured approaches to enhance operational safety. Such policies encourage investment in UTM technologies while providing a foundation for standardized implementation. The unmanned traffic management market benefits from these policies as they drive compliance and accelerate adoption. It positions UTM as a critical enabler of safe drone ecosystem expansion.
- For instance, Norway's Avinor selected Thales to deploy the country's next-generation nationwide UTM system in December 2024, utilizing the Topsky-UAS platform powered by AstraUTM technology.
Technological Advancements in Communication and Navigation Systems:
Advances in 5G connectivity, satellite navigation, and artificial intelligence are enabling more reliable and scalable UTM solutions. Real-time communication between drones, ground stations, and control systems enhances situational awareness. It supports beyond-visual-line-of-sight operations, which are crucial for applications like delivery and surveillance. These innovations make traffic management more accurate and reduce risks of mid-air conflicts. The unmanned traffic management market leverages these technologies to strengthen safety and efficiency.
Growing Investments in Urban Air Mobility and Future Air Transport:
The push toward urban air mobility, including passenger drones and air taxis, is creating new opportunities for UTM solutions. Major aerospace and technology firms are investing in projects that envision drones operating in densely populated cities. UTM systems are essential to ensure controlled, secure, and coordinated flights in such complex environments. It drives collaborations among aviation authorities, technology providers, and drone operators. The unmanned traffic management market stands at the core of enabling this next phase of aerial transport innovation.
Market Trends:
Integration of Artificial Intelligence, Automation, and Cloud-Based Solutions:
The unmanned traffic management market is witnessing a strong shift toward AI-driven and automated platforms that improve airspace coordination. Companies are deploying machine learning algorithms to predict traffic patterns, optimize flight routes, and prevent potential conflicts. Cloud-based solutions are being widely adopted to enable real-time data exchange between drones, operators, and regulators. It creates an ecosystem where traffic control is faster, more accurate, and scalable across regions. Automation also supports complex operations such as swarm drone flights and beyond-visual-line-of-sight missions. These advancements are transforming UTM systems into intelligent platforms that enhance both safety and efficiency.
- For instance, Google's Wing demonstrated real-time route planning capabilities through its OpenSky UTM platform that automatically managed flight paths of 3 Wing aircraft and multiple third-party drones simultaneously during Virginia Tech tests, preventing conflicts through automated algorithm-based routing without manual pilot intervention.
Expansion of Urban Air Mobility and Cross-Industry Collaborations:
The growing focus on urban air mobility is shaping a new trend where UTM solutions extend beyond traditional drone operations to include passenger drones and air taxis. Aerospace companies, telecom providers, and drone manufacturers are forming strategic alliances to create integrated ecosystems. It strengthens innovation by combining expertise in aviation, connectivity, and digital infrastructure. Governments and regulators are actively partnering with industry leaders to establish testbeds and pilot programs for advanced air mobility. The unmanned traffic management market is evolving into a critical enabler for future aerial transport networks. These collaborations are driving standardized protocols, ensuring scalability and safe operations in congested urban skies.
- For instance, Lilium has partnered with GE Aerospace since October 2024 to integrate their Event Measurement System platform into Lilium's POWER-ON aftermarket offering, with GE's EMS platform currently serving more than 60 airlines and over 500 business jet operators globally for flight data monitoring.
Market Challenges Analysis:
Regulatory Uncertainty and Complex Airspace Integration:
The unmanned traffic management market faces significant challenges due to varying regulatory frameworks across regions. Governments are still developing unified policies to integrate drones into national and international airspace. Lack of standardization creates operational delays and increases compliance costs for drone operators and technology providers. It restricts seamless cross-border operations and slows the adoption of advanced UTM solutions. Concerns over safety, liability, and privacy also complicate large-scale deployment. Without harmonized regulations, the market struggles to achieve consistent global scalability.
High Implementation Costs and Cybersecurity Risks:
Deploying UTM systems requires substantial investment in infrastructure, advanced communication networks, and cloud-based platforms. Smaller enterprises and emerging markets often find these costs prohibitive, limiting widespread adoption. It creates disparities in drone ecosystem development across regions. At the same time, growing reliance on digital platforms exposes UTM systems to cybersecurity threats. Risks such as data breaches, GPS spoofing, and unauthorized access undermine trust and safety in drone operations. The unmanned traffic management market must address these vulnerabilities while balancing cost efficiency to ensure sustainable growth.
Market Opportunities:
Expansion of Drone Applications in Commercial and Public Sectors
The unmanned traffic management market holds strong opportunities with the rapid expansion of drone applications across logistics, agriculture, healthcare, and emergency services. Growing use of drones for last-mile delivery, medical supply transport, and disaster response demands advanced traffic coordination systems. It creates new revenue streams for UTM providers through scalable and adaptable solutions. Public sector adoption, including law enforcement and environmental monitoring, further widens the scope of deployment. Rising investment in smart city projects also supports the integration of UTM systems into broader urban infrastructure. These developments highlight UTM’s role in enabling safe and efficient large-scale drone operations.
Growing Focus on Urban Air Mobility and Advanced Air Transport
The shift toward urban air mobility presents a transformative growth opportunity for UTM providers. Companies developing passenger drones and air taxis require reliable systems to manage high-density traffic in metropolitan areas. It positions UTM solutions as essential for the next phase of air transport innovation. Partnerships between aerospace firms, telecom providers, and regulators are accelerating pilot projects in advanced air mobility. Emerging economies with rising urbanization and demand for innovative transport are expected to adopt UTM solutions rapidly. The unmanned traffic management market is poised to benefit from this shift, creating long-term prospects for technological advancement and global expansion.
Market Segmentation Analysis:
By Component
The unmanned traffic management market is segmented into hardware, software, and services. Software dominates due to the rising demand for cloud-based platforms, real-time data sharing, and AI-driven analytics that enable safe and efficient drone operations. Hardware, including communication devices and surveillance systems, supports critical functions such as tracking and navigation. Services are expanding with growing reliance on managed solutions, consultancy, and integration support. It creates opportunities for providers to deliver end-to-end traffic management systems tailored to diverse operational needs.
- For instance, uAvionix’s Ping200X transponder, certified in 2022, weighs only 50 grams while meeting full ADS-B OUT standards, enabling drones to integrate into controlled airspace without compromising payload capacity.
By Application
The market covers applications in agriculture, logistics and transportation, surveillance and monitoring, and urban air mobility. Logistics and transportation lead the segment with high adoption of drones for last-mile delivery and cargo transport. Agriculture leverages UTM for precision farming and crop monitoring, driving efficiency in rural operations. Surveillance and monitoring support public safety, infrastructure inspection, and disaster management. It highlights UTM’s role in enabling safe and controlled drone flights across both commercial and public domains.
- For instance, in 2023, Alphabet’s Wing completed over 300,000 drone deliveries globally, showcasing the scalability of drone-based logistics supported by advanced traffic management systems.
By End Use
The end-use segmentation includes commercial, government, and defense sectors. Commercial applications dominate due to rapid adoption in e-commerce, healthcare logistics, and infrastructure services. Government entities invest in UTM for urban planning, law enforcement, and environmental monitoring. Defense forces employ UTM to coordinate unmanned aerial systems in surveillance and tactical missions. It strengthens operational efficiency while ensuring compliance with evolving regulatory frameworks.
Segmentations:
By Component:
- Hardware
- Software
- Services
By Application:
- Logistics and Transportation
- Agriculture
- Surveillance and Monitoring
- Urban Air Mobility
- Others
By End Use:
- Commercial
- Government
- Defense
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America:
North America holds a market share exceeding 35% in the unmanned traffic management market, driven by advanced regulatory frameworks and strong industry adoption. The Federal Aviation Administration plays a critical role in enabling large-scale drone integration through initiatives such as Remote ID and beyond-visual-line-of-sight approvals. The region benefits from the presence of leading technology providers and drone manufacturers, fostering innovation and large pilot programs. It also witnesses strong investment in urban air mobility, with multiple projects testing passenger drones and delivery networks. The United States remains the largest contributor, supported by government funding and private sector partnerships. Canada complements growth with active use of drones in energy, mining, and environmental monitoring.
Europe :
Europe accounts for a market share of nearly 30% in the unmanned traffic management market, supported by the European Union’s U-space initiative. This framework establishes standardized approaches for drone integration into shared airspace, creating consistency across member states. Countries such as Germany, France, and the United Kingdom are leading investment in UTM infrastructure and advanced mobility projects. It drives demand for scalable solutions capable of managing increasing drone traffic in both rural and urban environments. Strong participation from aerospace firms and telecom companies accelerates collaborative innovation. Government-backed testbeds for air taxi operations reinforce Europe’s position as a leader in advanced drone management systems.
Asia-Pacific:
Asia-Pacific captures a market share of close to 25% in the unmanned traffic management market, with rapid expansion fueled by drone adoption in logistics, agriculture, and public safety. China drives regional growth through its dominance in drone manufacturing and government-backed UTM projects. Japan and South Korea are investing heavily in urban air mobility initiatives, while India advances through supportive policies under its Digital Sky platform. It benefits from rising demand for smart city infrastructure and aerial transport solutions. The region’s strong manufacturing ecosystem and growing technological investments position it as a future hub for large-scale drone operations. Emerging economies in Southeast Asia are also creating demand for UTM solutions, strengthening Asia-Pacific’s role as the fastest-growing market.
Key Player Analysis:
- Leonardo S.p.A.
- L3Harris Technologies, Inc.
- Thales Group
- Lockheed Martin Corporation
- Unifly NV
- Airbus SE
- Frequentis AG
- OneSky Systems
- AirMap, Inc.
- RTX Corporation
Competitive Analysis:
The unmanned traffic management market is highly competitive, with global aerospace leaders and specialized technology firms driving innovation through strategic partnerships and advanced solutions. Key players include Leonardo S.p.A., L3Harris Technologies, Inc., Thales Group, Lockheed Martin Corporation, Unifly NV, Airbus SE, and Frequentis AG. These companies focus on integrating artificial intelligence, 5G, and cloud-based platforms to enhance safety, scalability, and regulatory compliance in drone operations. It is shaped by collaborations with regulators and aviation authorities to establish standardized frameworks for large-scale adoption. Competition is defined by investments in pilot projects, urban air mobility programs, and interoperability initiatives that strengthen global positioning. Leading firms leverage their expertise in aerospace and digital technologies to deliver end-to-end solutions, making UTM a cornerstone of future airspace management.
Recent Developments:
- In March 2025, At Verticon 2025, Leonardo announced new orders for nearly 30 commercial helicopters of various models for delivery between 2026 and 2028, valued at approximately EUR 370 million.
- In February 2025, EDGE Group and Leonardo signed a groundbreaking collaboration agreement to jointly develop future technologies and solutions in defense and security.
- In April 2025, L3Harris partnered with Kuiper Government Solutions to deliver hybrid SATCOM low-latency global connectivity solutions to government and military customers.
Market Concentration & Characteristics:
The unmanned traffic management market reflects a moderately concentrated structure, with leading players driving innovation through partnerships, pilot programs, and regulatory collaborations. It is characterized by a mix of established aerospace companies, technology providers, and emerging startups that focus on software, communication systems, and integration platforms. Competition intensifies through advancements in artificial intelligence, 5G connectivity, and cloud-based traffic management solutions. The market emphasizes safety, scalability, and compliance with evolving government regulations, shaping the pace of adoption. Regional variations in policy frameworks create diverse growth opportunities, while urban air mobility projects add a new dimension to demand. The industry continues to evolve through strategic alliances that strengthen global interoperability and position UTM as a cornerstone of the future airspace ecosystem.
Report Coverage:
The research report offers an in-depth analysis based on Component, Application, End Use and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The unmanned traffic management market will evolve into a critical enabler of safe large-scale drone operations across commercial, defense, and public sectors.
- Governments will strengthen regulatory frameworks to ensure standardized airspace integration and support long-term industry growth.
- Integration of artificial intelligence and machine learning will enhance predictive traffic management and improve operational efficiency.
- Cloud-based platforms and 5G connectivity will enable real-time communication between drones, operators, and regulators.
- Urban air mobility, including passenger drones and air taxis, will drive new demand for scalable UTM systems in metropolitan areas.
- Strategic collaborations among aerospace firms, telecom providers, and regulators will accelerate adoption of interoperable solutions.
- Cybersecurity solutions will become essential as digital traffic management systems face growing risks of data breaches and GPS spoofing.
- Emerging economies will adopt UTM rapidly, supported by smart city projects and expanding drone use in agriculture, logistics, and infrastructure.
- Investments in research and pilot programs will shape future business models, creating new opportunities for service providers.
- The unmanned traffic management market will transform into a global ecosystem, supporting advanced aerial transport and shaping the future of connected airspace.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Adoption of Drones Across Commercial and Industrial Applications
The increasing use of drones for logistics, agriculture, surveillance, and infrastructure monitoring is driving demand for scalable unmanned traffic management (UTM) systems to ensure safe and efficient coordination of growing drone fleets.
Government Regulations and Supportive Policy Frameworks
Clear regulatory frameworks such as the FAA’s Remote ID in the U.S. and the EU’s U-space initiative are accelerating the integration of drones into national airspace, encouraging investment in UTM technologies and enabling standardized, large-scale deployment.
Technological Advancements in Communication and Navigation Systems
Innovations in 5G connectivity, satellite navigation, and artificial intelligence are enabling real-time communication and beyond-visual-line-of-sight operations, making UTM systems more reliable, scalable, and capable of reducing mid-air conflict risks.
Growing Investments in Urban Air Mobility and Future Air Transport
The push toward urban air mobility, including passenger drones and air taxis, is creating new opportunities for UTM solutions, as these systems are essential for managing high-density aerial traffic in metropolitan areas and supporting advanced air transport innovation.
Expansion of Drone Applications in Public and Emergency Services
The rapid adoption of drones for medical supply transport, disaster response, and law enforcement is increasing the need for advanced UTM systems that can safely coordinate diverse and mission-critical drone operations across both public and commercial sectors.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the unmanned traffic management market, and what is its projected size in 2032?
Which unmanned traffic management market segment held the largest share in 2024?
What are the primary factors fueling the growth of the unmanned traffic management market?
Who are the leading companies in the unmanned traffic management market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Commercial
- 1.2.2 Government
- 1.2.3 Defense
- 1.3 By Component
- 1.3.1 Hardware
- 1.3.2 Software
- 1.3.3 Services
- 1.4 By Application
- 1.4.1 Logistics and Transportation
- 1.4.2 Agriculture
- 1.4.3 Surveillance and Monitoring
- 1.4.4 Urban Air Mobility
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1210 million → 2032: USD 6409.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Unmanned Traffic Management Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Unmanned Traffic Management Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Unmanned Traffic Management Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Unmanned Traffic Management Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Unmanned Traffic Management Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Unmanned Traffic Management Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Unmanned Traffic Management Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Unmanned Traffic Management Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1210 million → 2032: USD 6409.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Unmanned Traffic Management Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Commercial
- 12.3.7.2 Government
- 12.3.7.3 Defense
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hardware
- 12.4.7.2 Software
- 12.4.7.3 Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Logistics and Transportation
- 12.5.7.2 Agriculture
- 12.5.7.3 Surveillance and Monitoring
- 12.5.7.4 Urban Air Mobility
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Unmanned Traffic Management End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Unmanned Traffic Management Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Unmanned Traffic Management Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Unmanned Traffic Management Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Leonardo S.p.A.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 L3Harris Technologies, Inc.
- 18.4 Thales Group
- 18.5 Lockheed Martin Corporation
- 18.6 Unifly NV
- 18.7 Airbus SE
- 18.8 Frequentis AG
- 18.9 OneSky Systems
- 18.10 AirMap, Inc.
- 18.11 RTX Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

