
Governed profiles become the context layer for brand AI
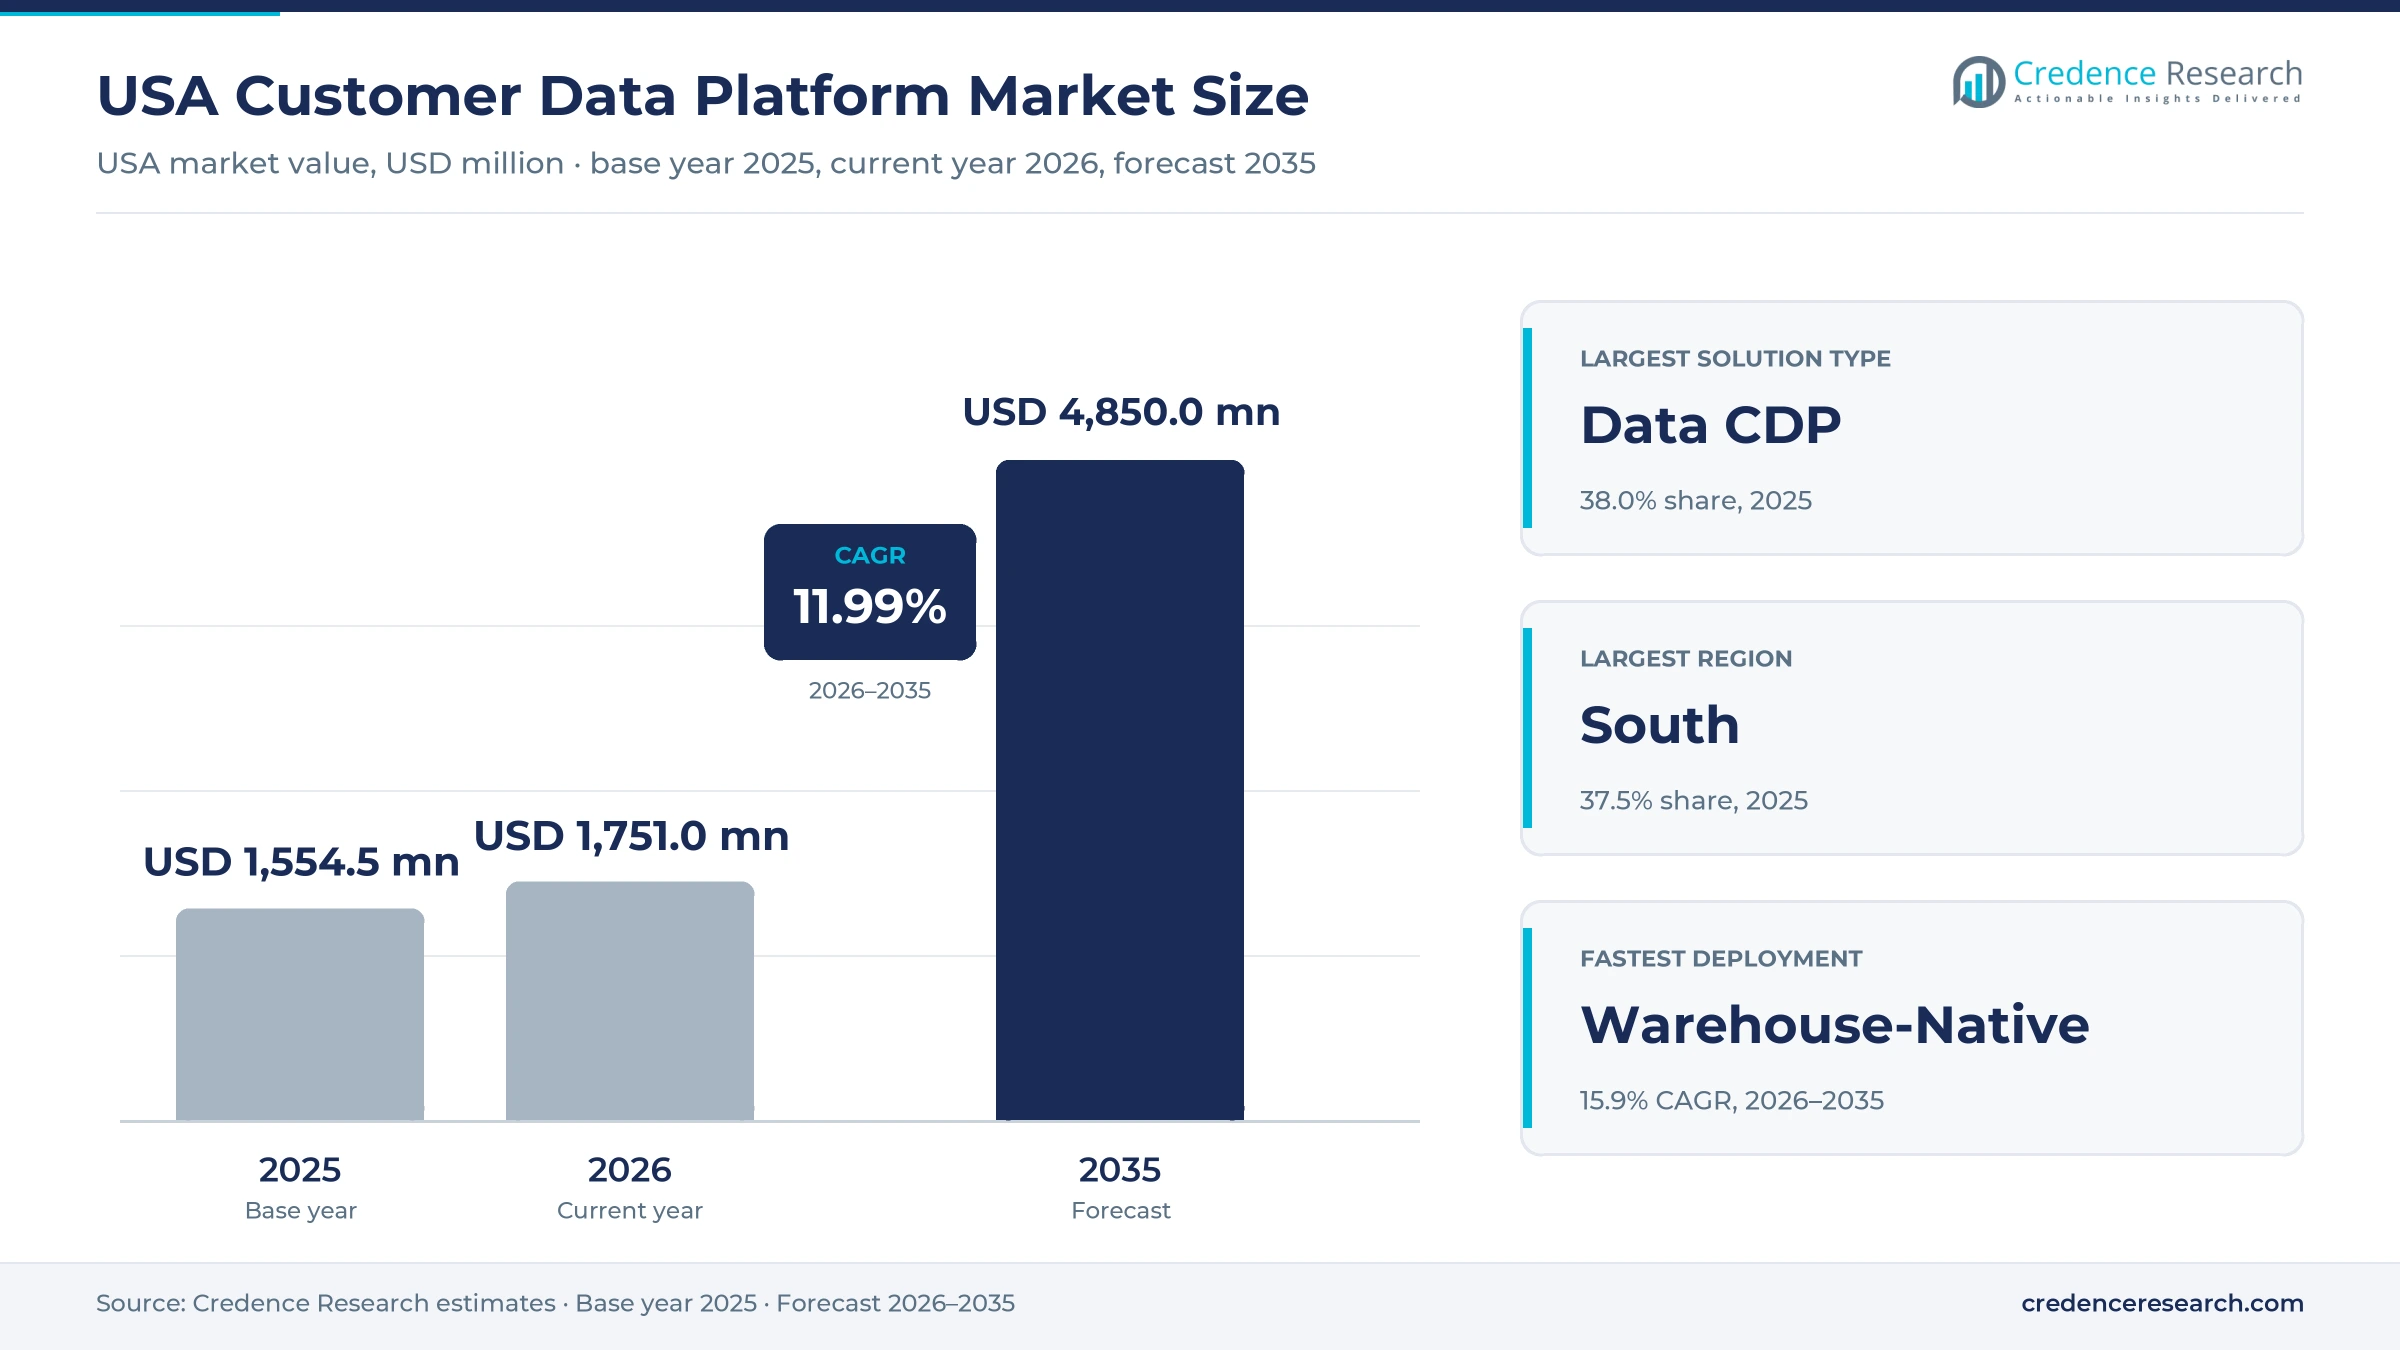
The USA customer data platform market was valued at USD 1.55 billion in 2025 and is projected to increase from USD 1.75 billion in 2026 to USD 4.85 billion by 2035, registering a CAGR of 11.99% during 2026–2035. Demand comes from retailers, banks, media firms and travel brands that need one consented profile per customer to run loyalty programs, personalize digital journeys and feed AI agents with reliable context. The South held the largest regional share, 37.5% in 2025, because it has the largest population of the four Census regions and the fastest population growth since 2020. The West is the fastest-growing region at 12.5% a year as California privacy rules and an early-adopting technology sector push brands toward governed profile data. The most important commercial change is the move from standalone profile stores toward warehouse-native designs and AI context services, which lets buyers keep records in their own cloud warehouse while vendors charge for identity resolution, activation and agent access.
Unified, consented profiles that other systems act on set the scope
The market counts software and subscription fees paid by organizations in the United States for packaged systems that collect first-party customer records, resolve identities into persistent profiles, and make those profiles available to marketing, service and analytics tools. Four product types are tracked, namely data, analytics, campaign and delivery systems, sold as vendor-hosted software as a service, as warehouse-native applications or in private cloud deployments.
Customer relationship management seats, per-message email and SMS fees, media spending, warehouse compute bought directly from cloud providers and third-party consulting fees sit outside the count. The value chain runs from collection tags and cloud warehouses through identity resolution and profile services to the marketing, service and AI applications that act on each profile.
USA Customer Data Platform Market Insights
- Spending rises from USD 1.55 billion in 2025 to USD 4.85 billion by 2035, an 11.99% CAGR, as brands rebuild customer records for state privacy rules and enterprise AI agents.
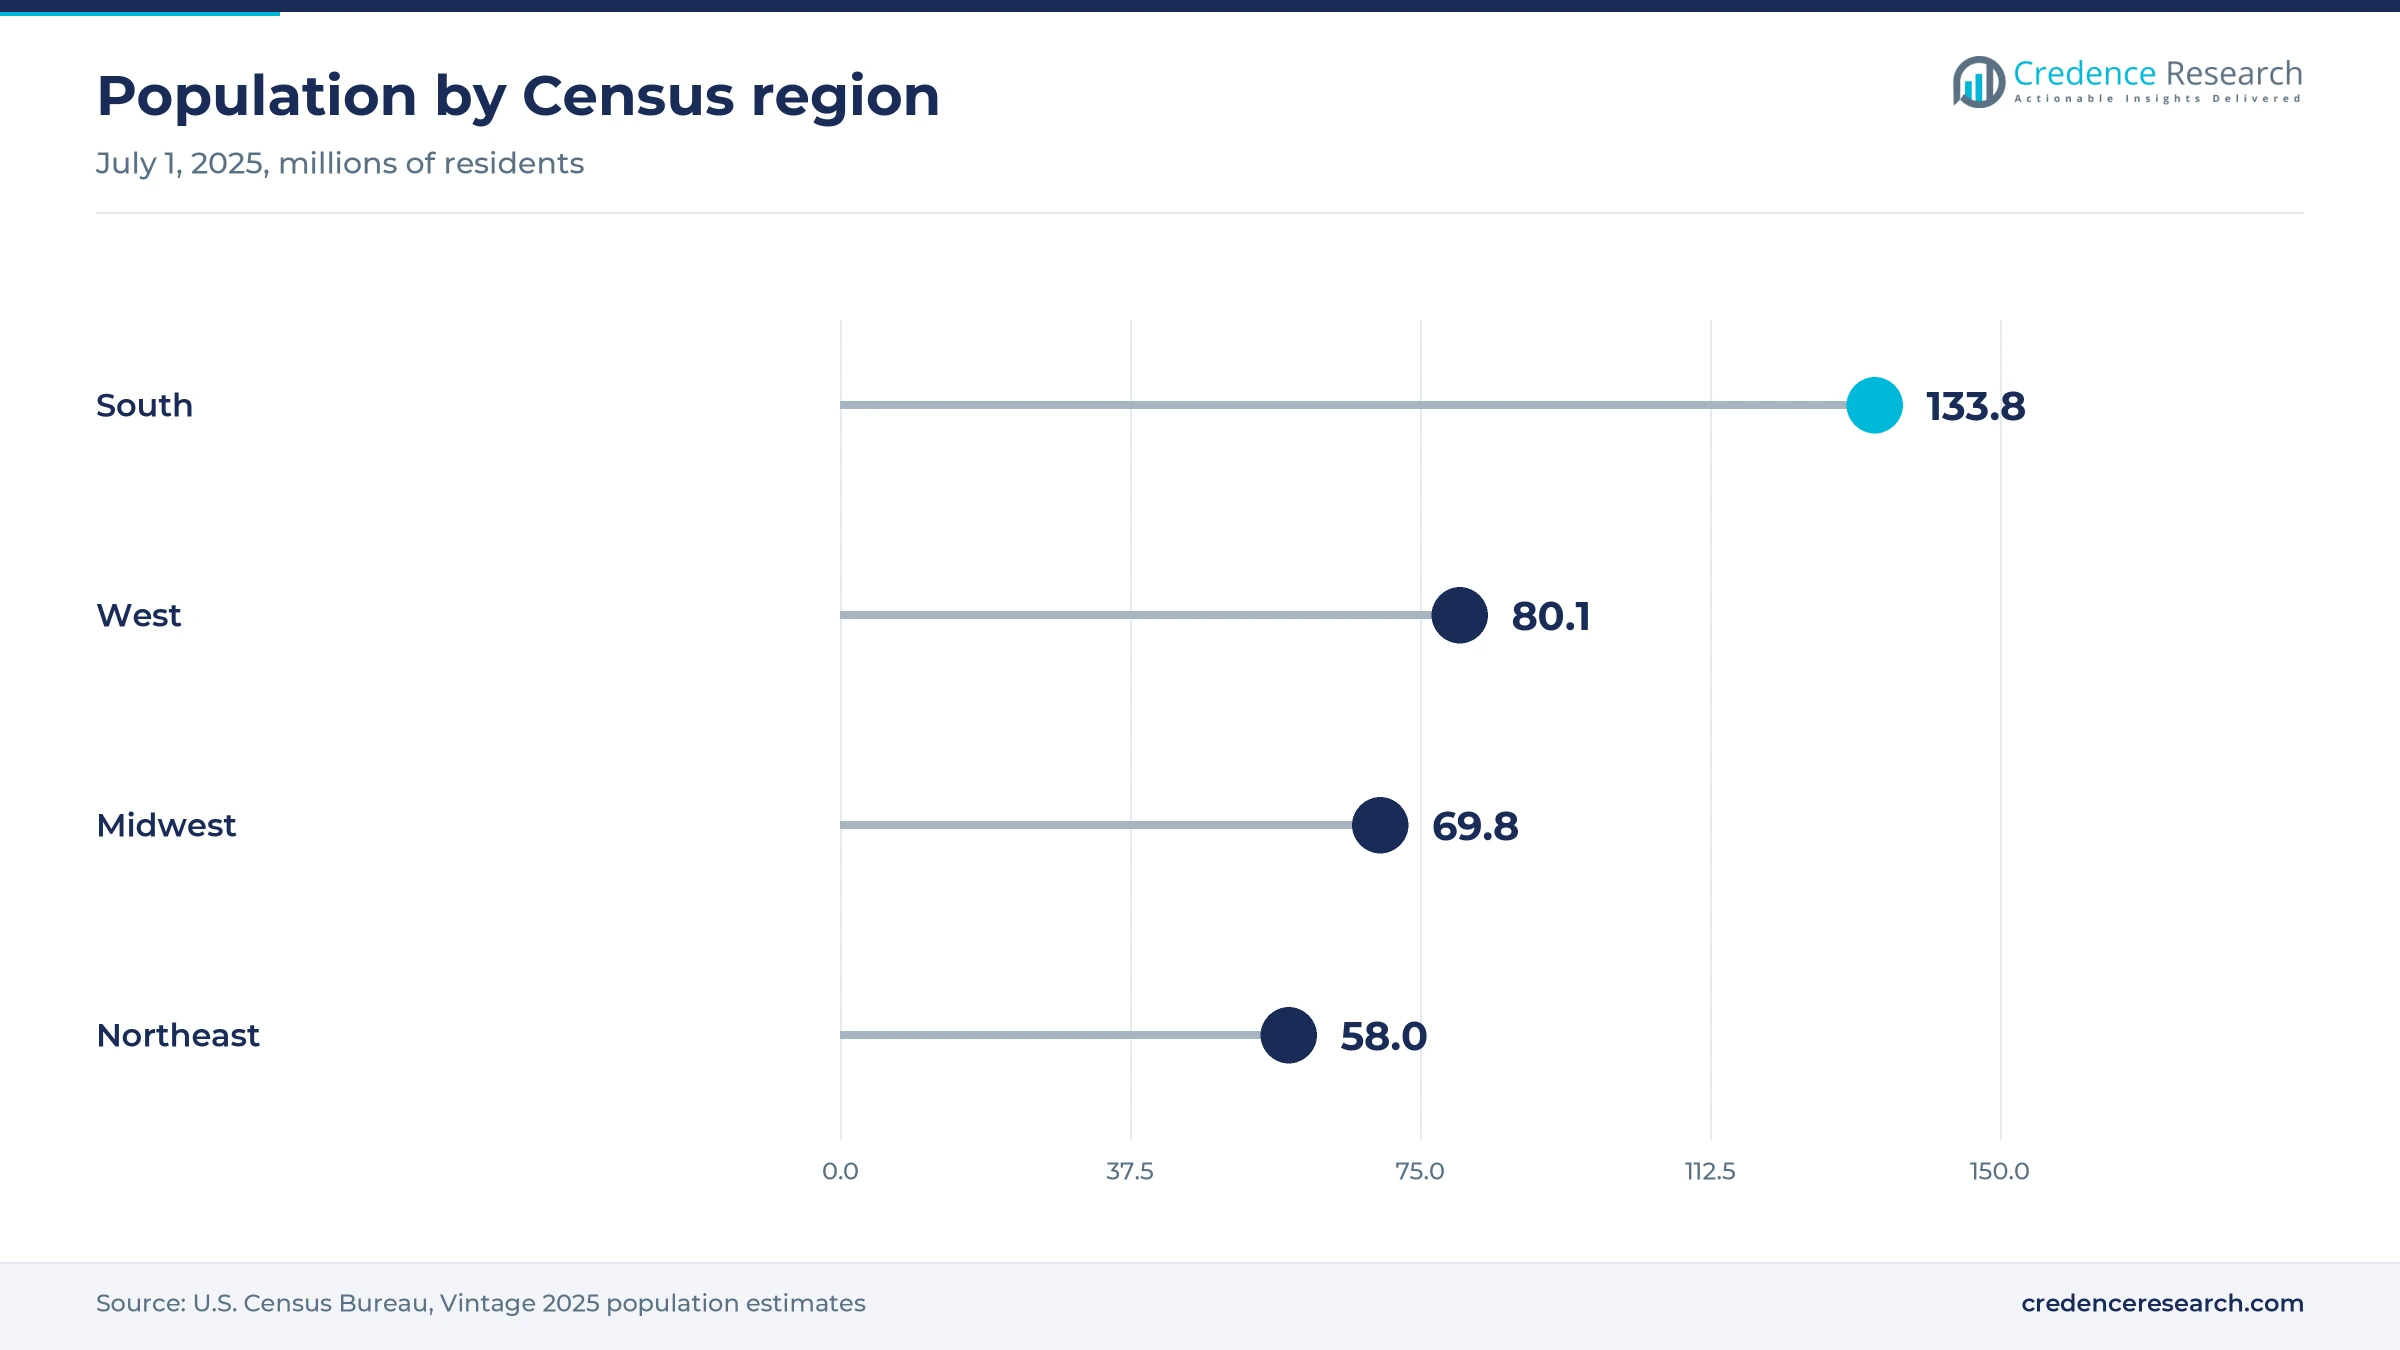
- The South held 37.5% of 2025 value, supported by a population of 133.8 million in July 2025, the largest of the four Census regions.
- Data CDP accounted for 38.0% of 2025 value, while Vendor-Hosted SaaS carried 68.0% of spending in the same year.
- Salesforce said Data 360 ingested 32 trillion records in its fiscal third quarter of 2026, up 119% year over year, as interaction volume kept rising.
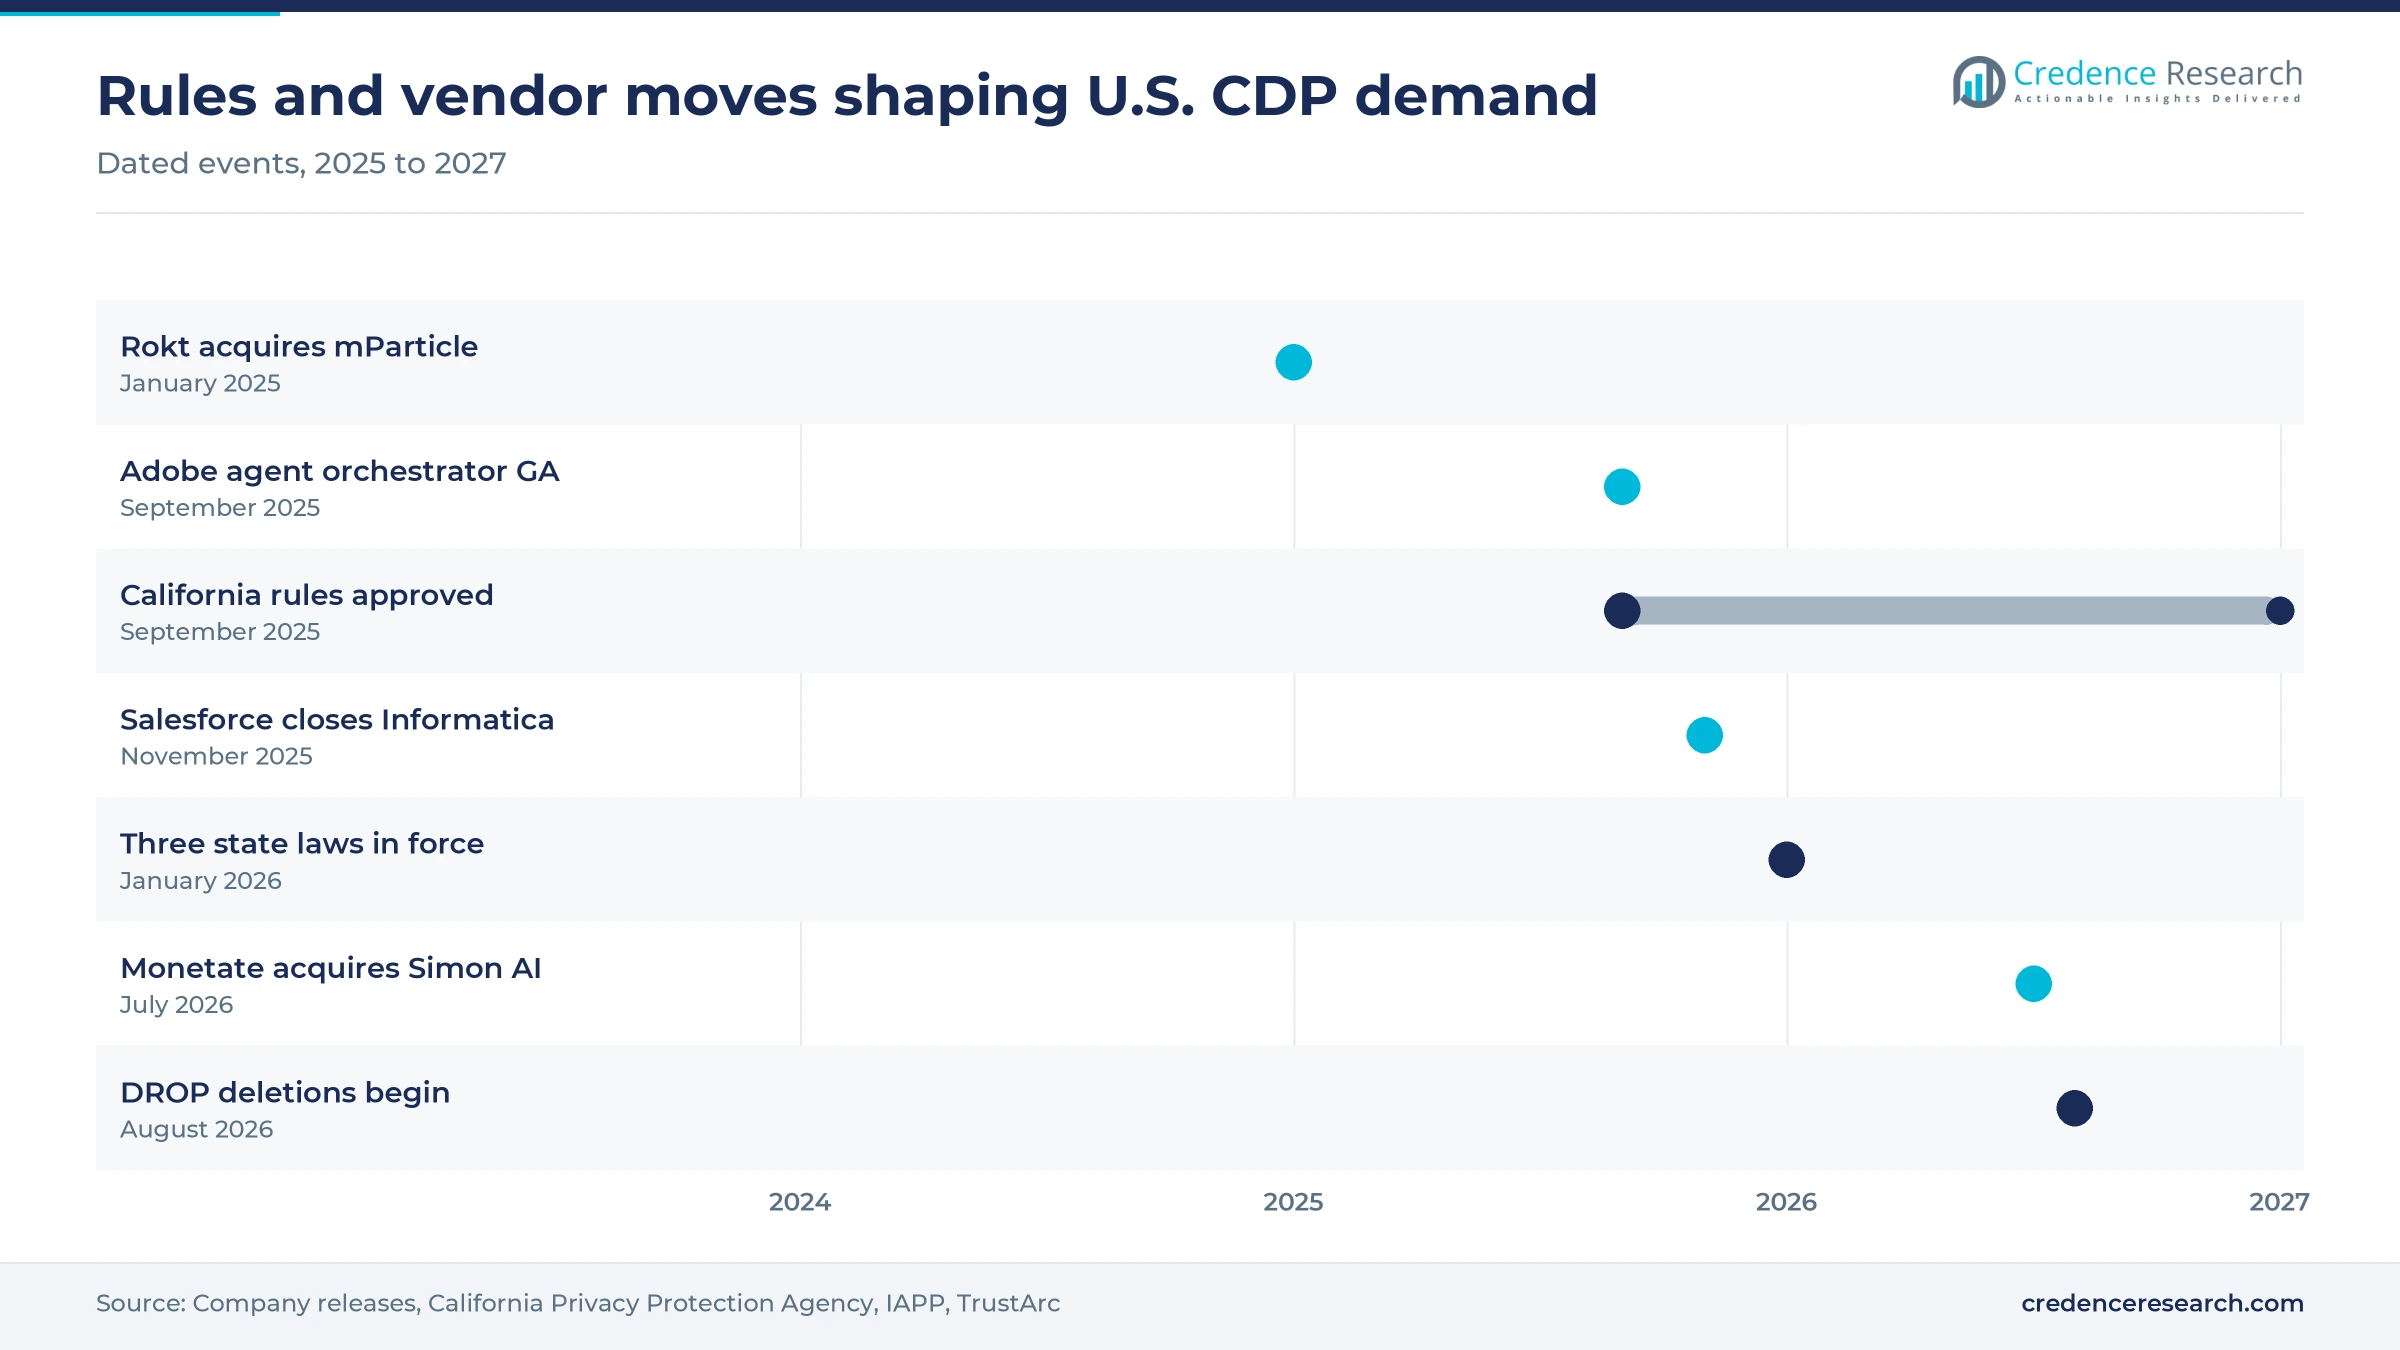
- Four ownership changes between January 2025 and July 2026, covering mParticle, Informatica, Blueshift and Simon AI, show buyers of profile and delivery layers consolidating supply.
Data CDPs lead while warehouse-native designs grow fastest
Why do data CDPs hold the largest share of spending?
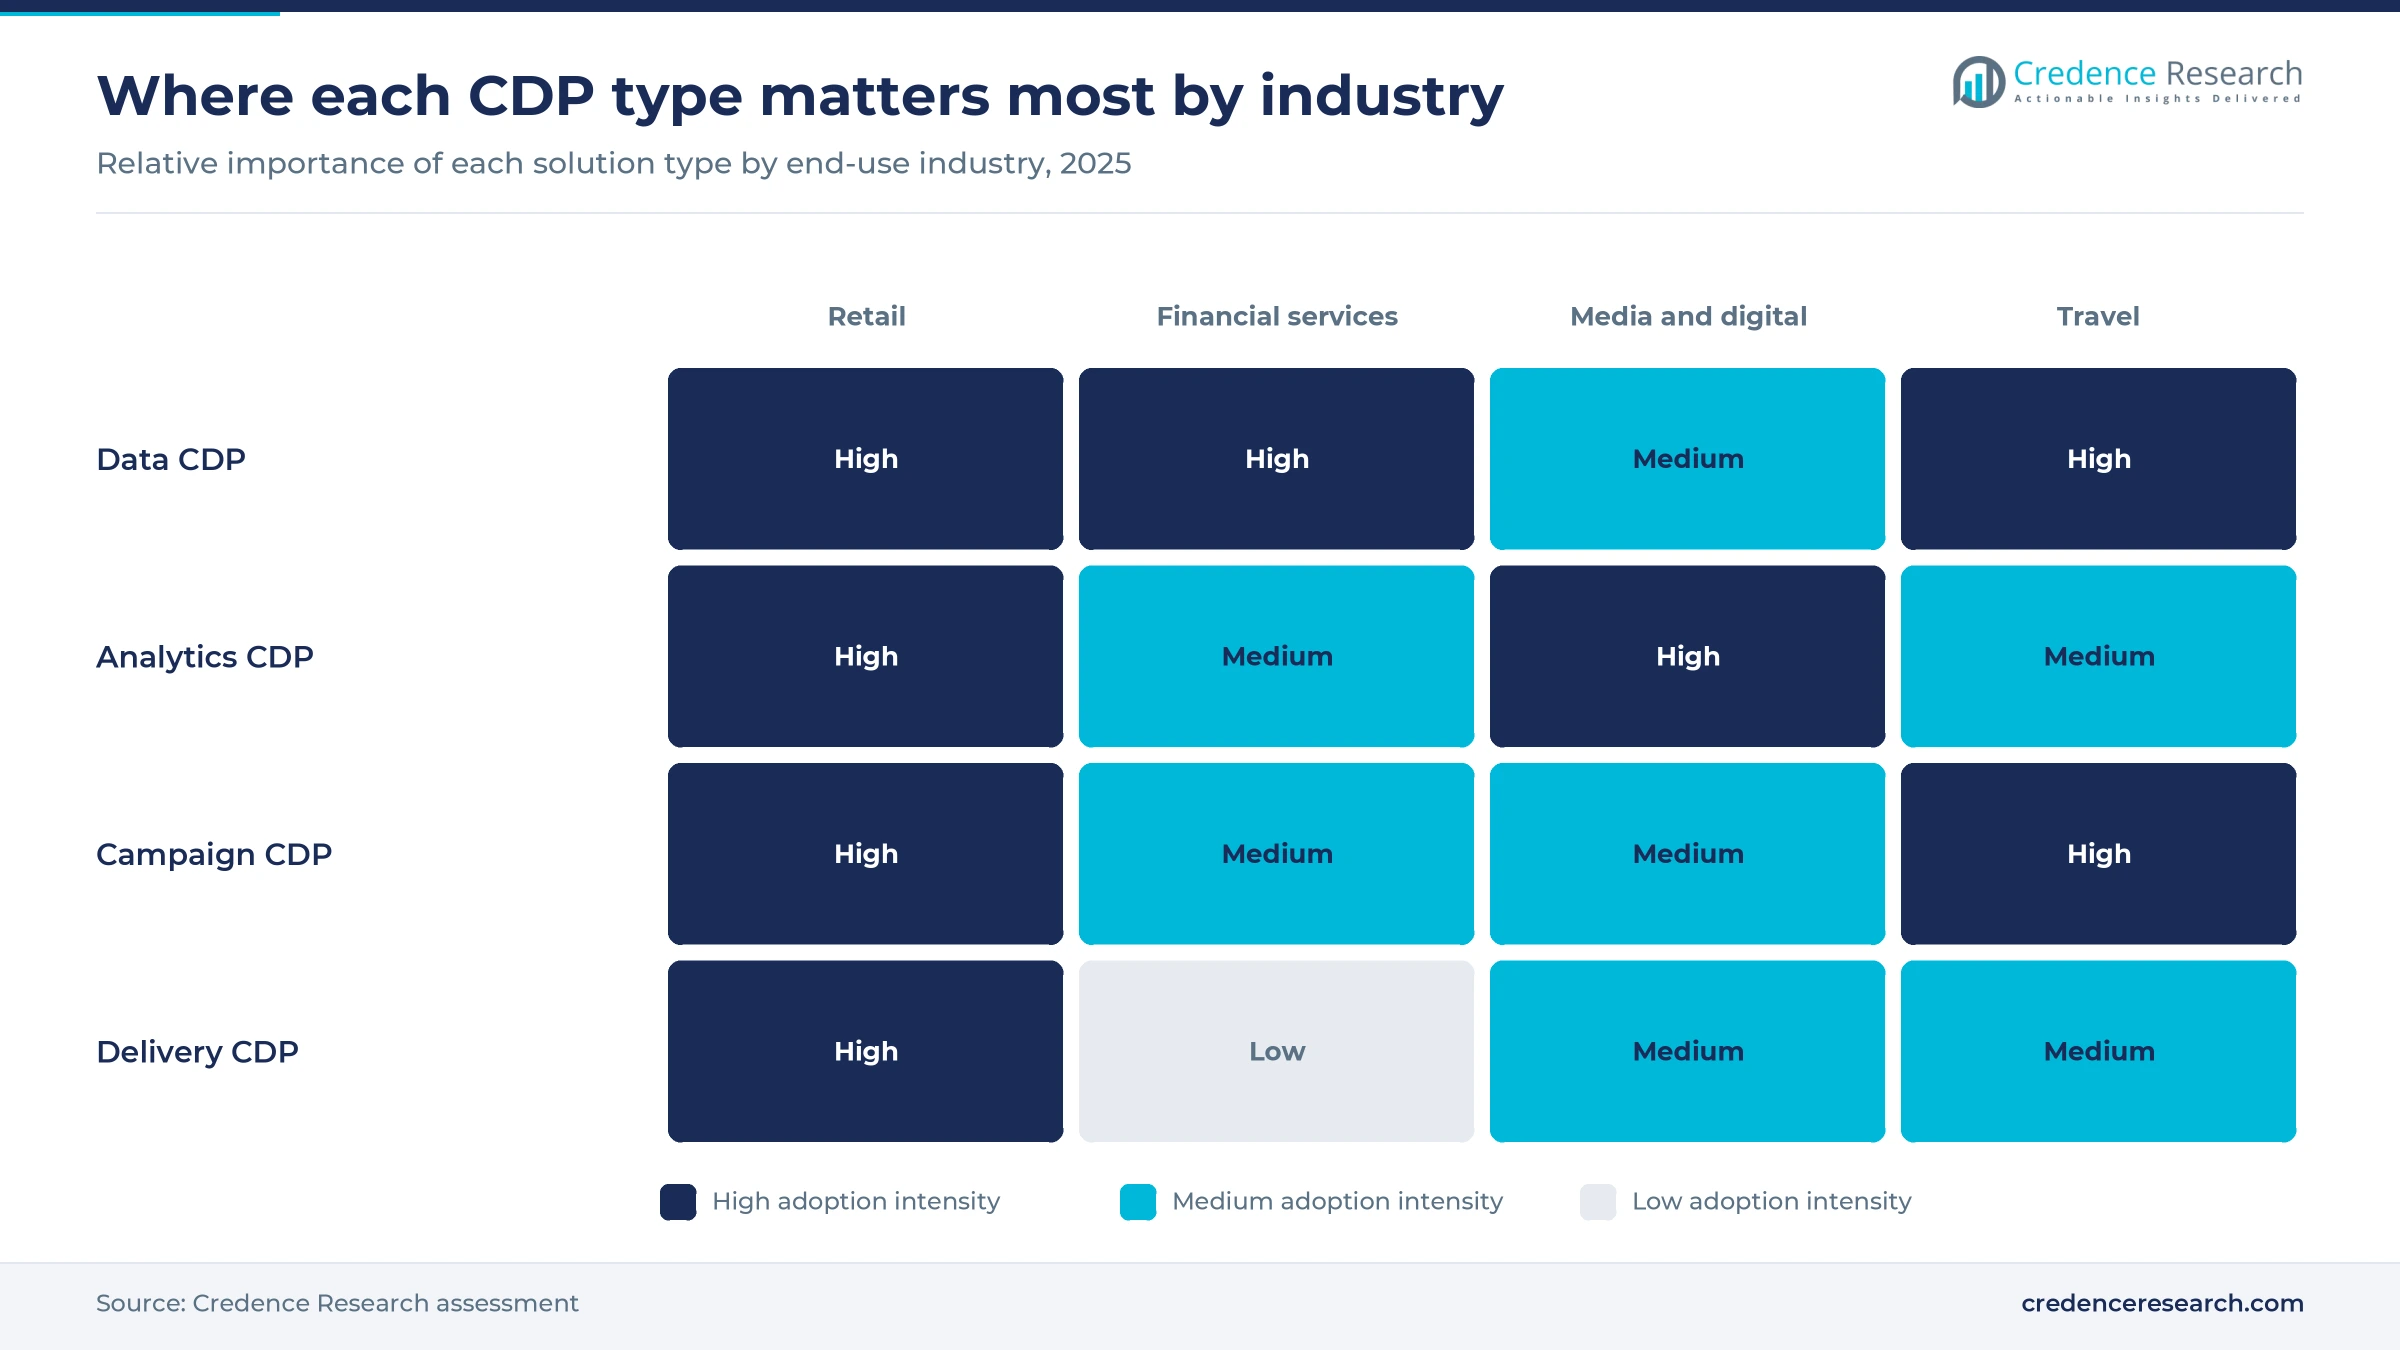
Based on solution type, the market is categorized into data CDP, analytics CDP, campaign CDP and delivery CDP. Data CDP led with 38.0% of 2025 value because identity resolution and profile storage form the layer every other use depends on, and Salesforce completed its Informatica acquisition on Nov. 18, 2025, to bring enterprise data management into that layer. Delivery CDP grows fastest at 13.6% a year as profile vendors buy channel execution, and BlueConic announced on June 17, 2026, that it had acquired Blueshift, creating a group that serves more than 600 customers across email, push, SMS and web.
How are U.S. buyers choosing between hosted and warehouse-native designs?
Based on deployment model, the market is categorized into vendor-hosted SaaS, warehouse-native and private cloud. Vendor-Hosted SaaS led with 68.0% of 2025 value because vendors ship AI features to hosted platforms first, and Adobe said in September 2025 that more than 70% of eligible Experience Platform customers already used its AI Assistant. The deployment split is a Credence Research estimate, because vendors do not report hosted and warehouse-native revenue separately. Warehouse-Native grows fastest at 15.9% a year as brands query records where they already sit, and Salesforce said Zero Copy access accounted for 15 trillion records in its fiscal third quarter of 2026, up 341% year over year.
Which industries spend the most on unified profiles?
Based on end-use industry, the market is categorized into retail and consumer brands, financial services and insurance, media and digital services, travel and hospitality, and healthcare and remaining sectors. Retail and Consumer Brands led with 36.0% of 2025 value because retailers must join store, online and loyalty records, and L.L.Bean said on Feb. 10, 2026, that it selected Amperity to personalize email, direct mail, web, loyalty and catalog journeys. Financial Services and Insurance grows fastest at 12.9% a year as banks merge branch, app and call records into one customer view, and M&T Bank selected Amperity on Aug. 5, 2025, to combine online and offline interactions, FF News reported.
How do revenue models shape what vendors earn?
Based on revenue model, the market is categorized into profile-based subscription, event-based subscription, consumption credits and flat platform subscription. Profile-Based Subscription led with 44.0% of 2025 value because enterprise buyers budget by the number of known customers, and Salesforce offers profile-based pricing alongside credit-based and dynamic models for its profile product. Consumption Credits grows fastest at 14.9% a year as AI agent work is metered, and Adobe said in April 2026 that more than 1,770 customers were entitled to use its agents under a credit-based pricing model, MarTech reported.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Solution Type | Data CDP | 38.0% | Delivery CDP | 13.6% |
| By Deployment Model | Vendor-Hosted SaaS | 68.0% | Warehouse-Native | 15.9% |
| By End-Use Industry | Retail and Consumer Brands | 36.0% | Financial Services and Insurance | 12.9% |
| By Revenue Model | Profile-Based Subscription | 44.0% | Consumption Credits | 14.9% |
Profiles, events and credits set what buyers pay
Pricing combines a platform fee with a volume meter, and the meter differs by vendor model. Entry tools charge by monthly visitors or events, enterprise suites charge per 1,000 known profiles a year, and AI and processing work increasingly draws on prepaid credits. Salesforce lists three Data 360 pricing models, namely credit-based, dynamic and profile-based, which lets buyers trade budget certainty for flexibility. Profile growth, event volume and agent usage move bills more than list prices do. Margins sit with vendors that sell identity resolution and activation on top of storage, since warehouse-native buyers already pay their cloud provider for compute.
| Offer or plan | Typical price or fee | Basis |
|---|---|---|
| Twilio Segment Connections Free | USD 0 for up to 1,000 visitors a month | Twilio pricing page, November 2026 |
| Twilio Segment Connections Team | From USD 120 a month for 10,000 visitors | Twilio pricing page, November 2026 |
| Salesforce Data 360 profiles | USD 240 per 1,000 profiles a year | Salesforce pricing page, November 2026 |
| Salesforce Data 360 enterprise profiles | USD 420 per 1,000 profiles a year | Salesforce pricing page, November 2026 |
| Salesforce Flex Credits | USD 500 per 100,000 credits | Salesforce pricing page, November 2026 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Commerce volume, privacy rules and AI agents lift demand
Digital commerce interaction density lifts profile volumes
Every online order, app session and loyalty scan adds events that must be stitched to a known profile, so interaction volume sets the scale of CDP workloads. E-commerce accounted for 17.1% of U.S. retail sales in the second quarter of 2026, the Census Bureau reported, and online sales rose 12.2% from a year earlier while total retail sales grew 6.7%. Salesforce said Data 360 ingested 32 trillion records in its fiscal third quarter of 2026, up 119% year over year. Retailers that run store, online and loyalty programs feel this growth first, which is why Retail and Consumer Brands hold 36.0% of spending. Vendors that price by events or records gain most when traffic rises, while profile-priced contracts follow the volume curve with a lag.
Governed customer data operations become a compliance duty
State and California rules now require brands to show which consent, opt-out and deletion status applies to every record, and that bookkeeping runs through profile systems. Indiana, Kentucky and Rhode Island privacy laws took effect on Jan. 1, 2026, TrustArc noted. California regulators announced on Sept. 23, 2025, that rules on risk assessments and automated decisionmaking had been approved, with automated decisionmaking duties starting on Jan. 1, 2027. From Aug. 1, 2026, registered data brokers must process deletion requests filed through the state DROP system, the IAPP reported, which pushes brands that buy or enrich audiences to record suppression status against every profile. Vendors with consent logs and audit trails now win budget from legal and data teams as well as marketing.
Customer context for enterprise AI raises contract values
AI agents can only personalize offers or answer service requests when they read a current, consented profile, which turns the CDP into the context layer for enterprise AI. AI use among U.S. businesses reached 19.8% in the period ending May 3, 2026, and 37% of firms with at least 250 employees reported using it, according to the Census Bureau. Amperity introduced its AI Assistant on Jan. 8, 2026, letting marketers build segments and journeys in plain language on profiles that more than 400 brands rely on. Twilio made its Segment Conversation Memory integration generally available on Oct. 5, 2026, so AI and human agents can look up profile traits during live conversations. Large enterprises adopt these tools first, so contract values rise before account counts do.
Loss of third-party signals raises the value of own identity
Brands that relied on third-party cookies and shared identifiers now need their own persistent identity, and CDPs supply the identity graph behind that shift. Google said on Oct. 17, 2025, that it would retire Attribution Reporting, IP Protection and other Privacy Sandbox technologies after low adoption, which leaves advertisers to build measurement on first-party records. Rokt, which places offers at online checkout, bought mParticle for USD 300 million on Jan. 16, 2025, AdExchanger reported, to add real-time profile data to its commerce network. Hightouch listed Autotrader, Cars.com and PetSmart among its customers in July 2025, brands that send warehouse audiences to marketing and ad tools. Media buyers that run programmatic advertising campaigns now feed these consented audiences into ad platforms instead of rented segments.
Warehouse-native designs and delivery deals reshape supply
Brands keep profile data inside their own warehouses
Large brands are shifting profile work into their own cloud warehouses to avoid copying records into another vendor store, creating openings for activation and context services that sit on top. Hightouch raised USD 150 million in a Series D round at a USD 2.75 billion valuation in April 2026, ContentGrip reported, after growth above 100% in each of the two prior years. Snowflake Ventures and Capital One Ventures invested in the company on July 29, 2025, to bring AI decisioning agents into the Snowflake AI Data Cloud. Tealium launched its Context API on June 9, 2026, adding a managed Model Context Protocol server that serves warehouse records to AI agents. Packaged suites respond with zero-copy connectors, which narrows their storage margin but protects their activation fees.
Profile vendors buy decisioning and delivery tools
Specialists are merging profile storage with decisioning and channel execution because buyers want one contract that both knows the customer and acts on that knowledge. Monetate acquired Simon AI, formerly Simon Data, in a deal announced on July 30, 2026, linking audiences for lifecycle email, SMS and ads to on-site personalization and experiments. Treasure Data renamed itself Treasure AI on April 20, 2026, and launched AI Studio with more than 50 prebuilt skills that require human approval before activation. The Blueshift purchase described in the segment section follows the same logic of owning delivery. Independent data CDP vendors without delivery tools face pressure to partner or sell, while buyers gain fewer integrations at the cost of thinner vendor choice.
Banks and insurers need agent-ready customer profiles
Banks and insurers hold rich account and transaction records yet often lack unified marketing profiles, which leaves room for vendors that pair governance with AI query tools. Extraco Banks, a Texas community bank, ingested 15 data sources into Treasure Data, built 60,000 unified profiles and reported a 27% year-over-year rise in campaign conversion rates, according to a Treasure AI case study published on Feb. 19, 2026. Finance and insurance businesses already lead AI use, at 33.9% in the period ending May 3, 2026, well above the national rate, the Census Bureau reported. The Capital One Ventures stake in Hightouch, noted above, signals lender interest in warehouse-native activation. Vendors that offer audit trails and private cloud options can win these regulated buyers at higher contract values.
Contact centers become the next profile buyers
Service teams are the next large buyer group, because agents handling calls and chats need the same profile that marketing teams use. Adobe said on April 20, 2026, that Real-Time CDP now adds unstructured data such as call center logs and chat transcripts to profiles, and that profile refresh time fell from three days to 14 seconds, MarTech reported. Tealium lists contact center assistance and next-best-action decisioning among the uses of its Context API, described above. Vendors that feed profiles into conversational AI tools can sell to service budgets that marketing systems rarely reached. Information-sector firms, 39.7% of which used AI in the period ending May 3, 2026, according to the Census Bureau, are early candidates for these deployments.
Penalties, metered bills and dirty data slow projects
Patchwork state penalties raise compliance costs
Compliance costs rise with every new state law, because Rhode Island allows fines of up to USD 10,000 per violation, while Indiana and Kentucky allow up to USD 7,500 with 30-day cure periods. California also requires businesses to attest to completed risk assessments by April 1, 2028. Midmarket brands without privacy staff are most exposed, since each rule set needs its own consent and opt-out logic in the profile store, which slows launches and diverts budget away from new use cases.
Consumption meters make annual bills hard to forecast
Usage pricing shifts budget risk onto buyers, because Salesforce sells Flex Credits at USD 500 per 100,000 credits, and ingestion, identity resolution and segmentation can all draw on that pool. A holiday traffic spike or a new AI agent rollout can use credits faster than finance teams planned. Retailers with sharp seasonal peaks are most exposed, and some respond by capping event collection, which limits the profile depth that personalization and AI use cases need.
Poor data quality stalls AI and profile projects
Data quality remains the main brake on returns, because 75% of organizations cited data integration and quality as their top AI implementation challenge in a March 2026 Adobe study, MarTech reported. Projects that inherit duplicate records and missing consent flags take longer to reach activation. Enterprises with many legacy systems, such as banks and multi-brand retailers, are most exposed and they often fund separate cleansing work before the profile store produces audiences that teams can use.
Vendor consolidation creates roadmap risk for buyers
Ownership changes create roadmap risk, because four CDP-related vendors changed hands between January 2025 and July 2026, namely mParticle, Informatica, Blueshift and Simon AI. Monetate says Simon AI continues as a separate product with its own team and roadmap, but buyers cannot know how long that will hold. Brands on multi-year contracts with acquired vendors are most exposed, and many now seek exit and data-portability clauses before they renew.
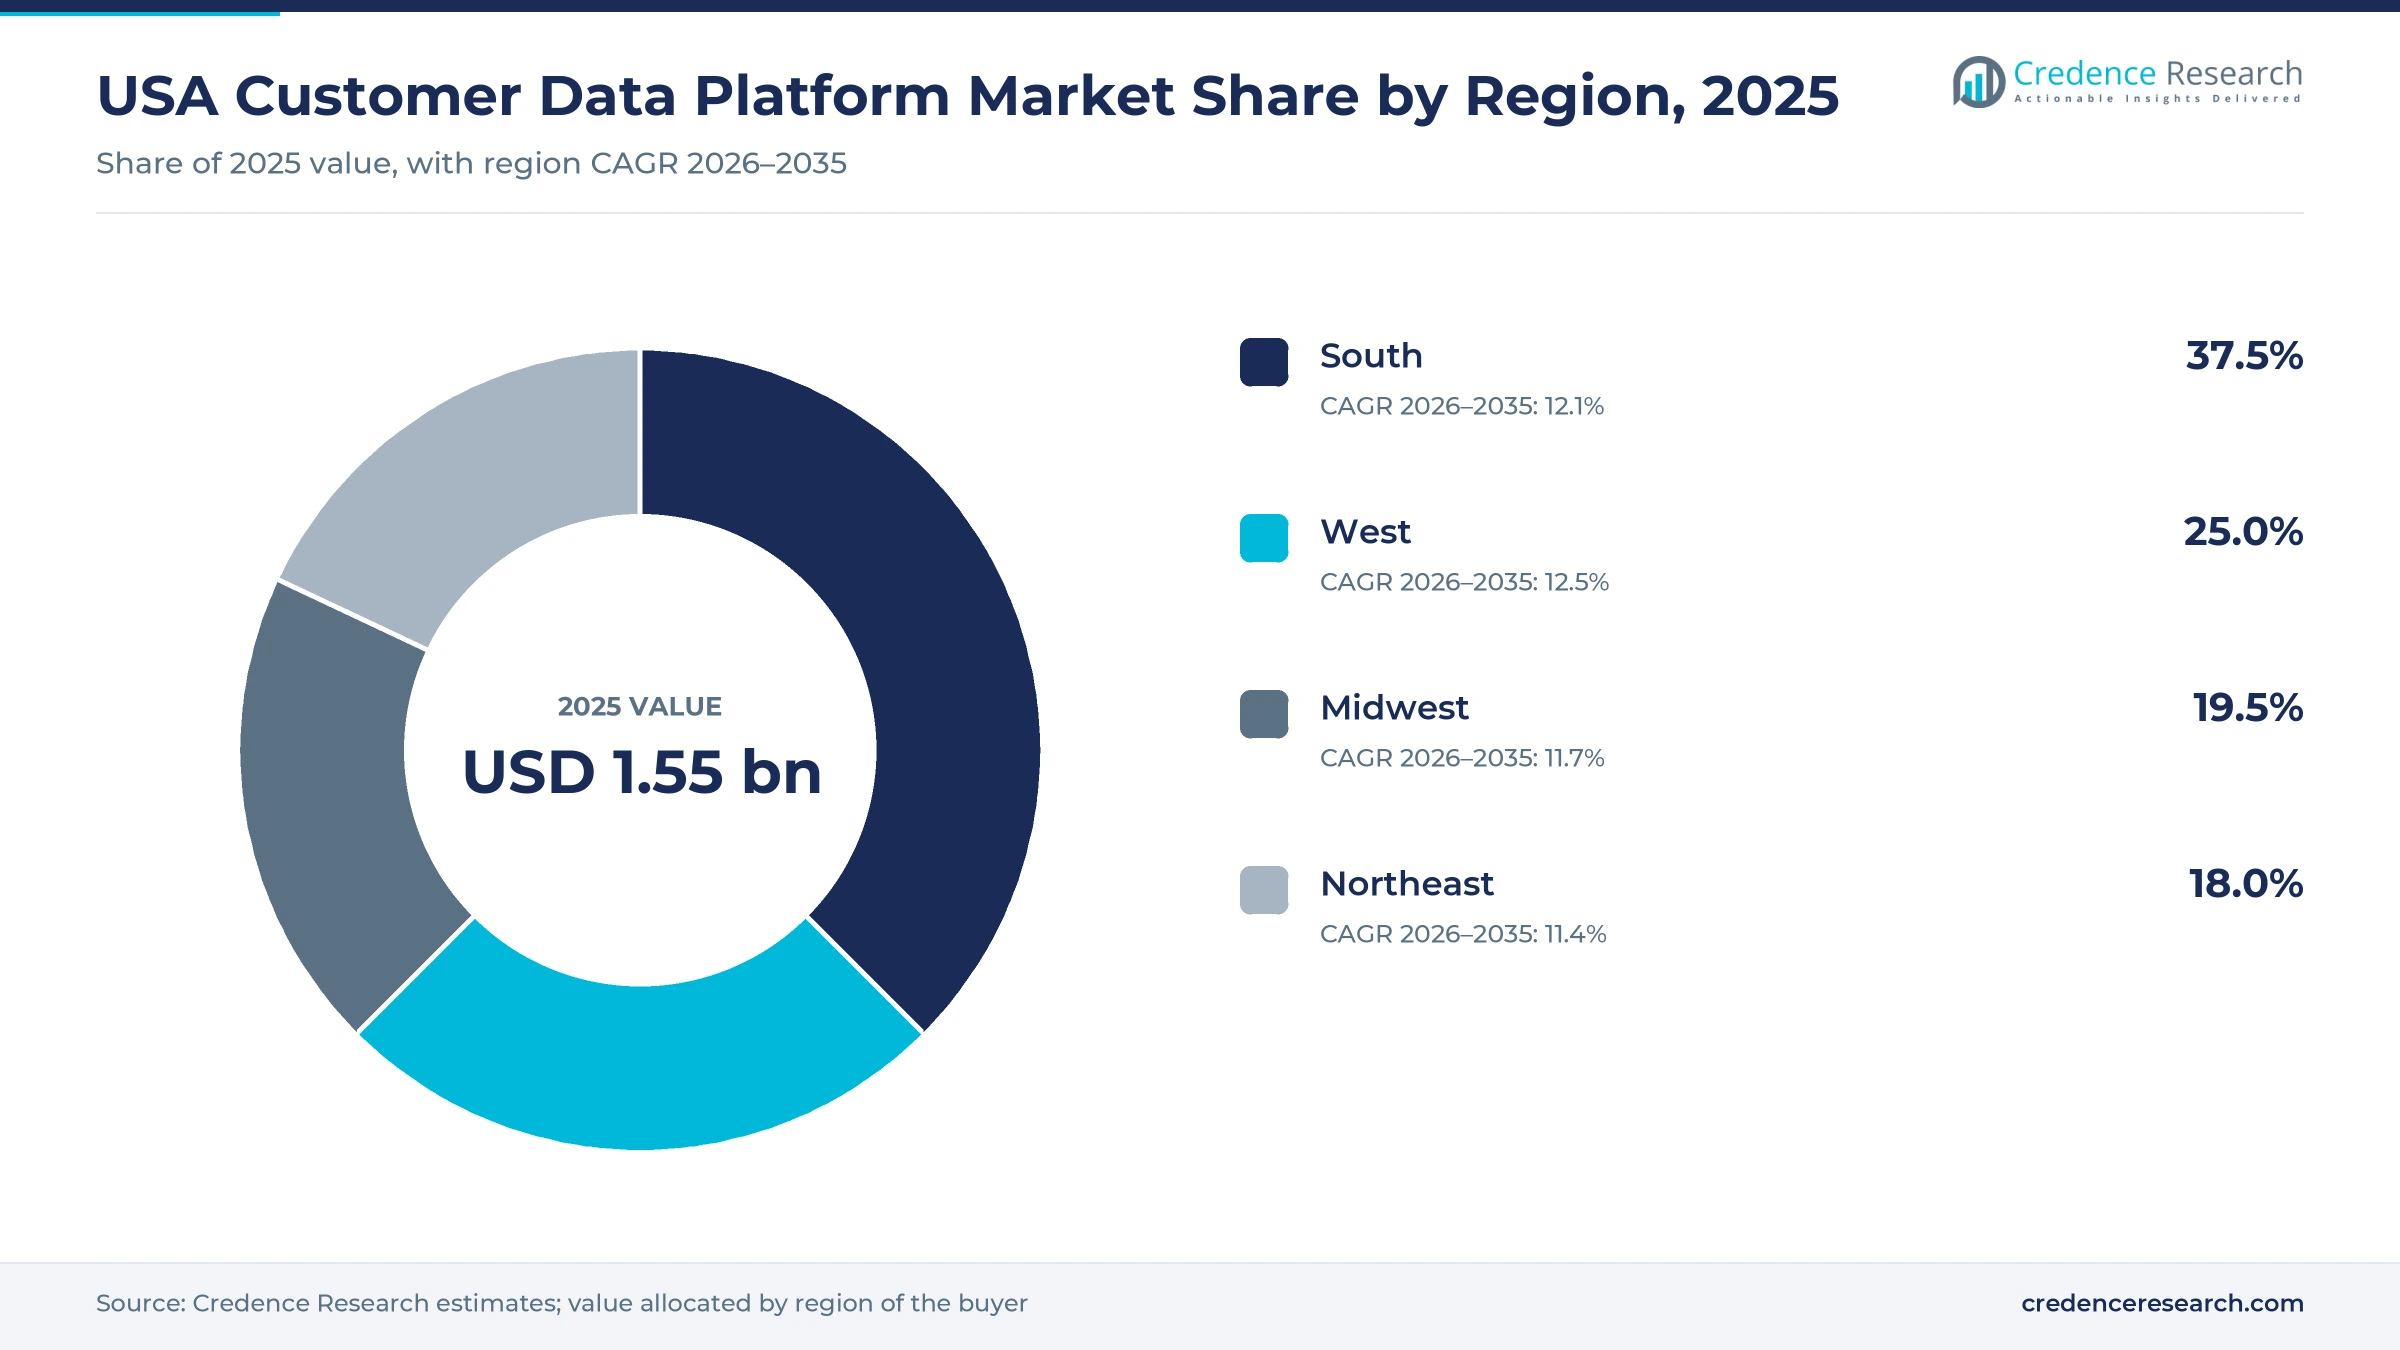
The South leads on population as the West grows fastest
No public statistic reports CDP spending by Census region, so regional shares are Credence Research estimates built from population, the location of retail, banking and media buyers, and supplier presence across the four Census regions. The South and the West together held 62.5% of 2025 value.
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| South | 0.58 | 37.5% | 12.1% |
| West | 0.39 | 25.0% | 12.5% |
| Midwest | 0.30 | 19.5% | 11.7% |
| Northeast | 0.28 | 18.0% | 11.4% |
The South leads on the largest and fastest-growing population
The South held 37.5% of 2025 value and grows at 12.1% a year. The region counted 133.8 million residents on July 1, 2025, and grew 6.0% from April 2020, the fastest rate of the four Census regions, according to the Census Bureau. It was also the only region whose under-18 population grew, which keeps adding new customer records for retailers, banks and travel brands to resolve. The region's share is a Credence Research estimate weighted by population, because no vendor reports bookings by Census region, and growth tracks new household formation more than new privacy rules.
The West grows fastest on privacy rules and regional buyers
The West is the fastest-growing region at 12.5% a year and held 25.0% of 2025 value. California rules, described in the drivers, make the state the first test market for governed profiles, and more than 242,000 Californians had filed DROP deletion requests by Feb. 27, 2026, the IAPP reported. Regional buyers are already active, as Amperity names Washington state-based Alaska Airlines and BECU among its customers, showing travel and credit union demand for identity-led profiles. The region had 80.1 million residents in July 2025, the second-largest consumer base.
The Midwest modernizes retail loyalty records
The Midwest held 19.5% of 2025 value and grows at 11.7% a year. Regional retailers are rebuilding loyalty data, and Fleet Farm, a Midwest retailer, selected Amperity on March 18, 2025 to unify store, home shipping and loyalty records. The region had 69.8 million residents in July 2025 but grew only 1.1% from April 2020, so brands compete for share of existing customers rather than new households. Indiana's privacy law, noted earlier, adds consent duties for firms that sell to Indiana residents.
The Northeast relies on established consumer brands and banks
The Northeast held 18.0% of 2025 value and grows at 11.4% a year. The region grew only 0.7% from April 2020 to 58.0 million residents, the slowest of the four Census regions, and it was the only region to lose residents aged 18 to 24. Demand rests on established consumer brands and banks, and Northeast-based Wegmans Food Markets and The Hershey Company were named as customers in Adobe's September 2025 release on its agents. Slower household growth keeps regional growth below the national rate.
Informatica, Simon AI and context APIs mark 2025 and 2026
| Development | Status and market relevance |
|---|---|
| In September 2025, Adobe announced general availability of AEP Agent Orchestrator, with agents surfaced in Real-Time CDP and Journey Optimizer. | Launch, generally available to enterprise customers |
| In November 2025, Salesforce completed its acquisition of Informatica. | Completed, data management added to Data 360 |
| In June 2026, Tealium launched its Context API with a managed Model Context Protocol server. | Launch, available globally |
| In July 2026, Monetate acquired Simon AI, formerly Simon Data. | Completed, terms not disclosed |
| In October 2026, Twilio made the Segment Conversation Memory integration generally available. | Launch, general availability |
Identity, zero-copy access and MCP servers set value
- Identity resolution merges records from stores, apps, call centers and loyalty programs into one persistent profile, which every downstream use depends on.
- Zero-copy federation lets vendors read records inside a brand's warehouse without duplicating them, which cuts storage costs and governance risk.
- Consent and deletion orchestration tracks opt-outs and deletion requests across systems, so brands can prove compliance with each state rule.
- Model Context Protocol servers expose governed profile data to AI agents with low latency, as the Tealium Context API does.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Suites defend accounts as specialists add AI context
Competition turns on identity accuracy, real-time activation, governance and the ability to feed AI agents, rather than on storage alone. Adobe, Salesforce and Microsoft defend enterprise accounts by bundling profiles with journey orchestration, analytics and agents, and Salesforce added Informatica, as noted above, to deepen that bundle with data management. Amperity competes on identity resolution for retail, travel and banking brands, naming DICK'S Sporting Goods and Wyndham Hotels & Resorts among its customers. Tealium and Treasure AI sell real-time collection and AI tooling on governed profiles, while BlueConic and Simon AI now pair profiles with owned-channel delivery after their 2026 deals. Hightouch and Twilio Segment target data teams that keep records in their own warehouse. Buyers often evaluate these vendors alongside digital marketing software suites, which pushes profile vendors to prove value through measurable activation.
Suites, specialists and warehouse activators split supply
Supply is organized in three groups that compete for the same profile budget. Adobe, Salesforce and Microsoft bundle profile stores with journey, analytics and AI agent tools and sell them through enterprise contracts. Specialists such as Amperity, Tealium, Treasure AI, BlueConic and mParticle compete on identity resolution, real-time collection and industry depth. Hightouch and Twilio Segment lead the activation layer that works with brands' own warehouses. Entry barriers are low for activation tools but high for identity resolution at enterprise scale, so margins concentrate where vendors own the identity graph and the consent record.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Adobe | Enterprise suite | Sells Real-Time CDP with journey, analytics and AI agent tools |
| Salesforce | Enterprise suite | Sells Data 360 profiles, Zero Copy access and Agentforce integration |
| Microsoft (Dynamics 365 Customer Insights) | Enterprise suite | Sells Customer Insights Data profiles unified with Dynamics 365 applications |
| Twilio (Segment) | Developer-focused CDP | Sells Segment event collection, profiles and audience activation |
| Tealium | Real-time CDP specialist | Sells tag-based collection, real-time profiles and the Context API |
| Treasure AI (Treasure Data) | Enterprise CDP specialist | Sells Intelligent CDP with AI Studio and agent tools |
| mParticle (Rokt) | Real-time CDP specialist | Sells mobile and web event collection and real-time profiles |
| Amperity | Identity-led CDP | Sells identity resolution and unified profiles for consumer brands |
| Hightouch | Warehouse-native activation | Sells composable CDP and AI decisioning on brand warehouses |
| BlueConic | Profile and delivery specialist | Sells first-party profiles plus Blueshift cross-channel delivery since 2026 |
| Simon AI (Monetate) | Composable CDP specialist | Sells composable CDP and lifecycle marketing agents as a Monetate company |
Identity and consent ownership decide pricing power
Credence Research's view is that the customer data platform is becoming the governed context layer for enterprise AI rather than a marketing database. Vendors that own identity resolution and consent records will keep pricing power even as storage moves into brand warehouses. The main risk for incumbents is that buyers pay their cloud provider for compute and pay CDP vendors only for activation, which compresses contract values. The main opening is in service centers and banks, where AI agents need the same profiles that marketing teams built. Buyers should favor vendors that support zero-copy access, portable profiles and audited consent logs.
Pricing, population and commerce data anchor the estimate
The report uses 2025 as the base year and forecasts spending from 2026 to 2035. Market values come from the Credence Research model, which combines vendor list prices for profile, event and credit plans with estimated counts of enterprise, midmarket and small buyers and with public indicators such as Census Bureau e-commerce and population statistics. Regional, segment and revenue model splits are Credence Research estimates built from population, industry mix and vendor activity. Sources used are government statistics, state privacy regulators, company releases and filings, vendor pricing pages and trade press, and no interviews or surveys were conducted for this edition.
Activation and AI context carry growth to 2035
U.S. customer data platform spending is projected to reach USD 4.85 billion by 2035 as profile systems take on governance and AI context duties across retail, finance and service teams. Warehouse-native deployment and consumption credits should grow faster than the market, which shifts vendor revenue toward activation and agent usage. The West is expected to remain the fastest-growing region on the strength of California rules and early regional buyers, while the South keeps the largest share. Forecasts beyond 2030 carry more uncertainty because AI pricing and warehouse economics are still changing quickly.
AI context demand and the warehouse shift decide the range
In the base case, spending follows the central forecast as privacy rules, interaction volume and AI context needs expand together. The downside case assumes warehouse-native buyers move storage and compute away from packaged vendors faster than activation fees replace them, and that consolidation slows new contracts. The upside case adds rapid adoption of profile-fed agents in service centers and banks, which would lift credit consumption above the base path.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 9.5% | USD 3.96 billion | Warehouse buyers strip storage fees and acquisitions delay new enterprise contracts |
| Base | 11.99% | USD 4.85 billion | Privacy rules, commerce volume and AI context needs expand along current trends |
| Upside | 14.2% | USD 5.78 billion | Service centers and banks adopt profile-fed AI agents quickly across their customer bases |
Frequently Asked Questions
How big is the USA customer data platform market?
Which solution type leads the market?
Which region leads U.S. spending on customer data platforms?
Why is warehouse-native deployment growing fastest?
How do state privacy laws affect demand?
How do vendors price these platforms?
Who are the key companies in the market?
What are the main challenges for buyers and vendors?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Solution Type
- 1.2.1 Data CDP
- 1.2.2 Analytics CDP
- 1.2.3 Campaign CDP
- 1.2.4 Delivery CDP
- 1.3 By Deployment Model
- 1.3.1 Vendor-Hosted SaaS
- 1.3.2 Warehouse-Native
- 1.3.3 Private Cloud
- 1.4 By End-Use Industry
- 1.4.1 Retail and Consumer Brands
- 1.4.2 Financial Services and Insurance
- 1.4.3 Media and Digital Services
- 1.4.4 Travel and Hospitality
- 1.4.5 Healthcare and Remaining Sectors
- 1.5 By Revenue Model
- 1.5.1 Profile-Based Subscription
- 1.5.2 Event-Based Subscription
- 1.5.3 Consumption Credits
- 1.5.4 Flat Platform Subscription
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 1.55 billion → 2035: USD 4.85 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 USA Customer Data Platform Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 USA Customer Data Platform Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 USA Customer Data Platform Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 USA Customer Data Platform Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 USA Customer Data Platform Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 USA Customer Data Platform Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 USA Customer Data Platform Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 USA Customer Data Platform Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 1.55 billion → 2035: USD 4.85 billion)
- 11.1.2 Historical Market Size, 2018-2025
- 11.1.3 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 USA Customer Data Platform Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Solution Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Base-Year Market Share, 2025
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Data CDP
- 12.3.6.2 Analytics CDP
- 12.3.6.3 Campaign CDP
- 12.3.6.4 Delivery CDP
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Deployment Model - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Base-Year Market Share, 2025
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Vendor-Hosted SaaS
- 12.4.6.2 Warehouse-Native
- 12.4.6.3 Private Cloud
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By End-Use Industry - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Base-Year Market Share, 2025
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Retail and Consumer Brands
- 12.5.6.2 Financial Services and Insurance
- 12.5.6.3 Media and Digital Services
- 12.5.6.4 Travel and Hospitality
- 12.5.6.5 Healthcare and Remaining Sectors
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Revenue Model - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Base-Year Market Share, 2025
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Profile-Based Subscription
- 12.6.6.2 Event-Based Subscription
- 12.6.6.3 Consumption Credits
- 12.6.6.4 Flat Platform Subscription
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 USA Customer Data Platform End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 USA Customer Data Platform Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 USA Customer Data Platform Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 USA Customer Data Platform Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Adobe
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Salesforce
- 18.4 Microsoft (Dynamics 365 Customer Insights)
- 18.5 Twilio (Segment)
- 18.6 Tealium
- 18.7 Treasure AI (Treasure Data)
- 18.8 mParticle (Rokt)
- 18.9 Amperity
- 18.10 Hightouch
- 18.11 BlueConic
- 18.12 Simon AI (Monetate)
- 18.13 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

