
Wireless Fetal Monitoring System Market Overview:
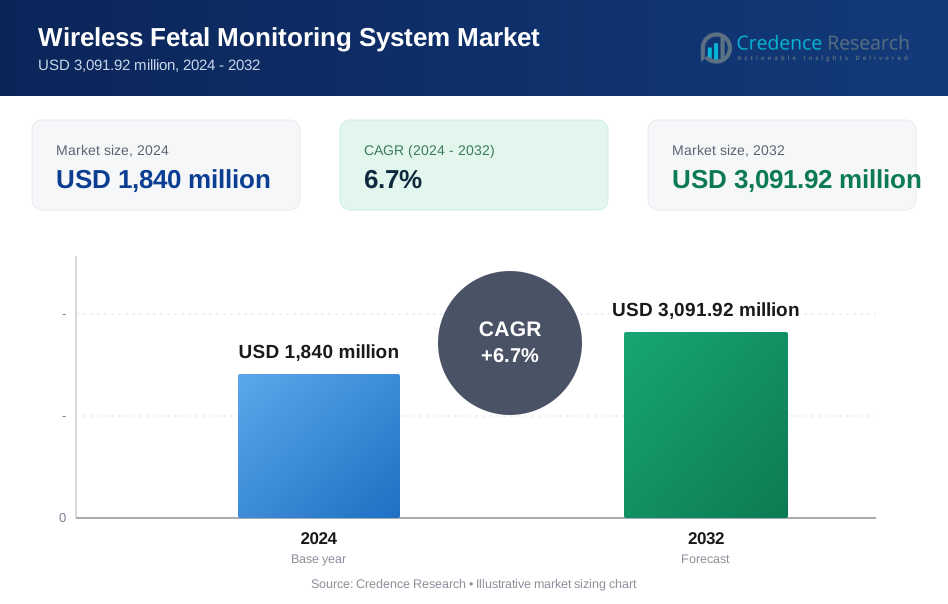
The Wireless Fetal Monitoring System Market size was valued at USD 1,840 million in 2024 and is anticipated to reach USD 3,091.92 million by 2032, growing at a CAGR of 6.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Wireless Fetal Monitoring System Market Size 2024 | USD 1,840 million |
| Wireless Fetal Monitoring System Market, CAGR | 6.7% |
| Wireless Fetal Monitoring System Market Size 2032 | USD 3,091.92 million |
Wireless Fetal Monitoring System Market Insights
- Market growth is driven by the rising incidence of high-risk pregnancies, increasing demand for continuous prenatal monitoring, and growing adoption of remote and home-based maternal care solutions across hospitals and clinics.
- Key market trends include integration of wireless fetal monitoring with telemedicine platforms, cloud-based data sharing, and AI-enabled analytics, while the Instrument segment dominated with a 64.2% share in 2024 and fetal heart rate monitoring led applications with a 71.6% share.
- Market restraints include high device costs, limited reimbursement for remote fetal monitoring services, and concerns related to data security, privacy, and regulatory compliance across regions.
- Regionally, North America led with a 38.6% share in 2024, followed by Europe at 29.4%, Asia Pacific at 22.1%, Latin America at 6.1%, and Middle East & Africa at 3.8%, reflecting varied healthcare infrastructure maturity.

Market Segmentation Analysis:
By Product Type:
The Wireless Fetal Monitoring System Market, by product type, is led by the Instrument segment, which accounted for 64.2% market share in 2024, driven by its critical role in continuous, real-time fetal monitoring during prenatal and intrapartum care. Instruments integrate wireless sensors, data transmission modules, and advanced analytics, making them essential across clinical and homecare settings. High adoption is supported by rising demand for non-invasive monitoring, improved maternal comfort, and growing hospital investments in connected obstetric devices. Accessories & consumables complement system usage but remain secondary due to lower unit value and replacement-driven demand.
- For instance, GE Healthcare's Novii+ Wireless Patch System, cleared by the FDA in February 2024, noninvasively monitors fetal heart rate, maternal heart rate, and uterine activity as early as 34 weeks gestation using a beltless patch for enhanced maternal mobility during labor.
By Application:
By application, Fetal Heart Rate Monitoring dominated the Wireless Fetal Monitoring System Market with a 71.6% share in 2024, reflecting its central importance in detecting fetal distress, hypoxia, and abnormal heart patterns. Continuous fetal heart rate assessment is a standard component of antenatal and labor monitoring, significantly increasing adoption of wireless systems. Growth is driven by rising high-risk pregnancies, increasing emphasis on early diagnosis, and technological advancements enabling accurate remote monitoring. Intrauterine pressure monitoring holds a smaller share, as it is typically used in specific labor conditions rather than routine prenatal care.
- For instance, GE Healthcare's Novii Wireless Patch System uses a single peel-and-stick patch with abdominal electrodes to non-invasively measure fetal heart rate via fetal ECG, maternal heart rate, and uterine activity simultaneously, even from 34 weeks gestation.
By End User:
The Hospitals segment held the dominant position in the Wireless Fetal Monitoring System Market, capturing 58.9% market share in 2024, supported by high patient volumes, advanced obstetric infrastructure, and the availability of skilled healthcare professionals. Hospitals are early adopters of wireless monitoring technologies to improve workflow efficiency, enable centralized monitoring, and enhance maternal-fetal outcomes. Strong reimbursement coverage and increasing investments in digital maternity wards further reinforce dominance. Obstetrics & gynecology clinics and homecare are growing steadily but trail hospitals due to limited infrastructure and lower device penetration.
Key Growth Drivers
Rising Incidence of High-Risk Pregnancies
The Wireless Fetal Monitoring System Market is significantly driven by the growing incidence of high-risk pregnancies associated with advanced maternal age, gestational diabetes, hypertension, obesity, and lifestyle-related health conditions. These pregnancies require continuous fetal surveillance to detect early signs of distress and reduce maternal and neonatal complications. Wireless fetal monitoring systems support uninterrupted tracking of fetal heart rate and uterine activity while allowing maternal mobility. Increasing clinical awareness and emphasis on preventive prenatal care are accelerating adoption across hospitals and specialized maternity centers.
- For instance, Philips launched the Avalon CL Fetal and Maternal Pod and Patch, a disposable wireless solution for high-risk pregnancies that reduces clinician-patient physical interactions.
Growing Demand for Remote and Home-Based Maternal Monitoring
Rising demand for remote healthcare solutions is a key growth driver in the Wireless Fetal Monitoring System Market. Wireless monitoring systems enable home-based fetal assessments, reducing frequent hospital visits while ensuring real-time data sharing with clinicians. This approach improves patient comfort, enhances care accessibility in rural regions, and lowers overall healthcare costs. The expanding use of telemedicine platforms and digital maternity care programs is further strengthening demand for connected fetal monitoring solutions.
- For instance, Nuvo Group's INVU system enables remote home monitoring of fetal heart rate and uterine activity via a wireless belt with cloud processing; clinical validation showed limits of agreement within ±8 bpm of standard cardiotocography, supporting safe non-stress tests at home.
Advancements in Wireless and Sensor Technologies
Technological advancements in wireless connectivity, sensor precision, and data analytics are accelerating growth in the Wireless Fetal Monitoring System Market. Innovations such as Bluetooth-enabled sensors, cloud-based monitoring platforms, and AI-supported fetal pattern analysis improve signal accuracy and clinical decision-making. These advancements reduce motion artifacts, enhance reliability, and support seamless integration with hospital information systems, making wireless fetal monitoring more efficient and clinically valuable.
Key Trends & Opportunities
Integration with Digital Health and Telemedicine Platforms
The integration of wireless fetal monitoring systems with digital health and telemedicine platforms represents a major trend in the Wireless Fetal Monitoring System Market. Cloud connectivity, mobile applications, and electronic health record integration enable real-time monitoring, automated alerts, and remote clinical supervision. This trend supports early intervention, improves pregnancy outcomes, and aligns with value-based healthcare models. Growing investments in smart maternity wards and digital prenatal care solutions are creating sustained opportunities for market expansion.
- For instance, GE Healthcare's Novii+ Wireless Patch System uses a noninvasive wearable sensor to measure fetal heart rate, maternal heart rate, and uterine activity from 34 weeks gestation, transmitting data wirelessly for remote monitoring.
Expansion of Homecare and Wearable Monitoring Solutions
The expansion of homecare and wearable fetal monitoring solutions is creating strong opportunities in the Wireless Fetal Monitoring System Market. Wireless devices allow expectant mothers to perform routine fetal monitoring outside clinical settings without compromising data accuracy. This trend supports long-term monitoring for high-risk pregnancies and post-discharge care. Increasing consumer acceptance of wearable medical technologies and growing insurer support for remote maternal monitoring services are expected to drive adoption.
- For instance, Monica Healthcare's AN24, a portable wireless monitor using abdominal ECG electrodes, enables continuous recording of fetal heart rate (FHR), maternal heart rate (MHR), and uterine activity (UA) for over 22 hours in homecare settings.
Key Challenges
High Cost of Devices and Limited Reimbursement
High device costs remain a key challenge for the Wireless Fetal Monitoring System Market, particularly in cost-sensitive and emerging healthcare systems. Advanced wireless monitoring solutions involve sophisticated hardware, software, and connectivity components, increasing overall system costs. Limited reimbursement coverage for remote fetal monitoring services further restricts adoption among smaller hospitals and clinics. Budget constraints and uneven reimbursement policies continue to slow large-scale implementation.
Data Security, Privacy, and Regulatory Barriers
Data security and regulatory compliance pose ongoing challenges in the Wireless Fetal Monitoring System Market. Wireless data transmission and cloud-based platforms raise concerns regarding patient data privacy and cybersecurity risks. Compliance with stringent medical device regulations and digital health standards increases development costs and approval timelines. Differences in regulatory frameworks across regions further complicate global market entry and slow widespread adoption of wireless fetal monitoring technologies.
Regional Analysis
North America
The Wireless Fetal Monitoring System Market in North America accounted for 38.6% market share in 2024, driven by advanced healthcare infrastructure, high adoption of digital health technologies, and strong awareness of maternal-fetal monitoring. Hospitals and maternity centers across the United States and Canada actively deploy wireless monitoring systems to manage high-risk pregnancies and improve clinical workflows. Favorable reimbursement policies, high healthcare spending, and early adoption of telemedicine further support market leadership. Continuous investments in connected medical devices and strong presence of leading manufacturers reinforce North America’s dominant position.
Europe
Europe held a 29.4% share of the Wireless Fetal Monitoring System Market in 2024, supported by well-established public healthcare systems and growing emphasis on maternal safety. Countries such as Germany, the United Kingdom, and France are adopting wireless fetal monitoring to enhance prenatal and intrapartum care efficiency. Government initiatives promoting digital health, combined with rising maternal age and increasing high-risk pregnancies, are driving demand. Strong regulatory standards ensure product reliability, while growing acceptance of remote monitoring solutions in hospitals and clinics continues to support steady regional growth.
Asia Pacific
Asia Pacific captured 22.1% market share in 2024 in the Wireless Fetal Monitoring System Market, driven by rising birth rates, improving healthcare infrastructure, and increasing awareness of prenatal monitoring. Rapid expansion of private hospitals, growing medical tourism, and increasing adoption of wireless medical devices in countries such as China, India, and Japan are supporting market growth. Government investments in maternal healthcare programs and expanding telehealth services are further accelerating adoption. Large patient populations and increasing focus on reducing maternal and neonatal mortality strengthen long-term growth potential.
Latin America
Latin America accounted for 6.1% of the Wireless Fetal Monitoring System Market in 2024, supported by gradual improvements in maternal healthcare access and hospital infrastructure. Countries such as Brazil and Mexico are increasingly adopting wireless fetal monitoring systems to enhance prenatal care and manage pregnancy-related complications. Growing awareness of early fetal monitoring benefits, coupled with rising private healthcare investments, is driving market expansion. However, limited reimbursement coverage and budget constraints continue to restrict faster adoption, keeping overall market share comparatively moderate.
Middle East & Africa
The Middle East & Africa region held a 3.8% share of the Wireless Fetal Monitoring System Market in 2024, reflecting emerging adoption across developing healthcare systems. Growth is supported by increasing investments in hospital infrastructure, rising government focus on maternal and neonatal health, and expanding private healthcare facilities in countries such as Saudi Arabia, the UAE, and South Africa. Adoption remains uneven due to cost sensitivity and limited access in rural areas, but improving healthcare policies and gradual digitalization are supporting steady regional market development.
Wireless Fetal Monitoring System Market Segmentations:
By Product Type :
- Instrument
- Accessories & Consumables
By Application
- Fetal Heart Rate Monitoring
- Intrauterine Pressure Monitoring
By End User
- Hospitals
- Obstetrics & Gynecology Clinics
- Homecare
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Wireless Fetal Monitoring System Market features the presence of key players such as Koninklijke Philips N.V., GE HealthCare, Siemens Healthineers, Medtronic plc, and Arjo (Huntleigh Healthcare), who focus on expanding wireless monitoring portfolios and strengthening digital maternity care solutions. Market participants compete through product innovation, system integration, and strategic partnerships with hospitals and telehealth providers. Companies are investing in advanced sensors, cloud connectivity, and AI-enabled analytics to improve signal accuracy and clinical decision-making. Expansion into homecare and remote monitoring applications is a major strategic focus, supporting long-term patient engagement and recurring revenue models. Regulatory compliance, data security capabilities, and interoperability with hospital information systems play a critical role in differentiation. Increasing emphasis on value-based maternal care and workflow efficiency continues to shape competitive strategies across global and regional players.
Key Player Analysis
- Shenzhen Aeon Technology Co., Ltd.
- Koninklijke Philips N.V.
- Mediana Co. Ltd.
- Shenzhen Jumper Medical Equipment Co., Ltd.
- Dixion Vertrieb der Medizingeräte GmbH
- Sunray Medical Apparatus Co., Ltd.
- OBMedical Company
- Shenzhen Unicare Electronic Co., Ltd.
- Huntleigh Healthcare Limited (ARJO Family)
- Shenzhen Lai Kang Ning Medical Technology Co. Ltd.
Recent Developments
- In November 2024, GE HealthCare received expanded FDA 510(k) clearance for its Novii+ Wireless Patch System, enabling noninvasive monitoring of fetal heart rate, maternal heart rate, and uterine activity for pregnant patients at 34 weeks or later.
- In September 2024, Comen launched the CF5 and CF8 fetal and maternal monitors, featuring improved connectivity, precision, and triplet monitoring capabilities.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Wireless Fetal Monitoring System Market will continue to expand as demand for continuous and non-invasive prenatal monitoring increases globally.
- Adoption of remote and home-based fetal monitoring solutions will rise due to growing telemedicine integration.
- Technological advancements in wireless connectivity and sensor accuracy will enhance monitoring reliability and clinical outcomes.
- Hospitals will remain the primary adopters, supported by investments in digital maternity care infrastructure.
- Homecare and ambulatory monitoring applications will gain stronger acceptance among high-risk pregnancy populations.
- Integration with electronic health records and digital health platforms will improve data accessibility and clinical decision-making.
- Increasing focus on maternal and neonatal safety will drive sustained demand across developed and emerging markets.
- Emerging economies will experience faster adoption as healthcare infrastructure and awareness improve.
- Manufacturers will emphasize data security, regulatory compliance, and interoperability to strengthen market positioning.
- Strategic partnerships and product innovation will remain central to long-term market competitiveness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Incidence of High-Risk Pregnancies
Increasing rates of high-risk pregnancies due to factors such as advanced maternal age, gestational diabetes, and hypertension are driving demand for continuous fetal monitoring. Wireless systems enable real-time, non-invasive surveillance, supporting early detection of fetal distress and improving maternal and neonatal outcomes.
Growing Demand for Remote and Home-Based Maternal Monitoring
The shift towards remote healthcare and telemedicine is fueling adoption of wireless fetal monitoring systems, which allow expectant mothers to undergo fetal assessments at home. This reduces hospital visits, enhances patient comfort, and ensures timely clinical intervention, especially in rural or underserved regions.
Advancements in Wireless and Sensor Technologies
Technological innovations such as Bluetooth-enabled sensors, cloud-based data sharing, and AI-powered analytics are improving the accuracy, reliability, and usability of wireless fetal monitoring systems. These advancements support seamless integration with hospital IT systems and enable more effective clinical decision-making.
Integration with Digital Health and Telemedicine Platforms
The integration of wireless fetal monitoring with telemedicine and digital health platforms allows for real-time data sharing, automated alerts, and remote supervision by clinicians. This trend enhances workflow efficiency, supports early intervention, and aligns with value-based healthcare models.
Expansion of Homecare and Wearable Monitoring Solutions
Increasing acceptance of wearable medical devices and insurer support for remote maternal monitoring are expanding the use of wireless fetal monitoring in homecare settings. This enables long-term monitoring for high-risk pregnancies and post-discharge care, driving market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Wireless Fetal Monitoring System Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Wireless Fetal Monitoring System Market projected to grow between 2024 and 2032?
Which Wireless Fetal Monitoring System Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Wireless Fetal Monitoring System Market?
Who are the leading companies in the Wireless Fetal Monitoring System Market?
Which region commanded the largest share of the Wireless Fetal Monitoring System Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Hospitals
- 1.2.2 Obstetrics & Gynecology Clinics
- 1.2.3 Homecare
- 1.3 By Application
- 1.3.1 Fetal Heart Rate Monitoring
- 1.3.2 Intrauterine Pressure Monitoring
- 1.4 By Product Type
- 1.4.1 Instrument
- 1.4.2 Accessories & Consumables
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,840 million → 2032: USD 3,091.92 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Wireless Fetal Monitoring System Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Wireless Fetal Monitoring System Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Wireless Fetal Monitoring System Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Wireless Fetal Monitoring System Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Wireless Fetal Monitoring System Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Wireless Fetal Monitoring System Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Wireless Fetal Monitoring System Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Wireless Fetal Monitoring System Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,840 million → 2032: USD 3,091.92 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Wireless Fetal Monitoring System Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Obstetrics & Gynecology Clinics
- 12.3.7.3 Homecare
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Fetal Heart Rate Monitoring
- 12.4.7.2 Intrauterine Pressure Monitoring
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Instrument
- 12.5.7.2 Accessories & Consumables
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Wireless Fetal Monitoring System End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Wireless Fetal Monitoring System Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Wireless Fetal Monitoring System Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Wireless Fetal Monitoring System Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Koninklijke Philips N.V.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 GE HealthCare
- 18.4 Siemens Healthineers
- 18.5 Medtronic plc
- 18.6 Arjo (Huntleigh Healthcare)
- 18.7 Shenzhen Aeon Technology Co., Ltd.
- 18.8 Mediana Co. Ltd.
- 18.9 Shenzhen Jumper Medical Equipment Co., Ltd.
- 18.10 Dixion Vertrieb der Medizingeräte GmbH
- 18.11 Sunray Medical Apparatus Co., Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

