
Market Overview:
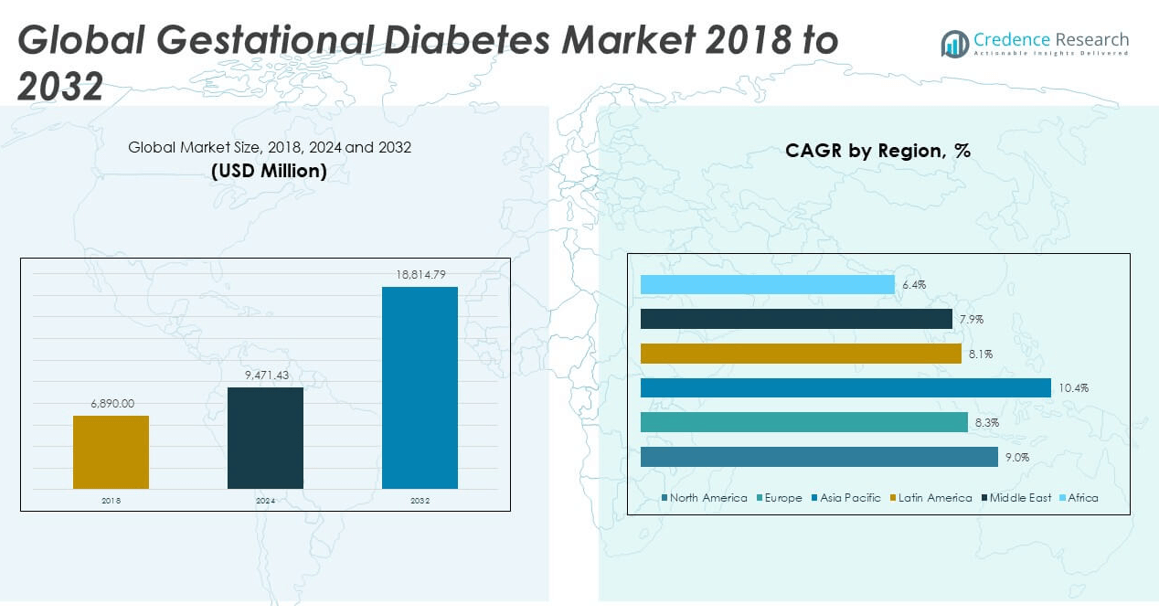
The Global Gestational Diabetes Market size was valued at USD 6,890.00 million in 2018 to USD 9,471.43 million in 2024 and is anticipated to reach USD 18,814.79 million by 2032, at a CAGR of 9.01% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Gestational Diabetes Market Size 2024 | USD 9,471.43 million |
| Gestational Diabetes Market, CAGR | 9.01% |
| Gestational Diabetes Market Size 2032 | USD 18,814.79 million |
The market is driven by the growing prevalence of gestational diabetes, influenced by rising maternal age, obesity rates, and sedentary lifestyles. Increasing awareness of prenatal health and government-led screening programs are improving early diagnosis and management. Healthcare providers are adopting advanced diagnostic tools and treatment protocols, including insulin therapies and oral hypoglycemics, to ensure maternal and fetal safety. Technological advancements in continuous glucose monitoring systems also play a critical role in enhancing patient outcomes and compliance, further fueling market growth across both developed and developing regions.
Geographically, North America leads the gestational diabetes market due to its advanced healthcare infrastructure, high diagnosis rate, and awareness programs. Europe follows closely with significant institutional support for maternal health. Meanwhile, the Asia Pacific region is emerging rapidly, driven by a large population base, growing urbanization, and a rising number of high-risk pregnancies. Countries like China and India are witnessing increased demand for screening and treatment solutions due to their expanding middle-class population and government healthcare initiatives. Latin America and the Middle East & Africa also show potential as healthcare access continues to improve.
Market Insights:
- The Global Gestational Diabetes Market was valued at USD 6,890.00 million in 2018, reached USD 9,471.43 million in 2024, and is projected to reach USD 18,814.79 million by 2032, growing at a CAGR of 9.01%.
- Rising obesity rates, maternal age, and sedentary lifestyles are key drivers increasing gestational diabetes prevalence worldwide.
- Government mandates and healthcare initiatives promoting routine prenatal screening support early detection and timely treatment.
- Limited awareness in rural areas and low-resource settings continues to restrict diagnosis and care access.
- Technological advancements such as continuous glucose monitoring and digital health platforms enhance treatment compliance and monitoring.
- North America leads the market due to strong healthcare infrastructure and policy support, while Asia Pacific emerges as a high-growth region driven by increasing population and urbanization.
- Variability in diagnostic protocols and healthcare infrastructure across regions poses a restraint on consistent market growth.
Market Drivers:
Rising Global Incidence of Gestational Diabetes Due to Lifestyle and Demographic Changes:
The increasing prevalence of gestational diabetes is directly linked to sedentary lifestyles, unhealthy diets, and the growing obesity burden. Women entering pregnancy at a later age experience higher risks of glucose intolerance, raising gestational diabetes diagnoses. Urbanization has contributed to reduced physical activity and poor nutritional habits, both recognized as major risk factors. The Global Gestational Diabetes Market expands due to the medical community’s emphasis on identifying and managing glucose abnormalities early in pregnancy. Demand for maternal-fetal monitoring and personalized care plans grows as awareness rises. The healthcare industry prioritizes early intervention strategies to reduce maternal and neonatal complications. Governments also implement population-based screening initiatives to address growing caseloads. These factors collectively drive the market’s growth trajectory.
- For instance, Novo Nordisk has implemented educational and clinical programs in collaboration with healthcare providers in over 70 countries, which have resulted in a measurable increase in early gestational diabetes screening coverage, helping identify more at-risk pregnant women compared to standard protocols.
Strong Support from Government and Public Health Organizations to Promote Screening Programs
Public health policies increasingly mandate routine gestational diabetes screening during pregnancy. National guidelines in countries such as the U.S., Canada, and China recommend early and repeated glucose tolerance tests. Governments allocate funding to expand maternal health infrastructure and training for healthcare workers. These efforts ensure timely diagnosis, reducing the risks of pregnancy complications and long-term health issues in mothers and infants. It strengthens healthcare systems’ ability to track, intervene, and manage gestational diabetes efficiently. The Global Gestational Diabetes Market benefits from this systemic prioritization of maternal health. Incentives for public-private collaboration foster access to affordable testing tools. Enhanced integration of diagnostic services into primary care accelerates demand and expands the market footprint.
- For instance, Roche Diagnostics partnered with the Indian government’s GDM screening initiative, providing their Accu-Chek diagnostic systems, which facilitated over 1.2 million glucose tests in public health centers within one year, significantly increasing detection rates of gestational diabetes in underserved regions.
Increasing Adoption of Technological Innovations in Diagnosis and Monitoring:
Technological advancements play a crucial role in expanding early detection and disease management capabilities. Healthcare providers adopt digital tools like continuous glucose monitoring (CGM) and connected glucometers for accurate, real-time tracking. These devices support proactive care, minimizing risks through data-driven interventions. Smartphone-linked platforms allow pregnant women to manage their condition and communicate with healthcare professionals effectively. The Global Gestational Diabetes Market gains momentum from the availability of user-friendly diagnostic devices. Innovations in non-invasive and rapid testing reduce patient discomfort and improve compliance. Start-ups and established med-tech firms invest heavily in research to improve testing accuracy and turnaround time. These innovations position technology as a cornerstone of gestational diabetes care.
Expanding Healthcare Access in Developing Economies Boosting Diagnosis Rates:
Healthcare infrastructure continues to improve in middle-income countries across Asia, Africa, and Latin America. With more women receiving prenatal care, diagnosis rates of gestational diabetes increase significantly. Government-funded health programs and insurance expansions drive maternal care access in underserved regions. The Global Gestational Diabetes Market sees significant growth in these areas due to greater diagnostic availability. Community-based awareness campaigns help overcome cultural barriers and encourage pregnant women to seek timely screening. Multinational companies target these regions by introducing affordable diagnostics and treatment solutions. Partnerships with local providers strengthen supply chains and market presence. With rising awareness and infrastructure upgrades, emerging markets are becoming key growth drivers.
Market Trends:
Integration of Digital Health Platforms for Gestational Diabetes Management:
Digital health solutions are becoming integral to managing gestational diabetes with increased precision and convenience. Mobile applications now help track blood glucose, medication schedules, nutrition intake, and physical activity. Many of these platforms integrate with wearable glucose monitors, creating a comprehensive management ecosystem. Telehealth services support continuous engagement between patients and healthcare providers. The Global Gestational Diabetes Market benefits from such platforms that empower patient self-management. AI-enabled platforms offer personalized alerts and recommendations to improve compliance. Digital tools improve health outcomes by enabling early interventions. They also reduce healthcare costs by minimizing emergency visits. The trend highlights the shift toward decentralized and patient-centric care models.
- For instance, Welldoc’s BlueStar® app, cleared by the FDA, has been shown in clinical studies to reduce mean fasting blood glucose by 23 mg/dl in gestational diabetes users over 12 weeks, while maintaining an 87% weekly engagement rate among patients.
Growing Demand for Plant-Based and Low Glycemic Index Diet Products:
Dietary control is a critical component of gestational diabetes management, prompting a surge in demand for specialized nutritional products. Pregnant women increasingly choose plant-based, high-fiber, and low-glycemic foods to stabilize blood sugar levels. Food companies respond by offering tailored products such as low-carb meal kits and sugar-free snacks. The Global Gestational Diabetes Market aligns with this dietary trend through partnerships with food and nutrition companies. Hospitals and clinics also promote dietary education programs, reinforcing long-term healthy eating habits. Nutrition start-ups explore new formulations for diabetic-friendly supplements and drinks. Increasing awareness of food as medicine drives consumer preference for preventive nutrition. This trend supports both clinical outcomes and commercial growth.
- For instance, Abbott’s Glucerna® line, clinically formulated for blood sugar management, is recommended in over 100 hospital-based gestational diabetes nutrition programs in the U.S., and clinical evaluations have demonstrated improved 2-hour postprandial glucose profiles in pregnant women regularly using these products in meal plans.
Collaborations Between Diagnostic Companies and Pharmaceutical Firms:
Strategic alliances between diagnostics and pharmaceutical companies are shaping innovation in the gestational diabetes space. Firms combine diagnostic capabilities with therapeutics to create end-to-end care models. Companion diagnostics help identify patients who would benefit from specific drug regimens. The Global Gestational Diabetes Market is seeing integrated product development pipelines emerge from such collaborations. These efforts accelerate the commercialization of new insulin formulations and oral antidiabetic drugs. Partnerships also support co-branded awareness campaigns and bundled care offerings. Regulatory pathways become more streamlined when diagnostics and treatments evolve together. The trend signals a move toward value-based healthcare solutions.
Focus on Early Biomarker Research for Predictive Diagnosis:
Researchers are investing in the identification of early biomarkers that could predict gestational diabetes before symptoms emerge. Studies explore the genetic, metabolic, and hormonal markers detectable during the first trimester. Early prediction enables more personalized interventions and better maternal outcomes. The Global Gestational Diabetes Market shows growing interest in this area due to its transformative clinical potential. Pharmaceutical companies are funding academic collaborations to validate new testing methods. Biomarker-based diagnostics could reduce dependence on glucose tolerance tests. Such predictive approaches align with the broader trend of precision medicine. This trend aims to improve disease forecasting and reduce complications through pre-emptive action.
Market Challenges Analysis:
Limited Awareness and Delayed Diagnosis in Low-Income and Rural Areas:
Despite rising global incidence, many women in underserved regions remain undiagnosed due to lack of awareness and healthcare access. Rural populations often have limited access to trained professionals and diagnostic tools. Cultural taboos and misinformation about pregnancy-related disorders further hinder early detection. In such settings, gestational diabetes is frequently detected late, increasing the risk of complications. The Global Gestational Diabetes Market must overcome these barriers through education and outreach programs. Efforts to localize screening guidelines and deploy mobile health units are critical. However, funding and infrastructure constraints continue to slow progress. Without targeted intervention, diagnosis gaps will persist in emerging economies.
Complexity in Treatment Adherence and Monitoring Compliance:
Effective management of gestational diabetes depends on strict dietary control, medication compliance, and regular glucose monitoring. Many patients struggle to adhere to treatment due to lifestyle constraints or lack of support. Insulin administration and frequent glucose checks can be challenging for first-time mothers. Even in developed countries, disparities in digital literacy and healthcare access affect compliance. It leads to inconsistent outcomes and raises long-term health risks. The Global Gestational Diabetes Market must address behavioral barriers by promoting personalized care plans. Healthcare providers face difficulties scaling individualized counselling in resource-constrained settings. This challenge limits the full effectiveness of available treatment solutions.
Market Opportunities:
Expanding Use of AI and Remote Monitoring Tools in Maternal Healthcare:
Artificial intelligence and remote patient monitoring technologies are creating new possibilities for early detection and personalized management. Predictive analytics can flag high-risk pregnancies using historical and real-time data. AI-powered tools assist healthcare professionals in making timely decisions. The Global Gestational Diabetes Market gains momentum from these innovations by improving outcomes and lowering care costs. Integration of remote devices supports regular monitoring without frequent clinic visits. These technologies also facilitate broader population screening in remote locations. Start-ups focusing on maternal health tech can capture untapped market segments through scalable AI solutions.
Rising Demand for Affordable Point-of-Care Testing Solutions:
Low-cost, rapid diagnostic tools are critical in expanding access to early gestational diabetes detection. Manufacturers are developing portable glucose testing kits tailored for use in community clinics and home settings. It helps reduce diagnostic delays in low-resource environments. The Global Gestational Diabetes Market is seeing increased investment in such solutions to reach underdiagnosed populations. Distribution through public health programs expands reach while ensuring cost-effectiveness. This opportunity enables companies to address healthcare equity and scale impact in emerging regions.
Market Segmentation Analysis:
By Treatment
The Global Gestational Diabetes Market by treatment is led by insulin therapy, which remains the standard for managing moderate to severe cases. Rapid-acting and short-acting insulin types offer precise glycemic control around meals, while intermediate and long-acting variants ensure baseline glucose regulation. Oral medications represent a growing segment, driven by patient preference for non-invasive options. Metformin dominates this space due to its proven safety and effectiveness during pregnancy. Sulfonylureas, though effective, see limited use due to potential neonatal risks, making them a secondary option in clinical protocols.
- For instance, Sanofi’s rapid-acting insulin analog, Apidra®, was documented in a multi-center study involving pregnant women with gestational diabetes, demonstrating a 29% reduction in postprandial blood sugar excursions compared to regular human insulin.
By Diagnosis
Diagnosis is bifurcated into the Glucose Challenge Test (GCT) and the Oral Glucose Tolerance Test (OGTT). OGTT leads in market share, favored for its accuracy in confirming gestational diabetes following abnormal GCT results. It is a widely adopted standard in prenatal screening protocols worldwide. GCT serves as an initial screening tool, especially in primary healthcare environments where rapid triage is required. Both tests remain integral in clinical pathways, supporting timely diagnosis and intervention across healthcare systems.
- For instance, The Siemens ADVIA Chemistry Glucose Hexokinase analytical system is FDA 510(k) cleared for quantitative glucose testing in human serum and plasma. Its precision and throughput have led to widespread adoption in clinical laboratories, supporting large-scale screening protocols such as OGTT (oral glucose tolerance test) for gestational diabetes.
By End-user
Hospitals dominate the end-user segment due to their capacity for comprehensive maternal care, including diagnostics, inpatient treatment, and emergency support. Clinics rank next, offering accessible, routine screening services. Home care settings are expanding with the adoption of digital health tools for remote glucose monitoring. Diagnostic centers support standalone testing, catering to outpatients. Others, including maternity centers and telehealth platforms, play a supplementary role, reflecting the market’s gradual shift toward decentralized and tech-enabled care.
Segmentation:
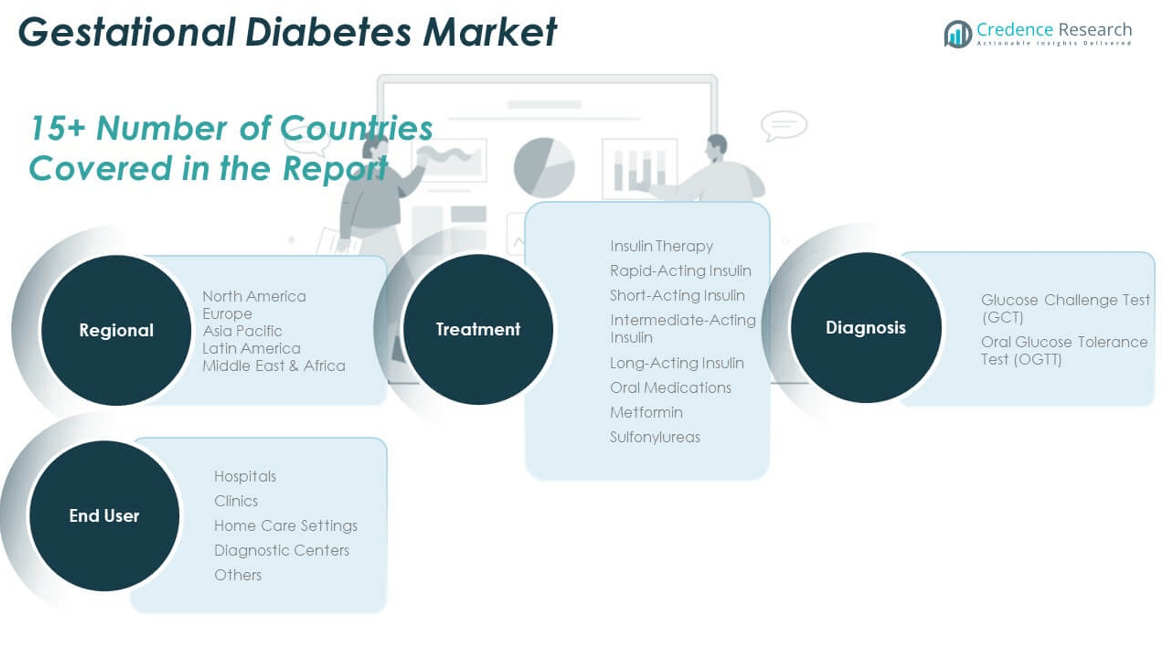
By Treatment Segment
- Insulin Therapy
- Rapid-Acting Insulin
- Short-Acting Insulin
- Intermediate-Acting Insulin
- Long-Acting Insulin
- Oral Medications
- Metformin
- Sulfonylureas
By Diagnosis Segment
- Glucose Challenge Test (GCT)
- Oral Glucose Tolerance Test (OGTT)
By End-user Segment
- Hospitals
- Clinics
- Home Care Settings
- Diagnostic Centers
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Gestational Diabetes Market size was valued at USD 2,466.62 million in 2018 to USD 3,349.04 million in 2024 and is anticipated to reach USD 6,643.53 million by 2032, at a CAGR of 9.0% during the forecast period. It accounts for the largest regional share of approximately 35.3% in 2024. The region leads due to its robust healthcare infrastructure, high awareness, and consistent implementation of screening guidelines. It benefits from early diagnosis protocols and wide availability of treatment options, including advanced insulin therapies and digital monitoring tools. The U.S. drives regional dominance with substantial investment in maternal healthcare and high obesity prevalence. Canada supports growth with universal health coverage and integrated prenatal care. Market players focus on expanding wearable glucose devices and telehealth support across the region. North America continues to attract innovation and partnerships in gestational diabetes care. It maintains strong reimbursement frameworks and clinical research participation, reinforcing leadership in the global market.
Europe
The Europe Gestational Diabetes Market size was valued at USD 1,845.14 million in 2018 to USD 2,439.58 million in 2024 and is anticipated to reach USD 4,582.39 million by 2032, at a CAGR of 8.3% during the forecast period. It holds a regional market share of approximately 25.8% in 2024. European countries actively implement standardized prenatal screening practices across national healthcare systems. Germany, France, and the UK represent key markets due to their advanced diagnostic and treatment infrastructure. Public health agencies support patient education and promote gestational health through digital campaigns. The region adopts insulin therapies and oral medications widely, supported by favorable reimbursement. It also supports collaborative research into early biomarkers and non-invasive diagnostic methods. Policy-driven digital health expansion enhances access to glucose monitoring solutions. Europe's focus on maternal and child well-being continues to strengthen its role in global gestational diabetes care.
Asia Pacific
The Asia Pacific Gestational Diabetes Market size was valued at USD 1,660.49 million in 2018 to USD 2,385.34 million in 2024 and is anticipated to reach USD 5,236.17 million by 2032, at a CAGR of 10.4% during the forecast period. It commands a regional share of approximately 25.2% in 2024 and is the fastest-growing region. Rapid urbanization, dietary changes, and delayed pregnancies contribute to rising gestational diabetes prevalence. China and India are central to market expansion due to their large pregnant populations and improving healthcare access. Governments introduce maternal screening programs in both rural and urban areas. Medical device manufacturers invest in low-cost glucose monitors to cater to underserved regions. It reflects high growth potential driven by public-private partnerships in prenatal diagnostics. Japan and South Korea adopt advanced insulin delivery and digital tracking solutions. Asia Pacific emerges as a strategic focus for global market participants targeting scalability and outreach.
Latin America
The Latin America Gestational Diabetes Market size was valued at USD 468.52 million in 2018 to USD 638.28 million in 2024 and is anticipated to reach USD 1,182.89 million by 2032, at a CAGR of 8.1% during the forecast period. It represents approximately 6.7% of the global market share in 2024. Brazil and Mexico lead the region with growing investments in maternal health infrastructure. Healthcare access in urban centers supports diagnosis and treatment availability, while rural areas remain underserved. National programs begin integrating gestational diabetes testing into routine prenatal care. Market growth is driven by awareness campaigns, improving insurance coverage, and mobile screening units. Pharmaceutical companies introduce affordable insulin and oral medication options to expand access. It sees increasing collaboration with NGOs and international health organizations. Clinics and diagnostic labs expand offerings to cover gestational diabetes detection. Latin America holds long-term potential with continued investment in public health systems.
Middle East
The Middle East Gestational Diabetes Market size was valued at USD 310.05 million in 2018 to USD 403.42 million in 2024 and is anticipated to reach USD 735.76 million by 2032, at a CAGR of 7.9% during the forecast period. It contributes around 4.3% to the global market in 2024. Countries such as Saudi Arabia, UAE, and Israel lead in adopting early detection protocols and insulin therapies. Rising rates of obesity and maternal age fuel demand for gestational diabetes care. Private sector hospitals and specialty clinics offer comprehensive diagnostic and treatment services. It benefits from national health reforms and digital health strategies that promote monitoring and teleconsultation. Government-backed maternal wellness programs encourage early testing. The region focuses on integrating AI-based screening tools for risk prediction. Market players explore partnerships to introduce cost-effective solutions. The Middle East sees steady market growth supported by healthcare modernization efforts.
Africa
The Africa Gestational Diabetes Market size was valued at USD 139.18 million in 2018 to USD 255.77 million in 2024 and is anticipated to reach USD 434.04 million by 2032, at a CAGR of 6.4% during the forecast period. It accounts for the smallest regional share at approximately 2.7% in 2024. Limited awareness and underdiagnosis continue to challenge the market. Urban centers in South Africa, Egypt, and Nigeria offer prenatal services that include gestational diabetes testing. Rural areas face access barriers due to resource constraints and insufficient healthcare personnel. NGOs and international organizations implement mobile health projects to improve outreach. Diagnostic manufacturers introduce portable kits tailored for low-infrastructure environments. It shows potential with ongoing maternal health investments and telemedicine expansion. Public-private collaborations work to train community health workers. Africa's market development depends on scalable, low-cost solutions and greater awareness initiatives.
Key Player Analysis:
- Novo Nordisk A/S
- Eli Lilly and Company
- Sanofi S.A.
- Merck & Co., Inc.
- F. Hoffmann-La Roche Ltd
- Abbott Laboratories
- AstraZeneca plc
- Boehringer Ingelheim GmbH
- Johnson & Johnson
- Medtronic plc
- Dexcom, Inc.
- Biocon Limited
- Bristol-Myers Squibb
- Bayer AG
- GlaxoSmithKline plc
- Roche Diabetes Care
- LifeScan Inc.
- Ascensia Diabetes Care
- Nipro Diagnostics
- Peptron Inc.
Competitive Analysis:
The Global Gestational Diabetes Market features a moderately consolidated landscape dominated by multinational pharmaceutical and medical device companies. Key players include Novo Nordisk, Eli Lilly, Sanofi, Abbott, and Roche, all of which maintain strong portfolios in insulin therapies, glucose monitoring, and diagnostics. These companies invest in research to develop more effective treatments, personalized care models, and digital platforms. Mid-tier firms and regional players contribute by offering cost-effective solutions in emerging markets. Strategic alliances, product innovation, and geographic expansion remain central to gaining competitive advantage. Companies focus on integrating telehealth and AI to enhance patient engagement and clinical outcomes. Market participants aim to address growing demand through scalable, accessible treatment models.
Recent Developments:
- In July 2025, Merck & Co., Inc. announced positive topline Phase 3 results for its investigational oral PCSK9 inhibitor, enlicitide, in treating adults with hyperlipidemia. This cardiovascular candidate showed clinically meaningful LDL cholesterol reductions, with regulatory filings planned following trial completion.
- In June 2025, Sanofi S.A. announced the acquisition of Blueprint Medicines, expanding Sanofi’s rare immunology disease portfolio and adding the only approved therapy for advanced and indolent systemic mastocytosis to its pipeline. The deal was completed by July 18, 2025, accelerating growth in their immunology and allergy portfolio.
- In July 2025, Merck & Co., Inc. announced positive topline Phase 3 results for its investigational oral PCSK9 inhibitor, enlicitide, in treating adults with hyperlipidemia. This cardiovascular candidate showed clinically meaningful LDL cholesterol reductions, with regulatory filings planned following trial completion.
- In March 2025, F. Hoffmann-La Roche Ltd. entered an exclusive collaboration and licensing agreement with Zealand Pharma to co-develop petrelintide, an amylin analog for obesity and metabolic diseases. This move strengthens Roche’s metabolic disease pipeline by combining petrelintide with Roche’s own incretin assets.
Market Concentration & Characteristics:
The Global Gestational Diabetes Market demonstrates moderate-to-high concentration, with top companies controlling significant shares through diversified product lines and global reach. It is characterized by strong innovation, with companies advancing insulin analogs, oral medications, and smart monitoring tools. Market dynamics are shaped by regulatory frameworks, clinical guidelines, and rising demand in emerging regions. Strategic partnerships and product launches drive competitive positioning. It remains highly responsive to technological shifts and demographic trends influencing maternal healthcare.
Report Coverage:
The research report offers an in-depth analysis based on treatment, diagnosis, and end-user segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for early diagnostic tools will increase as healthcare systems prioritize maternal and fetal outcomes.
- Adoption of continuous glucose monitoring and digital health platforms will accelerate across all income regions.
- Insulin analogs and combination therapies will see strong growth due to evolving treatment protocols.
- Emerging economies in Asia Pacific and Latin America will offer high-growth opportunities through public health investments.
- Oral antidiabetic medications like metformin will gain popularity for their convenience and cost-effectiveness.
- Government policies promoting universal prenatal screening will expand diagnosis rates globally.
- Integration of AI and predictive analytics will support risk stratification and personalized interventions.
- Home-based care and remote monitoring will become central to managing gestational diabetes efficiently.
- Strategic collaborations between pharmaceutical and diagnostic companies will drive innovation and access.
- Increasing focus on patient education and lifestyle modifications will strengthen long-term disease management.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Global Incidence Due to Lifestyle and Demographic Changes
Increasing maternal age, obesity rates, and sedentary lifestyles are leading to a higher prevalence of gestational diabetes worldwide. These demographic and lifestyle shifts are expanding the pool of at-risk pregnancies, driving demand for screening, diagnosis, and treatment solutions.
Government and Public Health Initiatives for Universal Screening
National guidelines and government mandates in countries such as the U.S., China, and India are promoting routine gestational diabetes screening during pregnancy. These policies increase early detection rates and expand the market for diagnostic and therapeutic products.
Technological Advancements in Diagnosis and Monitoring
The adoption of continuous glucose monitoring systems, digital health platforms, and non-invasive diagnostic tools is improving patient compliance and outcomes. These innovations make disease management more accessible and efficient, fueling market growth.
Expanding Healthcare Access in Emerging Markets
Improved healthcare infrastructure and insurance coverage in Asia Pacific, Latin America, and parts of Africa are increasing access to prenatal care and gestational diabetes diagnosis. Public-private partnerships and affordable point-of-care testing are enabling market expansion in previously underserved regions.
Integration of Digital Health and Remote Monitoring
The rise of telehealth, mobile applications, and AI-powered platforms is transforming gestational diabetes management by enabling remote monitoring, personalized care, and better patient engagement. This trend supports decentralized care models and broadens market reach.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Gestational Diabetes Market?
What are the key segments within the Global Gestational Diabetes Market?
What are some challenges faced by the Global Gestational Diabetes Market?
Who are the major players in the Global Gestational Diabetes Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-user
- 1.2.1 Hospitals
- 1.2.2 Clinics
- 1.2.3 Home Care Settings
- 1.2.4 Diagnostic Centers
- 1.2.5 Others
- 1.3 By Diagnosis
- 1.3.1 Glucose Challenge Test (GCT)
- 1.3.2 Oral Glucose Tolerance Test (OGTT)
- 1.4 By Treatment
- 1.4.1 Insulin Therapy
- 1.4.2 Rapid-Acting Insulin
- 1.4.3 Short-Acting Insulin
- 1.4.4 Intermediate-Acting Insulin
- 1.4.5 Long-Acting Insulin
- 1.4.6 Oral Medications
- 1.4.7 Metformin
- 1.4.8 Sulfonylureas
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 6,890.00 million → 2032: USD 18,814.79 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Gestational Diabetes Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Gestational Diabetes Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Gestational Diabetes Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Gestational Diabetes Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Gestational Diabetes Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Gestational Diabetes Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Gestational Diabetes Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Gestational Diabetes Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 6,890.00 million → 2032: USD 18,814.79 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Gestational Diabetes Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-user - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Clinics
- 12.3.7.3 Home Care Settings
- 12.3.7.4 Diagnostic Centers
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Diagnosis - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Glucose Challenge Test (GCT)
- 12.4.7.2 Oral Glucose Tolerance Test (OGTT)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Treatment - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Insulin Therapy
- 12.5.7.2 Rapid-Acting Insulin
- 12.5.7.3 Short-Acting Insulin
- 12.5.7.4 Intermediate-Acting Insulin
- 12.5.7.5 Long-Acting Insulin
- 12.5.7.6 Oral Medications
- 12.5.7.7 Metformin
- 12.5.7.8 Sulfonylureas
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Gestational Diabetes End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Gestational Diabetes Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Gestational Diabetes Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Gestational Diabetes Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Novo Nordisk A/S
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Eli Lilly and Company
- 18.4 Sanofi S.A.
- 18.5 F. Hoffmann-La Roche Ltd
- 18.6 Abbott Laboratories
- 18.7 Medtronic plc
- 18.8 Dexcom, Inc.
- 18.9 Johnson & Johnson
- 18.10 AstraZeneca plc
- 18.11 Bayer AG
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

