
Market Overview:
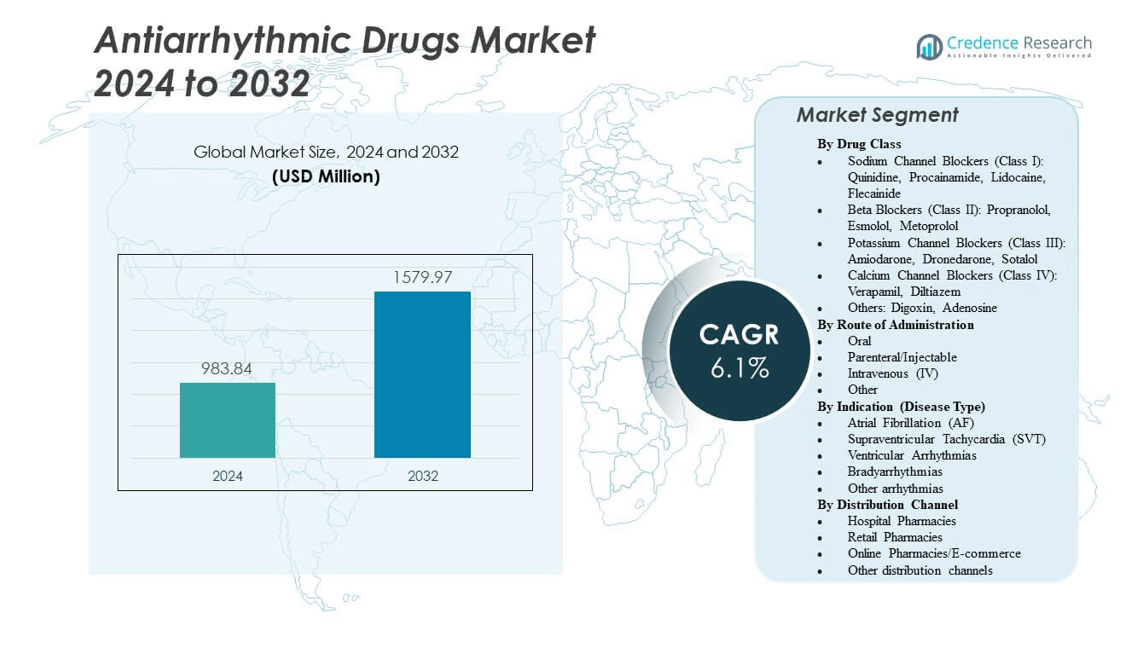
The Antiarrhythmic Drugs Market is projected to grow from USD 983.84 million in 2024 to an estimated USD 1,579.97 million by 2032, with a compound annual growth rate (CAGR) of 6.1% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Antiarrhythmic Drugs Market Size 2024 | USD 983.84 million |
| Antiarrhythmic Drugs Market, CAGR | 6.1% |
| Antiarrhythmic Drugs Market Size 2032 | USD 1,579.97 million |
The market growth is driven by the increasing prevalence of arrhythmias, particularly atrial fibrillation and ventricular tachycardia. As populations age and lifestyle factors contribute to heart conditions, the demand for effective treatments grows. Advances in drug development, including targeted therapies and improved drug formulations, are further propelling market expansion. The rising awareness of cardiovascular health and the availability of advanced treatment options are also contributing factors.
Geographically, North America leads the Antiarrhythmic Drugs Market, driven by advanced healthcare infrastructure and high healthcare spending. Europe follows closely, with a steady market driven by aging populations and strong healthcare systems. The Asia Pacific region, particularly China and India, represents the fastest-growing market, fueled by improving healthcare access, rising disposable incomes, and a high burden of cardiovascular diseases
Market Insights:
- The Antiarrhythmic Drugs Market is projected to grow from USD 983.84 million in 2024 to an estimated USD 1,579.97 million by 2032, with a compound annual growth rate (CAGR) of 6.1% from 2024 to 2032.
- Increasing prevalence of arrhythmias, particularly in aging populations, is driving the demand for antiarrhythmic therapies.
- Advancements in drug formulations and the development of targeted therapies are boosting market growth.
- Limited access to healthcare in emerging regions may restrain the widespread adoption of antiarrhythmic drugs.
- North America leads the market due to a strong healthcare system and high treatment rates for arrhythmias.
- Europe follows closely, supported by robust healthcare frameworks and an aging population.
- Asia Pacific represents the fastest-growing region, with rising healthcare access and a high incidence of cardiovascular diseases.
Market Drivers:
Increasing Incidence of Cardiac Arrhythmias
The rising prevalence of cardiac arrhythmias significantly contributes to the growth of the Antiarrhythmic Drugs Market. These conditions, including atrial fibrillation and ventricular tachycardia, have become increasingly common due to aging populations and unhealthy lifestyle habits. The increasing number of patients diagnosed with arrhythmias is driving demand for effective treatment options, thereby expanding the market for antiarrhythmic drugs. As more individuals seek long-term care, pharmaceutical companies are likely to continue developing tailored solutions to meet this growing demand.
- For instance, iRhythm Technologies’ Zio long-term continuous monitoring (LTCM) service, evaluated in the AVALON study, enabled a diagnostic yield of new arrhythmia diagnoses in 428,707 commercially insured U.S. patients and demonstrated the highest diagnostic yield, lowest retesting rate, and lowest rate of cardiovascular events compared to all other monitoring modalities in clinical practice.
Advancements in Drug Development and Technology
Recent advancements in drug development technology have led to the introduction of innovative antiarrhythmic agents that offer improved efficacy and safety profiles. These advancements, particularly in genetic and molecular research, are enhancing the therapeutic outcomes of treatments for arrhythmic conditions. Furthermore, the continuous development of new drug formulations that target specific heart arrhythmia mechanisms is driving the market expansion. These technologies ensure that patients receive optimal treatments with fewer side effects, helping improve quality of life for patients with chronic heart conditions.
Rising Awareness of Cardiac Health
Growing awareness regarding cardiac health is encouraging early detection and management of arrhythmias, further boosting the Antiarrhythmic Drugs Market. Health campaigns and medical research have contributed to an increase in patient knowledge, prompting timely intervention. This increased awareness also leads to more patients opting for long-term management, which sustains demand for antiarrhythmic drugs. As the population becomes more proactive about their cardiovascular health, the market is expected to see continued growth with higher adoption of preventive treatments.
- For instance, the American Heart Association’s “Go Red for Women” campaign led to an average 494% increase (range: 211%-789%) in search volume for “Go Red for Women” and related cardiac terms every February during active campaign months over a 15-year period, as measured in a peer-reviewed journal study published in 2020.
Government Initiatives and Reimbursement Policies
Government initiatives aimed at improving healthcare infrastructure and providing reimbursement policies for arrhythmia treatments contribute to the market growth. Many countries are investing in the healthcare sector, expanding access to treatments for heart-related conditions. These favorable policies make antiarrhythmic drugs more accessible, particularly in emerging markets, stimulating further demand. Governments are also supporting research and innovation, ensuring that effective antiarrhythmic therapies reach a wider population in need of care.
Market Trends:
Shift Towards Personalized Medicine in Arrhythmia Treatment
A key trend in the Antiarrhythmic Drugs Market is the growing emphasis on personalized medicine. Tailoring treatments based on individual genetic profiles enhances the effectiveness of therapies. Pharmaceutical companies are focusing on developing drugs that cater to specific patient subgroups, optimizing outcomes for those with distinct arrhythmia conditions. This shift towards personalized care is expected to drive the demand for specialized antiarrhythmic treatments. These therapies offer more targeted and precise options, leading to fewer side effects and better long-term results for patients.
Integration of Digital Health Solutions in Treatment Management
The integration of digital health solutions, such as wearable devices and mobile health applications, is transforming the management of arrhythmia conditions. Patients are increasingly using these technologies to monitor their heart health and medication adherence. The data collected by these devices allows healthcare providers to make more informed decisions about antiarrhythmic drug prescriptions, creating a more connected approach to managing arrhythmia. The ability to track and adjust treatment plans in real-time helps ensure better control of the condition, improving overall patient outcomes.
- For instance, the STROKE AF study shows a 10-fold increase in atrial fibrillation detection rates for stroke patients using the Reveal LINQ™ ICM over three years, compared to standard methods. At 3 years, 21.7% of patients in the device arm had AF detected, compared to 2.4% in controls, with a significant hazard ratio of 10.0.
Focus on Combination Therapies for Enhanced Efficacy
There is a growing trend towards combination therapies in the Antiarrhythmic Drugs Market. Combining antiarrhythmic drugs with other therapeutic agents enhances the efficacy of treatment and reduces the risks associated with monotherapy. This trend is gaining momentum as researchers explore synergistic drug combinations that can offer superior results in managing various types of arrhythmias, ensuring improved patient outcomes. Combination therapies provide a multifaceted approach to treatment, offering more comprehensive management for patients with complex arrhythmia conditions.
- For example, in the ATHENA trial post-hoc analysis, dronedarone significantly reduced the annual stroke rate compared with placebo - 1.2% vs. 1.8% - with a hazard ratio of 0.66 (95% CI: 0.46–0.96; p = 0.027). This finding demonstrates dronedarone’s efficacy in lowering stroke risk among patients with atrial fibrillation or flutter.
Development of Long-Acting Formulations
The development of long-acting formulations is another important trend in the Antiarrhythmic Drugs Market. Extended-release formulations allow for fewer doses throughout the day, enhancing patient compliance and treatment effectiveness. These innovations are especially beneficial for patients requiring chronic treatment for arrhythmias, as they help maintain stable drug levels in the body and reduce the frequency of dose administration. Long-acting drugs help streamline treatment regimens, which leads to higher adherence rates and improved therapeutic outcomes.
Market Challenges Analysis:
Regulatory Hurdles in Drug Approvals
One of the main challenges faced by the Antiarrhythmic Drugs Market is the stringent regulatory requirements for drug approval. The approval process for new antiarrhythmic drugs is lengthy and expensive, often resulting in delays in bringing innovative treatments to market. These regulatory hurdles can deter companies from investing in the development of new antiarrhythmic agents, slowing down market expansion. Regulatory authorities' strict scrutiny ensures patient safety but can also limit the speed at which new treatments become available to the public.
Side Effects and Safety Concerns
The use of antiarrhythmic drugs is often associated with side effects, including proarrhythmia, which can limit their effectiveness. Many of these drugs can cause severe complications if not properly monitored, leading to concerns over their safety. This presents a challenge for the Antiarrhythmic Drugs Market as healthcare providers must balance the potential risks and benefits of these treatments. With growing concerns about patient safety, there is an increasing focus on developing safer alternatives that offer improved efficacy with fewer side effects.
Market Opportunities:
Expanding Access to Healthcare in Emerging Markets
Emerging markets present a significant opportunity for growth in the Antiarrhythmic Drugs Market. Increased healthcare access and improvements in infrastructure are enabling more patients to receive timely treatment for arrhythmias. As healthcare systems in countries such as China and India evolve, there is a growing demand for affordable and effective antiarrhythmic drugs. This opens new avenues for pharmaceutical companies to expand their reach in these high-potential regions. The rise of middle-class populations and increased healthcare spending will continue to drive demand for these therapies.
Technological Innovations in Drug Development
Technological innovations in drug development, including artificial intelligence and biotechnology, offer substantial opportunities for the Antiarrhythmic Drugs Market. These advancements can lead to the discovery of more effective and targeted antiarrhythmic agents, especially for patients with resistant arrhythmias. Such innovations promise to revolutionize treatment strategies, increasing the market potential for pharmaceutical companies focused on developing cutting-edge drugs for arrhythmia management. These technologies can also accelerate the pace of research and improve the overall development cycle of new therapies.
Market Segmentation Analysis:
By Drug Class
The Antiarrhythmic Drugs Market is divided into several drug classes, each serving specific arrhythmia types. Sodium Channel Blockers (Class I), such as Quinidine, Procainamide, Lidocaine, and Flecainide, are commonly used to treat various arrhythmias by inhibiting the sodium channels that regulate heart muscle contraction. Beta Blockers (Class II) like Propranolol, Esmolol, and Metoprolol reduce heart rate and blood pressure, making them effective in controlling atrial fibrillation and other arrhythmic disorders. Potassium Channel Blockers (Class III) like Amiodarone, Dronedarone, and Sotalol work by prolonging the action potential, helping control irregular heart rhythms. Calcium Channel Blockers (Class IV), including Verapamil and Diltiazem, are used to treat supraventricular arrhythmias by blocking calcium influx in cardiac cells. Other drugs like Digoxin and Adenosine are also used for specific arrhythmia types, further enhancing the drug class diversity in this market.
- For instance, metoprolol succinate (Novartis) reduced relapses into atrial fibrillation to 48.7% versus 59.9% for placebo in a double-blind study of 394 patients after cardioversion, as published by Kühlkamp et al. in the Journal of the American College of Cardiology.
By Route of Administration
The Antiarrhythmic Drugs Market includes several routes of administration that cater to different patient needs. Oral administration is commonly used due to its convenience and suitability for long-term treatment. Parenteral/Injectable methods are used when immediate drug absorption is required, particularly in emergency settings. Intravenous (IV) administration provides rapid action and is ideal for acute conditions requiring precise drug delivery. Other methods, including sublingual or transdermal delivery, are emerging but remain less common. The choice of route affects drug efficacy and patient compliance, influencing the market’s growth in these segments.
By Indication (Disease Type)
The Antiarrhythmic Drugs Market addresses various arrhythmias, including Atrial Fibrillation (AF), Supraventricular Tachycardia (SVT), Ventricular Arrhythmias, and Bradyarrhythmias. AF is the most common arrhythmia treated with antiarrhythmic drugs due to its widespread occurrence in the aging population. SVT and Ventricular Arrhythmias also represent significant markets as they are often associated with severe, life-threatening conditions. Bradyarrhythmias, characterized by a slower-than-normal heart rate, require treatment to prevent further complications. The diverse range of indications provides opportunities for drug developers to target multiple patient groups and drive growth in the market.
- For instance, intravenous amiodarone (Fresenius Kabi and others) controlled life-threatening ventricular tachyarrhythmias in 50% of patients within the first 24 hours of intravenous administration in a study of 22 critically ill coronary patients.
By Distribution Channel
The Antiarrhythmic Drugs Market benefits from various distribution channels, including Hospital Pharmacies, Retail Pharmacies, Online Pharmacies/E-commerce, and other specialized distribution avenues. Hospital pharmacies play a crucial role, particularly in the acute treatment of arrhythmias in clinical settings. Retail pharmacies ensure broad access to antiarrhythmic drugs for outpatient care. The growing trend toward Online Pharmacies and E-commerce platforms offers greater accessibility, convenience, and competitive pricing, especially in regions with expanding digital healthcare infrastructure. These distribution channels contribute to increased drug availability, enhancing market penetration and accessibility for patients worldwide.
Segmentation:
By Drug Class
- Sodium Channel Blockers (Class I): Quinidine, Procainamide, Lidocaine, Flecainide
- Beta Blockers (Class II): Propranolol, Esmolol, Metoprolol
- Potassium Channel Blockers (Class III): Amiodarone, Dronedarone, Sotalol
- Calcium Channel Blockers (Class IV): Verapamil, Diltiazem
- Others: Digoxin, Adenosine
By Route of Administration
- Oral
- Parenteral/Injectable
- Intravenous (IV)
- Other
By Indication (Disease Type)
- Atrial Fibrillation (AF)
- Supraventricular Tachycardia (SVT)
- Ventricular Arrhythmias
- Bradyarrhythmias
- Other arrhythmias
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies/E-commerce
- Other distribution channels
By Regional
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The Antiarrhythmic Drugs Market in North America held approximately 37.55 % of the global market share in 2024. The region benefits from well‑developed healthcare infrastructure and high prevalence of cardiovascular disorders, which increase demand for arrhythmia therapies. It features a strong pipeline of innovative agents and regulatory support from bodies like the Food and Drug Administration (FDA) that facilitate approvals and market access. Insurance coverage and reimbursement schemes increase patient access to antiarrhythmic drugs, boosting uptake. The United States dominates within the region thanks to high arrhythmia treatment rates and robust clinical research. High per‑capita spending on cardiovascular care drives further growth. The region maintains its leadership due to these favorable health‑system and demographic drivers.
Europe
In Europe the Antiarrhythmic Drugs Market accounted for about 29.5 % of global share in 2024. Aging populations and increasing arrhythmia incidence in countries such as Germany, the UK and France create sustained demand. Healthcare systems across the region emphasise cardiovascular disease management programs and expand access to arrhythmia therapies. Strong regulation by the European Medicines Agency (EMA) ensures safety and effectiveness of novel treatments, which supports adoption. Differences in reimbursement policies across countries affect uptake speed, but overall the trend remains positive. Manufacturers target the region with new formulations and long‑acting therapies, leveraging high patient awareness. The region positions itself as a stable growth market despite moderate pace compared to emerging regions.
Asia Pacific and Other Regions
The Asia Pacific region held roughly 24.3 % share of the global Antiarrhythmic Drugs Market in 2024 and represents the fastest‑growing region. Countries such as China, India and Japan face rising cardiovascular disease incidence, expanding middle‑class populations and improving healthcare access, which drive market growth. Healthcare infrastructure improvements and regulatory reforms accelerate drug approvals and distribution. Latin America and the Middle East & Africa regions show smaller shares but present emerging opportunities as healthcare investment increases and arrhythmia awareness grows. In Latin America, growing healthcare spending and partnerships between local and global pharmaceutical firms are broadening access. In the Middle East & Africa region, government initiatives to tackle cardiovascular disease burden and upgrade systems spur uptake of arrhythmia therapies. These dynamics position these regions for long‑term growth in the global market context.
Key Player Analysis:
- Pfizer Inc.
- Novartis AG
- Sanofi S.A.
- GlaxoSmithKline plc
- Bristol‑Myers Squibb Company
- Merck & Co., Inc.
- AstraZeneca plc
- Johnson & Johnson (Janssen Pharma)
- Mylan N.V. (now Viatris Inc.)
- Bayer AG
- Abbott Laboratories
- Teva Pharmaceutical Industries Ltd.
- Baxter International Inc.
- Mayne Pharma
- Upsher‑Smith Laboratories LLC
Competitive Analysis:
The competitive landscape of the Antiarrhythmic Drugs Market features several major pharmaceutical firms that drive innovation and portfolio expansion. Companies such as Pfizer Inc., Novartis AG, Sanofi S.A. and GlaxoSmithKline plc maintain strong positions through extensive research, well‑established brands and global reach. These players focus on developing next‑generation antiarrhythmic agents and securing regulatory approvals to expand market share. They negotiate broad distribution agreements and engage in strategic partnerships to extend geographic penetration. Mid‑sized firms and generics specialists enhance competitive pressure by offering cost‑effective options and accelerating market access. Pricing strategies and patent lifecycles further influence competitive dynamics by shaping entry timing for new drugs and generics. Continuous investment in clinical trials and the introduction of novel therapies determine long‑term market positioning and influence competitive intensity.
Recent Developments:
- In September 2025, Pfizer Inc. announced the acquisition of Metsera, a clinical-stage biopharmaceutical company focused on obesity and cardiometabolic diseases. This acquisition, valued at approximately $4.9 billion, propels Pfizer’s presence in the antiarrhythmic and broader cardiovascular drug market by adding differentiated oral and injectable therapy candidates to its pipeline.
Report Coverage:
The research report offers an in-depth analysis based on Drug Class, Route of Administration, Indication (Disease Type) and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Continued development of targeted therapies will drive the market as precision medicine gains traction.
- Emerging markets, particularly in Asia Pacific, will fuel demand due to increasing healthcare access and rising arrhythmia incidences.
- Increased adoption of digital health solutions, including wearable devices for monitoring arrhythmias, will create new avenues for market growth.
- The growing geriatric population, with higher arrhythmia rates, will continue to expand the patient base for antiarrhythmic drugs.
- Combination therapies are expected to gain prominence, providing better efficacy and minimizing side effects.
- Ongoing advancements in biotechnology will lead to more efficient, personalized antiarrhythmic treatments.
- Regulatory support and faster drug approvals, especially for generics, will drive competitive dynamics in the market.
- The development of long-acting formulations will enhance patient adherence, further promoting market expansion.
- Increasing awareness about cardiovascular health will lead to earlier diagnosis and proactive treatment, expanding market opportunities.
- Strategic partnerships and collaborations among pharmaceutical companies will enable broader distribution networks and global reach.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Antiarrhythmic Drugs Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Antiarrhythmic Drugs Market projected to grow between 2024 and 2032?
Which Antiarrhythmic Drugs Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Antiarrhythmic Drugs Market?
Who are the leading companies in the Antiarrhythmic Drugs Market?
Which region commanded the largest share of the Antiarrhythmic Drugs Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 983.84 million → 2032: USD 1,579.97 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Antiarrhythmic Drugs Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Antiarrhythmic Drugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Antiarrhythmic Drugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Antiarrhythmic Drugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Antiarrhythmic Drugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Antiarrhythmic Drugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Antiarrhythmic Drugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Antiarrhythmic Drugs Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 983.84 million → 2032: USD 1,579.97 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Antiarrhythmic Drugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Antiarrhythmic Drugs Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Antiarrhythmic Drugs Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Antiarrhythmic Drugs Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

