
Firmness claims now carry body contour care
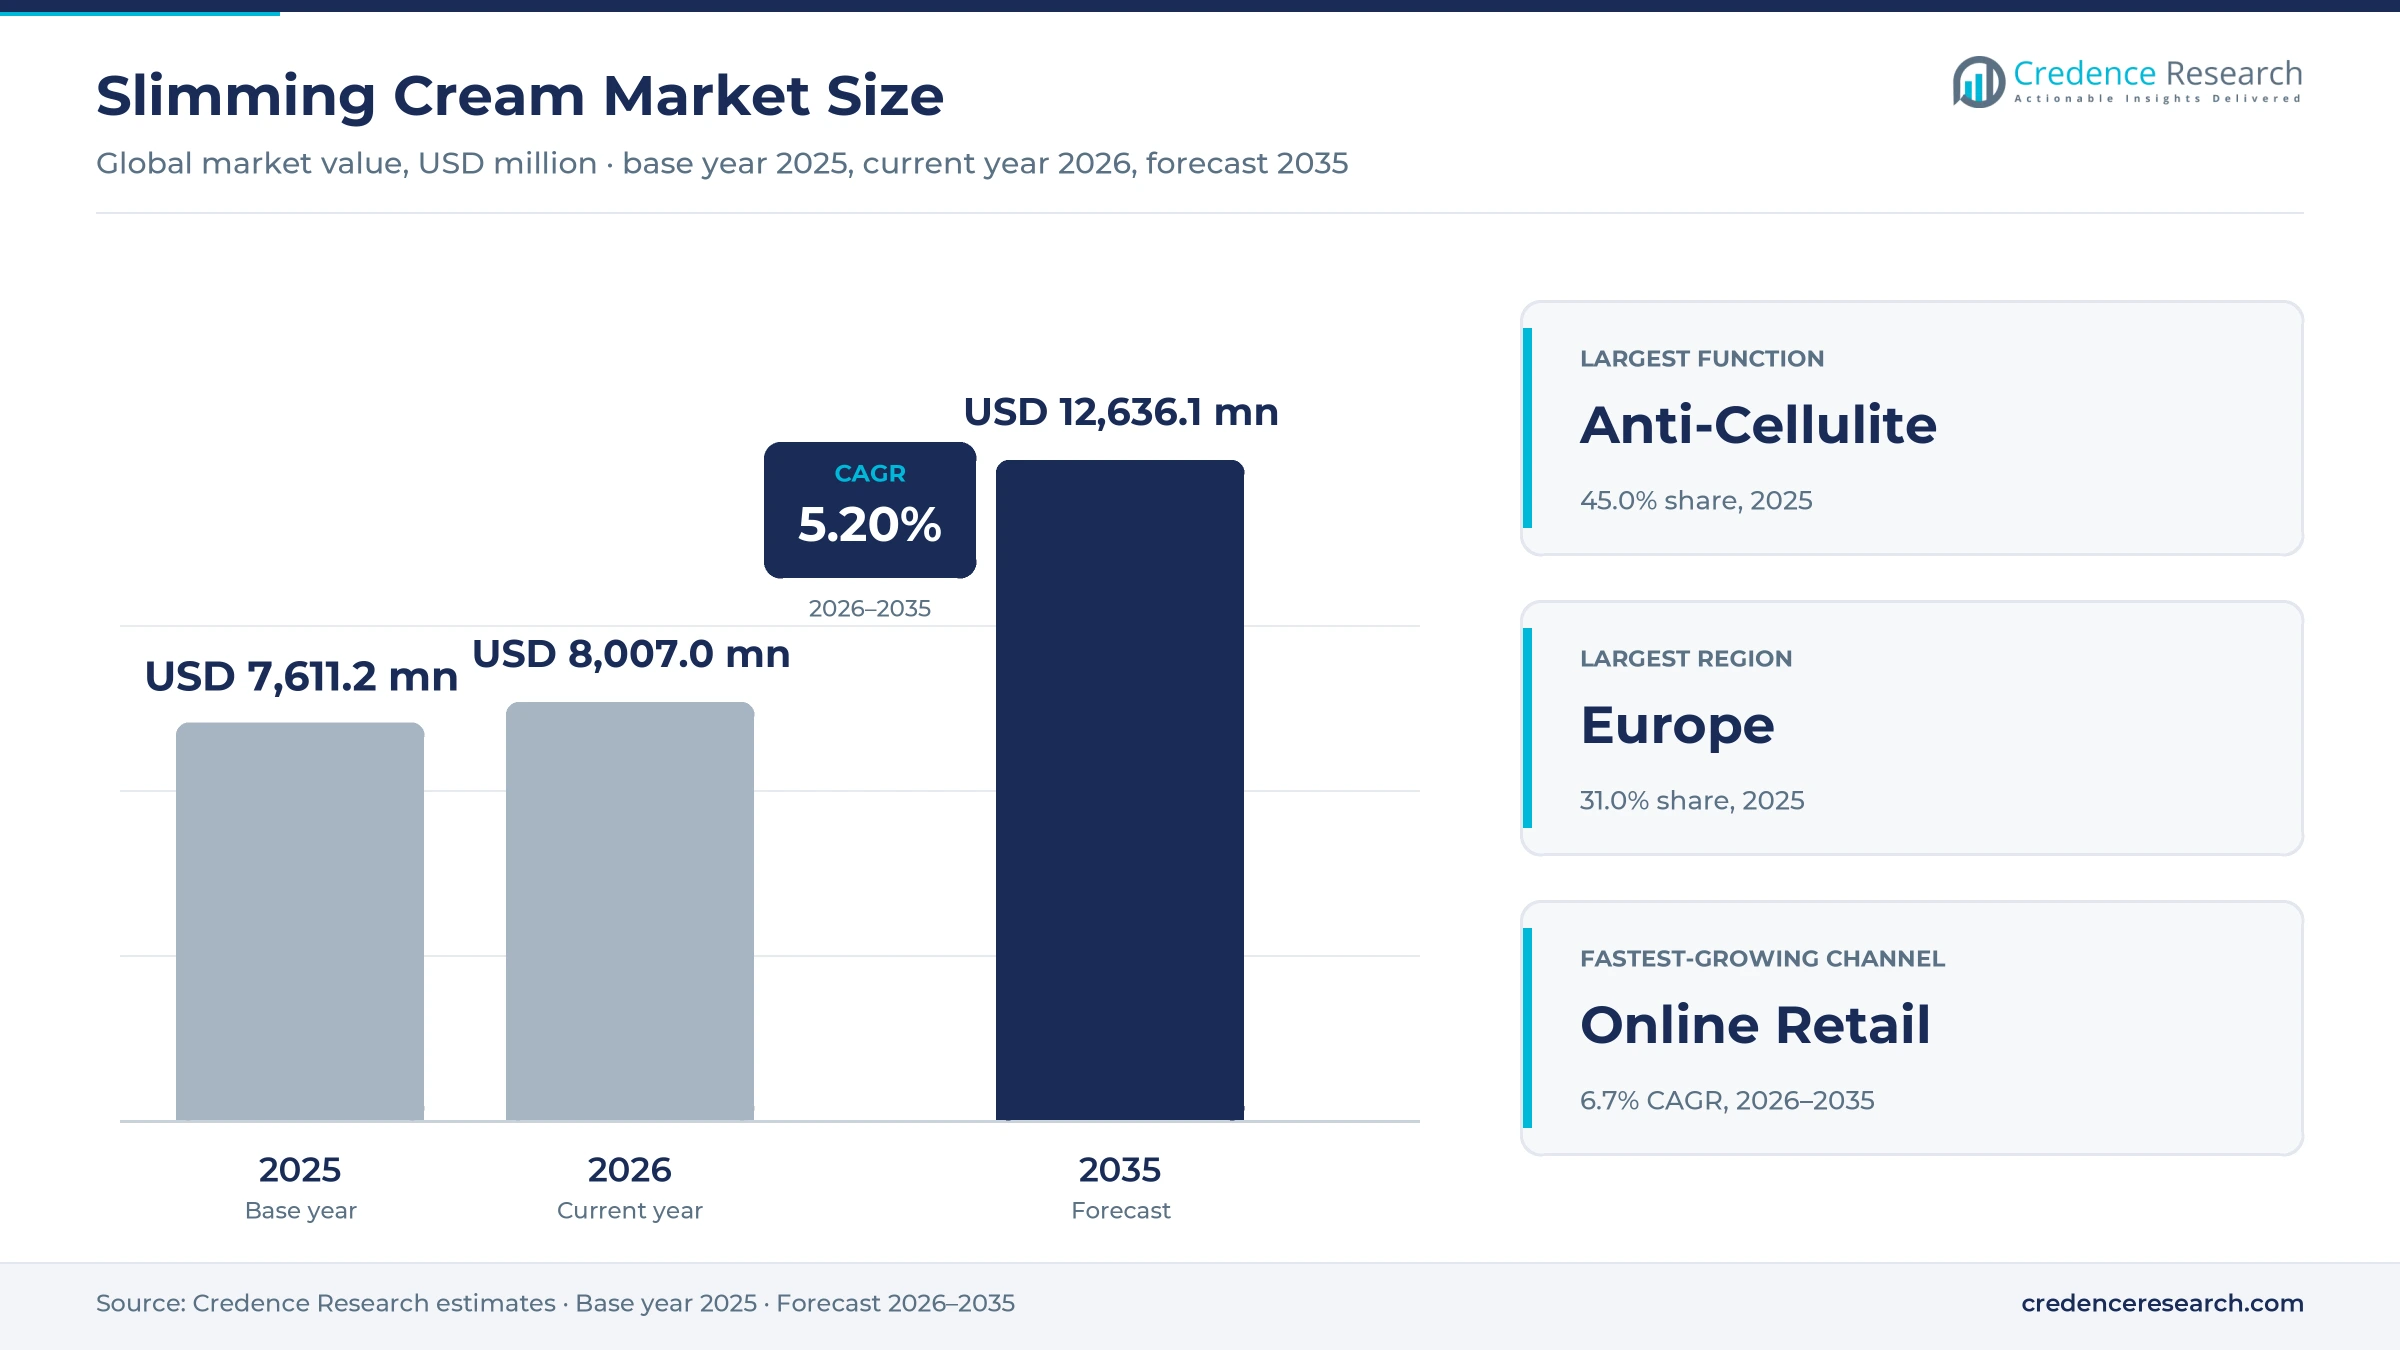
The global slimming cream market was valued at USD 7.61 billion in 2025 and is projected to increase from USD 8.01 billion in 2026 to USD 12.64 billion by 2035, registering a CAGR of 5.20% during 2026–2035. Demand comes from women treating cellulite on thighs and hips, from consumers who want firmer skin after weight loss, and from spas and clinics that pair topical products with body contouring sessions. Europe held the largest regional share, 31.0% in 2025, because French, Italian and Spanish pharmacies keep body contour care on their dermocosmetic shelves. Asia Pacific is the fastest-growing region at 6.2% a year as Chinese, Korean and Indian buyers trade up in body care. The main commercial change is the spread of weight-loss medicines, which moves the buying reason from losing centimeters toward tightening skin. Brands now compete on measured firmness, texture and fragrance rather than on promises of fat reduction.
Body contour care sells smoother skin rather than fat loss
The estimate counts creams, gels and emulsions applied to the thighs, hips, abdomen, buttocks and arms with slimming, anti-cellulite, draining or firming claims. Mass, pharmacy, prestige and professional products are included, whether sold in stores, online, through direct selling or used in spa and clinic treatments.
Oral slimming supplements, prescription weight-loss medicines, injectable fat dissolvers and energy-based body contouring devices sit outside the estimate. Most value moves from brand owners to pharmacies, department stores, beauty chains and online retailers, while contract manufacturers in France, Italy, Korea and China supply many smaller labels.
Slimming Cream Market Insights
- The market is valued at USD 7.61 billion in 2025 and is projected to reach USD 12.64 billion by 2035, growing at a 5.20% CAGR as firming care replaces fat-loss promises.
- Europe led with 31.0% of 2025 value, because pharmacy dermocosmetic brands such as Elancyl hold leading positions in France, Spain, Greece, Portugal and Poland.
- Anti-Cellulite products held 45.0% of 2025 value, because cellulite is estimated to affect 80% to 90% of postpubertal women.
- WHO issued its first guideline on GLP-1 medicines for obesity on Dec. 1, 2025, which widens the base of consumers seeking skin firming after weight loss.
- Online Retail grows fastest at 6.7% a year, as U.S. e-commerce reached 17.9% of retail sales in the third quarter of 2026.
Anti-cellulite creams lead while firming gels gain ground
Why do creams lead while gels grow fastest?
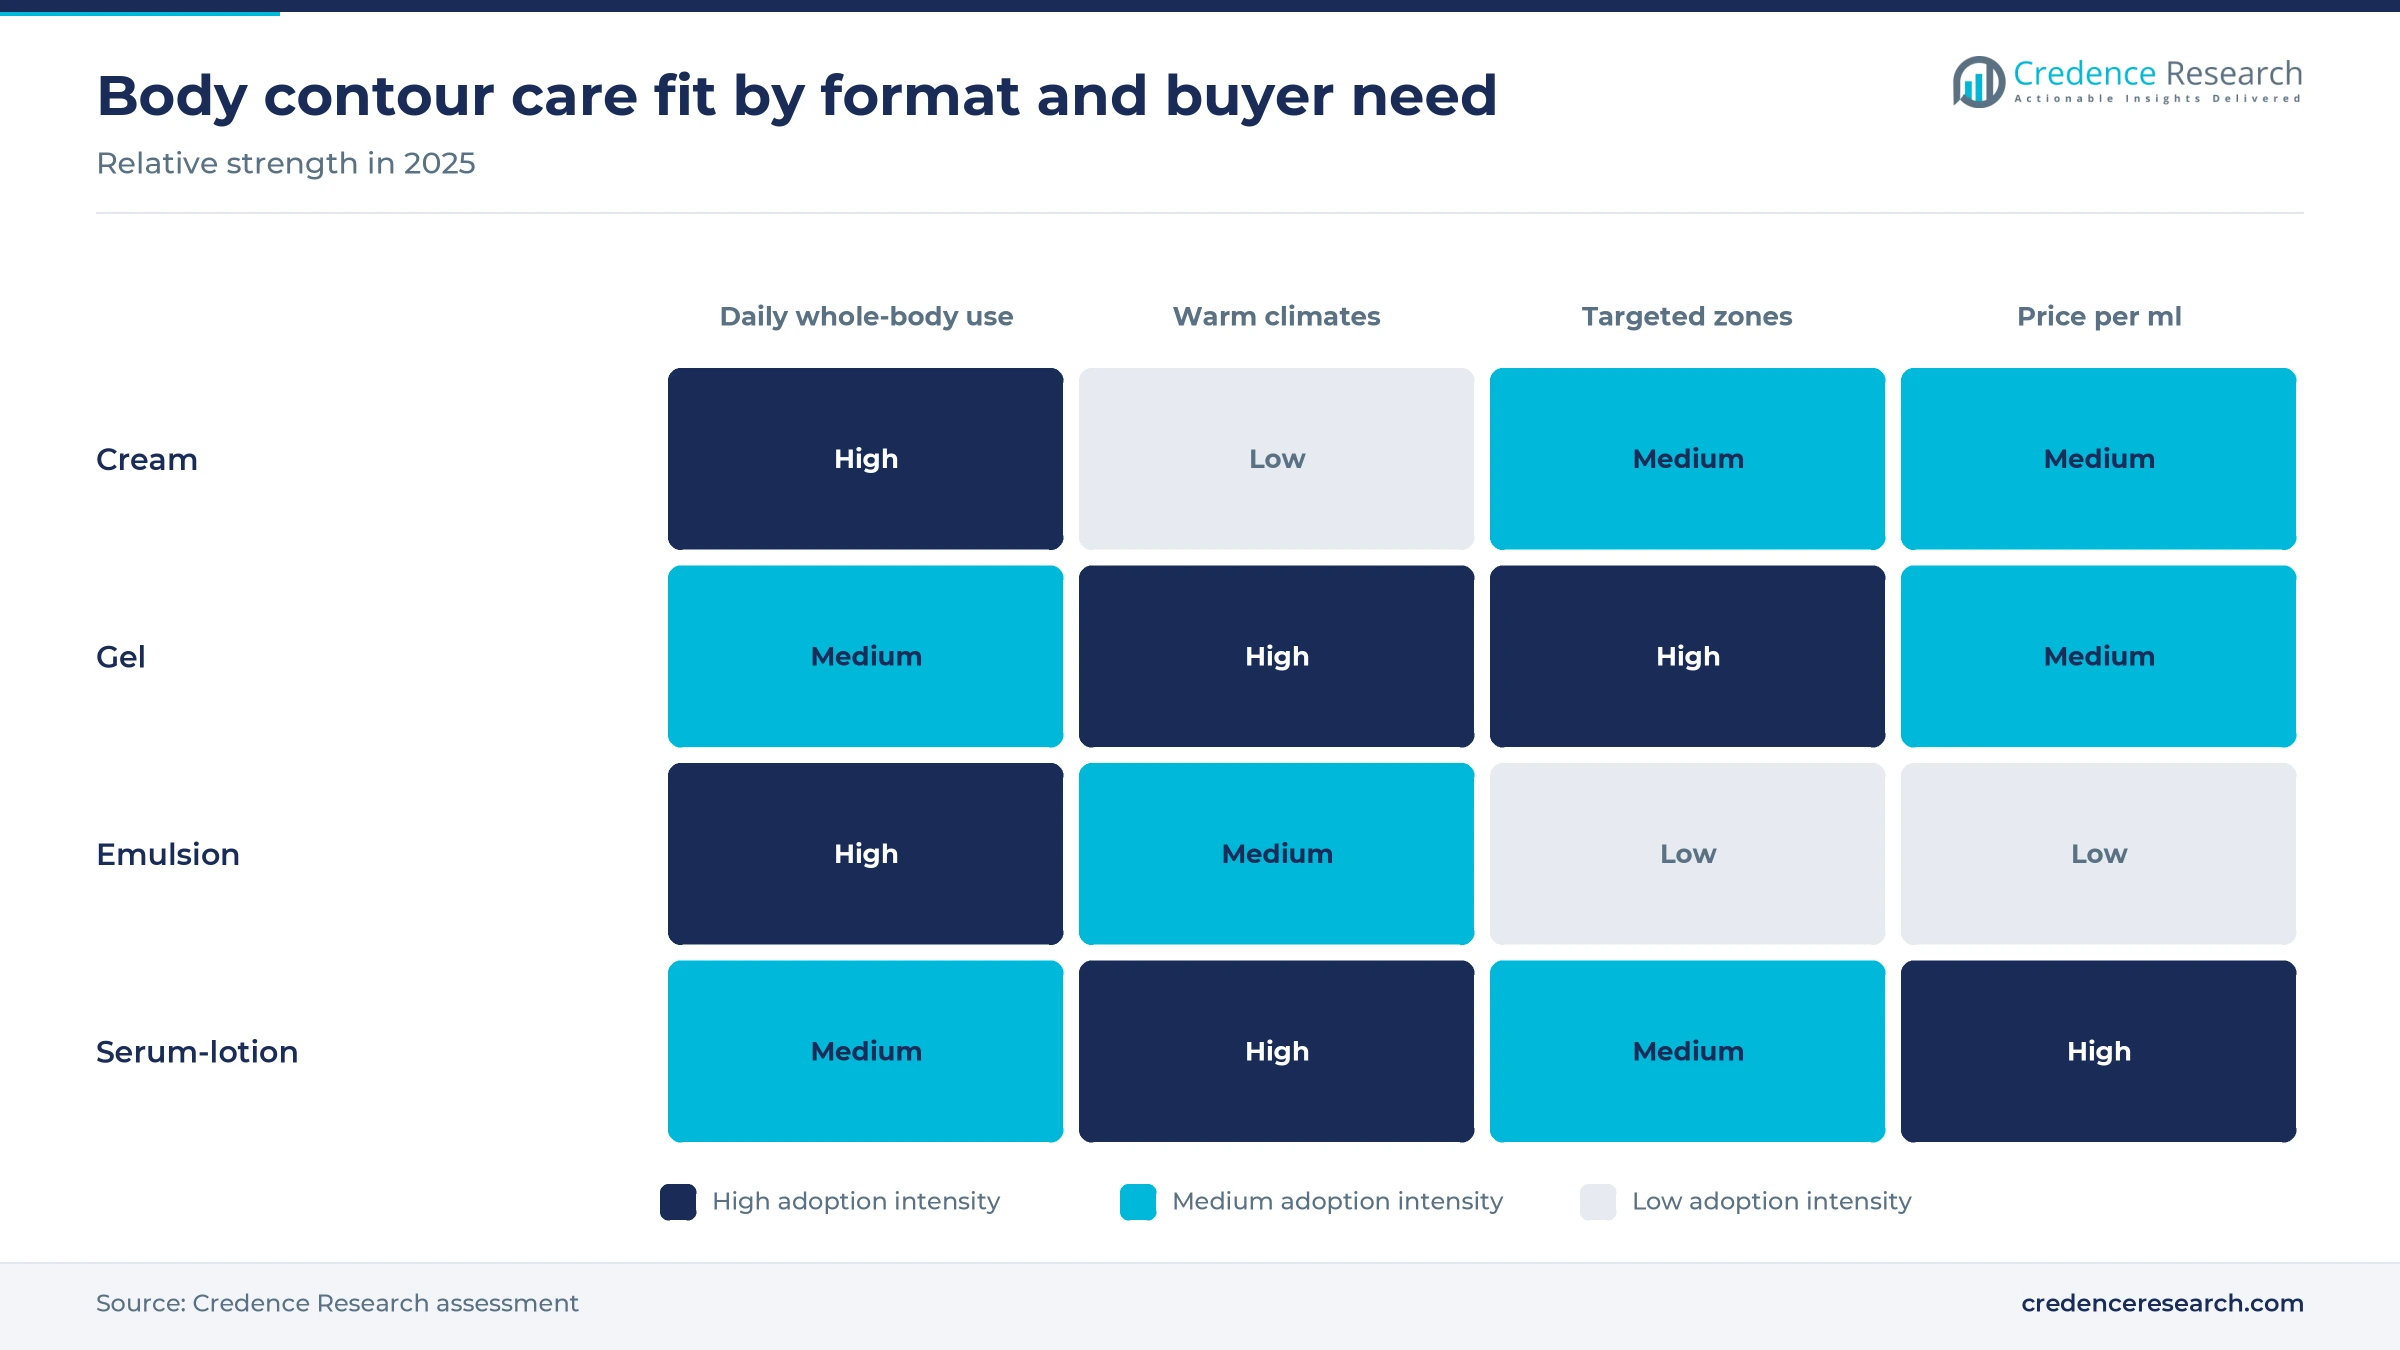
Based on type, the market is categorized into cream, emulsion and gel formats. Cream formats led with 52.0% of 2025 value because rich textures suit daily whole-body use, and a 300 ml Somatoline Cosmetic firming body cream sells for about EUR 0.12 per milliliter, as the pricing table shows. Gel formats grow fastest at 6.1% a year as cooling and fast-absorbing textures win in warm climates, with VLCC selling its 200 g Proshape slimming gel at INR 1,199 in India and Shiseido a sculpting gel in Asia.
Why do anti-cellulite products lead while firming care grows fastest?
Based on function, the market is categorized into anti-cellulite, firming and toning, and fat-burning products. Anti-Cellulite products led with 45.0% of 2025 value because dedicated anticellulite lines fill pharmacy and perfumery shelves, and Lookfantastic lists Collistar's 400 ml anticellulite cryo-gel at GBP 58 in November 2026. Firming & Toning care grows fastest at 6.3% a year as brands reposition, and Nivea launched a Q10 Firming + Energizing Body Serum-Lotion in August 2025 that claims visibly firmer skin in seven days.
Why do pharmacies lead while online retail grows fastest?
Based on distribution channel, the market is categorized into supermarkets and hypermarkets, pharmacies and drug stores, specialty stores, online retail and others. Pharmacies/Drug Stores led with 30.0% of 2025 value because European buyers seek advice at the counter, and Elancyl, sold in more than 20 countries, holds leading positions in five European pharmacy markets. Online Retail grows fastest at 6.7% a year, as Sephora and Clarins sell body contour care on auto-replenish and subscription, which turns a purchase made every few weeks into a scheduled reorder.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Type | Cream | 52.0% | Gel | 6.1% |
| By Function | Anti-Cellulite | 45.0% | Firming & Toning | 6.3% |
| By Distribution Channel | Pharmacies/Drug Stores | 30.0% | Online Retail | 6.7% |
Price per milliliter splits mass and prestige body care
Shelf prices span about USD 0.10 to USD 0.40 per milliliter, a fourfold gap between mass firming gel-creams and prestige cellulite treatments of the same 200 ml size. Mass brands price against ordinary body lotion and win on supermarket reach, while prestige brands justify higher prices with consumer test results and fragrance. Pharmacy brands sit between them and rely on advice at the counter. Refills, value sizes and subscription discounts of 5% to 10% online now shape the price that loyal buyers actually pay.
| Product or pack | Typical price or fee | Basis |
|---|---|---|
| Nivea Skin Firming and Toning Gel-Cream with Q10, 6.7 oz | USD 19.83, about USD 0.10 per ml | Walmart.com listing, November 2026 |
| Sol de Janeiro Brazilian Bum Bum Cream, 240 ml | USD 48.00, USD 0.20 per ml | Sephora.com listing, November 2026 |
| Clarins Body Fit Active, 6.7 oz | USD 80.00, about USD 0.40 per ml | Clarins USA listing, November 2026 |
| Collistar Anticellulite Cryo-Gel, 400 ml | GBP 58.00, about GBP 0.15 per ml | Lookfantastic listing, November 2026 |
| Somatoline Cosmetic daily firming body cream, 300 ml | EUR 34.90, about EUR 0.12 per ml | Cosmeticobs, May 2024 |
| VLCC Clinic Prosculpt Cellulite Reduction Gel, 90 g | INR 3,499 | VLCC online store, November 2026 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Cellulite, weight-loss drugs and Asian demand lift sales
Near-universal cellulite keeps a stable buyer base
Cellulite gives this market a buyer base that does not depend on weight, because it appears in lean and heavy women alike. A 2022 study in Plastic and Reconstructive Surgery Global Open estimates that it affects 80% to 90% of postpubertal women. Because the condition returns, users buy again and treatment is a routine rather than a one-off purchase. Clarins says 35% of 108 women in a consumer self-assessment saw dimpled skin look reduced after 28 days with Body Fit Active, a modest result that brands still use in marketing. Modest results still sell, because buyers treat cellulite care as maintenance, which keeps anti-cellulite products the largest function by value. Salons that sell a take-home cream between cellulite treatment sessions keep clients buying between appointments.
Weight-loss drugs widen demand for skin firming
Weight-loss medicines are creating new buyers for firming care, because fast loss of fat often leaves looser skin on the abdomen, arms and thighs. Obesity affects more than 1 billion people, and the WHO issued its first guideline on GLP-1 medicines for adults with obesity on Dec. 1, 2025. The agency also projects that these therapies will reach fewer than 10% of those who could benefit by 2030, so most demand for body care still comes from people outside drug treatment. IMAGE Skincare launched VOL.U.LIFT Body in August 2026, saying it was tested with current GLP-1 and GIP patients. Firming & Toning care grows at 6.3% a year, the fastest rate among functions.
Asian beauty spending lifts body care volumes
Rising beauty spending in Asia lifts body contour care, because buyers who already use multi-step facial routines are extending them to the body. China's National Bureau of Statistics reported cosmetics retail sales of 465.3 billion yuan in 2025, up 5.1% from 2024. South Korean cosmetics exports reached a record USD 11.43 billion in 2025, up 12.3%, according to the Ministry of Food and Drug Safety, with Japan taking USD 1.1 billion. Shiseido sells its Advanced Body Creator Super Slimming Reducer across Asia and Europe, which shows how Asian brand owners carry body care abroad. Brands with Asian production and light gel textures are best placed to win this volume.
Pharmacy advice sustains premium European demand
European pharmacies sustain premium pricing, because buyers trust pharmacists to recommend body care that suits their skin and budget. Elancyl, which Cantabria Labs bought from Pierre Fabre in November 2020, is sold in more than 20 countries and holds leading positions in France, Spain, Greece, Portugal and Poland after 45 years of development at Pierre Fabre, according to BeautyMatter. Bolton Group runs campaigns for its Somatoline Cosmetic line in Belgium, Spain, France, Greece and Switzerland under the line "Feel that it works." Pharmacies/Drug Stores hold 30.0% of 2025 value. This channel rewards brands that train counter staff and fund in-store sampling, which smaller labels find costly to match.
Firming claims and caffeine actives reshape the category
Firmness replaces centimeter loss as the main claim
Brands are shifting from fat-loss promises toward firmness and skin quality to address regulator scrutiny and buyer skepticism, creating openings for lifting creams across mass and prestige ranges. Cosmeticobs described a "180-degree turn" for the slimming category toward firmness in May 2024, citing Clarins' Body Firming Lift Cream at EUR 69 for 200 ml and a full Somatoline firming range. Nivea relaunched its Firming Body Lotion with a Collagen Boost Complex of Q10 and vitamin C in August 2025. Firming claims are easier to substantiate with instrument and consumer tests than claims of lost centimeters. Brands that hold clinical firmness data can defend premium prices as the claim mix changes.
Plant caffeine and natural-origin formulas gain shelf space
Formulators are shifting toward plant-derived caffeine and natural-origin bases to meet clean beauty requirements from retailers and buyers. Clarins says Body Fit Active contains 96% ingredients of natural origin, with organic matcha and plant caffeine from the arabica coffee shrub. Sephora lists Sol de Janeiro's Bum Bum Cream with guarana extract, which the retailer calls caffeine-rich, as vegan and refillable at USD 48 for 240 ml. Interest in botanical caffeine sources links body care to food and beverage supply chains for green coffee and guarana. Extract quality varies by harvest, so formulators now ask for standardized caffeine content on supplier certificates. Suppliers of standardized plant extracts gain pricing power with brands that market natural origin.
Online sales open a direct route to repeat buyers
Online retail creates an opening for direct sales to repeat buyers, because body contour care is bought every few weeks and depends on reviews. The Census Bureau reported that e-commerce reached 17.9% of U.S. retail sales in the third quarter of 2026. Sephora sells Bum Bum Cream on auto-replenish with refills, and Clarins sells Body Fit Active on subscription with free samples, which locks in reorders before buyers compare rival brands. Online Retail grows at 6.7% a year, the fastest of all channels. Brands that publish test results and before-and-after methods on product pages convert search traffic best, while thin evidence pages lose buyers to rivals.
Cheaper weight-loss drugs open a firming niche in India
India offers an opening for post-weight-loss firming care, because the price of semaglutide fell sharply once its patent expired in March 2026. BusinessToday reported that generic launches by Sun Pharma, Dr. Reddy's, Zydus, Glenmark and others cut prices by as much as 90% from the branded version. The National Family Health Survey (NFHS-5) found that 24% of Indian women were overweight or obese, up from 20.6% in the prior round. VLCC already sells a Prosculpt cellulite reduction gel at INR 3,499 for 90 g through its clinic brand. Local brands with clinic networks can sell body firming care to drug users at scale.
Claim enforcement and ingredient limits squeeze formulas
Fat-loss claims draw regulator penalties
Fat-loss claims expose brands to penalties, because regulators treat promises of lost inches as claims that need proof. The FTC settled with Beiersdorf on June 29, 2011, over claims that Nivea My Silhouette slimmed users, with a USD 900,000 payment. In January 2014 L'Occitane agreed to pay USD 450,000 over slimming claims for two almond body products. Brands selling fat-burning claims are most exposed, while firming claims carry less risk. EU Regulation No 655/2013 applies the same burden of proof to body care claims sold across the bloc.
China ended slimming as a special-use cosmetic
China has removed the regulatory home of many slimming products, which forces brands to rewrite claims and labels. The five-year transition for body slimming and four other former special-use categories ended on Dec. 31, 2025, so selling products under those approvals became non-compliant from Jan. 1, 2026, according to CIRS. Importers holding old approvals are most exposed, while brands with firming or moisturizing claims can file as ordinary cosmetics.
EU retinol limits constrain body firming formulas
EU limits on vitamin A constrain retinol-based firming formulas, because body products are applied over large areas of skin. Commission Regulation (EU) 2024/996 caps retinol and its esters at 0.05% retinol equivalent in body lotions, against 0.3% in most other products. New products had to comply from Nov. 1, 2025, and noncompliant stock must leave shelves by May 1, 2027. Brands built on high-retinol body serums must reformulate with peptides or bakuchiol.
U.S. listing duties raise costs for small brands
Compliance costs are rising in the United States, because cosmetic makers must now register facilities and list every product with the FDA. The FDA ended its enforcement delay for registration and listing under the Modernization of Cosmetics Regulation Act on July 1, 2024, and the law also requires reporting of serious adverse events. Small direct-to-consumer labels and importers without regulatory staff are most exposed, while large groups spread these costs over wide ranges.
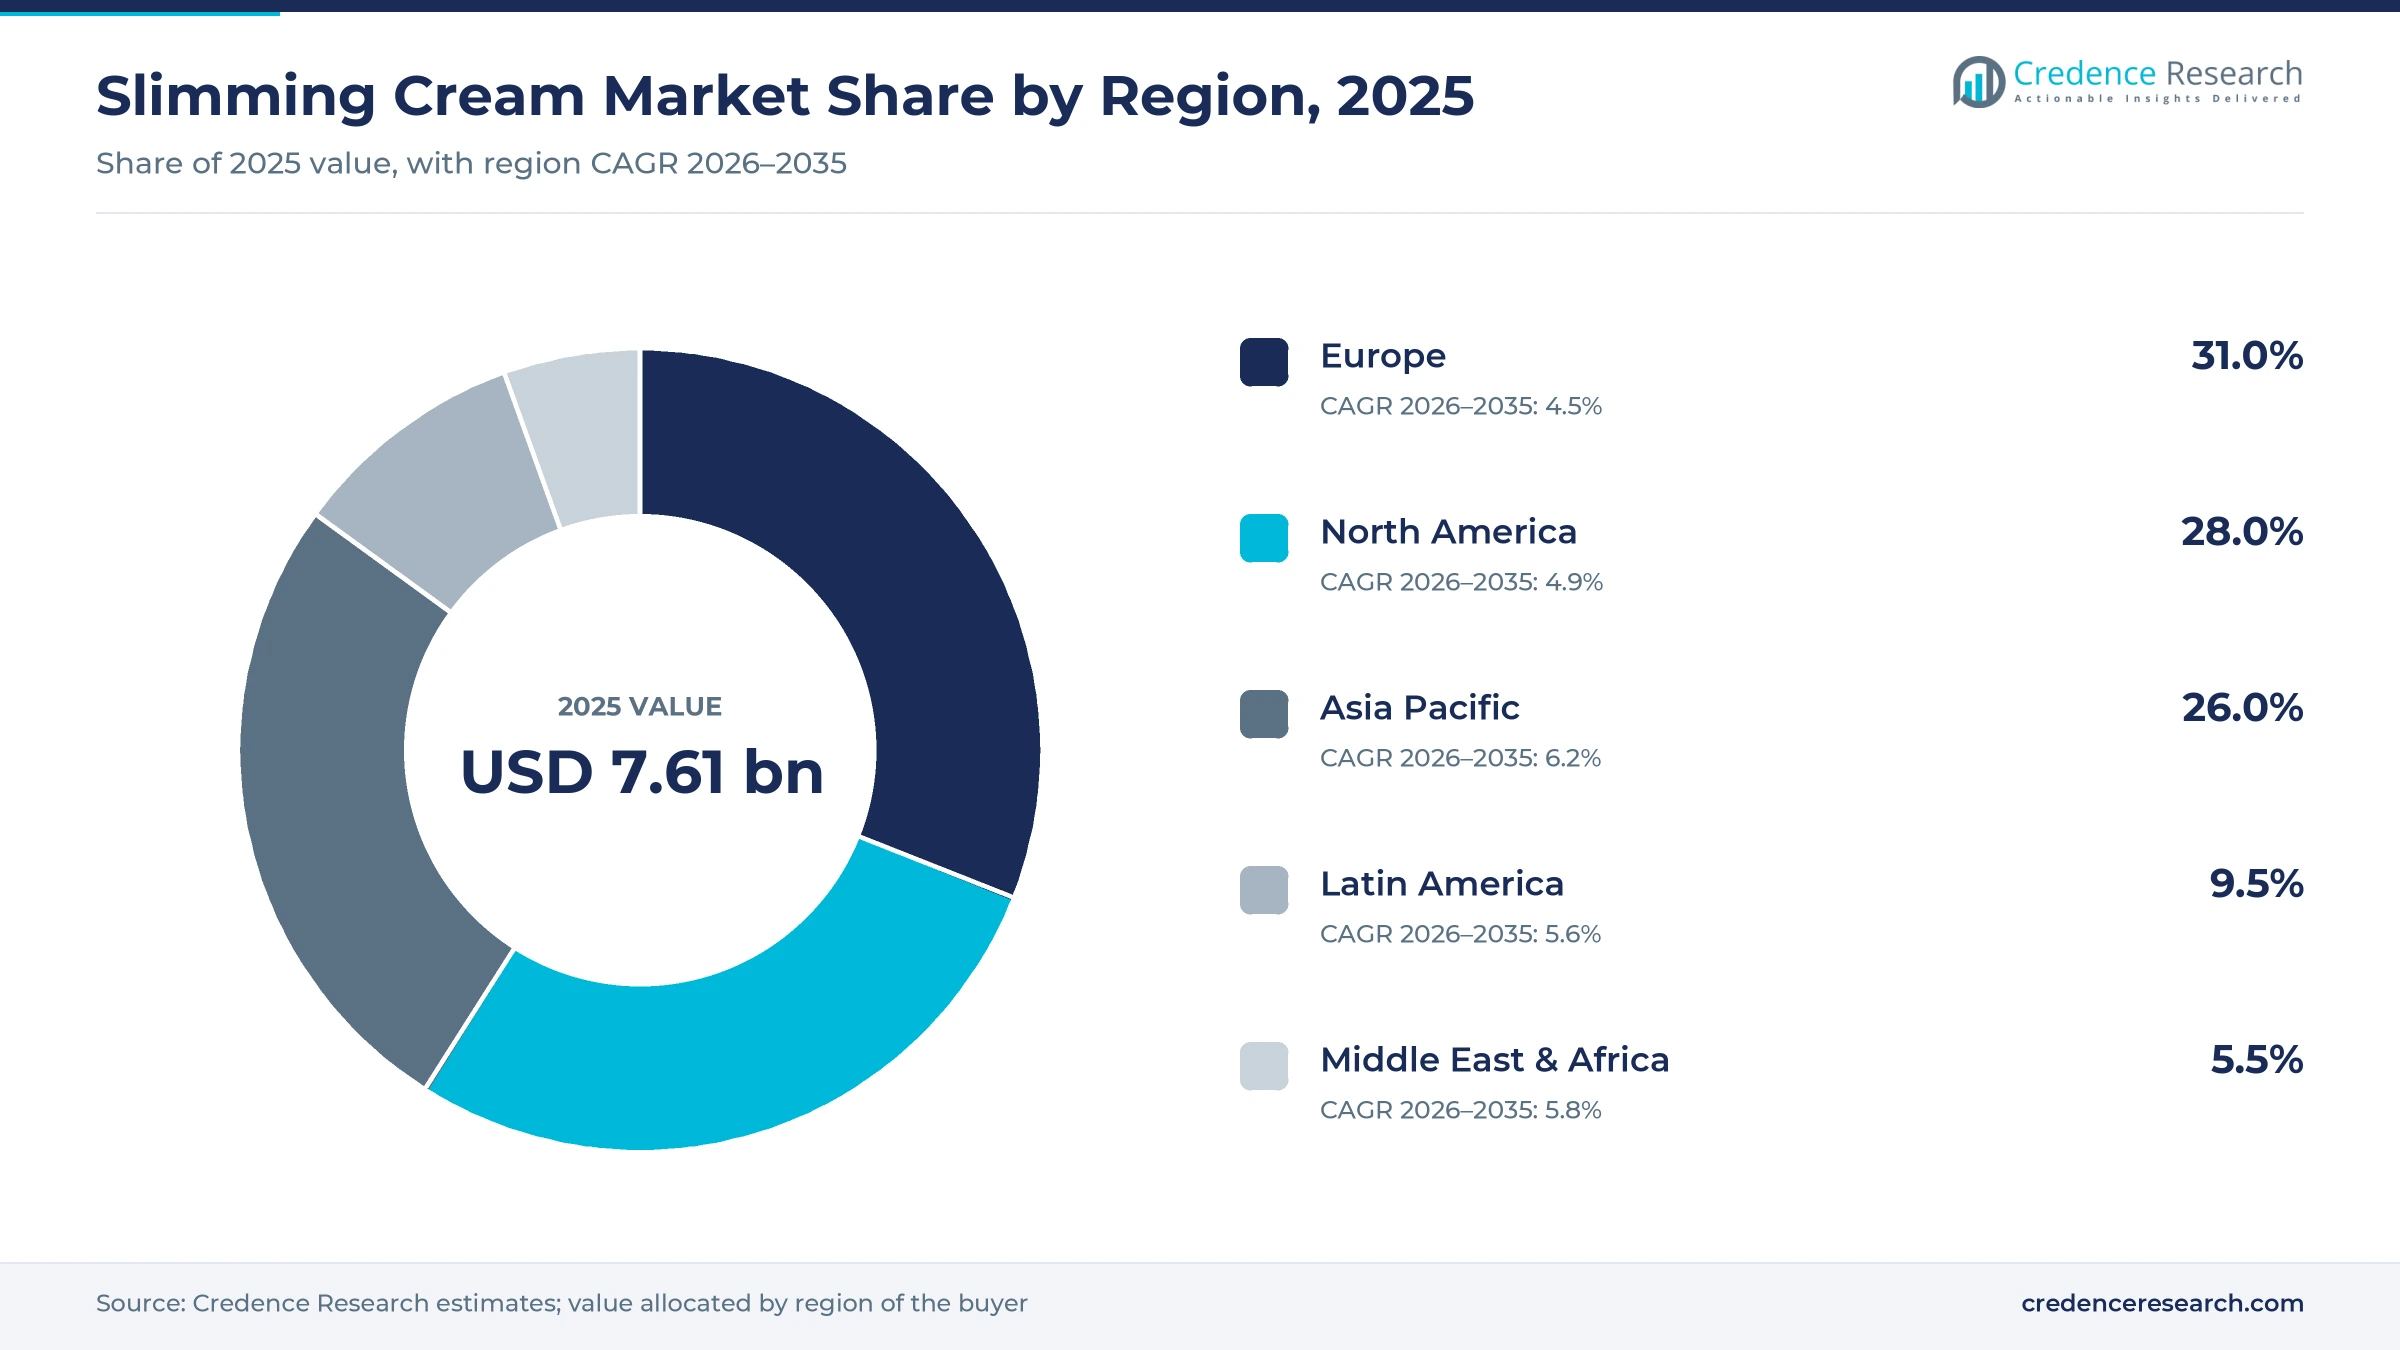
Europe leads on pharmacy body care and claim discipline
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Europe | 2.36 | 31.0% | 4.5% |
| North America | 2.13 | 28.0% | 4.8% |
| Asia Pacific | 1.98 | 26.0% | 6.2% |
| Latin America | 0.72 | 9.5% | 5.5% |
| Middle East & Africa | 0.42 | 5.5% | 5.8% |
Europe leads on pharmacy body care and claim rules
Europe held 31.0% of 2025 value and grows at 4.5% a year, the slowest pace, because the region's mature pharmacy channel already reaches most buyers. France, Italy and Spain host the main specialist brands, including Elancyl, Somatoline Cosmetic and Collistar, alongside Clarins and Biotherm. Commission Regulation (EU) No 655/2013 of July 10, 2013 sets common criteria for justifying cosmetic claims, which keeps fat-loss language cautious. The Somatoline campaign in five European markets, noted above, shows that brands there now sell sensation and self-care rather than lost centimeters.
North America grows on prestige body care and online sales
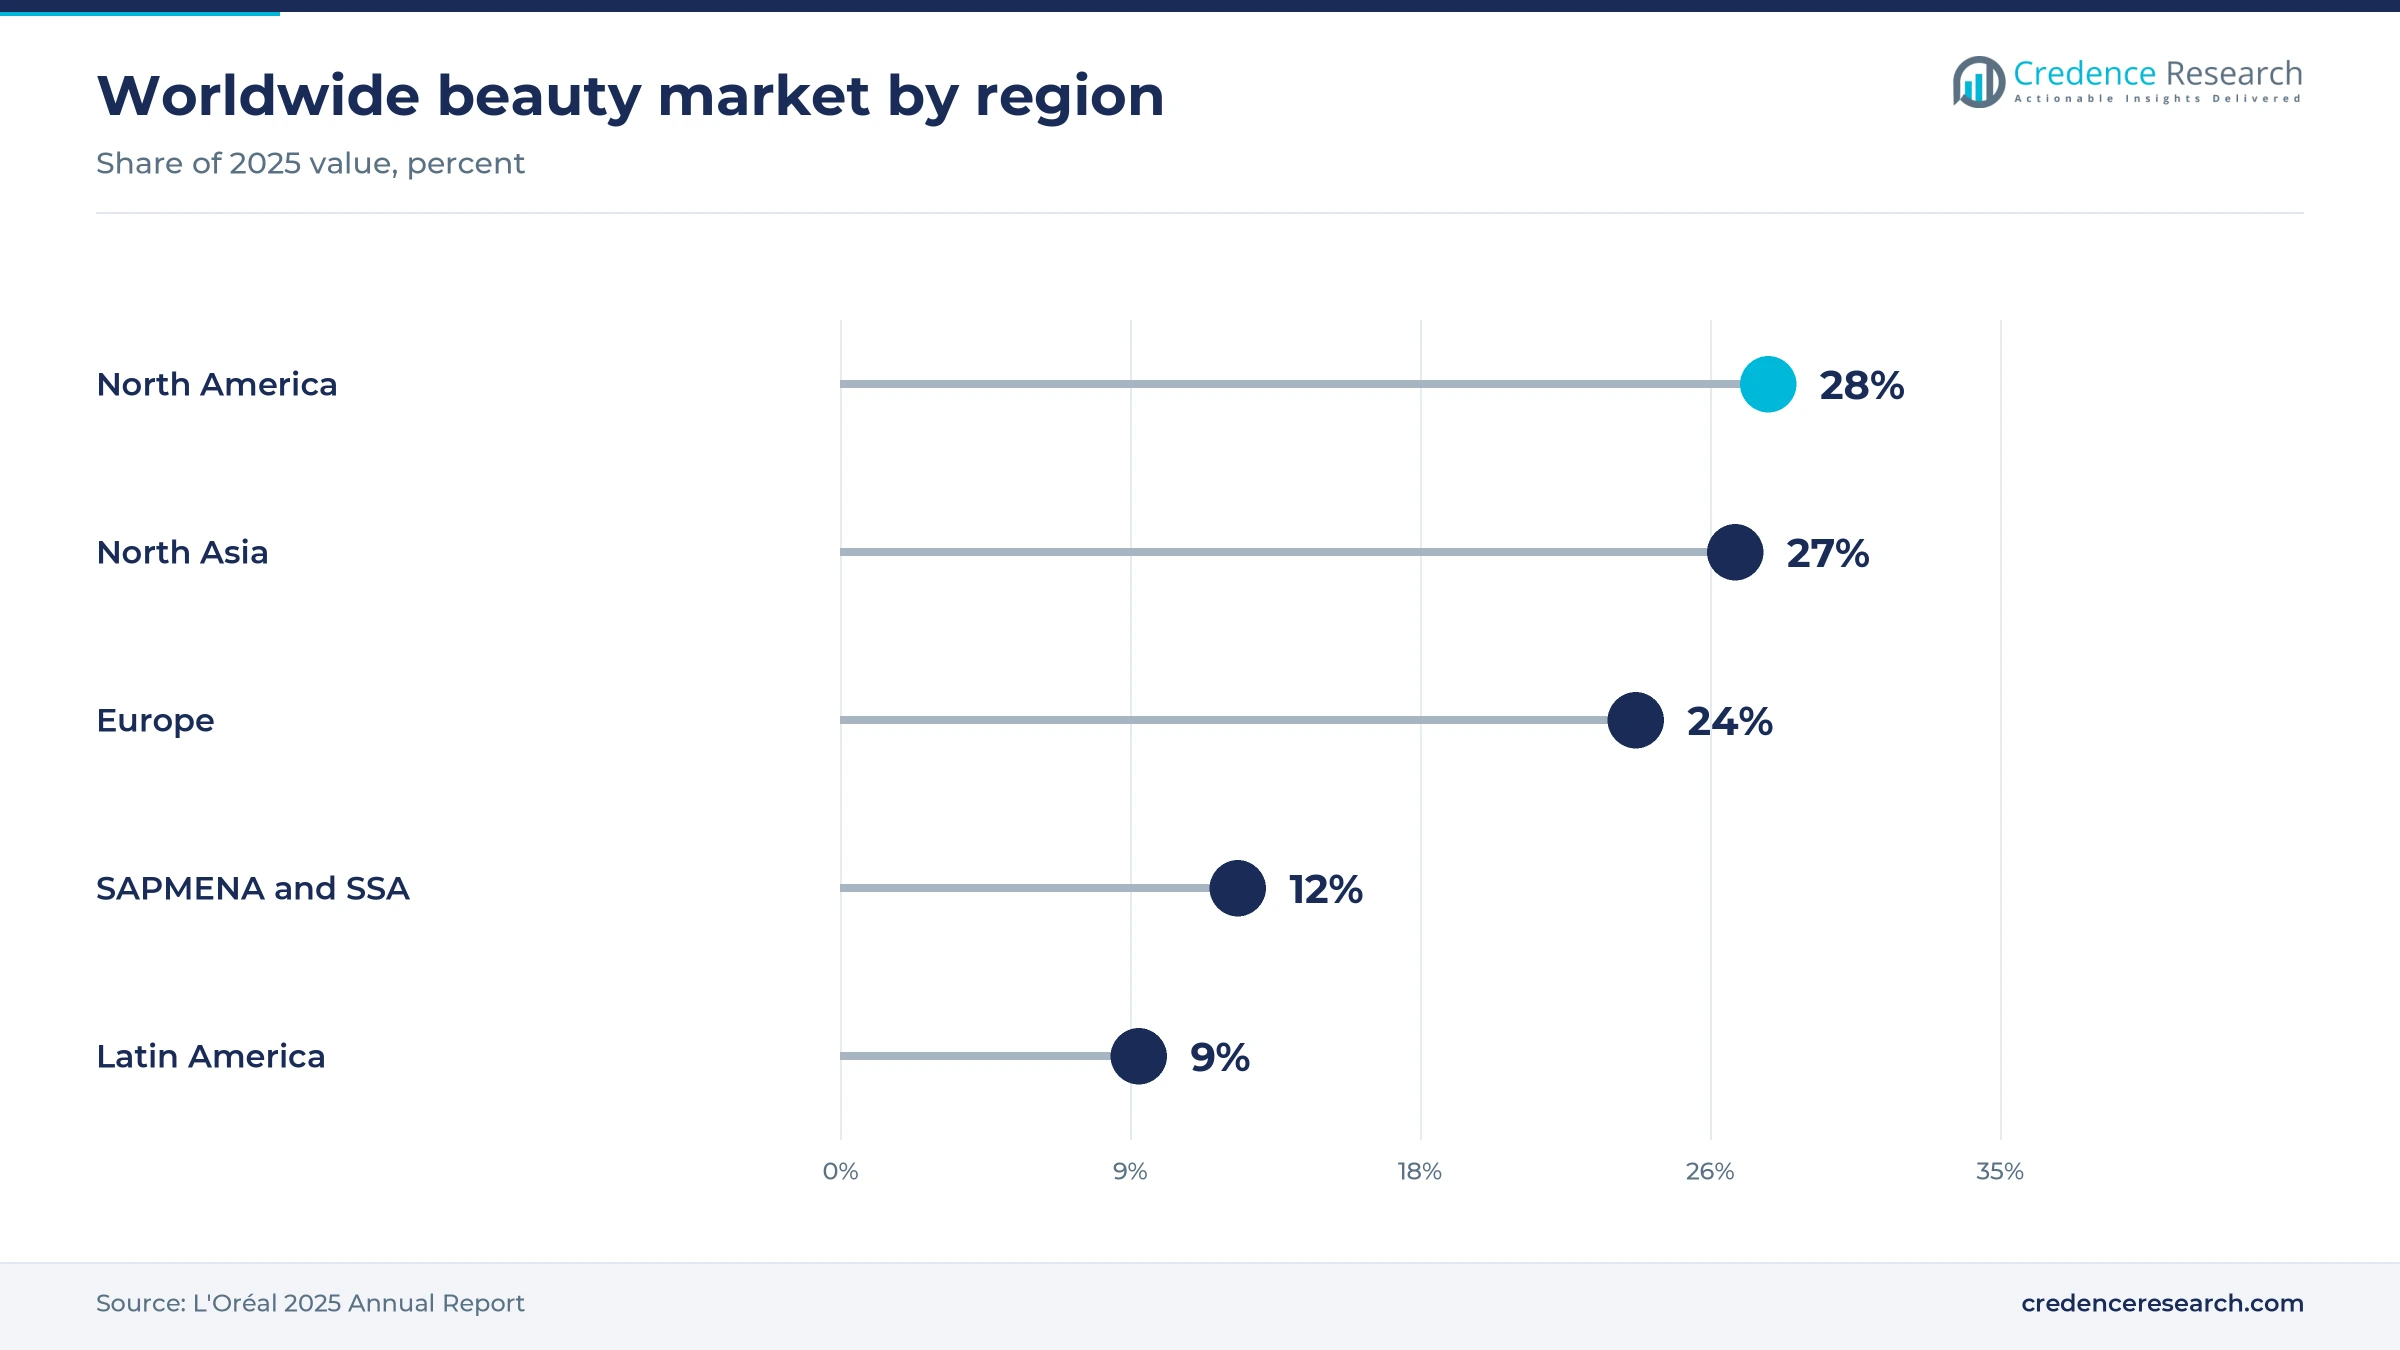
North America held 28.0% of 2025 value and grows at 4.8% a year, because U.S. buyers pay prestige prices for body care sold through beauty chains and online. L'Oréal estimates that North America accounts for 28% of the worldwide beauty market, the largest regional share. Sol de Janeiro, Clarins and Nivea compete there across the USD 20 to USD 80 price range shown in the pricing table. Strict federal enforcement on slimming claims steers U.S. brands toward firming and smoothing language.
Asia Pacific grows fastest on Chinese and Indian demand
Asia Pacific held 26.0% of 2025 value and grows fastest at 6.2% a year, because spending on beauty is rising in China and India from a low base for body care. Korean cosmetics exports to China reached USD 2 billion in 2025, according to the Ministry of Food and Drug Safety. Shiseido, Korean exporters and Indian brands such as VLCC sell light gels that suit humid climates, while China's end of the special-use slimming category pushes local claims toward firming. Public data on body care alone are thin, so this share is a Credence Research estimate.
Latin America follows Brazil's rising obesity
Latin America held 9.5% of 2025 value and grows at 5.5% a year, because Brazil combines a strong body care culture with rising obesity. The Health Ministry's Vigitel survey, released in January 2026, found that the number of Brazilian adults with obesity rose 118% between 2006 and 2024. L'Oréal estimates that Latin America accounts for 9% of worldwide beauty spending. Brazilian-inspired body creams, such as Sol de Janeiro's line, show how regional body care codes travel abroad.
Middle East & Africa rests on Gulf demand
Middle East & Africa held 5.5% of 2025 value and grows at 5.8% a year, because demand centers on Gulf buyers of prestige body care. The General Authority for Statistics reported that 23.1% of Saudis aged 15 and older were obese in 2024 and 45.1% were overweight. Prestige brands reach the region mainly through beauty chains and pharmacies, while public data on body care sales there are thin, so the share carries a wide error range.
Group deals, launches and rule changes from 2024 to 2026
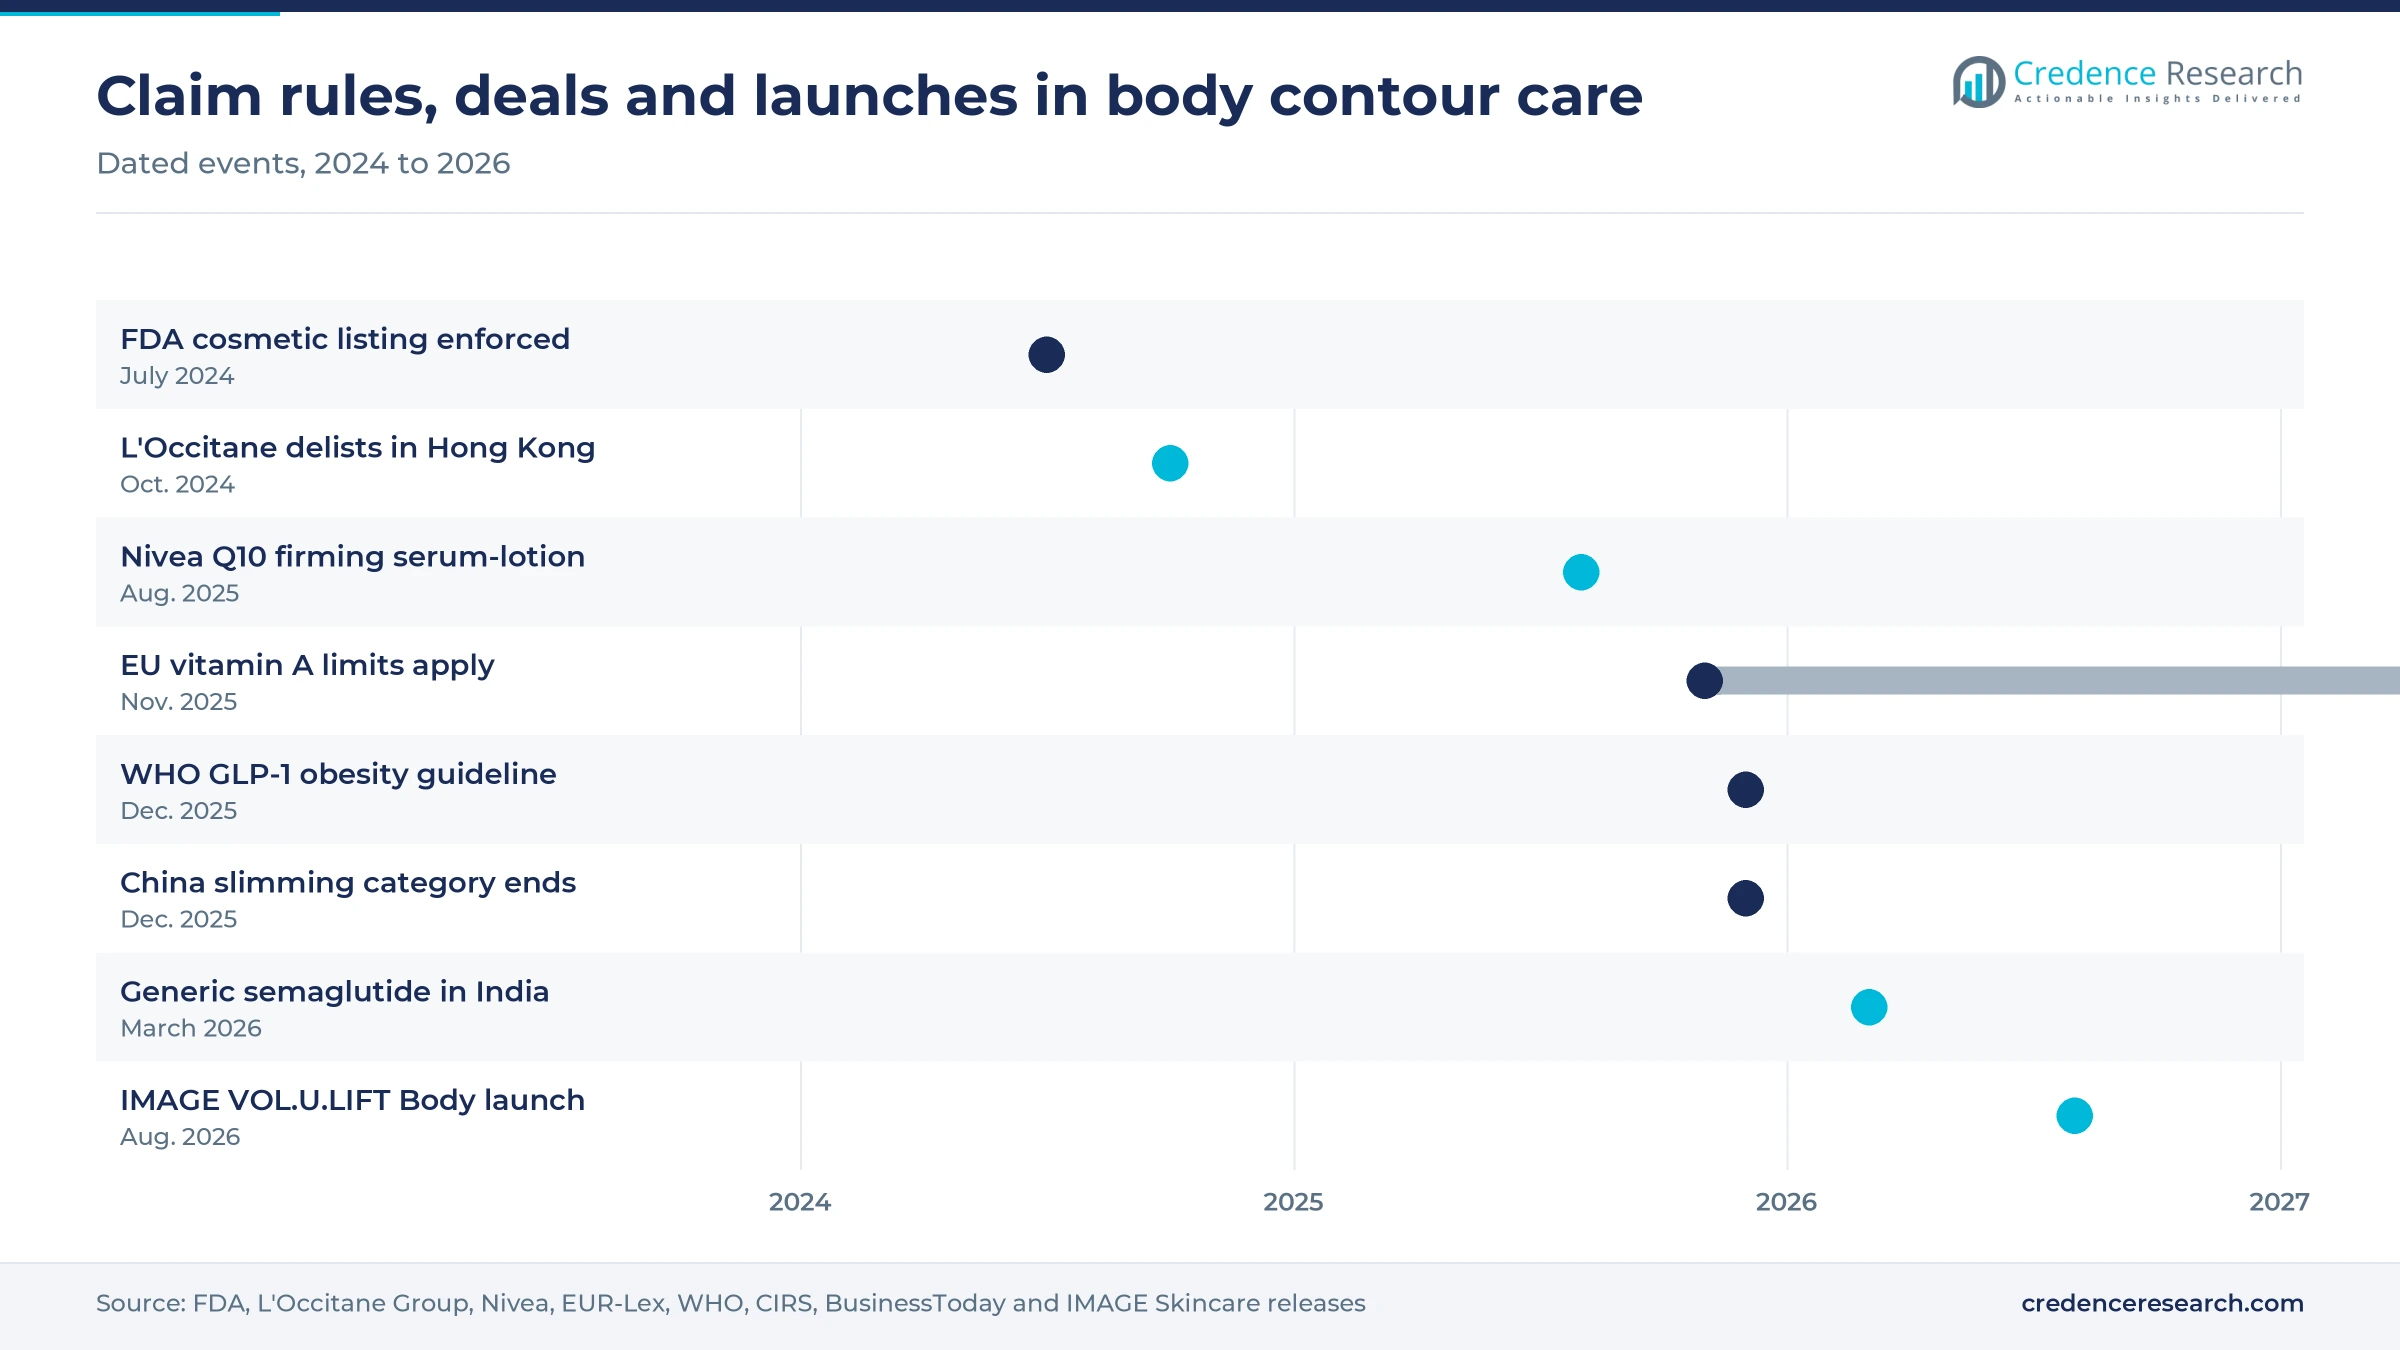
| Development | Status and market relevance |
|---|---|
| In July 2024, the FDA ended its enforcement delay for cosmetic facility registration and product listing under the Modernization of Cosmetics Regulation Act. | Requirement in force; every body care brand selling in the United States must now be registered and listed. |
| In October 2024, L'Occitane International completed its privatization by delisting from the Hong Kong Stock Exchange, keeping Sol de Janeiro in the group. | Completed transaction; the private owner now funds Sol de Janeiro's growth without public market reporting. |
| In August 2025, Nivea launched its Q10 Firming + Energizing Body Serum-Lotion and relaunched its Firming Body Lotion with a Collagen Boost Complex. | Commercial launch; it moves a mass brand further from cellulite claims toward firming claims. |
| In December 2025, China's transition for body slimming special-use cosmetics ended, making sales under those approvals non-compliant from January 2026. | Regulatory deadline passed; brands selling in China must recast slimming products as ordinary cosmetics. |
| In August 2026, IMAGE Skincare launched VOL.U.LIFT Body for skin laxity after weight loss through aesthetic distributor Wigmore Medical. | Commercial launch; it targets GLP-1 users through clinics, a channel new to body contour care. |
Caffeine, cooling agents and peptides set product claims
- Caffeine and other xanthines are the most common actives for smoothing claims, now often sourced from coffee, matcha or guarana extracts that support natural-origin labels.
- Cooling and warming agents give cryo-gels and heat-effect creams an immediate skin sensation that buyers read as a sign of action, which helps repeat purchase.
- Coenzyme Q10, peptides and vitamin C support firmness and collagen claims, as Nivea's Collagen Boost Complex shows, and suit buyers whose skin loosened after weight loss.
- Retinol alternatives such as bakuchiol let brands keep renewal claims in body products under the EU limit on vitamin A, which IMAGE Skincare also uses in its body formula.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Beauty groups and pharmacy specialists split the shelf
Competition in this market turns on claim support, channel reach and texture rather than on list price alone. Beiersdorf competes in mass channels with Nivea firming gel-creams and lotions priced near ordinary body lotion. Clarins and L'Oréal, through Biotherm, lead prestige cellulite care in department stores and beauty chains. Shiseido sells its Body Creator range across Asia and Europe. Cantabria Labs with Elancyl and Bolton Group with Somatoline Cosmetic and Collistar compete in European pharmacies and perfumeries. L'Occitane Group gains younger buyers with Sol de Janeiro's firming body cream. VLCC sells slimming and cellulite gels in India through its clinics and online store. Large groups win on media budgets and retail placement, while specialists defend share with pharmacist advice and narrower ranges that focus on cellulite and firming alone.
How is the supply side organized and where do margins sit?
The supply side of this market is split between global beauty groups, European pharmacy specialists and local brands in Asia. Beiersdorf, L'Oréal, Shiseido and Clarins carry body contour lines inside much larger skin care ranges, while Cantabria Labs and Bolton Group, through Somatoline Cosmetic and Collistar, build brands around them. Many smaller labels buy finished goods from contract manufacturers in Italy, France and Korea. Margins sit in brand and claim support, and entry barriers lie in pharmacy shelf access and in the consumer tests that regulators expect.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Clarins Group | Prestige body care leader | Sells Body Fit Active and Body Firming lines for cellulite and firmness |
| L'Oréal S.A. (Biotherm) | Global beauty group | Sells Biotherm Celluli Eraser cellulite gel through prestige retailers |
| Beiersdorf AG (Nivea) | Mass skin care leader | Sells Nivea Q10 firming gel-creams, lotions and serum-lotions |
| Shiseido Co., Ltd. | Japanese prestige group | Sells Advanced Body Creator Super Slimming Reducer and sculpting gel |
| L'Occitane Group (Sol de Janeiro) | Prestige body care group | Sells Brazilian Bum Bum firming body cream with guarana |
| Bolton Group (Somatoline Cosmetic, Collistar) | Pharmacy and perfumery specialist | Sells Somatoline reducer and firming creams and Collistar anticellulite cryo-gels |
| Cantabria Labs (Elancyl) | Pharmacy dermocosmetics | Sells Elancyl Slim Design cellulite and firming care in pharmacies |
| VLCC Health Care Ltd. | Indian wellness and clinic brand | Sells Proshape slimming gel and Prosculpt cellulite gel in India |
Firming evidence will matter more than fat-loss promises
Credence Research's view is that proof of firmness, more than promises of fat loss, will decide which brands gain share in this market. Weight-loss medicines and stricter claim rules in China, the EU and the United States push the category toward skin quality, where consumer tests and instrument data can back a claim. Pharmacy specialists are well placed in Europe, while light gels win in Asia. Brands should retire inch-loss language, publish test methods and pair firming care with weight loss supplements or clinic programs.
Earlier estimate rolled forward and tested on beauty data
The report uses 2025 as the base year and forecasts to 2035. The earlier Credence Research estimate for 2024 was rolled forward one year at its own growth rate and tested against public estimates of worldwide beauty and skin care spending and against listed retail prices per milliliter. Regional and segment shares are Credence Research estimates based on beauty spending, channel structure, obesity data and company product ranges. Sources include the WHO, FTC, FDA, EUR-Lex, the U.S. Census Bureau, China's National Bureau of Statistics, Korea's Ministry of Food and Drug Safety, national health surveys, company releases and retailer listings. No interviews or surveys were conducted for this update of the estimate.
Firming care and online sales carry growth to 2035
Growth to 2035 depends on how quickly brands turn slimming lines into firming care and on how widely weight-loss drugs spread. The base case assumes anti-cellulite products stay the largest function, while firming care gains share among buyers who lose weight with medicines. Gels should outgrow creams in Asia, and online retail should keep taking share from supermarkets. Europe stays the largest region, while Asia Pacific narrows the gap as Chinese and Indian buyers trade up in body care.
Claim rules and weight-loss drugs set the range of outcomes
The spread of outcomes depends mainly on how fast brands move from slimming to firming claims and on how widely weight-loss drugs spread. Strict claim enforcement and cheaper medicines could shrink the fat-burning segment faster than firming care grows. Broad drug uptake in India and China, with firming products sold beside it, forms the main upside.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 3.8% | USD 11.20 billion | Claim enforcement tightens and buyers drop topical slimming for medicines alone |
| Base | 5.20% | USD 12.64 billion | Firming care grows steadily while fat-burning claims fade slowly |
| Upside | 6.4% | USD 13.99 billion | Generic GLP-1 uptake in Asia lifts demand for firming care beside it |
Frequently Asked Questions
How big is the slimming cream market?
Do slimming creams actually reduce fat?
Which function holds the largest share?
How do weight-loss drugs affect slimming creams?
Which region leads the market?
What ingredients do slimming creams use?
What restrains the slimming cream market?
Who are the main slimming cream suppliers?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Cream
- 1.2.2 Gel
- 1.2.3 Emulsion
- 1.3 By Function
- 1.3.1 Anti-Cellulite
- 1.3.2 Firming & Toning
- 1.3.3 Fat-Burning
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 7.61 billion → 2035: USD 12.64 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Slimming Cream Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Slimming Cream Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Slimming Cream Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Slimming Cream Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Slimming Cream Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Slimming Cream Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Slimming Cream Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Slimming Cream Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 7.61 billion → 2035: USD 12.64 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Slimming Cream Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Cream
- 12.3.7.2 Gel
- 12.3.7.3 Emulsion
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Function - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Anti-Cellulite
- 12.4.7.2 Firming & Toning
- 12.4.7.3 Fat-Burning
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Slimming Cream Geographic Market Outlook, 2025-2035
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2035
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Slimming Cream Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Slimming Cream Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Clarins Group
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 L'Oréal S.A. (Biotherm)
- 17.4 Beiersdorf AG (Nivea)
- 17.5 Shiseido Co., Ltd.
- 17.6 L'Occitane Group (Sol de Janeiro)
- 17.7 Bolton Group (Somatoline Cosmetic, Collistar)
- 17.8 Cantabria Labs (Elancyl)
- 17.9 VLCC Health Care Ltd.
- 17.10 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

