
Australian brands measure journeys across stores and apps
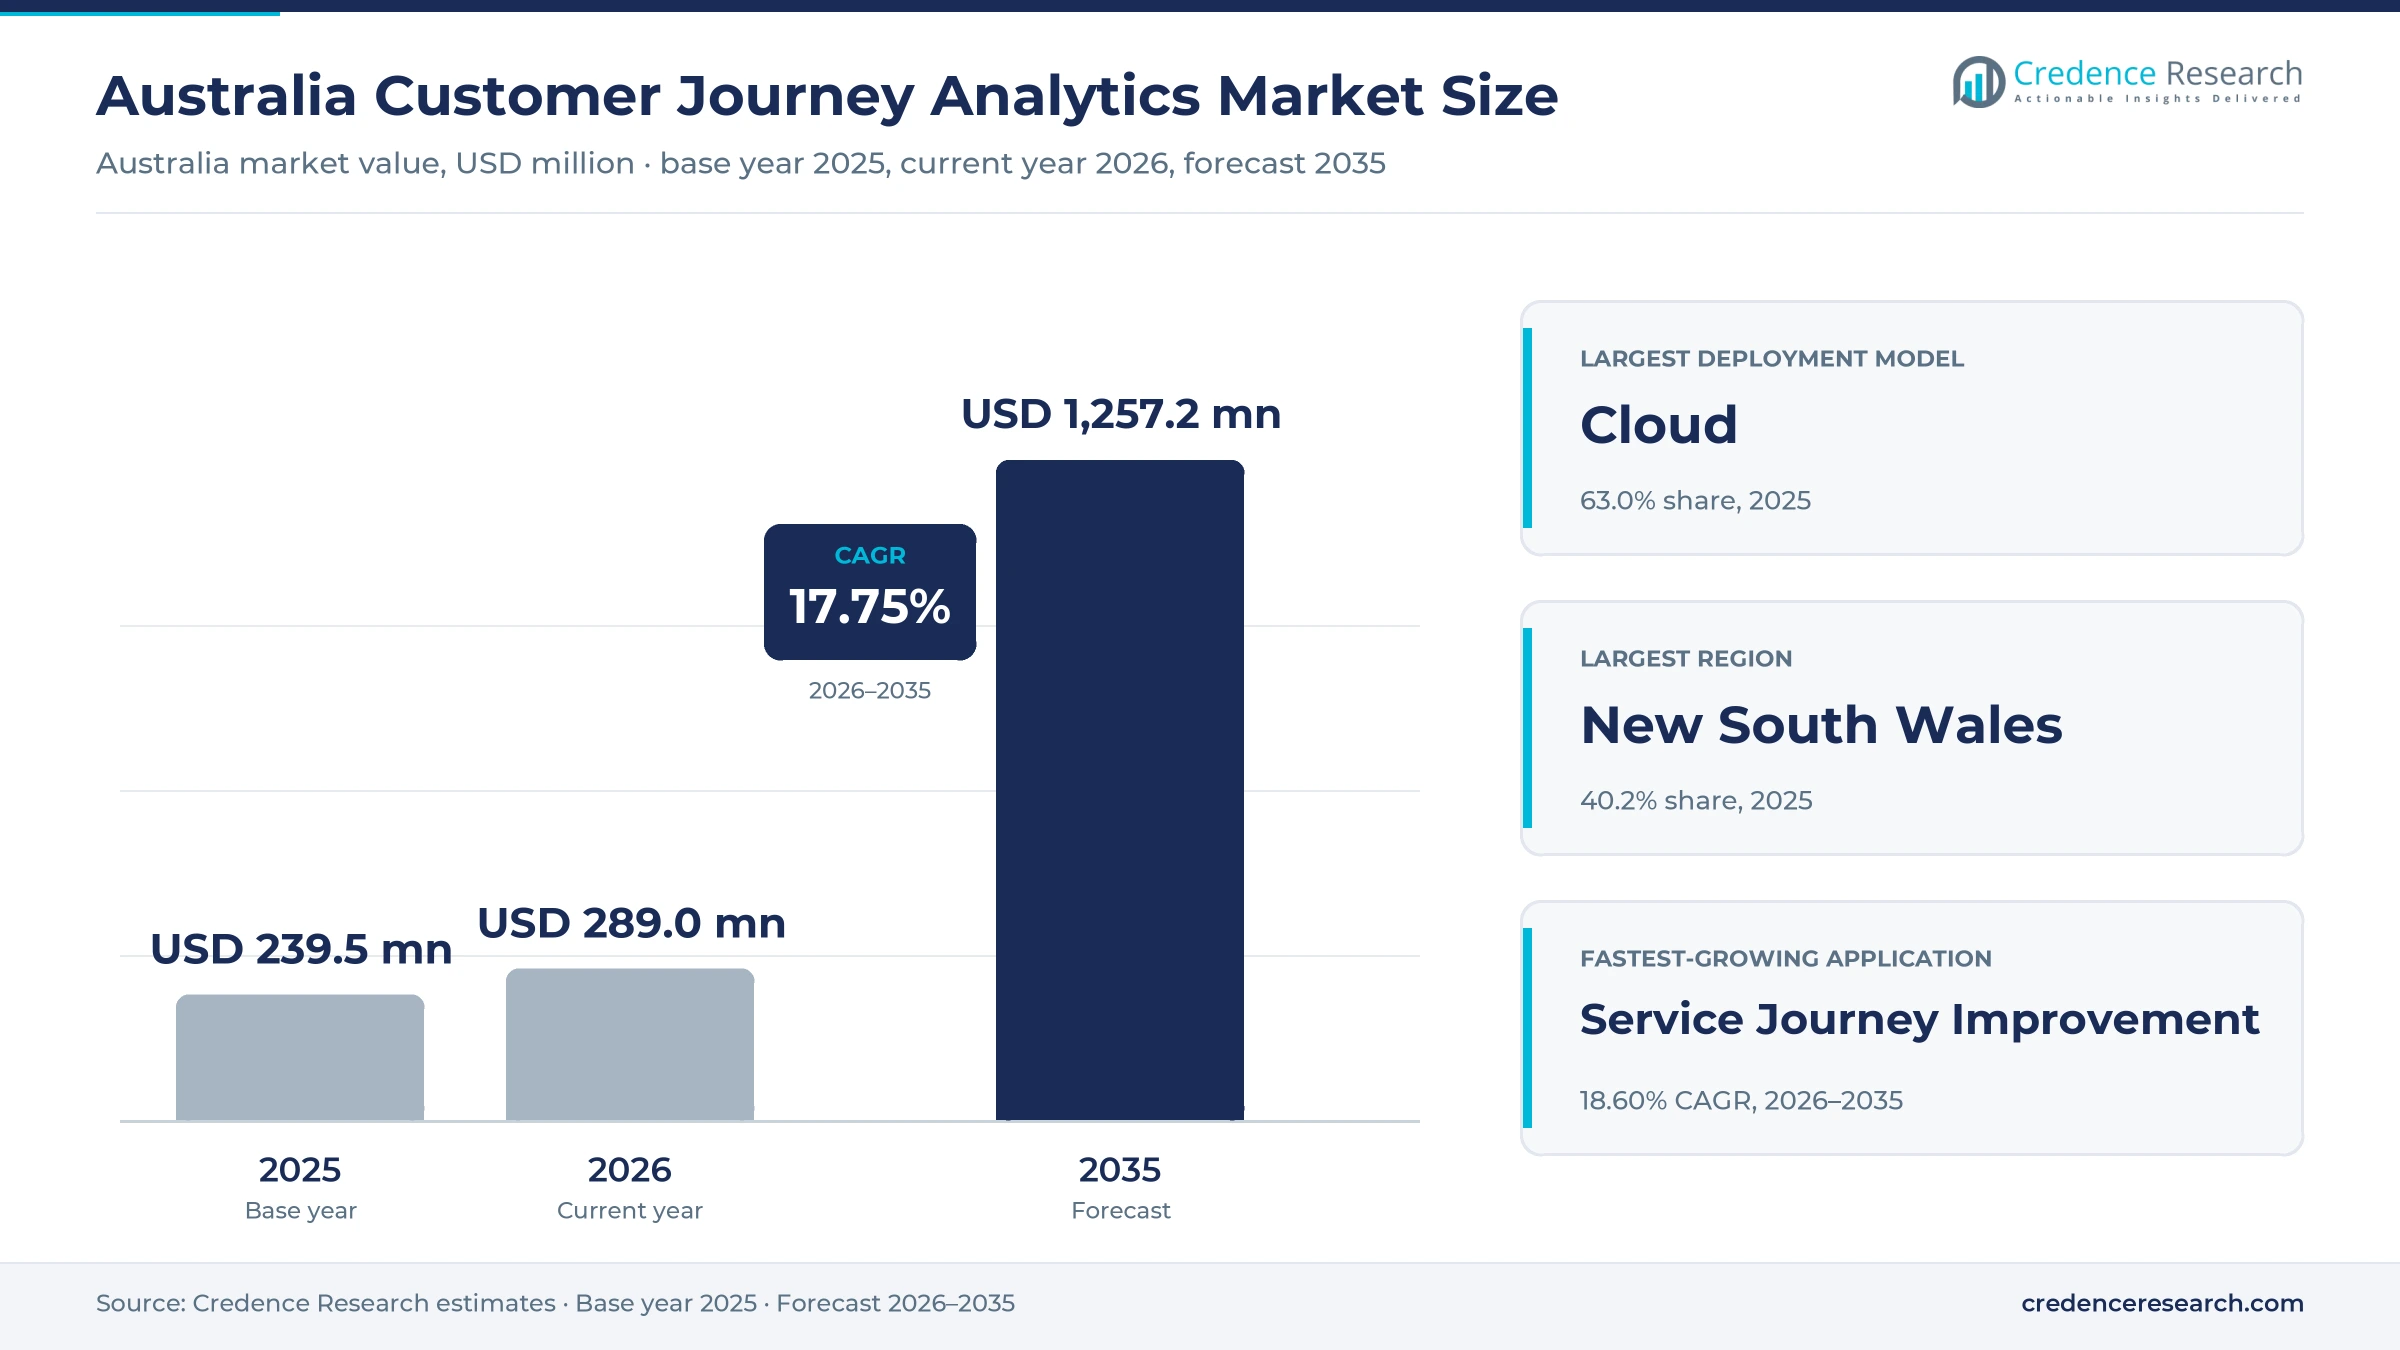
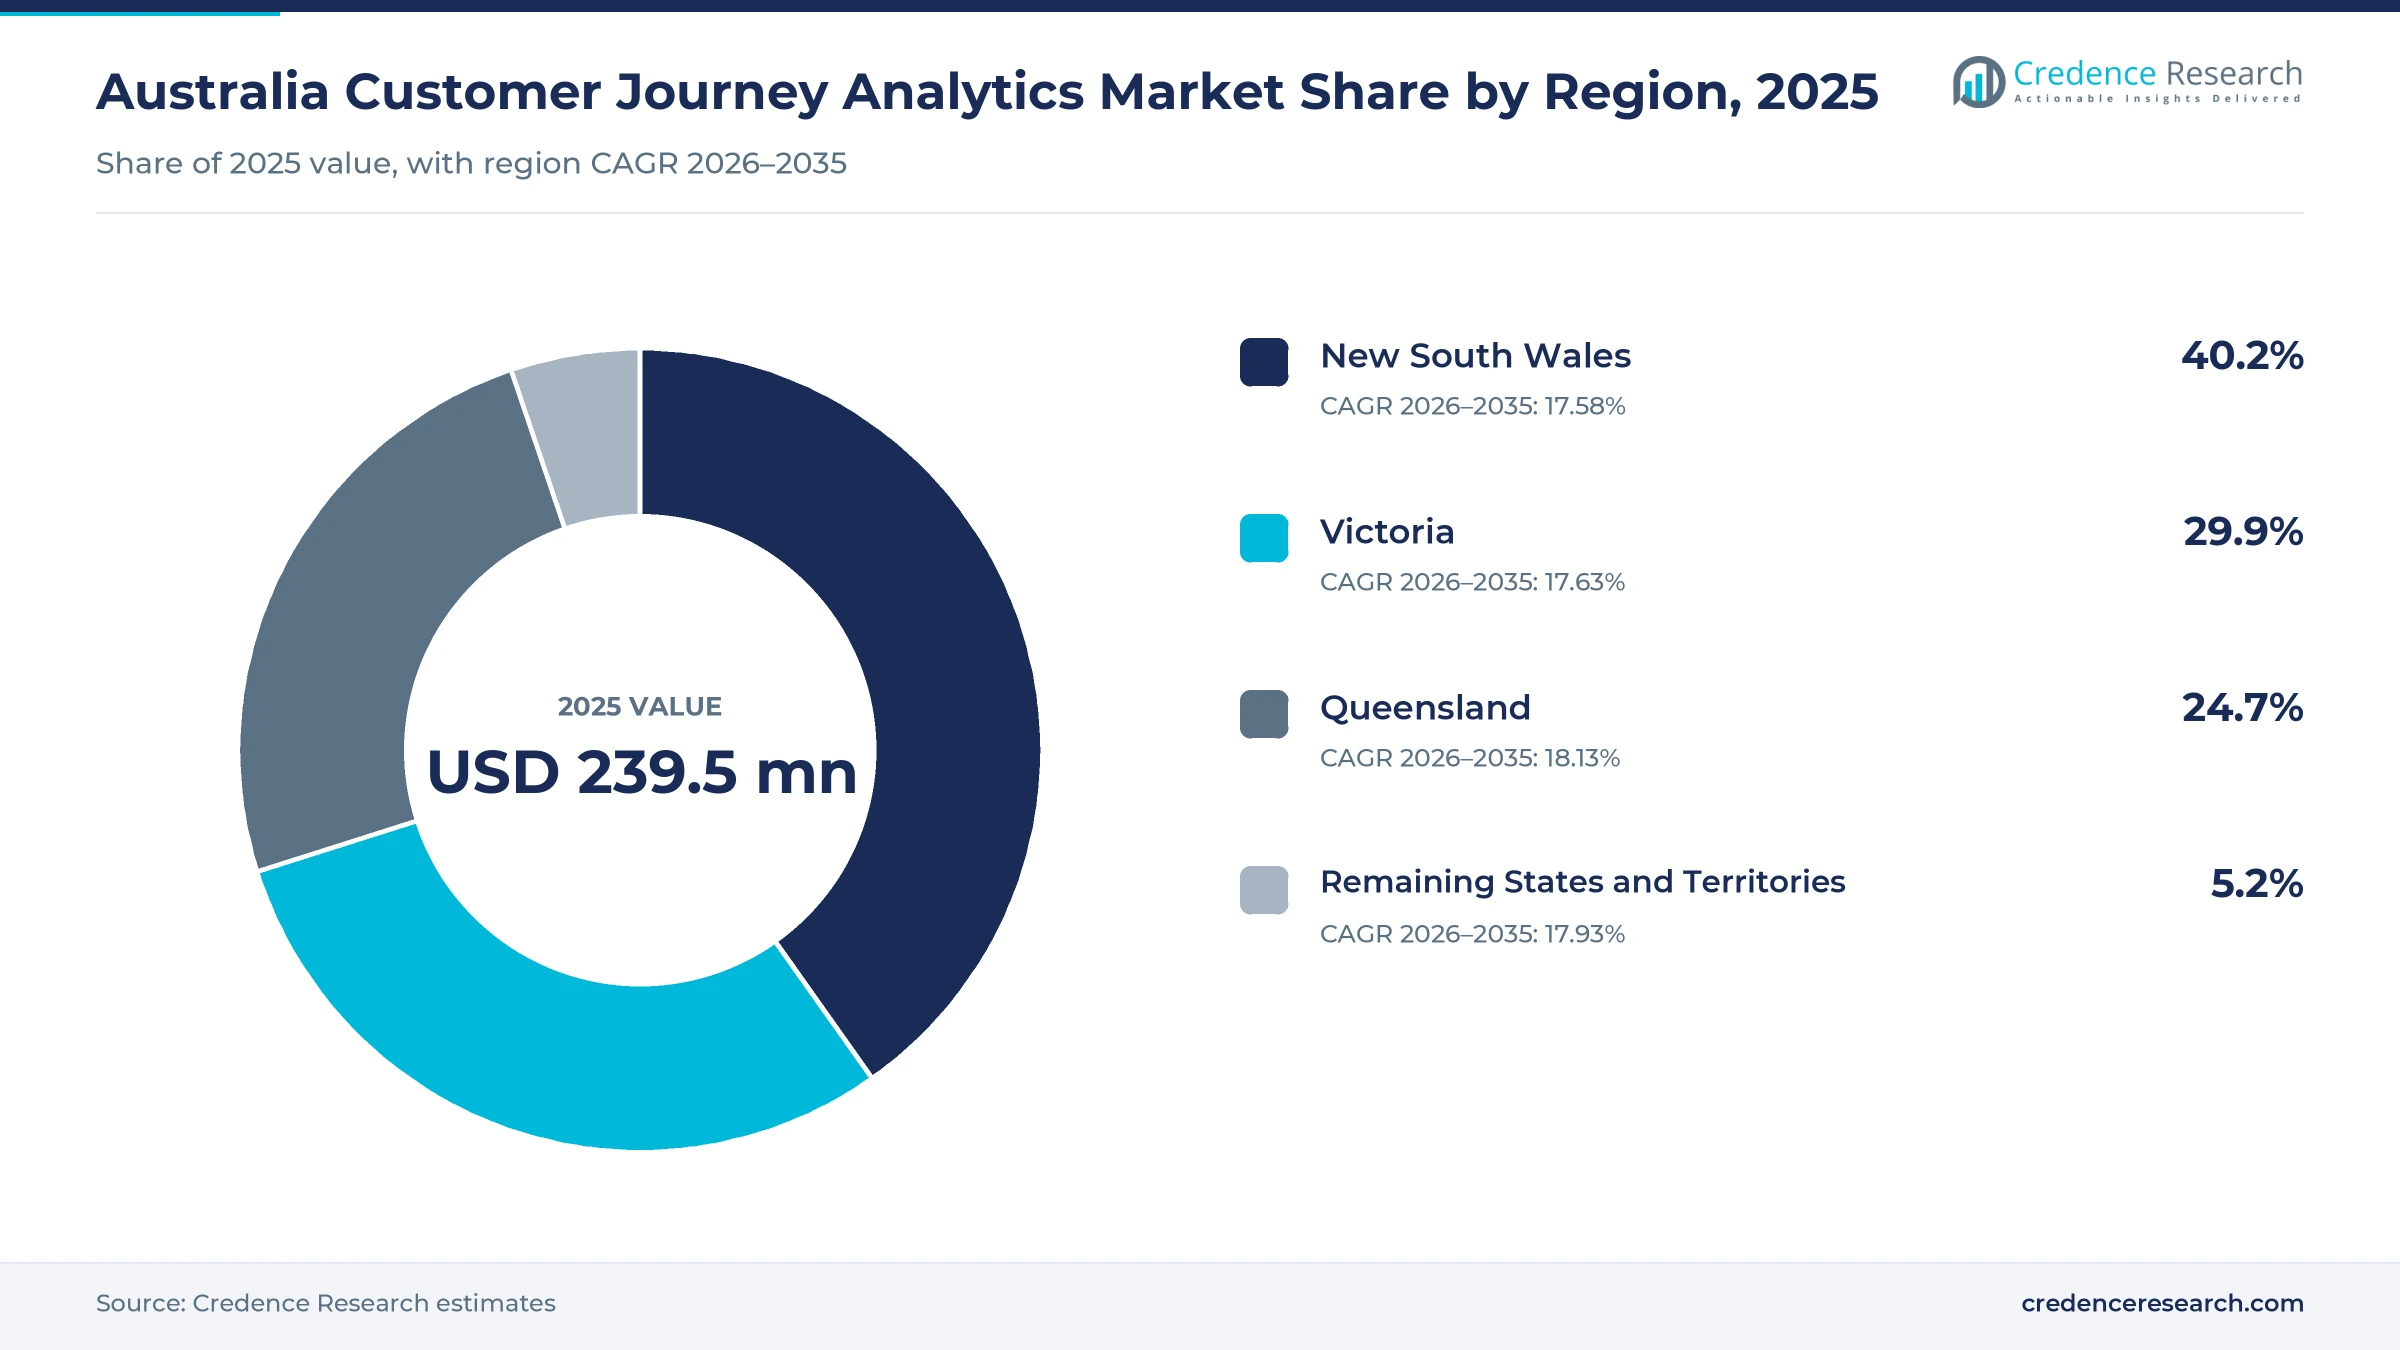
The Australia customer journey analytics market was valued at USD 239.5 million in 2025 and is projected to increase from USD 289.0 million in 2026 to USD 1.26 billion by 2035, registering a CAGR of 17.75% during 2026–2035. Demand comes from banks, retailers, telcos and public agencies that need to see how people move between websites, apps, marketplaces, stores and contact centers before they buy, renew or complain. New South Wales held the largest regional share, 40.2% in 2025, because Sydney concentrates bank and retailer head offices and the local teams of the main software vendors. Queensland is the fastest-growing region at 18.13% a year, as its online spending expands from a large household base. The Privacy and Other Legislation Amendment Act 2024 has also pushed buyers toward consented first-party data, because new automated decision transparency duties begin in December 2026.
Which journey measurement spending does the estimate count?
The estimate measures what Australian organizations spend on software and services that join customer interactions across digital and physical channels into journeys that teams can analyze and improve. It covers analytics software subscriptions and licences, implementation and integration projects, and managed analytics and support contracts bought by enterprises of every size.
The estimate excludes general business intelligence tools, advertising spend, contact center labor and customer relationship systems that are bought without journey analysis modules. The value chain runs from software vendors and cloud providers, through systems integrators and consultancies that connect data sources, to marketing, digital and service teams that act on the findings.
Australia Customer Journey Analytics Market Insights
- The Australia customer journey analytics market was valued at USD 239.5 million in 2025 and is projected to reach USD 1.26 billion by 2035, registering a CAGR of 17.75% during 2026–2035.
- New South Wales held a 40.2% share of 2025 value, because Sydney hosts the head offices of large banks and retailers and the local teams of global software vendors.
- Cloud deployment led with a 63.0% share of 2025 value, because vendors now host journey and profile platforms in Australian data centers for local buyers.
- Australians spent a record $82.6 billion online in 2025, up 14% year on year, which raises the number of digital touchpoints each brand must measure.
- Service journey improvement grows fastest at 18.60% a year during 2026–2035, as banks, telcos and agencies apply journey data to complaints, scams and digital service.
Cloud software leads as service journey work grows fastest
Why does analytics software hold the largest share?
Based on solution type, the market is categorized into analytics software, implementation services and managed analytics and support. Analytics Software led with a 56.0% share of 2025 value, because recurring platform subscriptions carry most spending once data feeds are connected. Managed Analytics and Support grows fastest at 18.44% a year, as firms that lack data teams hand ongoing analysis to partners alongside wider cloud professional services.
How do cloud and on-premises models split spending?
Based on deployment model, the market is categorized into cloud, hybrid and on-premises. Cloud led with a 63.0% share of 2025 value, because journey platforms now run in local regions operated by the main vendors. Cloud deployment also grows fastest at 18.10% a year, while on-premises systems shrink as banks and agencies retire older data warehouses.
Which industries carry the largest analytics budgets?
Based on end-use industry, the market is categorized into BFSI, retail and e-commerce, telecom and IT, and non-financial services and public sector. BFSI led with a 34.0% share of 2025 value, because banks and insurers run large digital channels under strict regulation. Retail and E-Commerce grows fastest at 18.23% a year, as online shopping and marketplaces spread spending across more channels.
Which uses of journey data attract the most spend?
Based on application, the market is categorized into acquisition and attribution, conversion optimisation, retention and churn, and service journey improvement. Acquisition and Attribution led with a 30.0% share of 2025 value, because marketing teams fund channel measurement first. Service Journey Improvement grows fastest at 18.60% a year, as service leaders use journey data to cut repeat contacts and spot scam patterns.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Solution Type | Analytics Software | 56.0% | Managed Analytics and Support | 18.44% |
| By Deployment Model | Cloud | 63.0% | Cloud | 18.10% |
| By End-Use Industry | BFSI | 34.0% | Retail and E-Commerce | 18.23% |
| By Application | Acquisition and Attribution | 30.0% | Service Journey Improvement | 18.60% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Online spend, AI use and privacy law lift analytics budgets
How does omnichannel shopping lift conversion measurement?
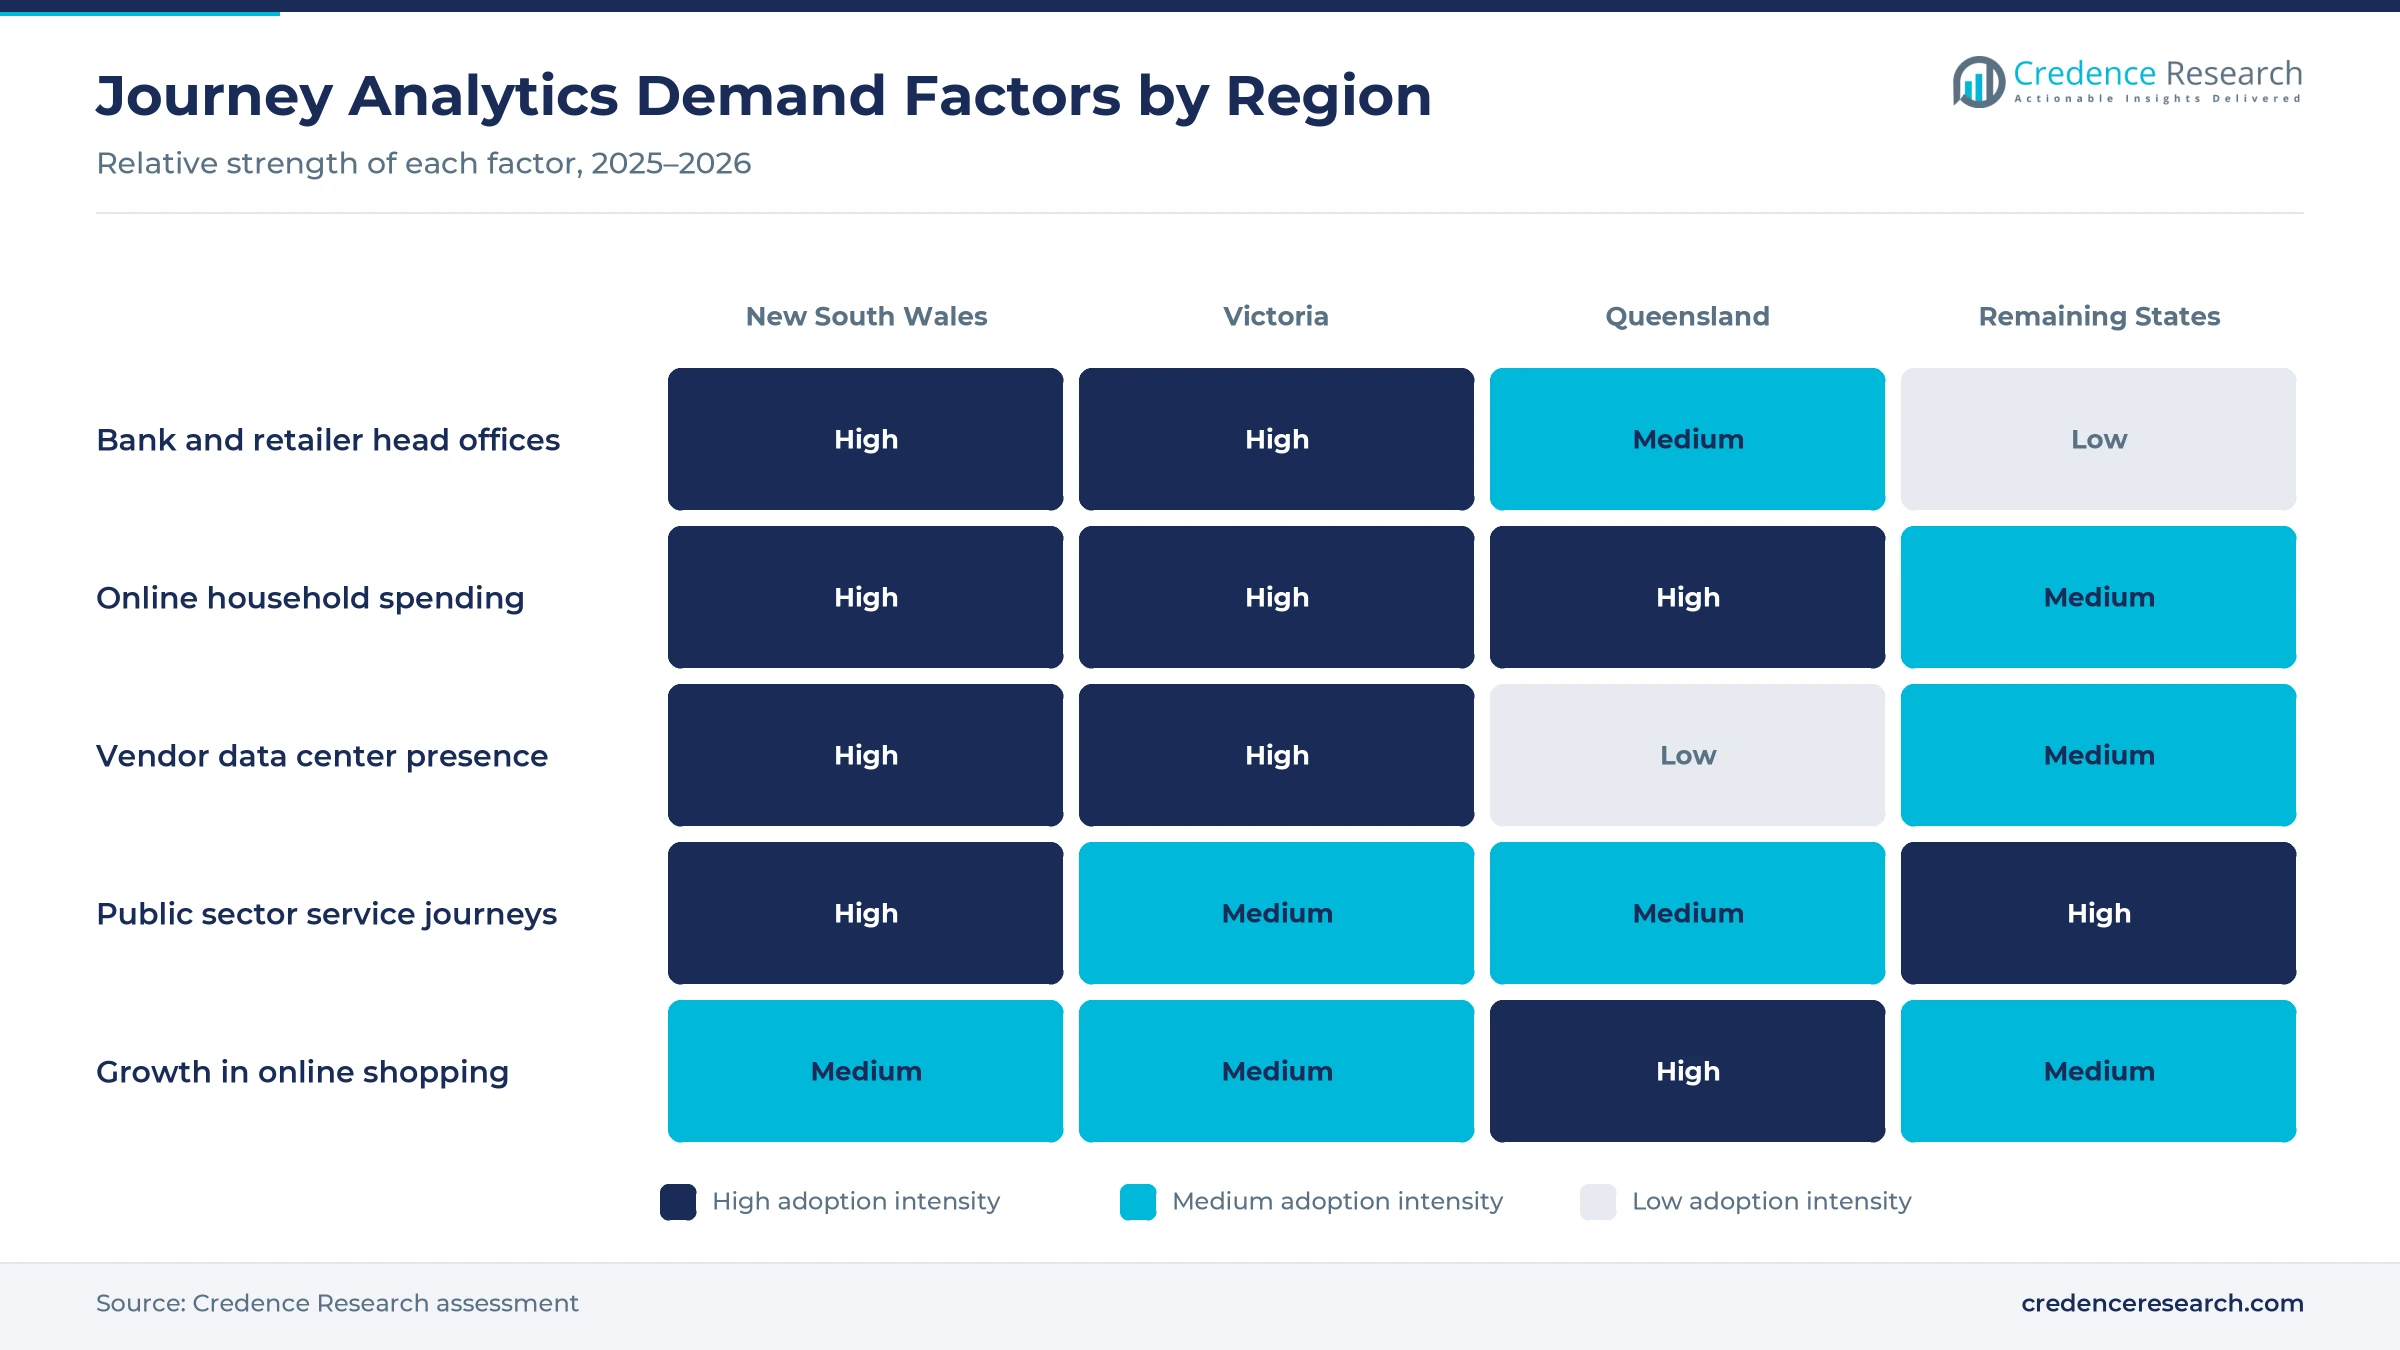
Australian shoppers now move between stores, websites, marketplace apps and phones before they buy, so retailers need tools that link each touchpoint to a sale. Australians spent a record $82.6 billion online in 2025, up 14% year on year, and 9.8 million households shopped online, according to Australia Post. Pure online marketplaces took $18.9 billion, or 23% of online spend, which pushes brands to compare their own sites with third-party channels. The Australian Communications and Media Authority found that 97% of adults accessed the internet by mobile phone in 2025, up from 95% in 2024. As a result, retail and e-commerce buyers grow at 18.23% a year, the fastest end-use rate in the market.
Why do connected data and AI analysis widen adoption?
Enterprises are joining CRM, web, app and contact center records so AI tools can explain where customers stall or leave, which lifts spending on journey software. About 35% of large businesses used AI in 2024-25, up from 9% in 2021-22, according to the Australian Bureau of Statistics, and information, media and telecommunications firms led at 38%. Data analytics ranked among the top two uses, at 54% of adopters and planned adopters, in the National AI Centre SME survey for December 2025 to February 2026. Salesforce named Telstra, Flight Centre and hipages among Australian firms that use its AI to improve customer experiences. In turn, cloud deployment held 63.0% of 2025 value, the largest deployment share.
How does privacy-led data governance shape buying?
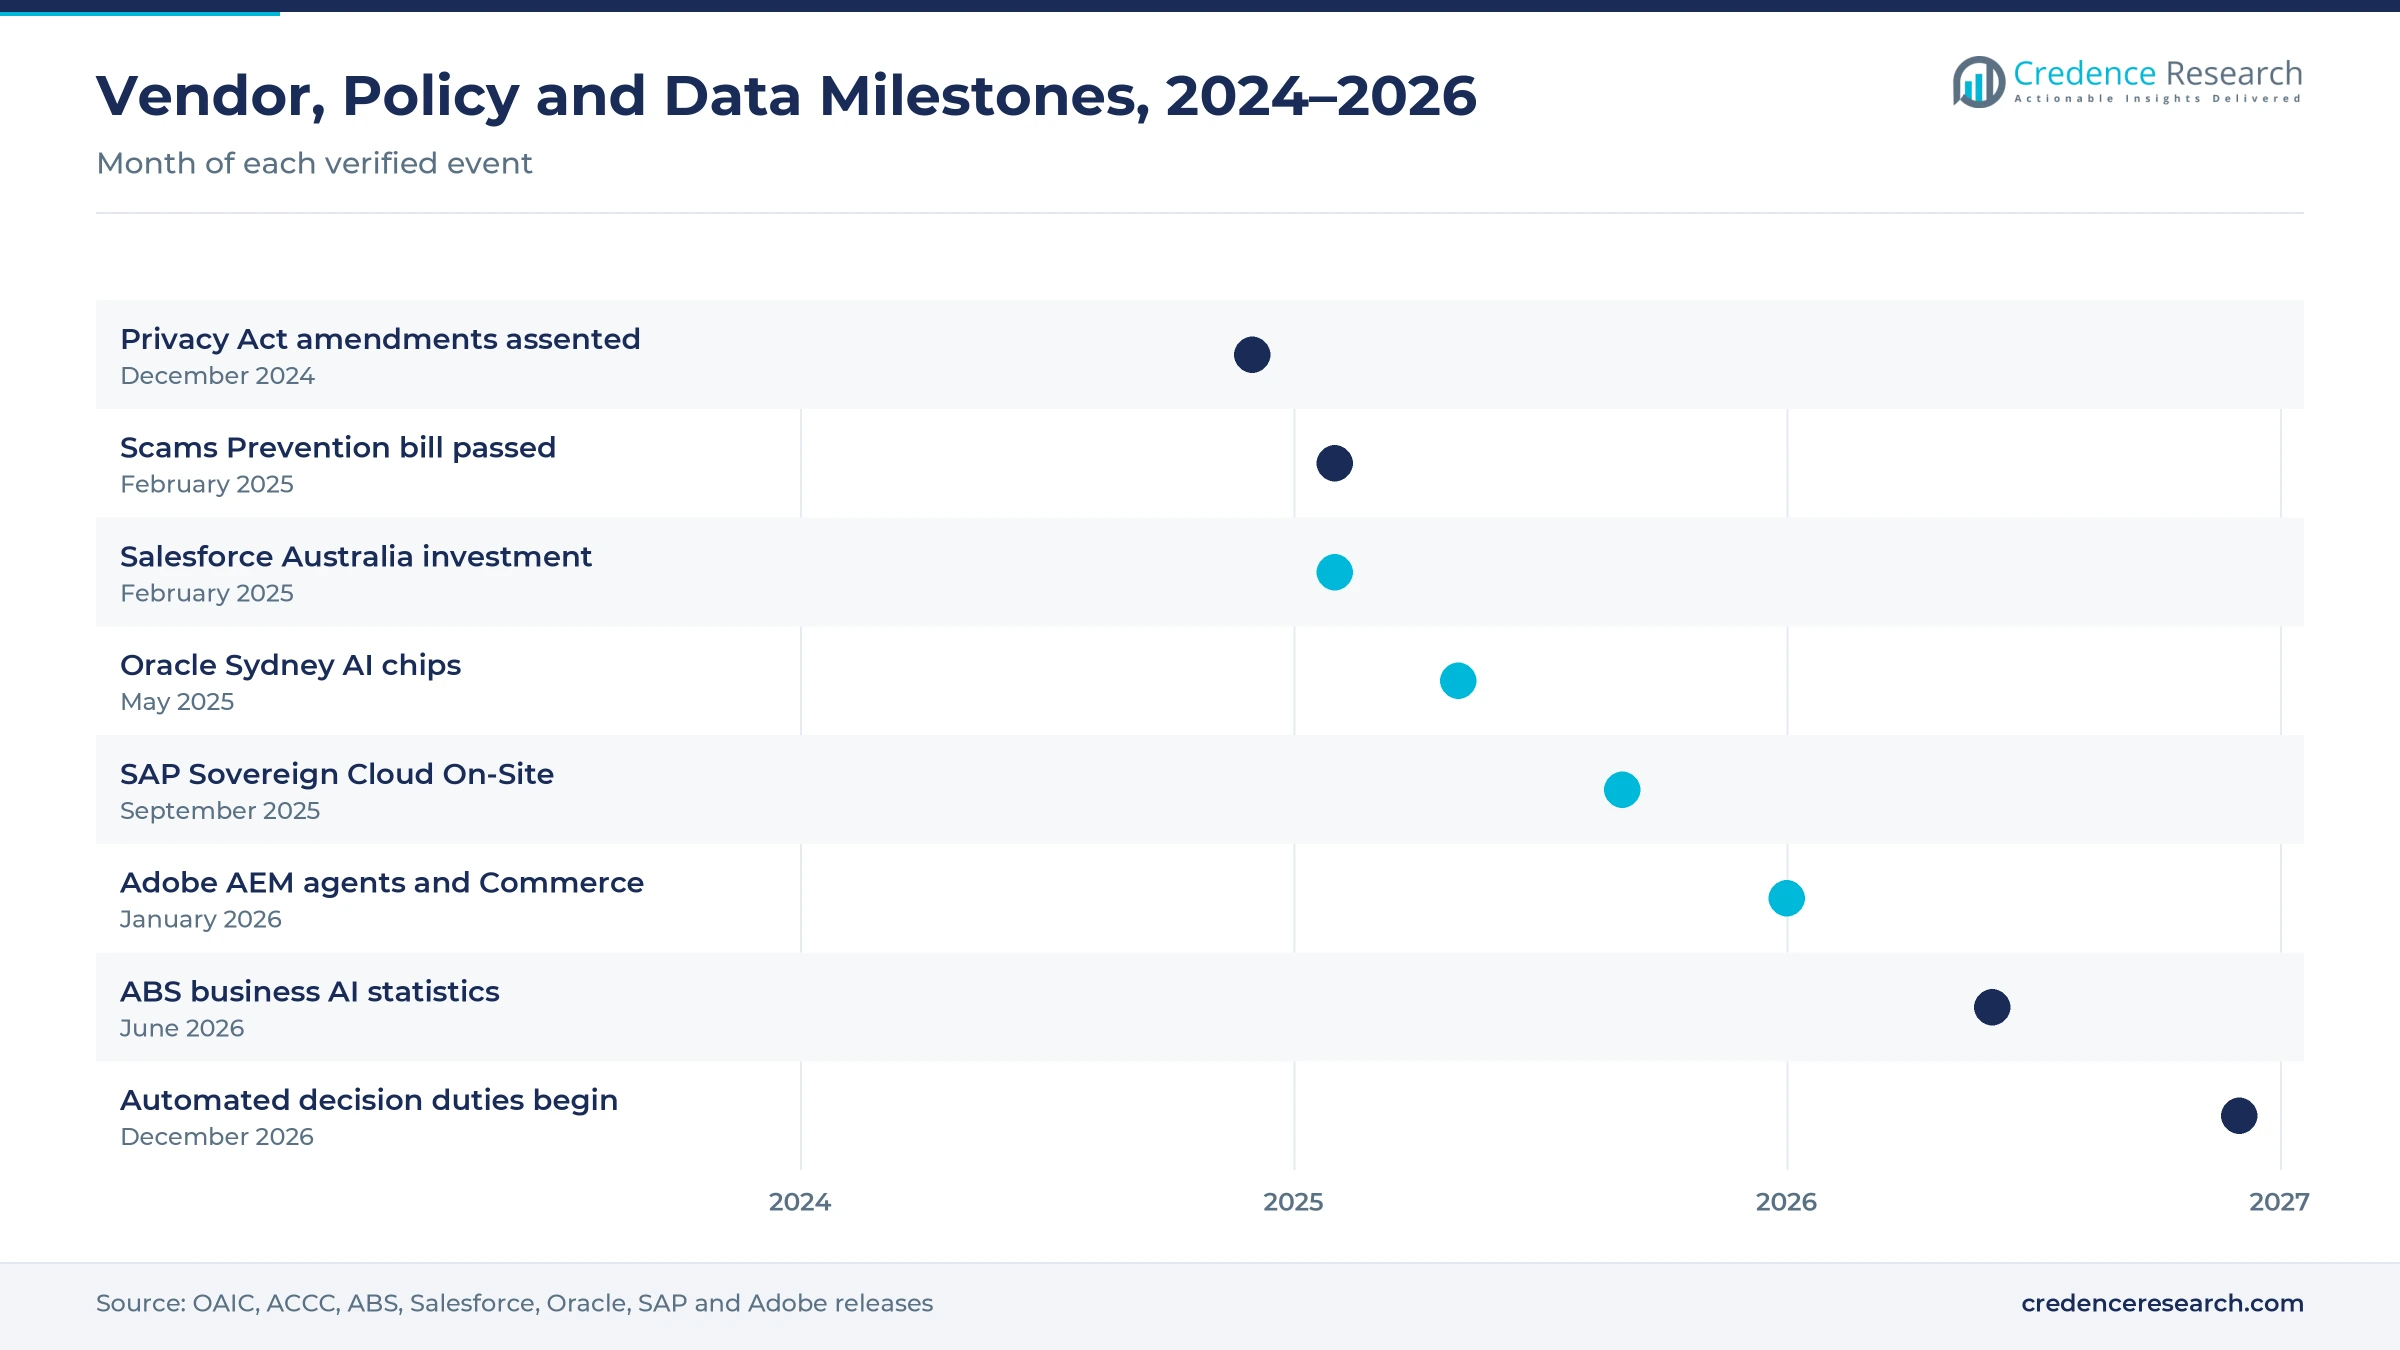
Stricter privacy law is pushing organizations to rebuild journey measurement on consented first-party data with clear audit trails, which favors governed analytics platforms. The Privacy and Other Legislation Amendment Act 2024 received royal assent on Dec. 10, 2024, and created a statutory tort for serious invasions of privacy. From Dec. 10, 2026, entities that use personal information in automated decisions that can affect individuals must describe those decisions in their privacy policies. The Office of the Australian Information Commissioner received 1,205 data breach notifications in 2025, the highest number since the scheme began in 2018. As a result, buyers now favor vendors that offer onshore hosting, consent controls and role-based access to unified profile platforms.
Why do scam rules push banks and telcos to track journeys?
Banks, telcos and digital platforms must now detect and disrupt scams across customer contacts, which raises demand for analytics that flag unusual service journeys. Parliament passed the Scams Prevention Framework bill on Feb. 13, 2025, covering banking, telecommunications and digital platform services, with fines of up to A$50 million for each breach. Australians lost $2.18 billion to scams in 2025, up 7.8% from 2024, and reports of online scams with a loss rose 31.8%, according to the Australian Competition and Consumer Commission. Commonwealth Bank said in June 2022 that its Customer Engagement Engine made more than 35 million decisions every day. In turn, BFSI held 34.0% of 2025 value, the largest end-use share.
AI agents, onshore hosting and mid-sized buyers gain ground
How is the shift to AI agents changing journey tools?
Vendors are adding AI agents that build segments, draft journeys and suggest fixes, which lets smaller teams act on journey data without writing queries. Adobe made five AI agents in Adobe Experience Manager generally available in Australia in January 2026, including a content optimization agent. Microsoft says Dynamics 365 Customer Insights lets marketers use Copilot to build journeys by stating their goals and target audience. Salesforce held its Agentforce World Tour in Sydney in February 2025, which drew more than 10,000 attendees. As a result, managed analytics and support grows at 18.44% a year, because buyers want partners to tune and monitor these agents after launch.
Why is the rise of onshore hosting reshaping vendor choice?
Australian banks, insurers and agencies prefer journey platforms that keep personal data in the country, and vendors have expanded local hosting to meet that demand. Adobe opened a Sydney data center for Adobe Experience Platform in February 2020 and added Australia as a deployment option for Adobe Commerce in January 2026. Microsoft committed A$5 billion over two years in October 2023 to grow its local data center sites from 20 to 29 across Canberra, Melbourne and Sydney. SAP plans to add SAP Business Data Cloud to its Australian sovereign cloud in 2026. In turn, this growing hyperscale capacity supports cloud adoption among regulated buyers.
Can mid-sized firms become a new buyer base?
Medium-sized firms have begun using AI and digital measurement at scale, which opens a buyer group that journey vendors have mostly served through partners. About 22% of medium businesses used AI in 2024-25, compared with 3% in 2021-22, according to the Australian Bureau of Statistics. The share of businesses that measured the contribution of digital activities to overall performance rose to 7%, from 3%. About 96.1% of Australians used the internet in 2024, according to the World Bank, so nearly every customer leaves a digital trail. As a result, vendors can package journey analysis with marketing measurement software for firms without data teams.
Is service journey improvement a growth opening?
Service leaders now see journey data as a way to cut repeat contacts and spot fraud, which moves budgets beyond marketing teams. The Australian Communications and Media Authority reported that access to government services through apps increased in 2025 after a decline the year before. The ACCC referred 4,246 phone numbers and 921 sender IDs to telecommunications partners for disruption in 2025. Health service providers made 225 data breach notifications in 2025, the most of any sector, which raises the value of tracking how sensitive journeys run. In turn, service journey improvement grows at 18.60% a year, and vendors can link it with experience management platforms.
Thin data skills, AI distrust and cyber gaps slow buyers
How do thin data skills slow journey programs?
Many Australian businesses still lack the habits and staff needed to use journey data in decisions. Only 10% of businesses actively collected or analyzed data to make informed decisions in 2024-25, down from 24% in 2021-22, according to the Australian Bureau of Statistics. As a result, software can sit underused after purchase, which delays renewals and expansion. Vendors respond with managed services, templates and training that help smaller teams read journey reports.
Why does distrust of AI limit automated analysis?
Many owners hesitate to let AI recommend actions on customer journeys because they want people to keep control. About 65% of businesses that do not use AI cited distrust in AI decision-making or a preference for human control, according to the National AI Centre survey for December 2025 to February 2026. In turn, AI features may sell slowly to smaller buyers. Vendors respond by explaining model outputs and keeping human approval steps.
How do cyber gaps raise the cost of journey data?
Journey platforms hold detailed records of customer behavior, which makes weak security a serious risk for buyers. About 21% of businesses reported a cyber security incident in 2024-25, and 28% had no measures in place to prevent one, according to the Australian Bureau of Statistics. As a result, buyers must fund access controls and audits before they expand data collection. Vendors respond with encryption, onshore hosting and certified security programs.
Why do new privacy duties lengthen project timelines?
New privacy duties force legal, risk and marketing teams to review how journey data feeds automated decisions before projects go live. Entities that use personal information in automated decisions must describe them in privacy policies from Dec. 10, 2026, which adds documentation work. In turn, implementation projects can take longer and cost more for banks, insurers and agencies. Vendors respond with consent tools and decision logs that support these disclosures.
New South Wales leads as Queensland grows fastest
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| New South Wales | 96.3 | 40.2% | 17.58% |
| Victoria | 71.6 | 29.9% | 17.63% |
| Queensland | 59.2 | 24.7% | 18.13% |
| Remaining States and Territories | 12.5 | 5.2% | 17.93% |
Why do Sydney head offices give the state the lead?
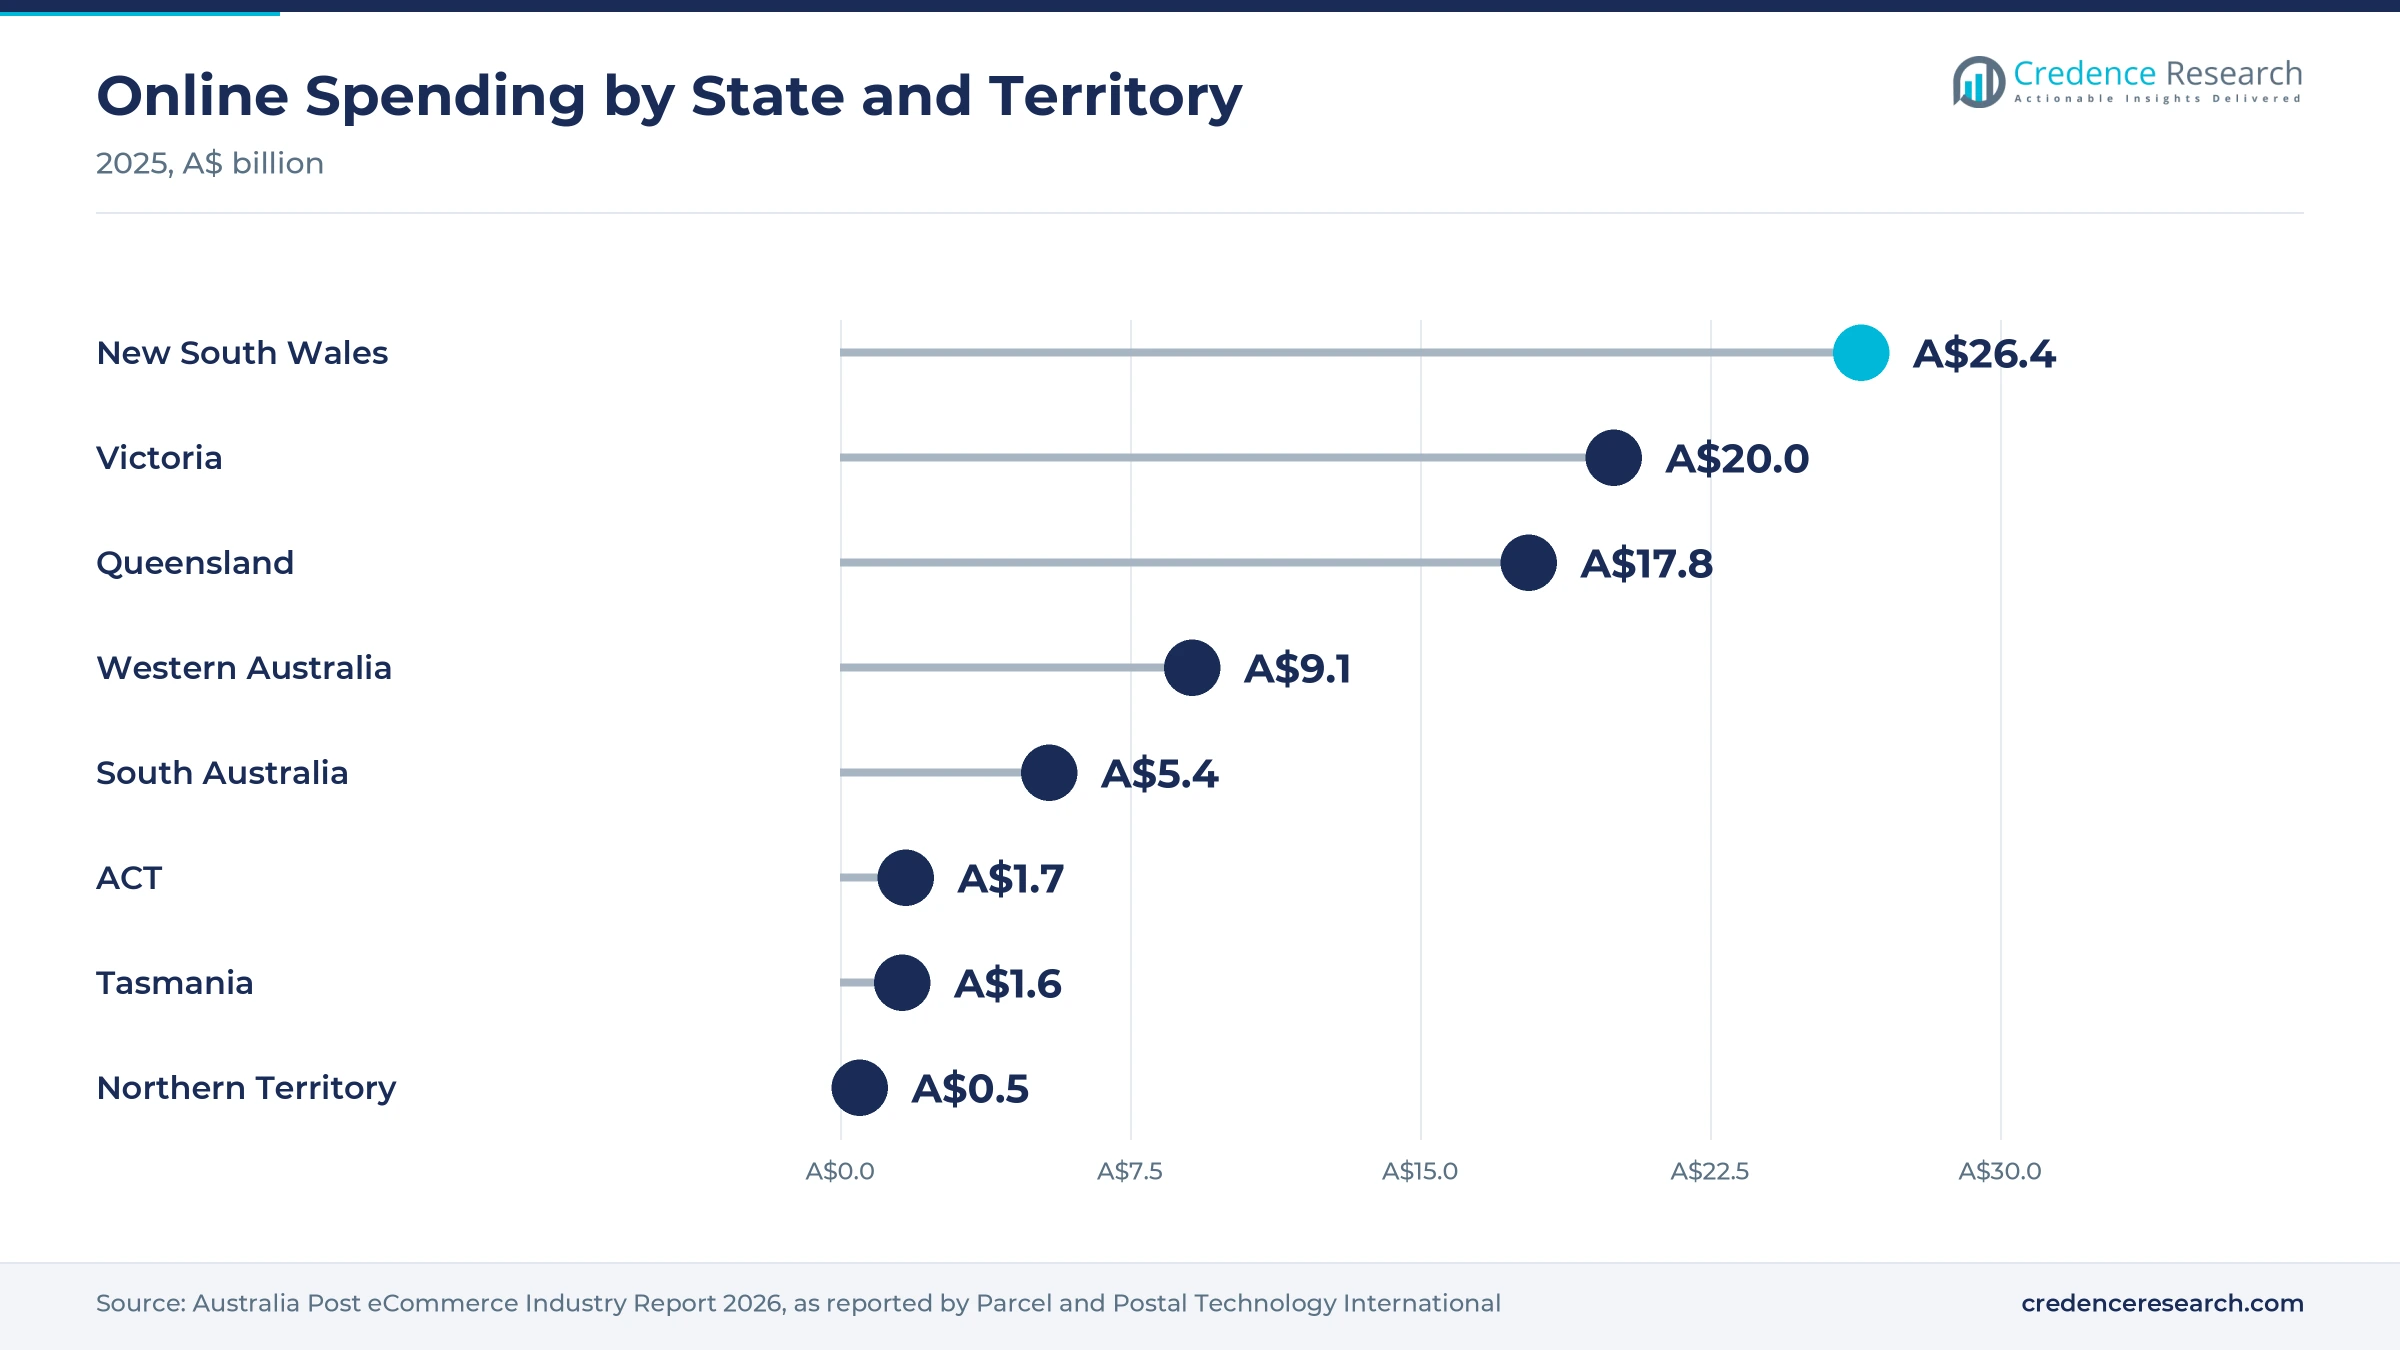
New South Wales held a 40.2% share of 2025 value and grows at 17.58% a year, because Sydney hosts the head offices of major banks, insurers and retailers. Households in the state spent about A$26.4 billion online in 2025, the largest total of any state, according to the Australia Post eCommerce Industry Report. Oracle said in May 2025 that its Sydney cloud region had received new NVIDIA AI chips, which adds local capacity for AI-assisted journey analysis. As a result, the state leads the country in large enterprise journey projects.
How does Victoria build on retail and cloud capacity?
Victoria held a 29.9% share of 2025 value and grows at 17.63% a year, because Melbourne hosts large retail, insurance and telecom employers. Victorian households spent about A$20 billion online in 2025, the second-largest state total. Microsoft named Melbourne among the cities in its October 2023 data center expansion, and Oracle launched Oracle Database@Google Cloud in the Melbourne region in October 2025. In turn, Victorian buyers gain local hosting choices for cloud journey platforms.
Why does Queensland lead growth in journey analytics?
Queensland held a 24.7% share of 2025 value and grows fastest at 18.13% a year, because its online spending base is expanding quickly. Queensland households spent about A$17.8 billion online in 2025, the third-largest state total. Flight Centre Travel Group runs its global head office in South Brisbane, which places a large travel retailer with heavy online booking traffic inside the state. As a result, travel, retail and service firms in the state add journey projects.
How do the remaining states and territories add demand?
The remaining states and territories held 5.2% of 2025 value and grow at 17.93% a year, because fewer enterprise head offices sit outside the three largest states. Western Australia households spent about A$9.1 billion online in 2025, South Australia A$5.4 billion and the Australian Capital Territory A$1.7 billion. Oracle opened a government cloud region in Canberra in August 2023 with more than 100 services. In turn, public agencies in the territory add service journey work.
Vendor investments and privacy rules since 2024
| Development | Status and market relevance |
|---|---|
| In December 2024, the Privacy and Other Legislation Amendment Act 2024 received royal assent, adding automated decision transparency duties from December 2026. | Raises governance demands on journey data |
| In February 2025, Salesforce announced a $2.5 billion, five-year investment in Australia at Agentforce World Tour Sydney. | Expands local AI and customer platform support |
| In September 2025, SAP announced Sovereign Cloud On-Site in Australia and plans to add SAP Business Data Cloud in 2026. | Widens sovereign data options for regulated buyers |
| In January 2026, Adobe made AI agents in Adobe Experience Manager generally available and added Australian deployment for Adobe Commerce. | Brings AI content and commerce tools onshore |
| In June 2026, the Australian Bureau of Statistics reported that about 35% of large businesses used AI in 2024-25. | Confirms rising enterprise AI use |
Unified profiles, AI agents and consent tools drive demand
- Unified customer profiles merge web, app, store and contact center records into one live record per customer, which journey analysis needs to link touchpoints.
- AI agents and copilots build segments and draft journeys from plain-language goals, as Microsoft describes for Dynamics 365 Customer Insights.
- Consent and preference tools record what each customer has agreed to, which supports the privacy disclosures that start in December 2026.
- Onshore cloud hosting keeps personal data inside Australia, which suits banks, insurers and public agencies with strict residency rules.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Global suites and local partners compete for enterprises
Competition centers on global software suites that combine customer data, analytics and journey orchestration, supported by local systems integrators. Salesforce, which employs more than 2,400 people in Australia, sells its AI and customer platforms to firms such as Telstra, Flight Centre and hipages. Adobe runs Adobe Experience Platform from a Sydney data center and offers Adobe Commerce with an Australian deployment option. Microsoft sells Dynamics 365 Customer Insights with Copilot features for journey building, backed by its local data center expansion. Oracle operates cloud regions in Sydney and a government region in Canberra, while SAP sells SAP Analytics Cloud through its Australian sovereign cloud. Rivals compete on onshore hosting, AI features, integration with existing CRM and commerce systems, consent controls and partner networks.
Which software vendors lead Australian journey analytics?
| Company | Type | Role in the market |
|---|---|---|
| Salesforce | CRM and AI platform vendor | Agentforce and customer platforms for Australian enterprises |
| Adobe | Digital experience vendor | Adobe Experience Platform hosted in Sydney |
| Microsoft | Cloud and business software vendor | Dynamics 365 Customer Insights with Copilot journeys |
| Oracle | Cloud and applications vendor | Sydney cloud region and Canberra government region |
| SAP | Enterprise software vendor | SAP Analytics Cloud on Australian sovereign cloud |
Credence Research view on Australian journey measurement
Credence Research's view is that Australian spending on journey analytics will rise much faster than general analytics budgets, because online spending, AI adoption and privacy law all push firms to understand each customer path. Cloud software keeps the largest share, while managed services grow faster as firms without data teams outsource analysis. Banks remain the largest buyers, yet retailers add the fastest growth as marketplace and app shopping spreads. Vendors that combine onshore hosting, consent controls and practical AI agents should gain the most share by 2035.
Commerce, AI adoption and privacy data behind the model
The report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. That model combines online spending data from Australia Post, ABS business technology statistics, National AI Centre adoption surveys, OAIC and ACCC regulatory releases, and vendor announcements on local hosting and AI products. Segment splits and zone growth rates are Credence Research estimates. Sources used are statistics agency and regulator publications, company releases, industry reports and international agency data, and no interviews or surveys were used.
Governed AI and retail data carry demand to 2035
The Australia customer journey analytics market is expected to reach USD 1.26 billion by 2035, a 17.75% CAGR during 2026–2035, as brands, banks and agencies measure journeys across apps, marketplaces, stores and contact centers. Growth should be strongest in managed analytics, cloud deployment, retail and e-commerce, service journey work and Queensland, because these areas gain most from AI tools and rising online spending. Thin data skills and new privacy duties could slow some projects, while onshore hosting should support regulated buyers after 2030.
Frequently Asked Questions
How big is the Australia customer journey analytics market?
Which deployment model leads the market?
Which region leads the market?
How much do Australians spend online?
How do privacy reforms affect journey analytics?
How widely do large Australian businesses use AI?
Who are the leading companies in the market?
What are the main challenges for the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Solution Type
- 1.2.1 Analytics Software
- 1.2.2 Implementation Services
- 1.2.3 Managed Analytics and Support
- 1.3 By Deployment Model
- 1.3.1 Cloud
- 1.3.2 Hybrid
- 1.3.3 On-Premises
- 1.4 By End-Use Industry
- 1.4.1 BFSI
- 1.4.2 Retail and E-Commerce
- 1.4.3 Telecom and IT
- 1.4.4 Non-Financial Services and Public Sector
- 1.5 By Application
- 1.5.1 Acquisition and Attribution
- 1.5.2 Conversion Optimisation
- 1.5.3 Retention and Churn
- 1.5.4 Service Journey Improvement
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 239.5 million → 2035: USD 1.26 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Customer Journey Analytics Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Customer Journey Analytics Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Australia Customer Journey Analytics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Australia Customer Journey Analytics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Customer Journey Analytics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Customer Journey Analytics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Customer Journey Analytics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Customer Journey Analytics Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 239.5 million → 2035: USD 1.26 billion)
- 11.1.2 Historical Market Size, 2018-2025
- 11.1.3 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Customer Journey Analytics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Solution Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Base-Year Market Share, 2025
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Analytics Software
- 12.3.6.2 Implementation Services
- 12.3.6.3 Managed Analytics and Support
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Deployment Model - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Base-Year Market Share, 2025
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Cloud
- 12.4.6.2 Hybrid
- 12.4.6.3 On-Premises
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By End-Use Industry - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Base-Year Market Share, 2025
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 BFSI
- 12.5.6.2 Retail and E-Commerce
- 12.5.6.3 Telecom and IT
- 12.5.6.4 Non-Financial Services and Public Sector
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Base-Year Market Share, 2025
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Acquisition and Attribution
- 12.6.6.2 Conversion Optimisation
- 12.6.6.3 Retention and Churn
- 12.6.6.4 Service Journey Improvement
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Customer Journey Analytics End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Customer Journey Analytics Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Customer Journey Analytics Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Customer Journey Analytics Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Salesforce
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Microsoft
- 18.4 Oracle
- 18.5 Adobe
- 18.6 SAP
- 18.7 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

