
Flavor, medicine and lab buyers keep guaiacol in demand
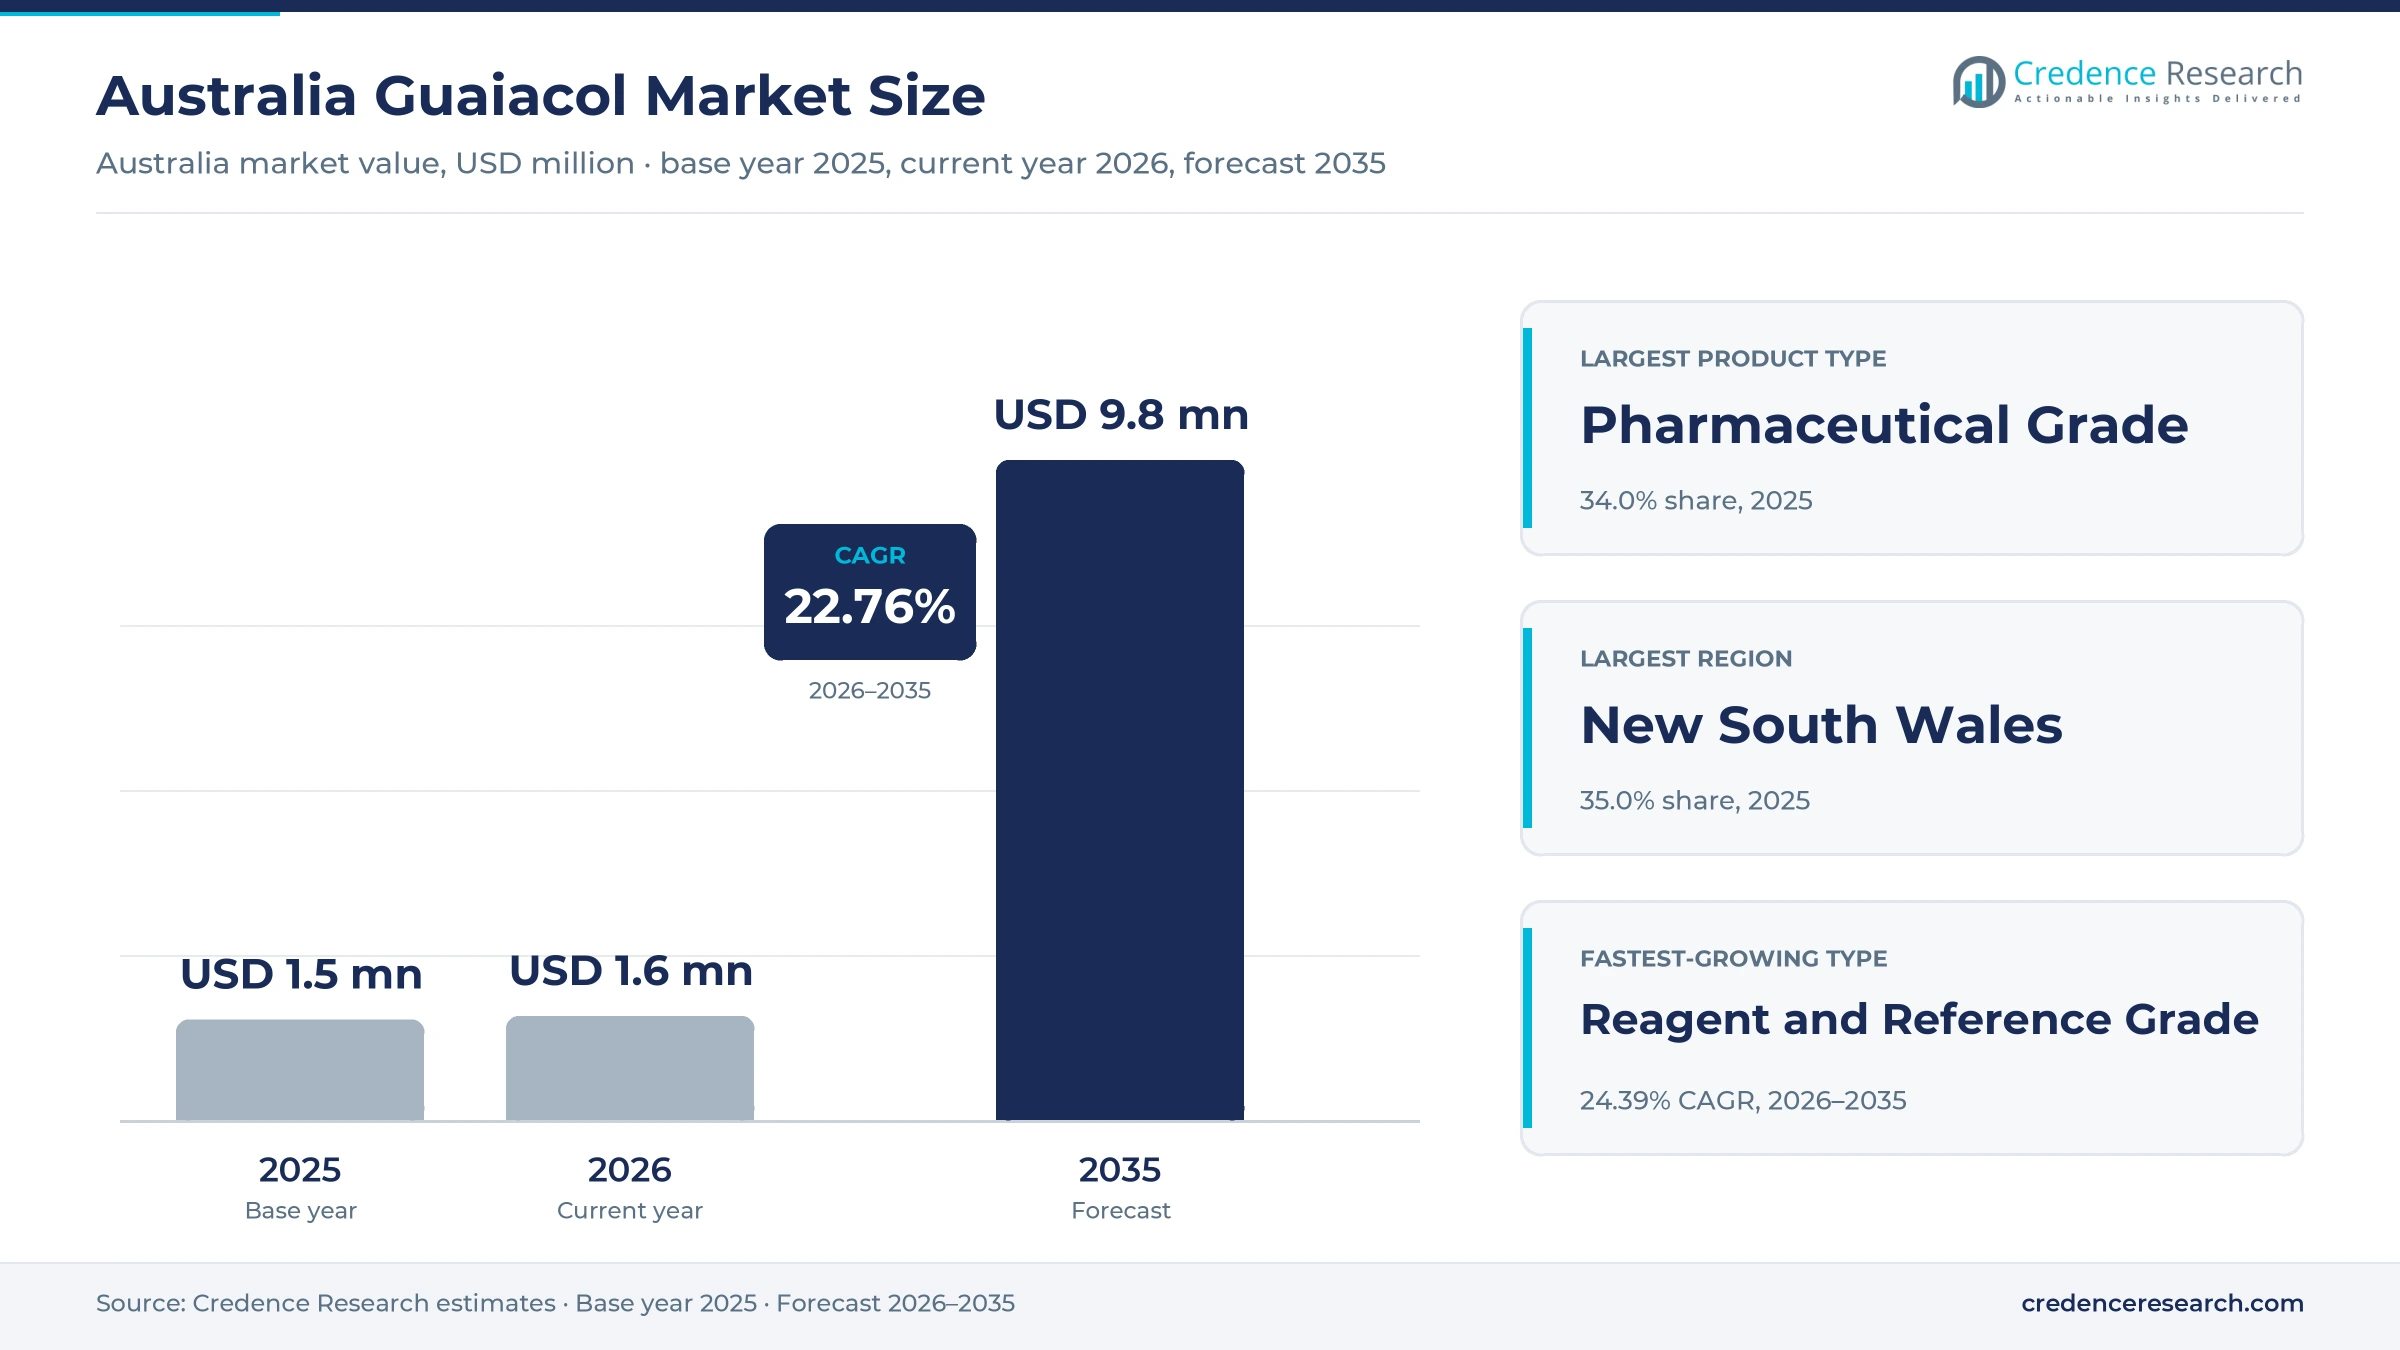
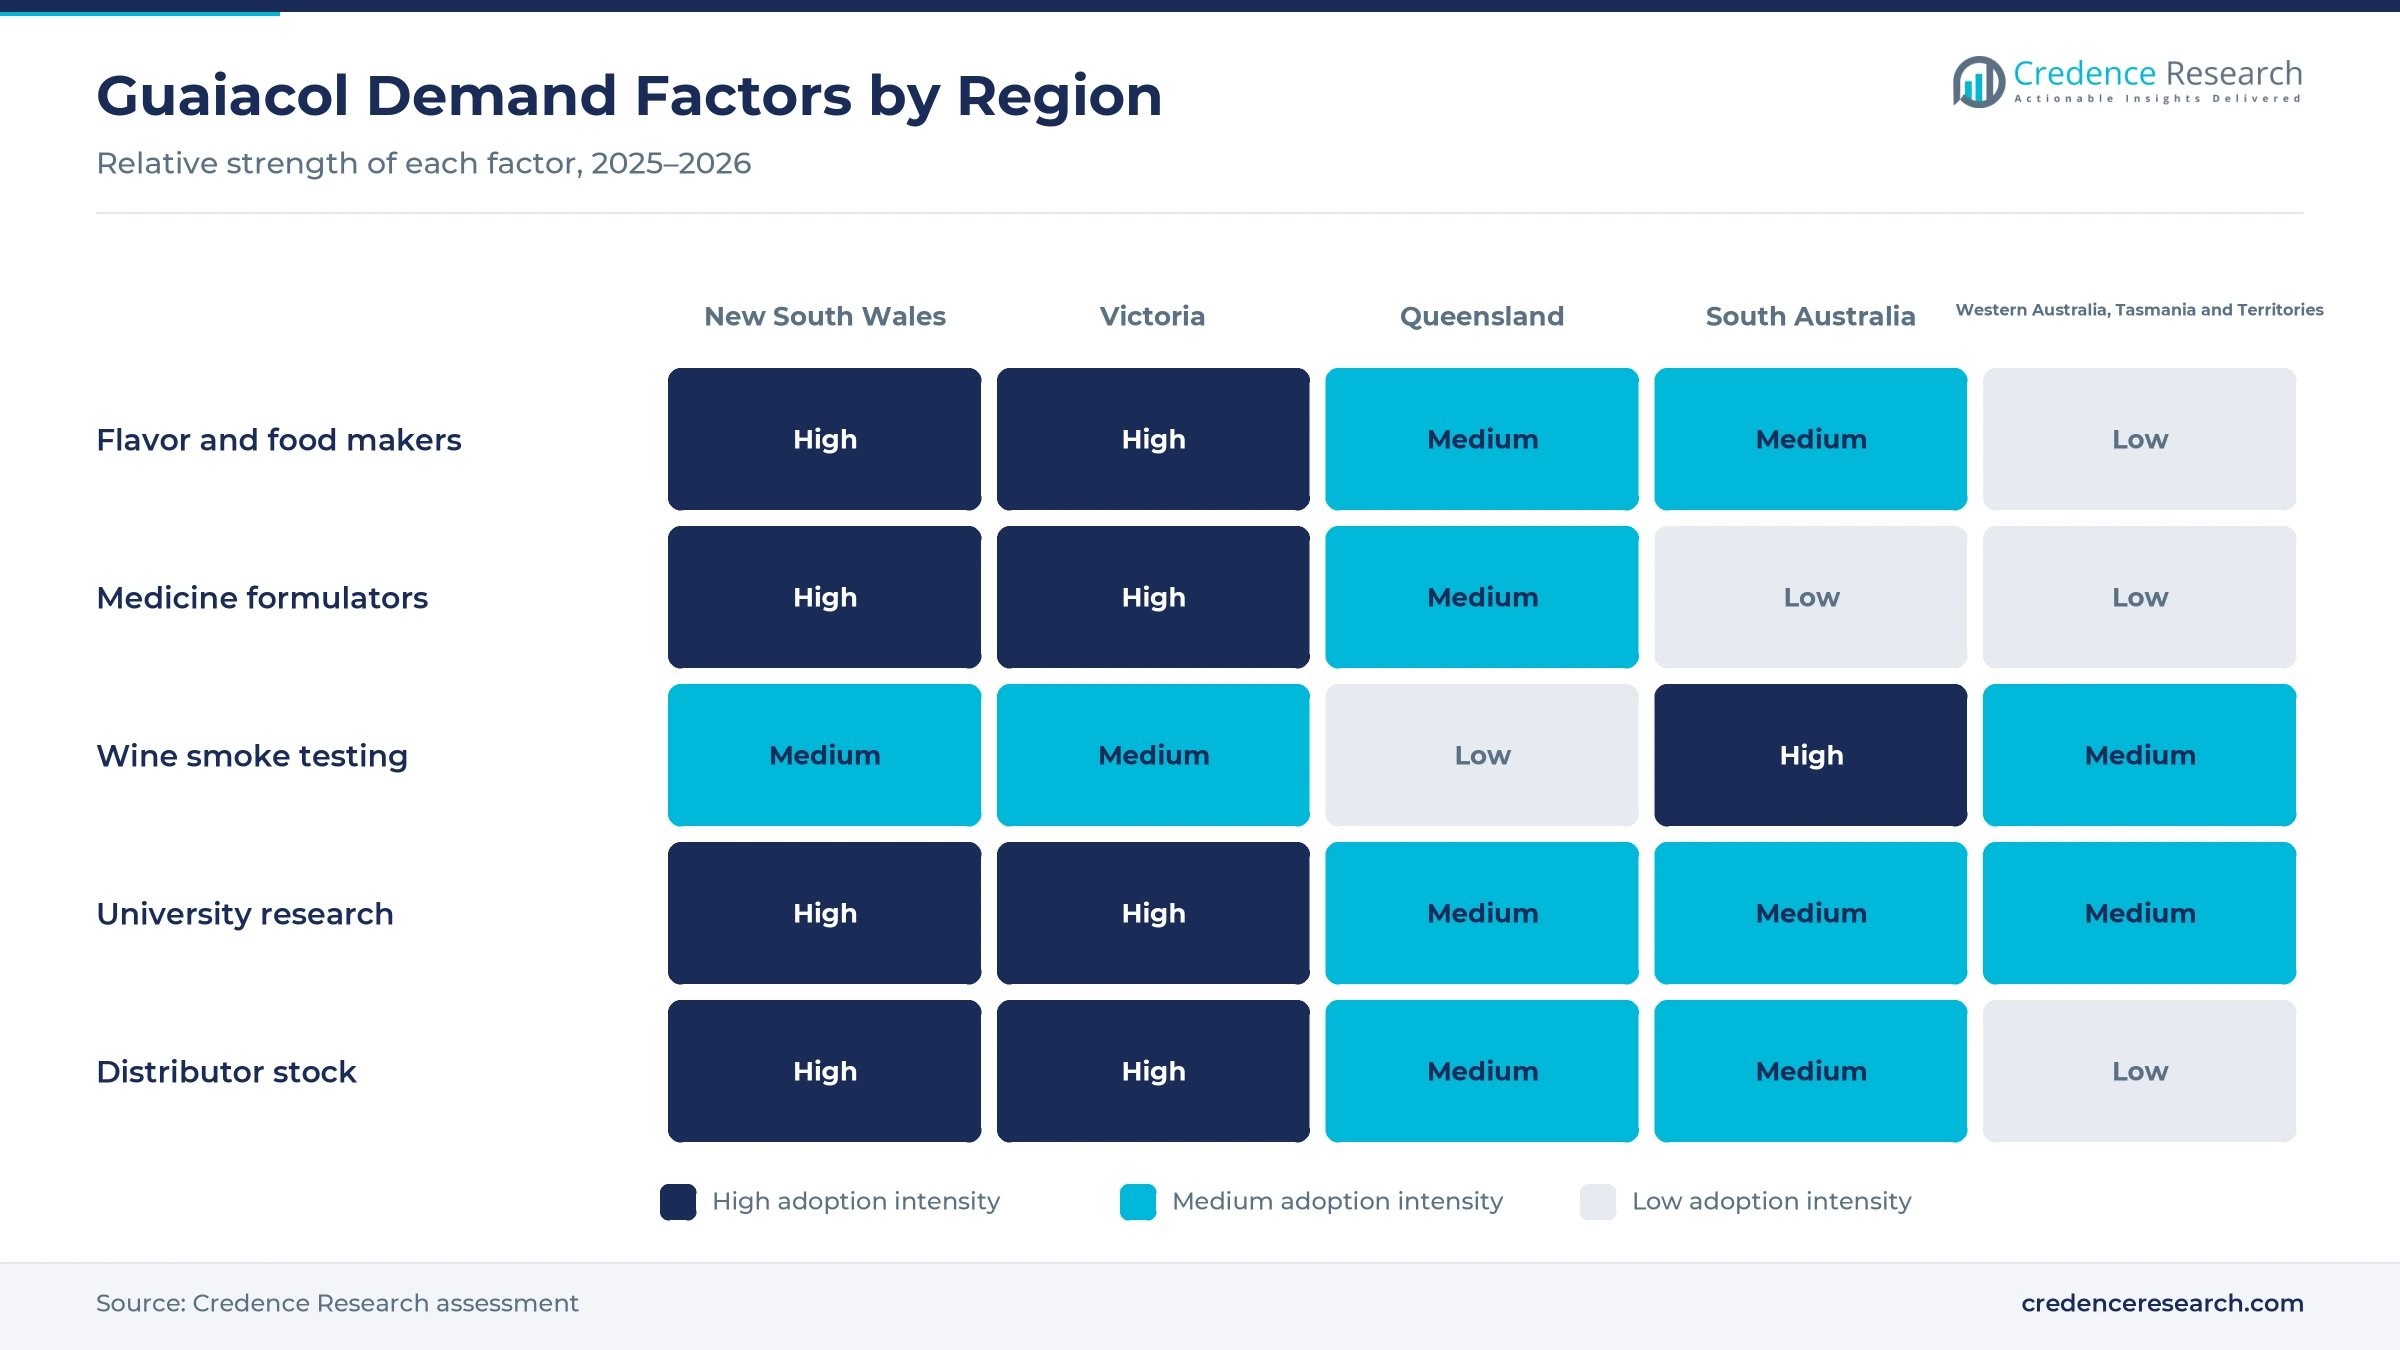
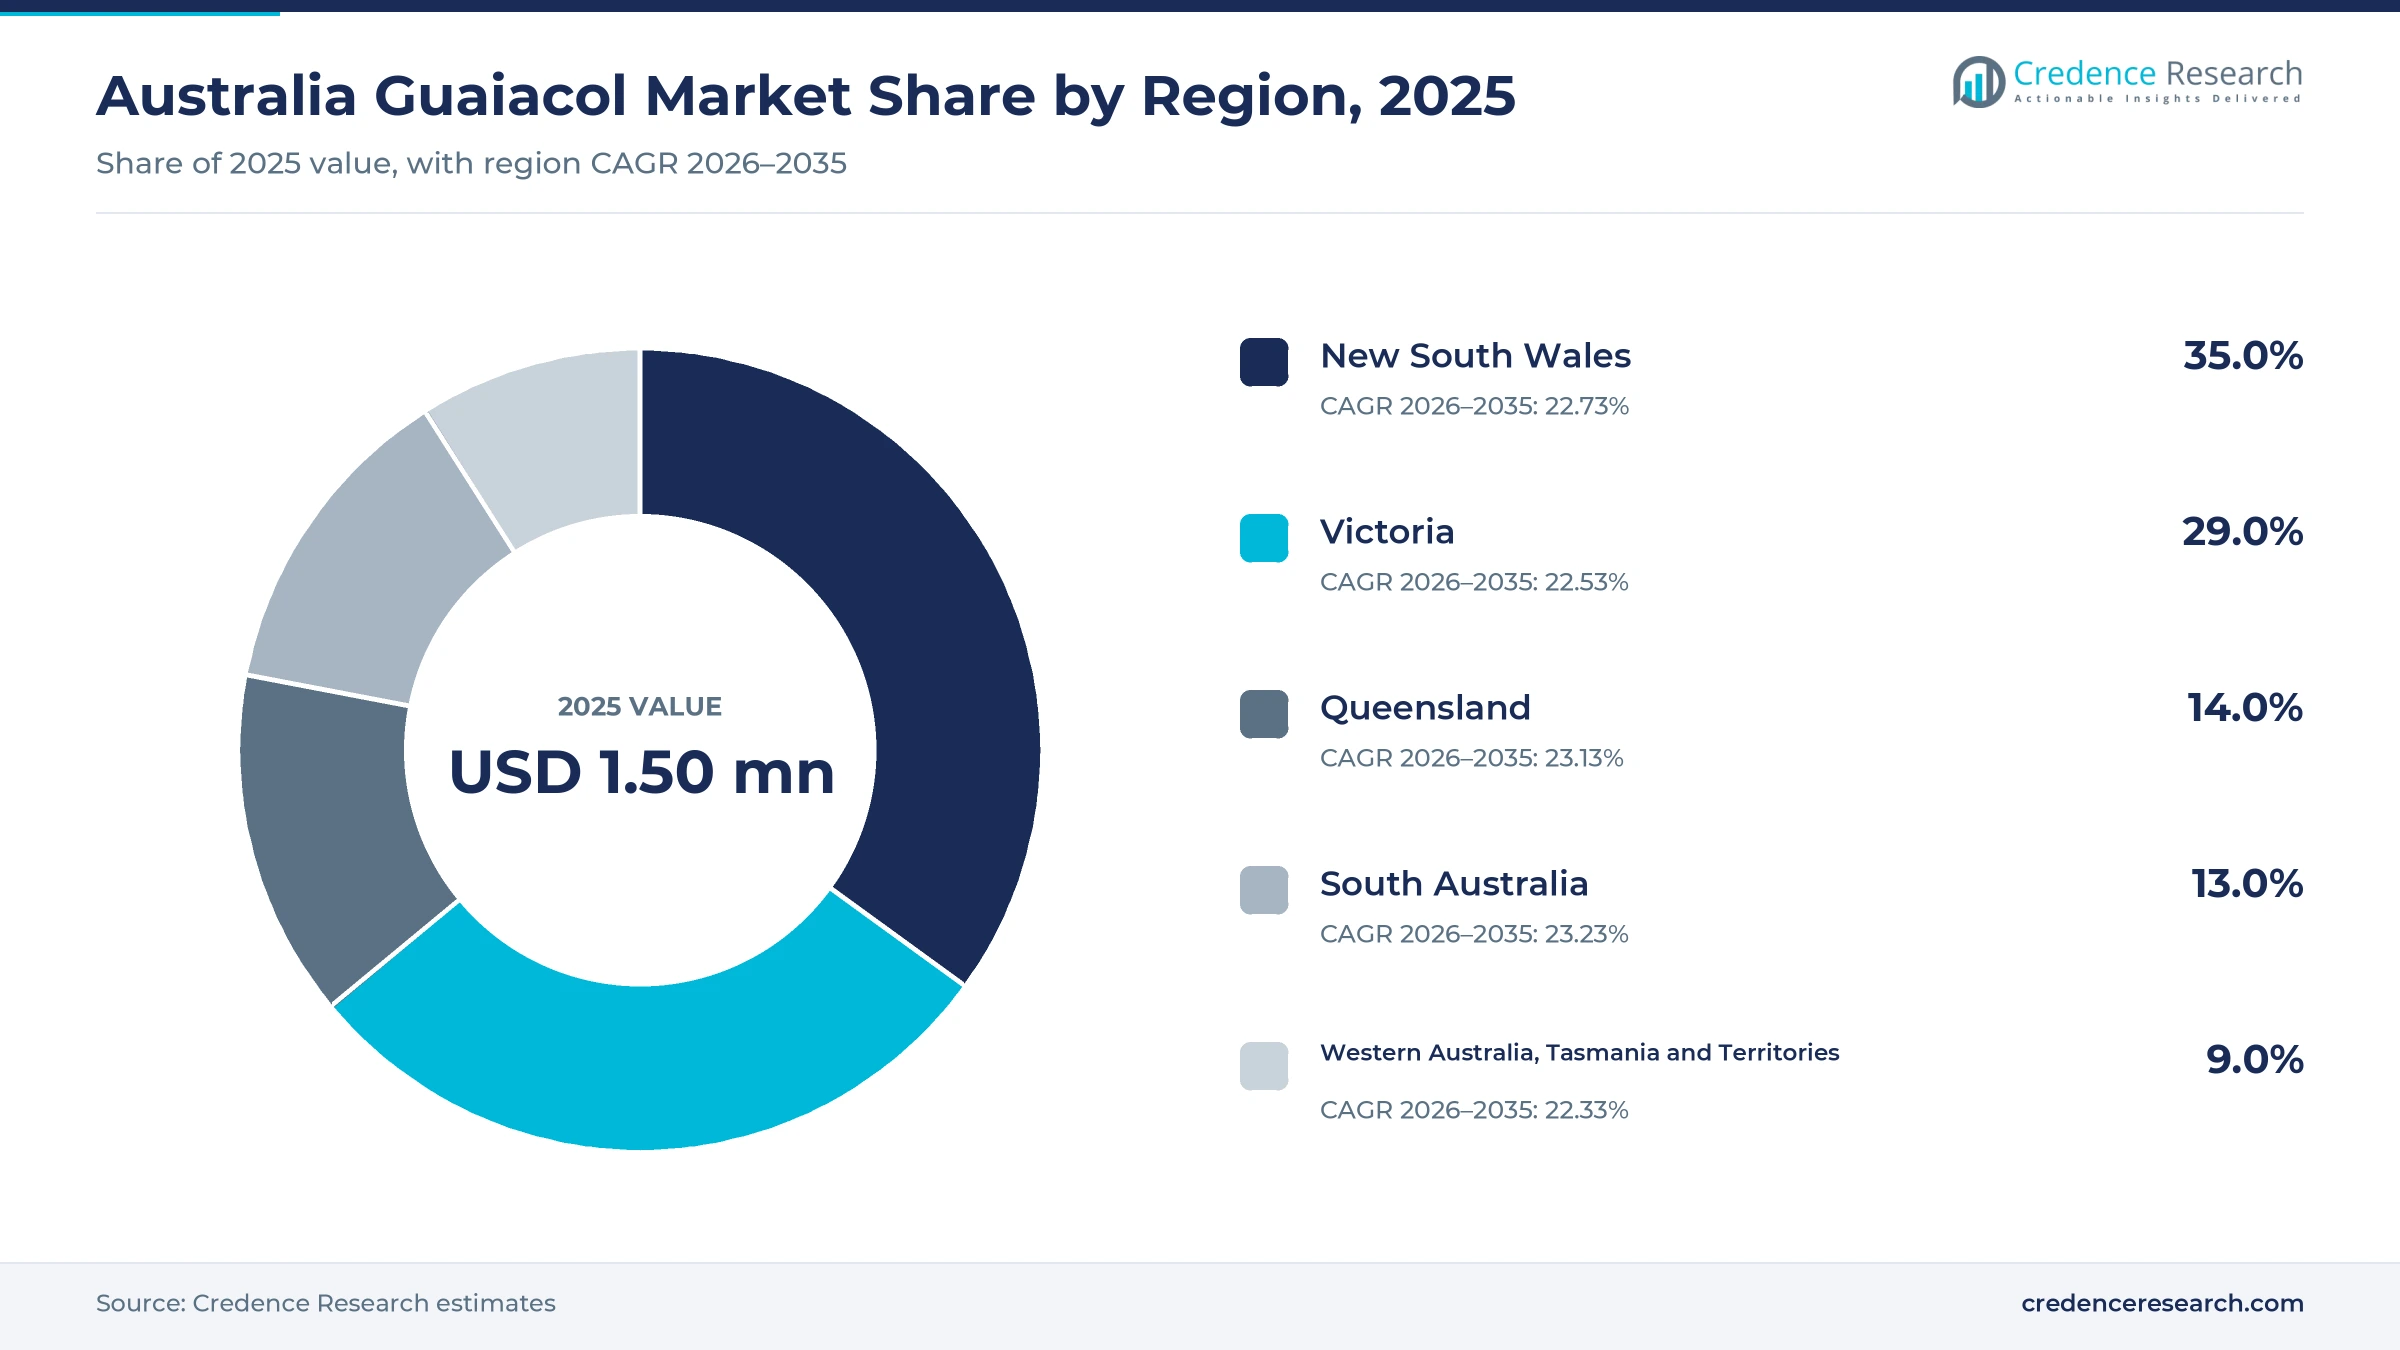
The Australia guaiacol market was valued at USD 1.50 million in 2025 and is projected to increase from USD 1.55 million in 2026 to USD 9.84 million by 2035, registering a CAGR of 22.76% during 2026–2035. Demand comes from flavor houses, food and beverage makers, medicine formulators and laboratories that buy guaiacol as a smoky flavor ingredient, an expectorant intermediate and an oxidation indicator for enzyme assays. New South Wales held the largest regional share, 35.0% in 2025, because the state has the largest population and the widest base of food, medicine and laboratory buyers. South Australia is the fastest-growing region at 23.23% a year, as wine laboratories test grapes and wine for smoke marker compounds such as guaiacol after bushfire seasons. In turn, laboratories now pair volatile phenol tests with glycoside panels, which raises demand for reference grade material in small, certified packs.
Which guaiacol grades and buyers are counted in Australia?
The estimate measures spending in Australia on pharmaceutical, food and flavor, technical and reagent and reference grades of guaiacol, also known as 2-methoxyphenol. It covers purchases by food and beverage manufacturers, pharmaceutical formulators, fragrance and personal care manufacturers, and research and testing laboratories through national chemical distributors, specialist laboratory suppliers and direct overseas procurement. Values are stated in USD million at current prices and exclude goods and services tax.
The estimate excludes finished medicines, finished flavors, guaifenesin and vanillin sold as separate products. The value chain runs from overseas producers that methylate catechol or recover guaiacol from biomass, through importers and catalog distributors, to flavor houses, medicine makers, wine laboratories and university research groups.
Australia Guaiacol Market Insights
- The Australia guaiacol market was valued at USD 1.50 million in 2025 and is projected to reach USD 9.84 million by 2035, at a 22.76% CAGR during 2026–2035.
- New South Wales held 35.0% of 2025 value, because the state had 8.67 million residents in March 2026 and hosts most distributors.
- Pharmaceutical grade led product types with 34.0% of 2025 value, as guaiacol serves as an intermediate for expectorant ingredients.
- Wine Australia reported a 2025 crush of about 1.57 million metric tons, up 11%, which widened the base of grapes tested for smoke markers.
- Reagent and reference grade grows fastest at 24.39% a year during 2026–2035, as wine and enzyme laboratories buy certified small packs.
Pharmaceutical grade leads, reference grade grows fastest
Why does pharmaceutical grade lead guaiacol demand?
Based on product type, the market is categorized into pharmaceutical grade, food and flavor grade, technical grade and reagent and reference grade. Pharmaceutical Grade led with 34.0% of 2025 value, because medicine makers need documented purity for expectorant ingredients. Reagent and Reference Grade grows fastest at 24.39% a year, as wine and enzyme laboratories buy certified material in small packs.
Which applications use the most guaiacol?
Based on application, the market is categorized into direct formulation, chemical synthesis, analytical testing and experimental research. Direct Formulation led with 46.0% of 2025 value, because flavor houses and medicine makers add guaiacol directly to formulas. Analytical Testing grows fastest at 24.20% a year, as wine laboratories test for smoke marker compounds after bushfire seasons.
Which buyers account for most guaiacol purchases?
Based on end user, the market is categorized into food and beverage manufacturers, pharmaceutical formulators, fragrance and personal care manufacturers, and research and testing laboratories. Food and Beverage Manufacturers led with 32.0% of 2025 value, because smoky and spicy flavor systems use guaiacol at low doses. Research and Testing Laboratories grow fastest at 23.90% a year, as smoke taint and enzyme assays expand.
How do Australian buyers source guaiacol?
Based on sales channel, the market is categorized into national chemical distributors, specialist laboratory suppliers and direct overseas procurement. National Chemical Distributors led with 52.0% of 2025 value, because most buyers need local stock, safety data and small delivery lots. Specialist Laboratory Suppliers grow fastest at 23.76% a year, as laboratories order certified reference packs online.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product Type | Pharmaceutical Grade | 34.0% | Reagent and Reference Grade | 24.39% |
| By Application | Direct Formulation | 46.0% | Analytical Testing | 24.20% |
| By End User | Food and Beverage Manufacturers | 32.0% | Research and Testing Laboratories | 23.90% |
| By Sales Channel | National Chemical Distributors | 52.0% | Specialist Laboratory Suppliers | 23.76% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Flavor approvals, assays and smoke taint testing lift use
How does qualified flavor ingredient demand lift volumes?
Qualified flavor ingredient demand lifts volumes, because food makers in Australia prefer additives with an international safety review. The joint FAO and WHO expert committee lists guaiacol as flavoring agent No. 713 and FEMA No. 2532, and its 2000 evaluation found no safety concern at current intakes. Public chemical data from the U.S. National Library of Medicine list guaiacol as a flavoring agent for non-alcoholic beverages and foods. The same record names guaiacol as an intermediate for vanillin, which links it to bio-based vanillin supply. As a result, food and beverage manufacturers lead end users with 32.0% of 2025 value in the Australia guaiacol market.
Why do laboratory assays and research raise reagent use?
Laboratory assays and research raise reagent use, because guaiacol is a standard oxidation indicator in enzyme tests. Merck sells guaiacol G5502 as an oxidation indicator with an assay of at least 98.0%, for peroxidase and laccase activity measurements. Cayman Chemical describes guaiacol as a reducing co-substrate for cyclooxygenase reactions, with a colored product read at 470 nanometers. Merck Life Science also runs its Australian office in Bayswater, Victoria, which gives Australian laboratories a local point of contact. Consequently, reagent and reference grade grows fastest among product types at 24.39% a year, as research groups in the Australia guaiacol market buy small, certified packs.
How does specification-led medicine formulation add demand?
Specification-led medicine formulation adds demand, because expectorant ingredients and guaiacol derivatives need documented purity. Public chemical data list guaiacol as a stimulant expectorant and as an intermediate for guaiacol carbonate and papaverine. Guaifenesin, a related expectorant, is sold as a 100 milligram per 5 milliliter oral liquid that is not scheduled, according to the national health information service. The medicines regulator also lists Vicks Formula 44 for Chesty Coughs with guaifenesin under ARTG ID 279356. As a result, pharmaceutical grade leads product types with 34.0% of 2025 value, because formulators pay more for certificates and batch records.
Why does smoke taint testing in wine regions raise demand?
Smoke taint testing in wine regions raises demand, because laboratories need guaiacol standards to measure smoke exposure in grapes and wine. The national wine research institute identified guaiacol and 4-methylguaiacol as key compounds behind smoky off-aromas, and its smoke analysis fact sheet lists seven volatile phenols and six phenolic glycosides. Results are returned within 10 working days of the day samples reach the laboratory. Wine Australia also reported a 2025 crush of about 1.57 million metric tons, up 11%, worth about AUD 1.13 billion. Consequently, analytical testing grows fastest among applications at 24.20% a year, as wineries test more lots after smoke events.
Glycoside panels, smaller vintages and lignin routes emerge
How is the rise of glycoside panels changing testing?
The rise of glycoside panels is changing smoke testing, because bound forms of guaiacol release smoky flavor long after fermentation. The research institute recommends running volatile phenol and glycoside panels together, and it measures guaiacol rutinoside and methylguaiacol rutinoside. On Nov. 5, 2025, it announced that its background database of smoke marker compounds now covers 21 Australian grape varieties. A study of the 2020 vintage also found that 13 smoke markers could predict smoky flavor in Chardonnay, Pinot Noir and Shiraz wines. As a result, research and testing laboratories grow fastest among end users at 23.90% a year, because each sample needs several calibrated reference compounds.
Why is the shift toward smaller vintages emerging?
The shift toward smaller vintages is emerging, because lower crushes push wineries to test fewer but more valuable grape lots. Wine Australia announced on July 15, 2026, that the 2026 crush fell about 19% to around 1.27 million metric tons, the smallest since 2000. The red crush fell 29%, while the average price of purchased grapes fell 6% to AUD 570 per metric ton. In 2025, South Australia held 48% of the national crush and New South Wales held 33%, according to Wine Australia. In turn, wine laboratories in South Australia keep testing premium lots, which supports steady orders for reference grade guaiacol.
Can bushfire preparedness programs open testing demand?
Bushfire preparedness programs open a clear testing opportunity, because governments and grower groups fund smoke analysis after fire seasons. In January 2020, the South Australian government announced free smoke taint tests funded through a AUD 330,000 recovery package after the Adelaide Hills fire that started on Dec. 20, 2019, when tests normally cost about AUD 300 each. Wine Australia estimated in March 2020 that fire and smoke damaged about 4% of the national wine grape crop, or 60,000 metric tons. On Feb. 3, 2025, smoke from Victorian fires drifted into regions in four states. Consequently, suppliers of analytical reference standards can build seasonal stock programs for wine laboratories.
Is there room to grow with lignin-derived guaiacol?
Lignin-derived guaiacol offers a growth opening, because buyers want flavor and aroma chemicals from renewable feedstocks. Public chemical data state that guaiacol was first isolated from guaiac resin and from the oxidation of lignin, and that it is commonly derived from guaiacum or wood creosote. The wine research institute also notes that guaiacol forms from lignin when oak barrels are toasted, and a control wine stored in stainless steel for 93 weeks held five micrograms per liter of guaiacol from fruit precursors. Interest in lignin as a chemical feedstock therefore supports biomass-derived recovery routes. As a result, food and flavor grade buyers in the Australia guaiacol market can qualify natural-origin material for direct formulation, which held 46.0% of 2025 value.
Import reliance, small lots and vintage swings weigh
How does import reliance raise supply risk?
Import reliance raises supply risk, because Australian buyers source guaiacol from overseas producers and catalog warehouses. Shipping delays and currency swings can lift landed costs quickly for small flavor houses and laboratories. As a result, buyers without safety stock face delays or must switch grades during disruptions. Distributors reduce this risk by holding local inventory and qualifying more than one producer for each grade, which protects regular customers during long shipping delays.
Why do small order sizes keep unit costs high?
Small order sizes keep unit costs high, because most Australian buyers purchase guaiacol in bottles rather than drums. Freight, dangerous goods handling and documentation add a large share to each small delivery. Consequently, laboratories and small formulators pay far more per kilogram than bulk buyers overseas. Suppliers answer with shared freight runs, larger pack options and standing orders, although these require buyers to commit volumes in advance.
How do feedstock swings affect guaiacol prices?
Feedstock swings affect guaiacol prices, because the synthetic O-methylation route starts from catechol, whose cost follows petrochemical feedstock prices. Producers pass these changes through price lists that can move within months. In turn, formulators on fixed-price supply contracts absorb margin pressure. Buyers manage this risk through shorter price reviews, dual sourcing and inventory timing that keeps flavor and medicine programs within budget.
Will vintage swings slow testing volumes?
Vintage swings can slow testing volumes, because smoke testing depends on fire seasons and on the size of each grape crush. Wine Australia reported that the 2026 crush was the smallest since 2000. As a result, laboratories may order fewer reference standards in quiet seasons and much more in smoky ones. Suppliers that offer short lead times and flexible pack sizes can manage these swings better than suppliers that ship only from overseas.
New South Wales leads as South Australia grows fastest
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| New South Wales | 0.5 | 35.0% | 22.73% |
| Victoria | 0.4 | 29.0% | 22.53% |
| Queensland | 0.2 | 14.0% | 23.13% |
| South Australia | 0.2 | 13.0% | 23.23% |
| Western Australia, Tasmania and Territories | 0.1 | 9.0% | 22.33% |
Why does New South Wales lead guaiacol demand?
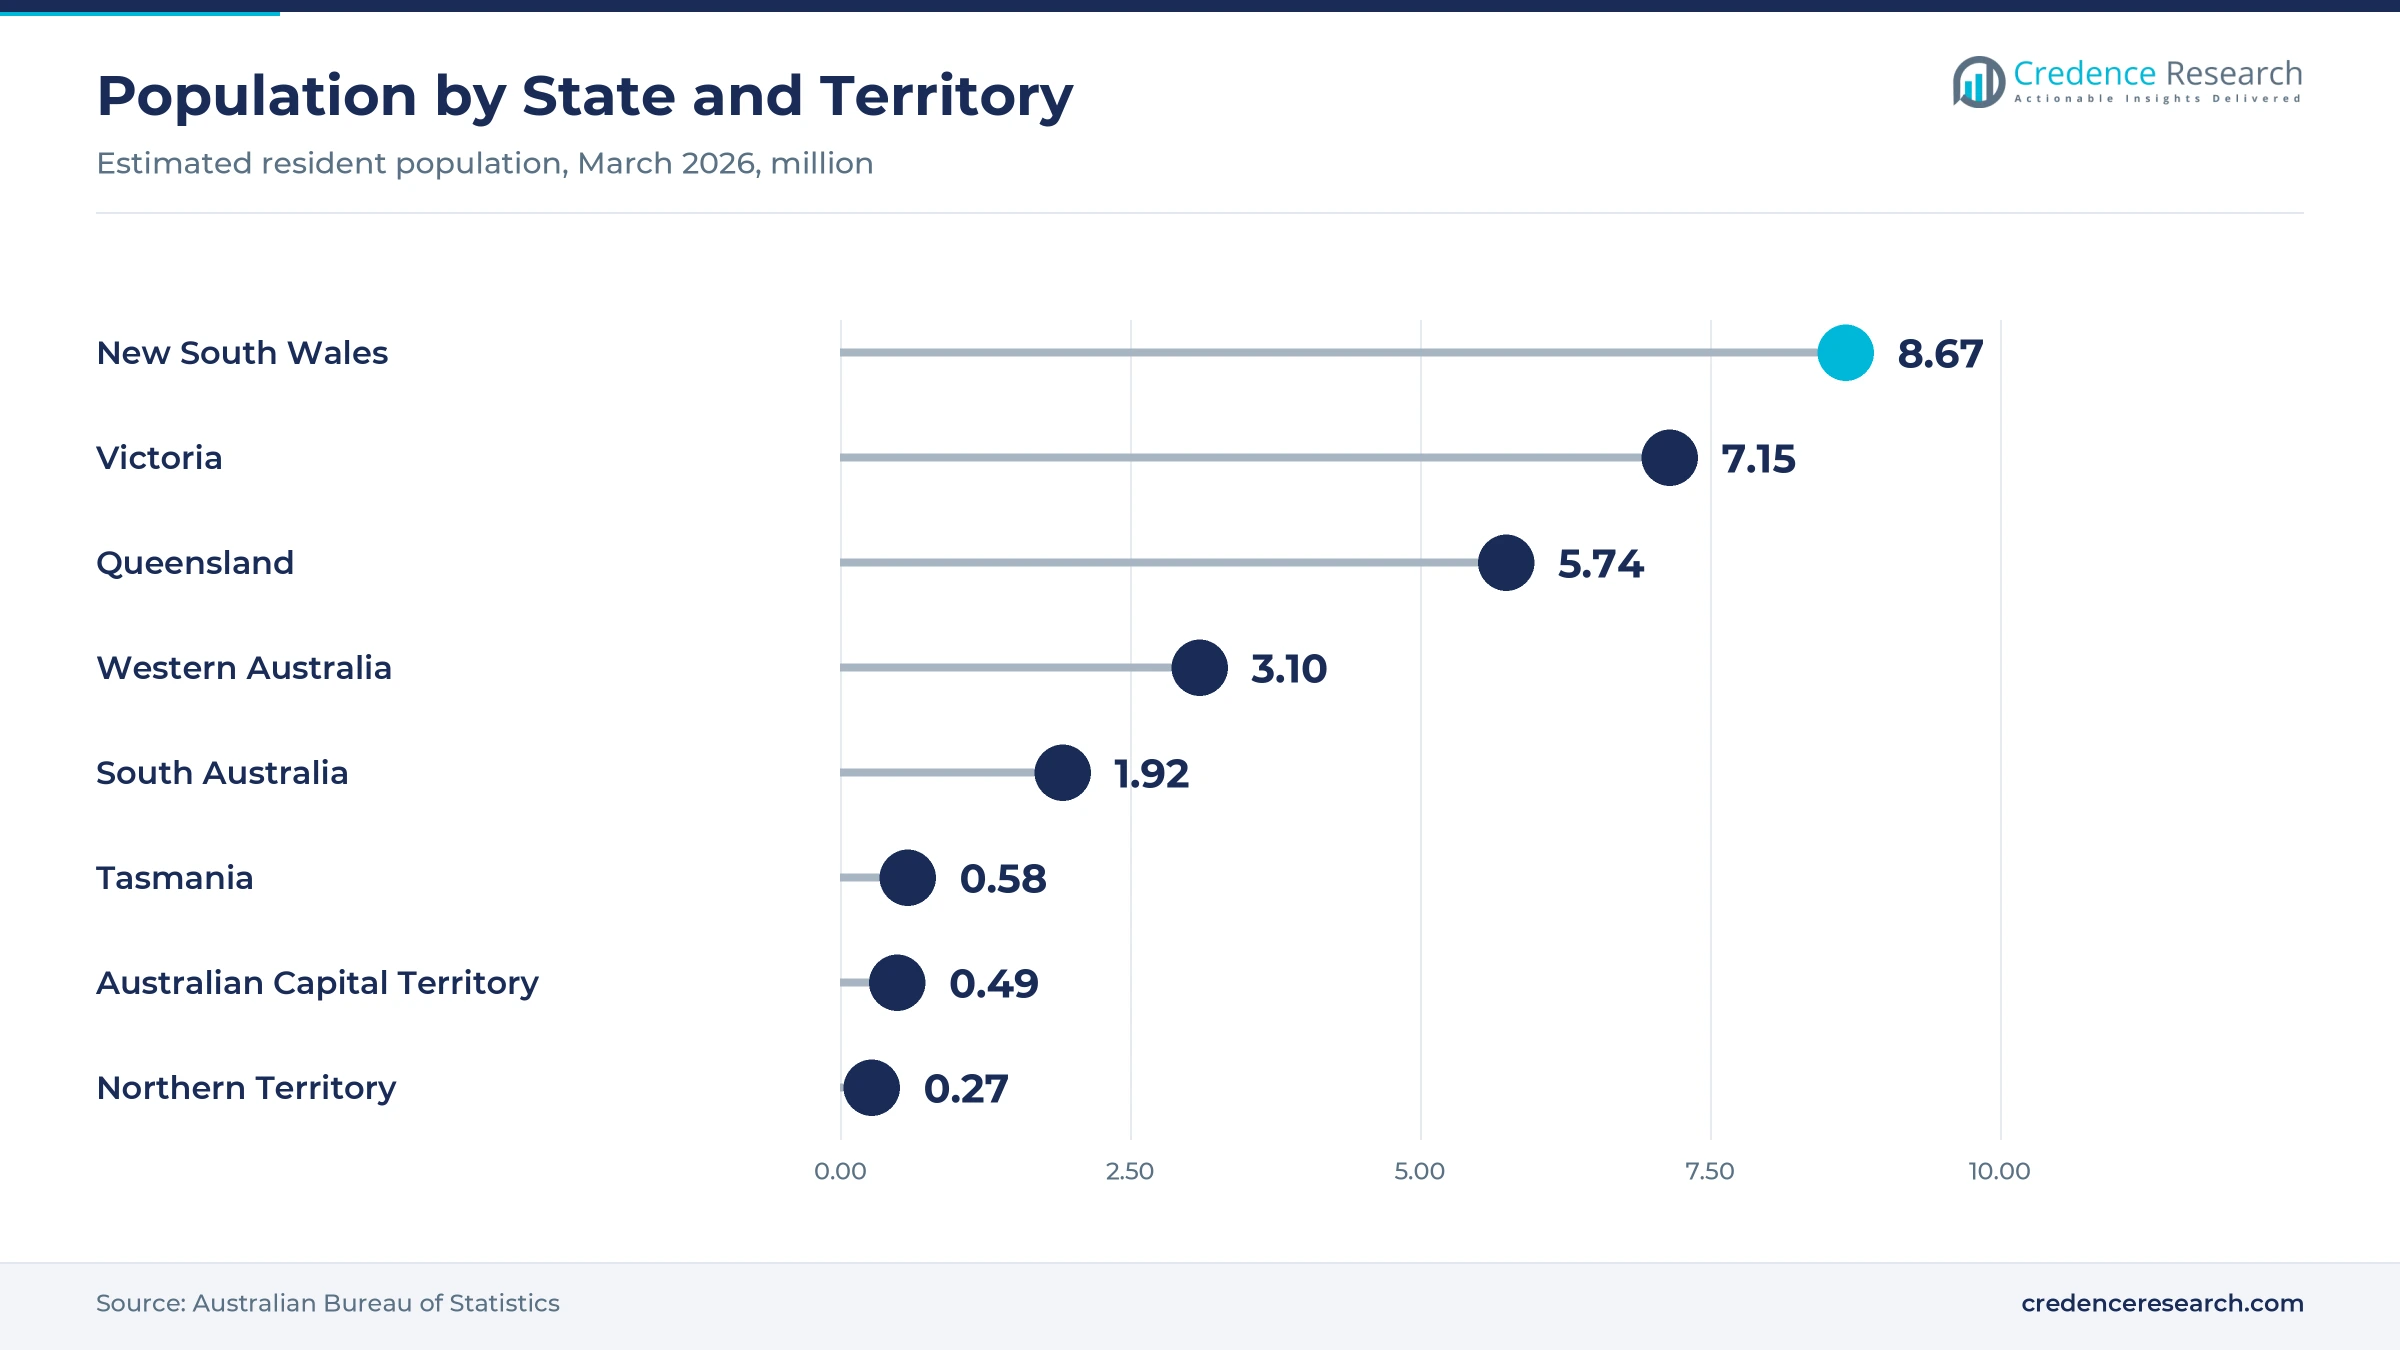
New South Wales held a 35.0% share of 2025 value and grows at 22.73% a year. The state had 8.67 million residents at March 2026, according to the Australian Bureau of Statistics, and that large population supports the widest base of food, medicine and laboratory buyers. New South Wales also held 33% of the 2025 wine grape crush. As a result, the state keeps the largest share of guaiacol purchases through 2035.
How does Victoria support the distribution corridor?
Victoria held a 29.0% share of 2025 value and grows at 22.53% a year, because the state has the second-largest population and a broad base of food, laboratory and university buyers. The state population grew 1.6% to 7.15 million in the year to March 2026. Merck Life Science also runs its Australian office in Bayswater. Consequently, Victoria and New South Wales together form the main corridor for guaiacol distribution and catalog orders.
Why is South Australia the fastest-growing zone?
South Australia held a 13.0% share of 2025 value and grows fastest at 23.23% a year, because the state crushed 48% of national wine grapes in 2025. Adelaide also hosts the national wine research institute, which runs smoke marker analysis for growers. In turn, smoke taint testing and wine research keep adding demand for reference grade guaiacol in the state.
How does Queensland add demand?
Queensland held 14.0% of 2025 value and grows at 23.13% a year. The state population grew 1.6% to 5.74 million in the year to March 2026, which supports food manufacturing and hospital laboratories. Therefore, Queensland adds steady demand for food and flavor grade and reagent grade material.
What role do Western Australia, Tasmania and the territories play?
Western Australia, Tasmania and the territories held 9.0% of 2025 value and grow at 22.33% a year. Western Australia grew fastest in population, at 2.1% in the year to March 2026. As a result, demand comes mainly from wine, food and university laboratories.
Smoke alerts, vintage reports and population data, 2025–2026
| Development | Status and market relevance |
|---|---|
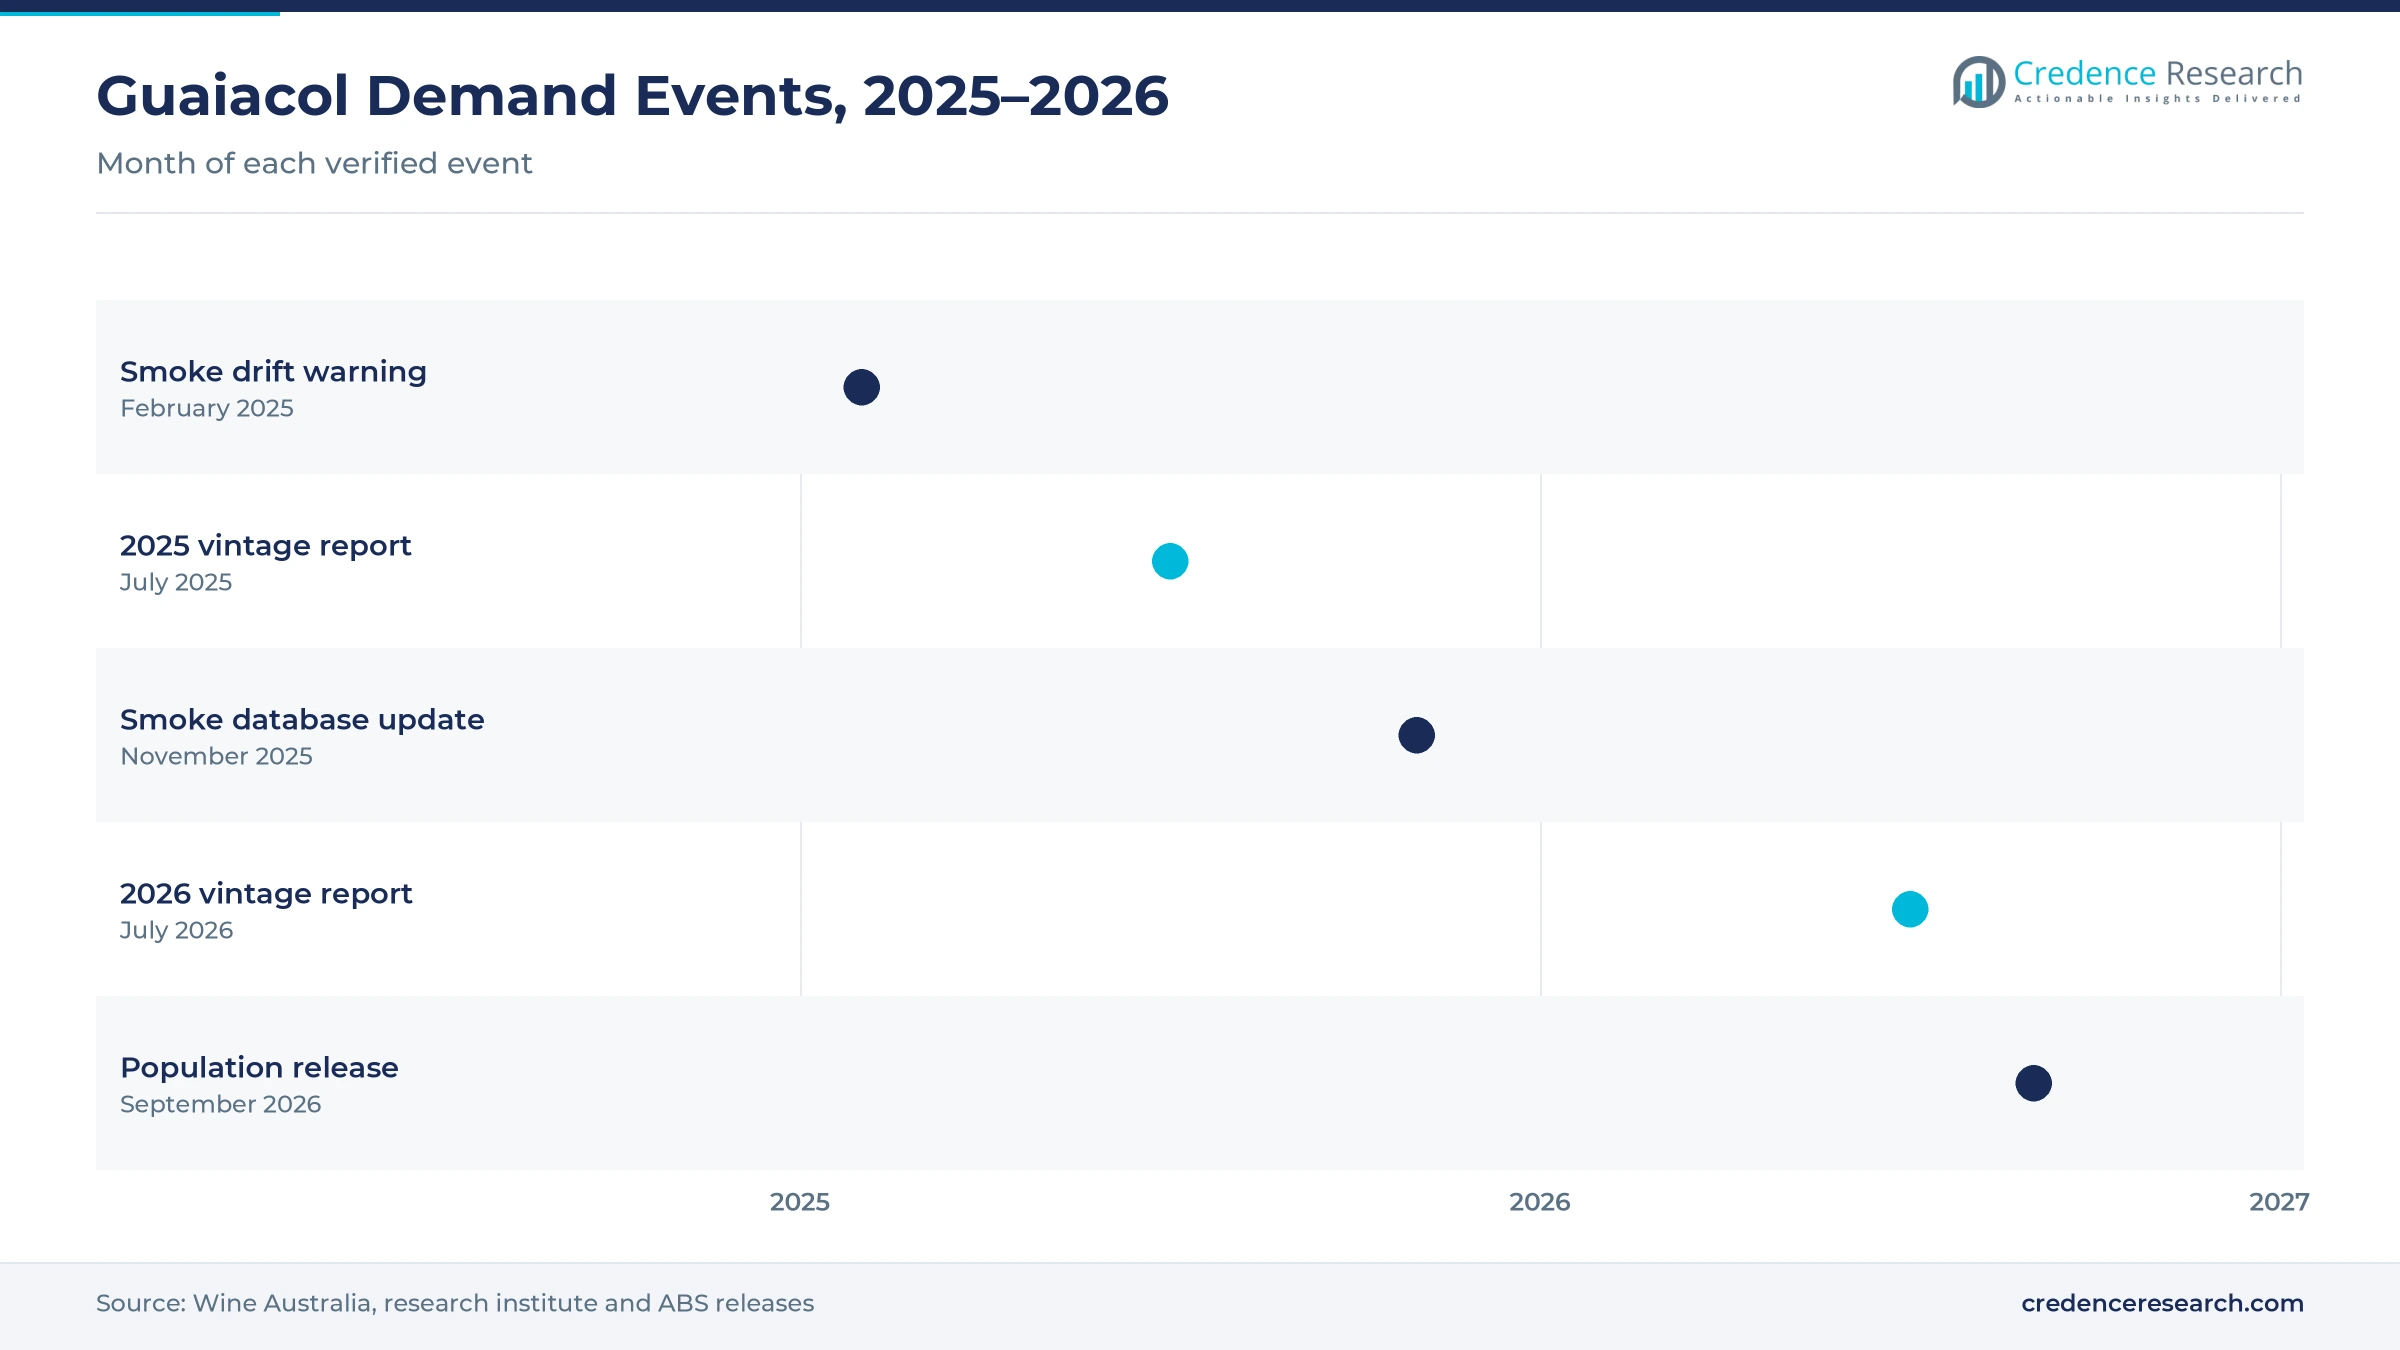
| In February 2025, the national wine research institute warned that smoke from Victorian bushfires was drifting into wine regions in Victoria, New South Wales, Tasmania and South Australia. | Raised smoke marker testing needs |
| In July 2025, Wine Australia announced a 2025 crush of about 1.57 million metric tons, up 11% on 2024. | Widened the base of grapes tested |
| In November 2025, the national wine research institute announced that its background database of smoke marker compounds covers 21 grape varieties. | Supports comparison of guaiacol results |
| In July 2026, Wine Australia announced the smallest crush since 2000, at about 1.27 million metric tons. | Shifts testing toward premium lots |
| In September 2026, the Australian Bureau of Statistics reported a population of 27.9 million at March 2026, up 1.4%. | Sets the base for regional demand |
Synthesis routes and test panels shape guaiacol supply
- Catechol O-methylation starts from catechol as the raw material, which gives consistent purity for pharmaceutical and flavor grades.
- Biomass-derived recovery separates guaiacol from lignin and wood creosote streams, which supports natural-origin claims for flavor buyers.
- Volatile phenol panels measure guaiacol, 4-methylguaiacol, syringol and cresols in wine, which needs calibrated reference standards.
- Glycoside panels measure bound smoke markers such as guaiacol rutinoside, which predicts smoky flavor that appears after fermentation.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Catalog suppliers compete on purity, stock and documents
Competition combines global catalog suppliers, Australian laboratory distributors and specialty chemical importers. Merck sells guaiacol G5502 as an oxidation indicator with an assay of at least 98.0% and serves Australian buyers from its Merck Life Science office in Bayswater, Victoria. Cayman Chemical offers guaiacol of at least 98% purity as a co-substrate for cyclooxygenase assays. The wider supplier field covered in this report also includes Thermo Fisher Scientific, TCI, Scharlab, Glentham Life Sciences, ChemSupply Australia, Haines Educational, Pure Science and POCD Scientific, which serve laboratory, education and industrial buyers. Companies compete on purity, documentation, local stock, dangerous goods handling and delivery speed. Larger suppliers also bundle guaiacol with other reference compounds, which helps them win smoke taint and enzyme assay programs at wine and university laboratories.
Which suppliers serve Australian guaiacol buyers?
| Company | Type | Role in the market |
|---|---|---|
| Merck (Merck Life Science Pty Ltd) | Catalog supplier | Guaiacol G5502 oxidation indicator; Australian office in Bayswater, Victoria |
Credence Research sees lab testing driving guaiacol growth
Credence Research's view is that Australian guaiacol demand will grow quickly from a small base through 2035, as smoke taint testing, enzyme assays and qualified flavor ingredients widen use. Pharmaceutical grade should keep the largest product share, while reagent and reference grade gains most from laboratory testing. New South Wales and Victoria will remain the main distribution corridor, although South Australia adds demand fastest. However, import reliance and small order sizes will reward suppliers that hold local stock and certified packs.
Pack sizes, end uses and imports anchor the guaiacol model
The report uses 2025 as the base year, with values in USD million at current prices. Market values come from the Credence Research model, which combines end-use volumes, pack sizes, import flows and price tiers. Regional shares and segment splits by product type, application, end user and sales channel are Credence Research estimates. Sources used are official statistics, regulator records, research institute publications, industry body releases and company product pages, and no interviews or surveys were used.
Testing and qualified grades shape guaiacol to 2035
The market is expected to reach USD 9.84 million by 2035, a 22.76% CAGR during 2026–2035, as testing and qualified grades keep demand rising. Growth should be strongest in reagent and reference grade, analytical testing and South Australia, while New South Wales keeps the largest share. Glycoside panels and bushfire preparedness programs will widen laboratory demand after 2026. In contrast, small vintages or long shipping disruptions could slow purchases and push buyers toward fewer, larger orders.
Frequently Asked Questions
How big is the Australia guaiacol market?
Which region leads guaiacol demand?
Which region grows fastest?
Which product type holds the largest share?
Why do wine laboratories buy guaiacol?
Which product type grows fastest?
Who are the leading companies in this market?
What are the main risks to growth?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Pharmaceutical Grade
- 1.2.2 Food and Flavor Grade
- 1.2.3 Technical Grade
- 1.2.4 Reagent and Reference Grade
- 1.3 By Application
- 1.3.1 Direct Formulation
- 1.3.2 Chemical Synthesis
- 1.3.3 Analytical Testing
- 1.3.4 Experimental Research
- 1.4 By End User
- 1.4.1 Food and Beverage Manufacturers
- 1.4.2 Pharmaceutical Formulators
- 1.4.3 Fragrance and Personal Care Manufacturers
- 1.4.4 Research and Testing Laboratories
- 1.5 By Sales Channel
- 1.5.1 National Chemical Distributors
- 1.5.2 Specialist Laboratory Suppliers
- 1.5.3 Direct Overseas Procurement
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 1.50 million → 2035: USD 9.84 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Guaiacol Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Guaiacol Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Guaiacol Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Guaiacol Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Guaiacol Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Guaiacol Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Guaiacol Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Guaiacol Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 1.50 million → 2035: USD 9.84 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Guaiacol Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Pharmaceutical Grade
- 12.3.7.2 Food and Flavor Grade
- 12.3.7.3 Technical Grade
- 12.3.7.4 Reagent and Reference Grade
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Direct Formulation
- 12.4.7.2 Chemical Synthesis
- 12.4.7.3 Analytical Testing
- 12.4.7.4 Experimental Research
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End User - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Food and Beverage Manufacturers
- 12.5.7.2 Pharmaceutical Formulators
- 12.5.7.3 Fragrance and Personal Care Manufacturers
- 12.5.7.4 Research and Testing Laboratories
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Sales Channel - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 National Chemical Distributors
- 12.6.7.2 Specialist Laboratory Suppliers
- 12.6.7.3 Direct Overseas Procurement
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Guaiacol End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Guaiacol Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Guaiacol Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Guaiacol Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Merck
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Thermo Fisher Scientific
- 18.4 ChemSupply Australia
- 18.5 TCI
- 18.6 Scharlab
- 18.7 Glentham Life Sciences
- 18.8 Cayman Chemical
- 18.9 Haines Educational
- 18.10 Pure Science
- 18.11 POCD Scientific
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

