
Frequent orders push sellers to outsourced fulfillment
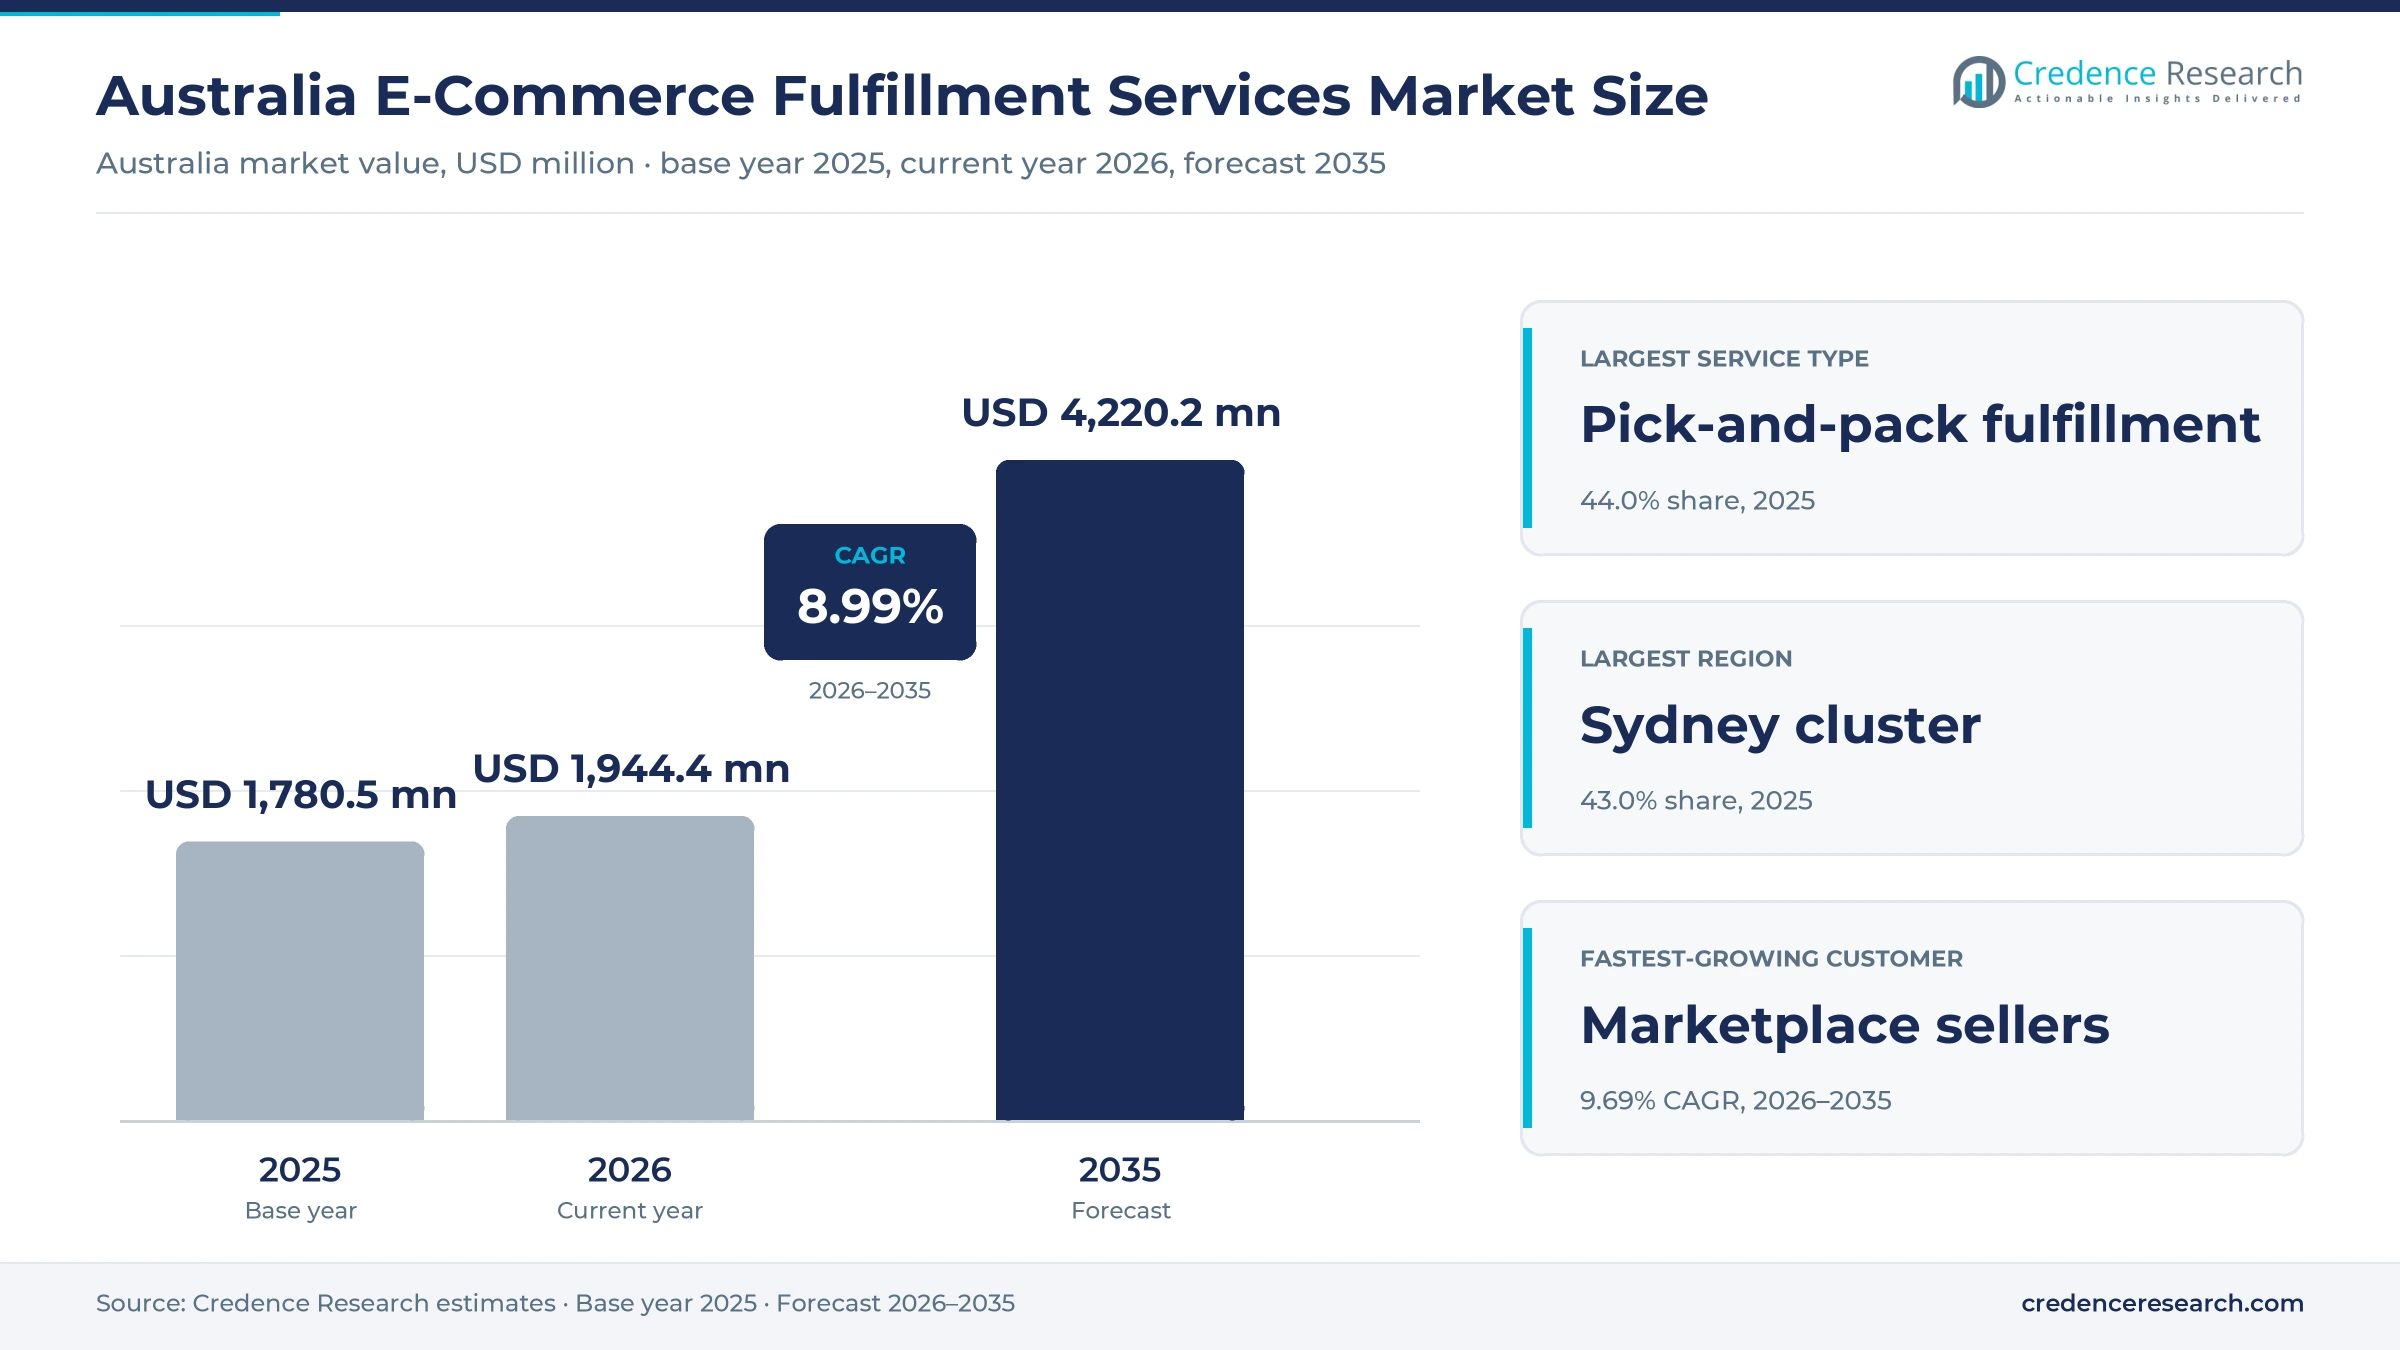
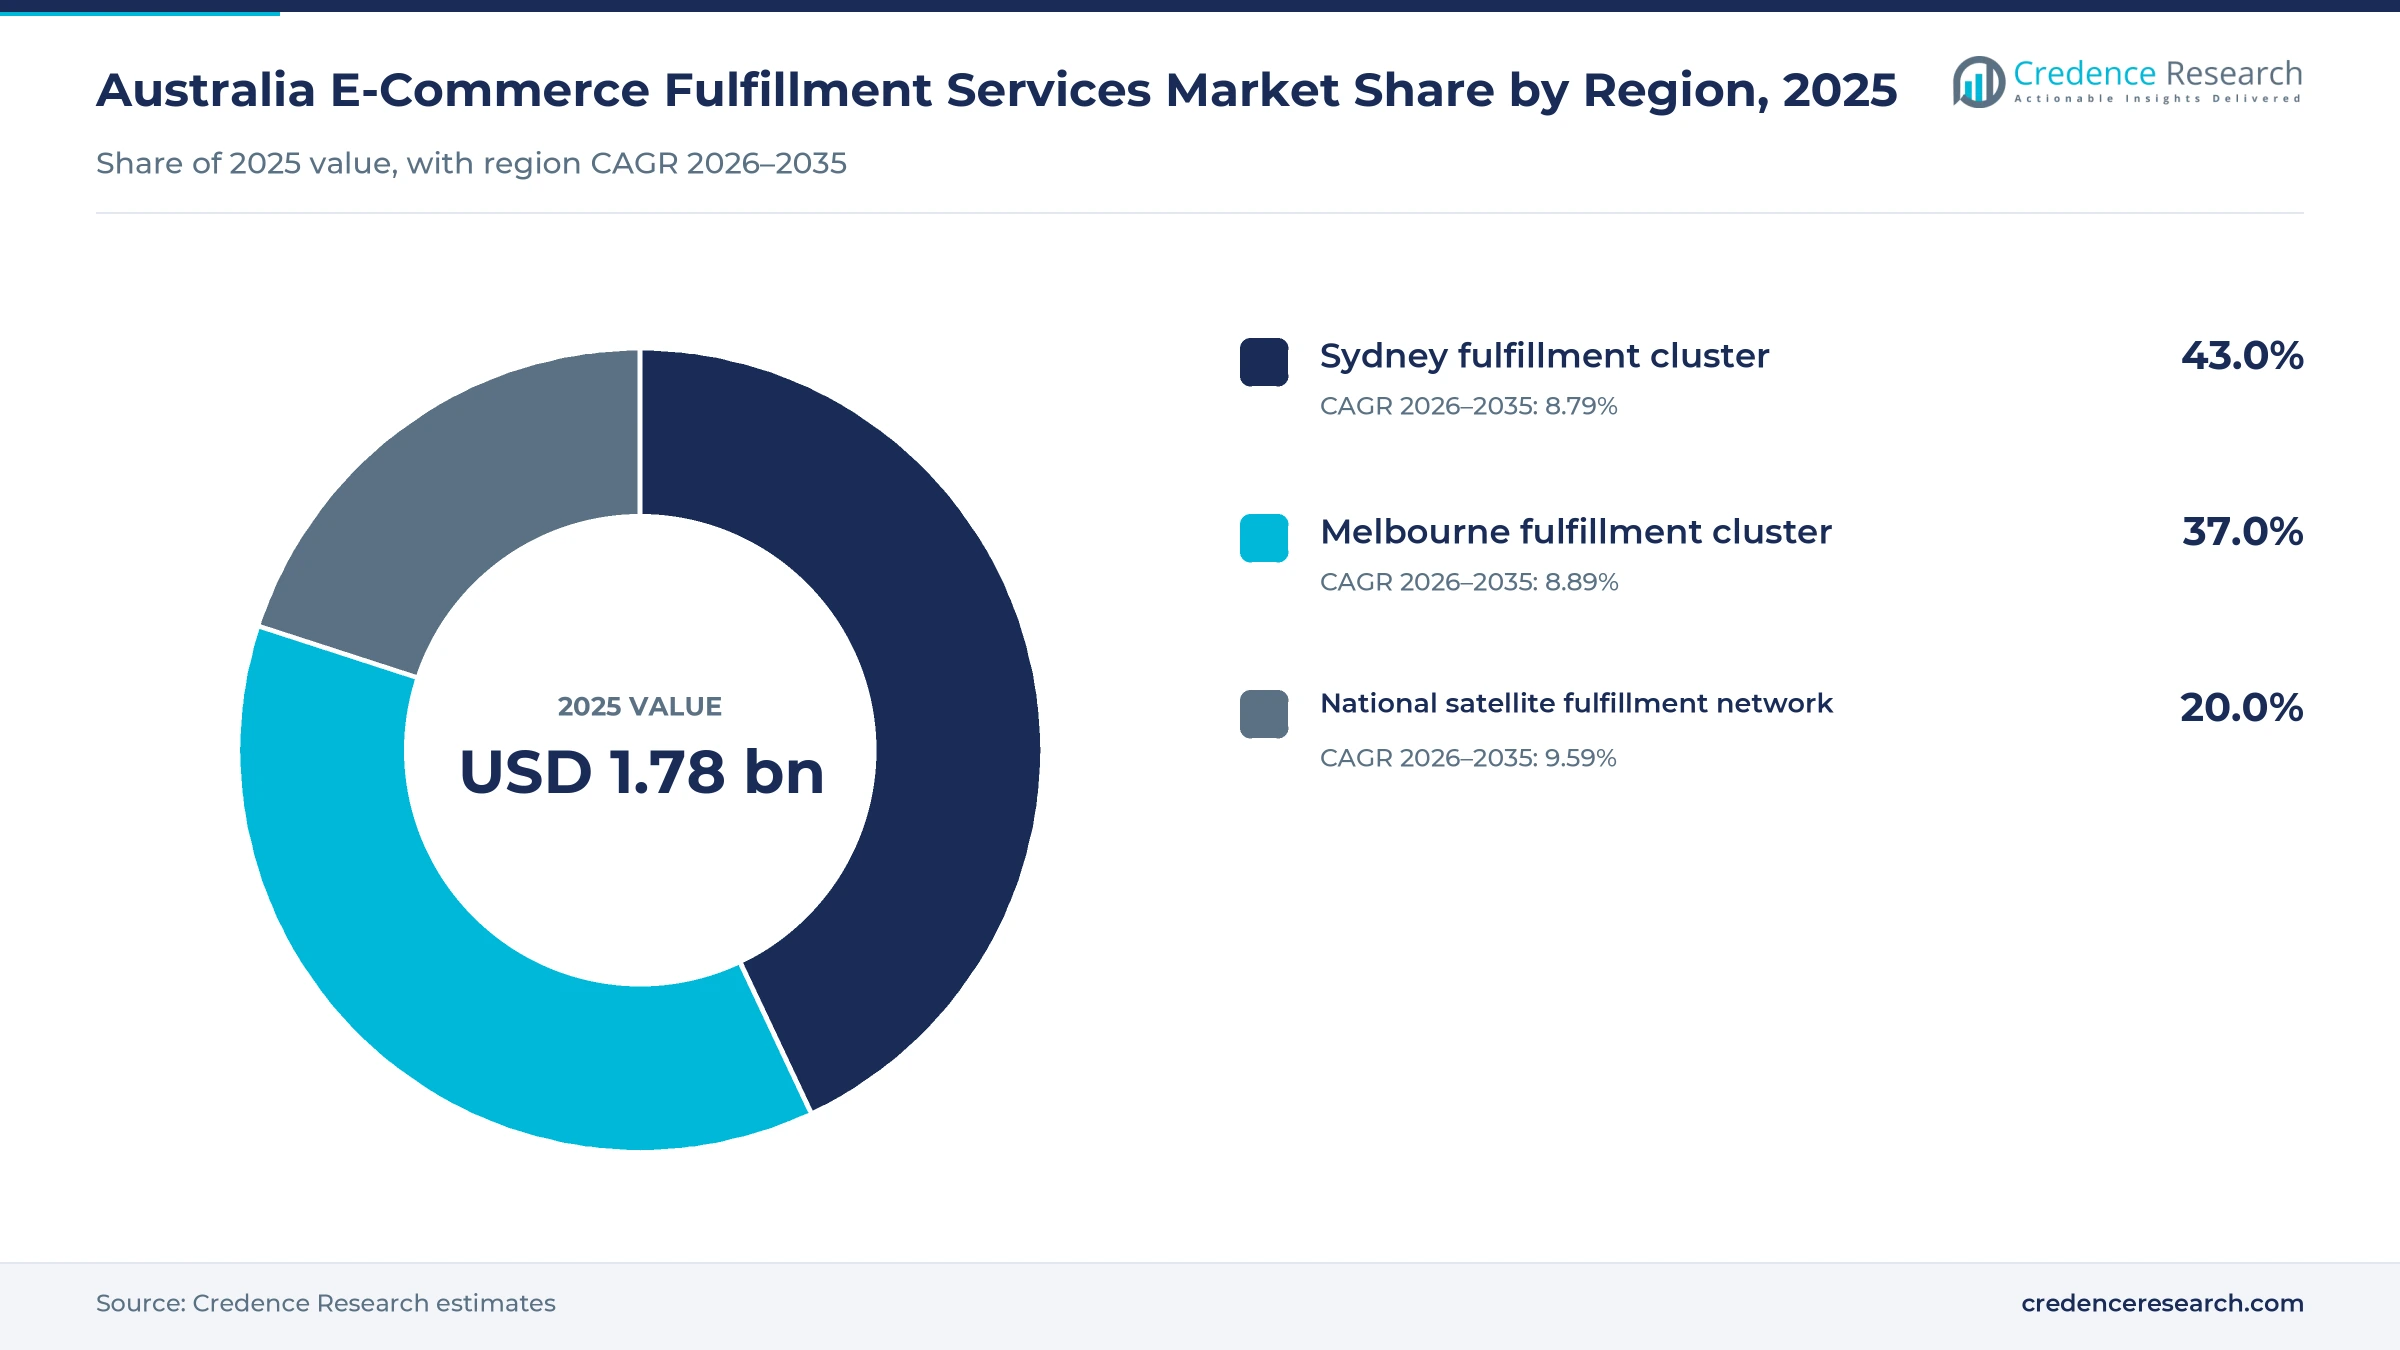
The Australia e-commerce fulfillment services market was valued at USD 1.78 billion in 2025 and is projected to increase from USD 1.94 billion in 2026 to USD 4.22 billion by 2035, registering a CAGR of 8.99% during 2026–2035. Demand comes from online shoppers who buy more often in smaller baskets, and from brands and retailers that hand storage, picking, packing and returns to specialist operators. The Sydney fulfillment cluster held the largest regional share, 43.0% in 2025, because western Sydney hosts the densest network of automated warehouses serving the largest state market. The national satellite fulfillment network is the fastest-growing region at 9.59% a year, as operators add capacity closer to customers in Brisbane, Perth and Adelaide. In turn, Amazon announced a robotics fulfillment site south of Brisbane in March 2026, which shows how automation is moving beyond the two largest cities.
Which outsourced order services does the estimate cover?
The estimate measures the value of third-party fulfillment services bought by online sellers in Australia, including warehousing and inventory management, pick-and-pack work and returns or value-added services. It counts fees paid by digital-native brands, omnichannel retailers and marketplace sellers under activity-based, fixed management and hybrid contracts.
The estimate excludes parcel delivery charges, freight forwarding, the goods themselves and fulfillment that retailers run entirely in-house with their own staff. The value chain runs from property developers and automation vendors through fulfillment operators to sellers, carriers and the households that order online.
Australia E-Commerce Fulfillment Services Market Insights
- The Australia e-commerce fulfillment services market was valued at USD 1.78 billion in 2025 and is projected to reach USD 4.22 billion by 2035, registering a CAGR of 8.99% during 2026–2035.
- The Sydney fulfillment cluster held a 43.0% share of 2025 value, because western Sydney hosts the largest group of automated multi-user warehouses.
- Pick-and-pack fulfillment led with a 44.0% share of 2025 value, because every online order needs picking, packing and labeling before dispatch.
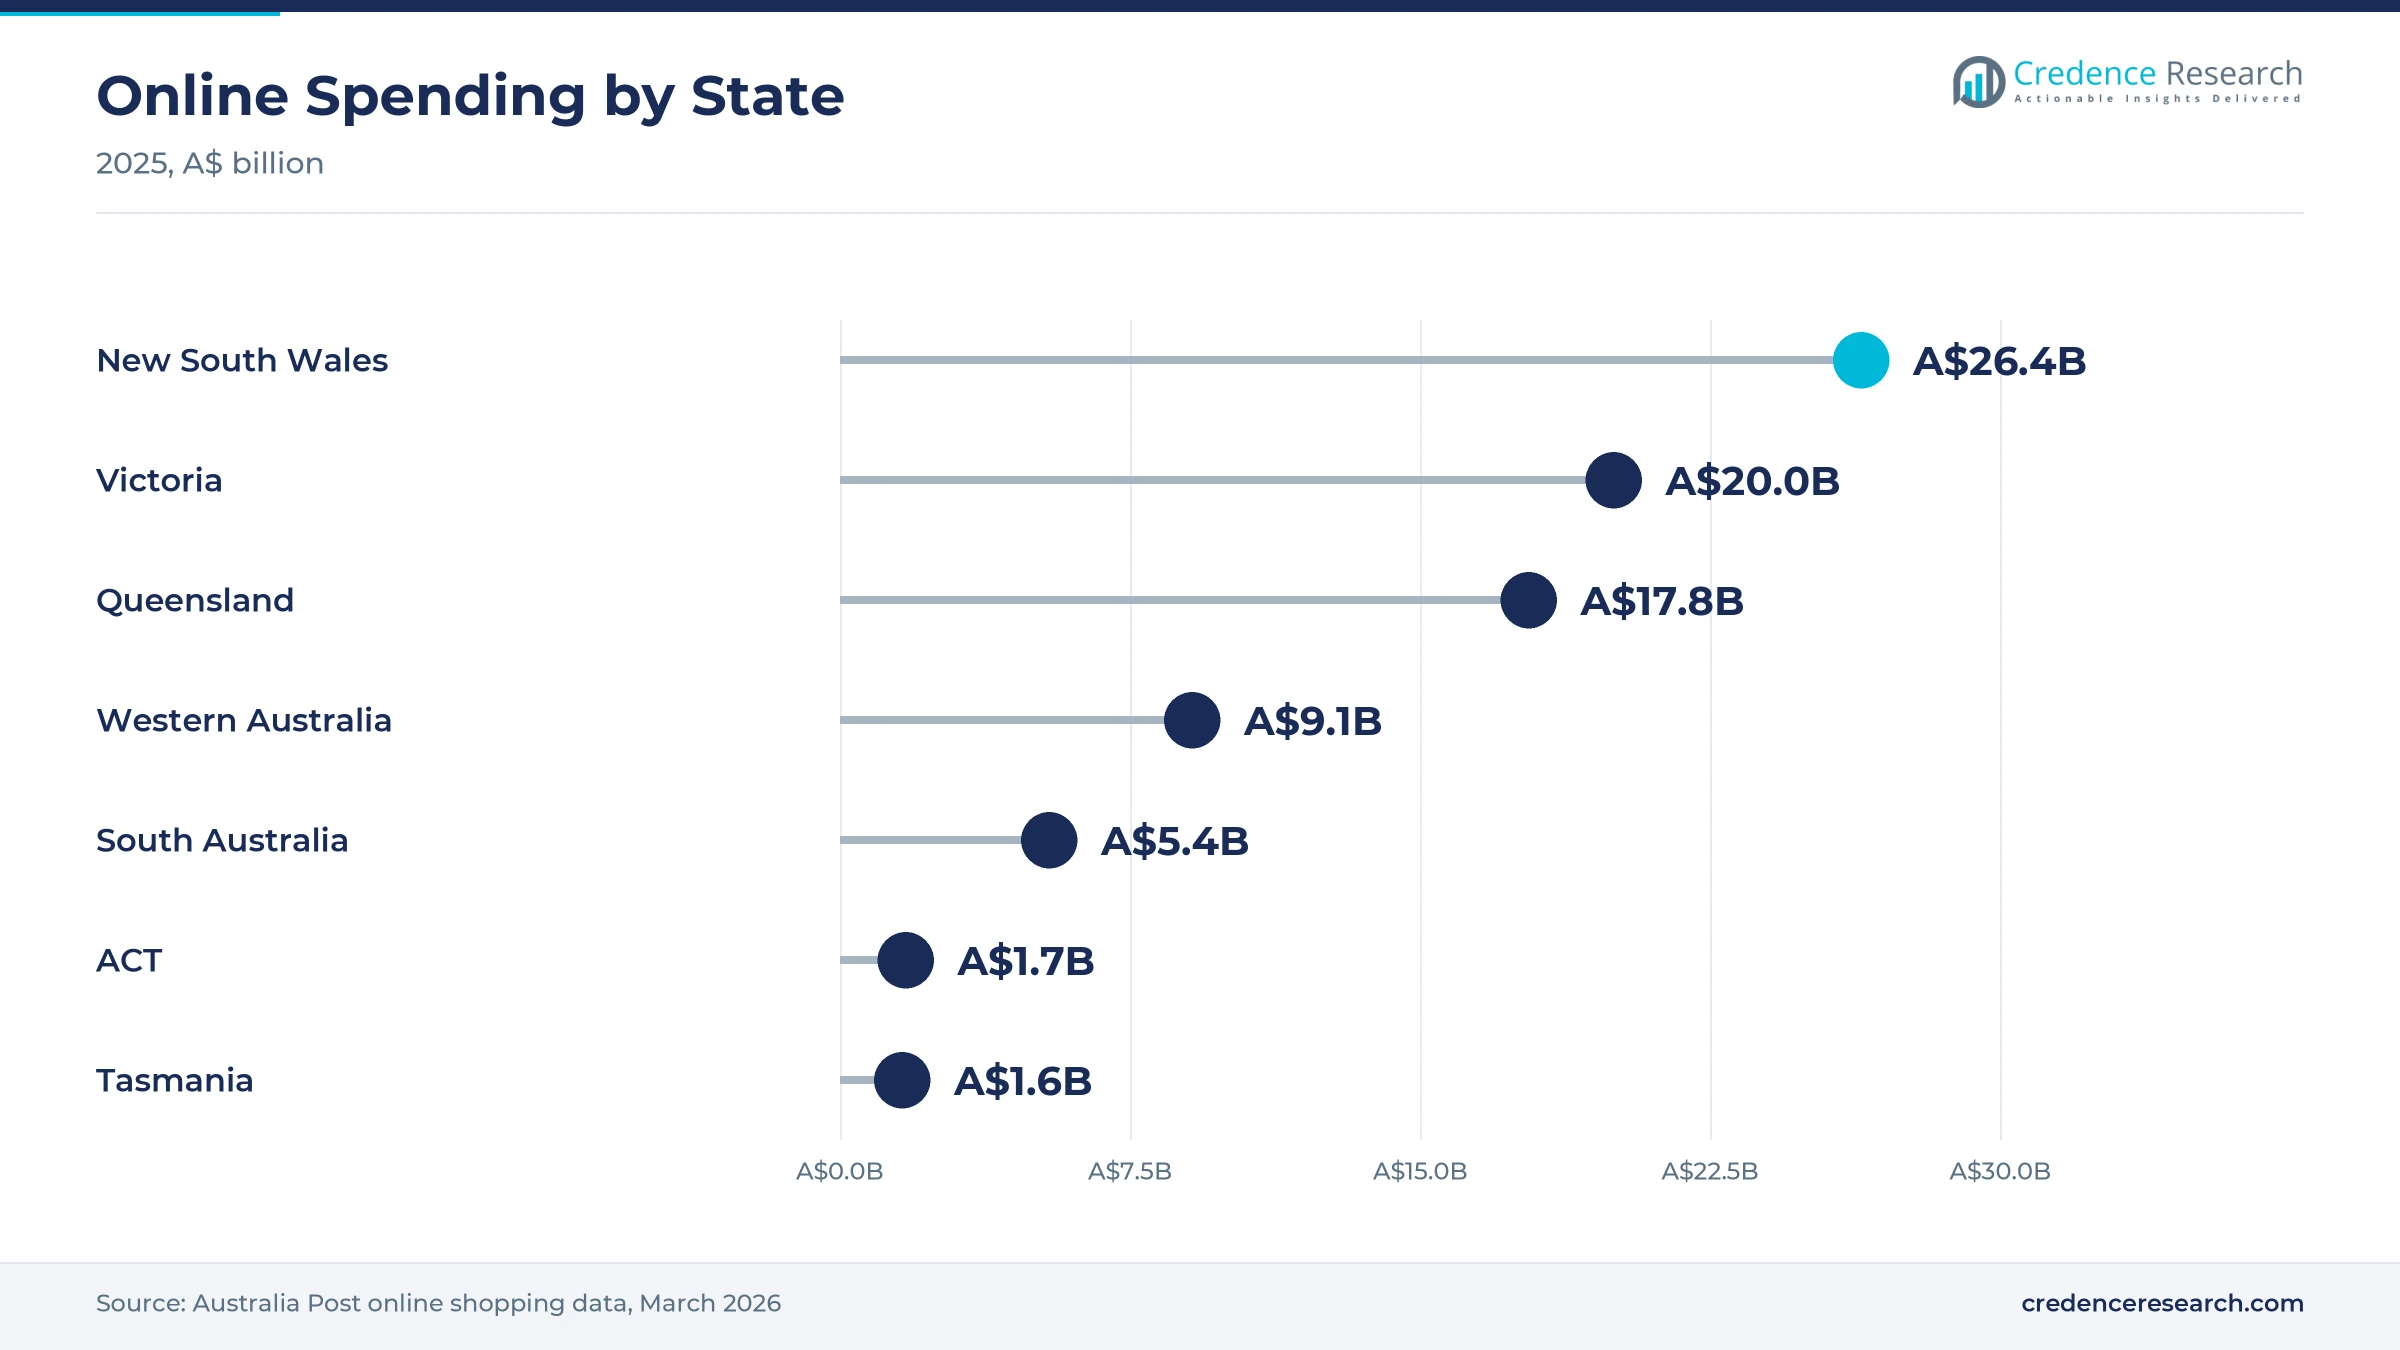
- Australian households spent A$82.6 billion online in 2025, up 13.9% from 2024, according to Australia Post data published in March 2026.
- Marketplace sellers grow fastest at 9.69% a year during 2026–2035, as marketplaces took the largest share of online spending in 2025.
Pick-and-pack leads while returns services grow fastest
Why does pick-and-pack work lead service value?
Based on service type, the market is categorized into warehousing and inventory management, pick-and-pack fulfillment and returns and value-added services. Pick-and-pack fulfillment led with a 44.0% share of 2025 value, because every order needs picking, packing and labeling before it leaves a warehouse. Returns and value-added services grow fastest at 9.87% a year, as fashion and electronics sellers outsource returns, kitting and repacking.
How do retailers, brands and marketplace sellers differ?
Based on customer type, the market is categorized into digital-native brands, omnichannel retailers and marketplace sellers. Omnichannel retailers led with a 40.0% share of 2025 value, because large chains move high volumes through outsourced sites that serve both stores and online orders. Marketplace sellers grow fastest at 9.69% a year, as marketplaces win a larger share of online spending.
Which product categories generate the most orders?
Based on end-use industry, the market is categorized into fashion and accessories, beauty and personal care, ambient groceries and household consumables, and homewares, electronics and leisure goods. Fashion and accessories led with a 31.0% share of 2025 value, because apparel orders are frequent and often returned. Ambient groceries and household consumables grow fastest at 9.73% a year, as households buy staples online more often.
Why do shared multi-client sites dominate?
Based on operating model, the market is categorized into multi-client fulfillment, dedicated outsourced fulfillment and operator-managed retailer facilities. Multi-client fulfillment led with a 46.0% share of 2025 value, because smaller sellers share space, labor and automation costs. Operator-managed retailer facilities grow fastest at 9.56% a year, as large retailers ask logistics groups to run automated sites they help design.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Service Type | Pick-and-pack fulfillment | 44.0% | Returns and value-added services | 9.87% |
| By Customer Type | Omnichannel retailers | 40.0% | Marketplace sellers | 9.69% |
| By End-Use Industry | Fashion and accessories | 31.0% | Ambient groceries and household consumables | 9.73% |
| By Operating Model | Multi-client fulfillment | 46.0% | Operator-managed retailer facilities | 9.56% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Order frequency, automation and shared stock lift demand
How does frequent ordering expand outsourced volume?
Frequency-led order expansion lifts demand, because shoppers now place more and smaller orders that each need picking and packing. Australian households spent A$82.6 billion online in 2025, up 13.9% on the year, and 9.8 million households shopped online, according to Australia Post data. The average basket fell 0.4% to A$96, while shoppers made four more online purchases each than a year earlier. Online marketplaces took the largest share of spending at A$18.9 billion, ahead of fashion and apparel at A$11.6 billion. As a result, pick-and-pack fulfillment holds 44.0% of 2025 value, because higher order counts raise handling fees even when basket values stay flat.
Why does automation push sellers to outsource?
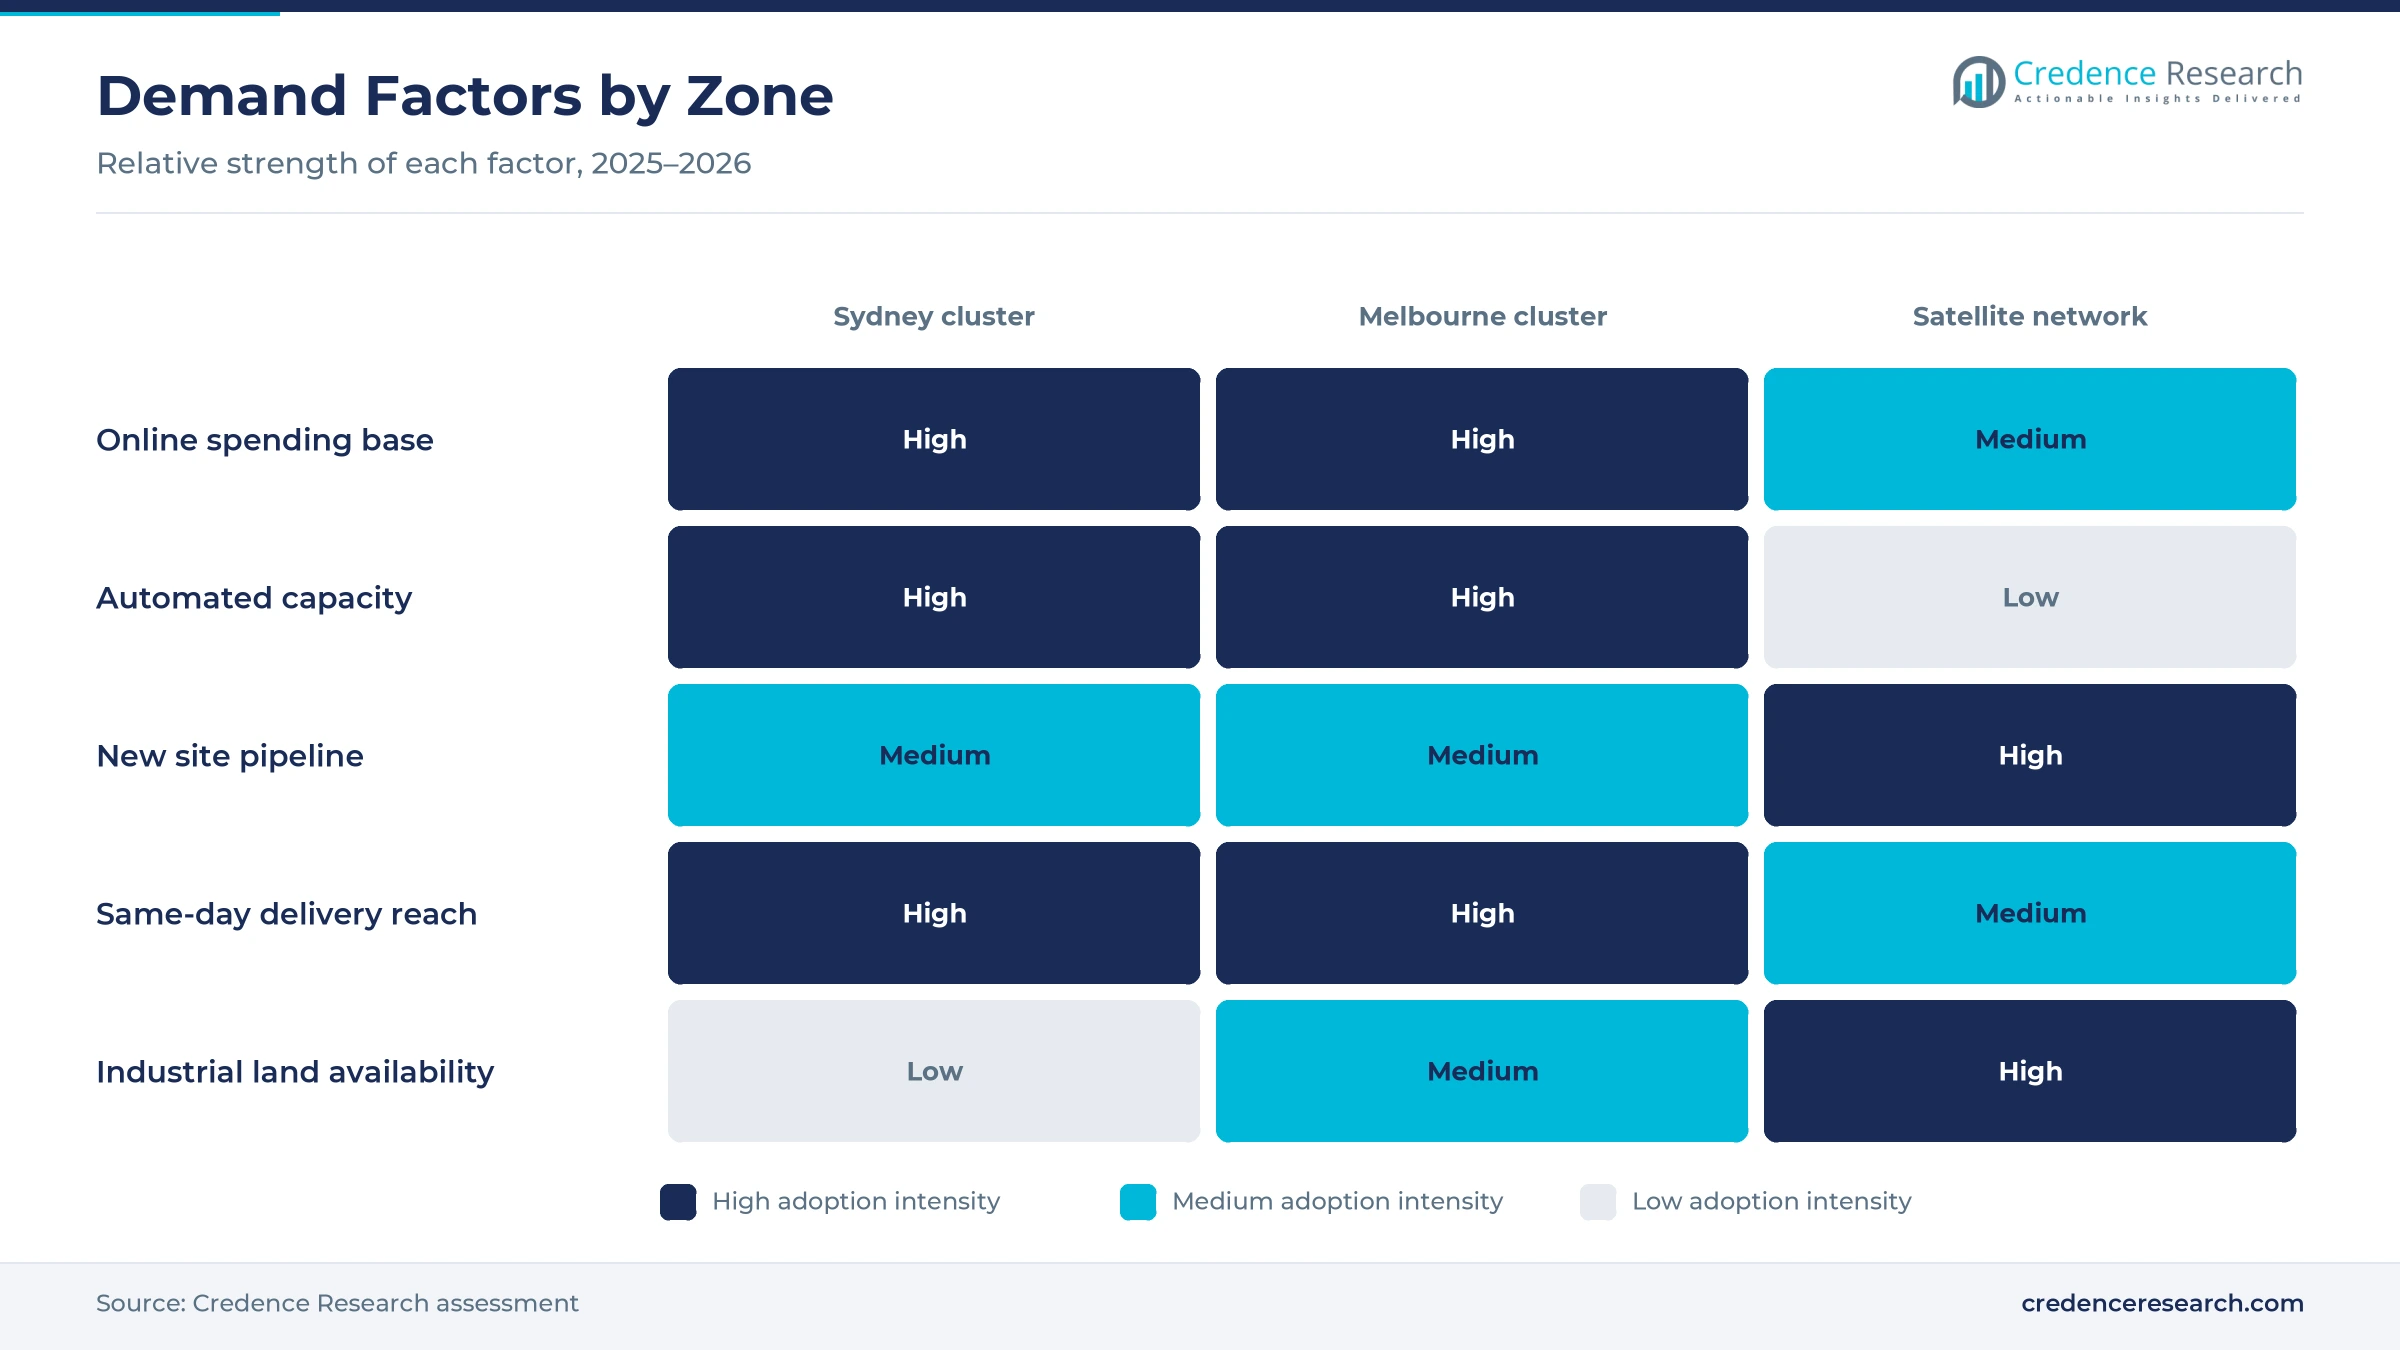
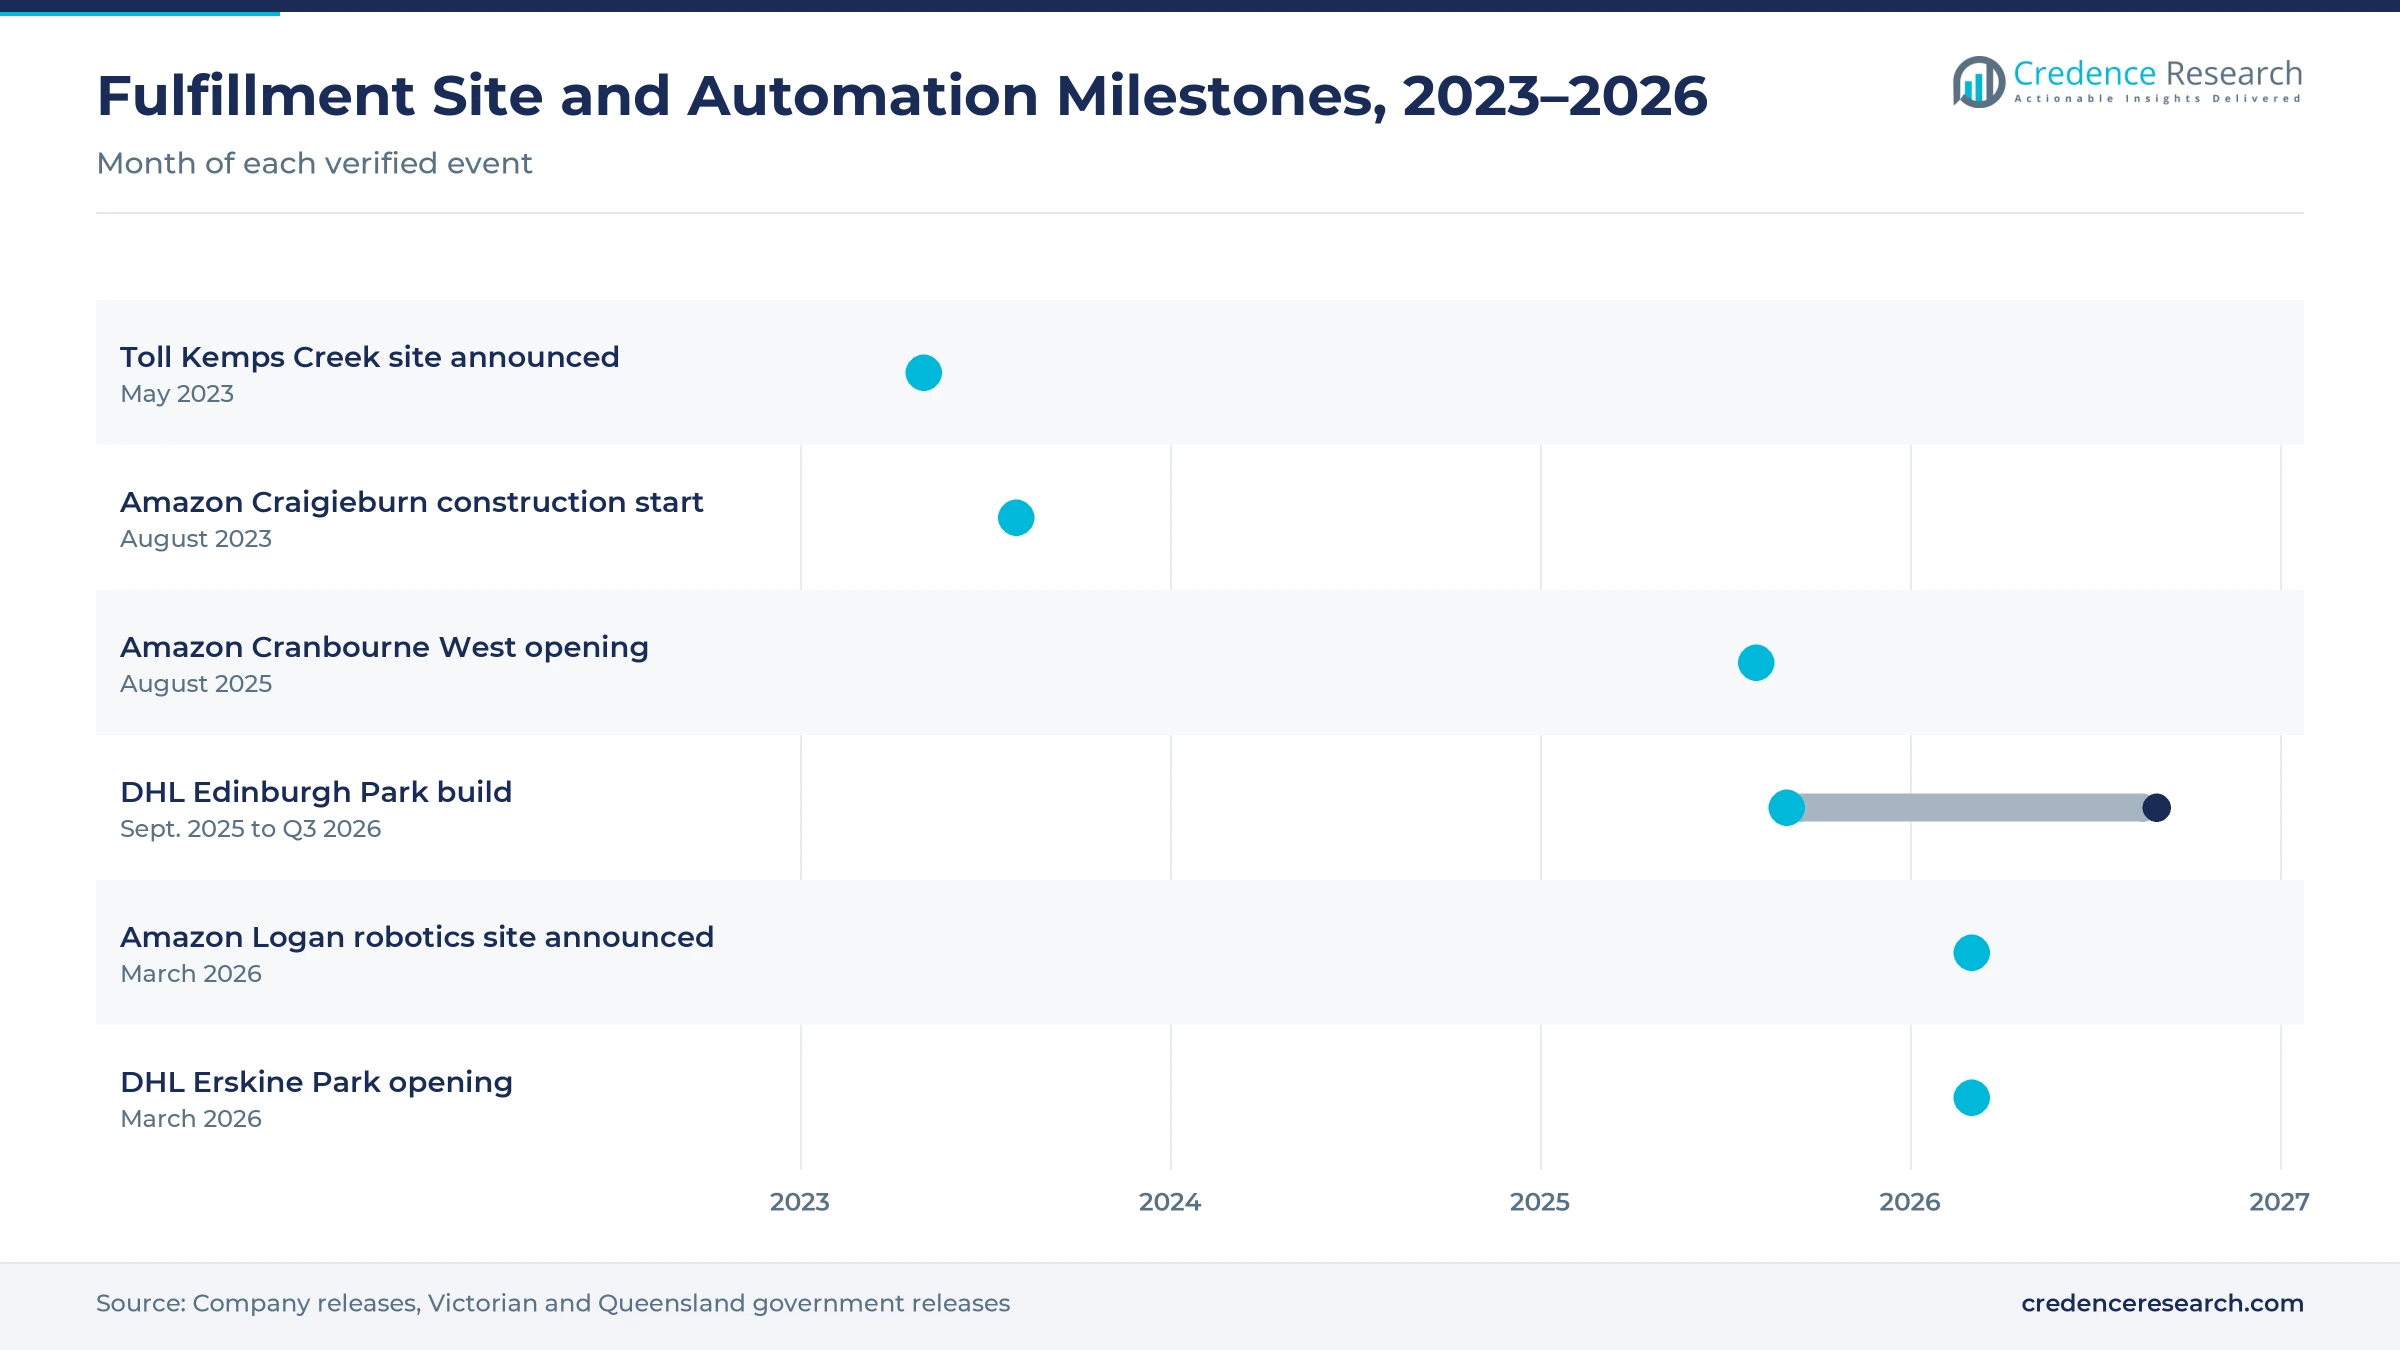
Automation-enabled outsourcing drives demand, because robotic sites cost more than most sellers can fund alone. Toll Group announced the A$200 million Kemps Creek fulfillment site in western Sydney in May 2023, including A$75 million for automation and capacity to dispatch 37 million items a year. DHL Supply Chain committed A$150 million over two years to automation and robotics in its Australian warehouses, with plans for 1,000 assisted picking robots by 2025. Amazon also began building a 209,000-square-meter robotics site at Craigieburn in Melbourne in 2023, with room for up to 25 million smaller items. In turn, sellers buy access to warehouse robots through shared contracts.
How does omnichannel inventory integration add contracts?
Omnichannel inventory integration adds contracts, because retailers want one stock pool that serves stores, websites and marketplaces. Toll Group designed its Kemps Creek site as an automated omni-channel facility that fills both e-commerce orders and store replenishment from a single 67,626-square-meter building. Online retail sales reached A$4,703.8 million in June 2025 in seasonally adjusted terms, according to the Australian Bureau of Statistics. Food online sales were A$1,449.9 million that month, which shows that grocers also run large online stock pools. As a result, omnichannel retailers hold 40.0% of 2025 value, as chains outsource shared inventory rather than run separate warehouses for each channel.
Why does near-universal internet access widen the buyer base?
Near-universal internet access widens the buyer base, because almost every household can now order online from regional and metropolitan addresses alike. Individuals using the internet reached 96.1% of the Australian population in 2024, according to the World Bank. Queensland households spent A$17.8 billion online in 2025, while Western Australia added A$9.1 billion and South Australia A$5.4 billion, according to Australia Post. Those three states together account for a large share of national online demand outside Sydney and Melbourne. In turn, the national satellite fulfillment network grows faster than the two city clusters, as operators move stock closer to buyers to shorten delivery times.
Robotic sites, marketplaces and returns reshape fulfillment
How is the shift to robotic megasites changing capacity?
The shift to robotic megasites is changing capacity, because operators now build multi-level automated buildings instead of adding manual sheds. Amazon announced the A$750 million robotics fulfillment site at North Maclean in Logan on March 13, 2026, according to Trade and Investment Queensland. The 150,000-square-meter site is expected to open in 2028 and create more than 1,000 permanent roles. Amazon also opened its A$200 million fulfillment site at Cranbourne West in Melbourne on Aug. 15, 2025, with storage for up to four million products. As a result, operator-managed retailer facilities grow at 9.56% a year, as large sellers seek warehouse automation without owning the buildings.
Why is the rise of marketplace sellers notable?
The rise of marketplace sellers is notable, because thousands of smaller merchants need storage and packing that a marketplace or third party can provide on demand. Online marketplaces led Australian online spending at A$18.9 billion in 2025, ahead of every other retail category tracked by Australia Post. Department stores also lifted online spending by 19.5% that year, which shows broad-range sellers gaining share. Shoppers bought from an average of 16 brands a year, which spreads orders across many small accounts. In turn, marketplace sellers grow fastest at 9.69% a year, because platform-linked fulfillment lets small merchants offer fast delivery without leasing a warehouse.
Can returns and value-added work open new revenue?
Returns and value-added work can open new revenue, because fashion and electronics sellers need goods inspected, repacked and restocked quickly after customers send them back. Fashion and apparel took A$11.6 billion of online spending in 2025, and home and garden added A$11.4 billion. DHL Supply Chain opened a 21,078-square-meter multi-user site at Erskine Park in western Sydney in March 2026 with a mezzanine for rework and value-added services, according to DHL. The site serves more than five customers, including consumer electronics and white goods brands. As a result, returns and value-added services grow at 9.87% a year, linking fulfillment with reverse logistics programs.
Is there room to grow in regional satellite hubs?
Regional satellite hubs offer room to grow, because buyers outside Sydney and Melbourne still wait longer for many orders. DHL Supply Chain broke ground on a 20,000-square-meter site at Edinburgh Park in South Australia on Sept. 16, 2025, consolidating three facilities, with completion due in the third quarter of 2026. Amazon also developed a Perth fulfillment site at Jandakot Airport in 2023, with room for more than three million items. Western Australia households spent A$9.1 billion online in 2025, according to Australia Post. In turn, operators that stock fast-moving items in Brisbane, Perth and Adelaide can shorten last-mile delivery times and win national accounts.
Land costs, labor and thin margins pressure operators
How do industrial land costs squeeze operators?
Industrial land costs squeeze operators, because the best fulfillment sites sit in western Sydney and outer Melbourne where vacant space is scarce. As a result, rents take a larger share of contract fees, especially for smaller multi-client operators. Operators respond with multi-level buildings, higher racking and automated storage, which fit more stock on each square meter and spread rent across more clients and more orders each day. In turn, operators that secure land early can offer lower storage rates to new clients.
Why do labor shortages limit peak capacity?
Labor shortages limit peak capacity, because online orders surge during sales events and the holiday season when warehouse staff are hardest to hire. In turn, operators pay overtime and agency rates that cut margins on fixed-price contracts. Operators respond with assisted picking robots, better rostering software and longer training programs, which raise output per worker and reduce the number of temporary staff needed in each peak. As a result, well-automated operators can accept more peak volume from large retailers.
How do thin margins affect contract terms?
Thin margins affect contract terms, because many sellers compare fulfillment fees order by order and switch providers when prices rise. As a result, operators carry the risk of volume drops and slow-moving stock under activity-based pricing. Operators respond with hybrid minimum-guarantee contracts, storage fees for aged stock and longer agreements, which give them steadier income to fund automation and new sites. In turn, sellers gain more predictable costs across the full year.
Why does integration complexity slow onboarding?
Integration complexity slows onboarding, because each seller uses different shopping platforms, marketplaces, inventory tools and carriers. In turn, new clients can take weeks to connect before the first order ships, which delays revenue for both sides. Operators respond with ready-made platform connectors, standard data formats and dedicated onboarding teams, which shorten setup and cut errors in stock counts and order routing. As a result, operators with strong connectors win smaller brands that want fast setup.
Sydney leads as satellite hubs in Brisbane and Perth grow
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Sydney fulfillment cluster | 0.77 | 43.0% | 8.79% |
| Melbourne fulfillment cluster | 0.66 | 37.0% | 8.89% |
| National satellite fulfillment network | 0.36 | 20.0% | 9.59% |
Why does the Sydney cluster hold the top share?
The Sydney fulfillment cluster held a 43.0% share of 2025 value and grows at 8.79% a year, because western Sydney hosts automated sites run by Toll Group, DHL Supply Chain and Amazon. New South Wales households spent A$26.4 billion online in 2025, the most of any state. The Australian Capital Territory added A$1.7 billion, much of it served from Sydney warehouses. As a result, the cluster handles the largest share of national orders for large retailers and brands.
How does the Melbourne cluster support national orders?
The Melbourne fulfillment cluster held a 37.0% share of 2025 value and grows at 8.89% a year, because Victorian households spent A$20 billion online in 2025. Amazon opened its A$200 million fulfillment site at Cranbourne West in August 2025 and a logistics site at Ravenhall the same month. Melbourne also serves Tasmania, where households spent A$1.6 billion online. In turn, the cluster acts as a second national hub for many brands.
Why is the satellite network growing fastest?
The national satellite fulfillment network held a 20.0% share of 2025 value and grows fastest at 9.59% a year, because new sites in Brisbane, Perth and Adelaide bring stock closer to buyers. Queensland households spent A$17.8 billion online in 2025, and Amazon plans a robotics site at North Maclean by 2028. As a result, the network wins more orders from sellers that want faster delivery outside the two largest cities.
New fulfillment sites and automation milestones
| Development | Status and market relevance |
|---|---|
| In May 2023, Toll Group announced the A$200 million automated fulfillment site at Kemps Creek in western Sydney, with A$75 million for automation. | Expands shared omnichannel capacity in Sydney |
| In August 2025, Amazon officially opened its A$200 million fulfillment site at Cranbourne West in Melbourne, with storage for up to four million products. | Adds marketplace fulfillment capacity in Victoria |
| In September 2025, DHL Supply Chain broke ground on a 20,000-square-meter site at Edinburgh Park in South Australia, due for completion in 2026. | Strengthens satellite coverage in Adelaide |
| In March 2026, Amazon announced the A$750 million robotics fulfillment site at North Maclean in Logan, expected to open in 2028. | Brings robotic capacity to Queensland |
| In March 2026, DHL Supply Chain opened a 21,078-square-meter multi-user site at Erskine Park with space for rework and value-added services. | Supports returns and value-added work |
Robotics, software and integrations define fulfillment
- Goods-to-person robotics bring shelves or totes to pickers, which cuts walking time and lets one worker fill far more orders each hour.
- Assisted picking robots guide staff around the floor and carry finished orders, which lifts output during peak sales events without large hiring rounds.
- Warehouse management software tracks every item, bin and order across sites, which lets operators run shared stock for stores and online channels.
- Platform connectors link shopping sites and marketplaces to the warehouse, which shortens onboarding for new sellers and keeps stock counts accurate.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Logistics groups and specialists compete on speed and scale
Competition is led by large logistics groups that run automated multi-user sites, alongside marketplace fulfillment and specialist operators that serve smaller online brands. Toll Group competes with large omnichannel facilities such as its A$200 million Kemps Creek site in western Sydney. DHL Supply Chain competes on automation, with its A$150 million robotics program and new sites at Erskine Park and Edinburgh Park. Amazon competes through its own fulfillment network, which serves marketplace sellers from sites in Sydney, Melbourne and Perth and a planned robotics site in Queensland. eStore Logistics, backed by Kogan.com founder Ruslan Kogan, competes with robot-assisted sites for online retailers. Rivals compete on order cutoff times, pick accuracy, platform connections, returns handling and contract flexibility. Because sellers compare fees per order, operators that spread automation costs across many clients usually win.
Which operators handle Australian online orders?
| Company | Type | Role in the market |
|---|---|---|
| Toll Group | Logistics group | Runs the A$200 million automated omnichannel site at Kemps Creek |
| DHL Supply Chain Australia | Contract logistics provider | Runs multi-user sites in Sydney and is building in Adelaide |
| Amazon FBA Australia | Marketplace fulfillment network | Operates fulfillment sites in Sydney, Melbourne and Perth |
| eStore Logistics | Specialist fulfillment operator | Runs robot-assisted fulfillment for online retailers |
Credence Research view on outsourced order handling
Credence Research's view is that Australian fulfillment services will keep growing faster than online sales because sellers outsource more work as order counts rise and automation costs climb. Pick-and-pack work remains the largest value pool, while returns services and marketplace sellers add the fastest growth. New robotic sites in Melbourne and Queensland will raise capacity and lower handling costs. Operators with shared automation, strong platform connections and sites outside Sydney should gain the most, while land costs and thin margins keep pressure on smaller operators.
How the national fulfillment estimate was built
The report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. That model combines online retail statistics, state online spending data, announced warehouse investments and company releases. Segment splits, zone shares and zone growth rates are Credence Research estimates. Sources used are official statistics, government agency releases, postal operator data published in trade media and company releases, and no interviews or surveys were used.
Automated hubs and marketplace volume carry growth to 2035
The Australia e-commerce fulfillment services market is expected to reach USD 4.22 billion by 2035, an 8.99% CAGR during 2026–2035, as shoppers order more often and sellers hand more warehouse work to specialists. Growth should be strongest in returns services, marketplace sellers and satellite hubs, because these areas gain most from automation and faster regional delivery. New robotic sites in Melbourne and Queensland will add capacity, while land costs, labor shortages and thin margins could slow smaller operators.
Frequently Asked Questions
How big is the Australia e-commerce fulfillment services market?
Which service type leads Australian fulfillment value?
Which region leads the Australian market?
How much did Australians spend online in 2025?
Which customer type is growing fastest?
What new fulfillment sites were announced recently?
Who are the leading companies in the Australian market?
What are the main challenges for fulfillment operators?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Service Type
- 1.2.1 Warehousing and inventory management
- 1.2.2 Pick-and-pack fulfillment
- 1.2.3 Returns and value-added services
- 1.3 By Customer Type
- 1.3.1 Digital-native brands
- 1.3.2 Omnichannel retailers
- 1.3.3 Marketplace sellers
- 1.4 By End-Use Industry
- 1.4.1 Fashion and accessories
- 1.4.2 Beauty and personal care
- 1.4.3 Ambient groceries and household consumables
- 1.4.4 Homewares, electronics and leisure goods
- 1.5 By Operating Model
- 1.5.1 Multi-client fulfillment
- 1.5.2 Dedicated outsourced fulfillment
- 1.5.3 Operator-managed retailer facilities
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 1.78 billion → 2035: USD 4.22 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia E-Commerce Fulfillment Services Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia E-Commerce Fulfillment Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Australia E-Commerce Fulfillment Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Australia E-Commerce Fulfillment Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia E-Commerce Fulfillment Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia E-Commerce Fulfillment Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia E-Commerce Fulfillment Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia E-Commerce Fulfillment Services Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 1.78 billion → 2035: USD 4.22 billion)
- 11.1.2 Historical Market Size, 2018-2025
- 11.1.3 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia E-Commerce Fulfillment Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Service Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Base-Year Market Share, 2025
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Warehousing and inventory management
- 12.3.6.2 Pick-and-pack fulfillment
- 12.3.6.3 Returns and value-added services
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Customer Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Base-Year Market Share, 2025
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Digital-native brands
- 12.4.6.2 Omnichannel retailers
- 12.4.6.3 Marketplace sellers
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By End-Use Industry - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Base-Year Market Share, 2025
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Fashion and accessories
- 12.5.6.2 Beauty and personal care
- 12.5.6.3 Ambient groceries and household consumables
- 12.5.6.4 Homewares, electronics and leisure goods
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Operating Model - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Base-Year Market Share, 2025
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Multi-client fulfillment
- 12.6.6.2 Dedicated outsourced fulfillment
- 12.6.6.3 Operator-managed retailer facilities
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Australia E-Commerce Fulfillment Services End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia E-Commerce Fulfillment Services Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia E-Commerce Fulfillment Services Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2025-2035
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia E-Commerce Fulfillment Services Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 DHL Supply Chain Australia
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Amazon FBA Australia
- 18.4 Toll Group
- 18.5 Linfox
- 18.6 eStore Logistics
- 18.7 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

