
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Peer to Peer Lending Market Size 2024 | USD 517197.6 million |
| Peer to Peer Lending Market, CAGR | 12.46% |
| Peer to Peer Lending Market Size 2032 | USD 1323247.65 million |
Market Overview:
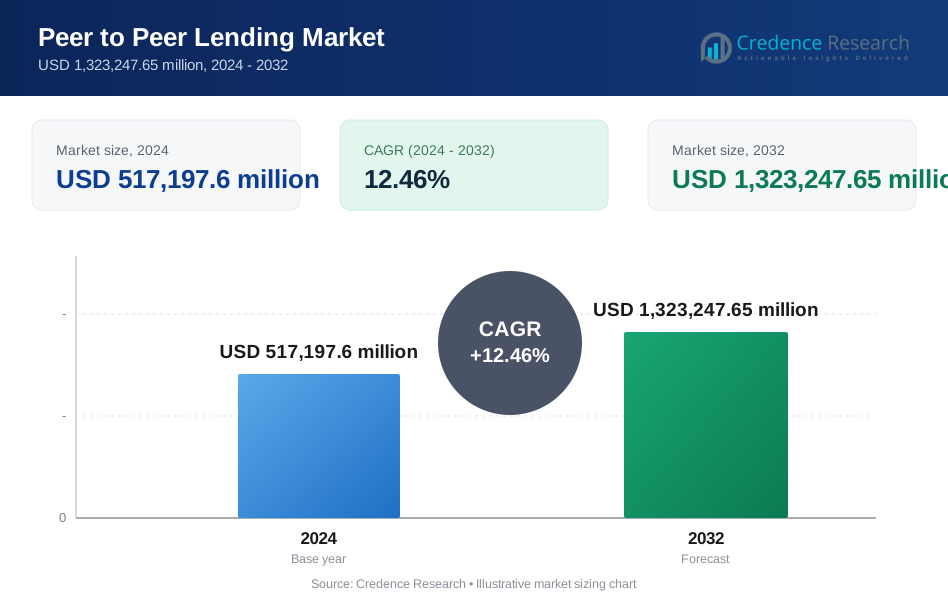
The Peer to Peer Lending market is projected to grow from USD 517197.6 million in 2024 to an estimated USD 1323247.65 million by 2032, with a compound annual growth rate (CAGR) of 12.46% from 2024 to 2032.
Several factors are propelling the growth of the P2P lending market. Firstly, the growing dissatisfaction with traditional banking services has led borrowers to explore alternative financing options, driving demand for P2P lending platforms. These platforms offer quicker, more flexible, and often more affordable loan options compared to traditional financial institutions. Additionally, advancements in technology, including AI and blockchain, have enhanced the efficiency, security, and transparency of P2P lending processes, attracting both lenders and borrowers. The increasing financial inclusion initiatives globally have also expanded the customer base for P2P lending services. Furthermore, the rise in entrepreneurial activities and small businesses seeking capital outside conventional banking channels fuels market growth.
The P2P lending market exhibits varied growth patterns across different regions. North America, particularly the United States, holds a significant share of the market due to a well-established financial ecosystem, high adoption rates of digital technologies, and a robust regulatory framework supporting P2P lending activities. Europe follows, with countries like the United Kingdom and Germany showing substantial market presence owing to favorable regulatory conditions and a growing acceptance of alternative lending. In the Asia-Pacific region, rapid economic growth, increasing digital literacy, and a burgeoning middle class are driving the market expansion. Emerging markets in this region present significant opportunities for P2P lending platforms due to a large, underserved population seeking accessible financial services. The Latin American and Middle Eastern regions are also witnessing increasing interest, although they are in earlier stages of market development compared to the other regions.
Market Drivers:
Growing Discontent with Traditional Banking:
A significant driver of the Peer-to-Peer (P2P) lending market is the increasing discontent among borrowers with traditional banking institutions. Many individuals and small businesses find conventional banks to be cumbersome and slow in processing loans, with stringent requirements and less flexibility. This dissatisfaction pushes borrowers towards alternative financing options offered by P2P lending platforms. These platforms streamline the borrowing process by reducing paperwork, expediting approvals, and offering more competitive interest rates. By addressing the inefficiencies and limitations of traditional banking, P2P lending provides a more appealing alternative, capturing the interest of both borrowers and investors seeking a more dynamic financial ecosystem.
Financial Inclusion and Market Expansion:
Financial inclusion is a key driver behind the growth of the P2P lending market. As traditional financial institutions often overlook underserved or unbanked populations, P2P lending platforms step in to fill this gap by providing access to credit for individuals and small businesses that might otherwise be excluded from traditional financial systems. This inclusivity is particularly prominent in emerging markets, where a significant portion of the population lacks access to conventional banking services. For instance, the National Financial Inclusion Survey 2022 conducted by the Maldives Monetary Authority revealed that 63% of respondents believe financial products should be provided by the government and financial institutions as partially subsidized financial services, emphasizing the need for more inclusive financial options. By offering financial products tailored to the needs of these underserved groups, P2P lending platforms are expanding their market reach and contributing to broader financial inclusion goals.
Increasing Entrepreneurial Activity and Small Business Financing:
The rise in entrepreneurial activity and the need for alternative financing options for small businesses are also driving the P2P lending market. Entrepreneurs and small business owners often face challenges in securing funding from traditional banks due to stringent credit requirements and lengthy approval processes. P2P lending platforms offer a viable solution by connecting borrowers directly with investors, facilitating quicker access to capital with fewer barriers. This is particularly beneficial for startups and small enterprises that require flexible funding solutions to support their growth and development. As entrepreneurial activity continues to rise globally, the demand for P2P lending services is expected to grow, further fueling market expansion. For instance, The Global Entrepreneurship Monitor (GEM) 2021/2022 Global Report revealed that 17.9% of working-age adults in the United States were either nascent entrepreneurs or owner-managers of new businesses, indicating a robust entrepreneurial ecosystem that could benefit from alternative financing options like P2P lending.
Technological Advancements and Innovation:
Technological advancements are significantly enhancing the P2P lending market. The integration of artificial intelligence (AI) and machine learning algorithms has improved credit risk assessment, enabling platforms to evaluate borrowers' creditworthiness more accurately and efficiently. This not only enhances the overall user experience but also reduces default rates, making P2P lending more attractive to investors. Additionally, the use of blockchain technology in P2P lending platforms enhances transaction transparency and security, addressing common concerns about fraud and data breaches. These technological innovations make P2P lending platforms more reliable and accessible, fostering increased adoption among both lenders and borrowers.
Market Trends:
Regulatory Developments and Compliance:
Regulatory developments are shaping the future of the P2P lending market, with evolving regulations aiming to ensure greater transparency, protect consumers, and mitigate risks. As the market grows, regulators are increasingly focusing on establishing comprehensive frameworks that govern P2P lending activities. These regulations address issues such as borrower protection, disclosure requirements, and platform accountability. While regulatory compliance may present challenges for P2P platforms, it also fosters greater trust and legitimacy within the market. For instance, the Financial Conduct Authority (FCA) in the UK has expressed concerns about the increasing complexity of P2P lenders and the need for relatively lighter regulation. This highlights the ongoing efforts by regulators to balance innovation with consumer protection. Adherence to regulatory standards is becoming a crucial factor for platform operators, influencing market dynamics and driving the need for more robust compliance measures.
Growth of Specialized Lending Platforms:
Another significant trend is the emergence of specialized P2P lending platforms that cater to niche markets and specific borrower needs. These platforms focus on particular types of loans, such as student loans, business loans, or real estate loans, providing tailored solutions that address the unique requirements of these segments. By offering specialized products, these platforms can attract a targeted user base and differentiate themselves from more generalized P2P lending services. This trend reflects the evolving landscape of P2P lending, where customization and specialization are becoming key competitive advantages.
Integration of Advanced Data Analytics:
“The integration of advanced data analytics is transforming the P2P lending market. Platforms are increasingly utilizing big data and sophisticated analytical tools to enhance their credit assessment processes, predict borrower behavior, and manage risk more effectively. For instance, P2P lending platforms analyze creditworthiness, establish interest rates, and manage the loan process using technology, data analytics, and algorithms. By leveraging data analytics, P2P lending platforms can offer more accurate credit scoring, improve loan underwriting procedures, and tailor investment opportunities to match investor preferences. This trend not only enhances the efficiency and reliability of P2P lending operations but also supports better decision-making for both lenders and borrowers, contributing to overall market growth. In fact, P2P lending platforms employ various credit assessment methods, including credit scores, income verification, employment history, and debt-to-income ratios. Some platforms may also use alternative data sources and machine learning algorithms to evaluate borrower risk. This increased loan availability benefits underprivileged or underrepresented communities, boosting financial inclusion.”
Rise of Institutional Investors:
One of the prominent trends in the Peer-to-Peer (P2P) lending market is the increasing involvement of institutional investors. Traditionally dominated by individual investors, the P2P lending space is witnessing a shift as large financial institutions, hedge funds, and private equity firms enter the market. These institutional investors are attracted by the potential for high returns and the diversification benefits that P2P lending offers. Their participation not only boosts the credibility and stability of P2P platforms but also increases the available capital for borrowers. This trend underscores the growing acceptance of P2P lending as a legitimate investment avenue and signals a maturation of the market.
Market Restraints and Challenges:
Regulatory Uncertainty:
One of the primary restraints in the Peer-to-Peer (P2P) lending market is regulatory uncertainty. As the market evolves rapidly, regulatory frameworks often lag behind technological advancements and market practices. Inconsistent regulations across different regions create a complex landscape for P2P platforms to navigate, potentially leading to compliance challenges and legal risks. The lack of a uniform global regulatory standard can hinder cross-border operations and impact investor confidence. Regulatory bodies are continually updating and introducing new rules, which can add operational costs and uncertainty for P2P lending platforms.
Credit Risk and Default Rates:
Credit risk remains a significant challenge in the P2P lending market. Although advanced data analytics improve credit assessments, the inherent risk of borrower default persists. The success of P2P lending largely depends on the accuracy of credit scoring models and the platform’s ability to manage and mitigate risk. High default rates can erode investor returns and undermine platform credibility. Effective risk management strategies, including diversified loan portfolios and robust borrower vetting processes, are essential to address these concerns and maintain market stability.
Market Competition:
Intense competition within the P2P lending market poses a restraint on growth and profitability. With numerous platforms entering the market, the competition for both borrowers and investors is fierce. Platforms must differentiate themselves through unique value propositions, such as lower fees, better interest rates, or specialized loan offerings. This competitive pressure can lead to reduced margins and increased marketing expenditures. Additionally, the proliferation of new entrants and technological innovations requires existing platforms to continuously adapt and invest in their services to remain competitive.
Data Security and Privacy Concerns:
Data security and privacy concerns are critical challenges for P2P lending platforms. As these platforms handle sensitive financial information, they are attractive targets for cyberattacks. Ensuring the security of user data and protecting against data breaches is paramount for maintaining trust and compliance with data protection regulations. Platforms must invest significantly in cybersecurity measures and data protection technologies to safeguard against potential threats and uphold user confidence. Failure to address these concerns can result in reputational damage and legal repercussions.
Market Segmentation Analysis:
By Type
The Peer-to-Peer (P2P) lending market can be segmented by type into consumer lending, business lending, and real estate lending. Consumer lending is the largest segment, encompassing personal loans for purposes such as debt consolidation, home improvement, and emergency expenses. Business lending, which includes small business loans and startup financing, is growing rapidly as entrepreneurs seek alternative funding sources outside traditional banks. Real estate lending focuses on property financing, including residential and commercial real estate investments. Each type caters to distinct borrower needs and presents unique opportunities and risks for investors.
By Business Model
P2P lending platforms operate under various business models, including marketplace lending, direct lending, and hybrid models. Marketplace lending platforms connect borrowers directly with individual or institutional investors, earning revenue through origination fees and service charges. Direct lending platforms, on the other hand, lend their own capital to borrowers and manage the loan servicing process, often earning interest income and fees. Hybrid models combine elements of both approaches, allowing platforms to blend their own capital with external investments. Each model impacts the platform’s revenue structure, risk management, and operational dynamics.
By End User
The end-user segment includes individual investors, institutional investors, and borrowers. Individual investors participate in P2P lending to achieve higher returns compared to traditional investment options, while institutional investors seek to diversify their portfolios and access large-scale investment opportunities. Borrowers, including both individuals and businesses, use P2P lending to secure funding that may not be available through traditional financial channels. This segmentation highlights the diverse motivations and requirements of market participants, influencing platform strategies and service offerings.
Segmentation:
By Type
- Consumer lending,
- Business lending,
- Real estate lending.
By Business Model
- Marketplace lending,
- Direct lending,
- Hybrid models.
By End User
- Individual investors,
- Institutional investors,
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a significant share of the global Peer-to-Peer (P2P) lending market, accounting for approximately 40% of the market. The United States is the largest contributor, driven by a well-established financial ecosystem, high adoption rates of digital technologies, and a favorable regulatory environment. The presence of major P2P lending platforms like LendingClub and Prosper has cemented the region's leading position. The market's growth is further supported by a robust investor base, including both individual and institutional investors, and a high demand for alternative financing solutions among consumers and small businesses.
Europe
Europe represents a substantial portion of the P2P lending market, with a share of around 30%. The United Kingdom and Germany are the primary contributors within the region, benefiting from favorable regulatory conditions and a growing acceptance of alternative lending solutions. The UK, in particular, has a mature P2P lending sector with prominent platforms such as Funding Circle and Ratesetter. European countries are increasingly adopting P2P lending as a viable financing option, driven by financial innovation and a shift towards digital financial services. However, regulatory diversity across European countries presents challenges for cross-border operations.
Asia-Pacific
The Asia-Pacific region is experiencing rapid growth in the P2P lending market, capturing approximately 25% of the global market share. China is the leading player in this region, with a massive and expanding market driven by a large population, increasing digital adoption, and a rising middle class. Platforms like Dianrong and Lufax are prominent in China, reflecting the country's significant market potential. Additionally, countries such as India and Australia are witnessing growing interest in P2P lending due to emerging financial inclusion initiatives and increasing entrepreneurial activities. However, regulatory frameworks vary widely, impacting market dynamics.
Rest of the World
The Rest of the World, including regions such as Latin America and the Middle East, holds a smaller share of the P2P lending market, around 5%. These markets are in the early stages of development, with increasing interest from both investors and borrowers. Latin America is gradually embracing P2P lending as a solution to financial exclusion, while the Middle East is exploring the potential of digital financial services. Despite the smaller market share, these regions present opportunities for growth as financial infrastructure develops and digital adoption increases.
Key Player Analysis:
- Prosper Marketplace, Inc.
- LendingClub Corporation
- CommonBond Inc.
- Funding Circle Limited
- Upstart Network Inc.
- OnDeck (US)
- Prosper Funding LLC. (US)
- Funding Circle (UK)
- LendingClub Bank (US)
- RateSetter (UK)
- Avant, LLC. (US)
- Social Finance (US)
- Zopa Bank Limited (UK)
- auxmoney GmbH (Germany)
- Funding Societies (Singapore)
- Mintos (Latvia)
- Upstart (US)
- SoFi (US)
- FundingSecure (UK)
- Faircent (India)
- Lufax (China)
- Bondora (Estonia)
- Bitbond (Germany)
- CircleUp (US)
Competitive Analysis:
The Peer to Peer (P2P) lending market is highly competitive, characterized by a mix of established platforms and new entrants. Key players like LendingClub, Prosper, and Funding Circle dominate due to their large user bases, extensive lending portfolios, and strong brand recognition. These companies benefit from economies of scale, advanced risk assessment algorithms, and robust regulatory compliance frameworks. Emerging platforms, particularly in Asia-Pacific, are gaining traction by offering competitive interest rates, specialized lending products, and localized services. Competition is further intensified by traditional financial institutions entering the P2P space, leveraging their existing customer relationships and financial expertise. To differentiate themselves, P2P platforms are focusing on technological innovation, including AI-driven credit scoring, blockchain for secure transactions, and user-friendly mobile interfaces. The market's competitive landscape is dynamic, with continuous innovation and strategic partnerships driving growth and enhancing customer experience.
Recent Developments:
- In January 2024, social media giant X, formerly known as Twitter, announced plans to introduce peer-to-peer payments later in the year. This move is expected to enhance user engagement and open new avenues for commerce, exemplifying the value of integrating multiple functionalities into a single platform.
- In December 2023, EaseMyDeal collaborated with LendBox to launch P2P investment opportunities on its app, offering returns of 10% per annum. This partnership aims to provide users with attractive investment options and expand the platform's financial services.
- In November 2023, Zopa, a prominent UK-based P2P lending platform, secured regulatory approval to establish a digital bank. This development allows Zopa to broaden its services beyond lending, including savings accounts, credit cards, and financial management tools, leveraging its established expertise in the P2P lending sector.
- In May 2022, LendingClub, a leading US-based P2P lending platform, finalized the acquisition of Radius Bank. This strategic acquisition marked a pivotal expansion into digital banking, enabling LendingClub to diversify its offerings and provide a comprehensive range of financial services to its customers.
Market Concentration & Characteristics:
The Peer-to-Peer (P2P) lending market exhibits moderate concentration, with several key players dominating the landscape while numerous smaller platforms contribute to its diversity. Major platforms such as LendingClub, Prosper, and Funding Circle hold significant market share, leveraging established networks and advanced technology to attract both borrowers and investors. However, the market remains dynamic, with new entrants continuously emerging and innovating. Characteristics of the market include a high degree of technological integration, with platforms employing advanced data analytics, artificial intelligence, and blockchain to enhance efficiency and security. Additionally, the market is marked by increasing specialization, with platforms focusing on niche segments such as small business loans or real estate. Regulatory scrutiny and the need for compliance play a crucial role in shaping market dynamics, influencing operational practices and competitive strategies within the sector.
Report Coverage:
The research report offers an in-depth analysis based on By Type, By Business Model and By End User It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Continued growth in market size driven by increasing demand for alternative financing solutions.
- Expansion of institutional investor participation, enhancing market stability and liquidity.
- Integration of advanced technologies, including AI and blockchain, to improve credit assessment and transaction security.
- Rise of specialized platforms catering to niche markets such as real estate and business loans.
- Increased adoption of P2P lending in emerging markets due to expanding digital infrastructure and financial inclusion efforts.
- Greater regulatory clarity and evolving frameworks to ensure consumer protection and platform accountability.
- Development of hybrid business models combining direct and marketplace lending approaches.
- Enhanced user experience through more sophisticated data analytics and personalized lending solutions.
- Growing competition leading to innovation in platform features, fee structures, and customer service.
- Expansion of partnerships between P2P platforms and traditional financial institutions for integrated service offerings.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size for Peer-to-Peer (P2P) lending?
What is the expected Compound Annual Growth Rate (CAGR) for the P2P lending market?
What factors are driving the growth of the P2P lending market?
Which region holds the largest share of the P2P lending market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Peer to Peer Lending Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Peer to Peer Lending Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 517,197.6 million → 2032: USD 1,323,247.65 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Peer to Peer Lending Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Peer to Peer Lending Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Peer to Peer Lending Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Peer to Peer Lending Market Drivers
- 3.3 Peer to Peer Lending Market Restraints & Challenges
- 3.4 Peer to Peer Lending Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Peer to Peer Lending Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Peer to Peer Lending Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Peer to Peer Lending category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Peer to Peer Lending Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Peer to Peer Lending Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Peer to Peer Lending market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Peer to Peer Lending Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Peer to Peer Lending Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Peer to Peer Lending Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Peer to Peer Lending (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Peer to Peer Lending Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Peer to Peer Lending Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Peer to Peer Lending Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Peer to Peer Lending Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Peer to Peer Lending Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Peer to Peer Lending Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Peer to Peer Lending Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Peer to Peer Lending Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Peer to Peer Lending Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
