
Weather losses and super cover shape Australian premiums
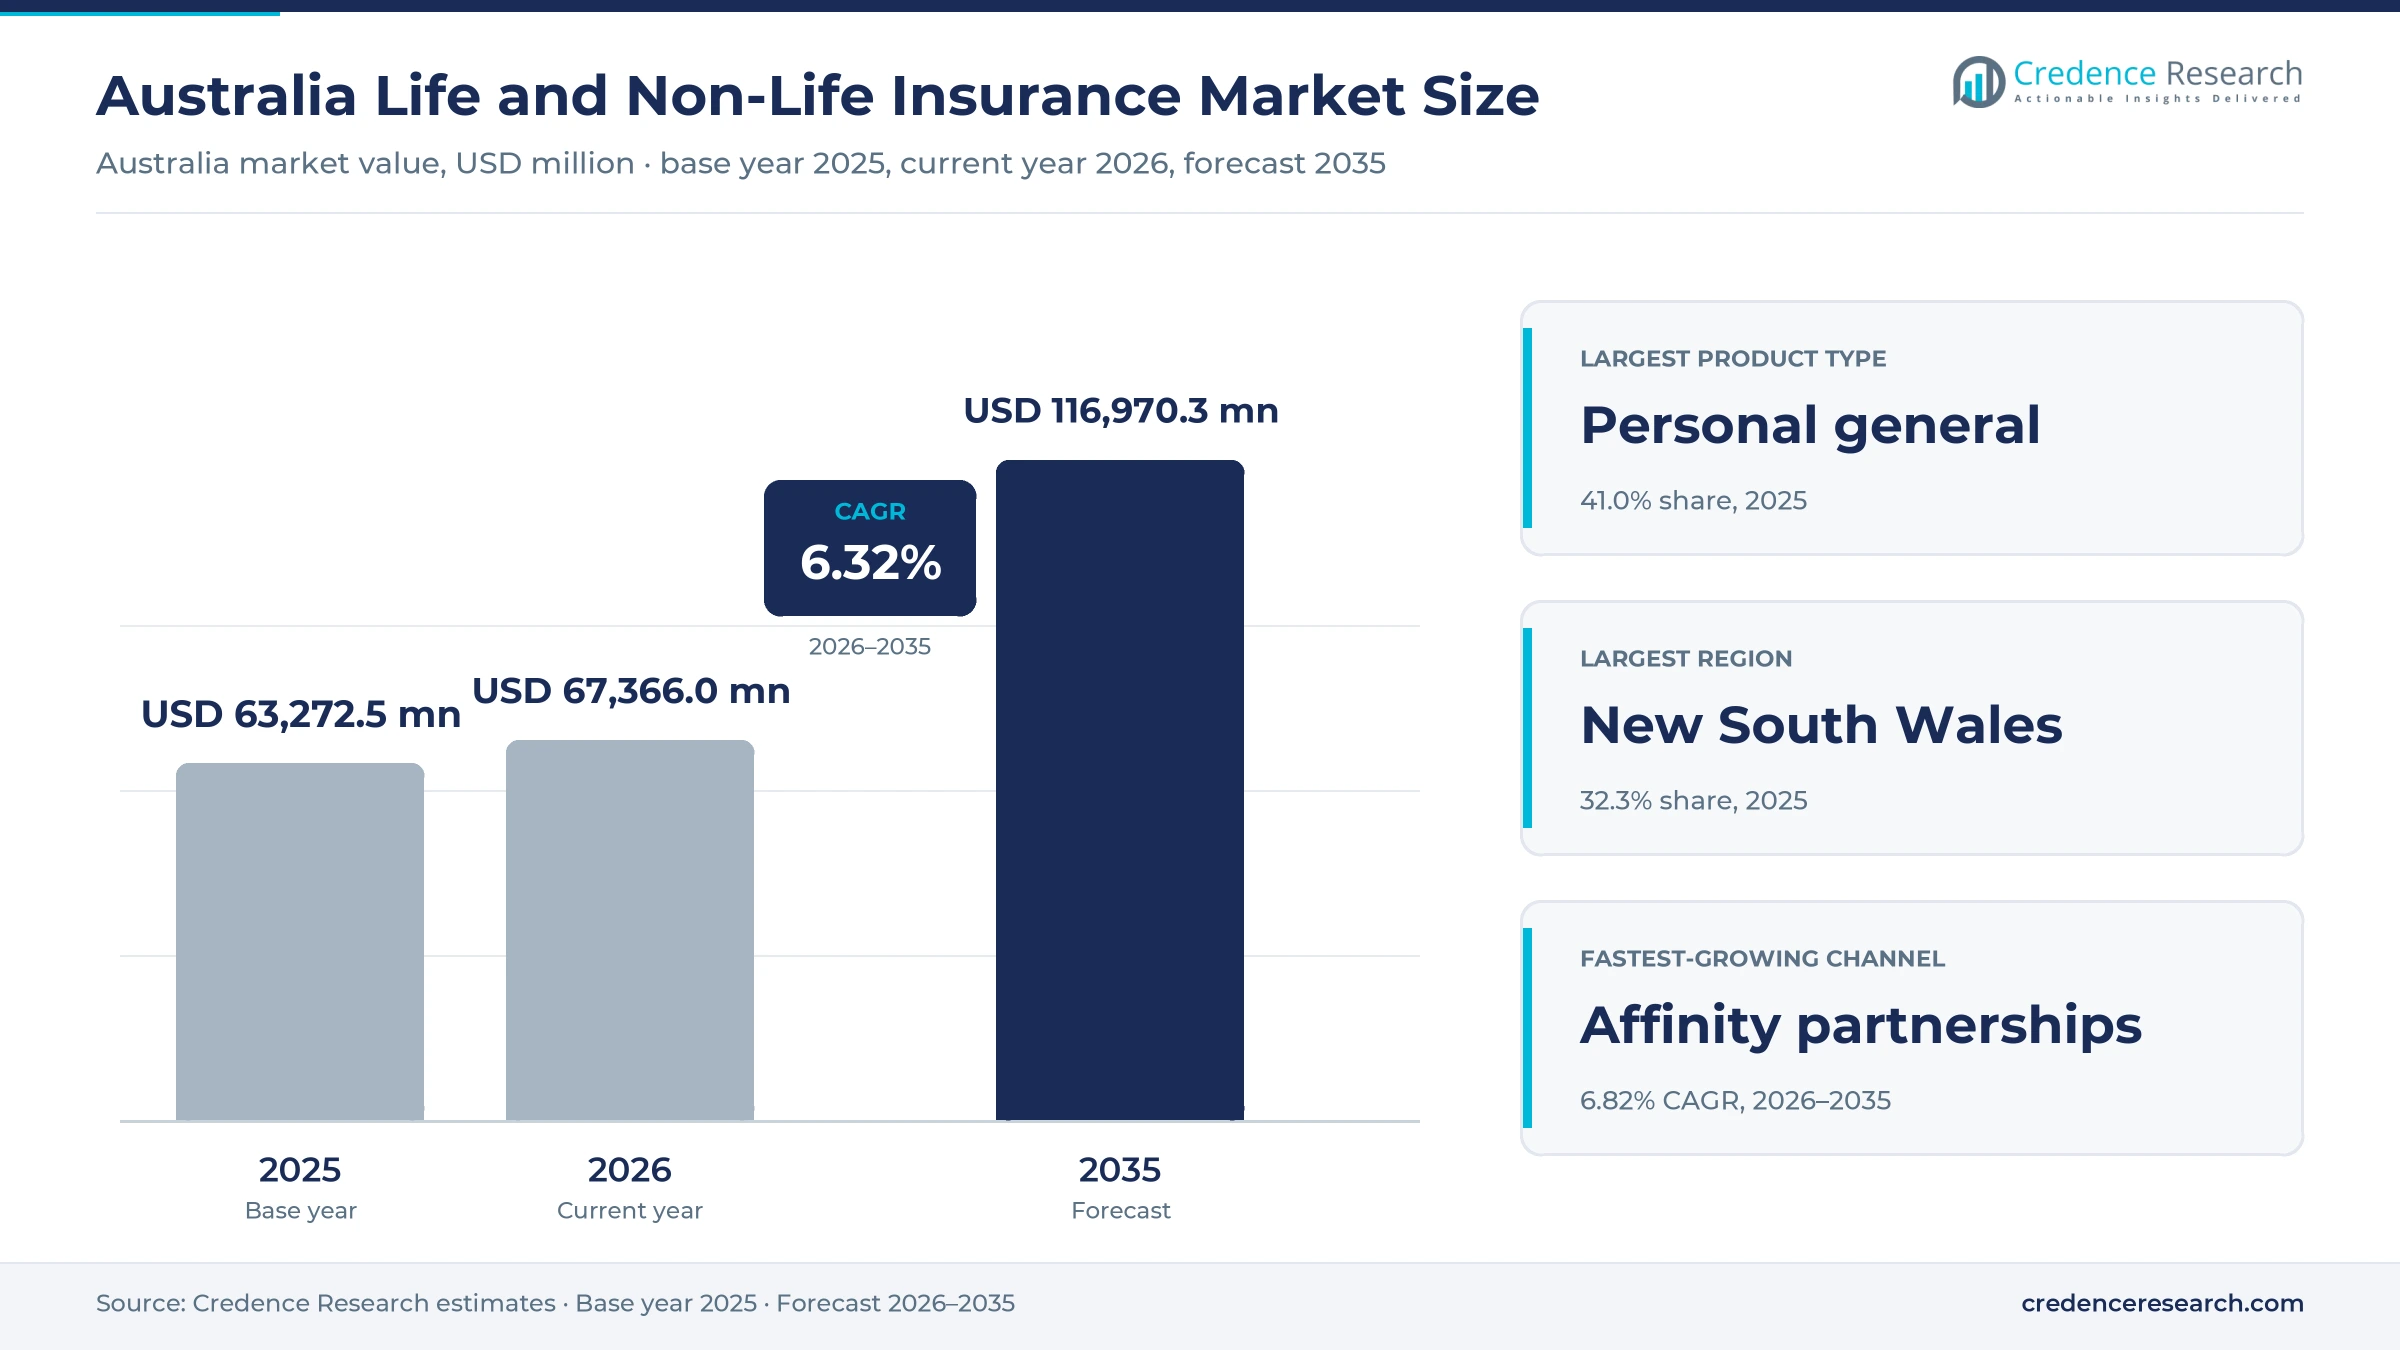
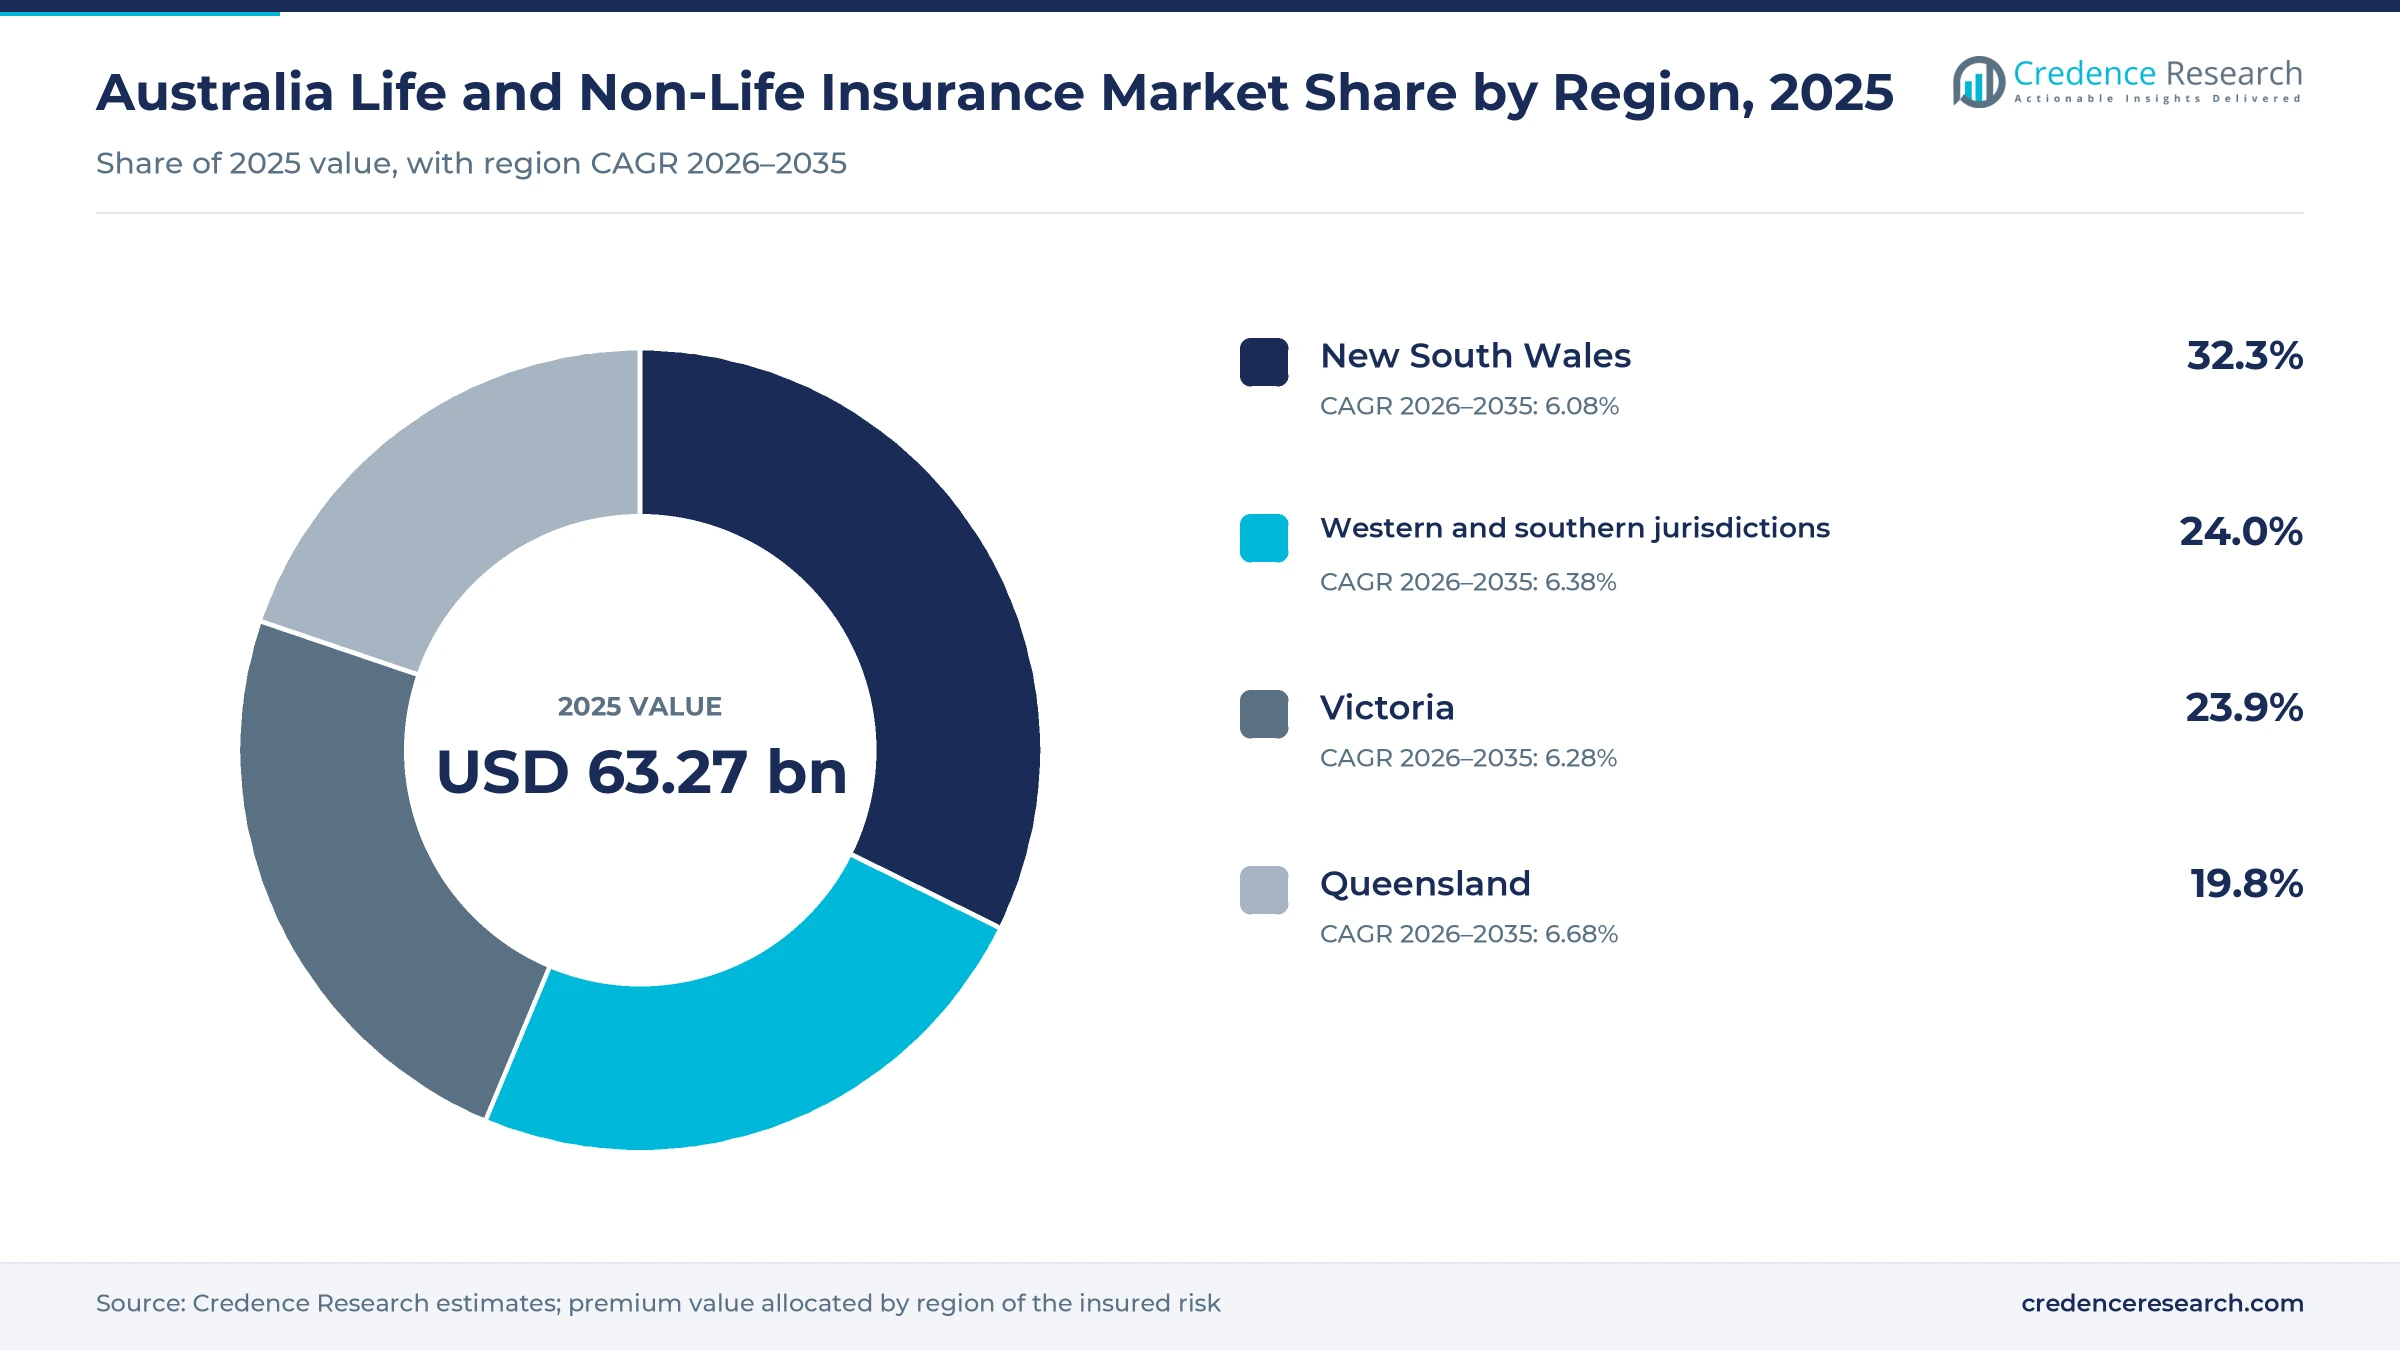
The Australia life and non-life insurance market was valued at USD 63.27 billion in 2025 and is projected to increase from USD 67.37 billion in 2026 to USD 116.97 billion by 2035, registering a CAGR of 6.32% during 2026–2035. Demand comes from households that insure homes and cars, businesses that transfer property, liability and cyber risk, and workers who hold death, disability and income protection cover through superannuation funds. New South Wales held the largest regional share, 32.3% in 2025, because Sydney concentrates corporate headquarters, brokers and high-value property. Queensland is the fastest-growing region at 6.68% a year, as cyclone, flood and storm losses lift the cost of property cover. Ex-Tropical Cyclone Alfred alone generated about 131,000 claims after its March 2025 catastrophe declaration. In turn, insurers are reshaping supply through motor club underwriting deals, a government cyclone reinsurance pool that covered about 3.2 million properties in 2026 and new ownership of major life insurers.
Which premiums and policy types does the estimate cover?
The estimate measures the value of premiums and contributions written by life insurers and general insurers for Australian risks. It covers term life, total and permanent disability, income protection, investment-linked life policies, home, motor, travel and personal accident cover, and commercial property, liability, cyber and workers cover. Values include policies bought directly, through brokers and advisers, through affinity partners and through superannuation group arrangements.
The estimate excludes private health insurance, statutory accident schemes run by state governments, and offshore reinsurance purchased by insurers for their own balance sheets. The value chain runs from capital providers and reinsurers through licensed insurers, underwriting agencies, brokers, advisers, superannuation trustees and affinity partners to households, employers and fund members across every state and territory.
Australia Life and Non-Life Insurance Market Insights
- The Australia life and non-life insurance market was valued at USD 63.27 billion in 2025 and is projected to reach USD 116.97 billion by 2035, registering a CAGR of 6.32% during 2026–2035.
- New South Wales held a 32.3% share of 2025 premium value, because Sydney concentrates corporate buyers, brokers and high-value insured property.
- Personal general insurance led with a 41.0% share of 2025 value, because nearly every household buys motor and home cover each year.
- Insurers recorded about $3.49 billion in insured losses from 264,000 claims across five declared extreme weather events in 2025, which keeps property pricing under pressure.
- Insurance Australia Group completed its purchase of 90% of RACQ Insurance on Sept. 1, 2025, under a 25-year distribution agreement with the Queensland motor club.
Personal cover leads while business lines grow fastest
Why does personal general cover lead product demand?
Based on product type, the market is categorized into life protection, life investment policies, personal general insurance and business general insurance. Personal general insurance led with a 41.0% share of 2025 value, because households renew motor, home and contents cover every year. Business general insurance grows fastest at 6.65% a year, as companies buy more property, liability and cyber protection.
How do individual buyers and businesses split premium value?
Based on customer segment, the market is categorized into individual policyholders, business policyholders and superannuation trustees. Individual policyholders led with a 60.0% share of 2025 value, because households buy motor, home and retail life cover in their own names. Business policyholders grow fastest at 6.57% a year, as firms of every size respond to rising cyber, property and liability exposure.
Why are affinity partnerships the fastest-growing channel?
Based on distribution channel, the market is categorized into insurer direct, insurance brokers and advisers, superannuation group tenders and affinity partnerships. Insurance brokers and advisers led with a 42.0% share of 2025 value, because commercial buyers and retail life clients rely on intermediaries. Affinity partnerships grow fastest at 6.82% a year, as motor clubs hand underwriting to large insurers under long-term agreements.
How does physical asset risk dominate covered exposure?
Based on risk category, the market is categorized into mortality and disability risk, physical asset risk and liability and financial risk. Physical asset risk led with a 52.0% share of 2025 value, because homes, vehicles and commercial buildings face storm, flood and fire losses. Liability and financial risk grows fastest at 6.75% a year, as cyber incidents and professional claims become more frequent.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product Type | Personal general insurance | 41.0% | Business general insurance | 6.65% |
| By Customer Segment | Individual policyholders | 60.0% | Business policyholders | 6.57% |
| By Distribution Channel | Insurance brokers and advisers | 42.0% | Affinity partnerships | 6.82% |
| By Risk Category | Physical asset risk | 52.0% | Liability and financial risk | 6.75% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Repricing, super cover and cyber risk lift premium value
How does asset repricing and risk transfer lift premiums?
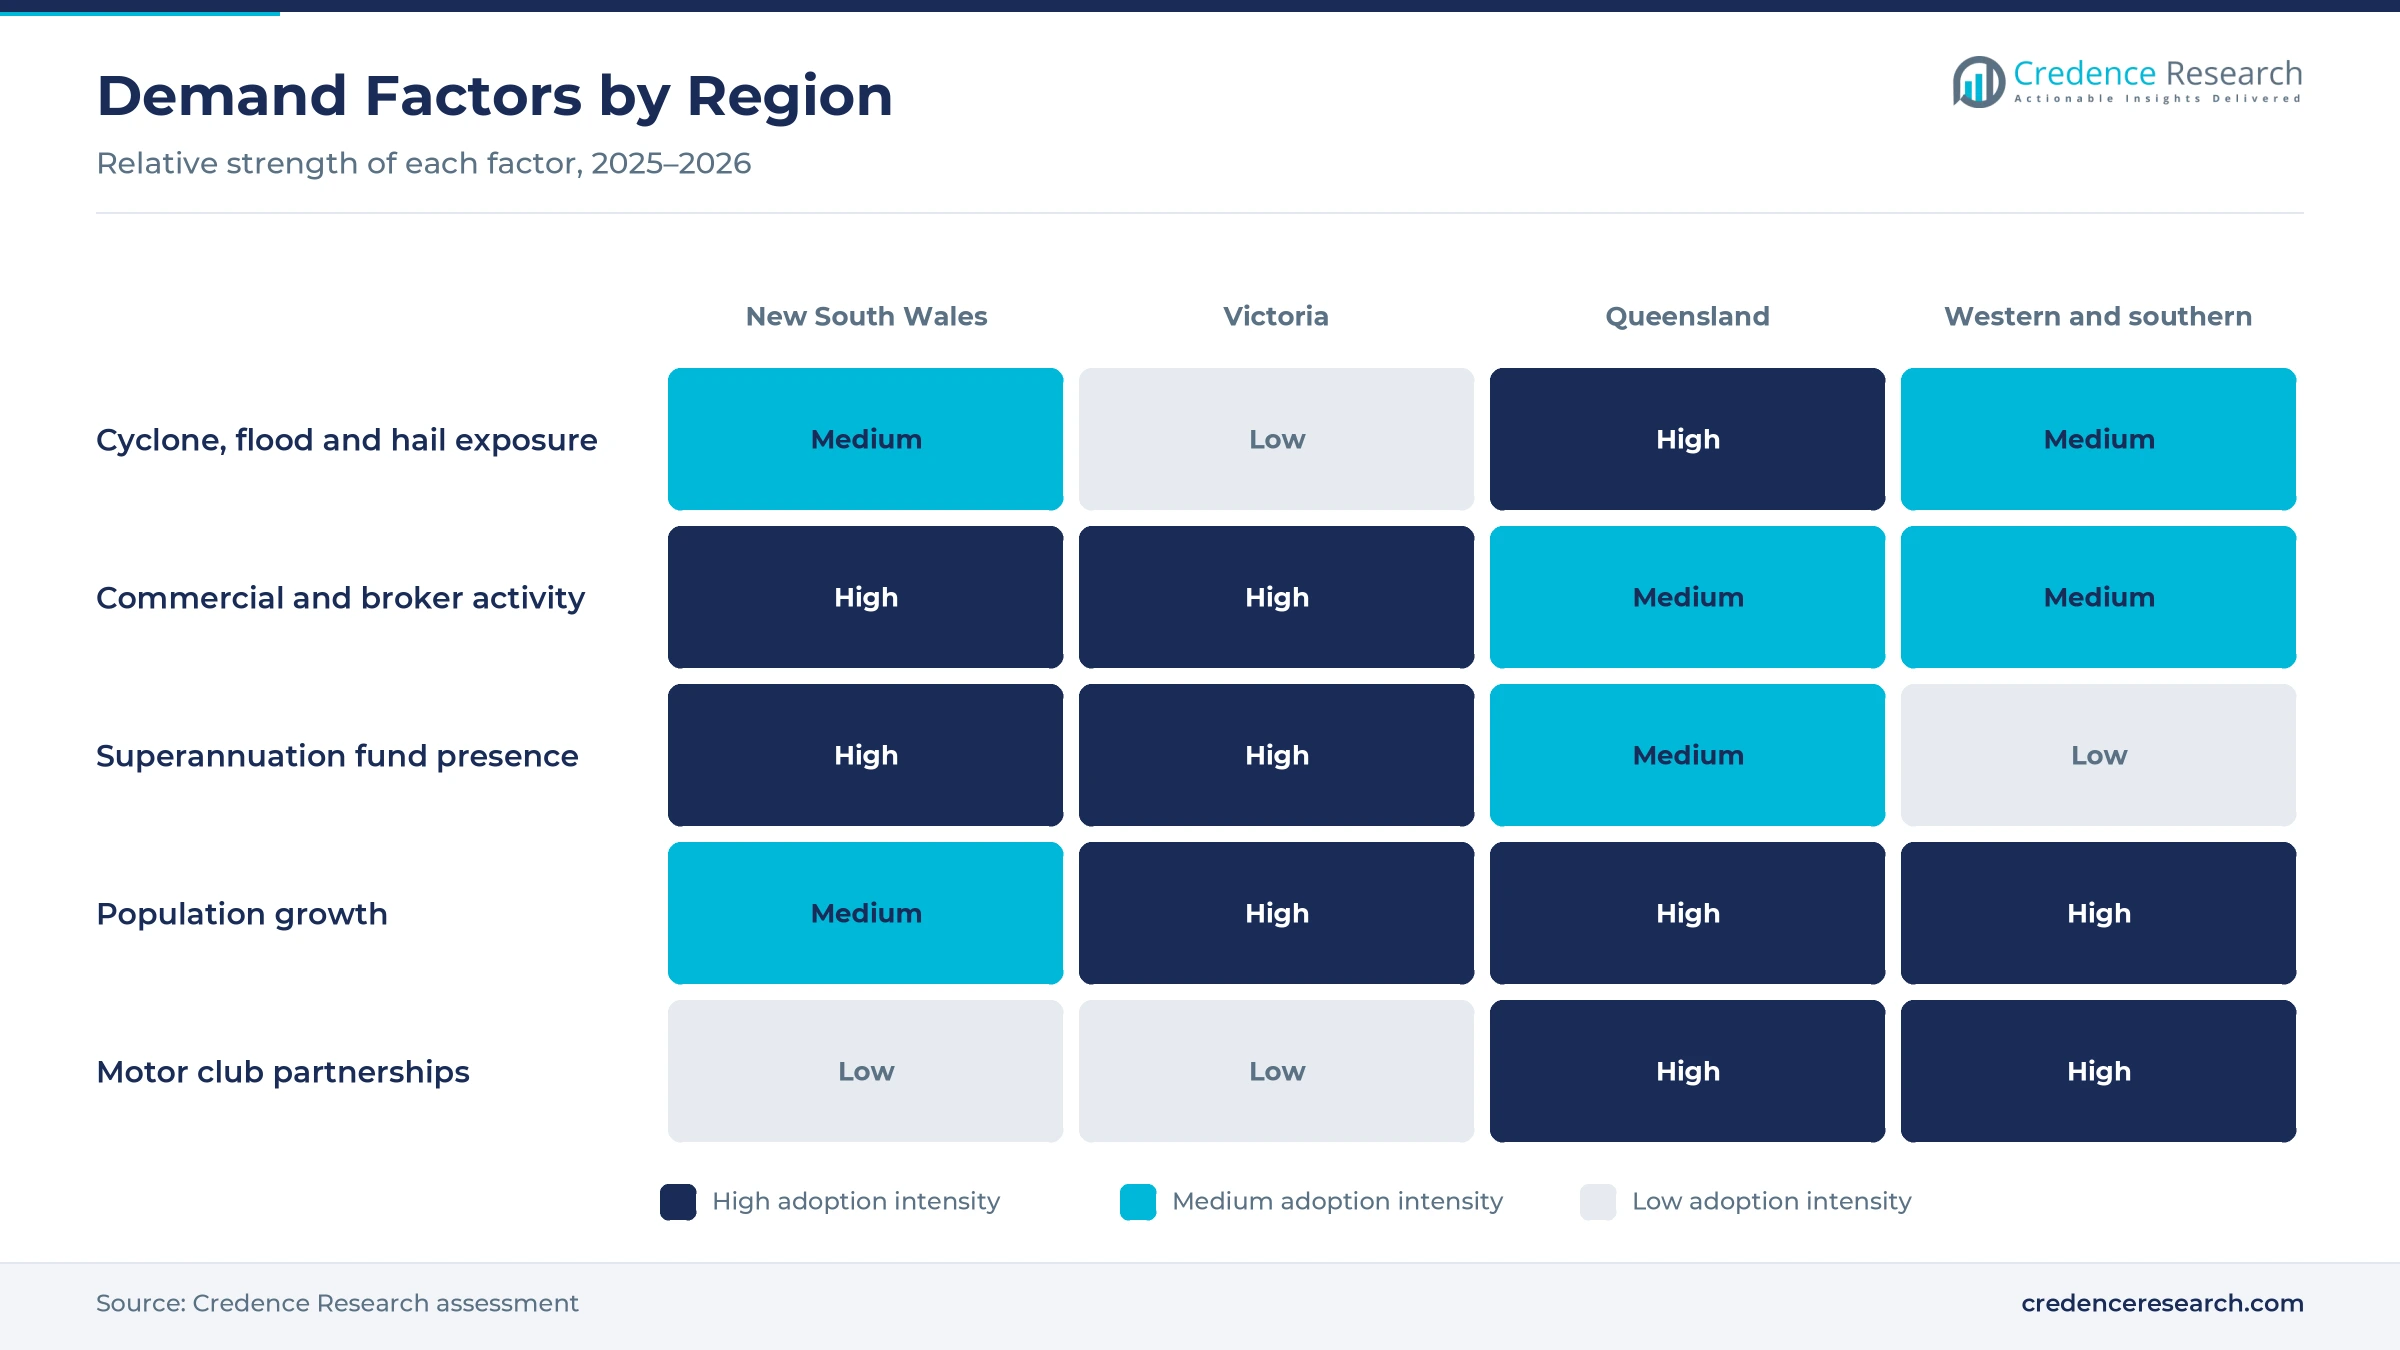
Asset repricing and risk transfer lift premium value, because insurers must charge more to cover rising weather losses and higher rebuilding costs. Insurers faced about $3.49 billion in insured losses from 264,000 claims across five declared events in 2025. Ex-Tropical Cyclone Alfred was declared a catastrophe on March 9, 2025, and the Insurance Council of Australia recorded about 131,000 claims across southeast Queensland and northern New South Wales. A further storm and hail event in late November 2025 produced 70,200 claims and $814 million in insured losses. As a result, physical asset risk holds a 52.0% share of 2025 value, and Queensland records the fastest regional growth as home and contents cover is repriced.
Why does superannuation keep protection cover widespread?
Superannuation protection distribution keeps life cover widespread, because most working Australians hold default death, disability and income cover inside their funds. About 9.26 million lives held death cover through super at June 2025, while 8.22 million held total and permanent disability cover, according to the Association of Superannuation Funds of Australia. Income protection covered about 4.39 million lives, and the average death cover premium rose to $240 a year from $188 in 2018. Finalized total and permanent disability claims also increased to 21,282 in the year to June 2025. In turn, superannuation trustees hold a steady part of 2025 value, as group tenders renew cover for millions of members at scale.
How does digital commercial risk transfer expand business cover?
Digital commercial risk transfer expands business cover, because firms now face cyber extortion, data breach and business interruption risks alongside traditional property and liability exposure. The Australian Signals Directorate received more than 84,700 cybercrime reports in 2024-25, roughly one every six minutes, according to the Defence ministers. The average self-reported cost of cybercrime per report for small businesses rose 14% to $56,600 over the same period. The agency also responded to more than 1,200 cyber security incidents, an 11% increase on 2023-24. As a result, demand for cyber cover rises quickly, and liability and financial risk grows at 6.75% a year.
Why does an aging population raise protection needs?
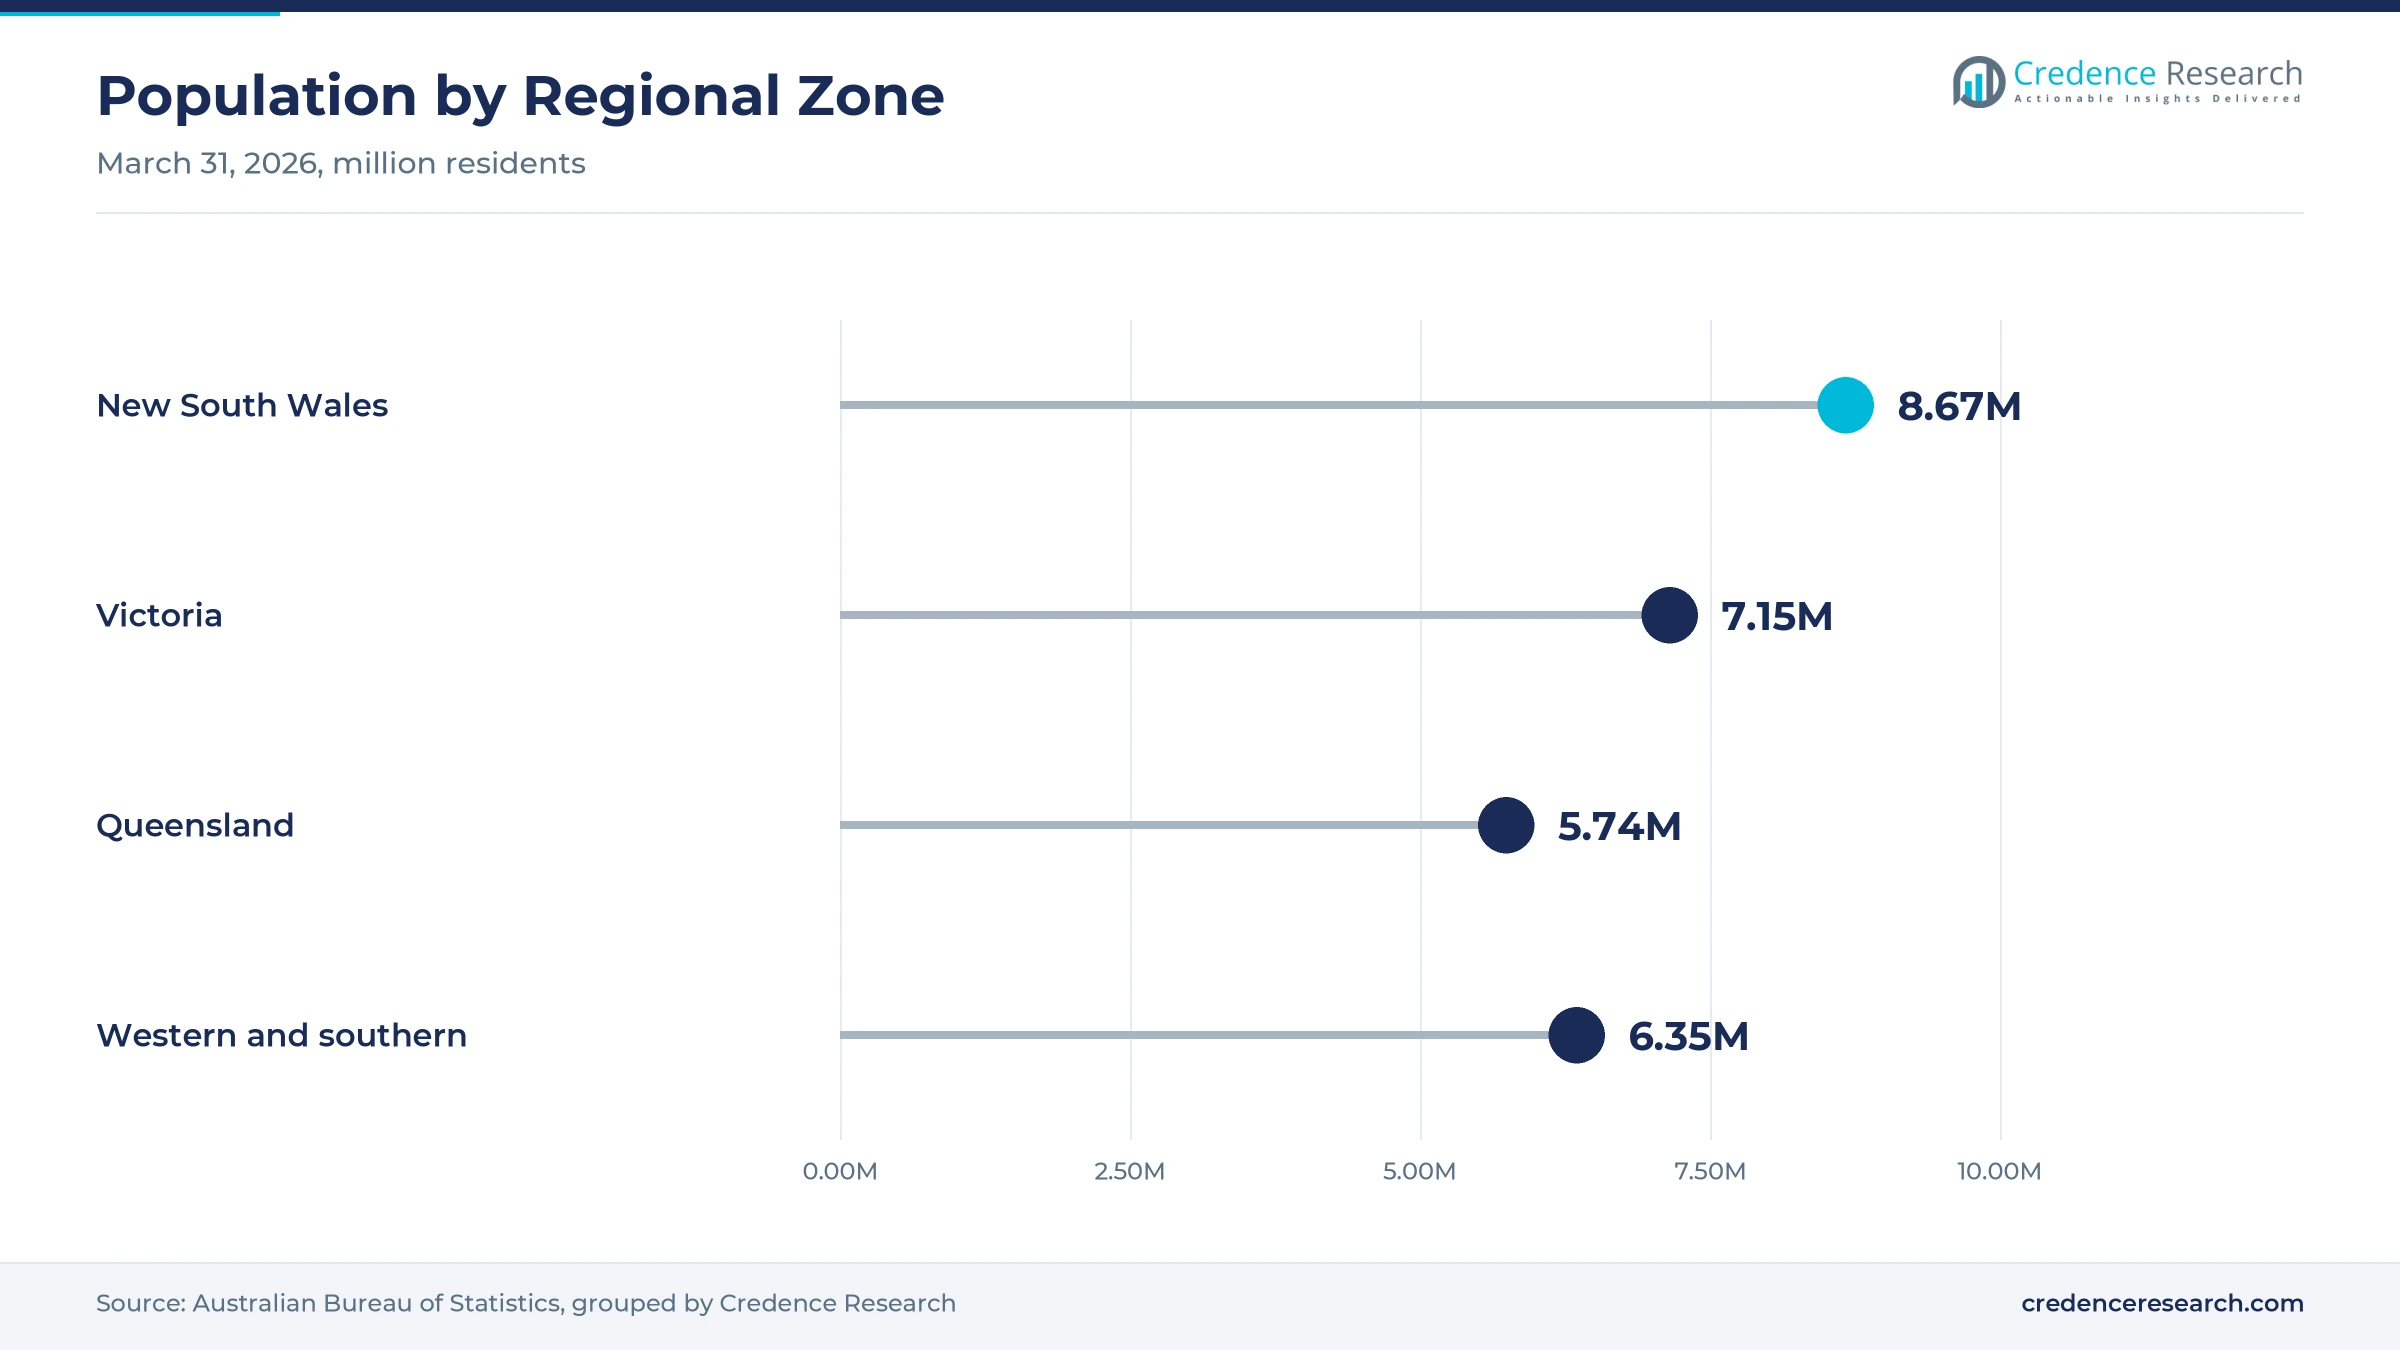
An aging and growing population raises protection needs, because older households hold more assets while working families need income and mortgage protection. People aged 65 and over made up about 18.1% of the population in 2025, up from 17.4% in 2023, according to World Bank data. Australia's population also reached 27.92 million at March 31, 2026, growing 1.4% over the year, according to the Australian Bureau of Statistics. Western Australia grew fastest at 2.1%, while Victoria and Queensland each grew 1.6%, which widens demand for motor, home and life cover. In turn, individual policyholders keep a 60.0% share of 2025 value, as more residents insure homes, cars and incomes.
Motor club deals and pooled cyclone cover reshape supply
How is the shift to motor club underwriting deals changing supply?
The shift to motor club underwriting deals is changing supply, because mutual clubs with large member bases now hand risk to well-capitalized insurers. Insurance Australia Group completed its purchase of 90% of RACQ Insurance on Sept. 1, 2025, under a 25-year exclusive distribution agreement. The Australian Competition and Consumer Commission cleared that deal in May 2025 after finding that RACQ Insurance faced material challenges from high natural hazard exposure. Allianz Australia also received clearance in June 2025 to underwrite RAA general policies under a 20-year distribution arrangement in South Australia. As a result, affinity partnerships grow at 6.82% a year, the fastest channel rate, as club members buy motor cover under familiar brands.
Why is the rise of pooled cyclone cover reshaping pricing?
The rise of pooled cyclone cover is reshaping pricing, because a government reinsurance pool now absorbs part of the cyclone risk that once made northern policies unaffordable. The pool covered about 3.2 million properties in 2026, including more than 3 million homes and over 100,000 small business properties. The competition regulator found that small business premiums in higher cyclone-risk areas fell 24% in the first year after insurers joined the pool. Home premiums in those areas fell 11% over the same period, while home premiums in no-cyclone-risk areas rose 6%. In turn, northern Queensland and Western Australian buyers keep cover, which supports growth in both zones.
Can new owners and brands open growth in life protection?
New owners and brands open growth in life protection, because recapitalized insurers are investing in claims support, digital service and retirement products. MLC Life rebranded as Acenda in September 2025 ahead of its combination with Resolution Life Australasia under Nippon Life ownership. The combined business is positioned to serve around 2 million customers across protection and retirement products. TAL also paid benefits to about 57,000 customers and their families between April 1, 2025, and March 31, 2026, with mental health the leading claim cause at 22%. As a result, life protection keeps a solid share of 2025 value, as insurers compete on support and claims experience.
Is there room to rebuild advice-led protection sales?
Advice-led protection sales have room to recover, because reforms are cutting the cost and paperwork of personal advice. Parliament passed the first tranche of the Delivering Better Financial Outcomes reforms on July 4, 2024, simplifying fee documents and adding consumer protections for insurance advice. The law also confirmed that members can use their super accounts to pay for personal advice about their super. The average income protection premium per life in super also rose to $410 in 2025 from $358 in 2018, which shows the value of reviewing cover with an adviser. In turn, insurance brokers and advisers keep a 42.0% share of 2025 value, as underinsured families return to advised cover.
Affordability, claims costs and advice gaps test insurers
How does affordability pressure push households to cut cover?
Affordability pressure pushes some households to cut cover, because home and motor premiums keep climbing for most households, especially in areas exposed to flood and storm. The competition regulator noted that pool relief does not extend to the 98% of policies with no elevated cyclone risk. As a result, some owners raise excesses or drop contents cover. Insurers respond with flood mapping, mitigation discounts and flexible excess options that keep core protection in place.
Why do rising claims costs squeeze underwriting margins?
Rising claims costs squeeze underwriting margins, because repair materials, trade labor and replacement vehicles cost more than when many policies were priced. Catastrophe events then add sudden surges of claims in the same months. In turn, insurers must hold more capital and buy more reinsurance. Insured losses of about $3.49 billion from declared events in 2025 show how quickly costs can build in a single year. Companies respond with repairer networks, faster settlement and outsourced claims handling services during peak events.
How do disability and mental health claims pressure life insurers?
Disability and mental health claims pressure life insurers, because longer claim durations raise the cost of income protection and total and permanent disability cover. Group claims in super paid out more than premiums for disability products in the year to June 2025. As a result, trustees face higher group premiums at each tender. Mental health conditions were the leading cause of TAL claims at 22% in the year to March 2026. Insurers respond with early intervention, rehabilitation support and redesigned benefit periods.
Why do advice costs limit retail protection sales?
Advice costs limit retail protection sales, because the time and paperwork needed to prepare personal advice raise the price clients pay for fully underwritten cover. Many families therefore rely only on default cover in super, which may be lower than their needs. In turn, underinsurance leaves households exposed after death or disability. Insurers respond with simpler products, direct quotes and adviser support tools that reduce the time needed to write a policy.
New South Wales leads while Queensland grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| New South Wales | 20.44 | 32.3% | 6.08% |
| Western and southern jurisdictions | 15.19 | 24.0% | 6.38% |
| Victoria | 15.12 | 23.9% | 6.28% |
| Queensland | 12.53 | 19.8% | 6.68% |
Why does New South Wales hold the largest share?
New South Wales held a 32.3% share of 2025 value and grows at 6.08% a year, because the state concentrates large commercial policyholders, brokers and high-value insured property. The state had about 8.67 million residents at March 31, 2026, the largest population of any state. However, growth is slower than in Queensland because population growth was lower at 1.1% over the year. Northern New South Wales also shared the storm and flood claims linked to Ex-Tropical Cyclone Alfred in 2025.
How does Victoria support premium growth?
Victoria held a 23.9% share of 2025 value and grows at 6.28% a year, because the state has the second-largest population and a broad base of employers, households and commercial property. The state added about 109,500 residents in the year to March 2026, a growth rate of 1.6%. This growth lifts demand for motor, home and protection cover across new suburbs. Superannuation group cover held by workers in the state also adds steady protection premiums each year.
Why is Queensland the fastest-growing region?
Queensland held a 19.8% share of 2025 value and grows fastest at 6.68% a year, because cyclone, flood and hail exposure keeps property premiums rising. Ex-Tropical Cyclone Alfred produced about 131,000 claims across southeast Queensland and northern New South Wales in 2025. Insurance Australia Group also took over underwriting for RACQ members in September 2025. The state added about 90,100 residents in the year to March 2026, which widens the insured base.
What drives demand in the western and southern jurisdictions?
The western and southern jurisdictions held a 24.0% share of 2025 value and grow at 6.38% a year, because Western Australia, South Australia, Tasmania, the Northern Territory and the Australian Capital Territory combine resource, farm and public sector demand. Western Australia had the fastest state population growth at 2.1% in the year to March 2026. Allianz Australia also gained clearance in 2025 to underwrite RAA general policies in South Australia.
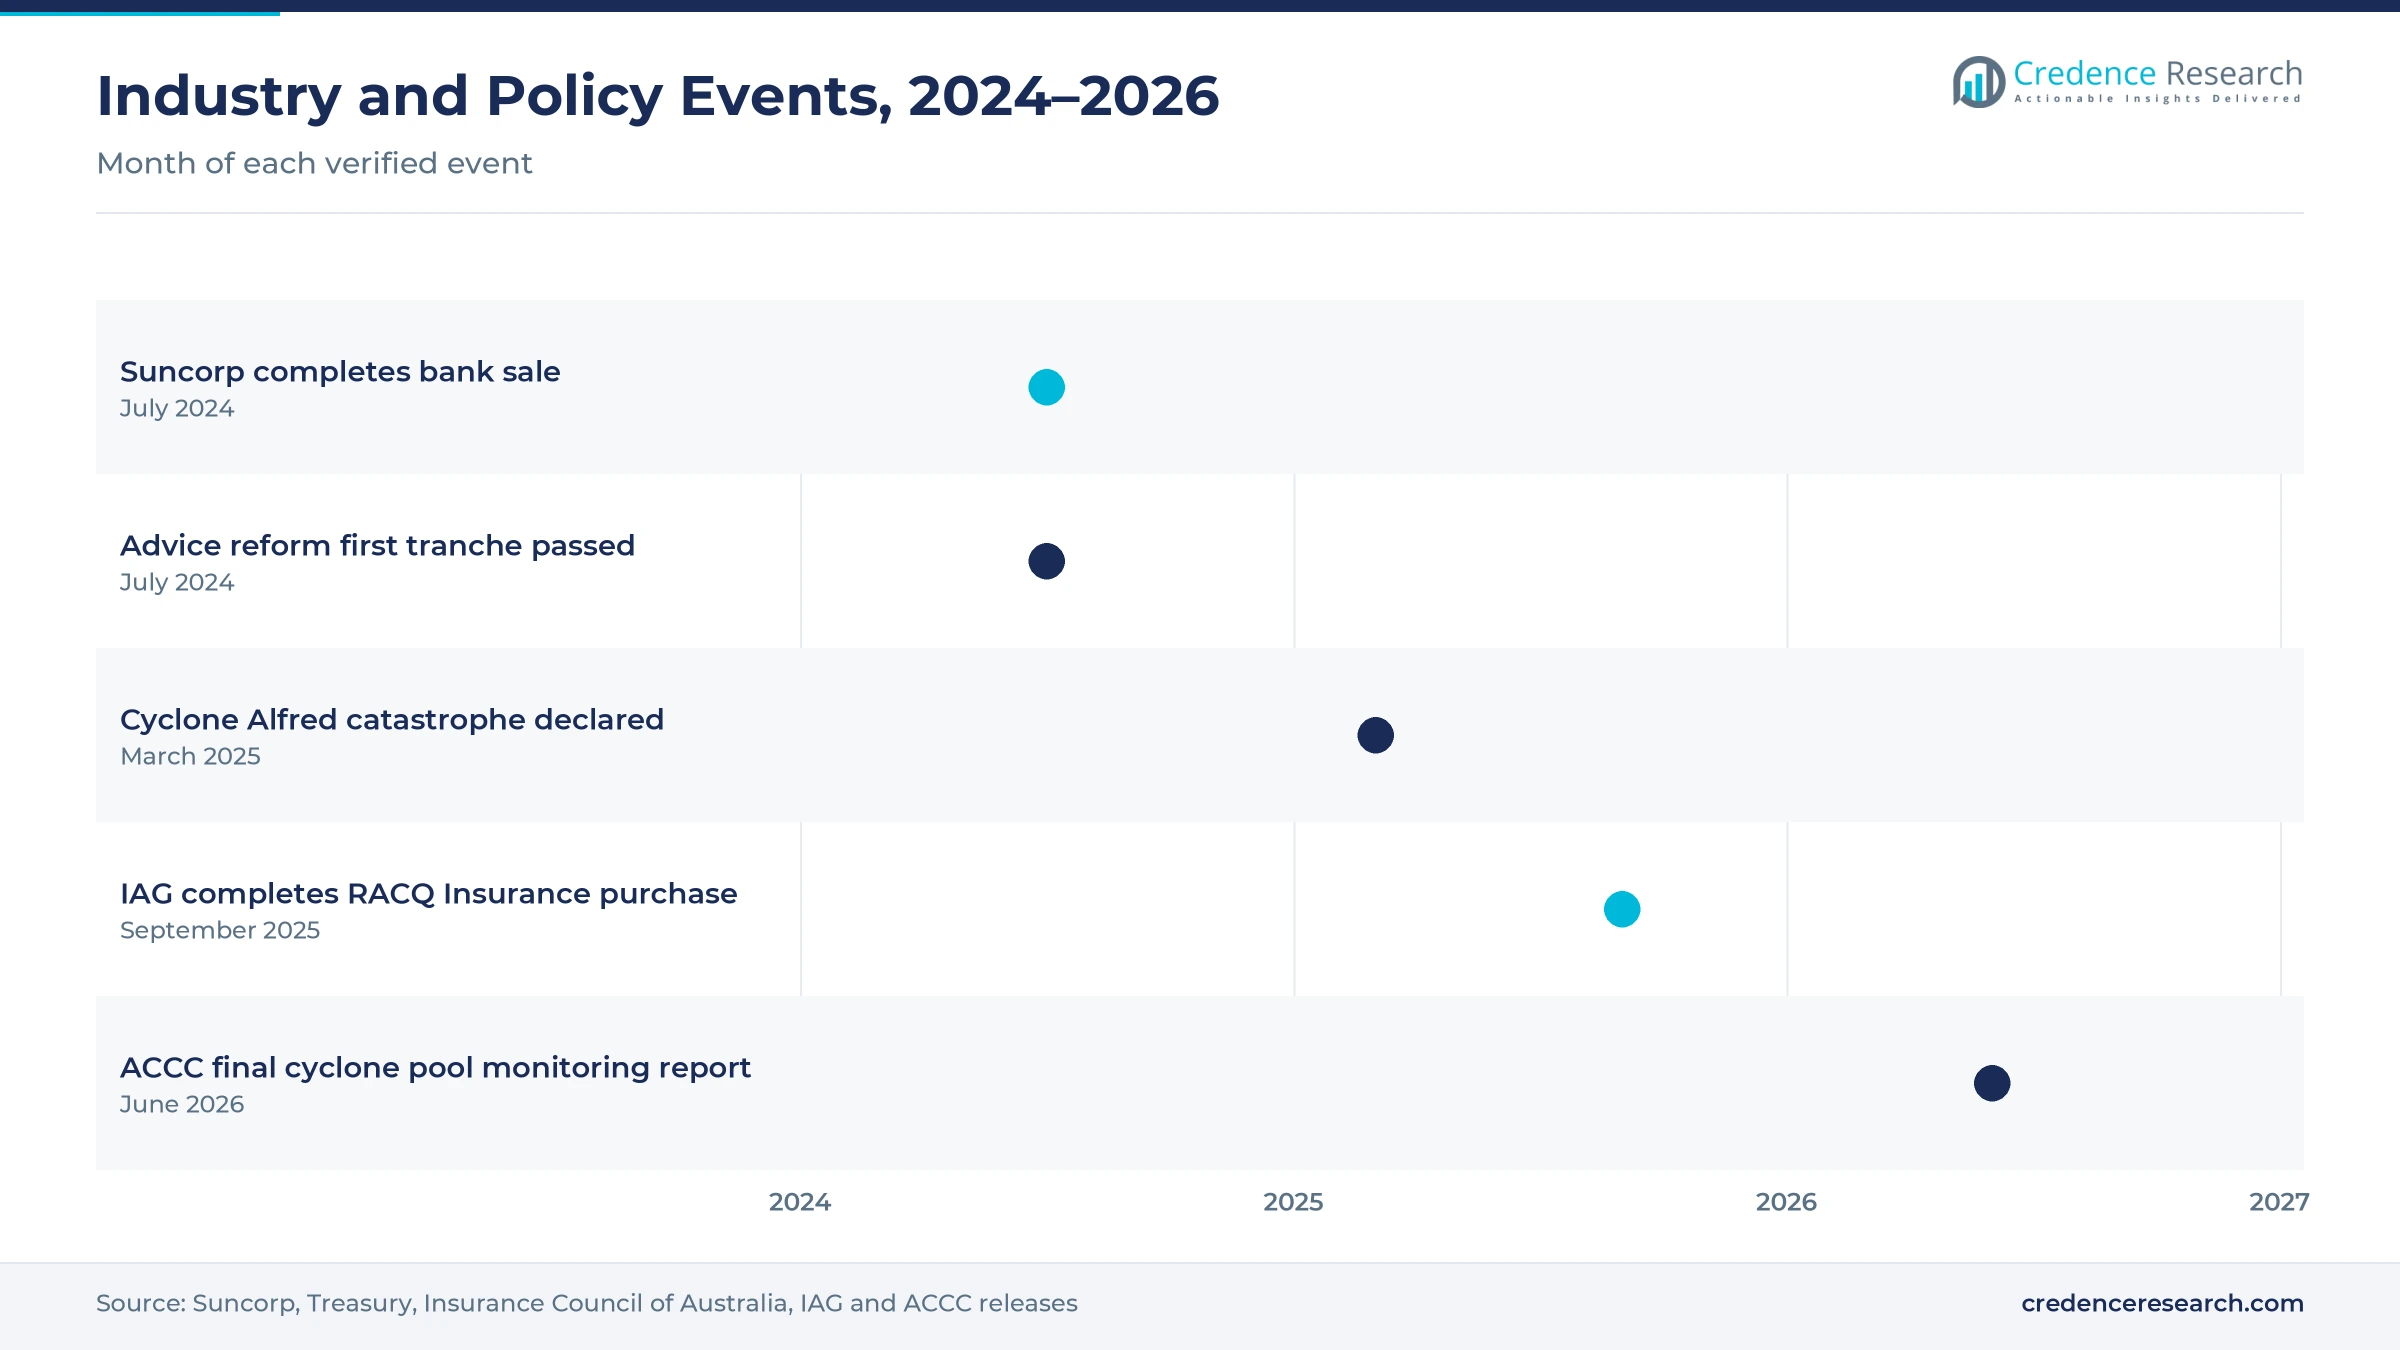
Bank exits, club deals and new owners marked 2024 to 2026
| Development | Status and market relevance |
|---|---|
| In July 2024, Suncorp completed the sale of Suncorp Bank to ANZ and became a pure-play insurer. | Focused capital on general insurance in Australia and New Zealand |
| In July 2024, Parliament passed the first tranche of the Delivering Better Financial Outcomes advice reforms. | Simplified advice documents and added protections for insurance advice |
| In March 2025, Ex-Tropical Cyclone Alfred was declared an insurance catastrophe. | Generated about 131,000 claims in Queensland and northern New South Wales |
| In September 2025, Insurance Australia Group completed its purchase of 90% of RACQ Insurance. | Added a 25-year exclusive distribution agreement with RACQ |
| In September 2025, MLC Life rebranded as Acenda ahead of its combination with Resolution Life Australasia. | Created a life insurer positioned to serve around 2 million customers |
Hazard models, digital claims and health data reshape cover
- Address-level hazard models score flood, cyclone and bushfire exposure for each property, which lets insurers price risk more precisely.
- Digital claims platforms accept photos, track repairs and pay settlements online, which shortens claim times after catastrophe events.
- Cyber risk scanning tools test the external security of small business applicants, which helps underwriters set cyber terms.
- Health and wellness programs such as AIA Vitality in super reward members for healthy activity, which supports retention of protection cover.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Scale insurers and partner networks compete on capacity
Competition is led by large general insurers with national brands and broker networks, alongside life insurers that win superannuation group tenders and adviser business. Insurance Australia Group added RACQ underwriting in 2025, while Suncorp became a pure-play insurer after selling its bank in 2024. Allianz Australia expanded through motor club partnerships, and QBE named a new Australia Pacific chief executive in September 2026. Hollard writes cover through partner brands such as Real Insurance, Australian Seniors and CBA Insurance. In life cover, TAL, Acenda, AIA, Zurich and MetLife compete for super fund tenders, adviser relationships and direct customers. Zurich, MetLife and AIA each run dedicated teams for advisers and superannuation partners, which keeps them active in both retail and group channels. Rivals compete on capital strength, claims service, distribution access and pricing accuracy.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Insurance Australia Group | General insurer | Completed purchase of 90% of RACQ Insurance in 2025 |
| Suncorp Group | General insurer | Became a pure-play insurer after its July 2024 bank sale |
| Allianz Australia | General insurer | Cleared in 2025 to underwrite RAA general policies |
| QBE Australia | General insurer | Named a new Australia Pacific chief executive in 2026 |
| Hollard Australia | Partner-led insurer | Writes cover for Real Insurance and Australian Seniors |
| TAL Australia | Life insurer | Paid benefits to about 57,000 customers in a year |
| Acenda Group | Life insurer | Formerly MLC Life, combining with Resolution Life |
| AIA Australia | Life insurer | Runs superannuation partnerships and Vitality in super |
| Zurich Australia | Life and general insurer | Serves advisers, brokers and super fund partners |
| MetLife Australia | Life insurer | Supplies group cover to superannuation and corporate partners |
Credence Research view on Australian risk transfer
Credence Research's view is that Australian premium value will grow faster than the economy because weather losses, cyber exposure and protection needs keep pushing prices and cover levels higher. General insurance remains the larger part of the market, while business lines and affinity partnerships gain share. Superannuation keeps millions of workers covered for death and disability, although claims costs keep group pricing under pressure. Insurers that price hazards precisely, secure long-term distribution deals and support claimants early should gain share fastest.
How the Australian premium estimate was built
The report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. That model combines regulator industry statistics, catastrophe claims data, superannuation insurance data, population statistics, World Bank demographic data, cyber threat reporting and company announcements on acquisitions and distribution deals. Segment splits and regional growth rates are Credence Research estimates, while regional shares follow the client-defined split. Sources used are public reports, official statistics, trade press, regulator decisions and company releases, and no interviews or surveys were used.
Repricing and protection needs carry growth to 2035
Premium value is expected to reach USD 116.97 billion by 2035, a 6.32% CAGR during 2026–2035, as property repricing, cyber cover and protection needs keep demand rising. Growth should stay strong through 2028 while insurers continue to reprice catastrophe exposure. After that, business cover, affinity deals and advised life sales will carry more growth as home premiums stabilize. A run of severe weather years would raise prices further, while stronger mitigation would ease them. Insurers with strong capital and long-term partners are expected to gain the most.
Frequently Asked Questions
How big is the Australia life and non-life insurance market?
Which product type leads Australian premium value?
Which region leads the Australia life and non-life insurance market?
How many Australians hold life cover through superannuation?
How did extreme weather affect insurers in 2025?
Which distribution channel is growing fastest?
Who are the leading insurers in Australia?
What are the main challenges for Australian insurers?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Personal general insurance
- 1.2.2 Business general insurance
- 1.2.3 Life protection
- 1.2.4 Life investment policies
- 1.3 By Customer Segment
- 1.3.1 Individual policyholders
- 1.3.2 Business policyholders
- 1.3.3 Superannuation trustees
- 1.4 By Risk Category
- 1.4.1 Physical asset risk
- 1.4.2 Liability and financial risk
- 1.4.3 Mortality and disability risk
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 63.27 billion → 2035: USD 116.97 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Life and Non-Life Insurance Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Life and Non-Life Insurance Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Australia Life and Non-Life Insurance Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Australia Life and Non-Life Insurance Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Life and Non-Life Insurance Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Life and Non-Life Insurance Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Life and Non-Life Insurance Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Life and Non-Life Insurance Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 63.27 billion → 2035: USD 116.97 billion)
- 11.1.2 Historical Market Size, 2018-2025
- 11.1.3 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Life and Non-Life Insurance Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Base-Year Market Share, 2025
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Personal general insurance
- 12.3.6.2 Business general insurance
- 12.3.6.3 Life protection
- 12.3.6.4 Life investment policies
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Customer Segment - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Base-Year Market Share, 2025
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Individual policyholders
- 12.4.6.2 Business policyholders
- 12.4.6.3 Superannuation trustees
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Risk Category - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Base-Year Market Share, 2025
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Physical asset risk
- 12.5.6.2 Liability and financial risk
- 12.5.6.3 Mortality and disability risk
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Life and Non-Life Insurance End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Life and Non-Life Insurance Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Life and Non-Life Insurance Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2025-2035
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Life and Non-Life Insurance Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Insurance Australia Group
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Suncorp Group
- 18.4 Allianz Australia
- 18.5 QBE Australia
- 18.6 Hollard Australia
- 18.7 TAL Australia
- 18.8 AIA Australia
- 18.9 Zurich Australia
- 18.10 Acenda Group
- 18.11 MetLife Australia
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

