
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
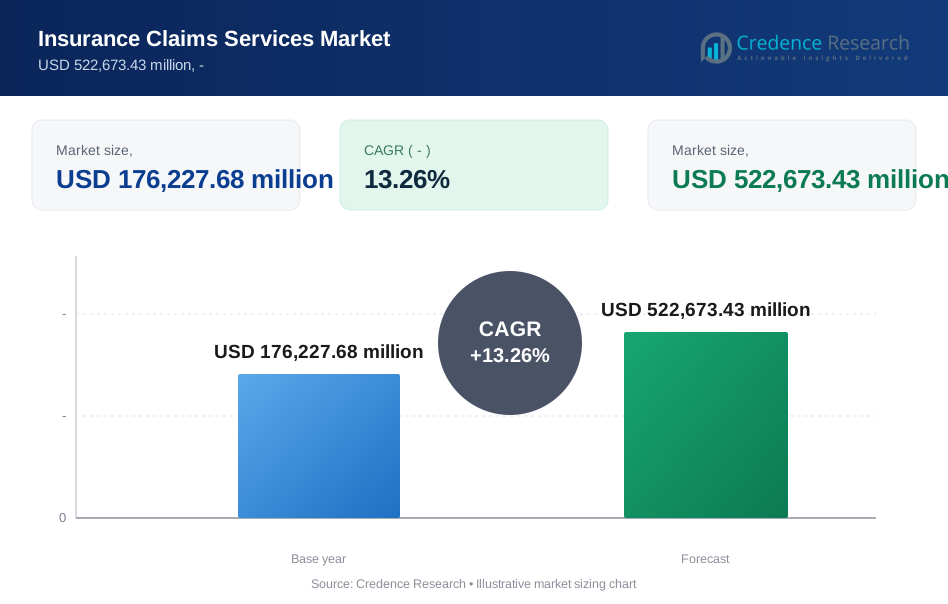
| Insurance Claims Services Market Size 2023 | USD 176,227.68 Million |
| Insurance Claims Services Market, CAGR | 13.26% |
| Insurance Claims Services Market Size 2032 | USD 522,673.43 Million |
Market Overview
The Insurance Claims Services Market is projected to witness substantial growth, with its value expected to surge from USD 176,227.68 million in 2023 to USD 522,673.43 million by 2032, marking an impressive compound annual growth rate of 13.26%. The Insurance Claims Services Market operates as a vital interface within the expansive insurance industry, bridging the gap between policyholders and insurers during times of crisis. This segment encompasses an array of services dedicated to expediting the assessment, processing, and settlement of insurance claims across diverse sectors such as automotive, healthcare, property, casualty, and life insurance. Driven by the perpetual risk exposure inherent in daily life and business operations, the demand for insurance claims services remains consistently robust. Natural disasters, accidents, health emergencies, and unforeseen events underline the necessity for efficient and reliable mechanisms for claims processing and settlement. Consequently, insurers are continuously refining their claims management processes to bolster customer satisfaction, streamline operations, and mitigate financial risks.
Technological advancements are playing a transformative role in reshaping the landscape of the Insurance Claims Services Market. Innovations like artificial intelligence, machine learning, data analytics, and automation have revolutionized conventional claims handling practices, enabling insurers to expedite claim processing, enhance accuracy, and reduce operational costs. Furthermore, advanced digital platforms and mobile applications have facilitated seamless communication between policyholders, claims adjusters, and insurance companies, thereby fostering transparency and efficiency throughout the claims lifecycle. Amidst this technological evolution, regulatory compliance remains paramount within the Insurance Claims Services Market. Operating within a complex regulatory framework designed to safeguard policyholders' interests and maintain financial stability, insurers are compelled to adhere to stringent standards pertaining to claims handling procedures, data privacy, consumer protection, and anti-fraud measures.
Market segmentation within the Insurance Claims Services Market reflects considerable diversity in terms of service offerings, target industries, and geographical regions. Key segments include property and casualty claims, healthcare claims, automotive claims, and life insurance claims. Each segment addresses specific needs within the insurance landscape, from assessing damages in property and casualty incidents to managing the adjudication and payment of medical claims in the healthcare sector. Looking ahead, the Insurance Claims Services Market is poised for sustained growth and innovation, driven by technological advancements, evolving consumer expectations, and regulatory developments. The adoption of digital solutions such as cloud-based claims management systems, predictive analytics, and blockchain technology is anticipated to enhance the efficiency, accuracy, and transparency of claims processing. Moreover, the increasing emphasis on customer-centricity and personalized service delivery is compelling insurers to invest in solutions prioritizing speed, convenience, and responsiveness in claims handling. As insurers endeavor to differentiate themselves in a competitive market environment, the quality of claims services is poised to emerge as a pivotal factor influencing customer loyalty and retention, underscoring the importance of continuous innovation and adaptation within the Insurance Claims Services Market.
Segmentation Analysis
By Type of Insurance
Life Insurance Claims encompass services geared towards facilitating the timely disbursement of death benefits to beneficiaries, ensuring financial support for the deceased's survivors. Motor Insurance Claims involve the settlement of claims arising from vehicle accidents, theft, vandalism, or mechanical failures, with claims adjusters playing a pivotal role in assessing damages and negotiating settlements. Property and Casualty Insurance Claims address damage or loss incurred due to events like natural disasters, accidents, theft, or vandalism, requiring efficient claims services to assess damages and facilitate reimbursement. Health Insurance Claims manage the adjudication and payment of medical claims, necessitating accurate processing, utilization review, and fraud detection to ensure fair reimbursement and cost containment.
By Insurance Providers
Examining the Insurance Claims Services Market through the lens of insurance providers unveils distinct operational dynamics. Insurance Companies, as primary stakeholders, handle claims internally, leveraging their resources and expertise to manage the claims process efficiently. Third-Party Administrators (TPAs) specialize in claims administration on behalf of insurers, offering expertise and scalability in managing claims across diverse portfolios. Specialized Claims Management Firms provide tailored solutions, catering to specific needs within the insurance landscape, from claims processing to fraud detection and mitigation.
By End User
Segmentation by end user sheds light on the diverse clientele served by the Insurance Claims Services Market. Individual Policyholders rely on claims services to navigate the claims process seamlessly, ensuring prompt resolution and fair compensation for covered losses. Commercial Policyholders, including businesses and organizations, require tailored claims solutions to address complex insurance portfolios and mitigate financial risks effectively. Government and Public Sector entities engage claims services to manage insurance programs and address claims arising from public initiatives, necessitating specialized expertise and compliance with regulatory requirements.
Segments:
By Type of Insurance
- Life Insurance Claims
- Motor Insurance Claims
- Others
- Property and Casualty Insurance Claims
- Health Insurance Claims
By Insurance Providers
- Insurance Companies
- Third-Party Administrators (TPAs)
- Specialized Claims Management Firms
By End User
- Individual Policyholders
- Commercial Policyholders
- Government and Public Sector
By Region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Market Drivers
Surge in Technological Advancements
The insurance sector is indeed experiencing a profound digital transformation, with claims services emerging as a focal point for innovation. For instance, technologies such as Artificial Intelligence (AI), automation, and data analytics are witnessing rapid adoption, revolutionizing traditional claims handling practices. AI-driven automation streamlines the claims process by automating tasks like document review, fraud detection, and initial claim assessment, leading to faster processing times and reduced operational costs. For example, in 2020, 54% of insurers reported using AI in claims processing. Data analytics plays a crucial role in improving claims accuracy by identifying fraudulent claims and ensuring fair and precise claim settlements. In fact, a recent Deloitte study found that 56% of North American insurance industry leaders are currently exploring ways to increase their investment in data analytics.
Rising Demand for Faster Claim Settlement
The modern insurance landscape is characterized by a growing expectation for expeditious and efficient claims settlement. Policyholders demand a seamless claims experience, prompting insurance companies to collaborate with claims service providers to accelerate the claims process and enhance customer satisfaction. This emphasis on speed and efficiency reflects the evolving needs of consumers in an increasingly fast-paced digital environment. For instance, during 2022-23, insurers have settled about 86% of the total number of claims registered in their books till March 31, 2023.
Growing Number of Insurance Claims
Several factors contribute to the escalating volume of insurance claims globally. The proliferation of property and vehicle ownership increases the exposure to risks, resulting in a higher frequency of accidents and damage claims. Additionally, the intensification of natural disasters due to climate change leads to more frequent and severe weather events, triggering a surge in natural disaster claims. Moreover, the expansion of insurance coverage, particularly in developing economies, has propelled an uptick in claims filed for various incidents, reflecting the increasing awareness and uptake of insurance products among diverse demographics.
Focus on Customer Experience
In today's competitive insurance landscape, delivering a superior claims experience is imperative for fostering customer retention and loyalty. Efficient claims services characterized by speed, transparency, and user-friendliness significantly enhance customer satisfaction. Insurers recognize the pivotal role of claims handling in shaping the overall perception of their brand and prioritize investments in technology and service enhancements to meet the evolving expectations of policyholders.
Regulatory Requirements
Stringent regulations surrounding data privacy and consumer protection underscore the importance of compliance within the Insurance Claims Services Market. Insurance companies rely on claims service providers with expertise in navigating regulatory complexities and ensuring adherence to regulatory standards. The evolving regulatory landscape necessitates continuous vigilance and adaptation to mitigate compliance risks and uphold the trust and confidence of policyholders and regulatory authorities alike. As regulations continue to evolve, collaboration between insurers and claims service providers remains essential to maintain compliance while delivering efficient and customer-centric claims services.
Market Trends
AI-powered claims automation:
With the advent of Artificial Intelligence (AI), tasks such as data entry, document verification, and initial claim triage are undergoing significant automation. For instance, in 2020, 54% of insurers reported using AI in claims processing. This advancement frees up human adjusters to concentrate on handling complex claims and providing more personalized service to policyholders. AI-driven automation not only expedites the claims process but also enhances accuracy and efficiency, ultimately improving the overall claims experience for both insurers and policyholders. By 2030, it’s estimated that 46 percent of current insurance claims and policy processing jobs in the United States will be displaced by automation.
Self-service claim portals:
Insurance companies are embracing self-service claim portals, offering user-friendly online platforms and mobile applications that empower policyholders to submit claims, upload supporting documents, and track their claim status in real-time. These self-service options not only enhance convenience for policyholders but also streamline the claims process, reducing administrative burdens for insurers. For example, a staggering 88% of customers expect brands to have an online self-service portal. By providing policyholders with greater autonomy and accessibility, insurers can foster stronger relationships and bolster customer satisfaction.
Big data and analytics for fraud detection:
Advanced data analytics play a pivotal role in combating insurance fraud by identifying patterns and anomalies in claims data. By leveraging big data analytics, insurers can detect fraudulent claims more efficiently, allowing for prompt intervention and cost reduction associated with fraudulent activities. This proactive approach to fraud detection not only safeguards insurers against financial losses but also helps maintain the integrity of the insurance system, benefitting honest policyholders in the process.
The rise of insurtech collaboration:
Insurance companies are increasingly collaborating with InsurTech startups specializing in claims automation, data analytics, and AI-powered solutions. This collaborative approach fosters innovation within the insurance industry, accelerating the adoption of cutting-edge technologies to enhance claims processing efficiency and customer experience. By leveraging the expertise of InsurTech partners, traditional insurers can stay ahead of the curve and remain competitive in a rapidly evolving market landscape.
Focus on preventative services:
In response to changing consumer demands and market dynamics, the insurance industry is shifting towards a more preventative approach. Claims service providers are expanding their offerings to include proactive services such as risk mitigation advice and property inspections. By empowering policyholders with tools and resources to prevent accidents and losses, insurers can mitigate risks, reduce claims frequency, and ultimately improve overall loss ratios. This preventative focus not only enhances customer satisfaction but also contributes to long-term cost savings for insurers.
Omnichannel claims experience:
To meet the diverse needs and preferences of policyholders, insurance companies are adopting an omnichannel approach to claims processing. Whether through online portals, mobile apps, phone, or in-person interactions, insurers are striving to deliver a seamless claims experience across various channels. This omnichannel approach allows policyholders to choose their preferred mode of communication and interaction, enhancing convenience and accessibility while ensuring consistent service delivery and communication throughout the claims lifecycle. By prioritizing omnichannel engagement, insurers can strengthen customer relationships and differentiate themselves in a competitive market landscape.
Market Restraints and Challenges
Data Security and Privacy Concerns:
The insurance claims process involves the handling of sensitive customer data, including financial information and details about the claim itself. Any compromise in data security or privacy can severely erode trust and result in regulatory fines. To address this challenge, insurers and claims service providers must implement robust cybersecurity measures and strictly adhere to data privacy regulations to safeguard customer information and maintain regulatory compliance.
Integration Challenges:
Integrating new technologies such as AI and automation with existing legacy systems within insurance companies poses significant challenges. The complexity and expense involved in system integration can slow down the adoption of innovative claims solutions. Overcoming these integration challenges requires careful planning, investment in interoperable systems, and collaboration between IT teams and business stakeholders to ensure seamless integration and minimize disruption to existing operations.
Lack of Standardization:
The lack of standardized data formats and processes across different insurance companies presents hurdles in seamless data exchange between insurers and claims service providers. This lack of standardization hinders efficiency and interoperability, leading to delays and inefficiencies in claims processing. Addressing this challenge requires industry-wide collaboration to establish common data standards and streamline processes, facilitating smoother data exchange and enhancing overall operational efficiency.
Skilled Workforce Shortage:
Implementing and managing new technologies in claims processing requires a skilled workforce with expertise in areas such as AI, data analytics, and cybersecurity. However, there is a shortage of talent with specialized skills in these domains, posing a significant challenge for claims service providers. Recruiting and retaining skilled professionals in a competitive labor market requires investment in training and development programs, as well as offering competitive compensation and career advancement opportunities to attract top talent.
Fraudulent Claims:
While AI holds promise in detecting fraudulent claims, completely eliminating fraud remains a challenge. Fraudsters continually evolve their tactics, making it imperative for insurers and claims service providers to continuously improve fraud detection methods and collaborate closely to combat fraudulent activities effectively. This ongoing effort requires investment in advanced analytics, machine learning algorithms, and proactive fraud prevention strategies to stay ahead of emerging threats and protect insurers and policyholders from financial losses.
Resistance to Change:
Some policyholders may be hesitant to embrace new technologies for claims processing, particularly if they lack digital literacy or have concerns about impersonal interactions. Overcoming resistance to change requires promoting transparency and education about the benefits of technological advancements in claims processing, such as improved efficiency, accuracy, and customer experience. Providing user-friendly interfaces, clear communication, and personalized support can help alleviate concerns and encourage broader adoption of innovative claims solutions among policyholders.
Key Players
- Oracle Corporation
- Hexaware Technologies Ltd
- HCL Technologies
- Pegasystems
- Accenture
- Avaya Inc
- Software AG
- International Business Machines Corporation
- Cognizant Technology Solutions Corp.
- DXC Technology Company
Recent Developments
In September 2023, Prudential Financial, Inc. forged a strategic partnership with EvolutionIQ, a technology company renowned for its artificial intelligence-driven platform. This collaboration aimed to bolster Prudential's disability claims ecosystem by integrating EvolutionIQ's advanced platform. With artificial intelligence assuming an increasingly pivotal role in modern business operations, the incorporation of this platform into Prudential's claims process signifies a significant advancement. EvolutionIQ utilizes proprietary, next-generation machine learning technology to furnish specialized insights, thereby facilitating the streamlining of the disability claims process.
In September 2023, Newgen Software and Coforge Limited, a global digital services and solutions provider, announced the elevation of their partnership to deliver transformative insurance lifecycle management solutions. These solutions encompass customer communications management (CCM) and document and content management (DCM) on a low code platform. This strategic move heralds a new era characterized by agility, customer-centricity, and operational efficiency for life and annuity (L&A) and property & casualty (P&C) insurers. By pooling their respective strengths, the companies are uniquely positioned to address the intricacies of the insurance domain across key markets including the US, UK, EMEA, and ANZ.
Regional Analysis
North America
North America dominates the global insurance claims services market, accounting for over 40% of the total market share. The United States is the primary driver of this dominance, boasting a mature insurance industry and a high adoption rate of advanced claims processing technologies. The region's well-established regulatory framework and the presence of major players, such as Crawford & Company, Sedgwick Claims Management Services, and Cunningham Lindsey, have contributed significantly to market growth. The increasing frequency of natural disasters and the adoption of digital transformation strategies by insurers have further fueled the demand for efficient claims services in North America.
Europe
Europe holds a substantial share of the insurance claims services market, capturing approximately 30% of the global revenue. Countries like the United Kingdom, Germany, and France have witnessed a surge in the adoption of claims services due to the presence of stringent regulations and the need for efficient claims processing. The region's focus on customer satisfaction and the integration of advanced technologies, such as artificial intelligence and data analytics, have driven market growth.
Asia Pacific
The Asia Pacific region is experiencing rapid growth in the insurance claims services market, with a market share of around 20%. Countries like China, Japan, and India are witnessing a surge in demand for claims services due to the expanding insurance penetration and the growing awareness of risk management. The region's vast population, coupled with the increasing urbanization and industrialization, has created a need for efficient claims processing solutions.
Latin America
Latin America accounts for a modest share of the insurance claims services market, estimated at around 6%. However, the region is anticipated to witness substantial growth in the coming years due to the rising adoption of insurance products and the increasing focus on customer experience. Countries like Brazil and Mexico are leading the way in adopting advanced claims services solutions, driven by the growing demand for efficient claims processing and the need to comply with regulatory requirements. The presence of favorable government initiatives and the increasing investments in technology are expected to drive market growth in the region.
Middle East and Africa
The Middle East and Africa region holds the smallest share of the insurance claims services market, accounting for approximately 4% of the global revenue. Limited insurance penetration, lack of awareness, and inadequate technological infrastructure have hindered market growth in this region. However, initiatives by governments and insurance companies to promote risk management practices and improve customer experience are expected to create growth opportunities in the future. Countries like the United Arab Emirates and South Africa are leading the way in adopting advanced claims services solutions, driven by the increasing demand for efficient claims processing and the need to comply with regulatory requirements.
Future Outlook
- Technological Advancements: Continued integration of AI, automation, and data analytics to enhance claims processing efficiency and accuracy.
- Customer-Centric Solutions: Focus on delivering personalized and seamless claims experiences to bolster customer satisfaction and loyalty.
- Regulatory Compliance: Heightened emphasis on adhering to evolving data privacy and consumer protection regulations to mitigate compliance risks.
- Collaborative Partnerships: Increased collaboration between insurers and technology providers to drive innovation and address industry challenges.
- Fraud Prevention: Continued investment in advanced analytics and fraud detection methods to combat fraudulent claims effectively.
- Data Security: Strengthening cybersecurity measures to safeguard sensitive customer data and maintain trust.
- Digital Transformation: Accelerated adoption of digital solutions for claims management, including self-service portals and mobile applications.
- Market Expansion: Opportunities for growth in emerging markets driven by increasing insurance penetration and demand for claims services.
- Enhanced Efficiency: Streamlining of claims processes through automation and optimization of workflows to reduce operational costs.
- Focus on Quality: Commitment to delivering high-quality claims services through continuous improvement and investment in talent and technology.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Insurance Claims Services Market between 2023 and 2032?
What factors are driving the growth of the Insurance Claims Services Market?
Who are the major players in the Insurance Claims Services Market?
How is the availability of Insurance Claims Services Market expanding, and through what channels?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Insurance Claims Services Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Insurance Claims Services Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 176,227.68 million → forecast year: USD 522,673.43 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Insurance Claims Services Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Insurance Claims Services Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Insurance Claims Services Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Insurance Claims Services Market Drivers
- 3.3 Insurance Claims Services Market Restraints & Challenges
- 3.4 Insurance Claims Services Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Insurance Claims Services Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Insurance Claims Services Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Insurance Claims Services category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Insurance Claims Services Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Insurance Claims Services Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Insurance Claims Services market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Insurance Claims Services Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Insurance Claims Services Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Insurance Claims Services Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Insurance Claims Services (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Insurance Claims Services Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Insurance Claims Services Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Insurance Claims Services Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Insurance Claims Services Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Insurance Claims Services Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Insurance Claims Services Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Insurance Claims Services Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Insurance Claims Services Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Insurance Claims Services Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
