
Market Overview
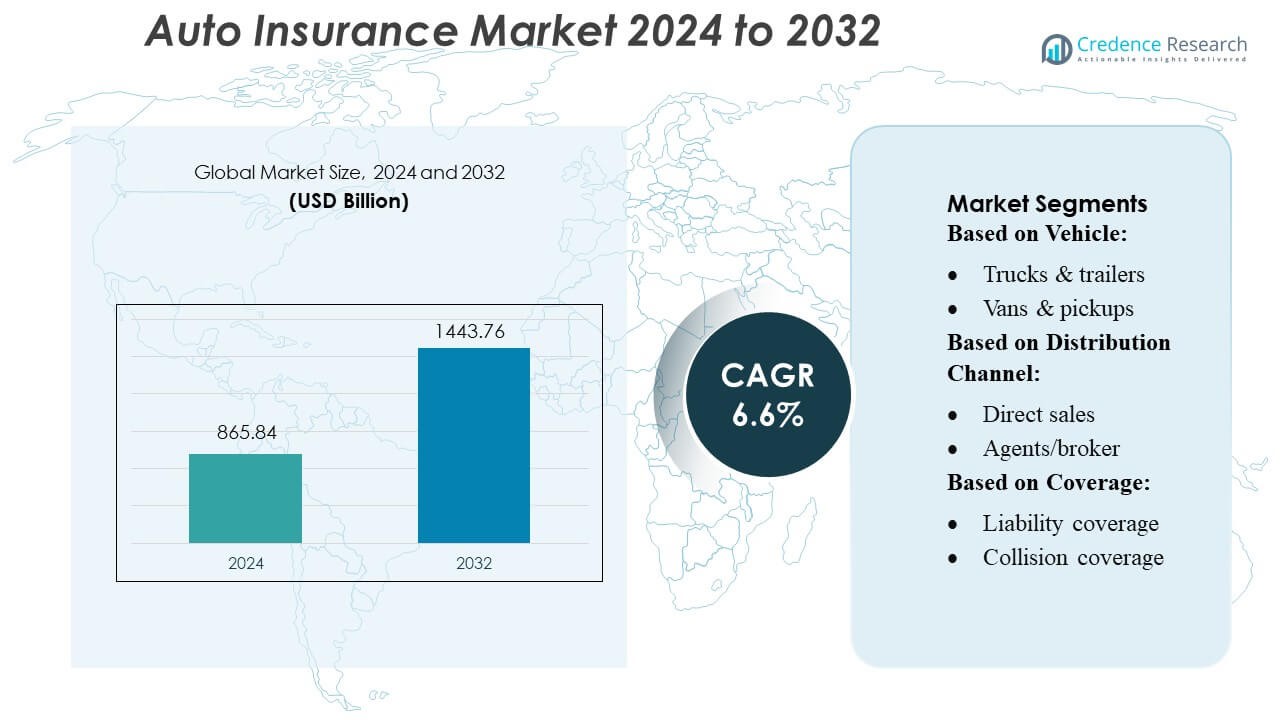
Auto Insurance Market size was valued USD 865.84 billion in 2024 and is anticipated to reach USD 1443.76 billion by 2032, at a CAGR of 6.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Auto Insurance Market Size 2024 | USD 865.84 Billion |
| Auto Insurance Market, CAGR | 6.6% |
| Auto Insurance Market Size 2032 | USD 1443.76 Billion |
The global auto-insurance market is dominated by a cohort of major players including State Farm, Progressive, GEICO (Berkshire Hathaway), Allstate, Liberty Mutual, Allianz, AXA, Zurich, Generali, and Ping An, all of whom leverage broad underwriting capacity, technology, and strong brand presence. Leading insurers like State Farm and Progressive command a significant share in the U.S., while Allianz, AXA, Zurich, and Generali bolster their reach in Europe and Asia. Regionally, North America leads the auto insurance market with about 35 %.
Market Insights
- The Auto Insurance Market reached USD 865.84 billion in 2024 and is projected to hit USD 1443.76 billion by 2032, expanding at a CAGR of 6.6% during the forecast period.
- Rising vehicle ownership, stricter road-safety regulations, and increasing adoption of telematics-based policies continue to drive steady premium growth across key markets.
- Usage-based insurance, AI-driven claims automation, and digital distribution channels are emerging as major trends, improving pricing accuracy and customer engagement.
- The market remains competitive, with State Farm, Progressive, GEICO, Allstate, Liberty Mutual, Allianz, AXA, Zurich, Generali, and Ping An strengthening their positions despite challenges such as rising claim costs and regulatory compliance pressures.
- North America holds the largest regional share at 35%, while the passenger-vehicle insurance segment maintains the highest contribution globally, supported by expanding urban mobility and increased demand for comprehensive coverage.
Market Segmentation Analysis:
By Vehicle
Trucks and trailers hold the dominant position in the auto insurance market, accounting for an estimated 38–42% share, driven by their extensive use in commercial logistics and higher exposure to operational risks. Vans and pickups follow, supported by rising SME adoption and last-mile delivery needs. Buses contribute moderately due to fleet-level insurance requirements in public and private transport networks. The “others” category-comprising passenger utility vehicles and specialized fleets-remains smaller but grows steadily with expanding industrial mobility and custom policy offerings targeting niche transportation activities.
- For instance, Chubb’s major-accounts team serves fleets with 500 or more vehicles, many of which include a significant portion of light commercial vans and pickups.
By Distribution Channel
Direct sales remain the leading distribution channel with an estimated 45–50% market share, driven by strong digital adoption, competitive pricing, and simplified online policy issuance. Agents and brokers maintain a significant share by serving customers requiring personalized consultation, particularly in commercial fleet insurance and high-value policies. Their advisory role supports higher conversion rates and tailored risk-assessment services. The dual-channel ecosystem continues to expand as insurers invest in digital onboarding tools, improving transparency and policy comparison efficiency while sustaining advisor-assisted models for complex coverage needs.
- For instance, Liberty Mutual reported that its direct sales and call-center channels are complemented by a partner network (specifically its Safeco independent agent network) that spans over 22,000 independent agencies.
By Coverage
Liability coverage dominates the segment with an estimated 40–45% share, supported by regulatory mandates and its essential role in covering third-party injury and property damage. Collision coverage follows, driven by rising accident rates and increasing vehicle repair costs. Comprehensive coverage gains traction owing to broader protection against theft, natural disasters, and non-collision events. Uninsured and underinsured motorist coverage show steady growth as insurers address rising concerns over inadequate coverage among road users, encouraging customers to adopt supplemental protection for financial risk mitigation.
Key Growth Drivers
- Rising Vehicle Ownership and Expanding Mobility Ecosystem
Increasing global vehicle ownership continues to fuel demand for auto insurance, particularly in emerging markets where rising incomes accelerate new car purchases. Growth in commercial mobility-ride-hailing fleets, logistics networks, and last-mile delivery operators-further expands the insured vehicle base. Insurers benefit from higher policy volumes and additional coverage requirements such as liability, collision, and commercial fleet protection. This expanding mobility ecosystem directly boosts premium revenue and strengthens long-term market growth.
- For instance, AXA Sigorta (AXA Turkey) developed a mobile telematics app called AXA GO and launched a pilot program with approximately 1,000 policyholders (the prompt mentions young drivers, but reports indicate it was offered to a tech-savvy focus group including young drivers).
- Advancements in Telematics and Usage-Based Insurance (UBI)
Rapid adoption of telematics devices and smartphone-based driving behavior analytics enhances underwriting accuracy and supports usage-based insurance models. Insurers leverage real-time data on braking patterns, mileage, and acceleration to personalize premiums and reduce risk exposure. This improves customer transparency, strengthens retention, and reduces claims frequency. As automotive IoT becomes mainstream, UBI policies accelerate market penetration by rewarding safe driving and enabling more precise risk segmentation across diverse customer groups.
- For instance, AIG’s global claims organization-which comprises more than 5,500 claims professionals-has been exploring the use of large language models and generative AI to streamline various internal processes, including claims handling.
- Government Regulations and Mandatory Insurance Policies
Strict regulatory frameworks and mandatory third-party liability insurance requirements significantly drive market expansion. Governments across many regions enforce compliance through digital monitoring systems, e-verification platforms, and automated penalty structures. These mechanisms increase policy penetration and curb uninsured vehicle rates. Additionally, regulatory incentives promoting digital claim processing and anti-fraud mechanisms strengthen insurer efficiency. Continuous regulatory modernization ensures steady demand and a stable revenue base for insurers operating in competitive and mature markets.
Key Trends & Opportunities
1. Digitalization and AI-Driven Claims Automation
Insurers increasingly deploy artificial intelligence, automated claims platforms, and digital self-service portals to improve operational efficiency and customer experience. AI-enabled image analytics, instant damage assessment, and automated approvals significantly reduce claim settlement time. This trend opens opportunities for insurers to scale digital-only policies, lower operational costs, and enhance fraud detection. The shift toward paperless, omnichannel customer engagement strengthens competitive positioning and attracts tech-savvy consumers seeking faster service.
- For instance, State Farm has filed numerous patents in AI, focusing on areas like generating 3D LIDAR-based models and mobility-profile analysis, and has also actively pursued patents in digitalization, including for edge-computing architectures to integrate telematics and personal data securely.
2. Growth of Electric Vehicles and Specialized Insurance Products
The global shift toward electric vehicles (EVs) presents new premium streams for insurers, driven by evolving risk profiles related to battery safety, repair costs, and charging infrastructure. EV-specific policies, extended warranty plans, and battery protection coverage create attractive growth avenues. As EV adoption accelerates across Asia, Europe, and North America, insurers can develop specialized underwriting models and partner with automakers to deliver bundled digital insurance products.
- For instance, Progressive’s Accident Response feature - built in collaboration with Cambridge Mobile Telematics - now serves over 1.5 million app users, using smartphone sensors and AI to automatically dispatch emergency services or initiate a claim following a detected collision.
3. Expansion of Embedded Insurance with Automotive OEMs
Automotive manufacturers increasingly integrate embedded insurance offerings directly into vehicle purchase and financing processes. This trend enables seamless policy onboarding, transparent pricing, and improved customer convenience. For insurers, partnerships with OEMs unlock access to large customer bases and real-time vehicle data that enhances underwriting precision. Embedded insurance solidifies long-term customer relationships and supports cross-selling opportunities across multiple coverage types.
Key Challenges
1. Rising Claims Costs and Repair Inflation
Increasing repair costs, driven by advanced vehicle components, expensive sensors, and complex electronics, continue to pressure insurer profitability. Labor shortages and supply-chain disruptions further inflate claims expenses and lengthen repair cycles. High medical costs and litigation trends in certain regions intensify liability claim burdens. Insurers must balance premium adjustments with market competitiveness while implementing predictive analytics to manage cost escalation and maintain sustainable margins.
2. Growing Exposure to Fraud and Cybersecurity Risks
Fraudulent claims, staged accidents, and identity manipulation pose significant challenges for insurers, contributing to substantial financial losses annually. As digital channels expand, cybersecurity vulnerabilities-including data breaches, system intrusions, and ransomware attacks-expose insurers to operational disruptions and reputational risks. Strengthening fraud-detection algorithms, enhancing verification protocols, and investing in robust cybersecurity frameworks are essential to mitigate these threats and maintain customer trust in digital insurance ecosystems.
Regional Analysis
North America
North America holds about 34% of the global auto insurance market, supported by high vehicle ownership, strict mandatory insurance laws, and a mature regulatory framework. The U.S. leads premium generation due to large insured vehicle fleets and strong adoption of telematics and usage-based insurance. Digital claims processing, AI-based pricing, and embedded insurance partnerships continue to strengthen competitiveness. The region’s stable economic environment and advanced distribution channels support steady premium growth and maintain its position as one of the most developed auto insurance markets globally.
Europe
Europe accounts for roughly 25–30% of the global market, driven by mandatory third-party liability requirements and high insurance penetration across major countries such as Germany, the UK, Italy, and France. Strong regulatory frameworks and advanced digital infrastructure support efficient claims management and pricing accuracy. European insurers increasingly adopt telematics, pay-as-you-drive models, and EV-specific products. The region’s well-organized automotive sector and rising electric vehicle sales continue to shape product innovation, ensuring consistent demand for both comprehensive and specialized auto insurance policies.
Asia-Pacific
Asia-Pacific contributes the largest share around 37–38% to the global auto insurance market, supported by rapid urbanization, rising disposable incomes, and expanding vehicle sales in China, India, Japan, and Southeast Asia. Governments are improving enforcement of motor insurance laws, which increases policy uptake. Digital platforms, online aggregators, and telematics adoption are accelerating distribution and underwriting efficiency. Growing demand for EVs and connected vehicles provides insurers opportunities to design customized coverage. The region’s large population and fast-growing mobility ecosystem continue to drive premium volume growth.
Latin America
Latin America represents about 3–4% of the global market, with growth driven by increasing vehicle ownership, gradual economic improvement, and stronger enforcement of compulsory motor insurance laws. Markets such as Brazil, Mexico, Argentina, and Chile lead regional premium generation. Digital insurers and online distribution channels are expanding access to low-cost policies. Although penetration remains lower than in mature markets, rising demand for financial protection and fleet insurance supports steady growth. The region presents long-term potential as insurance awareness and regulatory consistency improve.
Middle East & Africa
The Middle East & Africa region accounts for roughly 6–8% of the global auto insurance market. Demand increases with rising car ownership, expanding commercial fleets, and stricter implementation of mandatory vehicle insurance laws. Countries such as the UAE, Saudi Arabia, South Africa, and Egypt drive most premium activity. Digital underwriting and automated claims tools are gaining traction, and insurers are offering more tailored coverage for commercial transport and logistics. Although overall penetration is still developing, MEA offers significant growth potential due to regulatory modernization and expanding urban mobility.
Market Segmentations:
By Vehicle:
- Trucks & trailers
- Vans & pickups
By Distribution Channel:
- Direct sales
- Agents/broker
By Coverage:
- Liability coverage
- Collision coverage
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The auto insurance market features an intensely competitive landscape led by major global and regional insurers such as Chubb, Liberty Mutual Insurance, AXA, Bajaj Finserv, American International Group (AIG), State Farm Mutual Automobile Insurance Company, Progressive Casualty Insurance Company, Zurich Insurance Group, The Travelers Indemnity Company, and Allianz Group. The auto insurance market is highly competitive, characterized by a mix of global insurers, regional carriers, and emerging digital-first companies that continuously innovate to strengthen their market positions. Competition intensifies as insurers invest in advanced underwriting technologies, telematics-based pricing models, and AI-driven claims automation to enhance accuracy and reduce processing time. Digital distribution platforms, online aggregators, and embedded insurance offerings are reshaping customer acquisition strategies, while strong regulatory oversight ensures pricing discipline and compliance. As customer expectations shift toward personalized coverage, faster claim settlements, and transparent policy terms, insurers focus on product innovation, fraud prevention tools, and data-driven service models. This evolving competitive environment encourages continuous modernization, enabling insurers to differentiate through customer experience, technological capabilities, and scalable digital operations.
Key Player Analysis
- Chubb
- Liberty Mutual Insurance
- AXA
- Bajaj Finserv
- American International Group (AIG)
- State Farm Mutual Automobile Insurance Company
- Progressive Casualty Insurance Company
- Zurich Insurance Group
- The Travelers Indemnity Company
- Allianz Group
Recent Developments
- In December 2024, Bajaj Allianz General Insurance launched two new motor insurance: Eco Assure – Repair Protection and Named Driver Cover. These insurances provide comprehensive and customized coverage.
- In August 2024, ICICI Lombard launched the industry's first innovative "Smart Saver Plus" add-on for motor insurance policies. This insurance aims to address concerns of policyholders regarding prolonged turnaround times and the need for reliable repair quality by providing quality assurance, swift servicing, and customer convenience.
- In March 2024, Hub International (Hub) disclosed its acquisition of the assets of William R Cargill Insurance Agency, Inc (Cargill Insurance). Cargill Insurance is a family-owned, full-service insurance agency providing an array of personal coverage options, encompassing home, auto, personal umbrella, boat, and life insurance, alongside commercial and general liability insurance offerings.
Report Coverage
The research report offers an in-depth analysis based on Vehicle, Distribution Channel, Coverage and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will increasingly adopt telematics and driving-behavior analytics to enable more accurate and personalized premium pricing.
- Digital claims automation and AI-driven assessments will significantly shorten settlement cycles and improve customer satisfaction.
- Usage-based and pay-per-mile insurance models will expand as consumers seek flexible, cost-efficient coverage options.
- Electric and connected vehicles will drive demand for specialized policies tailored to battery risks, software failures, and advanced sensor repair costs.
- Embedded insurance partnerships with automakers and mobility platforms will become a mainstream distribution channel.
- Insurers will rely more on predictive analytics to reduce fraud, optimize underwriting, and enhance portfolio profitability.
- Growing adoption of autonomous driving technologies will reshape liability models and require new risk frameworks.
- Climate change and rising natural disasters will prompt insurers to refine risk pricing and strengthen catastrophe management strategies.
- Digital-only insurers and insurtechs will intensify competition by offering faster, more transparent policy experiences.
- Regulatory modernization will continue to promote compliance, data security, and greater transparency across insurance ecosystems.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Vehicle Ownership and Expanding Mobility Ecosystem
Increasing global vehicle ownership, especially in emerging markets, is expanding the insured vehicle base. Growth in commercial mobility and logistics further drives demand for diverse auto insurance products, boosting premium volumes.
Advancements in Telematics and Usage-Based Insurance
The adoption of telematics and smartphone-based driving analytics enables insurers to offer usage-based and behavior-based policies. This improves underwriting accuracy, personalizes premiums, and encourages safer driving, supporting market growth.
Government Regulations and Mandatory Insurance Policies
Strict regulatory frameworks and mandatory third-party liability insurance laws in many regions ensure high policy penetration. Digital enforcement and compliance measures further drive steady demand for auto insurance.
Digitalization and AI-Driven Claims Automation
Insurers are leveraging AI, automated claims platforms, and digital self-service portals to streamline operations and enhance customer experience. Faster claims processing and improved fraud detection attract tech-savvy consumers and improve retention.
Growth of Electric Vehicles and Specialized Insurance Products
The rise of electric vehicles introduces new risk profiles and coverage needs, prompting insurers to develop specialized policies. This creates new premium streams and opportunities for product innovation as EV adoption accelerates globally.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Auto Insurance Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Auto Insurance Market projected to grow between 2025 and 2032?
Which Auto Insurance Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Auto Insurance Market?
Who are the leading companies in the Auto Insurance Market?
Which region commanded the largest share of the Auto Insurance Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Vehicle
- 1.2.1 Trucks & trailers
- 1.2.2 Vans & pickups
- 1.2.3 Buses
- 1.2.4 Passenger utility vehicles
- 1.2.5 Specialized fleets
- 1.3 By Coverage
- 1.3.1 Liability coverage
- 1.3.2 Collision coverage
- 1.3.3 Comprehensive coverage
- 1.3.4 Uninsured/underinsured motorist coverage
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 865.84 billion → 2032: USD 1443.76 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Auto Insurance Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Auto Insurance Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Auto Insurance Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Auto Insurance Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Auto Insurance Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Auto Insurance Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Auto Insurance Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Auto Insurance Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 865.84 billion → 2032: USD 1443.76 billion)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Auto Insurance Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Vehicle - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Trucks & trailers
- 12.3.6.2 Vans & pickups
- 12.3.6.3 Buses
- 12.3.6.4 Passenger utility vehicles
- 12.3.6.5 Specialized fleets
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Coverage - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Liability coverage
- 12.4.6.2 Collision coverage
- 12.4.6.3 Comprehensive coverage
- 12.4.6.4 Uninsured/underinsured motorist coverage
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Auto Insurance Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Auto Insurance Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2024-2032
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Auto Insurance Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 State Farm
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Progressive
- 17.4 GEICO (Berkshire Hathaway)
- 17.5 Allstate
- 17.6 Liberty Mutual
- 17.7 Allianz
- 17.8 AXA
- 17.9 Zurich Insurance Group
- 17.10 Generali
- 17.11 Ping An
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

