
Market Overview
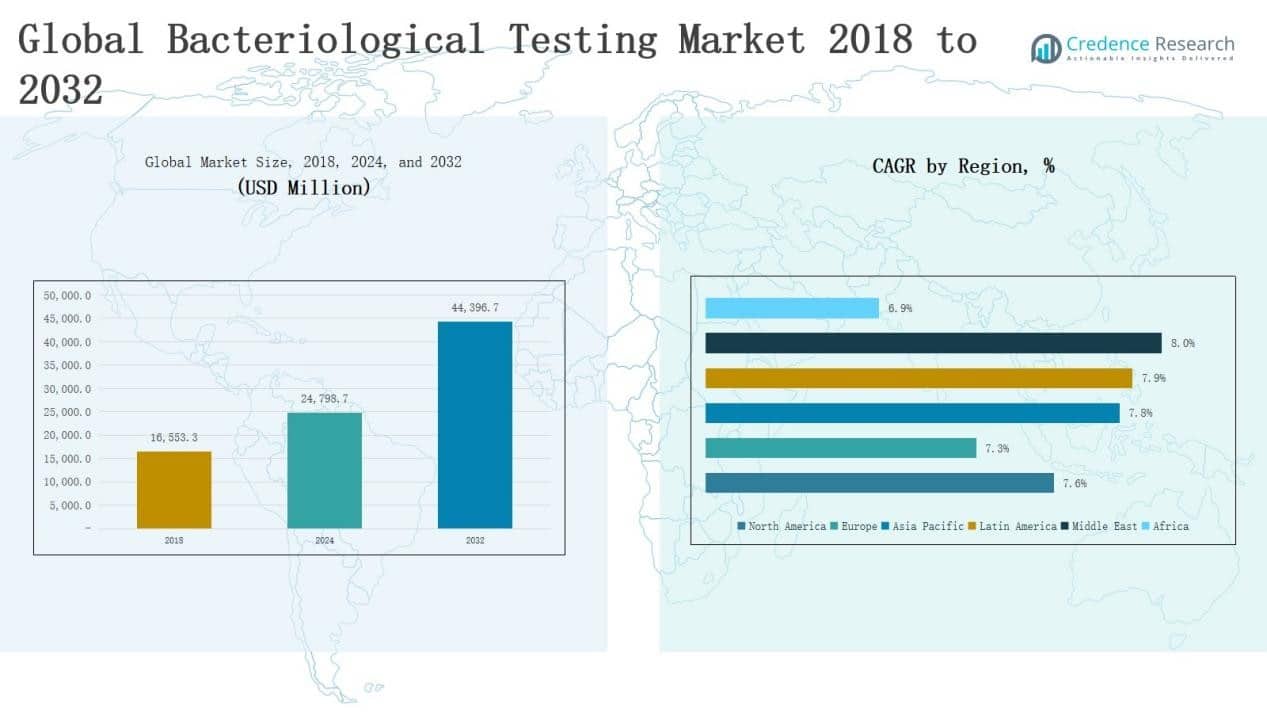
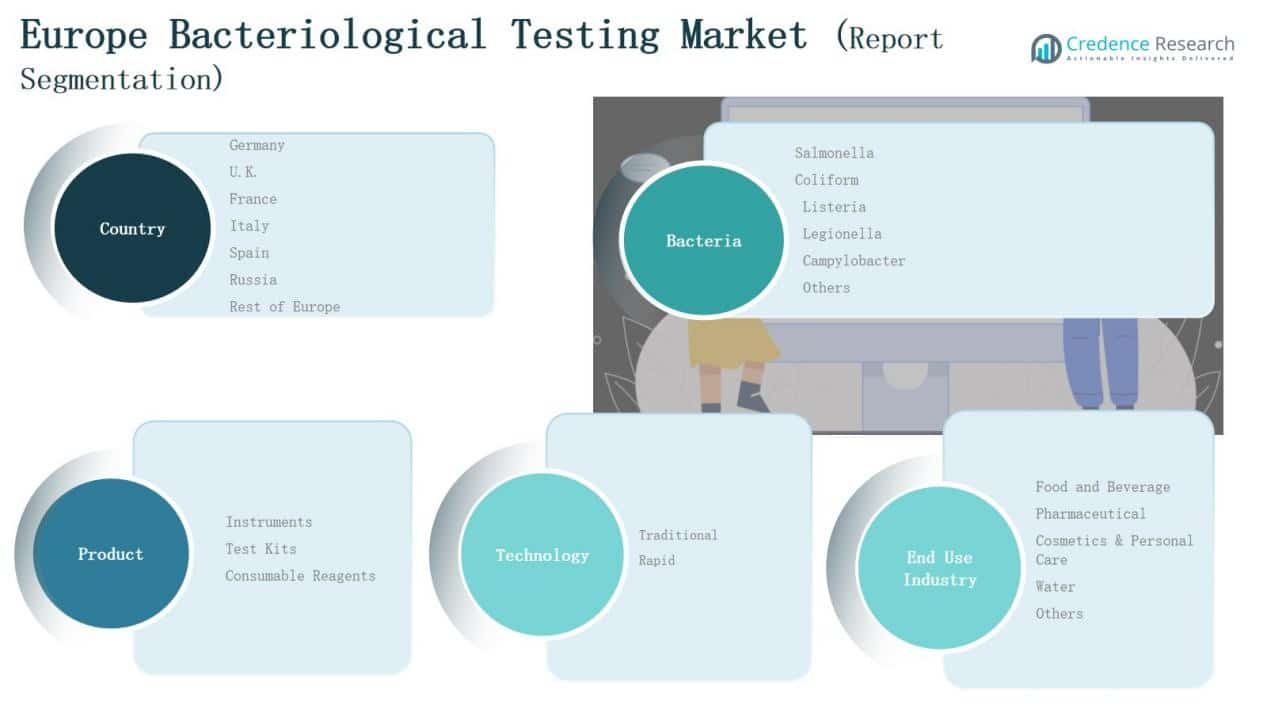
The Global Bacteriological Testing Market size was valued at USD 16,553.3 million in 2018, rising to USD 24,798.7 million in 2024, and is anticipated to reach USD 44,396.7 million by 2032, at a CAGR of 7.61% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Bacteriological Testing Market Size 2024 | USD 24,798.7 Million |
| Bacteriological Testing Market, CAGR | 7.61% |
| Bacteriological Testing Market Size 2032 | USD 44,396.7 Million |
The Global Bacteriological Testing Market is shaped by strong competition among multinational leaders and regional specialists. Major players include Thermo Fisher Scientific Inc., Eurofins, Agilent Technologies Inc., Bio-Rad Laboratories Inc., Merck KGaA, Intertek, Neogen Corporation, BioMerieux, ALS Ltd., Symbio Labs, Alfa Chemistry, and Vimta Labs. These companies drive growth through advanced testing instruments, rapid diagnostic kits, automation, and compliance-driven services tailored for food, pharmaceutical, and water industries. Asia Pacific emerged as the leading region in 2024, holding 35% of the global share, supported by its expanding food processing base, pharmaceutical manufacturing, and regulatory initiatives.
Market Insights
- The Global Bacteriological Testing Market grew from USD 16,553.3 million in 2018 to USD 24,798.7 million in 2024, and is projected at USD 44,396.7 million by 2032, expanding at a 61% CAGR.
- Instruments led with 42% share in 2024, supported by automation and advanced laboratory use, while test kits held 34% and consumable reagents accounted for 24%, driven by recurring demand.
- Salmonella testing dominated with 29% share in 2024, followed by Coliform at 22% and Listeria at 18%, reflecting strict regulations and increasing foodborne illness concerns.
- Rapid technology commanded 63% share in 2024, driven by demand for faster results across food, pharmaceutical, and water industries, while traditional testing retained 37% for confirmatory diagnostics.
- Asia Pacific led with 35% share in 2024, followed by North America at 27% and Europe at 22%, highlighting strong growth in food processing, pharmaceutical production, and regulatory compliance.
Market Segment Insights
By Product
Instruments dominate the global bacteriological testing market with a 42% revenue share in 2024, supported by automation, advanced detection technologies, and widespread adoption in laboratories. Their accuracy and ability to handle high testing volumes strengthen their market leadership. Test kits hold 34% share, driven by rising demand for user-friendly and rapid detection tools across food and healthcare applications. Consumable reagents account for 24% share, fueled by their recurring use in testing processes, ensuring consistent demand and revenue stability.
- For instance, Thermo Fisher Scientific launched the Applied Biosystems QuantStudio 7 Pro Dx Real-Time PCR System, designed to deliver high-throughput bacterial pathogen detection for clinical labs.
By Bacteria
Salmonella remains the leading bacteria segment with a 29% market share in 2024, driven by rising global foodborne illness cases and mandatory testing in poultry and meat industries. Coliform testing captures 22% share, widely used in water and beverage industries to ensure public health safety. Listeria represents 18% share, supported by stringent monitoring in dairy and processed food products. Legionella and Campylobacter together contribute 23% share, while others account for 8%, addressing specific regional and industrial requirements.
- For instance, Neogen Corporation launched its Reveal 3-D for Salmonella test designed for rapid on-site detection in poultry and meat, streamlining mandatory food safety testing.
By Technology
Rapid technology leads the market with a 63% share in 2024, reflecting demand for faster, reliable results in food safety, pharmaceutical, and water testing applications. Its adoption is encouraged by growing regulatory pressure to minimize contamination risks and enhance testing efficiency. Traditional technology, holding a 37% share,
continues to serve laboratories requiring confirmatory diagnostics and research precision. Although slower, it remains valued for accuracy in established testing environments, particularly in academic, government, and resource-limited regions where cost-efficiency is critical.
Key Growth Drivers
Rising Food Safety Concerns
Foodborne illnesses continue to rise globally, making bacteriological testing a critical requirement for food and beverage industries. Governments and regulatory bodies enforce stringent standards, particularly for Salmonella, Listeria, and Coliform detection, to reduce contamination risks. Growing consumer awareness of food safety further pushes manufacturers to invest in advanced testing technologies. The increasing volume of processed and packaged foods worldwide also creates strong demand for rapid, accurate bacteriological tests, establishing food safety regulations as a primary growth driver for the market.
- For instance, 3M Food Safety expanded its molecular detection system to cover Salmonella, enabling faster pathogen testing workflows for food producers.
Expanding Pharmaceutical and Healthcare Applications
The pharmaceutical sector heavily relies on bacteriological testing to ensure product safety, sterility, and compliance with global health regulations. Rising production of biologics, vaccines, and injectable drugs increases the demand for microbial quality control. Healthcare settings also emphasize bacterial testing to minimize risks of hospital-acquired infections and support patient safety. The global rise in antibiotic resistance further highlights the importance of routine bacteriological testing in healthcare. This expanding application base strengthens market growth by driving adoption of both rapid and traditional testing solutions.
- For instance, Mayo Clinic Laboratories has implemented advanced bacterial typing by whole genome sequencing to monitor and mitigate outbreaks of methicillin-resistant Staphylococcus aureus (MRSA) in neonatal intensive care units, helping to identify carriers and prevent infection spread from 2014 to 2017.
Advancements in Testing Technologies
Innovations in testing methods, including automation, molecular diagnostics, and biosensor-based solutions, have significantly improved efficiency and reliability. Rapid testing technologies now dominate due to their ability to deliver accurate results within hours rather than days. Automation reduces human error while supporting large-scale testing in industries such as food processing, pharmaceuticals, and water treatment. Continuous R&D investments from major players also foster integration of AI and digital platforms for real-time monitoring. These technological advancements remain a key driver, fueling market expansion and wider adoption.
Key Trends & Opportunities
Shift Toward Rapid Testing Solutions
The global market is witnessing a clear shift toward rapid bacteriological testing, which accounted for over 60% of the market share in 2024. Industries prefer these solutions for faster turnaround, regulatory compliance, and efficiency in high-volume testing. The trend aligns with the growing need for real-time monitoring in food and pharmaceutical supply chains. Portable and easy-to-use rapid kits are also enabling testing in remote or resource-limited areas. This ongoing transition creates opportunities for innovation and adoption of next-generation diagnostic platforms.
- For instance, the QuickMIC system from Gradientech received FDA Breakthrough Device Designation. It uses a microfluidic approach for antibiotic susceptibility testing, providing precise minimum inhibitory concentration values to optimize patient dosing and accelerate testing turnaround.
Emergence of Digital and Automated Platforms
Integration of digital solutions, robotics, and AI into bacteriological testing workflows is creating new opportunities. Automated systems enhance accuracy, reduce manpower costs, and enable continuous monitoring across industrial and healthcare applications. Cloud-based data platforms support traceability and regulatory reporting, making them attractive for compliance-driven industries. As industries expand globally, the demand for harmonized, digitally connected testing infrastructure grows. This trend fosters collaboration between diagnostic companies and technology providers, opening avenues for innovative product development and market penetration.
- For instance, BD (Becton, Dickinson and Company) introduced the BD Kiestra™ IdentifA, an automated preparation system linked to AI-enabled MALDI-TOF workflows, reducing manual interventions in bacteriology testing and enhancing throughput in hospital laboratories.
Key Challenges
High Cost of Advanced Testing Solutions
Despite their benefits, advanced bacteriological testing technologies involve high capital and operational costs. Instruments and automated platforms require significant upfront investment, making adoption difficult for small and medium enterprises. Consumables and reagents add recurring expenses, creating cost barriers in developing regions. While rapid tests promise efficiency, their affordability remains a concern. Limited budgets in public health and small-scale food producers further restrict widespread adoption. Addressing cost-effectiveness will be crucial for expanding the market reach across all industry verticals.
Shortage of Skilled Professionals
Bacteriological testing requires trained professionals capable of operating advanced instruments and interpreting results accurately. However, many developing regions face a shortage of qualified microbiologists and lab technicians. The lack of expertise hinders adoption of modern technologies and slows down testing efficiency. Even with automation, professional oversight remains essential for confirmatory diagnostics and compliance reporting. Bridging the skills gap through training programs, academic collaborations, and industry initiatives is vital for sustaining growth and ensuring consistent quality outcomes in testing processes.
Regulatory and Standardization Barriers
The bacteriological testing market operates under diverse regulatory frameworks that vary across regions, creating compliance challenges. Harmonizing global standards remains complex, as countries enforce different testing requirements for food, pharmaceuticals, and water. Delays in regulatory approvals can restrict the launch of innovative technologies, slowing adoption. Inconsistent regulations also pose difficulties for companies aiming for global market expansion. Addressing these barriers through international collaborations, standardized protocols, and supportive regulatory environments is critical for unlocking the full potential of market growth.
Regional Analysis
North America
North America accounted for 27% of the global market in 2024, with revenue rising from USD 4,538.93 million in 2018 to USD 6,776.44 million in 2024, and projected to reach USD 12,075.90 million by 2032 at a CAGR of 7.6%. The region benefits from stringent food safety regulations, advanced healthcare infrastructure, and strong pharmaceutical production. The U.S. dominates due to large-scale adoption of rapid testing technologies and robust R&D activities. Rising demand for compliance-driven solutions in Canada and Mexico further strengthens North America’s leadership in the global bacteriological testing market.
Europe
Europe represented 22% of the global market in 2024, growing from USD 3,659.94 million in 2018 to USD 5,375.66 million in 2024, and expected to reach USD 9,367.70 million by 2032, at a CAGR of 7.3%. Strong regulatory frameworks, especially in Germany, France, and the UK, drive testing adoption across food, beverage, and water industries. The region’s advanced laboratory infrastructure and emphasis on product traceability support continued market expansion. Demand for rapid testing kits is accelerating as manufacturers aim to meet EU food safety directives, while pharmaceutical and cosmetic industries add further growth momentum.
Asia Pacific
Asia Pacific held the 35% share in 2024, making it the largest regional market. Revenues increased from USD 5,757.25 million in 2018 to USD 8,719.59 million in 2024, and are projected to reach USD 15,836.30 million by 2032, reflecting a CAGR of 7.8%. Growth is fueled by rapid urbanization, rising food consumption, and increasing government focus on food safety and healthcare quality. China, Japan, and India dominate demand with strong pharmaceutical industries and large food processing bases. Expanding water quality monitoring and growing adoption of rapid testing technologies further reinforce the region’s leadership position.
Latin America
Latin America contributed 9% of the market in 2024, with revenue rising from USD 1,474.90 million in 2018 to USD 2,240.39 million in 2024, and projected at USD 4,084.50 million by 2032, at a CAGR of 7.9%. Brazil leads the region, supported by its large food and beverage industry and expanding healthcare sector. Growing government investments in food safety testing and water quality assessments are driving demand. Rising adoption of rapid diagnostic kits and increased focus on export-oriented food industries are expected to accelerate growth, strengthening Latin America’s emerging role in the global bacteriological testing market.
Middle East
The Middle East accounted for 5% of the global market in 2024, with revenue increasing from USD 791.25 million in 2018 to USD 1,209.82 million in 2024, and expected to reach USD 2,224.27 million by 2032, growing at a CAGR of 8.0%, the highest among all regions. GCC countries dominate demand due to strong investments in food safety, water testing, and healthcare. The region’s rising dependence on imported food products and increasing regulatory enforcement drive adoption of rapid testing methods. Partnerships with global diagnostic companies further support technological advancement and market penetration.
Africa
Africa held 2% of the market in 2024, with revenue expanding from USD 331.07 million in 2018 to USD 476.84 million in 2024, and projected to reach USD 808.02 million by 2032, at a CAGR of 6.9%. Growth is supported by rising awareness of foodborne diseases, increasing healthcare investments, and international aid programs promoting water quality testing. South Africa remains the key contributor, followed by Egypt, while other regions are gradually adopting testing technologies. Limited infrastructure and high costs pose challenges, yet opportunities exist in portable rapid kits that provide accessible solutions for resource-constrained settings.
Market Segmentations:
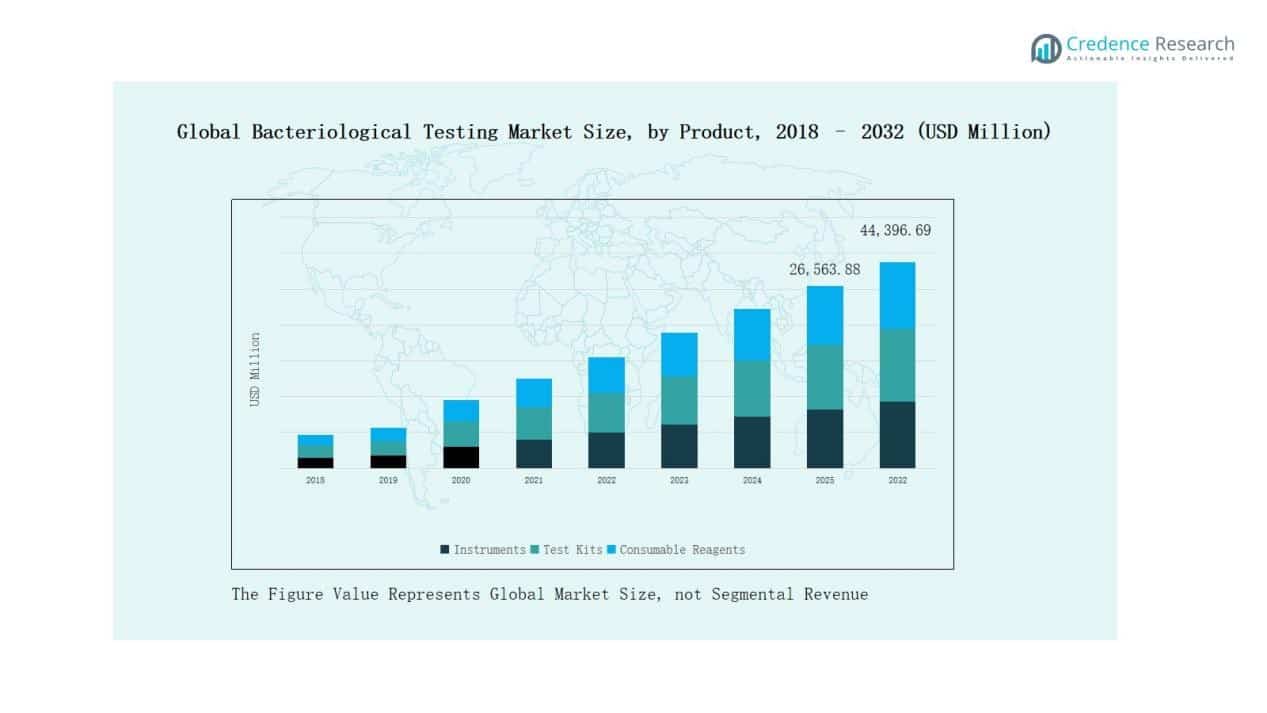
By Product
- Instruments
- Test Kits
- Consumable Reagents
By Bacteria
- Salmonella
- Coliform
- Listeria
- Legionella
- Campylobacter
- Others
By Technology
- Traditional
- Rapid
By End User
- Food and Beverage
- Pharmaceutical
- Cosmetics & Personal Care
- Water
- Others
By Region
- North America (U.S., Canada, Mexico)
- Europe (UK, France, Germany, Italy, Spain, Russia, Rest of Europe)
- Asia Pacific (China, Japan, South Korea, India, Australia, Southeast Asia, Rest of Asia Pacific)
- Latin America (Brazil, Argentina, Rest of Latin America)
- Middle East (GCC Countries, Israel, Turkey, Rest of Middle East)
- Africa (South Africa, Egypt, Rest of Africa)
Competitive Landscape
The global bacteriological testing market is highly competitive, characterized by the presence of multinational corporations and specialized regional players. Leading companies such as Thermo Fisher Scientific Inc., Eurofins, Agilent Technologies Inc., Bio-Rad Laboratories Inc., Merck KGaA, Intertek, Neogen Corporation, and BioMerieux dominate through extensive product portfolios, advanced technologies, and strong global distribution networks. These players focus on innovation, automation, and rapid testing platforms to meet regulatory standards across industries including food, pharmaceuticals, and water. Regional firms like ALS Ltd., Symbio Labs, Alfa Chemistry, and Vimta Labs strengthen their positions by offering cost-effective solutions tailored to local markets. Strategic initiatives such as mergers, acquisitions, and partnerships are common, enabling companies to expand their geographic reach and technological capabilities. Continuous investment in R&D, integration of digital platforms, and compliance-driven services remain central to competitive differentiation, shaping the market’s dynamic landscape and driving long-term growth opportunities.
Key Players
- ALS Ltd
- Thermo Fisher Scientific Inc.
- Eurofins
- Agilent Technologies Inc.
- Bio-Rad Laboratories Inc.
- Intertek
- Merck KGaA
- Neogen Corporation
- Vimta Labs
- BioMerieux
- Symbio Labs
- Alfa Chemistry
- Other Key Players
Recent Developments
- In June 2025, bioMérieux acquired Day Zero Diagnostics’ assets to enhance sequencing and ML-based diagnostic tools.
- In September 2025, LuminUltra Technologies Ltd. acquired GL Biocontrol to strengthen its European water diagnostics portfolio.
- In February 2025, Biolog, Inc. purchased Anaerobe Systems, Inc., adding anaerobic bacterial culture media to its expertise.
- In early 2025, Mérieux NutriSciences completed the acquisition of Bureau Veritas’ food testing business across Canada, the U.S., and other regions.
Report Coverage
The research report offers an in-depth analysis based on Product, Bacteria, Technology, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for rapid testing methods will continue to expand across industries.
- Food safety regulations will drive increased adoption of advanced testing solutions.
- Pharmaceutical and healthcare applications will remain major growth contributors.
- Integration of automation and digital platforms will improve testing efficiency.
- Emerging economies will witness accelerated adoption due to rising awareness.
- Portable and user-friendly test kits will gain popularity in resource-limited regions.
- Strategic partnerships will enhance global reach and product innovation.
- Water quality monitoring will create new opportunities for market players.
- R&D investments will strengthen technological advancement and product pipelines.
- Competition between multinational leaders and regional firms will intensify further.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Food Safety Regulations
Governments and regulatory bodies worldwide are enforcing stricter standards for food safety, particularly targeting pathogens like Salmonella, Listeria, and Coliform. This regulatory pressure compels food and beverage manufacturers to adopt advanced bacteriological testing solutions to ensure compliance and minimize contamination risks.
Expansion of Pharmaceutical and Healthcare Applications
The pharmaceutical industry relies heavily on bacteriological testing to ensure product sterility and safety, especially with the rise in biologics and injectable drugs. Healthcare settings also require routine bacterial testing to prevent hospital-acquired infections and monitor antibiotic resistance, driving market growth.
Advancements in Rapid and Automated Testing Technologies
Innovations such as molecular diagnostics, automation, and biosensor-based solutions have made bacteriological testing faster, more accurate, and scalable. The adoption of rapid testing technologies is particularly strong in industries requiring high-throughput and real-time results, fueling overall market expansion.
Rising Incidence of Foodborne Illnesses and Public Awareness
Increasing global cases of foodborne diseases have heightened consumer and industry awareness about food safety. This has led to greater demand for reliable and efficient bacteriological testing across food processing, water, and healthcare sectors.
Growth in Processed Food and Water Quality Monitoring
The surge in processed and packaged food consumption, along with expanding water quality monitoring initiatives, especially in emerging economies, is creating sustained demand for bacteriological testing. These trends are further supported by government investments and international aid programs focused on public health.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Bacteriological Testing Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Bacteriological Testing Market projected to grow between 2025 and 2032?
Which Global Bacteriological Testing Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Bacteriological Testing Market?
Who are the leading companies in the Global Bacteriological Testing Market?
Which region commanded the largest share of the Global Bacteriological Testing Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Instruments
- 1.2.2 Test Kits
- 1.2.3 Consumable Reagents
- 1.3 By Bacteria
- 1.3.1 Salmonella
- 1.3.2 Coliform
- 1.3.3 Listeria
- 1.3.4 Legionella
- 1.3.5 Campylobacter
- 1.3.6 Others
- 1.4 By End User
- 1.4.1 Food and Beverage
- 1.4.2 Pharmaceutical
- 1.4.3 Cosmetics & Personal Care
- 1.4.4 Water
- 1.4.5 Others
- 1.5 By Technology
- 1.5.1 Traditional
- 1.5.2 Rapid
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 24,798.7 million → 2032: USD 44,396.7 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Bacteriological Testing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Bacteriological Testing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Bacteriological Testing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Bacteriological Testing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Bacteriological Testing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Bacteriological Testing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Bacteriological Testing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Bacteriological Testing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 24,798.7 million → 2032: USD 44,396.7 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Bacteriological Testing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Instruments
- 12.3.7.2 Test Kits
- 12.3.7.3 Consumable Reagents
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Bacteria - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Salmonella
- 12.4.7.2 Coliform
- 12.4.7.3 Listeria
- 12.4.7.4 Legionella
- 12.4.7.5 Campylobacter
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End User - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Food and Beverage
- 12.5.7.2 Pharmaceutical
- 12.5.7.3 Cosmetics & Personal Care
- 12.5.7.4 Water
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Technology - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Traditional
- 12.6.7.2 Rapid
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Bacteriological Testing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Bacteriological Testing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Bacteriological Testing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Bacteriological Testing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Thermo Fisher Scientific Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Eurofins
- 18.4 Agilent Technologies Inc.
- 18.5 Bio-Rad Laboratories Inc.
- 18.6 Merck KGaA
- 18.7 Intertek
- 18.8 Neogen Corporation
- 18.9 BioMerieux
- 18.10 ALS Ltd.
- 18.11 Vimta Labs
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

