
Market Overview
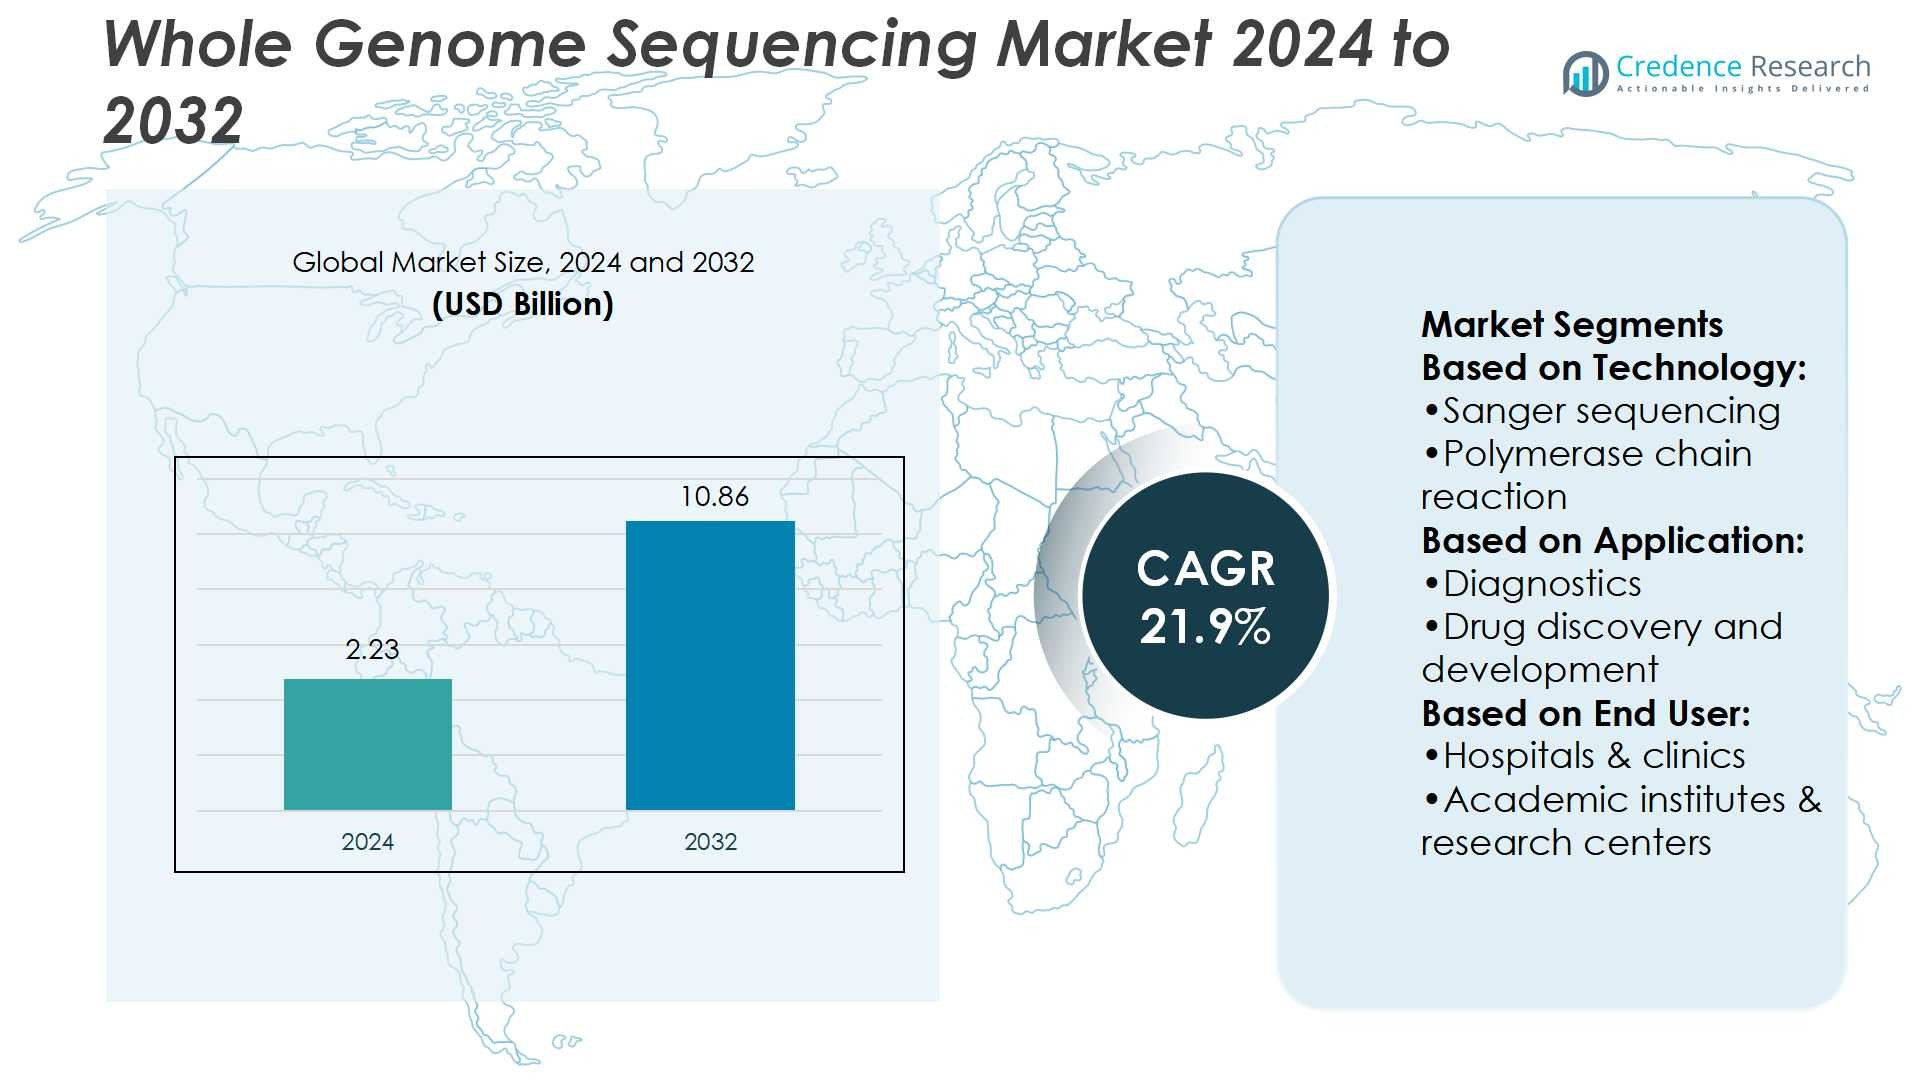
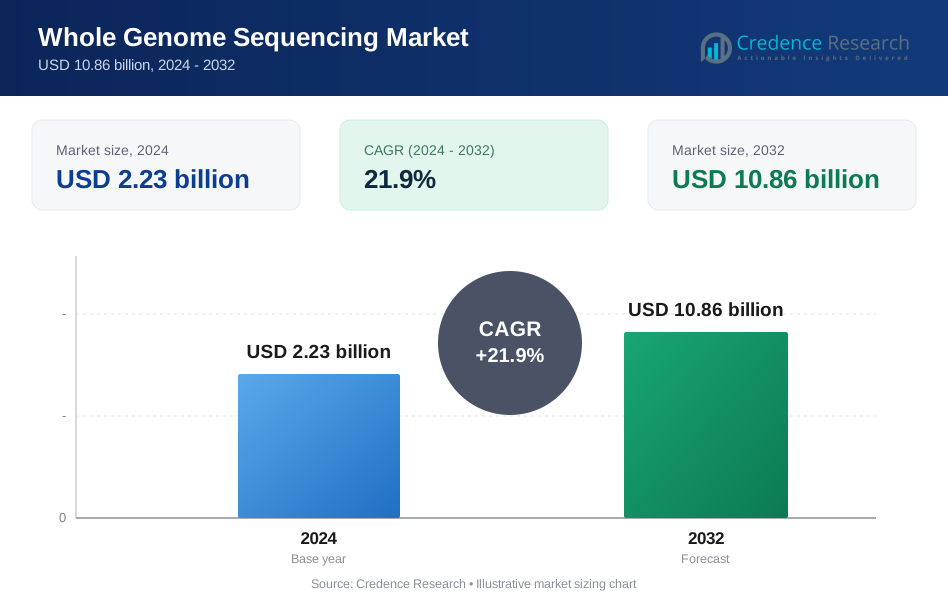
Whole Genome Sequencing Market size was valued USD 2.23 billion in 2024 and is anticipated to reach USD 10.86 billion by 2032, at a CAGR of 21.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Whole Genome Sequencing Market Size 2024 | USD 2.23 Billion |
| Whole Genome Sequencing Market, CAGR | 21.9% |
| Whole Genome Sequencing Market Size 2032 | USD 10.86 Billion |
The whole genome sequencing market features strong competition among major players such as Illumina, Inc., Thermo Fisher Scientific, Inc., Danaher Corporation, QIAGEN N.V., Merck KGaA, Eurofins Scientific, Siemens Healthineers, Macrogens, Inc., Bio-Rad Laboratories, Inc., and Agilent Technologies, Inc. These companies focus on advancing sequencing platforms, bioinformatics integration, and service expansion to strengthen global reach. Illumina and Thermo Fisher lead in high-throughput sequencing technologies, while Eurofins and Macrogens specialize in service-based genomics. Strategic investments, collaborations, and acquisitions remain central to market growth. North America emerges as the leading region, holding a 38% market share in 2024, supported by advanced healthcare infrastructure, large-scale genomics initiatives, and early adoption of precision medicine.
Market Insights
- The whole genome sequencing market size was USD 2.23 billion in 2024 and is projected to reach USD 10.86 billion by 2032, growing at a CAGR of 21.9% during the forecast period.
- Rising demand for precision medicine and integration of sequencing in oncology and rare disease diagnostics drive strong market growth, supported by declining costs and expanding clinical applications.
- Increasing adoption of AI-driven bioinformatics and cloud-based platforms for genomic data analysis marks a key trend, while large-scale population genomics initiatives enhance long-term opportunities.
- The market is highly competitive, with Illumina, Thermo Fisher, Danaher, QIAGEN, Merck KGaA, Eurofins, Siemens Healthineers, Macrogens, Bio-Rad, and Agilent Technologies focusing on innovation, service expansion, and strategic collaborations.
- North America leads with a 38% market share in 2024, driven by advanced infrastructure and genomics programs, while next-generation sequencing dominates the technology segment, holding the largest share due to its high throughput and efficiency.
Market Segmentation Analysis:
By Technology
Next-generation sequencing (NGS) dominates the whole genome sequencing market with the largest share. Its ability to deliver high-throughput, cost-efficient, and precise genomic data positions it as the leading technology. NGS supports broad clinical and research applications, driving demand from diagnostics to drug discovery. Continuous improvements in sequencing speed, scalability, and analytical tools further strengthen adoption. In contrast, traditional methods such as Sanger sequencing and PCR maintain niche use in validation and targeted analysis, but the efficiency of NGS remains the primary growth driver.
- For instance, QIAGEN N.V. expanded its sequencing solutions with the QIAseq Multimodal Panels, which combine DNA and RNA analysis in a single workflow. These panels provide more than 95% uniformity across target regions.
By Application
Diagnostics holds the largest share in applications, driven by the growing role of genomics in personalized healthcare. Whole genome sequencing enables early detection of genetic disorders, cancer profiling, and infectious disease monitoring. Precision medicine and targeted therapies increasingly rely on genomic insights, which reinforces adoption in diagnostics. While drug discovery and precision medicine also record steady uptake, the demand for timely, accurate, and actionable diagnostic insights ensures this segment’s continued leadership, supported by hospitals and testing centers adopting sequencing for routine clinical use.
- For instance, Eurofins offers a human whole genome sequencing (WGS) service using Illumina NovaSeq 6000 or Xplus with paired-end 2×150 base-pair reads, delivering approximately 90 gigabases raw data per sample for 30× coverage.
By End-user
Hospitals and clinics represent the dominant end-user segment, holding the highest share in the market. Their leadership stems from rising integration of genomic sequencing in patient care, particularly for oncology and rare diseases. Clinical demand for actionable results and growing partnerships with sequencing technology providers drive this segment’s strength. Academic institutes and research centers follow, supported by government funding and collaborations, while pharmaceutical and biotechnology companies leverage sequencing for drug pipelines. However, the consistent clinical demand in hospitals ensures their continued dominance in adoption and utilization.
Key Growth Drivers
Rising Demand for Precision Medicine
The growing emphasis on precision medicine is a major driver of the whole genome sequencing market. Healthcare providers increasingly use sequencing to tailor treatment plans, particularly in oncology and rare genetic disorders. Whole genome sequencing offers insights into gene mutations, treatment response, and disease progression, enabling more effective and individualized therapies. Expanding applications in pharmacogenomics further strengthen its relevance in clinical care. The shift toward patient-centric treatment, combined with falling sequencing costs, ensures rapid adoption across healthcare systems worldwide.
- For instance, Illumina's Cell-Free DNA Prep with Enrichment workflow can be combined with a custom 79-gene solid tumor panel. This workflow detects somatic mutations down to 0.2% variant allele frequency (VAF) in cfDNA samples.
Expanding Applications in Drug Discovery and Development
Pharmaceutical and biotechnology companies are adopting whole genome sequencing to accelerate drug discovery and development. Sequencing supports identification of novel drug targets, validation of biomarkers, and optimization of clinical trial designs. By enabling comprehensive genetic profiling, it reduces risks in drug pipelines and enhances success rates. Additionally, integration with bioinformatics and artificial intelligence allows faster analysis of large datasets. Growing demand for targeted therapies and biologics reinforces the importance of sequencing in research pipelines, driving strong investments from industry players.
- For instance, Macrogen processes over 300,000 genomes per year across its analytical infrastructure, serving more than 18,000 research institutes in 153 countries, which supports large-scale variant discovery in drug pipelines.
Declining Cost of Sequencing Technologies
The continuous decline in sequencing costs plays a crucial role in market growth. Next-generation sequencing platforms have significantly reduced per-genome costs, making whole genome sequencing more accessible for clinical and research use. Affordable sequencing drives adoption in routine diagnostics, population genomics, and academic research. Manufacturers are also introducing portable and automated platforms that reduce operational expenses. This affordability expands the market beyond high-end laboratories to hospitals and smaller institutions, accelerating adoption across developed and emerging regions. Lower cost barriers ensure long-term market sustainability.
Key Trends & Opportunities
Integration of Artificial Intelligence and Bioinformatics
Artificial intelligence (AI) and advanced bioinformatics tools are transforming the whole genome sequencing market. AI-driven platforms improve speed and accuracy in interpreting large genomic datasets, enabling more precise clinical insights. Integration with cloud computing allows real-time data analysis, facilitating rapid decision-making in diagnostics and research. Companies are investing heavily in AI-based genomic interpretation platforms to enhance scalability. This trend creates opportunities for providers to deliver comprehensive and efficient solutions, addressing the growing complexity of genomic data while strengthening their competitive edge.
- For instance, The ChAS + Franklin system taps into a knowledge base with more than 350,000 shared variant classifications, enabling phenotype matching, literature-supported evidence, and ACMG classification integration.
Expansion of Population Genomics Initiatives
Governments and research organizations are investing in large-scale population genomics projects, creating strong opportunities for the market. These initiatives aim to sequence millions of genomes to understand genetic diversity, disease risks, and drug responses. Such programs provide valuable datasets for pharmaceutical research, personalized medicine, and public health strategies. Countries including the U.S., U.K., and China have launched national sequencing programs, encouraging further adoption. The rise of these initiatives boosts demand for advanced sequencing platforms, data storage, and analytics, opening long-term growth avenues.
- For instance, Agilent's Avida hybrid-capture technology is designed to capture target molecules using input DNA, typically ranging from 10 ng upwards, and is compatible with both genomic DNA and cell-free DNA.
Key Challenges
Data Storage and Interpretation Complexity
The vast amount of data generated by whole genome sequencing poses a major challenge. Storing, securing, and managing terabytes of genomic data requires advanced infrastructure and high costs. Moreover, interpreting complex datasets demands skilled professionals and robust bioinformatics pipelines, which are often lacking in developing regions. These limitations slow clinical adoption and add to operational challenges for hospitals and laboratories. Without standardized frameworks for data handling, scalability and efficiency remain constrained, creating barriers for widespread implementation in healthcare systems.
Regulatory and Ethical Concerns
Regulatory hurdles and ethical issues present significant challenges in the whole genome sequencing market. Genomic data is highly sensitive, raising privacy concerns related to storage, sharing, and use. Lack of harmonized global regulations complicates international collaborations and commercialization. Additionally, ethical debates regarding patient consent, genetic discrimination, and potential misuse of data continue to grow. These factors create uncertainty for stakeholders, slowing adoption in clinical applications. Addressing these concerns through robust regulatory frameworks and transparent governance will be critical for sustainable market expansion.
Regional Analysis
North America
North America leads the whole genome sequencing market with a 38% share in 2024, supported by advanced healthcare infrastructure and strong adoption in precision medicine. The U.S. drives regional growth with extensive research funding, large-scale genomics initiatives, and integration of sequencing into clinical diagnostics. Favorable reimbursement policies and the presence of major sequencing companies further strengthen market dominance. Canada also contributes with population genomics projects and research collaborations. The region benefits from early adoption of AI and bioinformatics, reinforcing its position as the global hub for genomic innovation and commercialization of sequencing technologies.
Europe
Europe accounts for 29% of the whole genome sequencing market in 2024, driven by strong government funding and population-scale genomics projects. The U.K. leads with its 100,000 Genomes Project and expanding initiatives in rare disease research. Germany and France contribute through rising adoption in hospitals and collaborations with pharmaceutical companies. The European Union’s focus on data protection and ethical frameworks enhances patient confidence, supporting broader adoption. Increasing demand for precision medicine, coupled with a well-established academic research base, positions Europe as a key growth center for whole genome sequencing technologies across healthcare and life sciences.
Asia-Pacific
Asia-Pacific holds a 23% share in the whole genome sequencing market in 2024, with rapid growth driven by China, Japan, and India. Government-backed genomic programs and investments in healthcare modernization fuel adoption. China’s national genomics initiatives and growing sequencing capacity position it as a regional leader. Japan advances integration of sequencing in oncology and precision medicine, while India sees rising uptake in research institutes and clinical diagnostics. Expanding biotechnology hubs, growing healthcare expenditure, and increasing partnerships with global companies make Asia-Pacific the fastest-growing region, creating strong opportunities for sequencing technology providers and service companies.
Latin America
Latin America represents a 6% share in the whole genome sequencing market in 2024, supported by increasing adoption in Brazil, Mexico, and Argentina. Research collaborations, improving healthcare infrastructure, and government-backed genomics initiatives strengthen growth prospects. Brazil leads regional adoption with genomic medicine programs and cancer research projects. However, high costs and limited skilled workforce pose challenges for broader implementation. Growing partnerships with international companies and expanding private healthcare investments are driving sequencing accessibility. The region’s focus on addressing rare diseases and infectious disease surveillance enhances demand for sequencing technologies across both clinical and academic applications.
Middle East & Africa
The Middle East & Africa region holds a 4% share in the whole genome sequencing market in 2024, with growth concentrated in Gulf countries and South Africa. The UAE and Saudi Arabia are investing in national genome programs to advance precision medicine and diversify healthcare systems. South Africa contributes through research on genetic diversity and infectious diseases. Despite limited infrastructure in many parts of the region, international collaborations and rising private healthcare investments support market development. Growing awareness of genomic healthcare benefits and government-backed initiatives are expected to gradually expand sequencing adoption in this region.
Market Segmentations:
By Technology:
- Sanger sequencing
- Polymerase chain reaction
By Application:
- Diagnostics
- Drug discovery and development
By End User:
- Hospitals & clinics
- Academic institutes & research centers
By Geography
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- Italy
- U.K.
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Rest of Asia-Pacific
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East and Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Competitive Landscape
The whole genome sequencing market is highly competitive, with leading players including QIAGEN N.V., Eurofins Scientific, Illumina, Inc., Macrogens, Inc., Thermo Fisher Scientific, Inc., Merck KGaA, Agilent Technologies, Inc., Bio-Rad Laboratories, Inc., Siemens Healthineers, and Danaher Corporation. The whole genome sequencing market is characterized by intense competition, rapid technological innovation, and growing strategic collaborations. Companies are investing heavily in next-generation sequencing platforms, bioinformatics tools, and integrated diagnostics to enhance accuracy, speed, and affordability. Continuous advancements in high-throughput sequencing, automation, and cloud-based data analysis are reshaping clinical and research applications. Market participants focus on expanding their global footprint through partnerships, mergers, and acquisitions, while also targeting emerging economies with rising healthcare investments. Increasing demand for precision medicine, drug discovery, and large-scale genomics projects further fuels competition, driving continuous innovation and portfolio diversification across the industry.
Key Player Analysis
- QIAGEN N.V.
- Eurofins Scientific
- Illumina, Inc
- Macrogens, Inc
- Thermo Fisher Scientific, Inc
- Merck KGaA
- Agilent Technologies, Inc
- Bio-Rad Laboratories, Inc
- Siemens Healthineers
- Danaher Corporation
Recent Developments
- In May 2025, Twist Bioscience and Ginkgo Bioworks revised their collaboration agreement, transitioning from a four-year contract signed in 2022 to a three-year arrangement. Under the new terms, Ginkgo will continue to prepay annually for Twist's synthetic DNA products, with no minimum purchase volume required.
- In March 2025, Integrated DNA Technologies (IDT) and Elegen announced a strategic partnership to enhance long DNA synthesis capabilities. Through this collaboration, IDT customers gained early access to Elegen’s ENFINIA Plasmid DNA service, enabling rapid delivery of high-complexity clonal genes ranging from 5 kb to 15 kb.
- In Nov 2024, Ansa biotechnologies sets a new standard in long, complex DNA. A technology pairs with groundbreaking complex DNA synthesis platform. Ansa’s enzymatic idea has eliminated the need for harsh chemicals.
- In June 2024, GenScript Biotech Corporation introduced its FLASH Gene service, an ultra-fast sequence-to-plasmid (S2P) solution designed to expedite gene synthesis. This service delivers gene constructs in four business days, making it the fastest in the industry.
Report Coverage
The research report offers an in-depth analysis based on Technology, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Whole genome sequencing will gain wider adoption in routine clinical diagnostics.
- Precision medicine will remain the strongest driver of sequencing applications.
- Population genomics projects will expand across developed and emerging economies.
- Declining sequencing costs will improve accessibility in hospitals and research centers.
- AI-driven bioinformatics will enhance accuracy and speed of genomic data interpretation.
- Integration with cloud platforms will support real-time analysis and large-scale collaborations.
- Pharmaceutical companies will increase reliance on sequencing for drug discovery pipelines.
- Ethical and regulatory frameworks will evolve to address privacy and consent concerns.
- Emerging markets will invest more in genomics infrastructure and national sequencing programs.
- Strategic collaborations and acquisitions will intensify to strengthen technological capabilities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Precision Medicine Adoption
The increasing use of whole genome sequencing to tailor treatment plans, especially in oncology and rare genetic disorders, is driving market growth by enabling more effective and individualized therapies.
Declining Sequencing Costs
Continuous reductions in the cost of next-generation sequencing technologies are making whole genome sequencing more accessible for clinical diagnostics, research, and population genomics, expanding adoption across both developed and emerging markets.
Integration of AI and Bioinformatics
The adoption of artificial intelligence and advanced bioinformatics tools is enhancing the speed and accuracy of genomic data interpretation, supporting broader clinical use and enabling real-time, large-scale data analysis.
Expansion of Population Genomics Initiatives
Government and research-backed projects to sequence large populations are generating valuable datasets for disease research and personalized medicine, fueling demand for advanced sequencing platforms and analytics.
Pharmaceutical R&D Acceleration
Pharmaceutical and biotechnology companies are leveraging whole genome sequencing to identify novel drug targets, validate biomarkers, and optimize clinical trials, which accelerates drug discovery and increases the success rate of new therapies.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Whole Genome Sequencing Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Whole Genome Sequencing Market projected to grow between 2025 and 2032?
Which Whole Genome Sequencing Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Whole Genome Sequencing Market?
Who are the leading companies in the Whole Genome Sequencing Market?
Which region commanded the largest share of the Whole Genome Sequencing Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Hospitals & clinics
- 1.2.2 Academic institutes & research centers
- 1.2.3 Pharmaceutical & biotechnology companies
- 1.3 By Technology
- 1.3.1 Next-generation sequencing (NGS)
- 1.3.2 Sanger sequencing
- 1.3.3 Polymerase chain reaction (PCR)
- 1.4 By Application
- 1.4.1 Diagnostics
- 1.4.2 Drug discovery and development
- 1.4.3 Precision medicine
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2.23 billion → 2032: USD 10.86 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Whole Genome Sequencing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Whole Genome Sequencing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Whole Genome Sequencing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Whole Genome Sequencing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Whole Genome Sequencing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Whole Genome Sequencing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Whole Genome Sequencing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Whole Genome Sequencing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2.23 billion → 2032: USD 10.86 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Whole Genome Sequencing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals & clinics
- 12.3.7.2 Academic institutes & research centers
- 12.3.7.3 Pharmaceutical & biotechnology companies
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Next-generation sequencing (NGS)
- 12.4.7.2 Sanger sequencing
- 12.4.7.3 Polymerase chain reaction (PCR)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Diagnostics
- 12.5.7.2 Drug discovery and development
- 12.5.7.3 Precision medicine
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Whole Genome Sequencing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Whole Genome Sequencing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Whole Genome Sequencing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Whole Genome Sequencing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Illumina, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Thermo Fisher Scientific, Inc.
- 18.4 Danaher Corporation
- 18.5 QIAGEN N.V.
- 18.6 Merck KGaA
- 18.7 Eurofins Scientific
- 18.8 Siemens Healthineers
- 18.9 Macrogens, Inc.
- 18.10 Bio-Rad Laboratories, Inc.
- 18.11 Agilent Technologies, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

