
Market Overview
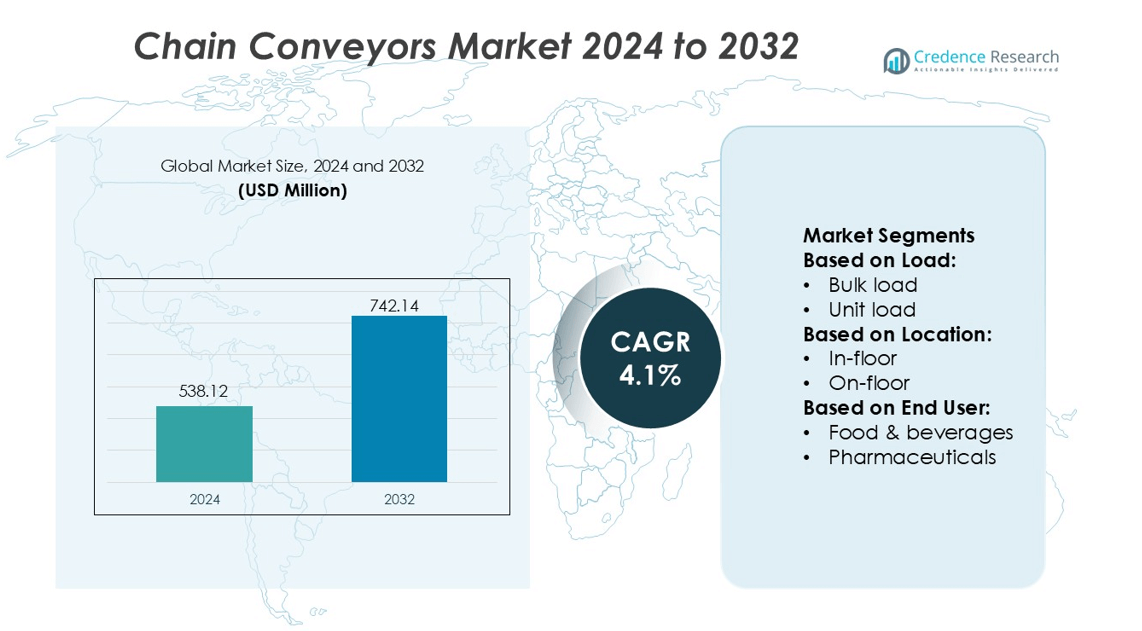
Chain Conveyors Market size was valued USD 538.12 million in 2024 and is anticipated to reach USD 742.14 million by 2032, at a CAGR of 4.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Chain Conveyors Market Size 2024 | USD 538.12 million |
| Chain Conveyors Market, CAGR | 4.1% |
| Chain Conveyors Market Size 2032 | USD 742.14 million |
The chain conveyors market is dominated by leading companies such as Hytrol Conveyor Company, Inc., Fives, Daifuku Co., Ltd., Interroll Group, Honeywell International Inc, BEUMER Group, Regal Rexnord Corporation, FlexLink, Kardex, and Dematic. These players focus on innovation, automation, and customized solutions to meet diverse industrial requirements across manufacturing, food processing, logistics, and e-commerce sectors. High-speed, durable, and energy-efficient systems, combined with IoT integration and predictive maintenance, strengthen their competitive positioning. Asia-Pacific emerges as the leading region, holding 35% of the global market share, driven by rapid industrialization, expanding e-commerce, and growing warehouse infrastructure in China, India, and Southeast Asia. The region’s adoption of smart conveyors and high-capacity systems further reinforces its dominance, while global players continue investing in technology upgrades, regional expansions, and partnerships to capitalize on increasing demand in industrial and logistics applications.
Market Insights
- The chain conveyors market was valued at USD 538.12 million in 2024 and is expected to reach USD 742.14 million by 2032, growing at a CAGR of 4.1% during the forecast period.
- Demand is driven by increasing industrial automation, e-commerce growth, and the need for efficient material handling across manufacturing, food processing, and logistics sectors.
- High-speed, durable, and energy-efficient systems with IoT integration and predictive maintenance are emerging trends, improving operational efficiency and reducing downtime.
- The market is highly competitive, led by Hytrol Conveyor Company, Inc., Fives, Daifuku Co., Ltd., Interroll Group, Honeywell International Inc, BEUMER Group, Regal Rexnord Corporation, FlexLink, Kardex, and Dematic, who focus on innovation, regional expansions, and customized solutions.
- Asia-Pacific holds 35% of the market share, supported by China, India, and Southeast Asia, while Europe and North America follow. Modular on-floor and overhead conveyors dominate the market segments, catering to high-capacity industrial and warehouse operations.Top of Form
Market Segmentation Analysis:
By Load
The bulk‑load segment leads the chain conveyors market with a 42.5 % share. This dominance stems from the systems’ strength in handling heavy, abrasive or loose materials - key in mining, cement and large‑scale manufacturing environments. Demand grows as operators invest in robust chain systems with reinforced chains, wear‑resistant linings and modular designs to minimize material loss and downtime.
- For instance, Hytrol Model 190-E24EZ zero-pressure accumulating live roller conveyor supports a maximum unit load of 75 lbs (pounds) per zone and a maximum distributed load of 37 lbs per foot of conveyor length.
By Location
The on‑floor segment holds the largest share (exceeding 48 %) in the chain conveyors market. On‑floor installations dominate because they are cost‑efficient, easier to install and scale, and integrate well with existing manufacturing layouts. Growth is driven by manufacturers seeking flexible, high‑throughput material flow solutions that require minimal structural alteration.
- For instance, Fives’ EASY‑Stream belt conveyor system handles loads up to 80 kg and reaches belt speeds of 180 m/min, enabling rapid material flow across factory floors.
By End‑User
The food & beverages end‑user segment accounts for around 27.5 % of the chain conveyors market. Its lead is supported by highly automated processing and strict hygiene requirements, pushing demand for corrosion‑resistant, easy‑clean chain systems. Another major driver is the rise in e‑commerce and fast‑turn packaging lines, which amplify need for efficient conveyor integration across ingredients, packing and sorting stages.
Key Growth Drivers
Increasing Industrial Automation
Rising adoption of industrial automation drives demand for chain conveyors across manufacturing sectors. Automated systems enhance material handling efficiency, reduce labor costs, and minimize human error. Industries such as automotive, food processing, and pharmaceuticals integrate conveyor systems for faster production cycles and consistent output quality. For instance, automotive assembly plants use chain conveyors with precise motorized controls to transport heavy components, improving throughput by up to 25% while reducing manual handling risks. This trend fuels investments in high-speed, durable, and programmable chain conveyor solutions globally.
- For instance, Daifuku’s “Unibilt Power & Free” overhead chain conveyor supports loads up to 3,000 lb (1,361 kg) per trolley in its four‑trolley load bar configuration.
Growing E-commerce and Warehousing Needs
Expansion of e-commerce and warehouse operations boosts the chain conveyors market. High-volume order fulfillment requires seamless transportation of goods across distribution centers, reducing turnaround time. Chain conveyors enable efficient sorting, loading, and storage of heavy pallets and products, enhancing logistics efficiency. For instance, leading e-commerce warehouses employ overhead and on-floor chain conveyors capable of handling 1,500–2,000 kg pallets per hour, optimizing space utilization and labor allocation. This rising demand in logistics and retail sectors underpins market growth across regions.
- For instance, Interroll’s Chain Conveyor PM 9720 is available in dual- or triple-chain run versions and supports a maximum distributed load capacity of 1,875 kg per meter of conveyor length.
Demand for Durable and Customized Solutions
Manufacturers increasingly seek durable, customizable chain conveyors to meet specific operational needs. Heavy-duty chains, corrosion-resistant materials, and modular designs ensure long service life in harsh industrial environments. For instance, food processing plants adopt stainless steel conveyors with adjustable pitch chains to handle high-moisture products without contamination, enhancing hygiene and operational efficiency. Customizable conveyor layouts allow seamless integration with existing production lines, reducing downtime. This focus on performance, longevity, and flexibility drives adoption across manufacturing, mining, and automotive industries worldwide.
Key Trends & Opportunities
Integration of Smart Technologies
Chain conveyors increasingly incorporate IoT sensors, automated monitoring, and predictive maintenance tools. Smart conveyors provide real-time data on load, speed, and system health, enabling proactive maintenance and minimizing downtime. For instance, pharmaceutical facilities use chain conveyors equipped with vibration sensors and load detectors to anticipate component wear, reducing service interruptions by 20%. The integration of digital monitoring and automation offers growth opportunities for suppliers offering advanced, connected conveyor systems across industrial applications.
- For instance, Rexnord 1533 Series MatTop® chain features an 8 mm transfer gap, which the company advertises as among the smallest on the market. It also supports approximately 4,600 rollers per square meter, offering improved product stability and safety during conveyance.
Expansion in Emerging Markets
Emerging economies in Asia-Pacific, Latin America, and the Middle East present significant growth opportunities. Rapid industrialization, rising manufacturing output, and infrastructure expansion drive chain conveyor adoption in automotive, food, and logistics sectors. For instance, Southeast Asian manufacturing hubs implement modular on-floor chain conveyors handling up to 3,000 kg per hour, improving efficiency in high-volume operations. Expanding industrial parks and logistics networks create avenues for local and international suppliers to penetrate untapped markets and establish long-term contracts.
- For instance, FlexLink’s modular plastic chain conveyor system X300X supports a maximum individual item load of approximately 15 kg. The system is rated for a maximum total weight of 200 kg across the entire conveyor length, and is capable of running speeds up to 80,000 mm/min (approximately 1,333 mm/s or 80 m/min).
Key Challenges
High Initial Capital Investment
The upfront cost of chain conveyor systems poses a challenge, especially for small and medium enterprises. Installation, customization, and integration with existing production lines require significant capital outlay. For instance, installing an overhead chain conveyor system in a medium-scale automotive plant may cost several hundred thousand dollars, limiting adoption among budget-constrained manufacturers. Companies must weigh long-term efficiency gains against high initial investment, slowing adoption rates in price-sensitive segments despite operational benefits.
Maintenance and Operational Downtime
Chain conveyors require regular maintenance to prevent mechanical failures, chain wear, and motor breakdowns, impacting operational continuity. Unexpected downtime can disrupt production schedules and increase maintenance costs. For instance, food processing facilities using high-capacity chain conveyors experience up to 8–10 hours of annual downtime due to chain tension adjustments or motor replacement. This operational vulnerability necessitates skilled maintenance staff and increases total cost of ownership, presenting a barrier to market expansion.
Regional Analysis
North America
North America holds 30% of the global chain conveyors market, driven by its advanced industrial base and strong logistics infrastructure. Automotive, food processing, and e-commerce industries increasingly rely on chain conveyors to improve production efficiency and reduce manual labor. Companies in the United States and Canada are adopting modular, high-speed conveyor systems with automated controls to optimize material handling and minimize downtime. Integration of smart sensors and predictive maintenance enhances operational reliability. The region’s mature manufacturing sector and focus on Industry 4.0 solutions continue to support steady growth and high demand for advanced conveyor systems.
Europe
Europe accounts for approximately 25% of the chain conveyors market, with Germany, France, and the UK leading adoption. Growth is driven by stringent regulatory standards, automation in manufacturing, and increasing demand in automotive and food industries. Western Europe is pioneering advanced material handling solutions that include IoT-enabled conveyors and predictive maintenance systems, enhancing production efficiency and reducing downtime. Eastern Europe is gradually catching up as manufacturing investments expand into countries like Poland and the Czech Republic, creating opportunities for conveyor suppliers. The combination of technological adoption and industrial modernization reinforces Europe’s strong market position.
Asia-Pacific
Asia-Pacific holds the largest share at 35% of the global chain conveyors market, supported by rapid industrialization and expanding e-commerce and warehousing sectors. China, India, and Southeast Asia are major contributors, where manufacturers deploy high-capacity, automated conveyor systems to handle large-scale production and logistics operations. Adoption of smart conveyors with sensors and automation is increasing to improve efficiency, reduce labor costs, and enable real-time monitoring. Rising investments in industrial infrastructure, manufacturing parks, and logistics hubs further drive demand. Asia-Pacific remains the fastest-growing market due to its combination of high production needs and modernization of supply chains.
Latin America
Latin America contributes around 5% of the global chain conveyors market, reflecting moderate industrial development. Brazil and Mexico lead the region in the adoption of chain conveyors, driven by warehouse expansion, manufacturing modernization, and growing e-commerce demand. Companies are investing in on-floor and overhead conveyors to improve material handling and productivity. However, economic volatility, lower automation levels, and limited infrastructure in some countries slow overall market growth. Despite these challenges, rising investments in industrial facilities and logistics centers offer opportunities for conveyor suppliers in key urban and industrial hubs across the region.
Middle East & Africa
The Middle East & Africa region holds approximately 5% of the global chain conveyors market. Growth is fueled by logistics hubs in Gulf countries, industrial projects, and demand in oil, gas, mining, and construction sectors. Manufacturers deploy heavy-duty chain conveyors for transporting bulk materials and improving operational efficiency. Adoption of automated and modular systems is increasing in industrial zones to optimize material handling. However, regional instability, low automation penetration, and infrastructure gaps limit faster expansion. Long-term opportunities exist as investments in industrial and logistics projects increase across Africa and the Middle East, supporting gradual market growth.
Market Segmentations:
By Load:
- Bulk load
- Unit load
By Location:
- In-floor
- On-floor
By End User:
- Food & beverages
- Pharmaceuticals
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The chain conveyors market players such as Hytrol Conveyor Company, Inc., Fives, Daifuku Co., Ltd., Interroll Group, Honeywell International Inc, BEUMER Group, Regal Rexnord Corporation, FlexLink, Kardex, and Dematic. The chain conveyors market is highly competitive, driven by continuous innovation, technological advancements, and growing demand for automation. Companies focus on developing high-speed, durable, and energy-efficient conveyor systems tailored to diverse industrial applications such as manufacturing, food processing, logistics, and e-commerce. Integration of smart sensors, IoT monitoring, and predictive maintenance enhances operational efficiency and reduces downtime. Market players also prioritize modular designs and customizable layouts to meet specific client requirements while ensuring quick installation and minimal disruption. Strategic initiatives, including regional expansion, partnerships, and after-sales support, further strengthen competitiveness. Rising emphasis on sustainability, automation, and digital solutions continues to shape the market, pushing companies to differentiate through advanced technologies, improved efficiency, and cost-effective solutions to capture growing industrial demand globally.
Key Player Analysis
- Hytrol Conveyor Company, Inc.
- Fives
- Daifuku Co., Ltd.
- Interroll Group
- Honeywell International Inc
- BEUMER Group
- Regal Rexnord Corporation
- FlexLink
- Kardex
- Dematic
Recent Developments
- In April 2025, African mine will be among the first adopters of the innovative rail-running conveyor (RRC) technology, commercialized by full flowsheet provider FLS in collaboration with the University of Newcastle, Australia.
- In April 2025, NTPC’s Pakri Barwadih coal mining project made operational a 21-kilometre-long conveyor belt system to transport coal to Hazaribag railway station. The PSU claims that the conveyor belt was Asia’s longest and significant advancement of coal transportation infrastructure.
- In July 2023, Dematic announced the global launch of its Noise Reduction Portfolio, a comprehensive solution specifically designed to address loud work environments in supply chain facilities. The service offering included essential features like before and after 3D noise mapping audits.
Report Coverage
The research report offers an in-depth analysis based on Load, Location, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of automated and smart chain conveyor systems will increase across industries.
- Integration of IoT and predictive maintenance will enhance operational efficiency and reduce downtime.
- Demand for energy-efficient and modular conveyors will grow in manufacturing and logistics sectors.
- E-commerce expansion will drive higher adoption of high-capacity conveyors in warehouses.
- Customizable conveyor solutions will gain popularity to meet specific industrial requirements.
- Emerging markets will see steady growth due to industrialization and infrastructure development.
- Focus on sustainable materials and eco-friendly designs will influence product development.
- Increased use of conveyors in food, pharmaceutical, and automotive industries will continue.
- Digital monitoring and automation technologies will become standard in new installations.
- Strategic partnerships and regional expansions will strengthen market presence globally.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Chain Conveyors Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Chain Conveyors Market projected to grow between 2025 and 2032?
Which Chain Conveyors Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Chain Conveyors Market?
Who are the leading companies in the Chain Conveyors Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 538.12 million → 2032: USD 742.14 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Chain Conveyors Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Chain Conveyors Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Chain Conveyors Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Chain Conveyors Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Chain Conveyors Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Chain Conveyors Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Chain Conveyors Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Chain Conveyors Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 538.12 million → 2032: USD 742.14 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Chain Conveyors Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Chain Conveyors Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Chain Conveyors Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Chain Conveyors Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

