
Market Overview:
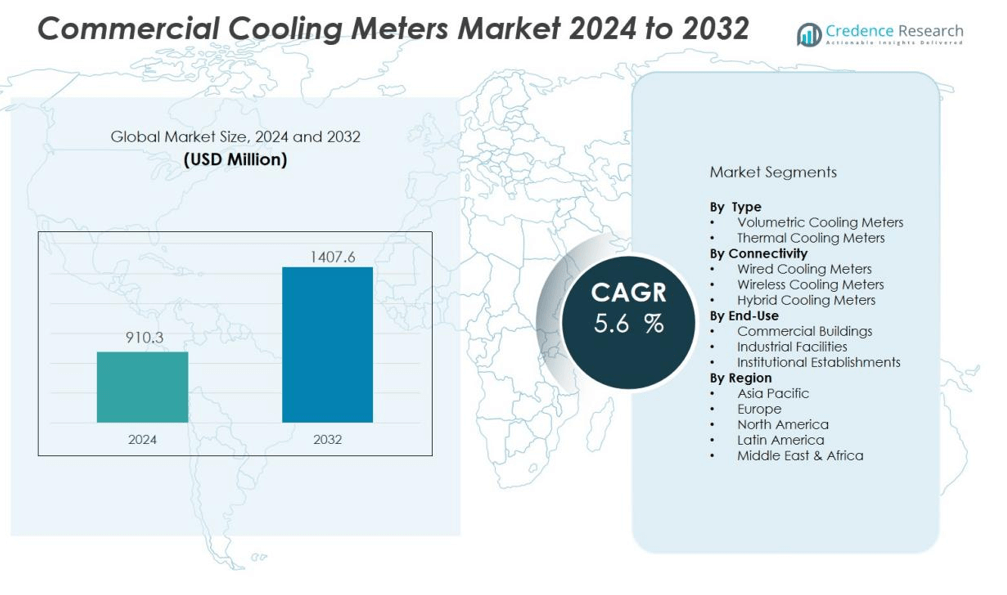
The Commercial cooling meters market size was valued at USD 910.3 million in 2024 and is anticipated to reach USD 1407.6 million by 2032, at a CAGR of 5.6 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Commercial Cooling Meters Market Size 2024 | USD 910.3 million |
| Commercial Cooling Meters Market, CAGR | 5.6% |
| Commercial Cooling Meters Market Size 2032 | USD 1407.6 million |
Key drivers fueling the commercial cooling meters market include growing awareness about energy conservation, stringent government regulations on energy monitoring, and the increasing adoption of smart metering solutions integrated with IoT and data analytics. The need to reduce operational costs and carbon footprints compels businesses to deploy advanced cooling meters that provide real-time data for optimized energy management. Additionally, expansion in commercial infrastructure, particularly in urban areas, further accelerates the demand for reliable cooling measurement systems.
Regionally, North America holds a dominant share due to stringent energy efficiency mandates, established smart building infrastructure, and high adoption of advanced metering technologies. Europe follows closely, driven by progressive regulatory frameworks and sustainability initiatives. The Asia-Pacific region is expected to register the fastest growth, supported by rapid industrialization, urbanization, and increasing investments in commercial infrastructure across countries such as China, India, and Southeast Asian nations. Emerging markets in Latin America and the Middle East & Africa are also showing growing interest in energy management solutions, contributing to overall market expansion.
Market Insights:
- The Commercial cooling meters market was valued at USD 910.3 million in 2024 and is expected to reach USD 1,407.6 million by 2032, growing at a CAGR of 5.6% during the forecast period.
- Growing awareness of energy conservation, stringent government regulations on energy monitoring, and the rising adoption of IoT-integrated smart metering solutions drive market expansion.
- The need to reduce operational costs and carbon footprints compels businesses to deploy advanced cooling meters that provide real-time data for optimized energy management.
- North America leads the market with nearly 35% share, supported by strong energy efficiency mandates, smart building infrastructure, and corporate sustainability commitments.
- Europe holds about 30% market share, fueled by stringent environmental regulations, green building standards, and initiatives aimed at achieving carbon neutrality by 2050.
- Asia-Pacific contributes close to 25% of the market and shows the fastest growth due to rapid urbanization, industrialization, and government support for smart city and energy conservation initiatives.
- High initial investment costs, integration complexity, data security concerns, and ongoing maintenance requirements pose challenges to widespread adoption but also drive innovation in scalable and secure solutions.
Market Drivers:
Rising Focus on Energy Efficiency and Regulatory Compliance Accelerates Market Demand:
The Commercial cooling meters market benefits significantly from heightened emphasis on energy efficiency across commercial and industrial sectors. Governments worldwide impose strict regulations requiring accurate monitoring of energy consumption to reduce wastage and carbon emissions. It supports organizations in meeting sustainability targets and avoiding penalties related to non-compliance. This regulatory push drives widespread adoption of cooling meters that enable precise measurement and control of cooling energy use.
- For instance, Schneider Electric’s Building Decarbonization Calculator is used by building owners-including JLL and C-scale-to model energy use and simulate up to 500,000 building performance optimization scenarios, directly supporting compliance with regulations such as New York City’s Local Law 97
Expansion of Smart Building Technologies and Integration with IoT Solutions:
Growing deployment of smart building technologies boosts the demand for advanced cooling meters capable of real-time data collection and remote monitoring. The Commercial cooling meters market leverages the integration of Internet of Things (IoT) devices to enhance energy management strategies through detailed analytics and automation. It allows facility managers to optimize cooling system performance and reduce operational costs effectively. This technology-driven evolution stimulates innovation and market growth.
- For instance, Schneider Electric’s EcoStruxure Building Advisor equipped 150 Holborn meeting rooms with IoT-enabled occupancy sensors and automated HVAC setbacks, cutting room cooling energy use by 22% over a six-month trial period.
Increasing Commercial Infrastructure Development Fuels Market Growth:
Rapid urbanization and infrastructural expansion in emerging economies create substantial opportunities for the Commercial cooling meters market. New commercial buildings and industrial facilities require efficient cooling systems equipped with accurate metering solutions to support energy management goals. It promotes demand for reliable cooling meters that facilitate sustainable building practices. Rising investments in construction and modernization projects contribute directly to market expansion.
Growing Corporate Awareness of Operational Cost Reduction and Sustainability:
Businesses increasingly prioritize reducing operational expenses and improving environmental footprints, driving the adoption of commercial cooling meters. It enables organizations to monitor and analyze cooling energy consumption in detail, identifying inefficiencies and opportunities for savings. The growing corporate focus on sustainability encourages investments in smart metering technologies to support green building certifications and energy audits. This heightened awareness serves as a critical catalyst for market development.
Market Trends:
Adoption of Advanced Smart Metering Technologies Enhances Market Competitiveness:
The Commercial cooling meters market increasingly shifts toward smart metering solutions that offer enhanced accuracy, connectivity, and user-friendly interfaces. It incorporates technologies such as wireless communication, cloud-based data management, and real-time analytics to provide actionable insights for energy optimization. These smart meters enable seamless integration with building management systems, facilitating automated control and predictive maintenance. The trend toward digitalization drives manufacturers to innovate and differentiate their product offerings. Customers demand scalable and interoperable systems that support sustainability goals and cost-efficiency, reinforcing the shift toward intelligent metering.
- For instance, Honeywell’s Next Generation Cellular Module (NXCM) transforms legacy gas and water meters into smart devices, delivering 24 hourly readings per day with 20-year battery life and robust tamper alerts.
Growing Emphasis on Sustainability and Green Building Certifications Influences Product Development:
Sustainability initiatives and green building certification programs strongly influence product design and adoption in the Commercial cooling meters market. It supports efforts to monitor and reduce energy consumption within commercial infrastructures, encouraging environmentally responsible operations. Manufacturers increasingly focus on developing meters that comply with global energy standards and offer features supporting comprehensive energy audits. The market witnesses rising interest in solutions that contribute to LEED, BREEAM, and other certification requirements. This trend motivates businesses to invest in advanced cooling meters that provide transparency and accountability in energy use, promoting long-term environmental and financial benefits.
For instance, evaporative cooling systems optimized for green buildings can earn significant LEED energy optimization points-up to 20 points in existing buildings-by reducing water and energy use.
Market Challenges Analysis:
High Initial Investment and Integration Complexity Hinder Market Penetration:
The Commercial cooling meters market faces challenges related to the substantial upfront costs associated with advanced metering systems. It deters small and medium-sized enterprises from adopting these technologies despite long-term benefits. Integration of cooling meters with existing building management systems often requires technical expertise and customization, increasing deployment time and expenses. This complexity may discourage potential buyers and slow market growth. Furthermore, lack of standardized protocols across devices creates compatibility issues, complicating system-wide implementation.
Data Security Concerns and Maintenance Requirements Impact Market Adoption:
Concerns over data privacy and cybersecurity pose significant barriers to widespread acceptance in the Commercial cooling meters market. It requires robust security measures to protect sensitive consumption data from cyber threats and unauthorized access. Regular maintenance and calibration of cooling meters demand specialized skills and resources, which increase operational costs for end users. These factors contribute to hesitation among organizations when considering investment in metering solutions. Overcoming these challenges is essential to foster broader market adoption and trust.
Market Opportunities:
Expansion of Smart City Initiatives and Digital Infrastructure Creates Growth Potential:
The Commercial cooling meters market benefits from the global rise of smart city projects focused on energy efficiency and sustainable resource management. It offers significant opportunities for deploying intelligent cooling meters integrated with broader urban infrastructure systems. Governments and private sectors invest heavily in digital infrastructure that supports real-time energy monitoring and optimization. This trend opens avenues for manufacturers to develop innovative solutions tailored for large-scale implementations. Growing partnerships between technology providers and utility companies further accelerate market penetration in this evolving landscape.
Increasing Demand for Energy Cost Management in Commercial Real Estate Drives Market Expansion:
Rising operational costs and growing awareness of energy consumption among commercial property owners create substantial demand in the Commercial cooling meters market. It enables facility managers to track and optimize cooling energy usage effectively, improving cost efficiency and environmental impact. Energy performance contracts and green financing models encourage investments in metering technologies. The expanding adoption of sustainability certifications also motivates businesses to implement precise cooling measurement systems. These factors collectively create a favorable environment for market growth and innovation.
Market Segmentation Analysis:
By Type:
The Commercial cooling meters market categorizes products primarily into volumetric and thermal cooling meters. Volumetric meters measure the volume of cooling fluid circulated, offering precise flow rate data crucial for billing and energy management. Thermal meters calculate the cooling load based on temperature differentials and flow, providing comprehensive energy consumption insights. Each type serves distinct application needs, with volumetric meters favored in systems requiring direct flow measurement and thermal meters preferred for integrated energy monitoring. The market demands meters with high accuracy, reliability, and compliance with industry standards.
- For instance, Kamstrup’s MULTICAL® 303-C ultrasonic meter delivers an approved dynamic range of 250:1 (qp:qi) for nominal flows between 0.6 and 2.5 m³/h, ensuring accurate volumetric readings even at very low flow rates.
By Connectivity:
Connectivity options in the Commercial cooling meters market include wired, wireless, and hybrid systems. Wired meters maintain popularity for their stable and secure data transmission, particularly in established commercial infrastructures. Wireless connectivity gains traction due to ease of installation, flexibility, and support for IoT integration, enabling remote monitoring and real-time analytics. Hybrid systems combine both approaches, optimizing reliability and scalability. The trend favors wireless and IoT-enabled meters, reflecting growing emphasis on smart building automation and data-driven energy management.
- For instance, Siemens' SITRANS FUE950 wired energy calculator used in commercial buildings provides precise acquisition of cooling energy with MID directive approval for custody transfer, offering reliable data communication through standardized M-Bus and pulse outputs, supporting operations up to 360,000 m³/h flow rates.
By End-Use:
The market segments end users into commercial buildings, industrial facilities, and institutional establishments. Commercial buildings such as offices, malls, and hotels lead demand, driven by stringent energy regulations and sustainability goals. Industrial facilities require cooling meters to monitor energy-intensive processes and optimize operational costs. Institutional users, including hospitals and educational campuses, invest in cooling meters to ensure efficient resource management and regulatory compliance. It supports diverse end-use requirements by offering customizable solutions tailored to specific operational environments.
Segmentations:
By Type:
- Volumetric Cooling Meters
- Thermal Cooling Meters
By Connectivity:
- Wired Cooling Meters
- Wireless Cooling Meters
- Hybrid Cooling Meters
By End-Use:
- Commercial Buildings
- Industrial Facilities
- Institutional Establishments
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America:
North America accounts for nearly 35% of the global Commercial cooling meters market, driven by extensive adoption of energy-efficient technologies in commercial and industrial sectors. It benefits from strict regulatory frameworks that mandate accurate monitoring of energy consumption and promote sustainability. The region hosts advanced smart building infrastructure, supporting integration of intelligent cooling meters with building management systems. Corporate commitment toward reducing carbon footprints fuels investments in cutting-edge metering solutions. The presence of major technology providers and continuous innovation further strengthen North America’s market position. Growing retrofit projects in older commercial buildings also contribute to steady demand.
Europe :
Europe holds approximately 30% of the Commercial cooling meters market, supported by stringent environmental regulations and widespread implementation of green building standards. It encourages deployment of precise energy measurement tools to optimize cooling systems and reduce emissions. The European Union’s focus on carbon neutrality by 2050 accelerates adoption of smart metering technologies. It benefits from government incentives and funding programs that facilitate infrastructure modernization. Leading economies like Germany, France, and the UK play key roles in driving regional growth. Industry players actively collaborate with research institutions to advance metering innovation in the region.
Asia-Pacific:
Asia-Pacific contributes nearly 25% to the Commercial cooling meters market and demonstrates the highest growth rate globally due to accelerated urban development and industrial sector expansion. It experiences rising demand for efficient cooling energy management driven by infrastructure growth in countries such as China, India, Japan, and Southeast Asian nations. Increasing awareness of energy conservation and government support for smart city initiatives boost adoption of advanced cooling meters. It faces opportunities in new construction and retrofit projects, supported by rising corporate focus on operational cost reduction. The growing presence of global and local manufacturers enhances competitive dynamics within the region.
Key Player Analysis:
- Sycous Limited
- ITRON
- Zenner International GmbH & Co. KG
- Apator S.A.
- BMETERS Srl
- Kamstrup
- Premier Control Technologies Ltd.
- Danfoss
- Siemens AG
- Diehl Stiftung & Co. KG
- Trend Control Systems Ltd.
- Cosmic Technologies
Competitive Analysis:
The Commercial cooling meters market features a competitive landscape with key players such as Sycous Limited, ITRON, Zenner International GmbH & Co. KG, Apator S.A., BMETERS Srl, Kamstrup, Premier Control Technologies Ltd., Danfoss, and Siemens AG driving innovation and market expansion. It focuses on delivering high-precision, reliable, and technologically advanced cooling meters that integrate seamlessly with smart building systems. Companies compete through continuous product development, enhanced connectivity options, and strategic partnerships to expand their global footprint. Strong emphasis on regulatory compliance, energy efficiency, and customer-centric solutions shapes the competitive dynamics. Market leaders invest heavily in R&D to develop IoT-enabled meters offering real-time data analytics and remote monitoring capabilities. These innovations address evolving customer demands and regulatory requirements, reinforcing their market positions. The presence of both multinational corporations and specialized regional players ensures dynamic competition, fostering innovation and improved service offerings within the commercial cooling meters market.
Recent Developments:
- In July 2025, Sycous planned participation at The UK District Energy Association Heat Networks Expo 2025, showing ongoing industry involvement and networking.
- In November 2024, Zenner International GmbH & Co. KG launched the Zenner IoT Gateway outdoor 16, a new LoRaWAN gateway for industrial and urban IoT applications in Europe.
- In March 2025, Itron announced a partnership with NVIDIA to enhance AI-powered grid edge solutions, focusing on improving utility operations in grid resilience, operational efficiency, disaster management, and decarbonization through advanced AI integration.
Market Concentration & Characteristics:
The Commercial cooling meters market exhibits moderate concentration with a mix of established multinational corporations and emerging specialized players competing for market share. It features a competitive landscape where companies focus on product innovation, technological advancements, and strategic partnerships to strengthen their positions. The market demands high precision, reliability, and integration capabilities, prompting providers to continuously improve meter accuracy and smart functionality. Customization for diverse commercial applications and compliance with regional energy regulations also shape market dynamics. It favors companies that can deliver scalable solutions tailored to complex building management systems. Strong emphasis on customer support and after-sales service further differentiates key players. The market remains dynamic, driven by ongoing investments in smart infrastructure and sustainability initiatives globally.
Report Coverage:
The research report offers an in-depth analysis based on Type, Connectivity, End-Use, Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- Increasing global emphasis on energy efficiency will drive widespread adoption of commercial cooling meters.
- Integration of artificial intelligence and machine learning will enhance meter analytics and predictive maintenance capabilities.
- Expansion of smart city projects will create new demand for advanced cooling energy monitoring solutions.
- Rising retrofit activities in aging commercial buildings will boost the need for precise cooling measurement systems.
- Growing adoption of renewable energy sources will require compatible cooling meters for hybrid energy management.
- Development of wireless and IoT-enabled meters will improve remote monitoring and real-time data accessibility.
- Regulatory bodies will continue tightening energy consumption reporting standards, encouraging market growth.
- Collaboration between technology providers and utility companies will accelerate deployment of innovative metering solutions.
- Advances in sensor technology will improve accuracy and reduce costs, making commercial cooling meters accessible to smaller enterprises.
- Increasing awareness of carbon footprint reduction and sustainability certifications will reinforce investments in metering infrastructure.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Commercial cooling meters market, and what is its projected size by 2032?
At what compound annual growth rate (CAGR) is the Commercial cooling meters market expected to grow between 2024 and 2032?
What are the key drivers fueling the growth of the Commercial cooling meters market?
Who are the leading companies operating in the Commercial cooling meters market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Commercial Cooling Meters Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Commercial Cooling Meters Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 910.3 million → 2032: USD 1,407.6 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Commercial Cooling Meters Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Commercial Cooling Meters Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Commercial Cooling Meters Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Commercial Cooling Meters Market Drivers
- 3.3 Commercial Cooling Meters Market Restraints & Challenges
- 3.4 Commercial Cooling Meters Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Commercial Cooling Meters Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Commercial Cooling Meters Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Commercial Cooling Meters category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Commercial Cooling Meters Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Commercial Cooling Meters Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Commercial Cooling Meters. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Commercial Cooling Meters Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Commercial Cooling Meters Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Commercial Cooling Meters Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Commercial Cooling Meters (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Commercial Cooling Meters
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Commercial Cooling Meters Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Commercial Cooling Meters Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Commercial Cooling Meters Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Commercial Cooling Meters Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Commercial Cooling Meters Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Commercial Cooling Meters Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Commercial Cooling Meters Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Commercial Cooling Meters Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
