
Crosslinking Agents Market Overview:
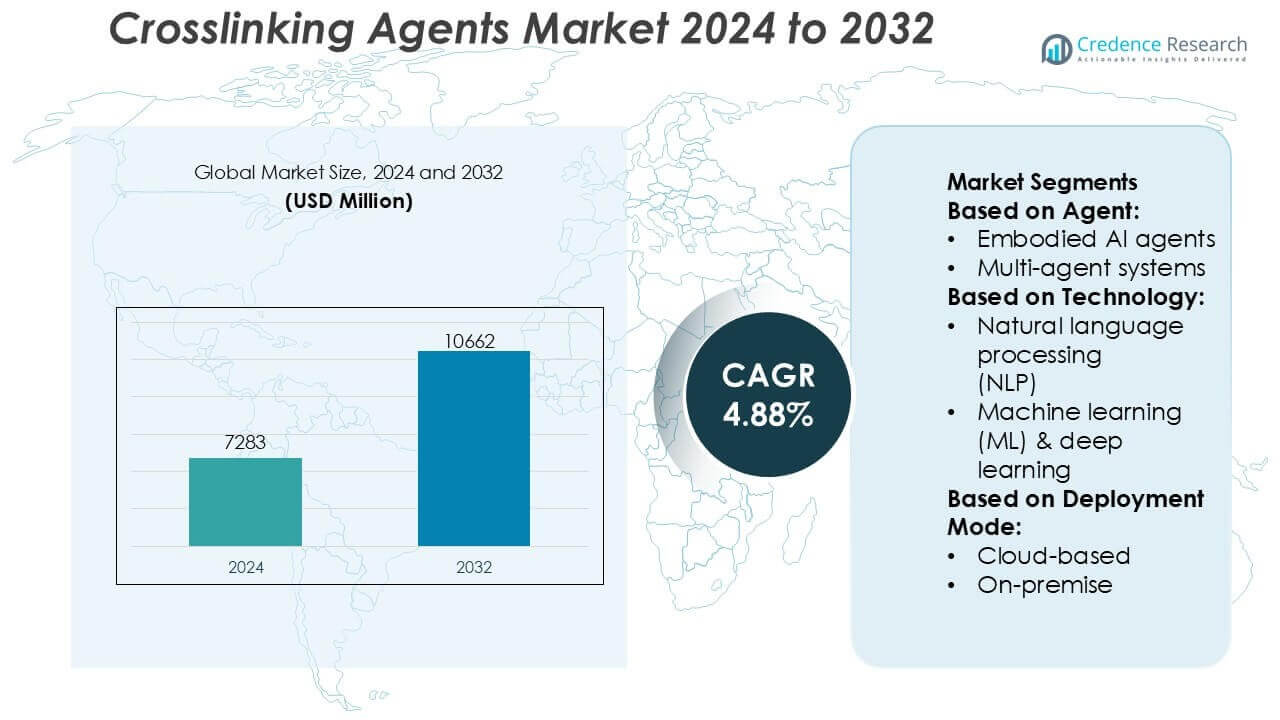
Crosslinking Agents Market size was valued USD 7283 million in 2024 and is anticipated to reach USD 10662 million by 2032, at a CAGR of 4.88% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Crosslinking Agents Market Size 2024 | USD 7283 million |
| Crosslinking Agents Market, CAGR | 4.88% |
| Crosslinking Agents Market Size 2032 | USD 10662 million |
Crosslinking Agents Market Insights
- Market growth is primarily driven by rising demand from coatings, adhesives, sealants, and composites, with epoxy- and polyurethane-based crosslinking agents together accounting for over 55% share due to superior mechanical strength and durability.
- Key market trends include increasing adoption of low-VOC, water-borne, and formaldehyde-free crosslinkers, alongside growing interest in bio-based chemistries to meet sustainability and regulatory requirements.
- Competitive dynamics are shaped by strong R&D investments, backward integration into intermediates, global manufacturing networks, and customized solutions that enhance performance and supply reliability for end users.
- Regionally, Asia-Pacific leads with approximately 39% market share, supported by rapid expansion in construction, automotive manufacturing, and industrial coatings, while Europe and North America follow with steady demand driven by regulatory-driven formulation upgrades.
Crosslinking Agents Market Segmentation Analysis:
By Agent
By agent type, conversational agents represent the dominant sub-segment, holding an estimated 41–43% market share, driven by their widespread deployment across customer support, enterprise automation, and digital commerce workflows. Conversational agents enable real-time human–machine interaction through text and voice interfaces, supporting tasks such as query resolution, transaction assistance, and guided decision-making. Their dominance is reinforced by rapid adoption in banking, healthcare, and retail, where scalable interaction handling and reduced response times are critical. Autonomous agents and multi-agent systems are gaining traction in complex decision environments, while embodied AI and task execution agents see targeted use in robotics and process automation.
- For instance, Wanhua Chemicals Group Co. Ltd. has integrated NLP-based conversational agents into its digital manufacturing and enterprise service platforms to support operations across more than 20 global production sites, where internal AI assistants are designed to process thousands of employee and supplier queries per day with response times measured in seconds, supporting faster issue resolution, standardized knowledge access, and more efficient cross-site coordination.
By Technology
By technology, large language models (LLMs) form the leading sub-segment with approximately 34–36% market share, supported by their ability to perform contextual reasoning, content generation, and multi-step task execution. LLMs integrate NLP, deep learning, and reinforcement learning capabilities into unified architectures, enabling advanced conversational depth and adaptive learning. Their dominance is driven by enterprise demand for scalable AI systems capable of handling unstructured data, multilingual interactions, and complex workflows. NLP and machine learning technologies maintain strong adoption as foundational layers, while computer vision and speech technologies expand use cases in multimodal and voice-enabled agent systems.
- For instance, BASF SE has implemented AI and language-model–driven solutions across its global Verbund operations, where machine-learning systems analyze data streams from more than 200,000 sensors at the Ludwigshafen site to support real-time process optimization, and internal AI platforms used by thousands of employees integrate large language models to search, summarize, and contextualize millions of pages of safety data sheets, technical reports, and formulation documents, significantly reducing manual data retrieval time and improving decision accuracy in R&D and manufacturing environments.
By Deployment Mode
By deployment mode, cloud-based deployment dominates the market with an estimated 46–48% market share, driven by scalability, rapid model updates, and lower infrastructure management requirements. Cloud platforms support high computational workloads, centralized model training, and seamless integration with enterprise software ecosystems, making them the preferred choice for large-scale agent deployments. On-premise solutions remain relevant in regulated industries requiring strict data control, while edge computing integration is expanding steadily, particularly in latency-sensitive applications such as real-time monitoring and autonomous systems. The growing emphasis on hybrid architectures further supports flexible, performance-optimized deployment strategies.
Key Growth Drivers
Rising Demand from Polymers, Coatings, and Adhesives
The expanding use of crosslinking agents in polymers, coatings, and adhesive formulations is a primary growth driver for the market. These agents enhance mechanical strength, chemical resistance, thermal stability, and durability of end products, making them essential in automotive, construction, packaging, and electronics applications. Increased infrastructure development, lightweight material adoption, and demand for high-performance coatings accelerate consumption. Manufacturers increasingly rely on advanced crosslinking chemistries to improve curing efficiency and extend product lifespan under demanding environmental and mechanical conditions.
- For instance, INEOS operates polymer production facilities with individual reactor capacities exceeding 500,000 tonnes per year, and its crosslinked polyethylene (PEX) materials are engineered to withstand continuous operating temperatures above 90 °C and short-term exposure up to 110 °C, supported by controlled crosslink density levels measured during extrusion and post-curing, demonstrating how precise crosslinking technologies directly translate into enhanced durability and thermal performance for industrial and infrastructure applications.
Growth of Automotive and Transportation Industries
The automotive and transportation sectors significantly drive crosslinking agent demand due to rising production volumes and the shift toward lightweight, high-strength materials. Crosslinking agents are widely used in rubber components, sealants, hoses, tires, and interior coatings to improve wear resistance and heat tolerance. The increasing focus on vehicle durability, safety standards, and emission reduction encourages the use of advanced polymer systems, where crosslinking agents play a critical role in enhancing performance and long-term reliability.
- For instance, Aditya Birla Group’s Novelis holds a global portfolio of hundreds of active patents related to aluminium rolling, recycling, and automotive sheet technologies. These innovations, including its Advanz™ and Fusion™ alloy platforms, underpin high-strength, lightweight structures for over 315 vehicle models, enabling significant weight reduction and advanced closed-loop recycling.
Expansion of Construction and Infrastructure Activities
Global growth in residential, commercial, and industrial construction strongly supports the crosslinking agents market. These agents are integral to cement modifiers, waterproofing systems, protective coatings, and insulation materials, where they improve bonding strength and environmental resistance. Urbanization, renovation of aging infrastructure, and increased spending on industrial facilities boost demand. The need for durable materials that withstand moisture, chemicals, and temperature fluctuations further reinforces the importance of crosslinking agents in construction-related applications.
Key Trends & Opportunities
Shift Toward Eco-Friendly and Low-Emission Formulations
A major trend in the crosslinking agents market is the shift toward environmentally friendly and low-emission chemistries. Regulatory pressure on volatile organic compounds and hazardous substances encourages manufacturers to develop water-based, low-toxicity, and bio-derived crosslinking agents. This trend creates strong opportunities for innovation, particularly in coatings, adhesives, and sealants used in indoor and consumer-facing applications, where environmental compliance and sustainability credentials increasingly influence purchasing decisions.
- For instance, Covestro AG reported that in fiscal 2024 it invested €392 million in research and development, employing 1,336 R&D specialists globally focused on developing new products and optimizing production and material performance.
Technological Advancements in High-Performance Crosslinking Systems
Continuous advancements in material science drive the development of high-performance crosslinking systems with improved curing speed, temperature tolerance, and compatibility with advanced polymers. Innovations such as UV-curable and moisture-activated crosslinking agents enable faster processing and energy-efficient manufacturing. These technologies open opportunities in electronics, aerospace, and advanced composites, where precision, performance consistency, and reduced production time are critical competitive factors.
- For instance, Evonik Industries AG has expanded its crosslinkers portfolio with products such as Ancamine® 2880, a fast-curing, UV-resistant epoxy curing agent engineered for enhanced abrasion resistance and service life across industrial coatings, and other Ancamine® grades like 2849 and 2859 designed for low-temperature cure applications that improve chemical resistance and reduce pot life during application.
Growing Adoption in Specialty and High-Value Applications
The rising use of crosslinking agents in specialty applications presents notable growth opportunities. Industries such as medical devices, electronics encapsulation, and specialty packaging increasingly require materials with precise mechanical and chemical properties. Crosslinking agents enable tailored performance characteristics, supporting miniaturization, enhanced protection, and extended product life. This trend supports higher-value formulations and encourages suppliers to focus on application-specific product development.
Key Challenges
Regulatory Compliance and Environmental Constraints
Strict environmental and safety regulations pose a significant challenge for crosslinking agent manufacturers. Compliance with chemical safety standards, emission limits, and worker exposure regulations increases development and production costs. Reformulating products to meet evolving regulatory requirements while maintaining performance consistency can be complex, particularly for legacy chemistries. These challenges may slow product approvals and limit adoption in highly regulated regions.
Volatility in Raw Material Supply and Pricing
Fluctuations in raw material availability and pricing create operational challenges for crosslinking agent producers. Many crosslinking agents rely on petrochemical-based inputs, making them sensitive to supply chain disruptions and feedstock price instability. Managing cost pressures while ensuring consistent quality and supply reliability remains a critical challenge, particularly for manufacturers serving price-sensitive end-use industries.
Regional Analysis
North America
North America represents a leading regional market for crosslinking agents, accounting for approximately 34–36% market share, supported by strong demand from automotive, construction, aerospace, and advanced coatings industries. The region benefits from a mature manufacturing base, high adoption of high-performance polymers, and continuous innovation in specialty chemicals. Stringent quality standards and advanced R&D capabilities drive the use of efficient and durable crosslinking systems. Additionally, growing investments in infrastructure renovation and lightweight automotive materials sustain steady demand, while regulatory emphasis on low-emission and safer chemical formulations encourages innovation in next-generation crosslinking technologies.
Europe
Europe holds an estimated 27–29% market share, driven by strong presence of automotive manufacturing, construction activities, and advanced industrial coatings applications. The region places high emphasis on sustainability, regulatory compliance, and material performance, which accelerates adoption of eco-friendly and low-VOC crosslinking agents. Demand is further supported by growth in renewable energy infrastructure, industrial equipment manufacturing, and high-durability protective coatings. European manufacturers actively focus on formulation optimization and specialty applications, particularly in high-value segments such as electronics, medical devices, and advanced composites, supporting stable market expansion.
Asia-Pacific
Asia-Pacific accounts for approximately 30–32% market share, making it the fastest-growing regional market for crosslinking agents. Rapid industrialization, expanding construction activity, and rising automotive production across China, India, and Southeast Asia strongly drive demand. The region benefits from large-scale manufacturing capacity, cost-competitive raw material access, and increasing adoption of advanced polymer systems. Growing investments in infrastructure, packaging, consumer goods, and electronics manufacturing further accelerate consumption. Additionally, improving regulatory frameworks and rising focus on product durability and performance support long-term growth across diverse end-use industries.
Latin America
Latin America contributes around 4–5% market share, supported by steady growth in construction, automotive assembly, and industrial coatings applications. Infrastructure development, urbanization, and expanding manufacturing activities in countries such as Brazil and Mexico drive demand for crosslinking agents. While adoption of advanced formulations remains moderate, increasing awareness of material durability and performance benefits encourages gradual market expansion. The region also benefits from improving industrial capabilities and foreign investments, which support demand for adhesives, sealants, and protective coatings incorporating crosslinking technologies.
Middle East & Africa
The Middle East & Africa region holds approximately 3–4% market share, driven primarily by construction, infrastructure development, and industrial coatings demand. Large-scale projects in commercial buildings, energy facilities, and transportation infrastructure increase the use of high-durability materials requiring crosslinking agents. Growth is supported by rising investments in industrial diversification and manufacturing capabilities, particularly in the Gulf region. Although market penetration remains comparatively lower, increasing focus on long-lasting materials and harsh-environment performance supports gradual adoption of advanced crosslinking solutions.
Crosslinking Agents Market Segmentations:
By Agent:
- Embodied AI agents
- Multi-agent systems
By Technology:
- Natural language processing (NLP)
- Machine learning (ML) & deep learning
By Deployment Mode:
- Cloud-based
- On-premise
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the crosslinking agents market players such as Wanhua Chemicals Group Co. Ltd., DSM Coatings Resin, BASF SE, Ineos, Allnex Group, Aditya Birla Corporation, Dow, Huntsman Corporation, Covestro AG, Evonik Industries. the crosslinking agents market is shaped by a mix of multinational chemical manufacturers and specialized formulation experts competing on performance, regulatory compliance, and application versatility. Market participants emphasize continuous innovation in epoxy, polyurethane, acrylic, and amino crosslinking systems to meet rising demand from coatings, adhesives, sealants, and composite applications. A strong shift toward low-VOC, water-borne, and formaldehyde-free chemistries reflects tightening environmental regulations and sustainability commitments across end-use industries. Companies increasingly differentiate through advanced R&D capabilities, application-specific customization, and technical support that enables faster product adoption by customers. Global production networks and backward integration into key intermediates support cost efficiency and supply stability, particularly in periods of raw-material volatility. Strategic capacity expansions, technology upgrades, and collaborations with downstream users remain central to maintaining competitiveness and capturing growth in automotive, construction, industrial, and high-performance materials segments.
Key Player Analysis
- Wanhua Chemicals Group Co. Ltd.
- DSM Coatings Resin
- BASF SE
- Ineos
- Allnex Group
- Aditya Birla Corporation
- Dow
- Huntsman Corporation
- Covestro AG
- Evonik Industries
Recent Developments
- In December 2025, Google released Google Workspace Studio, enabling business users to build and deploy AI-powered agents across Gmail, Drive, Chat, and other Google Workspace applications using the new Gemini 3 model.
- In November 2025, Baidu announced its new foundation model ERNIE 5.0, described as a natively omni-modal system capable of processing and generating across text, images, audio, and video. Alongside ERNIE 5.0, Baidu introduced a suite of AI offerings, including upgraded digital-human technology, a no-code application builder Miaoda, a general-AI agent GenFlow, a self-evolving agent Famou, and an integrated AI workspace Oreate for international deployment via its cloud and enterprise channels.
- In September 2024, Salesforce and Google Cloud announced the partnership in order to create Salesforce Agentforce Agents. This will allow consumers to deploy autonomous agents that can take action and seamlessly work with the apps utilized by consumers every day.
Report Coverage
The research report offers an in-depth analysis based on Agent, Technology, Deployment Mode and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for environmentally compliant crosslinking agents will increase as regulations favor low-VOC, water-based, and formaldehyde-free formulations.
- Advanced crosslinkers designed for high-performance coatings and adhesives will gain adoption in automotive and industrial applications.
- Growth in composites and engineered materials will expand the use of specialized crosslinking systems with enhanced thermal and mechanical properties.
- Innovation in bio-based and renewable crosslinking chemistries will accelerate to support sustainability goals.
- Asia-Pacific will remain a key growth region due to expanding manufacturing and infrastructure development.
- Customization and application-specific formulations will become critical competitive differentiators.
- Integration of crosslinking agents in high-solids and powder coatings will support efficiency and emission reduction targets.
- Strategic capacity expansions will address rising demand from construction and protective coatings segments.
- Collaboration between chemical suppliers and end users will strengthen product development and time-to-market.
- Ongoing investments in process optimization will improve performance consistency and cost competitiveness across applications.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Crosslinking Agents Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Crosslinking Agents Market projected to grow between 2024 and 2032?
Which Crosslinking Agents Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Crosslinking Agents Market?
Who are the leading companies in the Crosslinking Agents Market?
Which region commanded the largest share of the Crosslinking Agents Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7,283 million → 2032: USD 10,662 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Crosslinking Agents Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Crosslinking Agents Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Crosslinking Agents Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Crosslinking Agents Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Crosslinking Agents Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Crosslinking Agents Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Crosslinking Agents Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Crosslinking Agents Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7,283 million → 2032: USD 10,662 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Crosslinking Agents Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Crosslinking Agents Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Crosslinking Agents Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Crosslinking Agents Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

