
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Die-Cast Toys Market Size 2024 | USD 1,963.58 million |
| Die-Cast Toys Market, CAGR | 5.19% |
| Die-Cast Toys Market, Size 2032 | USD 2,943.94 million |
Market Overview
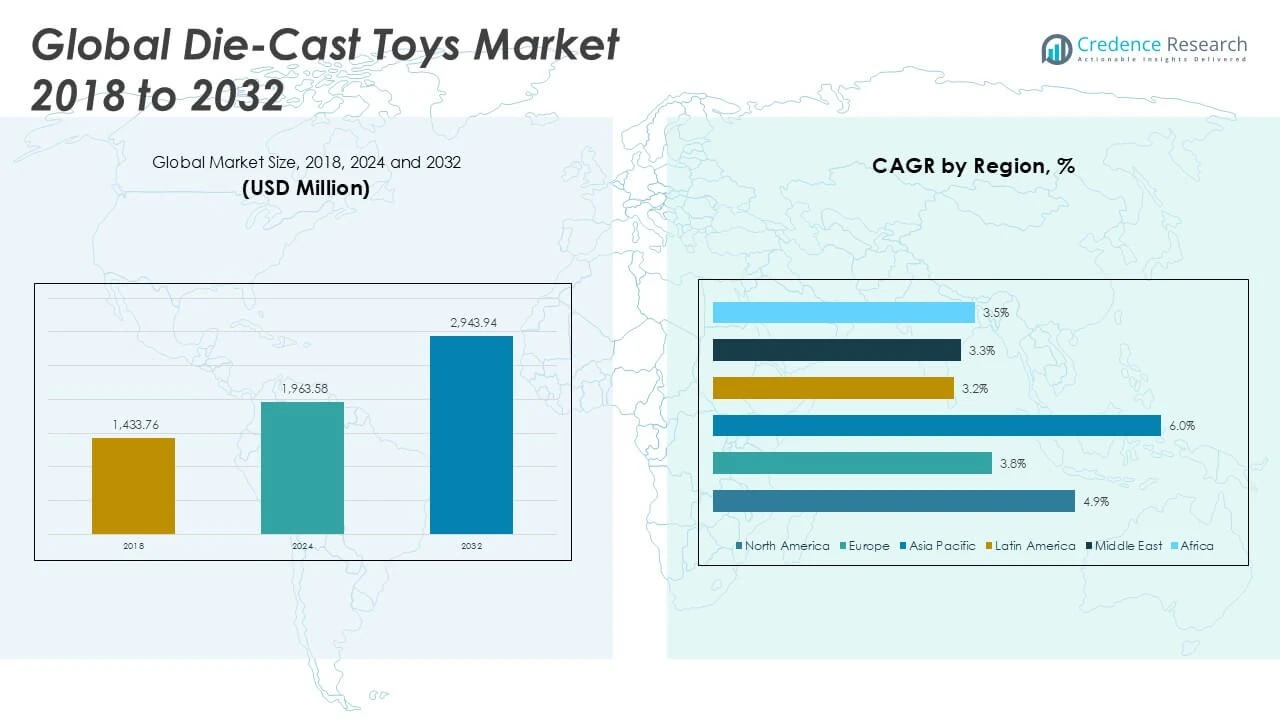
Die-Cast Toys Market size was valued at USD 1,433.76 million in 2018 to USD 1,963.58 million in 2024 and is anticipated to reach USD 2,943.94 million by 2032, at a CAGR of 5.19% during the forecast period.
The Die-Cast Toys Market is driven by rising consumer demand for collectible and high-quality model toys, fueled by both children and adult enthusiasts. Increasing disposable incomes, expanding e-commerce platforms, and frequent product launches featuring licensed characters and vehicles strengthen market growth. Manufacturers focus on precision detailing and innovative designs to attract collectors, while collaborations with entertainment franchises boost product appeal. The market benefits from growing interest in nostalgia-based toys, which appeal to adult consumers seeking to relive childhood memories. Sustainable materials and eco-friendly production practices are emerging as notable trends, aligning with shifting consumer preferences and regulatory requirements. Technological advancements in manufacturing processes enable greater customization and limited-edition releases, supporting premium pricing strategies. Regional market expansion, especially in Asia Pacific, further accelerates growth as urbanization and digital marketing efforts broaden consumer reach. Collectively, these factors contribute to a robust and evolving landscape for the Die-Cast Toys Market.
The Die-Cast Toys Market demonstrates strong geographical diversity, with significant presence across North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa. North America and Europe remain leading markets due to established collector bases, high disposable incomes, and frequent product launches featuring licensed themes. Asia Pacific is rapidly growing, driven by urbanization, rising middle-class populations, and increasing interest in collectible and branded toys, especially in China, Japan, and India. Latin America, the Middle East, and Africa show steady potential, supported by expanding retail sectors and youthful demographics. Key players in the Die-Cast Toys Market include Mattel, Inc., which is known for its iconic die-cast brands and continuous product innovation; Maisto International, Inc., recognized for its detailed vehicle replicas; and Tomica (TOMY Company, Ltd.), which has a strong footprint in Asia with a diverse product portfolio appealing to both children and collectors.
Market Insights
- The Die-Cast Toys Market is projected to grow from USD 1,963.58 million in 2024 to USD 2,943.94 million by 2032, at a CAGR of 5.19%.
- Rising demand for collectible and licensed die-cast models from both children and adults continues to drive market expansion globally.
- E-commerce growth and digital marketing strategies boost product visibility, making it easier for consumers to access a wide variety of die-cast toys.
- Key players such as Mattel, Inc., Maisto International, Inc., and Tomica (TOMY Company, Ltd.) focus on product innovation, brand collaborations, and expanding their distribution networks.
- Intense market competition and the prevalence of counterfeit products pose challenges to brand reputation and profitability.
- North America and Europe lead the market with a strong base of collectors and established retail channels, while Asia Pacific is witnessing the fastest growth, supported by urbanization and rising disposable incomes.
- Sustainable materials, eco-friendly packaging, and the integration of digital features into die-cast models represent notable trends shaping product development and consumer preferences
Market Drivers
Surging Consumer Demand for Collectibles and Licensed Products
The Die-Cast Toys Market benefits significantly from growing interest in collectibles and licensed merchandise among both children and adults. Collectors seek die-cast models of popular vehicles, iconic movie characters, and historical replicas, driving consistent demand. The appeal of limited-edition and themed product lines encourages repeat purchases and fosters strong brand loyalty. Collaborations with well-known entertainment franchises and automotive brands amplify consumer interest and elevate product prestige. The presence of passionate hobbyist communities and dedicated fan events further sustains enthusiasm for die-cast toys. This culture of collecting transforms the market into a dynamic segment within the broader toy industry.
- For instance, nostalgia-driven purchases have fueled demand for vintage-style die-cast models, with collectors seeking replicas of classic muscle cars and movie-themed vehicles.
Technological Advancements in Manufacturing and Design
Advances in die-casting technology and digital design tools empower manufacturers to produce highly detailed and realistic toys. Improved precision and automation allow for intricate features, enhanced durability, and efficient production. Companies leverage 3D modeling and prototyping to quickly adapt to emerging trends and consumer preferences. These innovations support the introduction of customizable models and premium offerings, which appeal to discerning collectors. Enhanced production capabilities also enable brands to launch special editions, driving value and market differentiation. The Die-Cast Toys Market continues to evolve, embracing technology to meet rising expectations.
- For instance, improvements in 3D modeling and die-casting techniques have enhanced the precision and durability of die-cast toys, making them more appealing to collectors.
E-Commerce Expansion and Global Distribution Networks
The rapid growth of e-commerce platforms has transformed the retail landscape for the Die-Cast Toys Market. Online marketplaces offer consumers greater access to a diverse range of products and exclusive releases, fueling cross-border demand. Manufacturers and retailers utilize digital marketing strategies to engage target audiences and showcase new launches. Streamlined logistics and efficient distribution networks ensure timely delivery and product availability across key regions. E-commerce facilitates direct-to-consumer sales, enhancing margins and customer relationships. The increased digital presence strengthens brand reach and accelerates global market penetration.
Sustainability Initiatives and Shifting Consumer Preferences
Rising environmental awareness among consumers prompts manufacturers to invest in sustainable materials and eco-friendly production practices. Brands introduce recyclable packaging and explore alternative metal alloys to reduce environmental impact. Regulatory pressure and ethical considerations guide innovation toward greener solutions. Consumers, particularly in developed markets, favor brands that demonstrate a commitment to sustainability and responsible sourcing. These initiatives not only align with regulatory trends but also build brand trust and foster customer loyalty. The Die-Cast Toys Market incorporates these drivers to remain competitive in a shifting global landscape.
Market Trends
Rising Demand for Licensed and Collectible Models
The Die-Cast Toys Market experiences growing demand for licensed and collectible models, driven by collaborations with popular entertainment franchises and automotive brands. Collectors and enthusiasts value authentic replicas of iconic vehicles, film characters, and limited-edition series. Manufacturers secure licensing agreements to introduce themed collections that resonate with a broad audience, creating exclusivity and increasing product appeal. This trend supports premium pricing strategies and encourages repeat purchases among both adult collectors and young consumers. Expanding fan communities and dedicated hobbyist events enhance market visibility, while digital platforms facilitate engagement and information sharing. The market leverages these dynamics to sustain interest and differentiate offerings.
- For instance, licensing agreements with major entertainment franchises have led to increased sales of die-cast toys featuring characters from blockbuster films.
Technological Innovations in Manufacturing and Customization
Technological advancements in die-casting processes and digital design have transformed the Die-Cast Toys Market, enabling manufacturers to produce highly detailed and realistic models. Precision engineering, automated assembly, and 3D printing capabilities allow for intricate features and customization options that appeal to discerning consumers. Brands introduce special editions and personalized models, strengthening customer loyalty and market differentiation. Improved manufacturing efficiency supports greater flexibility in responding to emerging trends and consumer preferences. This evolution in production techniques contributes to the introduction of premium product lines, driving value across both established and emerging markets. The market adapts these technologies to remain competitive and innovative.
- For instance, manufacturers are using digital prototyping to accelerate product development and introduce customizable die-cast models.
Expansion of E-Commerce and Direct-to-Consumer Sales Channels
E-commerce platforms and direct-to-consumer strategies play a pivotal role in the Die-Cast Toys Market, expanding product accessibility and broadening customer reach. Online marketplaces offer a diverse selection of models, exclusive releases, and global shipping options, increasing convenience for buyers. Brands utilize digital marketing and targeted advertising to engage specific segments, launch new products, and build brand communities. The integration of interactive online experiences, such as virtual showcases and live auctions, enhances customer engagement and supports brand loyalty. Efficient logistics and streamlined distribution networks ensure timely delivery and product availability across key regions. The market benefits from these channels to drive sales growth and brand visibility.
Focus on Sustainability and Eco-Friendly Materials
Sustainability initiatives increasingly influence the Die-Cast Toys Market, with manufacturers prioritizing the use of recycled metals and environmentally responsible packaging. Companies adopt eco-friendly production practices to address rising regulatory standards and consumer expectations for ethical sourcing. Product innovation now incorporates sustainable materials without compromising quality or durability. Transparency in supply chains and sustainability certifications help build consumer trust and reinforce positive brand reputation. Brands highlight these efforts in marketing communications, appealing to environmentally conscious buyers. The market integrates these sustainable practices to align with global trends and long-term growth objectives.
Market Challenges Analysis
Intensifying Competition and Price Sensitivity Limit Growth Potential
The Die-Cast Toys Market faces intensifying competition from both established players and emerging manufacturers, which puts significant pressure on pricing and profit margins. Companies must invest heavily in product innovation and licensing agreements to differentiate their offerings and maintain consumer interest. High levels of market saturation, particularly in developed regions, limit opportunities for rapid expansion and create challenges in sustaining long-term growth. The prevalence of counterfeit and low-cost alternatives in the market further erodes brand value and consumer trust, compelling established brands to focus on quality assurance and intellectual property protection. Companies also need to allocate resources for continuous marketing and brand engagement to remain competitive. These factors collectively constrain profitability and present hurdles in building and sustaining brand loyalty.
Supply Chain Disruptions and Regulatory Compliance Increase Operational Complexity
The Die-Cast Toys Market encounters operational challenges from volatile raw material prices, global supply chain disruptions, and evolving regulatory requirements. Fluctuating costs of metals and manufacturing inputs impact production planning and pricing strategies, while delays in shipping and logistics hinder timely product availability. Companies must navigate complex international regulations related to toy safety, environmental standards, and labor practices, which require ongoing investments in compliance and reporting systems. Efforts to incorporate sustainable materials and eco-friendly packaging demand upgrades in production processes and supply chain management. These operational hurdles increase costs and complicate efforts to streamline distribution and ensure consistent product quality across diverse markets.
- For instance, fluctuations in raw material costs, including metals used in die-cast production, have impacted pricing strategies and production planning.
Market Opportunities
Expansion into Emerging Markets and Untapped Demographics Fuels Growth
The Die-Cast Toys Market holds strong opportunities in expanding into emerging economies, where rising disposable incomes and urbanization contribute to increased consumer spending on toys and collectibles. It can tap into growing middle-class populations in regions such as Asia Pacific, Latin America, and the Middle East, where awareness and demand for branded toys are on the rise. Companies can introduce affordable product lines and localized designs to attract first-time buyers and foster brand loyalty among younger demographics. Targeting educational institutions and hobbyist communities further extends the market’s reach and creates avenues for repeat purchases. Strategic partnerships with local distributors and retailers enhance market penetration and visibility. The expansion into these markets positions brands for sustained long-term growth.
Innovation in Product Offerings and Digital Integration Drives Consumer Engagement
The Die-Cast Toys Market benefits from innovation in product design, digital integration, and personalized offerings. It can leverage advancements in 3D printing and smart manufacturing to create customizable and limited-edition models that cater to both collectors and enthusiasts. Integrating augmented reality features and interactive apps enhances the play and display experience, making products more attractive to tech-savvy consumers. Licensing agreements with popular entertainment and automotive franchises offer opportunities for exclusive collections that capture evolving consumer interests. Companies focusing on sustainable materials and eco-friendly packaging can appeal to environmentally conscious buyers, building a strong brand reputation. Embracing these innovations enables the market to differentiate itself and drive higher consumer engagement.
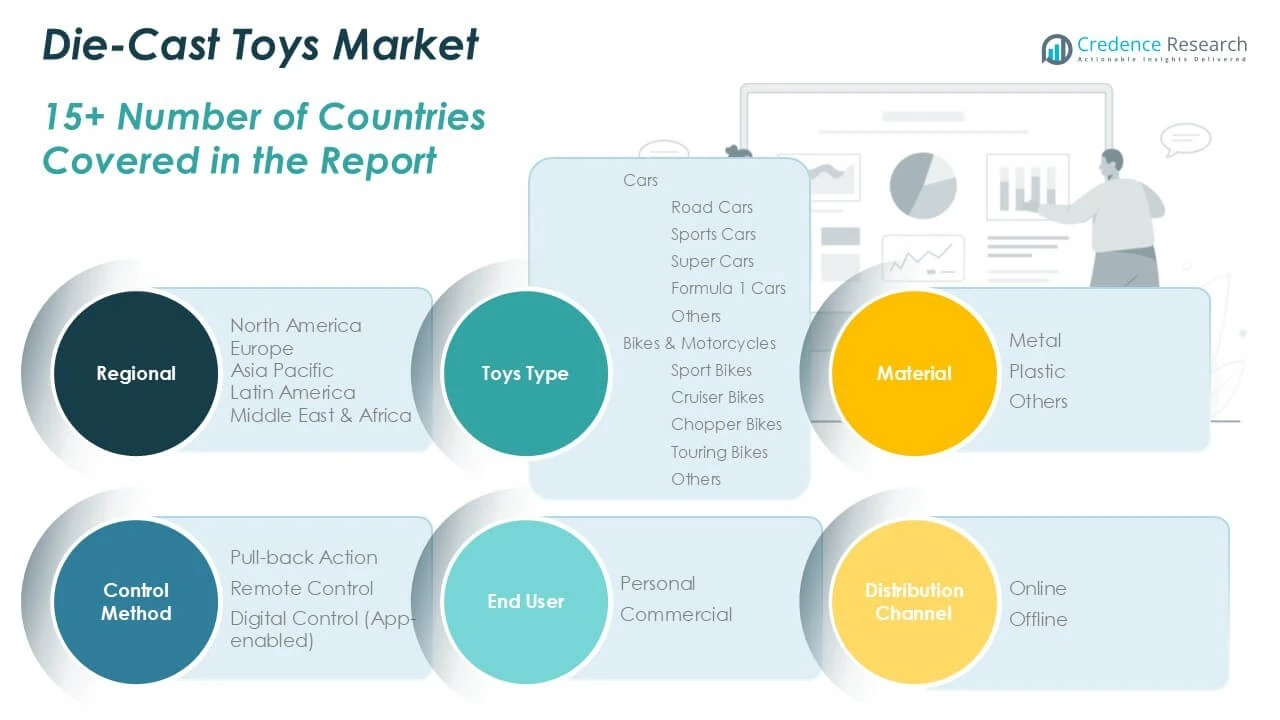
Market Segmentation Analysis:
By Type:
Cars dominate the market with strong sub-segments such as road cars, sports cars, and super cars, each catering to collectors and children attracted by realism and performance aesthetics. Construction sets within the car segment foster creativity and interactive engagement, while the “others” category accommodates niche and specialty vehicles. Bikes and motorcycles make up another dynamic segment, spanning sport bikes, cruiser bikes, chopper bikes, touring bikes, and unique models. These offerings appeal to motorcycle enthusiasts and collectors who seek variety in two-wheeled die-cast replicas.
By Material:
From a material perspective, metal remains the preferred choice due to its authenticity, weight, and collectible value, making it popular among adult hobbyists and premium buyers. Plastic models provide an economical alternative and appeal to younger audiences looking for durability and safety in play. Other material types are tailored for specific markets requiring unique properties or aesthetic enhancements.
By Control Method:
The market further segments by control method, supporting traditional play and integrating new technology. Pull-back action toys maintain popularity for their simplicity and classic appeal. Remote control models introduce interactive play, appealing to children and tech enthusiasts. Digital control, including app-enabled options, marks an emerging trend that attracts modern consumers who seek connectivity and innovative features. This layered segmentation structure allows the Die-Cast Toys Market to meet evolving consumer expectations, support innovation, and drive sustained growth across all user demographics.
Segments:
Based on Type:
- Cars
- Road Cars
- Sports Cars
- Super Cars
- Others
- Construction Sets
- Bikes & Motorcycles
- Sport Bikes
- Cruiser Bikes
- Chopper Bikes
- Touring Bikes
- Others
Based on Material:
- Metal
- Plastic
- Others
Based on Control Method:
- Pull-back Action
- Remote Control
- Digital Control (App-enabled)
Based on End- User:
- Personal
- Commercial
Based on Distribution Channel:
- Online
- Offline
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Die-Cast Toys Market
North America Die-Cast Toys market grew from USD 560.93 million in 2018 to USD 759.30 million in 2024 and is projected to reach USD 1,141.94 million by 2032, reflecting a compound annual growth rate (CAGR) of 4.9%. North America is holding a 30% market share, led by the United States and Canada. The region benefits from strong collector communities, high per capita incomes, and a mature retail landscape. Frequent launches of licensed and limited-edition products appeal to both children and adult collectors. The presence of major entertainment franchises and well-established e-commerce channels further boost sales and product accessibility. Regulatory standards ensure product safety and quality, supporting consumer confidence. Retailers and manufacturers invest in marketing and collaboration to strengthen brand loyalty.
Europe Die-Cast Toys Market
Europe Die-Cast Toys market grew from USD 304.45 million in 2018 to USD 396.86 million in 2024 and is projected to reach USD 547.90 million by 2032, reflecting a compound annual growth rate (CAGR) of 3.8%. Europe is holding a 27% market share, with Germany, the United Kingdom, and France as top contributors. The market thrives on a rich culture of collecting, supported by hobbyist clubs and specialized retailers. European consumers value authenticity and premium quality, driving demand for metal die-cast toys and environmentally conscious materials. Local brands maintain a legacy of craftsmanship and innovation. The growing adoption of app-enabled and interactive models aligns with evolving consumer preferences. Regional distribution networks support widespread product availability.
Asia Pacific Die-Cast Toys Market
Asia Pacific Die-Cast Toys market grew from USD 393.57 million in 2018 to USD 570.68 million in 2024 and is projected to reach USD 936.98 million by 2032, reflecting a compound annual growth rate (CAGR) of 6.0%. Asia Pacific is holding a 29% market share. China, Japan, and India are major markets, propelled by rapid urbanization, rising middle-class populations, and expanding disposable incomes. Local manufacturers deliver cost-effective production and cater to strong domestic demand, especially for car and motorcycle models. E-commerce platforms and digital marketing expand reach to new consumers. Collaborations with popular entertainment and automotive franchises further stimulate demand for licensed products. The region’s affinity for technology encourages adoption of digital control toys.
Latin America Die-Cast Toys Market
Latin America Die-Cast Toys market grew from USD 68.03 million in 2018 to USD 92.02 million in 2024 and is projected to reach USD 122.18 million by 2032, reflecting a compound annual growth rate (CAGR) of 3.2%. Latin America is holding a 8% market share, with Brazil and Mexico leading in sales. Young demographics, urbanization, and increasing exposure to global brands underpin growth. Price sensitivity influences purchasing decisions, driving preference for affordable plastic and hybrid models. Manufacturers respond by offering localized product ranges and engaging promotions. Expansion of retail and e-commerce channels improves access to branded toys. Strategic alliances with local distributors support broader market penetration.
The Middle East Die-Cast Toys Market
The Middle East Die-Cast Toys market grew from USD 56.63 million in 2018 to USD 72.84 million in 2024 and is projected to reach USD 97.43 million by 2032, reflecting a compound annual growth rate (CAGR) of 3.3%. The Middle East is holding a 4% market share, driven by economic development in the Gulf Cooperation Council (GCC) countries and urban centers. Demand centers on premium products and collectible cars, with a growing interest in high-end models among affluent consumers. Retailers focus on expanding toy sections and introducing global brands in major malls and specialty stores. E-commerce is gaining traction, making exclusive and imported models more accessible. Challenges include seasonal demand fluctuations and the need for region-specific marketing. Local partnerships and adaptation to cultural preferences support sustained market presence.
Africa Die-Cast Toys Market
Africa Die-Cast Toys market grew from USD 50.15 million in 2018 to USD 71.87 million in 2024 and is projected to reach USD 97.51 million by 2032, reflecting a compound annual growth rate (CAGR) of 3.5%. Africa is holding a 2% market share, shaped by demographic growth and urban expansion in countries such as South Africa, Nigeria, and Kenya. The market emphasizes affordability and durability, catering mainly to young children. Limited distribution channels and lower average incomes present challenges for premium product segments. Manufacturers offering cost-effective models and collaborating with local retailers find opportunities for gradual expansion. Awareness campaigns and partnerships with educational institutions can increase demand and brand recognition. Growth potential remains untapped as infrastructure and retail landscapes continue to develop.
Key Player Analysis
- Mattel, Inc.
- LEGO Group
- Hasbro, Inc.
- Jada Toys, Inc.
- Maisto International, Inc.
- Tomica (TOMY Company, Ltd.)
- Welly Diecast
- Yat Ming
- Greenlight Collectibles
- Majorette
Competitive Analysis
The Die-Cast Toys Market features a dynamic competitive landscape shaped by leading players such as Mattel, Inc., LEGO Group, Hasbro, Inc., Jada Toys, Inc., Maisto International, Inc., Tomica (TOMY Company, Ltd.), Welly Diecast, Yat Ming, Greenlight Collectibles, and Majorette. These companies invest significantly in product innovation, licensing agreements, and marketing strategies to capture diverse consumer segments. Leading companies consistently invest in research and development to introduce new models, advanced detailing, and licensed products that attract both children and collectors. Strategic collaborations with entertainment franchises and automotive brands strengthen product appeal and drive repeat purchases. Companies prioritize global distribution, leveraging e-commerce platforms and regional partnerships to broaden market reach and improve consumer accessibility. Competition also drives the adoption of sustainable materials, eco-friendly packaging, and integration of digital features such as app-enabled controls to stay ahead of market trends. The market faces persistent challenges from counterfeit products and price-sensitive segments, prompting manufacturers to emphasize quality assurance and brand protection strategies. Overall, the competitive landscape compels continuous product enhancement, marketing innovation, and adaptation to changing consumer demands.
Recent Developments
- In March 2025, Toy Fair, LEGO showcased its largest-ever portfolio, including the new Bluey theme in partnership with BBC Studios and the intricate LEGO Ideas River Steamboat set for adult builders.
- In January 2025, Majorette has unveiled a new logo and entered the true 1/64 scale segment, marking a significant shift from their traditional sizing. This move aligns the brand with collector expectations and industry standards.
- In January 2025, Mattel entered the building sets market with the Mattel Brick Shop brand, debuting building sets that include exclusive 1:64 scale die-cast Hot Wheels cars.
Market Concentration & Characteristics
The Die-Cast Toys Market displays moderate to high market concentration, with a handful of prominent players such as Mattel, Inc., Maisto International, Inc., Tomica (TOMY Company, Ltd.), and Hasbro, Inc. commanding significant influence. It features a blend of global brands and specialized manufacturers that compete across multiple product segments, from cars and motorcycles to construction sets and limited-edition collectibles. The market thrives on innovation, licensing agreements, and quality differentiation, with leading companies frequently launching new models and collaborating with entertainment and automotive franchises. It also reflects strong brand loyalty among collectors and hobbyists, while catering to a broad consumer base that includes both children and adults. The Die-Cast Toys Market is characterized by its focus on product authenticity, durable materials, and the integration of digital features, which support its ongoing evolution in response to changing consumer trends and regulatory standards.
Report Coverage
The research report offers an in-depth analysis based on Type, Material, Control Method, End-User, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is projected to experience steady growth, driven by increasing demand for collectible and licensed die-cast models.
- Nostalgia and retro-themed products continue to appeal to adult collectors, fueling demand for vintage-style releases and limited editions.
- The rise of e-commerce platforms enhances global accessibility, allowing consumers to explore and purchase a diverse range of die-cast toys.
- Manufacturers are focusing on sustainability by adopting eco-friendly materials and reducing plastic usage in packaging.
- Technological advancements enable the integration of digital features, such as app-enabled controls, enhancing interactivity and user engagement.
- Collaborations with entertainment franchises and automotive brands remain pivotal in expanding product portfolios and attracting diverse consumer segments.
- Emerging markets, particularly in Asia Pacific, present significant growth opportunities due to rising disposable incomes and urbanization.
- The popularity of die-cast vehicles, especially cars and motorcycles, continues to dominate, driven by detailed replicas and brand affiliations.
- Online communities and collector forums play a crucial role in influencing purchasing decisions and fostering brand loyalty.
- Continuous innovation in design and manufacturing processes ensures the production of high-quality, detailed models that meet evolving consumer preferences.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Surging Consumer Demand for Collectibles and Licensed Products
The popularity of collectible die-cast models, especially those featuring licensed vehicles and entertainment franchises, is driving repeat purchases among both children and adult collectors. Limited-edition releases and nostalgia-driven themes foster strong brand loyalty and expand the consumer base.
Technological Advancements in Manufacturing and Design
Innovations in die-casting technology, 3D modeling, and digital prototyping enable manufacturers to produce highly detailed, realistic, and customizable models. This supports premium product lines and appeals to discerning collectors seeking authenticity and uniqueness.
E-Commerce Expansion and Global Distribution Networks
The growth of online marketplaces and direct-to-consumer sales channels has made die-cast toys more accessible globally, increasing product visibility and enabling cross-border sales. Efficient logistics and digital marketing further accelerate market penetration and consumer engagement.
Sustainability Initiatives and Eco-Friendly Materials
Rising environmental awareness and regulatory pressures are prompting manufacturers to adopt sustainable materials and eco-friendly packaging. These initiatives align with consumer preferences, particularly in developed markets, and help build brand trust and loyalty.
Collaborations with Entertainment and Automotive Brands
Strategic partnerships with popular entertainment franchises and automotive companies allow manufacturers to launch themed collections that resonate with a wide audience. These collaborations enhance product appeal, support premium pricing, and drive market differentiation.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Die-Cast Toys Market?
What factors are driving the growth of the Die-Cast Toys Market?
What are some challenges faced by the Die-Cast Toys Market?
Who are the major players in the Die-Cast Toys Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Cars (Road Cars, Sports Cars, Super Cars, Others)
- 1.2.2 Construction Sets
- 1.2.3 Bikes & Motorcycles (Sport Bikes, Cruiser Bikes, Chopper Bikes, Touring Bikes, Others)
- 1.3 By Material
- 1.3.1 Metal
- 1.3.2 Plastic
- 1.3.3 Others
- 1.4 By Control Method
- 1.4.1 Pull-back Action
- 1.4.2 Remote Control
- 1.4.3 Digital Control (App-enabled)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,963.58 million → 2032: USD 2,943.94 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Die-Cast Toys Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Die-Cast Toys Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Die-Cast Toys Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Die-Cast Toys Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Die-Cast Toys Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Die-Cast Toys Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Die-Cast Toys Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Die-Cast Toys Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,963.58 million → 2032: USD 2,943.94 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Die-Cast Toys Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Cars (Road Cars, Sports Cars, Super Cars, Others)
- 12.3.7.2 Construction Sets
- 12.3.7.3 Bikes & Motorcycles (Sport Bikes, Cruiser Bikes, Chopper Bikes, Touring Bikes, Others)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Metal
- 12.4.7.2 Plastic
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Control Method - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Pull-back Action
- 12.5.7.2 Remote Control
- 12.5.7.3 Digital Control (App-enabled)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Die-Cast Toys Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Die-Cast Toys Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Die-Cast Toys Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Mattel, Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 LEGO Group
- 17.4 Hasbro, Inc.
- 17.5 Jada Toys, Inc.
- 17.6 Maisto International, Inc.
- 17.7 Tomica (TOMY Company, Ltd.)
- 17.8 Welly Diecast
- 17.9 Yat Ming
- 17.10 Greenlight Collectibles
- 17.11 Majorette
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

