
Market Overview
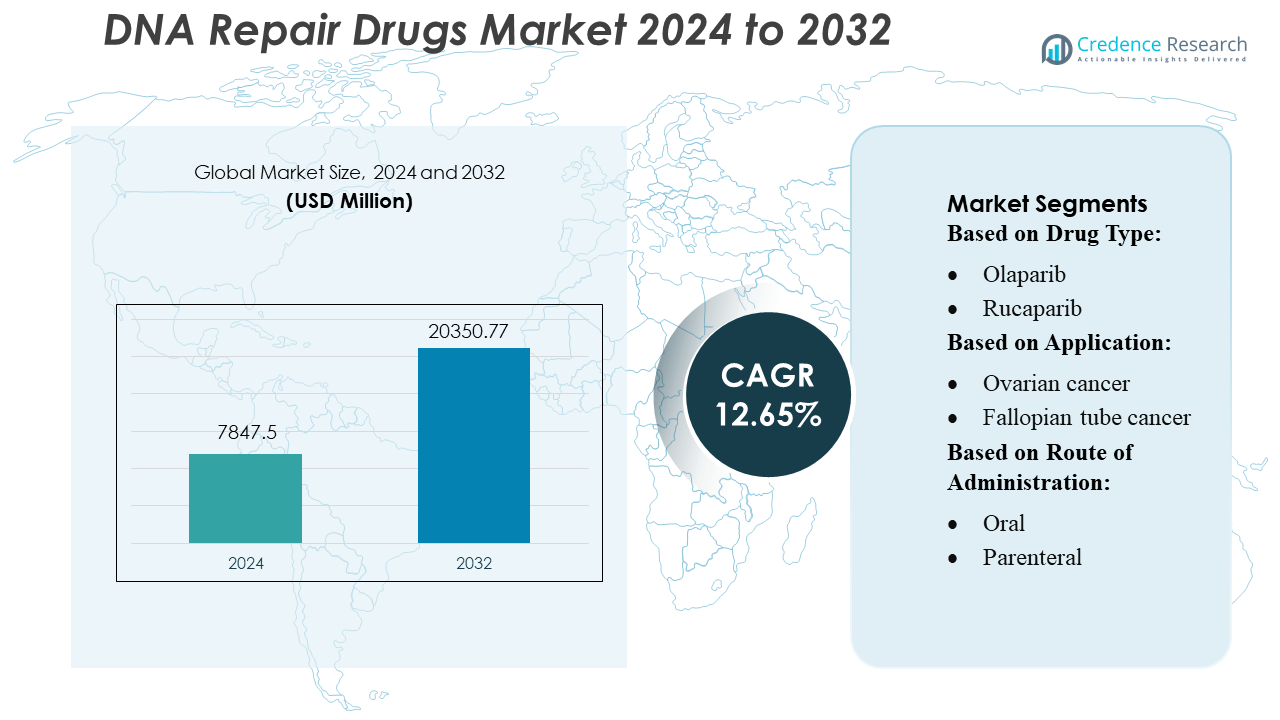
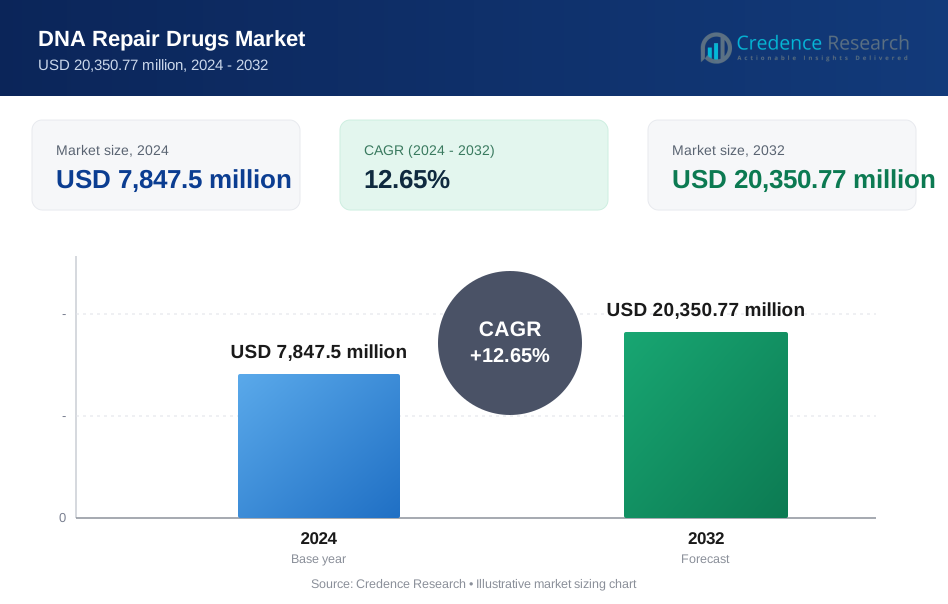
DNA Repair Drugs Market size was valued USD 7847.5 million in 2024 and is anticipated to reach USD 20350.77 million by 2032, at a CAGR of 12.65% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| DNA Repair Drugs Market Size 2024 | USD 7847.5 Million |
| DNA Repair Drugs Market, CAGR | 12.65% |
| DNA Repair Drugs Market Size 2032 | USD 20350.77 Million |
The DNA repair drugs market is shaped by strong participation from leading pharmaceutical and biotechnology companies, including FoRx Therapeutics, Merck KGaA, Artios Pharma Limited, GlaxoSmithKline plc., Clovis Oncology Inc., Breakpoint Therapeutics, Luciole Pharmaceuticals, AbbVie, Johnson & Johnson, and AstraZeneca Plc. These players compete through advancements in PARP inhibitors, expansion into next-generation DDR targets, and strategic collaborations aimed at strengthening clinical pipelines. North America remains the leading region in this market, holding 42% of the global share, supported by advanced oncology infrastructure, high genomic testing rates, and rapid adoption of targeted therapies across multiple cancer types.
Market Insights
- The DNA Repair Drugs Market was valued at USD 7,847.5 million in 2024 and is projected to reach USD 20,350.77 million by 2032, growing at a CAGR of 12.65%, driven by rising cancer incidence and increasing adoption of precision oncology.
- Market growth accelerates due to expanding use of PARP inhibitors, wider BRCA/HRD genetic testing, and strong clinical evidence supporting targeted maintenance therapies across ovarian, breast, prostate, and pancreatic cancers.
- Key players, including FoRx Therapeutics, Merck KGaA, Artios Pharma Limited, GlaxoSmithKline plc., and AstraZeneca Plc., strengthen competition through DDR pipeline expansion, combination-therapy development, and strategic R&D collaborations.
- High drug costs, treatment resistance, and limited diagnostic access in emerging economies restrain broader adoption, slowing penetration despite strong therapeutic demand.
- North America leads with 42% market share, while oral formulations dominate with nearly 80% share; ovarian cancer remains the largest application segment, supported by strong clinical adoption and frontline therapy approvals.
Market Segmentation Analysis:
By Drug Type
Olaparib leads the DNA repair drugs market, accounting for an estimated 42–45% share, driven by its broad regulatory approvals across BRCA-mutated ovarian, breast, pancreatic, and prostate cancers. Its strong clinical evidence, including improved progression-free survival in multiple Phase III trials, strengthens adoption across oncology clinics. Niraparib follows due to its advantage as the only PARP inhibitor approved for both BRCA-mutated and non-mutated ovarian cancers. Rucaparib and Talazoparib show moderate uptake, while other drug types occupy a smaller niche driven by pipeline diversity and combination-therapy trials.
- For instance, FoRx Therapeutics is targeting a distinct DDR vulnerability via FORX-428, a PARG inhibitor with an IC₅₀ of < 1 nM in biochemical assays and < 4 nM in cell-based assays, based on its own preclinical profiling.
By Application
Ovarian cancer remains the dominant application segment, holding over 50% market share, supported by high treatment demand and strong clinical validation of PARP inhibitors as maintenance therapy post-platinum chemotherapy. The segment’s growth is driven by rising early genetic testing, expanded frontline therapy approvals, and improved survival outcomes in recurrent disease. Breast cancer forms the second-largest segment, supported by approvals in HER2-negative BRCA-mutated patients. Fallopian tube and peritoneal cancers contribute steadily, while other applications grow as PARP inhibitors advance into prostate, pancreatic, and solid-tumor combination regimens.
- For instance, FoRx Therapeutics is targeting a distinct DDR vulnerability via FORX-428, a PARG inhibitor with an IC₅₀ of < 1 nM in biochemical assays and < 4 nM in cell-based assays, based on its own preclinical profiling.
By Route of Administration
The oral route dominates with nearly 80% share, driven by the fact that leading PARP inhibitors-Olaparib, Rucaparib, Niraparib, and Talazoparib-are all available as oral formulations, offering superior patient convenience and adherence compared to clinic-based therapies. The rising preference for at-home cancer management, reduced hospital visits, and favorable pharmacokinetic profiles further accelerate adoption. The parenteral segment remains comparatively small and is driven mainly by emerging combination treatments evaluated in intravenous immunotherapy and targeted-therapy regimens under clinical development.
Key Growth Drivers
- Rising Prevalence of BRCA-Mutated and HRD-Positive Cancers The increasing global incidence of BRCA1/BRCA2 mutations and homologous recombination deficiency (HRD) across ovarian, breast, prostate, and pancreatic cancers strongly drives demand for DNA repair drugs. Wider adoption of genomic profiling enables earlier detection of gene mutations, making targeted therapies such as PARP inhibitors the preferred treatment option. As precision oncology expands, more patients qualify for mutation-specific therapies, accelerating clinical uptake and market penetration. This growing diagnostic integration significantly boosts the overall demand for DNA repair–focused therapeutics.
- For instance, Artios Pharma Limited has demonstrated clear proof of concept in this area: its ATR inhibitor alnodesertib (ART0380), in combination with low-dose irinotecan, achieved a 50% confirmed overall response rate (cORR) in ATM-negative solid tumor patients in its Phase 1/2a STELLA trial.
- Expansion of Regulatory Approvals for PARP Inhibitors Regulatory agencies continue to broaden indications for DNA repair drugs, particularly PARP inhibitors, across multiple cancer types and treatment lines. Approvals for frontline maintenance therapy, metastatic settings, and recurrent disease enhance clinical utility and increase patient access. Accelerated approvals supported by strong Phase III trial outcomes further strengthen market growth. Additionally, companion diagnostic approvals streamline patient selection, improving treatment outcomes and boosting confidence among oncologists. This continuous regulatory momentum supports sustained expansion of the DNA repair drugs market.
- For instance, GlaxoSmithKline plc. has secured multiple global approvals for its PARP inhibitor niraparib, supported by strong late-stage data. In the PRIMA Phase III trial, niraparib achieved a median progression-free survival of 21.9 months in HRD-positive advanced ovarian cancer patients compared with 10.4 months for standard therapy.
- Growing Adoption of Combination Therapies Combination regimens involving PARP inhibitors with immunotherapies, angiogenesis inhibitors, and DNA-damaging chemotherapies create new clinical opportunities and drive market expansion. These synergistic approaches aim to overcome resistance mechanisms and improve long-term patient survival. Ongoing trials exploring PARP–PD-1/PD-L1 combinations and PARP–ATR inhibitor combinations broaden therapeutic scope across solid tumors. As combination therapies demonstrate promising efficacy in previously unresponsive patients, pharmaceutical companies invest heavily in joint development programs, accelerating innovation and expanding the treatment landscape.
Key Trends & Opportunities
- Increasing Focus on Next-Generation DNA Repair Targets Beyond PARP inhibition, industry players are shifting focus toward next-generation DNA repair pathways such as ATR, ATM, DNA-PK, and polymerase theta. These emerging targets offer significant opportunities to overcome resistance and treat tumors with diverse genetic profiles. Multiple early-stage pipelines show encouraging safety and efficacy signals, presenting long-term growth potential. As understanding of synthetic lethality deepens, developers aim to create multi-target inhibitors and dual-mechanism drugs, opening new segments within precision oncology and expanding revenue possibilities.
- For instance, ARIEL2, genomic sequencing of 491 tumor samples identified distinct resistance-associated alterations, including RAD51 upregulation and BRCA reversion mutations, observed in 32 analyzed cases, underscoring why next-generation pathways must be targeted.
- Rising Demand for Personalized and Biomarker-Driven Therapies Advancements in genomic sequencing and tumor profiling enhance the ability to match patients with highly targeted DNA repair therapies. Increased availability of cost-effective next-generation sequencing (NGS) promotes broader biomarker testing, expanding the eligible patient pool. Precision oncology initiatives from hospitals and government agencies further support biomarker-driven prescribing patterns. This trend creates opportunities for drug–diagnostic partnerships, companion test development, and personalized treatment algorithms, ultimately improving treatment outcomes and driving market growth.
- For instance, Breakpoint Therapeutics-a company dedicated to DNA damage response drug development-was launched with a €30 million Series A financing round, enabling the build-out of high-throughput genomic screening platforms that evaluate DDR pathway vulnerabilities across more than 200 engineered cellular models.
- Untapped Potential in Emerging Markets Emerging economies in Asia-Pacific, Latin America, and the Middle East present substantial growth opportunities due to improving cancer diagnosis infrastructure and rising awareness of genetic testing. As healthcare systems modernize, patient access to targeted therapies increases, supported by expanding reimbursement policies and oncology investments. Growing oncology clinical trial activity in these regions also accelerates drug adoption. Pharmaceutical companies are actively strengthening regional distribution networks and partnerships, creating long-term expansion opportunities across underpenetrated markets.
Key Challenges
- High Treatment Costs and Limited Reimbursement Coverage The premium pricing of PARP inhibitors and other DNA repair drugs poses a significant barrier, particularly in developing markets with limited insurance coverage. High out-of-pocket expenses restrict patient accessibility, reducing optimal utilization despite clinical benefits. Reimbursement policies remain inconsistent across regions, and stringent cost-effectiveness evaluations by payers delay market entry in many countries. These financial barriers hinder widespread adoption and limit the overall growth potential of the DNA repair drugs market.
- Development of Drug Resistance in Long-Term Therapy The emergence of acquired resistance to PARP inhibitors presents a critical clinical challenge, reducing long-term treatment efficacy. Tumor cells adapt through restoration of homologous recombination pathways, drug efflux mechanisms, or mutations that undermine therapeutic response. This resistance complicates treatment strategies, requiring alternative regimens, combination therapy approaches, or next-generation inhibitors. Addressing resistance demands substantial research investment, extended clinical trial timelines, and innovative mechanism-based drug design, creating operational and scientific challenges for developers.
Regional Analysis
North America North America holds the largest share of the DNA repair drugs market, accounting for around 40–42%, driven by strong adoption of PARP inhibitors, extensive genomic testing coverage, and a high prevalence of BRCA-mutated cancers. The region benefits from advanced oncology infrastructure, favorable reimbursement frameworks, and rapid integration of companion diagnostics that support personalized treatment. The presence of major pharmaceutical companies and ongoing clinical trials further accelerate innovation. Increasing patient awareness and early cancer screening rates continue to strengthen market growth, solidifying North America’s position as the leading regional contributor.
Europe
Europe represents the second-largest regional market with approximately 28–30% share, supported by widespread utilization of targeted therapies, strong national cancer control programs, and broad access to genomic profiling. Countries such as Germany, the U.K., and France drive market expansion through favorable reimbursement for PARP inhibitors and structured clinical pathways for BRCA and HRD testing. The region also benefits from active clinical research networks and accelerated regulatory approvals from the EMA. Rising adoption of maintenance therapy in ovarian and breast cancers continues to strengthen Europe’s overall market presence.
Asia-Pacific
Asia-Pacific is the fastest-growing region and accounts for around 20–22% share, driven by improving cancer diagnosis rates, increasing investment in precision oncology, and expanding patient access to targeted therapies. Countries such as China, Japan, South Korea, and Australia show strong uptake due to the growing availability of BRCA testing and rapid approval of PARP inhibitors. Rising healthcare expenditure, supportive government initiatives, and expanding clinical trial participation contribute to accelerated market penetration. The region’s large patient population and underdiagnosed BRCA mutation base create significant long-term growth potential.
Latin America
Latin America holds approximately 5–6% share, with growth influenced by gradual improvements in genetic testing accessibility and expanding adoption of targeted therapies in major markets such as Brazil, Mexico, and Argentina. While reimbursement challenges persist, increasing private healthcare spending and oncology-focused investments support moderate demand. The introduction of cost-effective diagnostic platforms and participation in international clinical research programs help drive awareness and early mutation detection. As regulatory frameworks evolve and more targeted therapies become accessible, the region continues to show steady but emerging growth potential.
Middle East & Africa
The Middle East & Africa region accounts for around 3–4% share, driven by rising cancer incidence and improving access to advanced therapies in Gulf Cooperation Council (GCC) countries. Wealthier markets such as the UAE, Saudi Arabia, and Qatar exhibit growing adoption of genomic testing and targeted oncology treatments due to strong healthcare modernization initiatives. However, limited diagnostic infrastructure and affordability issues restrict broader uptake across Africa. International collaborations and oncology center expansions are gradually improving access, supporting incremental growth in DNA repair drug utilization across the region.
Market Segmentations:
By Drug Type:- Olaparib
- Rucaparib
By Application:
- Ovarian cancer
- Fallopian tube cancer
By Route of Administration:
- Oral
- Parenteral
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the DNA repair drugs market features a mix of established pharmaceutical leaders and emerging biotechnology innovators, including FoRx Therapeutics, Merck KGaA, Artios Pharma Limited, GlaxoSmithKline plc., Clovis Oncology Inc., Breakpoint Therapeutics, Luciole Pharmaceuticals, AbbVie, Johnson & Johnson, and AstraZeneca Plc. The DNA repair drugs market is defined by rapid innovation, expanding clinical pipelines, and increasing investment in next-generation DNA damage response (DDR) therapies. Companies actively pursue advancements in PARP, ATR, ATM, and DNA-PK inhibition to strengthen their oncology portfolios and address unmet needs in solid tumors. Strategic collaborations, licensing agreements, and biomarker-driven clinical development serve as key competitive strategies, enabling faster entry into high-value cancer segments. Market participants focus heavily on combination-therapy research to overcome resistance and extend patient survival. Growing emphasis on precision oncology, companion diagnostics, and scalable manufacturing capabilities further intensifies competition across global markets.
Key Player Analysis
- FoRx Therapeutics
- Merck KGaA
- Artios Pharma Limited
- GlaxoSmithKline plc.
- Clovis Oncology Inc.
- Breakpoint Therapeutics
- Luciole Pharmaceuticals
- AbbVie
- Johnson & Johnson
- AstraZeneca Plc
Recent Developments
- In October 2025, Mabwell presented data from a Phase I/II study of its B7-H3 antibody-drug conjugate (ADC), 7MW3711, at the European Society for Medical Oncology (ESMO) Congress. The results showed that the ADC produced tumor regression (partial and complete responses) in patients with B7-H3-positive solid tumors, including esophageal and lung cancers.
- In January 2025, Senaparib Approved by NMPA for 1L Maintenance Therapy in Ovarian Cancer. Impact Therapeutics received Chinese marketing authorization for senaparib as maintenance therapy for advanced ovarian cancer.
- In June 2023, AstraZeneca introduced IMJUDO® (tremelimumab) in the UAE, pioneering cancer treatment in the Middle East. The groundbreaking medication heralds a new era in cancer therapy, offering hope to patients and positioning the UAE at the forefront of medical innovation in the region.
Report Coverage
The research report offers an in-depth analysis based on Drug Type, Application, Route of Administration and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand as genomic testing becomes routine in oncology and identifies more patients eligible for DNA repair–targeted therapies.
- PARP inhibitors will maintain strong momentum while next-generation DDR targets such as ATR, ATM, and DNA-PK gain commercial relevance.
- Combination therapies integrating PARP inhibitors with immunotherapy and targeted agents will shape future treatment standards.
- Earlier-line approvals across multiple tumor types will significantly broaden clinical use.
- Advances in synthetic lethality research will drive the development of more selective and durable DNA repair inhibitors.
- Resistance-mitigation strategies will influence innovation, leading to improved second-generation therapies.
- Precision oncology adoption will increase demand for companion diagnostics and biomarker-driven treatments.
- Emerging markets will contribute faster growth due to expanding cancer infrastructure and improved diagnostic access.
- Digital health integration will support real-world evidence generation and optimize treatment outcomes.
- Strong pipeline investments and collaborative research programs will accelerate diversification of the DNA repair drug landscape.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of BRCA-Mutated and HRD-Positive Cancers
The increasing incidence of BRCA1/BRCA2 mutations and homologous recombination deficiency (HRD) in cancers such as ovarian, breast, prostate, and pancreatic is expanding the eligible patient pool for DNA repair drugs, driving market growth as more patients are identified for targeted therapies.
Expansion of Regulatory Approvals for PARP Inhibitors
Broader regulatory approvals for PARP inhibitors across multiple cancer types and treatment lines, including frontline and maintenance settings, are increasing clinical adoption and patient access, fueling market expansion.
Growing Adoption of Combination Therapies
The integration of DNA repair drugs, especially PARP inhibitors, with immunotherapies and other targeted agents is creating new treatment paradigms, overcoming resistance, and improving patient outcomes, which accelerates market uptake.
Increasing Focus on Next-Generation DNA Repair Targets
Industry innovation is shifting toward next-generation DDR targets such as ATR, ATM, and DNA-PK, offering new therapeutic options for resistant or genetically diverse tumors and expanding the market beyond traditional PARP inhibitors.
Rising Demand for Personalized and Biomarker-Driven Therapies
Advancements in genomic sequencing and tumor profiling are enabling more precise patient selection for DNA repair drugs, increasing the use of companion diagnostics and personalized treatment regimens, and thus driving market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the DNA Repair Drugs Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the DNA Repair Drugs Market projected to grow between 2025 and 2032?
Which DNA Repair Drugs Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the DNA Repair Drugs Market?
Who are the leading companies in the DNA Repair Drugs Market?
Which region commanded the largest share of the DNA Repair Drugs Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Drug Type
- 1.2.1 Olaparib
- 1.2.2 Rucaparib
- 1.2.3 Niraparib
- 1.2.4 Talazoparib
- 1.2.5 Others (e.g., PARG, ATR, ATM inhibitors)
- 1.3 By Application
- 1.3.1 Ovarian cancer
- 1.3.2 Breast cancer
- 1.3.3 Prostate cancer
- 1.3.4 Pancreatic cancer
- 1.3.5 Other solid tumors (e.g., fallopian tube, peritoneal cancers)
- 1.4 By Route of Administration
- 1.4.1 Oral
- 1.4.2 Parenteral
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7,847.5 million → 2032: USD 20,350.77 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global DNA Repair Drugs Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global DNA Repair Drugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global DNA Repair Drugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global DNA Repair Drugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global DNA Repair Drugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global DNA Repair Drugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global DNA Repair Drugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global DNA Repair Drugs Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7,847.5 million → 2032: USD 20,350.77 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global DNA Repair Drugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Drug Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Olaparib
- 12.3.7.2 Rucaparib
- 12.3.7.3 Niraparib
- 12.3.7.4 Talazoparib
- 12.3.7.5 Others (e.g., PARG, ATR, ATM inhibitors)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Ovarian cancer
- 12.4.7.2 Breast cancer
- 12.4.7.3 Prostate cancer
- 12.4.7.4 Pancreatic cancer
- 12.4.7.5 Other solid tumors (e.g., fallopian tube, peritoneal cancers)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Route of Administration - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Oral
- 12.5.7.2 Parenteral
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global DNA Repair Drugs End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global DNA Repair Drugs Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global DNA Repair Drugs Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global DNA Repair Drugs Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 AstraZeneca Plc
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 GlaxoSmithKline plc.
- 18.4 Merck KGaA
- 18.5 AbbVie
- 18.6 Johnson & Johnson
- 18.7 FoRx Therapeutics
- 18.8 Artios Pharma Limited
- 18.9 Clovis Oncology Inc.
- 18.10 Breakpoint Therapeutics
- 18.11 Luciole Pharmaceuticals
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

