
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Singapore Medical Tourism Market Size 2024 | USD 274.72 million |
| Singapore Medical Tourism Market, CAGR | 16.75% |
| Singapore Medical Tourism Market Size 2032 | USD 948.01 million |
Market Overview
Singapore Medical Tourism market size was valued at USD 274.72 million in 2024 and is anticipated to reach USD 948.01 million by 2032, at a CAGR of 16.75% during the forecast period (2024-2032).
Singapore's medical tourism market is driven by its world-class healthcare infrastructure, highly skilled medical professionals, and strong government support for medical excellence. The country attracts international patients due to its cutting-edge medical technologies, advanced treatments, and strict healthcare regulations ensuring quality and patient safety. Competitive pricing compared to Western countries and streamlined medical visa policies further enhance Singapore’s appeal. Additionally, a rise in medical travelers from neighboring Asian countries, particularly for specialized procedures such as oncology, cardiology, and cosmetic surgery, is boosting market growth. Key trends include the integration of artificial intelligence in diagnostics, increasing collaborations between hospitals and travel agencies, and the expansion of wellness tourism services. Moreover, Singapore’s focus on personalized treatment plans and telemedicine services enhances patient experience and accessibility. As demand for premium healthcare services rises, the country's medical tourism sector is poised for substantial expansion, reinforcing its status as a global medical hub.
Singapore’s medical tourism market is driven by its geographical advantage, world-class healthcare infrastructure, and advanced medical technologies. Central Singapore remains the core hub for medical tourism, housing internationally accredited hospitals such as Mount Elizabeth Hospital, Raffles Hospital, and Singapore General Hospital, offering specialized treatments in oncology, cardiology, orthopedics, and cosmetic procedures. East Singapore, with its proximity to Changi Airport, enhances accessibility for international patients, while Jurong and other regions are emerging as key healthcare destinations with expanding medical facilities. The market is shaped by leading players, including National University Hospital, National Cancer Centre, National Heart Centre Singapore, Gleneagles Hospital, and Parkway East Hospital, which provide cutting-edge treatments and personalized healthcare services. These institutions continuously invest in robotic surgeries, AI-driven diagnostics, and telemedicine, reinforcing Singapore’s reputation as a premier global medical tourism destination. Strategic partnerships and government initiatives further support the market’s growth, attracting a diverse patient base seeking high-quality medical care.
Market Insights
- The Singapore medical tourism market was valued at USD 274.72 million in 2024 and is projected to reach USD 948.01 million by 2032, growing at a CAGR of 16.75% during the forecast period.
- Singapore’s reputation for high-quality healthcare, internationally accredited hospitals, and advanced medical technologies attracts a steady influx of international patients.
- Rising demand for specialized treatments such as oncology, cardiology, orthopedic procedures, and cosmetic surgeries drives market growth.
- The integration of AI-driven diagnostics, robotic surgeries, and telemedicine solutions enhances patient outcomes and accessibility.
- Key players, including Mount Elizabeth Hospital, Raffles Hospital, and National University Hospital, continuously invest in medical advancements to maintain a competitive edge.
- High treatment costs and strict medical visa regulations pose challenges, leading some patients to choose more affordable regional alternatives.
- Central Singapore remains the dominant healthcare hub, while East Singapore, Jurong, and other regions are expanding their medical tourism infrastructure.
Report scope
This reports segments are Singapore Medical Tourism Market as follows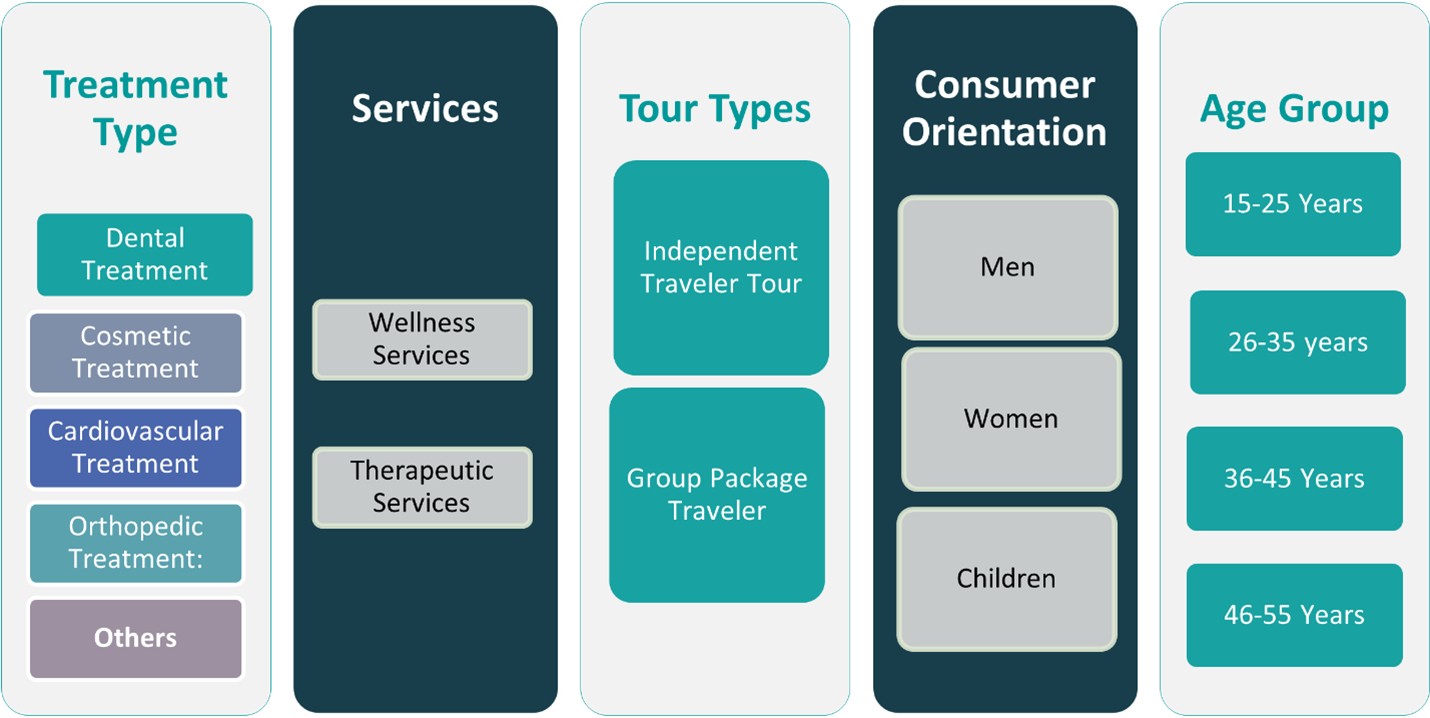
Market Drivers
World-Class Healthcare Infrastructure and Skilled Medical Professionals
Singapore's medical tourism industry thrives on its advanced healthcare infrastructure, internationally accredited hospitals, and highly skilled medical professionals. For instance, Mount Elizabeth Hospital and Singapore General Hospital are Joint Commission International (JCI)-accredited, ensuring high standards of patient care and safety. Renowned institutions such as Mount Elizabeth Hospital, Singapore General Hospital, and National University Hospital attract international patients seeking top-tier medical treatments. The presence of well-trained specialists, many of whom have international experience, enhances Singapore’s reputation as a global medical hub. Additionally, government investments in cutting-edge medical technologies and research further strengthen the country's healthcare sector, making it a preferred destination for complex procedures such as organ transplants, robotic surgeries, and oncology treatments.
Cost-Effective Treatments Compared to Western Countries
Singapore offers competitive pricing for medical procedures compared to Western countries, making it a cost-effective alternative for patients seeking high-quality healthcare. For instance, a knee replacement surgery in Singapore costs approximately $16,000, significantly lower than the $35,000 charged in the United States. International patients benefit from shorter hospital stays due to efficient medical services and advanced treatment methodologies, reducing overall expenses. Additionally, the presence of comprehensive medical insurance coverage for expatriates and international patients further supports Singapore’s growing medical tourism sector. The government’s efforts to maintain price transparency and standardized healthcare costs contribute to greater trust and confidence among international medical travelers.
Favorable Government Policies and Streamlined Medical Visas
The Singaporean government actively supports medical tourism through favorable policies, efficient visa procedures, and public-private partnerships. The government has implemented initiatives to streamline medical visa approvals, allowing patients to seek treatment in Singapore with minimal bureaucratic hurdles. Medical concierge services and collaborations between hospitals and travel agencies ensure seamless medical journeys, from pre-treatment consultations to post-treatment recovery. Additionally, Singapore’s strategic location in Asia, with excellent air connectivity and world-class airport facilities, makes it highly accessible to international patients. The government’s continued investments in medical innovation, digital health services, and telemedicine further enhance the country’s attractiveness as a premier medical tourism destination.
Rising Demand for Specialized Treatments and Wellness Tourism
The growing prevalence of chronic diseases and lifestyle-related conditions has increased demand for specialized treatments, including oncology, cardiology, fertility treatments, and cosmetic surgery in Singapore. Patients from neighboring countries, particularly Indonesia, Malaysia, China, and the Middle East, seek Singapore’s expertise in advanced medical procedures. Additionally, the integration of wellness tourism with medical treatments is gaining traction, with patients combining medical procedures with holistic wellness programs, rehabilitation services, and premium recovery facilities. Singapore’s emphasis on personalized healthcare, medical concierge services, and high-end hospitality ensures a superior patient experience. The rising adoption of AI-driven diagnostics, robotic surgeries, and telemedicine platforms further strengthens the country’s competitive edge in medical tourism.
Market Trends
Integration of Artificial Intelligence and Digital Health Solutions
Singapore’s medical tourism sector is embracing artificial intelligence (AI) and digital health technologies to enhance patient care, improve diagnostics, and streamline treatment processes. For instance, the A*STAR-EVYD Joint Laboratory for AI for Population Health and Digital Health has developed AI-powered systems for early disease detection and personalized treatment plans. Telemedicine and virtual consultations have also gained momentum, enabling international patients to connect with Singaporean specialists before traveling for treatment. Additionally, hospitals and medical centers are adopting electronic health records (EHRs) and blockchain technology to ensure seamless and secure access to patient data, enhancing the overall treatment experience. These advancements position Singapore as a technologically advanced medical tourism destination, catering to the growing demand for efficient and patient-centric healthcare solutions.
Growing Demand for Specialized and High-End Medical Treatments
There is an increasing influx of international patients seeking specialized treatments in Singapore, particularly for complex medical conditions such as oncology, cardiology, neurology, and fertility treatments. For instance, the National Cancer Centre Singapore is renowned for its advanced oncology treatments, attracting patients from neighboring countries. Additionally, Singapore’s fertility clinics are witnessing rising demand from medical tourists, driven by advancements in assisted reproductive technologies (ART), high success rates, and regulatory support. As lifestyle-related diseases continue to surge globally, more patients are opting for preventive healthcare check-ups and executive health screening programs offered by Singaporean hospitals. This trend underscores Singapore’s growing reputation as a center of excellence for advanced and specialized medical care.
Expansion of Wellness Tourism and Holistic Healthcare Services
The intersection of medical and wellness tourism is becoming a significant trend in Singapore’s healthcare industry. Medical tourists increasingly seek complementary wellness services, including post-surgery rehabilitation, integrative medicine, and luxury health retreats. High-end medical facilities now offer holistic healthcare packages that combine traditional medicine, physiotherapy, nutrition counseling, and stress management programs to promote long-term well-being. Singapore’s wellness tourism growth is further fueled by partnerships between hospitals, wellness resorts, and luxury hospitality providers, ensuring a seamless experience for international patients. The focus on preventive healthcare, mental wellness, and post-treatment recovery programs is attracting a broader demographic of medical travelers seeking a comprehensive approach to health and wellness.
Strategic Collaborations and Government Initiatives to Boost Medical Tourism
Singapore’s government actively promotes medical tourism through strategic collaborations with healthcare providers, travel agencies, and insurance companies. Leading hospitals are partnering with global medical tourism agencies to offer customized treatment packages, including visa assistance, travel arrangements, and post-care support. Additionally, the government continues to invest in healthcare innovation, infrastructure development, and regulatory frameworks to maintain Singapore’s competitive edge in the medical tourism sector. The rise of corporate wellness programs and international health insurance tie-ups further supports inbound medical travel. As these collaborations expand, Singapore is poised to attract a more diverse patient base, reinforcing its status as a global leader in medical tourism.
Market Challenges Analysis
High Medical Costs Compared to Regional Competitors
While Singapore offers world-class healthcare services, its relatively higher treatment costs compared to regional competitors such as Thailand, Malaysia, and India pose a challenge for attracting price-sensitive medical tourists. For instance, a heart bypass surgery in Singapore costs 41% more than in Thailand and 106% more than in Malaysia. Many patients from Southeast Asia and the Middle East, who seek affordable yet high-quality treatments, may opt for alternative destinations where medical expenses are significantly lower. Despite Singapore’s reputation for medical excellence, procedures such as cosmetic surgery, dental care, and elective treatments are often more cost-effective in neighboring countries. Additionally, fluctuations in currency exchange rates and rising operational costs for healthcare providers may further impact Singapore’s competitiveness in the global medical tourism market. To address this, hospitals and clinics are increasingly offering tailored medical packages, bundled services, and strategic partnerships to provide better value while maintaining premium healthcare standards.
Stringent Regulations and Limited Availability of Medical Visas
Singapore’s strict healthcare regulations, while ensuring high-quality standards, sometimes create barriers for international patients seeking urgent or specialized treatments. Lengthy visa approval processes, medical eligibility criteria, and stringent insurance policies can deter medical tourists who require faster access to healthcare services. Unlike other medical tourism hubs that offer streamlined medical visas or visa-on-arrival options, Singapore enforces stricter entry regulations, which may limit the influx of international patients. Additionally, the country’s focus on maintaining a high doctor-to-patient ratio and prioritizing local healthcare needs can restrict the availability of appointments for foreign patients, leading them to seek treatment in more accessible destinations. To overcome these challenges, Singapore’s healthcare sector is working towards improving visa facilitation services, enhancing cross-border collaborations, and expanding digital health solutions to attract and accommodate a larger international patient base.
Market Opportunities
Singapore’s medical tourism sector presents significant growth opportunities driven by advancements in cutting-edge medical technologies, specialized treatments, and digital healthcare solutions. The increasing global demand for high-quality medical care, particularly in areas such as oncology, cardiology, fertility treatments, and robotic surgeries, positions Singapore as a key player in the industry. The country’s reputation for medical excellence, supported by internationally accredited hospitals and top-tier specialists, continues to attract affluent patients seeking advanced procedures. Additionally, the integration of artificial intelligence, telemedicine, and precision medicine enhances diagnostic accuracy and treatment outcomes, further strengthening Singapore’s appeal. By expanding digital health platforms and remote consultation services, Singaporean healthcare providers can engage with international patients before and after treatment, ensuring seamless medical experiences and fostering long-term patient relationships.
The rise of wellness tourism and holistic healthcare services offers another avenue for growth. Medical travelers increasingly seek a combination of medical treatment and wellness programs, including rehabilitation services, preventive health check-ups, and personalized wellness retreats. Singapore’s ability to offer luxury medical experiences, premium recovery facilities, and integrative medicine programs presents a lucrative opportunity to cater to high-net-worth individuals seeking comprehensive healthcare solutions. Additionally, strategic collaborations between hospitals, wellness resorts, and hospitality providers can enhance patient convenience and satisfaction. With strong government support, continuous investment in medical research, and a focus on innovation, Singapore is well-positioned to expand its medical tourism market by diversifying service offerings, improving accessibility, and leveraging its reputation as a global medical hub.
Market Segmentation Analysis:
By Treatment:
The Singapore medical tourism market is segmented by treatment type, with key categories including dental treatment, cosmetic treatment, cardiovascular treatment, orthopedic treatment, and others. Dental and cosmetic treatments are among the most sought-after procedures, driven by Singapore’s reputation for high-quality, minimally invasive aesthetic procedures and advanced dental care. Patients from neighboring countries seek services such as dental implants, orthodontics, skin rejuvenation, and cosmetic surgeries, benefiting from the expertise of internationally trained specialists and state-of-the-art medical facilities. Cardiovascular treatments also attract a significant number of international patients, as Singapore is known for advanced heart surgeries, interventional cardiology, and post-cardiac rehabilitation programs. Additionally, the demand for orthopedic treatments, including joint replacements and spinal surgeries, is rising due to an aging global population and increasing sports-related injuries. The others category includes a wide range of specialized treatments such as oncology, fertility treatments, and neurological procedures, positioning Singapore as a preferred medical destination for complex and high-precision healthcare services.
By Services:
The market is further segmented based on services, primarily into wellness services and therapeutic services. Wellness services are gaining traction as medical tourists increasingly seek preventive healthcare, holistic healing, and rehabilitation programs. Singapore offers premium wellness packages that integrate traditional medicine, physiotherapy, nutrition counseling, and mental health support, catering to high-net-worth individuals looking for luxury healthcare experiences. Meanwhile, therapeutic services, including post-surgical recovery, rehabilitation, and chronic disease management, continue to drive market growth. The availability of specialized therapeutic programs for conditions such as cancer, cardiovascular diseases, and orthopedic recovery ensures that patients receive comprehensive, long-term medical care. The integration of digital health services, telemedicine, and AI-driven diagnostics further enhances patient accessibility and service efficiency, reinforcing Singapore’s position as a global leader in medical tourism. As demand for personalized healthcare solutions grows, Singapore’s ability to offer both high-end wellness services and cutting-edge therapeutic treatments will continue to drive the expansion of its medical tourism market.
Segments:
Based on Treatment:
- Dental Treatment
- Cosmetic Treatment
- Cardiovascular Treatment
- Orthopedic Treatment
- Others
Based on Services:
- Wellness Services
- Therapeutic Services
Based on Tour Type:
- Independent Traveler Tour
- Group Package Traveler
Based on Consumer Orientation:
- Men
- Women
- Children
Based on the Geography:
- Central Singapore
- Jurong
- East Singapore
- Other Regions
Regional Analysis
Central Singapore
Central Singapore is the leading region in the medical tourism market, accounting for nearly 45% of the total market share. This dominance is attributed to the presence of renowned hospitals such as Mount Elizabeth Hospital, Singapore General Hospital, and Raffles Hospital, which offer cutting-edge medical treatments across various specialties, including oncology, cardiology, orthopedics, and cosmetic surgery. The region is home to a high concentration of Joint Commission International (JCI)-accredited hospitals, ensuring superior healthcare standards that attract a steady influx of international patients. Additionally, Central Singapore benefits from strong medical infrastructure, government support, and a well-developed ecosystem of medical tourism facilitators, including travel agencies, wellness centers, and luxury accommodation options for international patients. The integration of AI-powered diagnostics, robotic surgeries, and telemedicine services further strengthens its position as a premier destination for medical tourism.
East Singapore
East Singapore holds approximately 25% of the medical tourism market, largely due to its strategic location near Changi Airport, which facilitates seamless travel for international patients. The presence of well-established healthcare facilities, including Changi General Hospital and Parkway East Hospital, has significantly contributed to its growing market share. East Singapore has become a preferred choice for medical tourists seeking specialized treatments in cardiology, general surgery, and wellness services, as it offers a balance between high-quality healthcare and accessibility. Additionally, several medical wellness resorts and rehabilitation centers have emerged in this region, catering to patients who seek holistic recovery options post-treatment. The region is also witnessing an increase in government initiatives to expand healthcare infrastructure, making it a rising hub for integrated medical and wellness tourism.
Jurong
Jurong accounts for 18% of Singapore’s medical tourism market, positioning itself as an emerging healthcare destination. The region has seen significant development in medical facilities, with the establishment of Ng Teng Fong General Hospital and Jurong Community Hospital, offering comprehensive healthcare services to both local and international patients. As part of Singapore’s long-term healthcare strategy, Jurong is focusing on expanding medical research, rehabilitation centers, and specialized clinics, making it an attractive alternative to Central Singapore. The region is also strengthening public-private partnerships to enhance medical service offerings and accommodate the rising demand for orthopedic and therapeutic treatments. With continuous infrastructure expansion and investments in telemedicine and digital health services, Jurong is poised to increase its market share in the coming years.
Other Regions
Other regions collectively contribute 12% of the medical tourism market, but they hold significant growth potential as Singapore continues to decentralize its healthcare services. Efforts to establish specialized medical hubs and wellness centers in less saturated areas are driving the gradual increase in medical tourist arrivals to these regions. The government is investing in developing healthcare clusters, expanding hospital networks, and integrating digital healthcare solutions to improve accessibility and affordability for international patients. Additionally, rehabilitation centers and wellness tourism services are gaining traction, offering medical tourists an alternative to traditional hospital-based treatments. With ongoing advancements in healthcare infrastructure and service innovation, these regions are expected to play a more substantial role in the future growth of Singapore’s medical tourism sector.
Key Player Analysis
- Mount Elizabeth Hospital
- National University Hospital
- Raffles Hospital
- National Cancer Centre
- National Heart Centre Singapore
- Gleneagles Hospital
- Changi General Hospital
- Parkway East Hospital
- Tan Tock Seng Hospital
- Khoo Teck Puat Hospital
Competitive Analysis
Singapore's medical tourism market is highly competitive, driven by leading players such as Mount Elizabeth Hospital, Raffles Hospital, National University Hospital, National Cancer Centre, National Heart Centre Singapore, Gleneagles Hospital, Parkway East Hospital, Changi General Hospital, Tan Tock Seng Hospital, and Khoo Teck Puat Hospital. These institutions compete on the basis of advanced medical technology, internationally accredited facilities, specialized treatments, and patient-centric services. Key hospitals focus on continuous innovation in robotic surgeries, AI-driven diagnostics, and precision medicine to enhance treatment outcomes and attract international patients. Additionally, strategic partnerships with global healthcare providers, insurance companies, and travel agencies strengthen their position in the market. Premium facilities, multilingual staff, and personalized healthcare packages further differentiate them from regional competitors. Despite their strengths, high treatment costs and competition from emerging medical tourism destinations pose challenges. However, Singapore’s strong regulatory framework, government support, and reputation for medical excellence continue to give these key players a competitive advantage in the global medical tourism industry.
Recent Developments
- In March 2025, Raffles Medical Group signed a strategic collaboration agreement with Shanghai Renji Hospital to establish a "dual circulation" service system. This partnership aims to promote cross-border healthcare services and position Shanghai as a hub for international medical tourism.
- In March 2025, MOHW Hengchun Tourism Hospital was highlighted as a key player in the global medical tourism market in a report projecting significant growth for the industry. The hospital continues to play a pivotal role in expanding medical tourism opportunities, particularly in Asia.
- In February 2025, Apollo Hospitals emphasized the need for a liberal visa policy to enhance India's medical tourism sector. The hospital is collaborating with the Indian government on the "Heal in India" initiative to attract international patients and streamline medical visa processes.
- In January 2025, Mount Elizabeth Hospitals unveiled new facilities under "Project Renaissance," which included expanded wards, upgraded critical care units, and additional single-bedded and negative pressure rooms. This expansion added 62 beds to its capacity and enhanced patient care infrastructure.
Market Concentration & Characteristics
The Singapore medical tourism market exhibits a high level of concentration, with a few leading hospitals dominating the industry through advanced healthcare services and internationally accredited facilities. Major players such as Mount Elizabeth Hospital, Raffles Hospital, and National University Hospital set industry benchmarks by offering specialized treatments in oncology, cardiology, orthopedics, and cosmetic surgery. The market is characterized by premium healthcare infrastructure, cutting-edge medical technology, and a strong focus on patient-centric care. Hospitals emphasize AI-driven diagnostics, robotic-assisted surgeries, and personalized treatment plans, enhancing both efficiency and patient experience. Additionally, government regulations ensure stringent quality control and ethical medical practices, further solidifying Singapore’s reputation as a trusted medical hub. While the market remains highly competitive, its high treatment costs limit accessibility for some medical tourists, leading to a selective patient base that prioritizes quality over affordability. The continued expansion of healthcare services and strategic collaborations reinforces Singapore’s position as a premier medical tourism destination.
Report Coverage
The research report offers an in-depth analysis based on Treatment, Services, Tour Type, Consumer Orientation and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Singapore’s medical tourism market is expected to grow steadily, driven by advancements in healthcare infrastructure and medical technology.
- Increasing demand for specialized treatments such as oncology, cardiology, and orthopedic procedures will continue to attract international patients.
- The integration of AI-driven diagnostics, robotic surgeries, and precision medicine will enhance treatment accuracy and efficiency.
- Government initiatives and public-private partnerships will further strengthen the country’s position as a global medical tourism hub.
- Rising healthcare costs may limit accessibility for some patients, prompting hospitals to offer personalized and cost-effective treatment packages.
- Expansion of telemedicine and digital health services will improve patient engagement and post-treatment care.
- Central Singapore will remain the dominant medical hub, while other regions will continue developing their healthcare infrastructure.
- Collaborations with international insurance providers and medical travel agencies will enhance service accessibility for global patients.
- Growing competition from emerging medical tourism destinations may drive Singapore’s hospitals to focus on innovation and premium healthcare services.
- Sustainability initiatives and wellness tourism will gain traction, adding new dimensions to Singapore’s medical tourism industry.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
World-Class Healthcare Infrastructure and Skilled Medical Professionals
Singapore’s internationally accredited hospitals and highly trained specialists attract international patients seeking advanced treatments, supported by government investments in cutting-edge medical technologies and research.
Cost-Effective Treatments Compared to Western Countries
Singapore offers competitive pricing for high-quality medical procedures, making it an attractive alternative for patients from developed countries, with efficient services that reduce overall treatment costs.
Favorable Government Policies and Streamlined Medical Visas
Government initiatives to simplify medical visa processes and support public-private partnerships make it easier for international patients to access Singapore’s healthcare services, enhancing the country’s appeal as a medical tourism destination.
Integration of Advanced Medical Technologies
The adoption of AI-driven diagnostics, robotic surgeries, and telemedicine solutions improves patient outcomes and accessibility, positioning Singapore as a technologically advanced and patient-centric medical tourism hub.
Rising Demand for Specialized Treatments and Wellness Tourism
Increasing prevalence of chronic diseases and lifestyle-related conditions drives demand for specialized procedures and holistic wellness programs, with Singapore offering premium, personalized healthcare and recovery experiences.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Singapore Medical Tourism?
What factors are driving the growth of the Singapore Medical Tourism?
What are some challenges faced by the Singapore Medical Tourism?
Who are the major players in the Singapore Medical Tourism?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Services
- 1.2.1 Wellness Services
- 1.2.2 Therapeutic Services
- 1.3 By Tour Type
- 1.3.1 Independent Traveler Tour
- 1.3.2 Group Package Traveler
- 1.4 By Treatment
- 1.4.1 Dental Treatment
- 1.4.2 Cosmetic Treatment
- 1.4.3 Cardiovascular Treatment
- 1.4.4 Orthopedic Treatment
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 274.72 million → 2032: USD 948.01 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Singapore Medical Tourism Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Singapore Medical Tourism Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Singapore Medical Tourism Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Singapore Medical Tourism Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Singapore Medical Tourism Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Singapore Medical Tourism Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Singapore Medical Tourism Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Singapore Medical Tourism Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 274.72 million → 2032: USD 948.01 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Singapore Medical Tourism Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Services - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Wellness Services
- 12.3.6.2 Therapeutic Services
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Tour Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Independent Traveler Tour
- 12.4.6.2 Group Package Traveler
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Treatment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Dental Treatment
- 12.5.6.2 Cosmetic Treatment
- 12.5.6.3 Cardiovascular Treatment
- 12.5.6.4 Orthopedic Treatment
- 12.5.6.5 Others
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Singapore Medical Tourism Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Singapore Medical Tourism Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2024-2032
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 Singapore Medical Tourism Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Mount Elizabeth Hospital
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Raffles Hospital
- 17.4 National University Hospital
- 17.5 National Cancer Centre
- 17.6 National Heart Centre Singapore
- 17.7 Gleneagles Hospital
- 17.8 Changi General Hospital
- 17.9 Parkway East Hospital
- 17.10 Tan Tock Seng Hospital
- 17.11 Khoo Teck Puat Hospital
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

