
Market Overview:
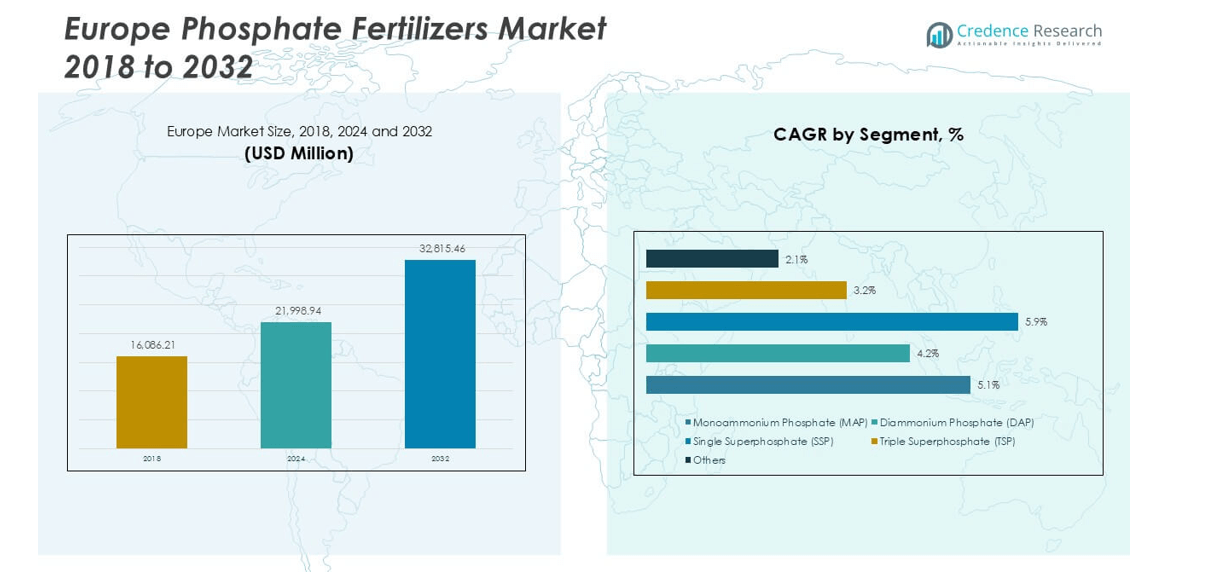
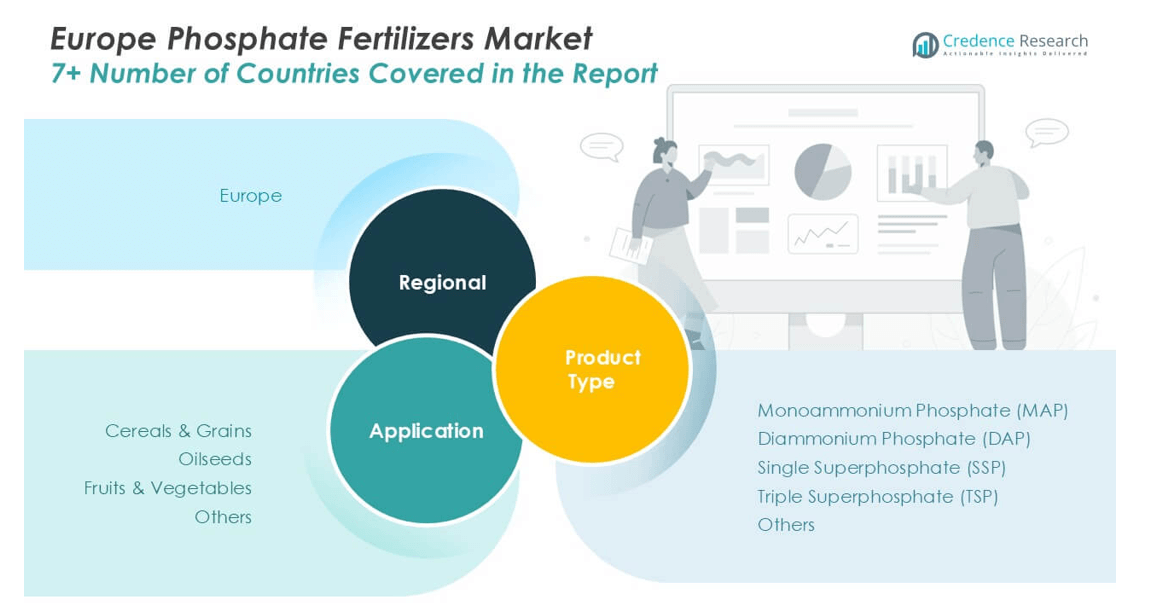
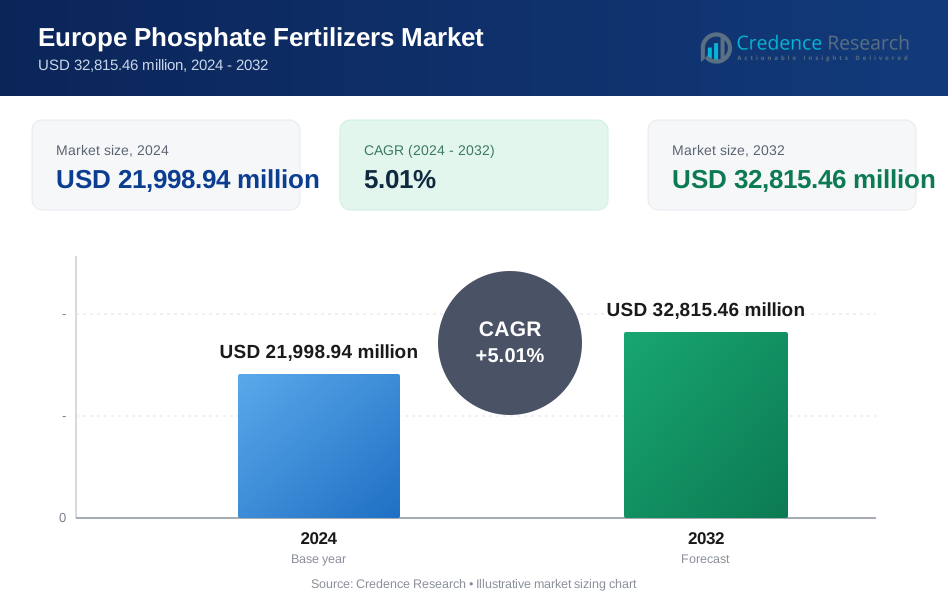
Europe Phosphate Fertilizers market size was valued at USD 16,086.21 million in 2018, reached USD 21,998.94 million in 2024, and is anticipated to reach USD 32,815.46 million by 2032, at a CAGR of 5.01% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe Phosphate Fertilizers Market Size 2024 | USD 21,998.94 million |
| Europe Phosphate Fertilizers Market, CAGR | 5.01% |
| Europe Phosphate Fertilizers Market Size 2032 | USD 32,815.46 million |
The Europe phosphate fertilizers market is led by Yara International, EuroChem Group, ICL Group Ltd, BASF SE, and Nutrien Ltd, which together hold a significant share through strong distribution networks and advanced product portfolios. These players focus on high-efficiency MAP and DAP fertilizers and invest in sustainable, water-soluble solutions to meet EU environmental goals. Western Europe dominates with over 40% market share in 2024, driven by extensive wheat and barley cultivation in France and Germany. Eastern Europe follows with around 25% share, supported by growing acreage and modernization of farming practices.
Market Insights
- Europe phosphate fertilizers market was valued at USD 21,998.94 million in 2024 and is projected to reach USD 32,815.46 million by 2032, growing at a CAGR of 5.01%.
- Demand is driven by rising cereal and oilseed production, precision farming adoption, and EU policies supporting balanced nutrient management and soil fertility improvement.
- Key trends include growing use of water-soluble fertilizers, micronutrient-enriched phosphate blends, and digital farming solutions for optimized nutrient application.
- The market is moderately consolidated, with leading players like Yara International, EuroChem, ICL Group, BASF SE, and Nutrien focusing on sustainable production and expansion in high-demand regions.
- Western Europe leads with over 40% share, followed by Eastern Europe with 25%; by product, MAP dominates with 35% share, followed by DAP and SSP used widely across cereals & grains (50% of demand).
Market Segmentation Analysis:
By Product Type
Monoammonium Phosphate (MAP) dominates the Europe phosphate fertilizers market, accounting for over 35% share in 2024. MAP is preferred due to its high phosphorus concentration and water solubility, making it ideal for precision farming and fertigation. Diammonium Phosphate (DAP) follows closely, driven by its dual nitrogen-phosphorus benefits that support rapid crop growth. Single Superphosphate (SSP) and Triple Superphosphate (TSP) remain important for cost-sensitive farming regions, while niche demand for specialty and blended fertilizers supports the “Others” category. MAP growth is fueled by rising adoption of high-yield cereal crop cultivation and sustainable farming practices.
- For instance, MAP (Monoammonium Phosphate) is a highly water-soluble fertilizer with a high phosphorus concentration. These properties make it a preferred choice for modern agricultural applications like precision farming and fertigation, allowing for the precise and efficient delivery of nutrients to crops.
By Application
Cereals & grains represent the largest application segment, contributing over 50% of total demand in 2024. The dominance is supported by Europe’s extensive wheat, barley, and maize production, which require consistent phosphate input to maintain soil fertility and maximize yield. Oilseeds, including rapeseed and sunflower, form the second-largest segment, driven by growing demand for edible oils and biofuel production. Fruits & vegetables show strong growth potential due to increasing consumer demand for nutrient-rich and organic produce. Controlled phosphate application enhances root development and crop quality, supporting greenhouse and open-field farming. This segment benefits from precision agriculture adoption and rising horticulture exports from Spain, Italy, and the Netherlands. The “Others” category includes pulses, forage, and turf applications, which see steady but smaller contributions to overall demand.
- For instance, the EU harvested about 270 million tonnes of cereals in 2023, with wheat & maize applications likely consuming more than 1.2 million tonnes of phosphate fertilizers.
Market Overview
Supportive EU Agricultural Policies
EU Common Agricultural Policy (CAP) reforms encourage sustainable fertilizer usage and better nutrient efficiency. Incentives for precision agriculture and controlled-release fertilizers push adoption of phosphate-based products. Programs promoting reduced nutrient losses and circular economy practices help farmers optimize phosphorus use. Subsidies and training initiatives further encourage small and medium farms to adopt modern fertilization techniques. This policy support is critical in maintaining long-term demand for phosphate fertilizers, while aligning with EU climate targets and water framework directives for responsible nutrient management.
- For instance, EU farmers applied an estimated 4.1 million tonnes of mineral phosphate (P) fertilizers between 2021 and 2023 across an average of approximately 157 million hectares of utilized agricultural area.
Growth in Biofuel and Oilseed Cultivation
The European biodiesel industry drives phosphate demand through increased oilseed production, particularly rapeseed and sunflower. Rising demand for biofuels to meet renewable energy targets creates strong consumption growth for phosphate fertilizers in oilseed farming. Fertilizers help improve seed quality and oil yield, making them vital for meeting EU blending mandates. Expansion of biofuel refining capacity across countries such as France, Germany, and the Netherlands further stimulates phosphate use. This trend strengthens long-term market growth prospects and enhances farmer investment in soil fertility management.
- For instance, ance produced approximately 3.83 million tonnes of rapeseed on a harvested area of 1.16 million hectares. This was a higher yield than the previous year due to improved weather conditions.
Rising Demand for High-Yield Crops
Europe’s phosphate fertilizer market benefits from growing demand for high-yield cereal, oilseed, and vegetable production. Farmers are adopting balanced phosphorus application to increase productivity and address soil nutrient depletion. Government-backed initiatives promoting food security and precision farming further strengthen demand. Expanding wheat and barley cultivation in France, Germany, and Poland continues to drive phosphate consumption. Sustainable farming practices, such as integrated nutrient management, are gaining traction, supporting the consistent use of phosphate fertilizers for improved soil health and crop output.
Key Trends & Opportunities
Shift Toward Specialty and Water-Soluble Fertilizers
European farmers increasingly adopt water-soluble phosphate fertilizers and fertigation-compatible solutions to support precision agriculture. These fertilizers allow targeted nutrient delivery, improving uptake efficiency and reducing runoff. This trend supports sustainable farming initiatives and helps meet EU nutrient reduction targets. Specialty products such as micronutrient-enriched phosphates present growth opportunities for manufacturers. The market is also seeing demand for customized blends tailored for specific crops and soil types, creating a lucrative niche for companies offering innovative, high-efficiency formulations.
- For instance, Lifosa operates a crystalline MAP plant with an annual production capacity of 30,000 tonnes of fully water-soluble fertilizer for fertigation systems.
Adoption of Digital Farming Solutions
Digital agriculture platforms and soil testing technologies are transforming phosphate fertilizer use across Europe. Farmers use data-driven insights to determine optimal application rates and timings, reducing waste and boosting crop performance. This precision approach aligns with environmental regulations and lowers input costs. Agritech collaborations and IoT-enabled nutrient monitoring solutions are creating new market opportunities. Suppliers integrating decision-support tools with fertilizer products gain a competitive edge, promoting efficient phosphorus usage and strengthening long-term relationships with farmers and cooperatives.
- For instance, the European Union has allocated hundreds of millions of euros for digital farming tools through various official programs, including Horizon Europe and the Common Agricultural Policy (CAP), with funding available from 2022–2024 and beyond.
Key Challenges
Stringent Environmental Regulations
The market faces pressure from strict EU regulations targeting phosphate runoff and eutrophication in water bodies. Policies limiting phosphorus application rates challenge fertilizer consumption growth, particularly in environmentally sensitive areas. Farmers must comply with nutrient management plans, adding compliance costs and limiting over-application. This regulatory environment pushes producers to innovate low-impact and slow-release phosphate solutions, but compliance complexity may slow adoption rates among small-scale farmers lacking access to advanced agronomic support systems.
Volatility in Raw Material Supply and Prices
Fluctuating prices of phosphate rock and rising energy costs impact production economics for European fertilizer manufacturers. Dependence on imports from Morocco and Russia exposes the market to geopolitical risks and supply chain disruptions. Price instability affects farmer purchasing decisions and can delay application schedules. This challenge pushes manufacturers to secure long-term supply contracts and explore recycling of phosphorus from wastewater as an alternative source. However, large-scale adoption of recycled phosphorus solutions is still limited and requires further investment.
Regional Analysis
Western Europe
Western Europe leads the Europe phosphate fertilizers market with over 40% market share in 2024. Countries such as France, Germany, and the UK drive demand due to extensive cereal and oilseed cultivation. Strong adoption of precision farming techniques, favorable CAP subsidies, and investment in sustainable agriculture support steady growth. France dominates the region, with high phosphate usage in wheat and barley farming. The presence of advanced distribution networks and major fertilizer producers enhances supply reliability. Western Europe is expected to maintain its lead as farmers adopt balanced nutrient management programs and water-soluble phosphate solutions.
Eastern Europe
Eastern Europe accounts for around 25% of the market share in 2024, led by Poland, Ukraine, and Romania. Expanding agricultural acreage and cost-effective phosphate availability support strong consumption. Farmers increasingly invest in modern fertilizers to boost productivity and export competitiveness. Growing oilseed and corn production also drives demand, supported by government-backed agricultural modernization programs. Despite price sensitivity, this region sees rising adoption of MAP and DAP fertilizers for high-yield crop cultivation. Eastern Europe shows significant growth potential as regional governments focus on soil fertility restoration and rural development initiatives, particularly post-harvest recovery in Ukraine.
Southern Europe
Southern Europe holds approximately 20% market share in 2024, driven by high phosphate demand for fruit, vegetable, and vineyard cultivation. Spain and Italy dominate this region due to intensive horticulture, greenhouse farming, and export-oriented production. Controlled phosphate application helps improve crop quality, taste, and shelf life. Adoption of drip irrigation systems and fertigation enhances fertilizer efficiency. Southern Europe benefits from strong government support for sustainable farming and climate-smart agriculture. Market growth is further supported by rising consumer preference for high-value crops and export-driven production of Mediterranean fruits, vegetables, and wine grapes.
Northern & Other Europe
Northern and other European countries collectively account for 15% of market share in 2024. The region includes Scandinavia, the Baltics, and smaller agricultural nations. Phosphate fertilizer demand is driven by cereal and forage production, especially in Denmark and Finland. Cold climate conditions limit growing seasons, but greenhouse farming and precision fertilizer application help optimize yields. Strict environmental regulations push adoption of slow-release and low-runoff phosphate solutions. While overall consumption is lower compared to other regions, strong focus on sustainable farming practices and government-backed nutrient management programs provide steady demand growth over the forecast period.
Market Segmentations:
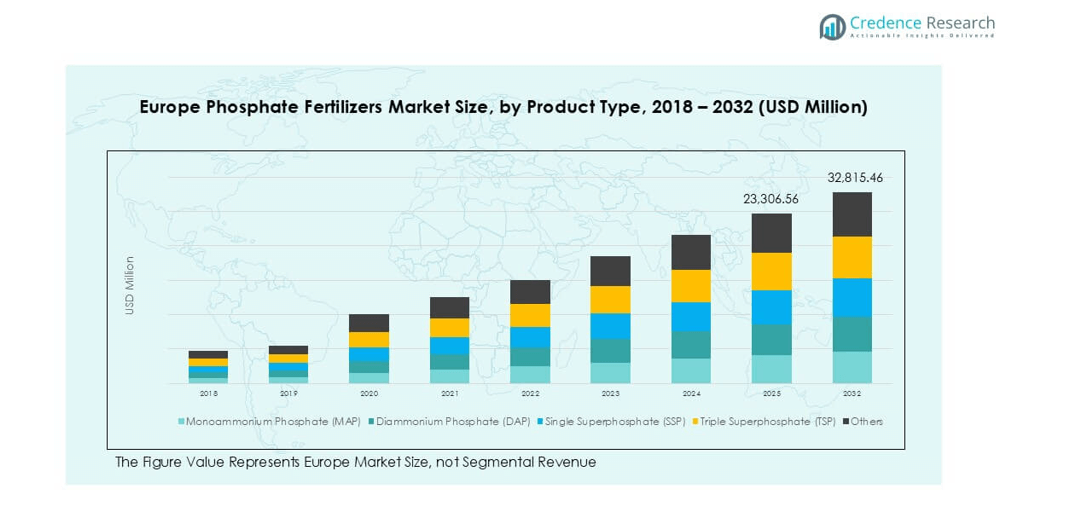
By Product Type:
- Monoammonium Phosphate (MAP)
- Diammonium Phosphate (DAP)
- Single Superphosphate (SSP)
- Triple Superphosphate (TSP)
- Others
By Application:
- Cereals & Grains
- Oilseeds
- Fruits & Vegetables
- Others
By Geography:
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
Competitive Landscape
The Europe phosphate fertilizers market is moderately consolidated, with leading players focusing on capacity expansion, product innovation, and sustainable solutions. Yara International, EuroChem Group, ICL Group Ltd, BASF SE, and Nutrien Ltd hold significant market presence, offering a wide portfolio of MAP, DAP, SSP, and customized phosphate blends. Companies invest in water-soluble and micronutrient-enriched fertilizers to meet the growing demand for precision farming and sustainable nutrient management. Strategic mergers, acquisitions, and partnerships strengthen supply networks across key agricultural regions. For instance, EuroChem has expanded production capacities in Lithuania and Belgium to enhance regional availability. Sustainability initiatives, such as BASF’s focus on reducing carbon footprint in fertilizer production, are gaining importance. Players also emphasize digital advisory services and soil testing solutions, providing integrated crop nutrition support to farmers. Competition is expected to intensify as regional and global manufacturers align with EU Green Deal targets and launch low-impact phosphate solutions.
Key Player Analysis
- Yara International
- EuroChem Group
- ICL Group Ltd
- BASF SE
- OCI Nitrogen (OCI NV)
- Nutrien Ltd.
- CF Industries Holdings
- K+S AG
- Helm AG
- COMPO Expert GmbH
Recent Developments
- In December 2023, Yara announced that it is acquiring the organic-based fertilizer business of Agribios, a company in Italy. The acquisition includes a production facility in Ronco all’Adige, focused on sustainable farming solutions through organic-based and organo-mineral fertilizers. This deal aligns with Yara’s strategy to expand its offerings in regenerative agriculture, complementing its current mineral fertilizer portfolio.
- In May 2022, Coromandel International, a fertilizer manufacturer, plans to buy a 45% stake in Baobab Mining and Chemicals Corporation (BMCC), a rock phosphate mining firm based in Senegal Africa, for $19.6 million (approximately $150 crore).
- In May 2022, Indian Potash Ltd signed a five-year agreement with Israel Chemical Ltd to import 0.6-0.65 million tonnes of potash muriate annually.
- In February 2022, EuroChem Group (hereafter referred to as "EuroChem" or "the Group"), a leading global producer of fertilizer, recently announced that it had completed the acquisition of the Serra do Salitre phosphate project in Brazil.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Market will see steady growth supported by rising demand for high-yield crop production.
- Precision farming adoption will boost use of water-soluble and controlled-release phosphate fertilizers.
- EU policies will push manufacturers to innovate low-runoff and environmentally safe formulations.
- Demand for MAP and DAP will remain dominant due to balanced nutrient content and efficiency.
- Digital soil monitoring and advisory tools will drive optimized fertilizer application rates.
- Oilseed production for biofuel will continue to expand, supporting phosphate consumption.
- Greenhouse and horticulture sectors will increase use of soluble phosphate products.
- Investment in local production will rise to reduce import dependence and price volatility.
- Companies will focus on sustainability, reducing carbon footprint in production processes.
- Competition will intensify with new product launches targeting EU Green Deal compliance.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Europe Phosphate Fertilizers market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Europe Phosphate Fertilizers market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Europe Phosphate Fertilizers market?
Who are the leading companies in the Europe Phosphate Fertilizers market?
Which region commanded the largest share of the Europe Phosphate Fertilizers market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Europe Phosphate Fertilizers Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Europe Phosphate Fertilizers Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 21,998.94 million → 2032: USD 32,815.46 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Europe Phosphate Fertilizers Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Europe Phosphate Fertilizers Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Europe Phosphate Fertilizers Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Europe Phosphate Fertilizers Market Drivers
- 3.3 Europe Phosphate Fertilizers Market Restraints & Challenges
- 3.4 Europe Phosphate Fertilizers Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Europe Phosphate Fertilizers Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Europe Phosphate Fertilizers Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Europe Phosphate Fertilizers category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Europe Phosphate Fertilizers Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Europe Phosphate Fertilizers Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Europe Phosphate Fertilizers market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Europe Phosphate Fertilizers Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Europe Phosphate Fertilizers Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Europe Phosphate Fertilizers Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Europe Phosphate Fertilizers (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Europe Phosphate Fertilizers Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Europe Phosphate Fertilizers Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Europe Phosphate Fertilizers Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Europe Phosphate Fertilizers Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Europe Phosphate Fertilizers Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Europe Phosphate Fertilizers Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Europe Phosphate Fertilizers Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Europe Phosphate Fertilizers Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Europe Phosphate Fertilizers Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
