
Market Overview:
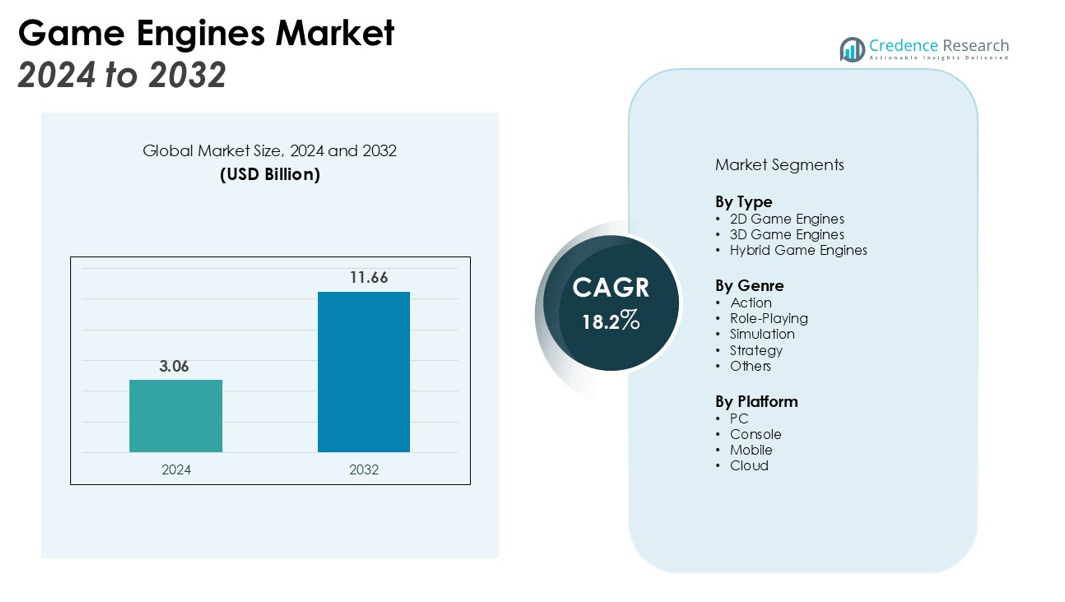
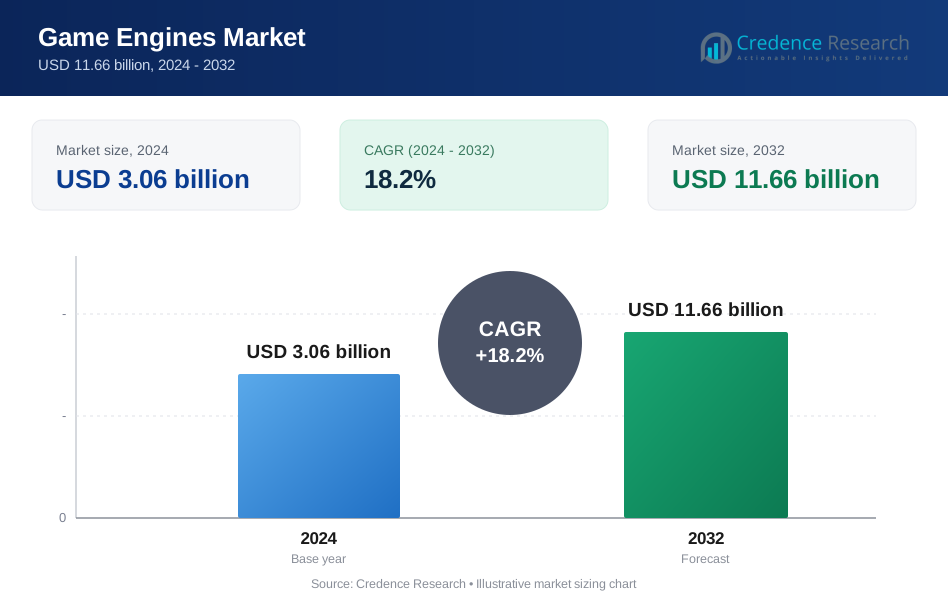
The Game Engines Market size was valued at USD 3.06 billion in 2024 and is anticipated to reach USD 11.66 billion by 2032, at a CAGR of 18.2% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Game Engines Market Size 2024 | USD 3.06 billion |
| Game Engines Market, CAGR | 18.2% |
| Game Engines Market Size 2032 | USD 11.66 billion |
Growth in this market is strongly driven by the surge in mobile gaming, rising investments in AR/VR, and expanding applications of game engines in film production, automotive design, and simulation training. Game engines provide developers with scalable solutions, reducing development costs and time while enabling interactive and cross-platform experiences. Increasing focus on cloud gaming and demand for realistic graphics further support widespread adoption.
Regionally, North America dominates the Game Engines Market with strong gaming infrastructure, leading publishers, and high consumer spending. Europe follows, supported by advancements in AR/VR and a thriving indie game ecosystem. Asia-Pacific is expected to record the fastest growth, driven by China, Japan, and South Korea’s expanding gaming industry, large mobile gamer base, and rising esports popularity. Emerging markets in Latin America and the Middle East are also experiencing steady adoption, supported by digitalization and improving internet connectivity. Growing collaboration between global developers and regional studios is further accelerating market penetration.
Market Insights:
- The Game Engines Market was valued at USD 3.06 billion and is projected to reach USD 11.66 billion by 2032, growing at a CAGR of 18.2%.
- Rising mobile gaming adoption and affordable internet access are driving strong global demand.
- Investments in AR and VR technologies are enhancing immersive experiences and broadening engine applications.
- Game engines are expanding into non-gaming industries, including film, automotive, healthcare, and architecture.
- Cloud gaming and demand for realistic graphics are pushing developers to adopt scalable, high-performance engines.
- North America leads with 38% market share, supported by strong infrastructure, publishers, and esports expansion.
- Asia-Pacific is the fastest-growing region, driven by mobile gamers, esports popularity, and government-backed digital initiatives.
Market Drivers:
Rising Demand for Mobile and Online Gaming
The Game Engines Market is driven by the rapid growth of mobile and online gaming. Increasing smartphone penetration and affordable internet access are enabling wider consumer reach. It supports cross-platform compatibility, ensuring consistent gameplay across devices. Strong consumer preference for engaging mobile content continues to strengthen market demand.
- For instance, Unity Technologies' engine supports development across more than 20 different platforms, enabling game creators to reach a massive and diverse mobile audience on various devices.
Expansion of AR and VR Applications
AR and VR technologies are creating new opportunities for immersive experiences. The Game Engines Market benefits from engines optimized for real-time rendering and interactive design. It helps developers integrate virtual environments into gaming, training, and simulation. Growing investments in VR hardware further reinforce engine adoption across industries.
- For instance, Epic Games showcased the capability of its Unreal Engine by rendering a complex open-world demonstration on a console at a consistent 60 frames per second with ray tracing enabled.
Adoption in Non-Gaming Industries
The market is expanding beyond entertainment, with adoption in film, automotive, and architecture. The Game Engines Market enables advanced visualization and prototyping, reducing design costs and enhancing efficiency. It supports simulation training in healthcare, defense, and engineering. Such cross-industry applications increase reliance on advanced engine capabilities.
Advancements in Cloud Gaming and Graphics Quality
Cloud gaming platforms are transforming how games are delivered and played. The Game Engines Market gains from engines that support scalable, high-quality streaming experiences. It addresses the demand for realistic graphics and seamless online performance. Continuous improvements in hardware and rendering techniques sustain this growth momentum.
Market Trends:
Integration of AI and Real-Time Technologies
Artificial intelligence and real-time rendering are shaping the future of the Game Engines Market. Developers are using AI for automated asset creation, behavior simulation, and advanced testing processes. It reduces development cycles while improving design accuracy and gameplay experiences. Real-time ray tracing is becoming a standard for achieving cinematic visuals, which strengthens demand for high-performance engines. Cloud-based collaboration tools are also improving workflow efficiency for global development teams. These advancements ensure game engines remain central to innovation across entertainment and enterprise applications.
- For instance, the scale of the developer ecosystem leveraging these tools is evident with a major platform like Unity, which has over 1.2 million monthly active users engaging with its editor.
Growing Adoption Beyond Gaming and Rising Esports Influence
The Game Engines Market is experiencing strong traction in industries beyond gaming, including film, automotive, and healthcare. It enables immersive training simulations, advanced visualization, and interactive product design, expanding its value proposition. Esports growth is pushing publishers to adopt scalable engines that handle high-performance gameplay and large user engagement. The market is also witnessing strong demand for engines supporting AR and VR, particularly in consumer applications. Regional studios are increasingly collaborating with global developers to create localized yet globally competitive titles. This convergence of gaming, esports, and non-gaming adoption is redefining the market’s scope and long-term growth trajectory.
- For instance, the digital distribution platform Steam reached a record of 40.27 million concurrent users on March 2, 2025, demonstrating the massive scale of user engagement that modern game engines are built to support.
Market Challenges Analysis:
High Development Costs and Technical Complexity
The Game Engines Market faces challenges due to rising development costs and technical barriers. Advanced engines demand significant investment in skilled talent, hardware, and software infrastructure. It creates difficulties for small and mid-sized studios competing with global publishers. Continuous updates and the need for compatibility across platforms increase resource burdens. Complex coding frameworks and steep learning curves further limit adoption by new developers. These factors restrict broader market penetration despite rising demand.
Intellectual Property Risks and Market Fragmentation
Intellectual property protection remains a critical concern for the Game Engines Market. It is vulnerable to piracy, unauthorized modifications, and misuse of assets, which impacts profitability. Market fragmentation with multiple competing engines also creates uncertainty for developers. Lack of standardization makes cross-platform optimization time-consuming and costly. Rising pressure to deliver realistic graphics while maintaining performance adds further strain. These challenges slow scalability and affect long-term innovation across the industry.
Market Opportunities:
Expanding Role in Non-Gaming Industries
The Game Engines Market is positioned to benefit from wider adoption in non-gaming sectors. It supports applications in automotive, healthcare, film, and architecture by enabling advanced simulations and visualization. Studios and enterprises are leveraging engines to cut design costs and accelerate product development. Demand for immersive training tools in defense and medical fields is rising steadily. The ability to create interactive environments makes engines critical for enterprise digital transformation. Growing investments in 3D modeling and visualization will further enhance market opportunities.
Growth Potential in Cloud Gaming and Esports
Cloud gaming and esports represent strong growth avenues for the Game Engines Market. It offers scalable solutions that enhance real-time gameplay across global audiences. Cloud platforms provide access to high-quality gaming without hardware limitations, strengthening consumer adoption. Esports expansion is driving demand for engines that deliver seamless performance under heavy loads. Developers are also adopting engines with AR and VR features to attract competitive gamers. These opportunities highlight the increasing importance of advanced engines in shaping digital entertainment and connected ecosystems.
Market Segmentation Analysis:
By Type
The Game Engines Market is segmented into 2D, 3D, and hybrid engines. 3D engines hold the dominant share, supported by demand for realistic graphics and immersive experiences. It enables developers to create lifelike environments across gaming, simulation, and virtual training. 2D engines continue to find relevance in mobile and casual games due to their lightweight design. Hybrid engines are gaining attention for flexibility across both simple and complex projects.
- For instance, Epic Games’ Unreal Engine provides developers with precise performance control for high-fidelity 3D graphics.
By Genre
Segmentation by genre covers action, role-playing, simulation, strategy, and others. Action and role-playing genres drive the largest demand, fueled by high consumer engagement and esports growth. It supports advanced storytelling and interactive gameplay features, strengthening reliance on powerful engines. Simulation and strategy genres also contribute significantly with expanding applications in education and enterprise. Rising demand for casual and indie titles supports growth across diverse genres.
By Platform
The market is divided into PC, console, mobile, and cloud platforms. Mobile leads growth, driven by large smartphone penetration and cost-effective access to gaming. It pushes developers to focus on engines optimized for cross-platform performance. PC and console segments remain critical, supported by high-quality AAA titles and strong esports presence. Cloud gaming adoption is accelerating, offering scalable opportunities and reducing hardware dependence for players and developers alike.
- For instance, according to a 2015 report, 174,183 unique games were made with Unity's engine over a four-month period. More recently, software built with the engine was running on over 1.5 billion devices as of 2020
Segmentations:
By Type
- 2D Game Engines
- 3D Game Engines
- Hybrid Game Engines
By Genre
- Action
- Role-Playing
- Simulation
- Strategy
- Others
By Platform
- PC
- Console
- Mobile
- Cloud
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America Leading with Strong Industry Infrastructure
North America accounted for 38% of the Game Engines Market share, making it the leading region. It benefits from advanced gaming infrastructure and established publishers driving steady adoption. High consumer spending on premium content and early use of AR, VR, and cloud-based platforms strengthen growth. Major studios continue to invest in cutting-edge technologies, boosting innovation across the region. Strong presence of global engine providers further enhances competitiveness. The region also records consistent expansion in esports, supporting long-term market penetration.
Europe Strengthened by AR/VR and Indie Ecosystem
Europe held 27% of the Game Engines Market share, supported by a robust AR/VR ecosystem and a strong indie developer base. It gains momentum from regional funding programs and strict quality standards set by regulators. Adoption is expanding into film production, automotive visualization, and architecture, creating new opportunities. Esports growth across Germany, the UK, and France fuels wider engagement. The market also benefits from rising consumer interest in immersive experiences. These factors ensure steady adoption of game engines across the region.
Asia-Pacific Emerging as the Fastest-Growing Market
Asia-Pacific represented 24% of the Game Engines Market share, with the fastest projected growth ahead. It is driven by China, Japan, and South Korea, supported by a large mobile gaming audience. Rising esports adoption and strong demand for immersive technologies are reinforcing market expansion. Regional studios are partnering with global publishers to create competitive titles. Government-backed digital initiatives strengthen infrastructure for gaming and related technologies. Strong growth momentum positions Asia-Pacific as a key driver of global market development.\
Key Player Analysis:
- Unity Technologies (U.S.)
- Stride (U.S.)
- Scirra Ltd. (Construct 3) (U.K.)
- RPG Maker (U.S.)
- Epic Games, Inc. (U.S.)
- AppOnboard, Inc. (U.S.)
- Cocos (China)
- Clickteam (France)
- Crytek GmbH (Germany)
- GameSalad (U.S.)
- Stencyl LLC (U.S.)
- YoYo Games Ltd. (GameMaker Studio 2) (U.K.)
- Marmalade Technologies Ltd. (U.K.)
- Electronic Arts Inc. (U.S.)
- Photon Storm Ltd. (U.K.)
Competitive Analysis:
The Game Engines Market is highly competitive, with global and regional players focusing on innovation and ecosystem expansion. Leading companies emphasize continuous upgrades in rendering, physics, and cross-platform integration to strengthen developer adoption. It is driven by the rising need for engines that support AR, VR, and cloud-based gaming. Strategic partnerships with studios, hardware providers, and content creators help key players expand their influence. Open-source engines are gaining traction by offering flexible licensing models and attracting independent developers. Established providers maintain a stronghold by leveraging brand recognition, extensive developer communities, and long-term support networks. Competition remains intense, with players investing in scalability and advanced features to differentiate their offerings.
Recent Developments:
- In August 2025, Stride, Inc. announced new partnerships with Chama Valley Independent Schools and Santa Rosa Consolidated Schools to operate its K12-powered online public school in New Mexico.
- In February 2025, Electronic Arts announced it had reached an agreement to acquire TRACAB Technologies, a company specializing in advanced sports optical tracking technology.
Report Coverage:
The research report offers an in-depth analysis based on Type, Genre, Platform and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Game Engines Market will expand with growing demand for immersive AR and VR applications.
- Developers will prioritize engines that enable cross-platform performance across mobile, PC, console, and cloud.
- It will witness increasing adoption in non-gaming sectors such as automotive, healthcare, and architecture.
- Cloud gaming growth will drive investments in engines optimized for scalable, high-quality streaming.
- AI-driven tools for asset creation and behavior simulation will streamline development processes.
- Esports expansion will push demand for engines supporting real-time, high-performance gameplay.
- Indie developers will gain opportunities through open-source and low-cost engine solutions.
- Regional studios will collaborate more with global publishers, creating localized yet competitive titles.
- Real-time ray tracing and advanced rendering technologies will become standard for high-end projects.
- Continuous innovation in simulation and training applications will reinforce the role of engines in enterprise digital transformation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Surge in Mobile and Online Gaming
The proliferation of smartphones and affordable internet access has dramatically expanded the global gaming audience, driving demand for game engines that support cross-platform and mobile-first development.
Expansion of AR/VR Applications
Investments in augmented and virtual reality are enabling more immersive gaming and simulation experiences, increasing the need for engines optimized for real-time rendering and interactive design across industries.
Adoption in Non-Gaming Industries
Game engines are increasingly used in film, automotive, healthcare, and architecture for advanced visualization, prototyping, and simulation training, broadening the market beyond traditional entertainment.
Growth of Cloud Gaming and Realistic Graphics
The shift toward cloud gaming platforms and consumer demand for high-fidelity, realistic graphics are pushing developers to adopt scalable, high-performance engines capable of delivering seamless, visually rich experiences.
Esports and Indie Development Ecosystem
The rapid expansion of esports and a thriving indie developer community are fueling demand for flexible, scalable engines that can support both large-scale competitive titles and innovative independent projects.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Game Engines, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Game Engines Market projected to grow between 2024 and 2032?
Which Game Engines Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Game Engines Market?
Which region commanded the largest share of the Game Engines Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 2D Game Engines
- 1.2.2 3D Game Engines
- 1.2.3 Hybrid Game Engines
- 1.3 By Genre
- 1.3.1 Action
- 1.3.2 Role-Playing
- 1.3.3 Simulation
- 1.3.4 Strategy
- 1.3.5 Others
- 1.4 By Platform
- 1.4.1 PC
- 1.4.2 Console
- 1.4.3 Mobile
- 1.4.4 Cloud
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3.06 billion → 2032: USD 11.66 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Game Engines Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Game Engines Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Game Engines Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Game Engines Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Game Engines Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Game Engines Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Game Engines Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Game Engines Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3.06 billion → 2032: USD 11.66 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Game Engines Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 2D Game Engines
- 12.3.7.2 3D Game Engines
- 12.3.7.3 Hybrid Game Engines
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Genre - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Action
- 12.4.7.2 Role-Playing
- 12.4.7.3 Simulation
- 12.4.7.4 Strategy
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Platform - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 PC
- 12.5.7.2 Console
- 12.5.7.3 Mobile
- 12.5.7.4 Cloud
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Game Engines Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Game Engines Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Game Engines Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Unity Technologies
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Epic Games, Inc.
- 17.4 Crytek GmbH
- 17.5 YoYo Games Ltd.
- 17.6 Cocos
- 17.7 Scirra Ltd.
- 17.8 Stride
- 17.9 Electronic Arts Inc.
- 17.10 Clickteam
- 17.11 GameSalad
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

