
Market Overview:
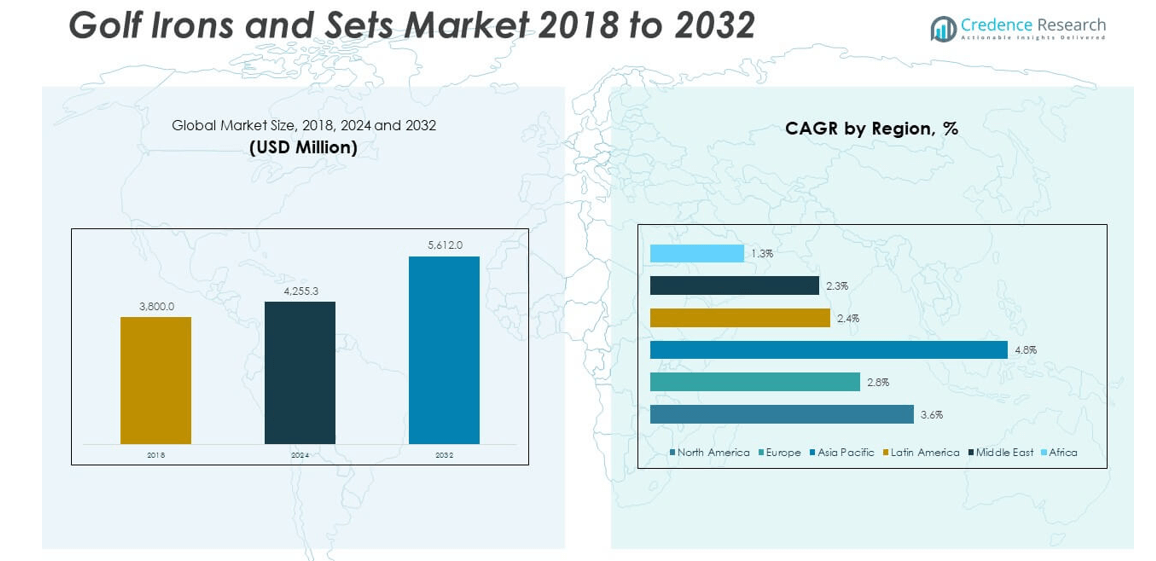
The Golf Irons and Sets Market size was valued at USD 3,800.0 million in 2018 to USD 4,255.3 million in 2024 and is anticipated to reach USD 5,612.0 million by 2032, at a CAGR of 3.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Golf Irons and Sets Market Size 2024 | USD 4,255.3 million |
| Golf Irons and Sets Market, CAGR | 3.6% |
| Golf Irons and Sets Market Size 2032 | USD 5,612.0 million |
The market is witnessing steady growth driven by rising participation in golf as both a professional sport and a recreational activity. Increased consumer spending on premium equipment, technological innovations in club design for improved forgiveness and distance, and the influence of professional tournaments are fueling demand. Additionally, growing interest among younger demographics, coupled with lifestyle-driven adoption of golf as a leisure activity, further supports market expansion.
Regionally, North America dominates the market due to a well-established golf culture, strong infrastructure, and a high concentration of professional players and courses. Europe follows closely, supported by a growing base of golf tourism and active participation in countries such as the UK, Germany, and Spain. Meanwhile, Asia-Pacific is emerging as a high-potential region, with countries like China, Japan, and South Korea investing heavily in golf infrastructure and experiencing rising interest among the middle-class population.
Market Insights:
- The Golf Irons and Sets Market was valued at USD 3,800.0 million in 2018, reached USD 4,255.3 million in 2024, and is projected to attain USD 5,612.0 million by 2032, registering a CAGR of 3.6%.
- Rising golf participation across recreational and professional levels supports steady equipment demand and broadens consumer adoption.
- Technological advancements in irons and sets enhance playability, forgiveness, and distance, driving preference for premium designs.
- High equipment costs and limited accessibility in price-sensitive regions act as restraints, slowing wider market penetration.
- North America dominates due to strong golf culture and infrastructure, while Asia Pacific emerges as the fastest-growing region with rising middle-class interest.
- Europe sustains growth through golf tourism and major tournaments, despite moderate economic pressures.
- Latin America, the Middle East, and Africa display niche but expanding potential, supported by tourism, infrastructure investments, and gradual lifestyle adoption.
Market Drivers
Rising Participation in Recreational and Professional Golf Creates Consistent Demand
The Golf Irons and Sets Market benefits from the steady expansion of golf participation among both recreational players and professional athletes. It gains momentum from the rising interest in organized tournaments and international events that increase global visibility. New players enter the sport due to its association with lifestyle, networking, and health benefits. Premium golf clubs and resorts promote the activity, attracting more consumers to invest in quality equipment. The availability of flexible membership packages broadens accessibility across different income groups. Governments in certain regions invest in golf tourism, further encouraging course development. Sports associations introduce training initiatives, creating a skilled base of future golfers. The market aligns with changing consumer priorities by offering equipment tailored for beginners and advanced players alike.
- For example, Callaway Golf extended its partnership with the Future Champions Golf (FCG) Tour in 2023, supporting nearly 900 junior golfers from more than 50 countries who competed across 12 championship courses, highlighting its role in fostering youth participation in the sport.
Influence of Celebrity Endorsements and Professional Golf Tournaments on Consumer Preferences
The Golf Irons and Sets Market experiences significant influence from endorsements by professional players who shape purchasing decisions. It benefits when top athletes publicly highlight the role of advanced irons in improving performance. Sponsorship agreements with leading tournaments showcase brands to global audiences. Equipment launches coincide with professional events, ensuring higher visibility. Rising fan engagement with televised tournaments strengthens interest in replicating professional-grade performance. Younger players increasingly follow professionals, creating aspirational demand for premium sets. Marketing campaigns emphasize alignment with high-profile golf events, reinforcing brand trust. Manufacturers integrate feedback from professionals to enhance credibility and technical refinement.
Continuous Advancements in Material Technology and Equipment Design Strengthen Performance Appeal
The Golf Irons and Sets Market advances through innovations in materials and structural design. It integrates lighter alloys, graphite composites, and variable face thicknesses to improve forgiveness and ball speed. Brands invest in research facilities to develop precision-engineered equipment that supports both distance and accuracy. Smart club designs reduce vibration and enhance feel, catering to varied skill levels. Adjustable weighting options expand customization for diverse swing styles. Enhanced durability and sustainability in materials build consumer trust and reduce replacement cycles. Hybrid iron sets combine distance and control, appealing to multi-level golfers. These advancements ensure performance benefits that justify premium pricing.
- For example, Ping’s G430 irons, launched in 2023, feature a thinner face made from Hyper 17-4 stainless steel with a proprietary heat-treatment process, designed to increase face flex and generate faster ball speeds.
Expanding Consumer Lifestyle Shifts and Income Growth Encourage Premium Equipment Adoption
The Golf Irons and Sets Market expands as higher disposable incomes and lifestyle changes drive consumers toward premium recreational equipment. It benefits from urban elites and corporate professionals adopting golf as a networking and leisure activity. Rising interest in wellness lifestyles encourages participation, strengthening the link between health and sports investment. Growing middle-class populations in emerging economies create new demand pools. Retailers offer personalized fitting services, making premium sets more attractive to buyers. Technological awareness motivates consumers to select advanced equipment rather than entry-level alternatives. Course expansions in suburban areas provide easier access to facilities. The market adapts to rising demand by diversifying product ranges across price tiers.
Market Trends
Integration of Smart Technologies and Digital Enhancements to Improve Playing Experience
The Golf Irons and Sets Market integrates smart technologies that enhance user experience and performance tracking. It now incorporates embedded sensors and swing analysis tools within irons, allowing real-time feedback. Players use companion mobile applications to monitor progress and receive training insights. Digital integration creates strong appeal among younger and tech-savvy players. Equipment customization is refined with advanced simulations that test different club combinations. Cloud-based data storage supports long-term performance monitoring. Smart features allow retailers to position products as premium, technology-driven solutions. Continuous digital integration reshapes consumer expectations for golf equipment.
Rising Popularity of Custom-Fit Golf Clubs Among Amateur and Semi-Professional Players
The Golf Irons and Sets Market experiences a surge in demand for custom-fit equipment that aligns with individual playing styles. It benefits from advances in fitting technologies that capture swing data with precision. Consumers prefer tailored solutions that provide better control and accuracy. Retail outlets and golf academies now emphasize personalized fitting sessions. Digital simulations aid consumers in visualizing performance improvements with specific designs. Semi-professional players invest in tailored sets to bridge the gap toward professional-level performance. Marketing strategies highlight the tangible performance advantages of customization. This trend reinforces the perception of golf as a technical and skill-based sport.
- For instance, Titleist’s global club fitting network uses SureFit® hosel technology and TrackMan™ ball flight monitoring to deliver precision fittings that optimize irons based on individual swing characteristics.
Expansion of E-Commerce and Online Retail Channels as Growth Accelerators
The Golf Irons and Sets Market strengthens through the expansion of digital sales platforms. It benefits from online marketplaces offering wider product ranges and competitive pricing. Direct-to-consumer strategies increase brand control and customer interaction. E-commerce platforms provide virtual fitting tools and remote consultation services, attracting global buyers. Younger consumers prefer the convenience of purchasing through mobile platforms. Discount strategies and loyalty programs offered online improve customer retention. Global players rely on digital presence to penetrate emerging markets. This trend reduces reliance on traditional specialty stores and creates broader accessibility.
- For instance, PXG emphasized its direct-to-consumer e-commerce model in 2023, offering personalized custom club fittings and online ordering to enhance access and buyer experience.
Sustainability Focus and Eco-Friendly Product Lines Create Distinctive Consumer Appeal
The Golf Irons and Sets Market responds to consumer awareness of environmental responsibility by promoting sustainable product lines. It incorporates recycled materials and eco-friendly production techniques. Brands emphasize durability to minimize replacement cycles and waste. Consumers increasingly prefer equipment with transparent sustainability certifications. Marketing campaigns highlight the reduced carbon footprint of advanced manufacturing. Manufacturers align with global sustainability initiatives to strengthen brand image. Younger consumers value eco-conscious choices when investing in premium products. This trend positions sustainability as both a differentiator and a long-term growth enabler.
Market Challenges Analysis
High Costs of Premium Equipment and Limited Accessibility Reduce Market Penetration
The Golf Irons and Sets Market faces challenges due to the high costs of premium irons, limiting accessibility for many consumers. It remains associated with a luxury segment, creating barriers for middle-income players. Limited awareness of affordable options restricts broader adoption. Golf course fees combined with equipment investments make the sport cost-intensive. Price-sensitive consumers often seek used or lower-tier alternatives, affecting new product sales. The demand gap widens between established markets and emerging regions. Manufacturers must balance innovation costs with affordability. Without strong value-based offerings, penetration in developing regions remains constrained.
Declining Participation in Certain Regions and Limited Infrastructure Growth Constrain Expansion
The Golf Irons and Sets Market encounters difficulties in regions where participation declines due to limited infrastructure growth. It struggles in markets with insufficient golf courses and training facilities. Population shifts toward urban centers reduce availability of large land areas for new developments. Younger demographics in some regions show lower interest in traditional sports. Seasonal dependency affects year-round engagement, particularly in colder climates. Infrastructure limitations in emerging economies restrict full market development. Governments often prioritize other sports investments over golf, slowing infrastructure progress. These conditions reduce growth potential despite global innovations and demand in established regions.
Market Opportunities
Expanding Middle-Class Demographics and Rising Golf Tourism Drive Future Potential
The Golf Irons and Sets Market holds strong potential through rising middle-class participation and the expansion of golf tourism. It benefits from urbanization in emerging markets where lifestyle-driven activities gain traction. Golf resorts and travel destinations integrate premium experiences that encourage equipment purchases. Rising tourism inflows create opportunities for rental and retail outlets. Government-backed promotional campaigns highlight golf tourism as a revenue source. Growing demand for leisure activities supports greater product acceptance. It aligns with consumer willingness to spend on experiential travel and recreational sports.
Adoption of Digital Retail and Technological Innovation Strengthens Market Prospects
The Golf Irons and Sets Market gains opportunities from digital retail expansion and continued technological progress. It benefits when brands integrate augmented reality and online fitting tools to improve consumer trust. E-commerce platforms extend reach to regions with limited physical retail infrastructure. New material innovations reduce weight and improve durability, enhancing product appeal. Manufacturers invest in training partnerships with academies to showcase advanced designs. Digital engagement through social platforms attracts younger audiences. It positions the market to capture future generations of players and long-term growth opportunities.
Market Segmentation Analysis:
By product type, the Golf Irons and Sets Market is defined by a diverse product range that meets the needs of different playing styles and skill levels. Irons dominate usage due to their versatility across courses, while woods remain critical for distance-driven shots. Hybrids gain preference among amateurs for their forgiving design, bridging the gap between irons and woods. Wedges hold importance for short-game precision, and putters are indispensable for finishing strokes. Complete sets appeal strongly to beginners and recreational players seeking comprehensive and affordable solutions. Each product type plays a unique role in driving purchase decisions and sustaining steady demand across varied consumer bases.
- For instance, TaylorMade launched its Stealth irons and hybrids in 2022, incorporating Cap Back™ design and toe-wrap construction to enhance face flexibility, lower the center of gravity, and deliver improved performance.
By application, professional golfers represent a high-value segment driven by performance requirements and endorsements, creating strong visibility for advanced designs. Amateur and recreational players contribute significantly to volume sales, supported by lifestyle adoption and casual participation. The beginner segment fuels long-term growth by introducing new players through cost-effective sets and tailored entry-level products. The Golf Irons and Sets Market balances these application segments by offering a wide spectrum of designs that address performance, affordability, and ease of play.
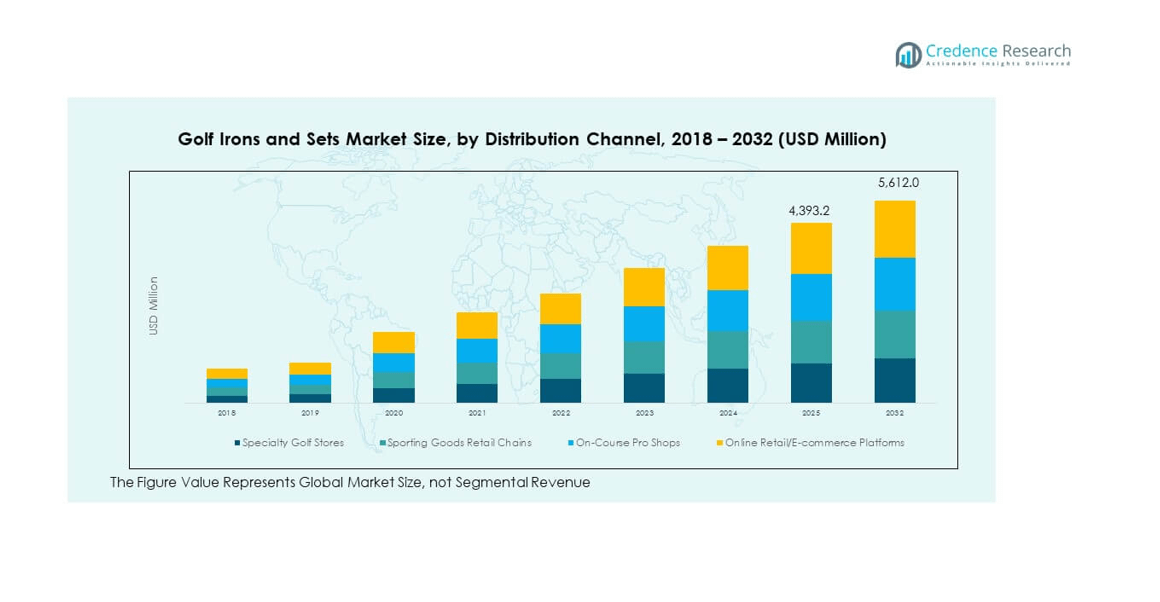
By distribution channels shape accessibility, with specialty golf stores delivering expert guidance and fitting services that enhance customer confidence. Sporting goods retail chains extend reach by offering a broader product mix to diverse consumers. On-course pro shops provide convenient purchase points directly linked to golf facilities, strengthening impulse and need-based sales. Online retail and e-commerce platforms grow rapidly, driven by convenience, virtual fitting technologies, and global accessibility. It reflects a market adapting to modern buying behavior and evolving consumer expectations.
- For instance, PGA Tour Superstore owned by AMB Group continued expanding its U.S. presence, reaching 78 locations by 2025, while offering in-store club fitting services such as its free “Fit & Go” walk-in fittings and full studio fittings for members.
Segmentation:
By Product Type
- Irons
- Woods
- Hybrids
- Wedges
- Putters
- Complete Sets
By Application
- Professional Golfers
- Amateur / Recreational Players
- Beginner Segment
By Distribution Channel
- Specialty Golf Stores
- Sporting Goods Retail Chains
- On-Course Pro Shops
- Online Retail / E-commerce Platforms
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America
The North America Golf Irons and Sets Market size was valued at USD 1,501.0 million in 2018 to USD 1,662.1 million in 2024 and is anticipated to reach USD 2,188.9 million by 2032, at a CAGR of 3.6% during the forecast period. North America accounts for 39% of the global share in 2024, reflecting its established golf culture and wide player base. The Golf Irons and Sets Market here benefits from high participation levels, with the U.S. leading in terms of course availability and professional tournaments. It is supported by endorsements from globally recognized golfers, which stimulate consumer interest in premium equipment. Canada contributes with a growing recreational base and investments in golf tourism, while Mexico is gradually emerging as a market with expanding golf infrastructure. The strong presence of leading brands ensures innovation and consumer choice. Rising adoption of smart technologies in clubs further enhances the market. Retail networks and online platforms provide wide accessibility across the region.
Europe
The Europe Golf Irons and Sets Market size was valued at USD 1,000.2 million in 2018 to USD 1,076.5 million in 2024 and is anticipated to reach USD 1,341.0 million by 2032, at a CAGR of 2.8% during the forecast period. Europe holds 25% of the global market share in 2024, supported by a mix of professional and recreational demand. The Golf Irons and Sets Market in this region thrives on a strong golf tourism industry in the UK, Spain, and France. It is reinforced by major tournaments such as the Ryder Cup, which elevate equipment demand. Germany and Italy are witnessing steady adoption due to growing participation among younger demographics. The availability of heritage golf courses contributes to continued interest in the sport. Sustainability-focused equipment and eco-friendly production practices resonate strongly with European consumers. Digital retail adoption improves accessibility, while premium club fittings remain popular. The market sustains growth despite economic pressures through strong brand loyalty.
Asia Pacific
The Asia Pacific Golf Irons and Sets Market size was valued at USD 889.2 million in 2018 to USD 1,041.9 million in 2024 and is anticipated to reach USD 1,517.7 million by 2032, at a CAGR of 4.8% during the forecast period. Asia Pacific commands a 24% market share in 2024, making it a rapidly expanding growth hub. The Golf Irons and Sets Market is fueled by rising disposable incomes and urbanization in China, India, and Southeast Asia. Japan and South Korea remain established markets with strong professional bases. It benefits from government-backed initiatives to expand golf tourism in countries like Thailand and Vietnam. Demand is expanding among younger demographics driven by lifestyle aspirations. Premium brands are investing in dedicated retail outlets and training academies across the region. E-commerce plays a critical role in broadening accessibility, particularly in countries with fewer physical stores. Innovation and competitive pricing ensure strong consumer adoption across diverse segments.
Latin America
The Latin America Golf Irons and Sets Market size was valued at USD 202.2 million in 2018 to USD 223.8 million in 2024 and is anticipated to reach USD 269.8 million by 2032, at a CAGR of 2.4% during the forecast period. Latin America represents 5% of the global share in 2024, with Brazil and Argentina leading demand. The Golf Irons and Sets Market is shaped by rising golf tourism, particularly in resort destinations. It gains traction from increasing visibility of international tournaments hosted in the region. Brazil demonstrates steady demand driven by a mix of professional and amateur players. Argentina reflects growth supported by club expansions and active training programs. Mexico, though categorized under North America, complements regional growth by promoting golf-linked travel. Limited infrastructure in smaller countries constrains expansion, but targeted investments are building momentum. Online retail channels expand access and increase product awareness.
Middle East
The Middle East Golf Irons and Sets Market size was valued at USD 147.8 million in 2018 to USD 155.3 million in 2024 and is anticipated to reach USD 185.2 million by 2032, at a CAGR of 2.3% during the forecast period. Middle East holds 4% of the global share in 2024, anchored by GCC countries, particularly the UAE. The Golf Irons and Sets Market is driven by government investments in sports tourism and luxury resorts. Dubai and Abu Dhabi stand out as leading destinations with world-class facilities and frequent tournaments. Saudi Arabia is emerging with ambitious sports diversification programs. Demand grows among expatriates and high-net-worth individuals seeking premium recreational experiences. The region emphasizes luxury and exclusivity, supporting demand for high-end equipment. Retail expansion aligns with tourism inflows, making resorts key retail hubs. E-commerce remains limited but shows growth potential through regional integration.
Africa
The Africa Golf Irons and Sets Market size was valued at USD 59.7 million in 2018 to USD 95.8 million in 2024 and is anticipated to reach USD 109.5 million by 2032, at a CAGR of 1.3% during the forecast period. Africa contributes 2% of the global market share in 2024, reflecting limited but steady participation. The Golf Irons and Sets Market benefits from South Africa’s established golfing culture, supported by international tournaments. Egypt emerges with growing investment in golf resorts catering to tourists. Nigeria and Kenya show early signs of adoption but face infrastructure limitations. Market growth is closely linked to tourism-driven demand in coastal and luxury destinations. High costs limit wider consumer adoption across most African economies. Brands target elite and expatriate communities, where demand for premium products is concentrated. The gradual rise of e-commerce creates pathways for broader regional access.
Key Player Analysis:
- Callaway Golf Company
- TaylorMade Golf Company
- Titleist (Acushnet Holdings Corp.)
- Ping (Karsten Manufacturing Corp.)
- Cobra Golf
- Mizuno Corporation
- Bridgestone Golf
- Srixon / Cleveland Golf (Sumitomo Rubber Industries)
- Wilson Sporting Goods
- PXG (Parsons Xtreme Golf)
- Honma Golf
- Adams Golf
- Nike Golf
Competitive Analysis:
The Golf Irons and Sets Market is highly competitive, led by global brands such as Callaway, TaylorMade, Titleist, Ping, and Mizuno, which command strong loyalty and visibility. It is defined by continuous innovation in material technology, product design, and custom fitting solutions that differentiate offerings. Strategic endorsements by professional golfers strengthen brand influence and consumer trust. Companies focus on launching advanced irons and complete sets tailored to performance-driven players while expanding accessibility through e-commerce and retail partnerships. Regional players and niche brands target affordability and customization to capture emerging segments. Mergers, acquisitions, and strategic alliances enhance portfolios and expand geographic presence. Competitive intensity remains high, with innovation speed and distribution strength acting as key differentiators.
Recent Developments:
- In July 2025, Callaway officially launched its new X Forged and X Forged Max irons to the U.S. retail market after gaining traction with PGA TOUR players and in Asian markets. The models became available for pre-sale beginning July 7, 2025, with a retail launch date of July 25, 2025, offering advanced design validated by professional players like Min Woo Lee, who provided direct feedback on performance and design features.
- In March 2025, KemperSports and Touchstone Golf announced a strategic partnership aimed at strengthening their market presence and services in golf course management. The partnership combines the expertise of two major industry players, expanding their reach to more than 180 managed golf courses and over 40 properties primarily in the Western U.S
- In January 2025, PowerBilt Holdings entered into a global licensing agreement with HEAD Sport GmbH to introduce a new line of HEAD-branded golf equipment. This partnership empowers PowerBilt as the exclusive global licensee for HEAD golf products and expands the market with premium golf bags, woods, irons, and more, officially launched at the 2025 PGA Merchandise Show in Orlando.
Market Concentration & Characteristics:
The Golf Irons and Sets Market displays moderate to high concentration, dominated by a handful of multinational brands with strong global distribution networks. It emphasizes innovation, performance, and brand prestige, shaping consumer choices across both professional and recreational segments. It reflects a blend of premium positioning and growing affordability through mid-range offerings. Regional diversity in consumer demand requires adaptive strategies that balance advanced features with accessibility. The market’s competitive nature ensures continuous product upgrades, sustaining consumer interest and reinforcing brand differentiation. Strong after-sales services and fitting support further enhance long-term customer loyalty.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Application, Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Golf Irons and Sets Market will witness steady growth supported by increasing global participation in both recreational and professional golf.
- It is expected to benefit from technological advancements that enhance precision, forgiveness, and overall playability.
- Online retail and digital fitting tools will expand accessibility, particularly in regions with limited specialty stores.
- Rising golf tourism will stimulate demand in resort destinations and premium club facilities worldwide.
- Customization options will gain traction as players seek equipment tailored to individual swing styles and preferences.
- Sustainability initiatives will influence product development, with brands focusing on eco-friendly materials and production processes.
- Emerging economies will offer growth opportunities as rising incomes expand consumer interest in lifestyle sports.
- Strategic endorsements and high-profile tournaments will continue to shape brand visibility and influence purchase decisions.
- Competitive intensity will drive innovation cycles, with companies focusing on differentiation through design and technology.
- Integration of smart technologies will redefine consumer expectations, linking equipment performance with data-driven insights.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Participation in Golf
Increasing engagement in both recreational and professional golf is expanding the consumer base for golf irons and sets, supported by the sport's growing popularity as a lifestyle and networking activity.
Technological Advancements in Club Design
Continuous innovation in materials, club face engineering, and smart technologies is enhancing playability, forgiveness, and distance, driving consumer preference for premium and custom-fit equipment.
Influence of Professional Tournaments and Endorsements
High-profile tournaments and endorsements by professional golfers boost brand visibility and aspirational demand, encouraging consumers to invest in advanced irons and complete sets.
Expansion of E-Commerce and Digital Fitting Tools
The growth of online retail channels and the integration of digital fitting technologies are making golf equipment more accessible, especially in regions with limited specialty stores, thus broadening market reach.
Rising Middle-Class and Lifestyle-Driven Adoption
Increasing disposable incomes and the adoption of golf as a leisure and wellness activity among urban elites and the middle class in emerging markets are fueling demand for both entry-level and premium golf sets.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Golf Irons and Sets Market, and what is its projected size in 2032?
Which Golf Irons and Sets Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Golf Irons and Sets Market?
Who are the leading companies in the Golf Irons and Sets Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Professional Golfers
- 1.2.2 Amateur / Recreational Players
- 1.2.3 Beginner Segment
- 1.3 By Product Type
- 1.3.1 Irons
- 1.3.2 Woods
- 1.3.3 Hybrids
- 1.3.4 Wedges
- 1.3.5 Putters
- 1.3.6 Complete Sets
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,255.3 million → 2032: USD 5,612.0 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Golf Irons and Sets Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Golf Irons and Sets Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Golf Irons and Sets Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Golf Irons and Sets Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Golf Irons and Sets Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Golf Irons and Sets Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Golf Irons and Sets Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Golf Irons and Sets Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,255.3 million → 2032: USD 5,612.0 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Golf Irons and Sets Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Professional Golfers
- 12.3.7.2 Amateur / Recreational Players
- 12.3.7.3 Beginner Segment
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Irons
- 12.4.7.2 Woods
- 12.4.7.3 Hybrids
- 12.4.7.4 Wedges
- 12.4.7.5 Putters
- 12.4.7.6 Complete Sets
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Golf Irons and Sets End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Golf Irons and Sets Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Golf Irons and Sets Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Golf Irons and Sets Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Callaway Golf Company
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 TaylorMade Golf Company
- 18.4 Titleist (Acushnet Holdings Corp.)
- 18.5 Ping (Karsten Manufacturing Corp.)
- 18.6 Cobra Golf
- 18.7 Mizuno Corporation
- 18.8 Bridgestone Golf
- 18.9 Srixon / Cleveland Golf (Sumitomo Rubber Industries)
- 18.10 PXG (Parsons Xtreme Golf)
- 18.11 Wilson Sporting Goods
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

