
Market Overview:
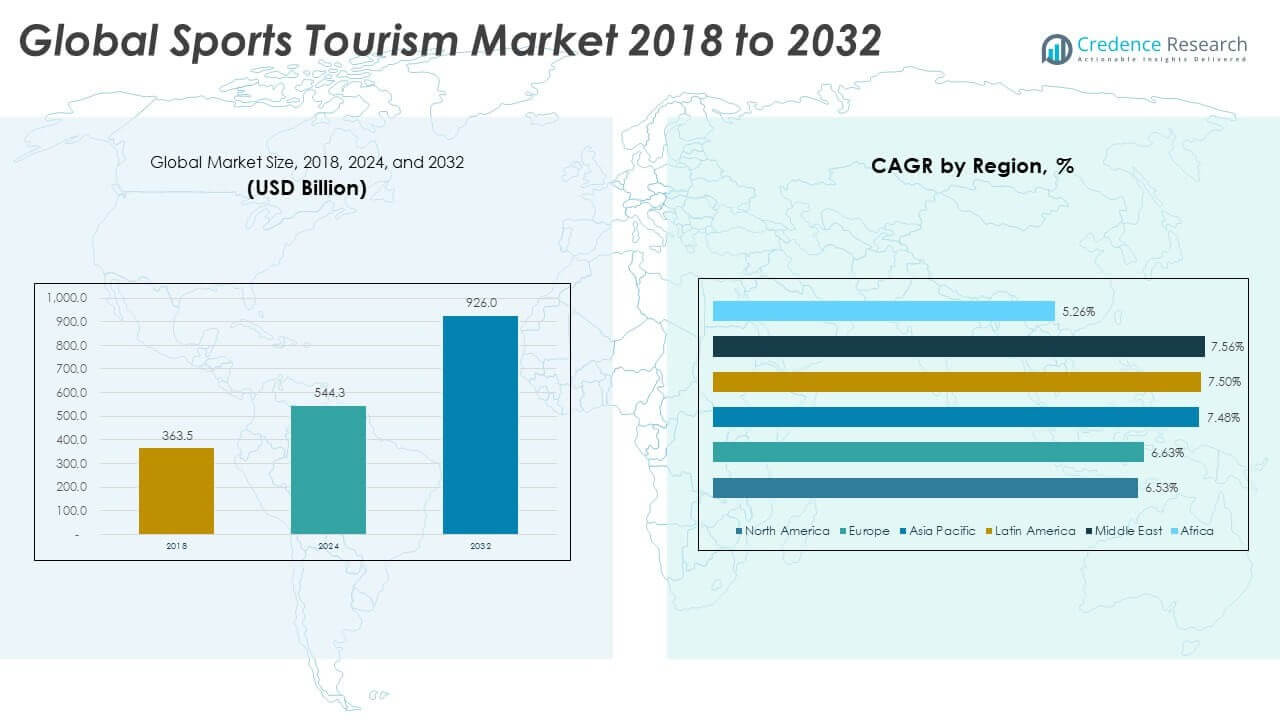
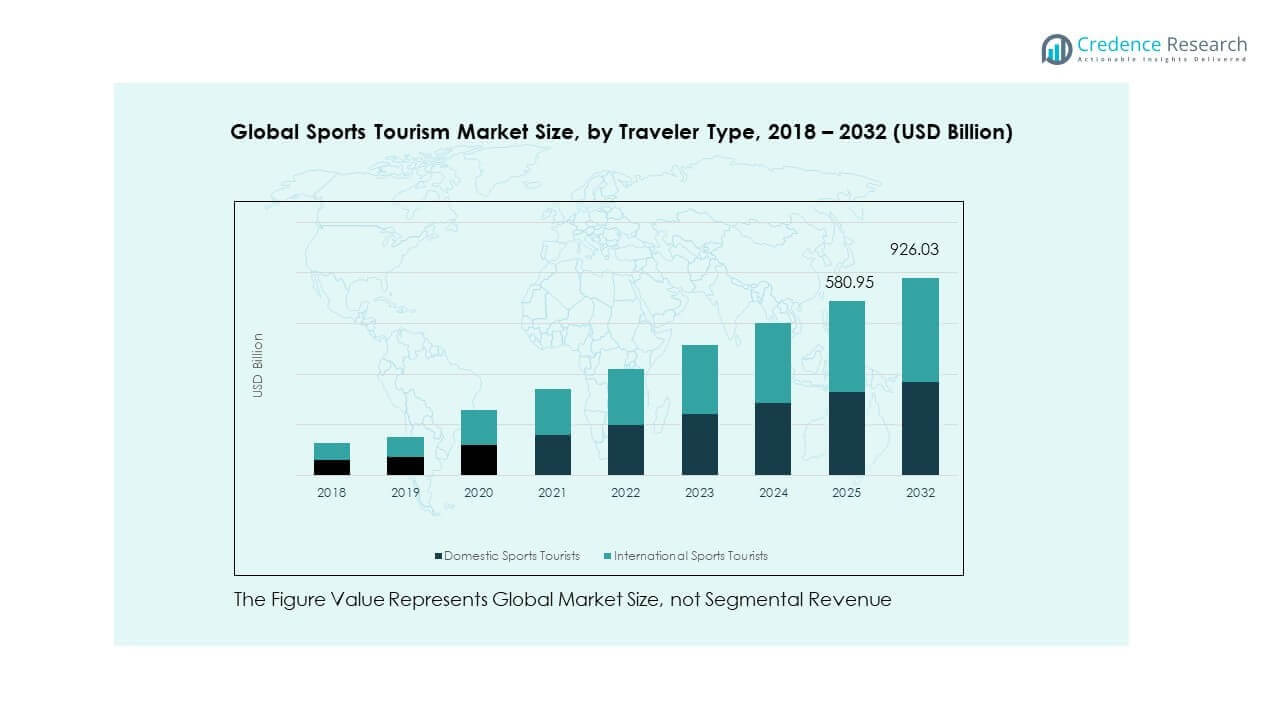
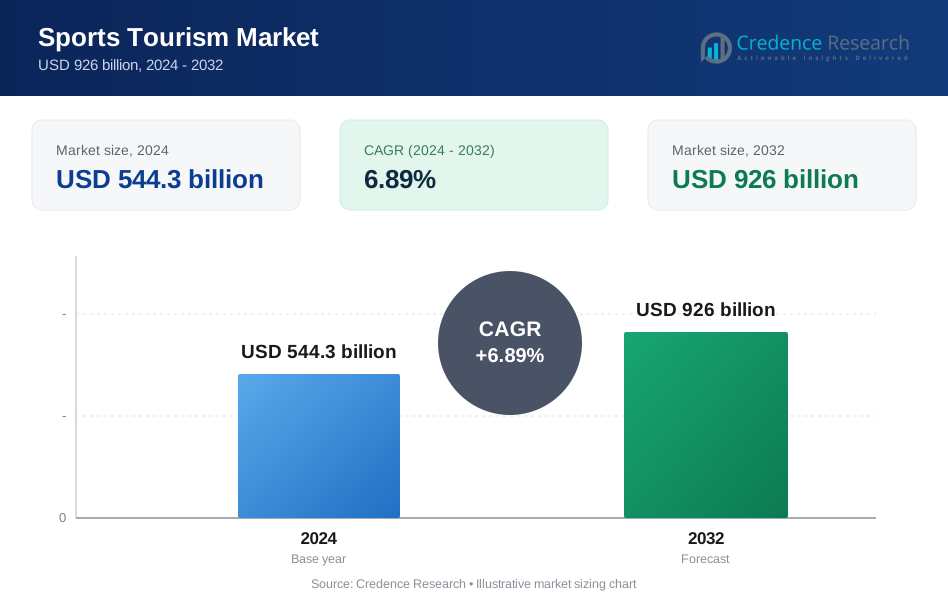
The Global Sports Tourism Market size was valued at USD 363.5 billion in 2018 to USD 544.3 billion in 2024 and is anticipated to reach USD 926 billion by 2032, at a CAGR of 6.89% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Sports Tourism Market Size 2024 | USD 544.3 Billion |
| Sports Tourism Market, CAGR | 6.89% |
| Sports Tourism Market Size 2032 | USD 926 Billion |
Market growth is driven by rising interest in live sporting experiences. Fans travel to attend global tournaments and league events. Adventure and fitness tourism attract active travelers seeking participation. Governments support sports infrastructure to boost tourism appeal. Media coverage increases event visibility and travel intent. Sports franchises promote destination-based events year-round. Improved transport access supports cross-border travel. Digital ticketing and travel platforms simplify planning. Corporate sponsorships also support international sports events.
North America leads the market due to strong sports culture and frequent mega-events. The United States drives demand through leagues and international tournaments. Europe follows with football-driven travel across major destinations. Countries such as the UK, Germany, and Spain attract steady inflows. Asia Pacific is emerging rapidly due to rising incomes and new venues. China, Japan, and Australia invest in global events. The Middle East gains traction through event-led tourism strategies.
Market Insights:
- The market was valued at USD 363.5 billion in 2018, reached USD 544.3 billion in 2024, and is projected to hit USD 926.0 billion by 2032, growing at a CAGR of 6.89%.
- North America leads with about 31.8% share, followed by Europe at 26.6% and Asia Pacific at 23.9%. These regions dominate due to dense sports calendars, strong fan travel culture, and advanced travel infrastructure.
- Asia Pacific is the fastest-growing region with nearly 23.9% share, supported by rising disposable income, large domestic sports audiences, and heavy investment in global event hosting.
- By traveler type, domestic sports tourists account for about 60% of total market share, driven by frequent short-distance travel and regional league events.
- International sports tourists hold roughly 40% share, supported by mega events, premium experiences, and cross-border fan mobility.
Market Drivers:
Rising Global Interest In Live Sports Events And Fan Travel Mobility
The Global Sports Tourism Market benefits from strong fan demand for live sports experiences. Major leagues and international tournaments attract steady domestic and cross-border travel. Fans value stadium atmosphere, social engagement, and emotional connection with teams. Host cities invest in modern venues to secure repeat events. Sports calendars now operate across most months of the year. Travel operators bundle tickets, lodging, and transport services. Airlines and hotels align offerings with event schedules. This driver sustains consistent visitor movement across key destinations.
- For instance, the FIFA World Cup Qatar 2022 recorded 3.4 million stadium attendances across 64 matches. Host cities invested an estimated $220 billion in infrastructure, including seven new stadiums and extensive transport links like the Doha Metro.
Growth Of Participatory And Adventure-Based Sports Travel Experiences
Active travellers increasingly seek hands-on sports experiences during leisure trips. It benefits from rising health, fitness, and lifestyle awareness. Events such as marathons, cycling tours, and golf travel gain traction. Destinations promote amateur competitions to attract global participants. Training camps draw youth teams and semi-professional athletes. Sports academies partner with tourism authorities for structured programs. Longer stay durations support local economies. This driver expands demand beyond spectator-focused travel.
- For instance, the Boston Marathon typically welcomes around 30,000 registered runners from approximately 129 countries along its course each year.
Government Investment In Sports Infrastructure And Event Hosting
Public authorities invest heavily in stadiums and multi-sport facilities. It aligns national sports policy with tourism growth objectives. Governments actively bid for global tournaments and championships. Infrastructure upgrades improve visitor comfort and safety. Visa facilitation supports short-term sports travel. Public spending raises destination credibility. Urban renewal often follows large sports projects. This driver strengthens long-term market foundations.
Media Coverage And Commercial Sponsorship Expansion Across Sports
Global media coverage increases sports event visibility across regions. It benefits from streaming platforms and digital broadcasts. Sponsors link brands with destination exposure and fan loyalty. Media narratives build emotional attachment to events. Sports tourism gains aspirational value through promotion. Athlete endorsements influence travel choices. Marketing reaches younger audiences effectively. This driver accelerates international travel interest.
Market Trends:
Shift Toward Multi-Day Sports Festivals And Integrated Event Formats
The Global Sports Tourism Market shows a shift toward festival-style events. Organizers combine sports with music, culture, and food experiences. Visitors prefer immersive, multi-day formats. Cities design dedicated event districts near venues. Integrated formats raise per-visitor spending levels. Local businesses gain broader participation benefits. Event schedules cluster multiple competitions. This trend reshapes destination planning strategies.
- For instance, the Formula 1 World Championship’s 2023 season drew over 6 million total attendances across 22 race weekends globally.
Rising Demand For Premium And VIP Sports Travel Experiences
High-income travellers increasingly seek exclusive sports travel packages. It includes premium seating and behind-the-scenes access. Luxury hotels partner with event organizers. Customized itineraries gain preference among elite travellers. Private transport and concierge services see rising demand. Brands target niche premium segments. Experience quality outweighs price sensitivity. This trend supports higher revenue potential.
- For instance, at the 2024 The Championships, Wimbledon fortnight, about 526,455 spectators visited the All England Club across the two weeks.
Digital Platforms Supporting Personalized Sports Travel Planning
Online platforms play a central role in sports travel planning. It enables real-time booking and itinerary customization. Mobile apps support venue access and event updates. Data tools predict fan travel preferences. Travel firms adopt dynamic pricing strategies. Digital access improves planning efficiency. Self-guided sports travel gains acceptance. This trend improves booking transparency.
Expansion Of Sports Tourism Beyond Tier-One Cities
Sports tourism activity expands into secondary cities. It reduces congestion in major hubs. Regional destinations gain national and international visibility. Smaller venues offer cost and access advantages. Domestic leagues attract regional tourists. Infrastructure investment spreads beyond capitals. Community engagement improves event success. This trend supports geographic diversification.
Market Challenges Analysis:
High Event Costs And Price Sensitivity Among Leisure Travelers
The Global Sports Tourism Market faces challenges from rising event-related costs. Major tournaments drive up ticket and accommodation prices. It limits access for price-sensitive travelers. Peak demand strains local infrastructure. Cost volatility affects travel planning confidence. Smaller operators face margin pressure. High prices reduce repeat visitation rates. Affordability remains a key concern.
Operational Risks From Seasonality And Event Dependency Patterns
Sports tourism relies heavily on fixed event schedules. It faces strong seasonal demand swings. Weather disruptions affect outdoor sports events. Event cancellations impact local revenues. Seasonal employment creates workforce instability. Facilities remain underused during off-periods. Risk concentration affects investment decisions. Diversification remains complex for operators.
Market Opportunities:
Emergence Of Sports Tourism In Developing And New Host Regions
The Global Sports Tourism Market presents strong opportunities in emerging regions. New host countries invest in international visibility. Asia Pacific expands venue and event capacity. Middle Eastern nations pursue event-led tourism strategies. Africa attracts niche adventure sports travelers. Governments support destination branding initiatives. Early market entry offers strategic advantages. This opportunity supports long-term expansion.
Integration Of Sustainability And Community-Based Sports Tourism Models
Sustainability creates new growth pathways for sports tourism. It encourages eco-friendly venue design and operations. Community sports programs attract responsible travelers. Local sourcing improves economic inclusion. Green travel appeals to younger demographics. Event waste reduction gains focus. Responsible practices strengthen destination trust. This opportunity aligns with future demand patterns.
Market Segmentation Analysis:
By Sports Type
The Global Sports Tourism Market shows strong variation across sports categories. Football and cricket drive large spectator travel due to league density and fan loyalty. Basketball attracts urban and indoor event travelers. Motorsports generate high-spend travel linked to premium events. Tennis supports steady travel around global tournaments. Golf tourism benefits from destination resorts and seasonal travel. Winter sports depend on alpine destinations and climate conditions. Other sports add niche demand and regional diversity.
- For instance, the British Grand Prix of the British Grand Prix 2023 season weekend saw 480,000 spectators, highlighting motorsport’s travel draw.
By Event Type
Mega sporting events create short-term travel surges and global visibility. Regional and league events support stable year-round tourism flows. Amateur and grassroots events attract families and community travelers. Sports training camps extend stay duration and repeat visits. Exhibition and friendly matches support off-season travel. Event diversity reduces dependence on single tournament cycles. Host cities benefit from varied visitor profiles.
- For instance, the FIFA World Cup format spreads over 64 matches with cumulative attendance topping 4 million, creating multiple travel peaks
By Traveler Type
Domestic sports tourists form the largest and most frequent travel base. Short travel distance supports weekend and repeat trips. International sports tourists drive higher per-trip spending. Cross-border travel links with flagship events and leagues. Visa access and connectivity influence travel volume. Both segments support different revenue patterns.
By Booking Channel
Direct booking grows with official event platforms. Online travel agencies support price comparison and convenience. Sports tour operators offer bundled and guided experiences. Event organizers manage premium and group travel demand. Channel mix reflects traveler planning preference. Digital access improves booking efficiency across segments.
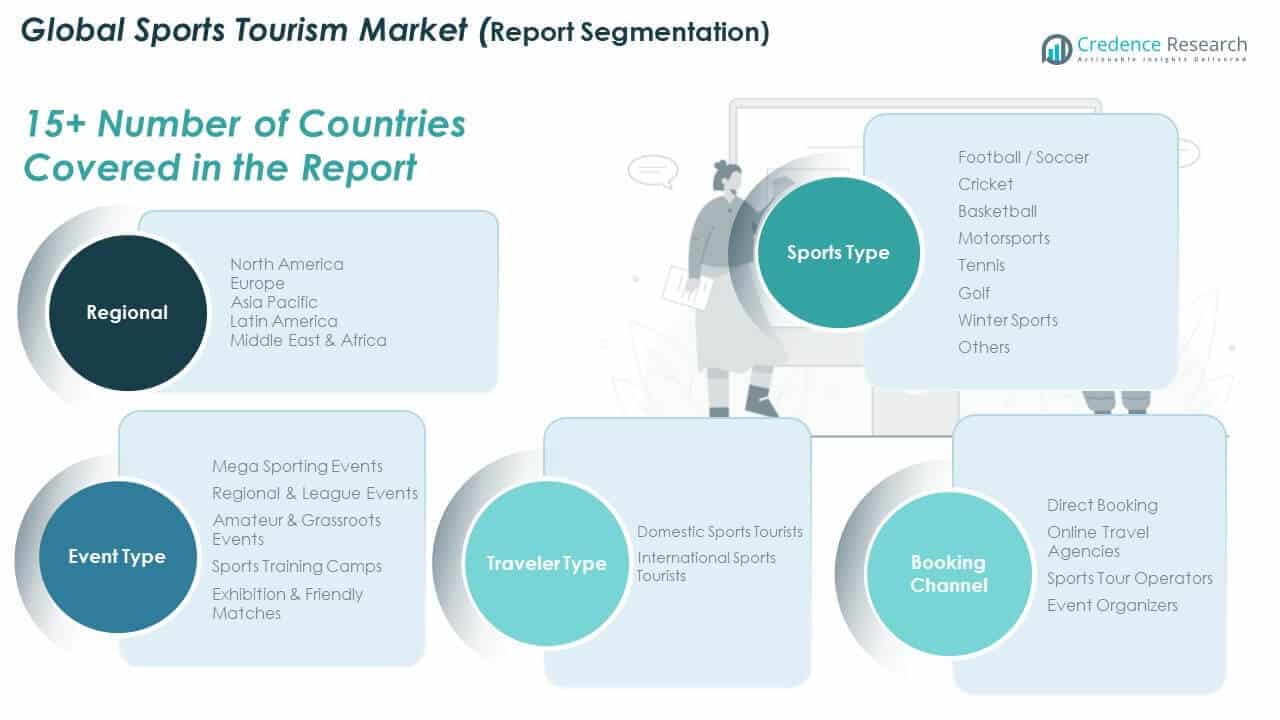
Segmentation:
By Sports Type
- Football / Soccer
- Cricket
- Basketball
- Motorsports
- Tennis
- Golf
- Winter Sports
- Others
- Mega Sporting Events
- Regional & League Events
- Amateur & Grassroots Events
- Sports Training Camps
- Exhibition & Friendly Matches
- Domestic Sports Tourists
- International Sports Tourists
- Direct Booking
- Online Travel Agencies
- Sports Tour Operators
- Event Organizers
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Global Sports Tourism Market size was valued at USD 118.00 billion in 2018 to USD 173.27 billion in 2024 and is anticipated to reach USD 287.07 billion by 2032, at a CAGR of 6.53 during the forecast period. North America accounts for about 31.8% market share in 2024. The region benefits from strong professional leagues and frequent international events. The United States drives demand through year-round sports calendars. Canada supports growth through hockey, motorsports, and major tournaments. Well-developed travel infrastructure supports fan mobility. Corporate sponsorship strengthens event scale. Media reach supports destination visibility. The market shows stable and predictable demand patterns.
Europe
The Europe Global Sports Tourism Market size was valued at USD 98.16 billion in 2018 to USD 144.86 billion in 2024 and is anticipated to reach USD 241.69 billion by 2032, at a CAGR of 6.63 during the forecast period. Europe holds nearly 26.6% market share in 2024. Football dominates travel flows across countries. The UK, Germany, Spain, and Italy attract consistent fan travel. Regional leagues ensure steady tourism activity. Cross-border travel remains high due to proximity. Historic venues add destination appeal. Public transport supports event access. The region shows strong repeat visitation.
Asia Pacific
The Asia Pacific Global Sports Tourism Market size was valued at USD 84.01 billion in 2018 to USD 130.19 billion in 2024 and is anticipated to reach USD 231.51 billion by 2032, at a CAGR of 7.48 during the forecast period. Asia Pacific captures about 23.9% market share in 2024. Rapid income growth supports travel spending. China, Japan, India, and Australia lead demand. Cricket, football, and motorsports drive travel. Governments invest in global event hosting. New venues raise regional competitiveness. Domestic tourism forms a strong base. The region shows fast structural expansion.
Latin America
The Latin America Global Sports Tourism Market size was valued at USD 31.85 billion in 2018 to USD 49.40 billion in 2024 and is anticipated to reach USD 87.97 billion by 2032, at a CAGR of 7.50 during the forecast period. Latin America holds nearly 9.1% market share in 2024. Football shapes most travel demand. Brazil and Argentina lead regional activity. Fan culture supports strong event attendance. Regional tournaments attract cross-border visitors. Infrastructure gaps still limit scale. Public and private investment improves access. The market shows rising international interest.
Middle East
The Middle East Global Sports Tourism Market size was valued at USD 17.38 billion in 2018 to USD 27.07 billion in 2024 and is anticipated to reach USD 48.43 billion by 2032, at a CAGR of 7.56 during the forecast period. The Middle East accounts for about 5.0% market share in 2024. Governments pursue event-led tourism strategies. GCC countries host global tournaments actively. Premium venues support high-spend visitors. Air connectivity supports international access. Sports align with national branding goals. Seasonal events attract global audiences. The region shows strong future positioning.
Africa
The Africa Global Sports Tourism Market size was valued at USD 14.14 billion in 2018 to USD 19.49 billion in 2024 and is anticipated to reach USD 29.36 billion by 2032, at a CAGR of 5.26 during the forecast period. Africa holds around 3.6% market share in 2024. South Africa leads regional sports travel. Adventure and grassroots events support demand. Infrastructure limits large-scale hosting. Domestic tourism forms the core base. International events draw selective inflows. Policy support improves market confidence. The region shows gradual and steady growth.
Key Player Analysis:
- TUI Group
- Endeavor Group
- Sports Travel and Hospitality Group
- Kuoni Sports Travel
- Melsh Sports Tours
- QuintEvents
- Sports Tours International Ltd.
- ATPI Ltd.
- DTB Sports Management Ltd.
Competitive Analysis:
The Global Sports Tourism Market features a mix of global travel groups, niche sports tour operators, and event-focused specialists. Competition centers on event access, destination partnerships, and bundled service quality. Leading players focus on exclusive ticket rights and long-term contracts with leagues. It shows moderate consolidation, with larger firms expanding through partnerships and acquisitions. Service differentiation relies on premium experiences and logistics reliability. Digital booking capability strengthens competitive positioning. Regional operators compete through local expertise and pricing flexibility. Brand trust and event portfolio depth remain key success factors.
Recent Developments:
- STH Group solidified its position as a leading global sports travel provider through a high-profile partnership announced on April 12, 2025. New Zealand Rugby officially announced a four-year exclusive partnership with STH Group to deliver travel and hospitality experiences for All Blacks and Black Ferns fans globally. The partnership builds on a 12-year working relationship on All Blacks Tours. According to the official SportCal announcement, STH introduced premium offerings including "The 1905 Club," featuring exclusive food and beverage packages, premium seating, entertainment, and guest speaker appearances at All Black fixtures. STH's track record includes delivery of five Rugby World Cup hospitality programs, London 2012 Olympics, and Tokyo 2020 Olympics.
- Dertour Group, the tourism division of the cooperatively organized REWE Group, completed a major European acquisition in February 2025. On February 12, 2025, Dertour Group acquired the majority stake in Hotelplan Group from Swiss parent Migros for an undisclosed sum. The acquisition brought under Dertour's umbrella the Hotelplan Group's collection of specialist travel brands including Hotelplan Suisse, Hotelplan UK, Inghams, Explore Worldwide, Esprit, Santa's Lapland, and Inntravel. The acquisition was completed on August 28, 2025, according to official announcements from DERTOUR Group. The group stated that acquired brands would complement Dertour's existing portfolio including Kuoni, Carrier, CV Villas, Journey Latin America, Jules Verne, and Kirker. Dertour UK operates approximately 650 employees and maintains nearly 30 Kuoni-branded retail outlets.
- Liberty Media completed its acquisition of QuintEvents on January 4, 2024, having announced the definitive agreement on September 9, 2023. According to official Liberty Media and iSportConnect announcements, the transaction valued QuintEvents at $313 million for a stake exceeding 90%. QuintEvents operates the F1 Experiences program, which has served as Formula One's official ticketing and hospitality provider since 2017. The company maintains partnerships with the NBA, MotoGP, and Kentucky Derby. Following the acquisition, Liberty Media and QuintEvents continue to operate as separate companies while leveraging enhanced partnership opportunities.
Report Coverage:
The research report offers an in-depth analysis based on sports type, event type, traveler type, and booking channel segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Global event calendars will continue to support steady travel demand.
- Premium and experiential sports travel will gain stronger traction.
- Emerging regions will attract more international sports events.
- Digital booking and personalization tools will shape traveler choices.
- Partnerships between leagues and travel firms will deepen.
- Domestic sports tourism will remain a stable revenue base.
- Infrastructure investment will improve event hosting capacity.
- Sustainability practices will influence destination selection.
- Secondary cities will host more regional tournaments.
- Brand-led sports experiences will strengthen customer loyalty.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Sports Tourism Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Sports Tourism Market projected to grow between 2025 and 2032?
Which Global Sports Tourism Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Sports Tourism Market?
Who are the leading companies in the Global Sports Tourism Market?
Which region commanded the largest share of the Global Sports Tourism Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Sports Tourism Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Sports Tourism Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 544.3 billion → 2032: USD 926 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Sports Tourism Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Sports Tourism Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Sports Tourism Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Sports Tourism Market Drivers
- 3.3 Sports Tourism Market Restraints & Challenges
- 3.4 Sports Tourism Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Sports Tourism Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Sports Tourism Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Sports Tourism category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Sports Tourism Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Sports Tourism Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Sports Tourism market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Sports Tourism Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Sports Tourism Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Sports Tourism Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Sports Tourism (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Sports Tourism Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Sports Tourism Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Sports Tourism Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Sports Tourism Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Sports Tourism Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Sports Tourism Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Sports Tourism Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Sports Tourism Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Sports Tourism Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
