
Market Overview:
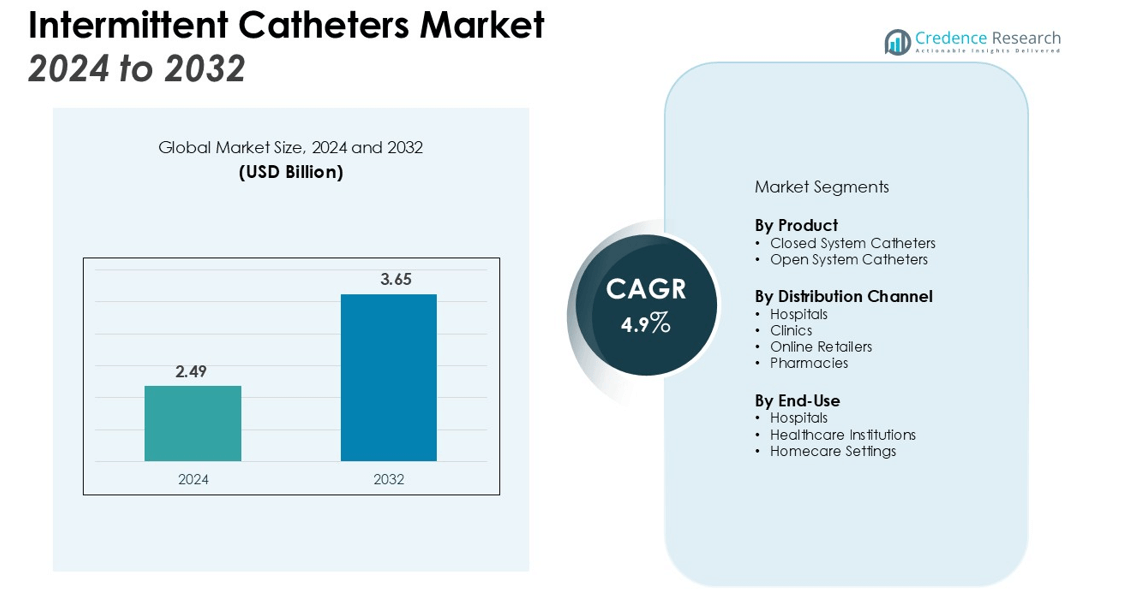
The Intermittent Catheters Market size was valued at USD 2.49 billion in 2024 and is anticipated to reach USD 3.65 billion by 2032, at a CAGR of 4.9% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Intermittent Catheters Market Size 2024 | USD 2.49 billion |
| Intermittent Catheters Market , CAGR | 4.9% |
| Intermittent Catheters Market Size 2032 | USD 3.65 billion |
Key drivers of the market include an aging global population, which leads to a higher incidence of conditions that necessitate urinary catheters, such as prostate enlargement, multiple sclerosis, and stroke. Additionally, advancements in catheter materials, such as hydrophilic coatings that reduce discomfort and the risk of infections, are boosting market growth. The introduction of user-friendly, single-use, and eco-friendly intermittent catheters further supports the market's expansion. Furthermore, increasing preference for homecare settings over hospital stays is driving the demand for these devices.
Geographically, North America holds the largest market share due to well-established healthcare systems and rising healthcare expenditure. Europe follows closely, with an increasing demand for advanced healthcare solutions. The Asia Pacific region is expected to witness the highest growth during the forecast period, attributed to improving healthcare infrastructure and increasing awareness in emerging economies like India and China.
Market Insights:
- The Intermittent Catheters Market is projected to grow from USD 2.49 billion in 2024 to USD 3.65 billion by 2032, at a CAGR of 4.9%.
- An aging global population is driving the demand for urinary catheters due to higher incidences of conditions like prostate enlargement and multiple sclerosis.
- Technological advancements, such as hydrophilic coatings, reduce discomfort and infection risks, making intermittent catheters safer and more comfortable.
- Increasing patient preference for homecare settings is fueling demand for easy-to-use and disposable intermittent catheters.
- Regulatory barriers and high production costs for advanced catheter designs are limiting market adoption, especially in cost-sensitive regions.
- Asia Pacific is expected to witness the highest market growth due to rising healthcare investments and an aging population in countries like China and India.
- North America holds the largest market share of 40%, supported by strong healthcare infrastructure, high spending, and technological adoption.
Market Drivers:
Aging Population and Increased Prevalence of Chronic Diseases
The growing global aging population is a significant driver for the Intermittent Catheters Market. As people age, they are more likely to experience medical conditions such as prostate enlargement, multiple sclerosis, and stroke, which often necessitate the use of urinary catheters. These chronic conditions increase the demand for intermittent catheters as a long-term management solution for urinary retention and incontinence.
Technological Advancements in Catheter Design
Advancements in catheter materials and designs have played a critical role in boosting market growth. Modern intermittent catheters are equipped with hydrophilic coatings, which reduce friction and discomfort during insertion. These innovations also help minimize the risk of infections, providing a safer and more comfortable experience for patients. The availability of easy-to-use designs encourages more patients to adopt this solution for managing urinary conditions.
- For instance, Hollister's Infyna Chic™ catheter features a hydrophilic coating that is ready to use and comes in a discrete, 5.5-inch-long case, which enhances convenience and user comfort.
Shift Toward Homecare Settings
There is a notable shift from hospital-based care to homecare for patients requiring urinary management. Intermittent catheters are increasingly being used in homecare settings due to their ease of use, disposable nature, and the growing trend of patient autonomy in healthcare. This shift has accelerated demand, particularly for single-use and compact catheters that are suitable for personal use at home.
- For instance, Teleflex's Rüsch® MMG H2O® closed system includes a 1300 mL collection bag, allowing for a complete and self-contained catheterization process at home, which can reduce the risk of UTIs.
Rising Healthcare Awareness and Accessibility
Increasing awareness of urological health and improved access to healthcare services are contributing to the growth of the Intermittent Catheters Market. Public education on urinary conditions, along with better access to healthcare products and devices, encourages more people to seek appropriate treatments. Enhanced awareness, especially in emerging economies, continues to drive adoption and use of intermittent catheters globally.
Market Trends:
Growing Demand for Eco-Friendly and Single-Use Catheters
A significant trend in the Intermittent Catheters Market is the rising demand for eco-friendly and single-use devices. The healthcare industry is increasingly focusing on reducing environmental impact, driving manufacturers to develop sustainable and biodegradable catheter solutions. Single-use catheters, made from materials that minimize the risk of infections and contamination, are growing in popularity due to their convenience and safety. This shift aligns with global sustainability initiatives and the increased emphasis on minimizing healthcare-associated risks. Manufacturers are responding to consumer preferences by producing more environmentally friendly products without compromising on performance or patient comfort.
- For instance, Johnson & Johnson's single-use medical device recycling program successfully recycled components from more than 25,000 of its products in Europe between 2021 and 2022, helping to keep valuable materials in the circular economy.
Advancements in Smart Catheters and Digital Integration
The integration of digital technology into intermittent catheter systems is another emerging trend in the market. Manufacturers are developing smart catheters equipped with sensors that monitor usage, fluid flow, and pressure, providing real-time feedback to patients and healthcare providers. These innovations enhance patient safety and comfort while offering better management of urinary conditions. The growing adoption of digital health solutions is pushing the market toward more intelligent devices that contribute to efficient healthcare delivery. With the incorporation of telemedicine and remote monitoring, these smart devices help patients manage their conditions more effectively and reduce hospital visits.
- For instance, in August 2021, Freudenberg Medical expanded its sensor integration capabilities for catheter manufacturing, incorporating technology for at least 3 types of sensors, including temperature, pressure, and fiber optic sensors.
Market Challenges Analysis:
Risk of Infection and Complications
One of the primary challenges facing the Intermittent Catheters Market is the risk of infections and other complications associated with catheter use. Although advancements in materials and coatings have minimized some of these risks, catheter-associated urinary tract infections (CAUTIs) remain a significant concern. Patients are at risk of developing infections due to improper usage, lack of hygiene, or prolonged catheterization. Manufacturers continue to focus on developing safer, more effective solutions, but the challenge of minimizing infections persists, especially in healthcare settings where patient management is critical.
Regulatory and Cost Constraints
Regulatory hurdles and cost limitations also impact the Intermittent Catheters Market. Stringent regulations for medical devices require compliance with safety and performance standards, which can delay product approval and market entry. High production costs, especially for advanced catheter designs and smart catheter technologies, can limit adoption in price-sensitive regions. Patients and healthcare providers often face financial barriers when seeking high-quality, innovative solutions, further limiting market growth. Cost-effectiveness remains a key factor for broader adoption, particularly in emerging markets.
Market Opportunities:
Expansion in Emerging Markets
The Intermittent Catheters Market holds significant opportunities in emerging economies, where healthcare infrastructure is improving rapidly. Increasing urbanization, better access to healthcare products, and rising awareness about urological health are contributing to the growth of the market in regions like Asia Pacific, Latin America, and the Middle East. As healthcare standards rise in these regions, there is greater demand for effective, affordable solutions for managing chronic urological conditions. The expanding middle class in these regions also opens doors for more people to access high-quality intermittent catheters, boosting market growth.
Growing Demand for Homecare Solutions
The growing trend toward homecare presents an opportunity for the Intermittent Catheters Market. With more patients opting for home-based care, especially for chronic conditions, there is an increasing need for user-friendly and disposable catheter products. Patients seek solutions that provide comfort, safety, and convenience in a home setting. This trend drives demand for portable and easy-to-use intermittent catheters that can be managed independently. As the preference for home healthcare increases globally, it presents a lucrative opportunity for companies to innovate and expand their product offerings to cater to this growing segment.
Market Segmentation Analysis:
By Product
The market is primarily divided into two product categories: closed system catheters and open system catheters. Closed system catheters are designed for easy and hygienic use, reducing the risk of infection, which makes them increasingly popular among patients and healthcare providers. Open system catheters, on the other hand, are cost-effective but require more manual handling. The preference for closed system catheters is expected to drive market growth due to their added convenience and safety features.
By Distribution Channel
The Intermittent Catheters Market is distributed through hospitals, clinics, online retailers, and pharmacies. Hospitals and clinics remain the primary distribution channels, driven by the demand from healthcare professionals for sterile and safe catheterization solutions. However, the rise in e-commerce and online pharmacies is contributing significantly to the market’s growth. Consumers are opting for the convenience of purchasing catheters online, making this channel increasingly popular, especially in regions with strong internet penetration.
- For instance, Boston Scientific supplies highly specialized catheters to hospitals, such as its Site Selective Pacing Catheter, which has a working length of 40 cm and is intended to introduce pacing leads in cardiovascular procedures.
By End-Use
The primary end-users of intermittent catheters are individuals requiring long-term care for conditions such as spinal cord injuries, neurological disorders, and urinary retention. Hospitals and healthcare institutions are the leading end-users due to their infrastructure for patient care. However, the growing shift toward homecare settings is expanding the market, as more patients opt for independent management of their conditions. Homecare adoption will continue to accelerate the demand for disposable and user-friendly intermittent catheters.
- For instance, Hollister Incorporated addresses the homecare market with its VaPro Plus Pocket™ intermittent catheter, which provides a completely no-touch system that includes an integrated 1000ml collection bag for convenient self-catheterization anywhere.
Segmentations:
By Product:
- Closed System Catheters
- Open System Catheters
By Distribution Channel:
- Hospitals
- Clinics
- Online Retailers
- Pharmacies
By End-Use:
- Hospitals
- Healthcare Institutions
- Homecare Settings
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America
North America holds the largest share of the Intermittent Catheters Market, accounting for 40%. This dominance is due to well-established healthcare infrastructure, high healthcare spending, and advanced technological adoption. The U.S. and Canada continue to lead the market, driven by a growing aging population and the prevalence of chronic conditions that require catheterization. The region benefits from strong healthcare policies, which support the availability and accessibility of advanced medical devices. The presence of key market players in North America also fosters innovation and product development, further strengthening its market position.
Europe
Europe accounts for 30% of the Intermittent Catheters Market share, with strong healthcare systems and a focus on patient care and urological health. The rising prevalence of age-related diseases, such as prostate enlargement and stroke, contributes to the demand for intermittent catheters. Countries like Germany, the UK, and France are key contributors to market growth. Regulations focusing on quality standards and safety also drive the development of more effective and safer catheter solutions. Europe’s commitment to improving healthcare access and reducing hospital-associated infections promotes the adoption of advanced catheter technologies.
Asia Pacific
The Asia Pacific region holds 20% of the Intermittent Catheters Market share and is expected to experience the highest growth in the forecast period. Factors such as rising healthcare investments, improving medical infrastructure, and increasing healthcare awareness in countries like China, India, and Japan are major drivers. The growing incidence of chronic diseases in this region, combined with a large aging population, fuels the demand for urological products like intermittent catheters. As healthcare accessibility improves and patient education increases, the market is poised for rapid expansion in these emerging economies.
Key Player Analysis:
- Teleflex Incorporated
- Hollister Incorporated
- Coloplast
- Cardinal Health
- Medline Industries, LP.
- ConvaTec
- BD
Competitive Analysis:
The Intermittent Catheters Market is highly competitive, with key players like Coloplast, ConvaTec, B. Braun Melsungen AG, BD (Becton Dickinson), Medtronic, and Hollister Incorporated leading the market. These companies maintain strong positions through extensive product portfolios, large distribution networks, and continuous investments in research and development. Innovations such as ConvaTec's GentleCath Air catheter and Coloplast's expanded manufacturing capabilities address specific patient needs, while emerging companies like Hunter Urology and Pennine Healthcare focus on niche markets. Competitive strategies include adopting advanced materials, improving product comfort and safety, and integrating digital health technologies. The market remains dynamic, driven by continuous product innovations and regulatory compliance.
Recent Developments:
- In July 2025, Hollister Incorporated announced an €80 million investment in its facility in Ballina, County Mayo, Ireland, to support research and development as well as digital transformation, creating approximately 50 new positions.
- In February 2025, Teleflex Incorporated announced its intention to separate into two independent, publicly traded companies, with one company focusing on its Urology, Acute Care, and OEM businesses.
- In September 2025, Medline UNITE is scheduled to launch its new FORCECORD™ and DEXLOCK® Achilles repair systems at the American Orthopedic Foot and Ankle Society (AOFAS) Annual Meeting.
Report Coverage:
The research report offers an in-depth analysis based on Product, Distribution Channel, End-Use and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for intermittent catheters will continue to grow due to the rising prevalence of chronic conditions, such as prostate enlargement, multiple sclerosis, and stroke.
- Technological advancements in catheter materials, including hydrophilic coatings and biocompatible designs, will enhance patient comfort and safety.
- The shift towards homecare settings will drive growth, as more patients seek convenient and user-friendly solutions for managing urinary retention and incontinence.
- Increasing healthcare awareness globally will lead to higher adoption rates, especially in emerging economies.
- Strong growth in online sales and e-commerce platforms will make catheters more accessible to patients in both developed and developing regions.
- The development of eco-friendly and disposable catheters will address sustainability concerns, further driving adoption.
- Increased focus on patient education and self-care will empower individuals to manage their conditions independently, creating a larger market for home-use devices.
- North America will continue to dominate the market, with significant contributions from healthcare infrastructure and high healthcare spending.
- Asia Pacific is expected to witness rapid market expansion, driven by improving healthcare infrastructure and a growing aging population in countries like India and China.
- Partnerships between catheter manufacturers and healthcare providers will foster innovations and expand market reach, particularly in developing regions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Aging Population and Chronic Disease Prevalence
The global increase in the elderly population leads to a higher incidence of conditions such as prostate enlargement, multiple sclerosis, and stroke, all of which often require intermittent catheterization for urinary management. This demographic trend is a major factor driving sustained demand for intermittent catheters.
Technological Advancements in Catheter Design
Innovations such as hydrophilic coatings and biocompatible materials have made intermittent catheters safer and more comfortable, reducing infection risks and improving patient compliance. These advancements encourage both healthcare providers and patients to adopt newer, higher-value catheter products.
Shift Toward Homecare Settings
There is a growing preference for home-based care over hospital stays, especially for chronic urinary conditions. User-friendly, disposable, and portable intermittent catheters enable patients to manage their conditions independently, fueling market growth in the homecare segment.
Rising Healthcare Awareness and Accessibility
Increased public education about urological health and improved access to healthcare services, particularly in emerging economies, are encouraging more individuals to seek appropriate treatment for urinary retention and incontinence, thereby expanding the market.
Growth of Eco-Friendly and Single-Use Catheters
The healthcare industry's focus on sustainability and infection control is driving demand for single-use, eco-friendly intermittent catheters. These products reduce the risk of cross-contamination and align with global sustainability initiatives, further supporting market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Intermittent Catheters, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Intermittent Catheters market projected to grow between 2024 and 2032?
Which Intermittent Catheters market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Intermittent Catheters market?
Who are the leading companies in the Intermittent Catheters market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-Use
- 1.2.1 Hospitals
- 1.2.2 Healthcare Institutions
- 1.2.3 Homecare Settings
- 1.3 By Product
- 1.3.1 Closed System Catheters
- 1.3.2 Open System Catheters
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2.49 billion → 2032: USD 3.65 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Intermittent Catheters Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Intermittent Catheters Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Intermittent Catheters Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Intermittent Catheters Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Intermittent Catheters Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Intermittent Catheters Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Intermittent Catheters Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Intermittent Catheters Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2.49 billion → 2032: USD 3.65 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Intermittent Catheters Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Healthcare Institutions
- 12.3.7.3 Homecare Settings
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Closed System Catheters
- 12.4.7.2 Open System Catheters
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Intermittent Catheters End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Intermittent Catheters Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Intermittent Catheters Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Intermittent Catheters Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Teleflex Incorporated
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Hollister Incorporated
- 18.4 Coloplast
- 18.5 Cardinal Health
- 18.6 Medline Industries, LP.
- 18.7 ConvaTec
- 18.8 BD (Becton Dickinson)
- 18.9 B. Braun Melsungen AG
- 18.10 Medtronic
- 18.11 Hunter Urology
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

