
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Lightweight Aggregate Concrete Market Size 2023 | USD 48,762.39 Million |
| Lightweight Aggregate Concrete Market, CAGR | 4.80% |
| Lightweight Aggregate Concrete Market Size 2032 | USD 74,359.51 Million |
Market Overview
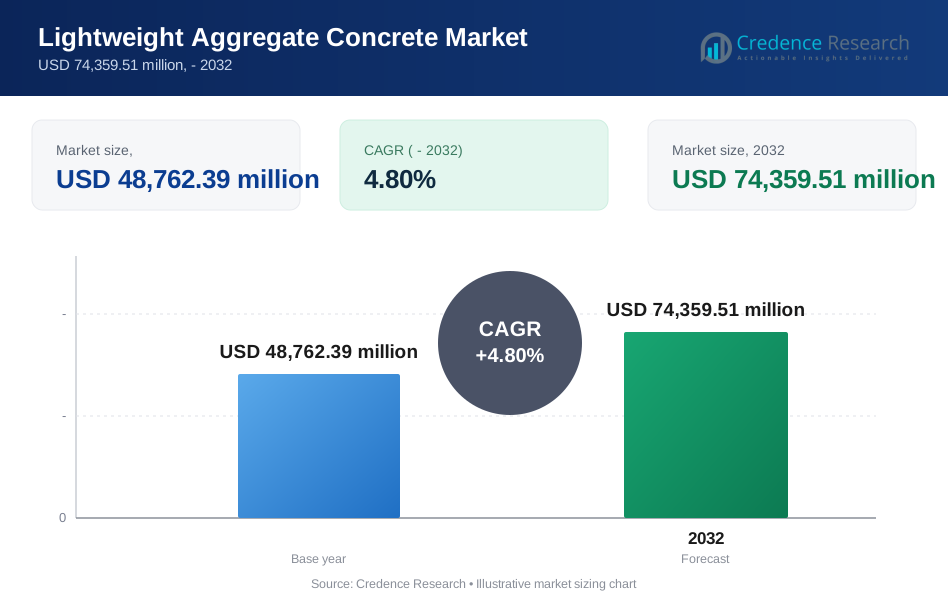
The Lightweight Aggregate Concrete Market is projected to grow from USD 48,762.39 million in 2023 to USD 74,359.51 million by 2032, at a compound annual growth rate (CAGR) of 4.80%.
The Global Lightweight Aggregate Concrete Market is driven by the growing demand for sustainable and energy-efficient building materials, as well as the increasing emphasis on reducing the overall weight of structures without compromising strength. As urbanization and infrastructure development accelerate, lightweight aggregate concrete is becoming a preferred choice for its benefits in improving structural performance and reducing transportation costs. Additionally, advancements in production technologies and the rising adoption of green building practices are further propelling market growth. The trend towards using environmentally friendly materials is also fostering innovation in lightweight aggregate concrete formulations, enhancing its appeal across various construction sectors.
The global Lightweight Aggregate Concrete (LWAC) market exhibits diverse geographical dynamics, with significant growth in Asia-Pacific due to rapid urbanization and infrastructure development, capturing a notable market share. North America follows closely, driven by advancements in construction technology and sustainable building practices. Key players such as Holcim, Boral Limited, and CRH plc lead the market with extensive product portfolios and strategic expansions. Additionally, companies like HEIDELBERGCEMENT and Cemex contribute to market growth through innovations and regional market penetration, ensuring a competitive landscape across major global regions.
Market Drivers
Energy Efficiency, Sustainability, and Seismic Resistance
The global shift towards energy efficiency and sustainable construction practices is another major driver for the LWAC market. With its lower thermal conductivity, LWAC helps maintain stable indoor temperatures, thereby reducing energy consumption for heating and cooling. For instance, buildings in the United States were responsible for roughly 13.5 percent of the greenhouse gas emissions in 2022. This characteristic aligns with the increasing emphasis on green building initiatives and sustainability, making LWAC a preferred choice for environmentally conscious construction projects. Additionally, in earthquake-prone regions, LWAC's lighter weight and enhanced seismic performance make it a safer alternative, reducing the risk of structural damage during seismic events. This dual benefit of energy efficiency and seismic resistance positions LWAC as a valuable material in both residential and commercial construction.
Improved Fire Resistance and Cost-Effectiveness
Stricter fire safety regulations have heightened the demand for building materials with superior fire resistance properties, further boosting the adoption of LWAC. The material's inherent fire-resistant characteristics make it suitable for use in structures that must adhere to rigorous safety standards. According to testing data from the National Institute of Standards and Technology, LWAC can maintain its structural integrity for up to 4 hours in standard fire resistance tests, compared to 2-3 hours for normal weight concrete. While LWAC may have a slightly higher initial cost compared to traditional concrete, its long-term benefits such as reduced energy consumption, lower maintenance costs, and improved safety make it a cost-effective option for many projects. These factors contribute to LWAC's growing popularity in regions where both safety and sustainability are top priorities.
Increased Construction Activity and Urbanization
The rapid pace of urbanization and population growth worldwide is driving a significant increase in construction activities, spanning residential, commercial, and infrastructure developments. As cities expand and populations rise, the demand for building materials like Lightweight Aggregate Concrete (LWAC) is surging. LWAC is favored for its ability to reduce the overall weight of structures without compromising strength, making it ideal for high-rise buildings and large-scale infrastructure projects. This trend is particularly pronounced in rapidly developing regions where the need for new housing, commercial spaces, and public infrastructure is critical to accommodating growing urban populations.
Technological Advancements and Material Innovation
Ongoing research and development in the field of LWAC technology continue to drive market growth by introducing new formulations with enhanced properties. Innovations in material science have led to the development of LWAC that offers higher strength, greater durability, and improved performance under various environmental conditions. These advancements not only broaden the range of applications for LWAC but also enhance its appeal as a modern, versatile building material. As construction projects become more complex and demanding, the continuous improvement of LWAC ensures that it remains a competitive and attractive option for builders and architects looking to meet the challenges of contemporary construction.
Market Trends
Increasing Adoption in Prefabricated Construction and Integration with Advanced Technologies
The Global Lightweight Aggregate Concrete (LWAC) Market is witnessing a significant trend towards the adoption of prefabricated construction methods, driven by the need for efficiency and speed in building projects. For instance, about 90% of users report improved productivity, improved quality, and increased schedule certainty when using these methods compared to traditional stick-built construction. LWAC's lightweight nature and ease of handling make it an ideal material for prefabricated components, which can be quickly assembled on-site, reducing construction timelines and minimizing disruptions. This modularity not only improves the overall quality control of construction projects but also enhances the flexibility of design, allowing for faster project completion and cost savings. Simultaneously, LWAC is increasingly being integrated with advanced technologies, such as the Internet of Things (IoT) and automation, to create smart buildings that offer enhanced energy efficiency, security, and occupant comfort. The development of 3D printing technologies for concrete further expands the possibilities for LWAC applications, enabling the construction of complex and customized structures that were previously difficult to achieve with traditional methods. This integration of LWAC with cutting-edge technologies is transforming the construction industry, paving the way for more innovative and sustainable building solutions.
Focus on Recycled Materials and Regional Variations
Sustainability continues to be a key focus in the LWAC market, with a growing trend towards incorporating recycled materials into concrete production. The use of recycled aggregates in LWAC not only reduces the environmental impact of construction but also makes the material more cost-effective. By utilizing waste products and recycled materials, LWAC manufacturers can lower production costs while contributing to the circular economy, making it an attractive option for environmentally conscious projects. This trend is particularly relevant in emerging markets across Asia-Pacific and Latin America, where rapid urbanization and infrastructure development are driving demand for sustainable construction materials. These regions are experiencing significant growth in the LWAC market as they seek to balance the need for new construction with environmental considerations. In contrast, developed markets like North America and Europe, which already have established LWAC industries, are focusing on further advancements in technology and sustainability initiatives to drive continued growth. The competitive landscape in the LWAC market is marked by consolidation, with both large multinational companies and regional players investing in research and development to innovate new formulations, improve manufacturing processes, and expand their product offerings.
Market Challenges Analysis
Initial Cost and Limited Awareness and Knowledge
One of the primary challenges facing the Global Lightweight Aggregate Concrete (LWAC) market is the higher initial cost associated with its use. Although LWAC offers significant long-term cost savings through reduced energy consumption and lower maintenance expenses, the upfront investment required for specialized materials and equipment can be substantially higher compared to traditional concrete. For instance, the average estimated cost of LWA in the United States is USD 67.5/tonne, which is much more expensive than conventional aggregates. This initial expense, combined with the perception of LWAC as a more costly option, may deter potential users and inhibit widespread adoption. Additionally, limited awareness and knowledge about LWAC further compound this issue. Many stakeholders, including builders, contractors, and project owners, may lack comprehensive information about the benefits and applications of LWAC. This gap in understanding can lead to misconceptions about its performance and durability, which may hinder its acceptance and integration into mainstream construction practices. Educating stakeholders and increasing awareness about the advantages of LWAC are crucial steps in overcoming this challenge.
Quality Control and Supply Chain Challenges
Quality control and standardization present significant hurdles for the LWAC market. Variability in the quality of LWAC can arise from differences in composition, manufacturing processes, and adherence to regional standards. The absence of universally accepted standards for LWAC can result in inconsistent quality and performance, complicating its acceptance across different markets. Furthermore, supply chain challenges, including the availability and cost of lightweight aggregates, impact the overall cost and supply of LWAC. The availability of these aggregates can fluctuate based on regional factors, and their transportation costs tend to be higher than those for traditional aggregates due to their lower density. These supply chain issues can add to the overall cost and logistical complexities associated with LWAC. Additionally, LWAC faces competition from alternative lightweight building materials, such as aerated concrete blocks and expanded clay concrete, which may offer similar benefits but at varying price points or with different performance characteristics. Regulatory barriers, including outdated building codes and complex permitting processes, can also impede the adoption of LWAC, as some regions may not have fully integrated its use into their regulatory frameworks. Addressing these challenges requires focused efforts on standardization, supply chain optimization, and regulatory alignment to facilitate broader acceptance and integration of LWAC in the construction industry.
Market Segmentation Analysis:
By Type:
The Global Lightweight Aggregate Concrete (LWAC) market is segmented by type into Expanded Clay, Expanded Perlite, Expanded Glass, Expanded Shale, and Others. Expanded Clay dominates this segment due to its favorable properties, including thermal insulation and lightweight characteristics, making it ideal for various construction applications. Expanded Perlite follows closely, appreciated for its excellent insulation and fire-resistance qualities. Expanded Glass and Expanded Shale are also significant, with Expanded Glass being valued for its durability and resistance to weather conditions, while Expanded Shale offers high strength and low density. The "Others" category includes niche materials that cater to specific project requirements. Each type presents unique advantages that cater to different construction needs, contributing to the diverse applications and growth of the LWAC market.
By Application:
In terms of application, the LWAC market is divided into Structural and Non-Structural categories. Structural applications hold a substantial share of the market due to the material's strength and load-bearing capabilities, which are essential for building frameworks, bridges, and high-rise buildings. Non-Structural applications are also significant, where LWAC is used in infill panels, partitions, and lightweight roofing solutions. The growing preference for energy-efficient and sustainable building solutions drives demand across both segments. Structural applications benefit from LWAC's ability to reduce overall building weight and enhance seismic performance, while Non-Structural applications leverage its insulation properties and ease of handling. This segmentation reflects the material's versatility and broad applicability in modern construction projects.
Segments:
Based on Type:
- Expanded Clay
- Expanded Perlite
- Expanded Glass
- Expanded Shale
- Others
Based on Application:
- Structural
- Non-Structural
Based on End-user:
- Industrial Use
- Infrastructure
- Civil Use
- Commercial
- Others
Based on Density & Strength:
- Low Density Concrete
- Medium Density Concrete
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds approximately 30% of the global market share, reflecting its strong position and ongoing investment in infrastructure and sustainable construction. In North America, the market is robust, driven by a high level of construction activity, particularly in commercial and residential sectors. For instance, a survey conducted by the National Ready Mixed Concrete Association found that 78% of contractors in the U.S. reported using lightweight aggregate concrete in at least one project over the past year. The United States, in particular, contributes a substantial portion of the market share due to its advanced construction practices and increasing adoption of sustainable building materials. The region's focus on energy efficiency and compliance with stringent building codes has bolstered demand for LWAC, which offers benefits like improved thermal insulation and reduced building weight.
Asia-Pacific
In contrast, the Asia-Pacific region is experiencing rapid growth, driven by urbanization and infrastructure development in emerging economies such as China and India. This region is expected to capture around 40% of the global market share due to its large-scale construction projects and the increasing need for cost-effective and energy-efficient building solutions. The surge in residential, commercial, and infrastructure developments, combined with supportive government policies promoting green building practices, is fueling the demand for LWAC. The region's expansive growth opportunities are supported by its large population base and accelerating urbanization, positioning it as a key player in the global LWAC market.
Key Player Analysis
- Cimpor
- Holcim
- Boral Limited
- CRH plc
- SCG
- Cemex
- Litagg Corporation
- HEIDELBERGCEMENT
- Lafarge
- Buzzi Unicem
- Italcementi
- Votorantim
- S. Concrete
- China Resources Cement
Competitive Analysis
In the global lightweight aggregate concrete market, leading players such as Cimpor, Holcim, Boral Limited, CRH plc, SCG, Cemex, Litagg Corporation, HEIDELBERGCEMENT, Lafarge, Buzzi Unicem, Italcementi, Votorantim, U.S. Concrete, and China Resources Cement are at the forefront, each employing distinctive strategies to enhance their market position. Their efforts range from pioneering sustainable and innovative concrete solutions to expanding their geographic footprint through strategic acquisitions and partnerships. These companies also focus on enhancing product performance and environmental sustainability, which are key factors in meeting the evolving demands of the construction industry. Their collective advancements in technology and strong focus on customer-centric solutions enable them to effectively compete and lead in this highly competitive market.
Recent Developments
- In January 2024, Holcim announced plans to spin off 100% of its North American operations, which could impact its lightweight aggregate concrete business in the region.
- In February 2024, CRH plc announced that it had reached an agreement to acquire an attractive portfolio of cement and readymixed concrete assets in Texas, USA for a total consideration of $2.1 billion.
- In February 2024, Heidelberg Materials, a subsidiary of Heidelberg Cement, announced that they have been awarded a $2 million grant from the US Department of Energy Industrial Efficiency and Decarbonization Office (IEDO) to develop a project regarding low-carbon non-ordinary Portland cements.
- In January 2023, Holcim acquired US aggregates business, which included 13 sand and aggregates quarries from Pioneer Landscape Centers.
- In May 2023, Cemex USA announced it has finalized an acquisition that secures new long-term aggregates reserves, expanding its aggregates footprint and further strengthening the company’s position in aggregate constrained markets.
Market Concentration & Characteristics
The global lightweight aggregate concrete market exhibits a moderate to high level of market concentration, with several key players dominating the industry. This market is characterized by a blend of global and regional players, where major companies like Holcim, Cemex, and HEIDELBERGCEMENT leverage extensive R&D capabilities and broad distribution networks to maintain their leadership positions. The market is also marked by a strong focus on sustainability and innovation, as companies continuously seek to develop lighter, more durable, and environmentally friendly concrete solutions to meet stringent global standards and evolving construction needs. Competitive strategies often include mergers and acquisitions, which allow larger companies to enhance their market reach and product portfolio. Meanwhile, regional players contribute to market diversity by offering specialized products adapted to local conditions and regulations, thus enhancing the overall competitive dynamics of the sector.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End-user, Density & Strength and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Increasing urbanization and infrastructural development will drive demand for lightweight aggregate concrete.
- Technological advancements will lead to the development of more durable and sustainable concrete solutions.
- The shift towards green building materials will significantly influence product innovation in the market.
- Expansion in emerging markets will be a key growth strategy for major players.
- Regulatory changes emphasizing energy efficiency and emission reductions will shape production techniques and material choices.
- Adoption of recycled materials in manufacturing processes will become more prevalent.
- Market participants will likely engage in strategic partnerships to enhance supply chain efficiencies and expand geographic reach.
- Continuous investment in R&D will be crucial for maintaining competitive advantages and meeting regulatory standards.
- The rise of modular construction and prefabrication techniques will boost the utilization of lightweight aggregate concrete.
- Consumer preferences for lightweight and high-strength materials will guide product development and marketing strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Energy Efficiency and Sustainability
Lightweight aggregate concrete (LWAC) offers superior thermal insulation and lower embodied energy, aligning with global trends toward sustainable construction and energy-efficient buildings. This makes LWAC attractive for green building initiatives and regulatory compliance.
Urbanization and Infrastructure Development
Rapid urbanization, especially in Asia-Pacific, is driving large-scale residential, commercial, and infrastructure projects that require lightweight, high-strength materials, boosting demand for LWAC in high-rise and complex structures.
Seismic and Fire Resistance
LWAC's reduced weight improves seismic performance and its inherent fire resistance meets stricter safety regulations, making it a preferred material in earthquake-prone and safety-conscious regions.
Technological Advancements and Material Innovation
Ongoing R&D is leading to new LWAC formulations with enhanced strength, durability, and environmental performance, expanding its applications and making it more competitive against traditional and alternative materials.
Growth in Prefabricated and Modular Construction
The rise of prefabrication and modular building methods benefits from LWAC's lightweight and easy-to-handle properties, enabling faster construction timelines and improved quality control.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Lightweight Aggregate Concrete Market?
What factors are driving the growth of the Global Lightweight Aggregate Concrete Market?
What are the key segments within the Global Lightweight Aggregate Concrete Market?
What are some challenges faced by the Global Lightweight Aggregate Concrete Market?
Who are the major players in the Global Lightweight Aggregate Concrete Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Expanded Clay
- 1.2.2 Expanded Perlite
- 1.2.3 Expanded Glass
- 1.2.4 Expanded Shale
- 1.2.5 Others
- 1.3 By End-user
- 1.3.1 Industrial Use
- 1.3.2 Infrastructure
- 1.3.3 Civil Use
- 1.3.4 Commercial
- 1.3.5 Others
- 1.4 By Application
- 1.4.1 Structural
- 1.4.2 Non-Structural
- 1.5 By Density & Strength
- 1.5.1 Low Density Concrete
- 1.5.2 Medium Density Concrete
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 48,762.39 million → 2032: USD 74,359.51 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Lightweight Aggregate Concrete Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Lightweight Aggregate Concrete Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Lightweight Aggregate Concrete Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Lightweight Aggregate Concrete Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Lightweight Aggregate Concrete Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Lightweight Aggregate Concrete Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Lightweight Aggregate Concrete Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Lightweight Aggregate Concrete Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 48,762.39 million → 2032: USD 74,359.51 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Lightweight Aggregate Concrete Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Expanded Clay
- 12.3.7.2 Expanded Perlite
- 12.3.7.3 Expanded Glass
- 12.3.7.4 Expanded Shale
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-user - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Industrial Use
- 12.4.7.2 Infrastructure
- 12.4.7.3 Civil Use
- 12.4.7.4 Commercial
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Structural
- 12.5.7.2 Non-Structural
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Density & Strength - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Low Density Concrete
- 12.6.7.2 Medium Density Concrete
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Lightweight Aggregate Concrete End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Lightweight Aggregate Concrete Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Lightweight Aggregate Concrete Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Lightweight Aggregate Concrete Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Holcim
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Boral Limited
- 18.4 CRH plc
- 18.5 HEIDELBERGCEMENT
- 18.6 Cemex
- 18.7 Lafarge
- 18.8 Buzzi Unicem
- 18.9 Votorantim
- 18.10 China Resources Cement
- 18.11 SCG
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

