
One prepaid pass now unlocks dozens of mountains
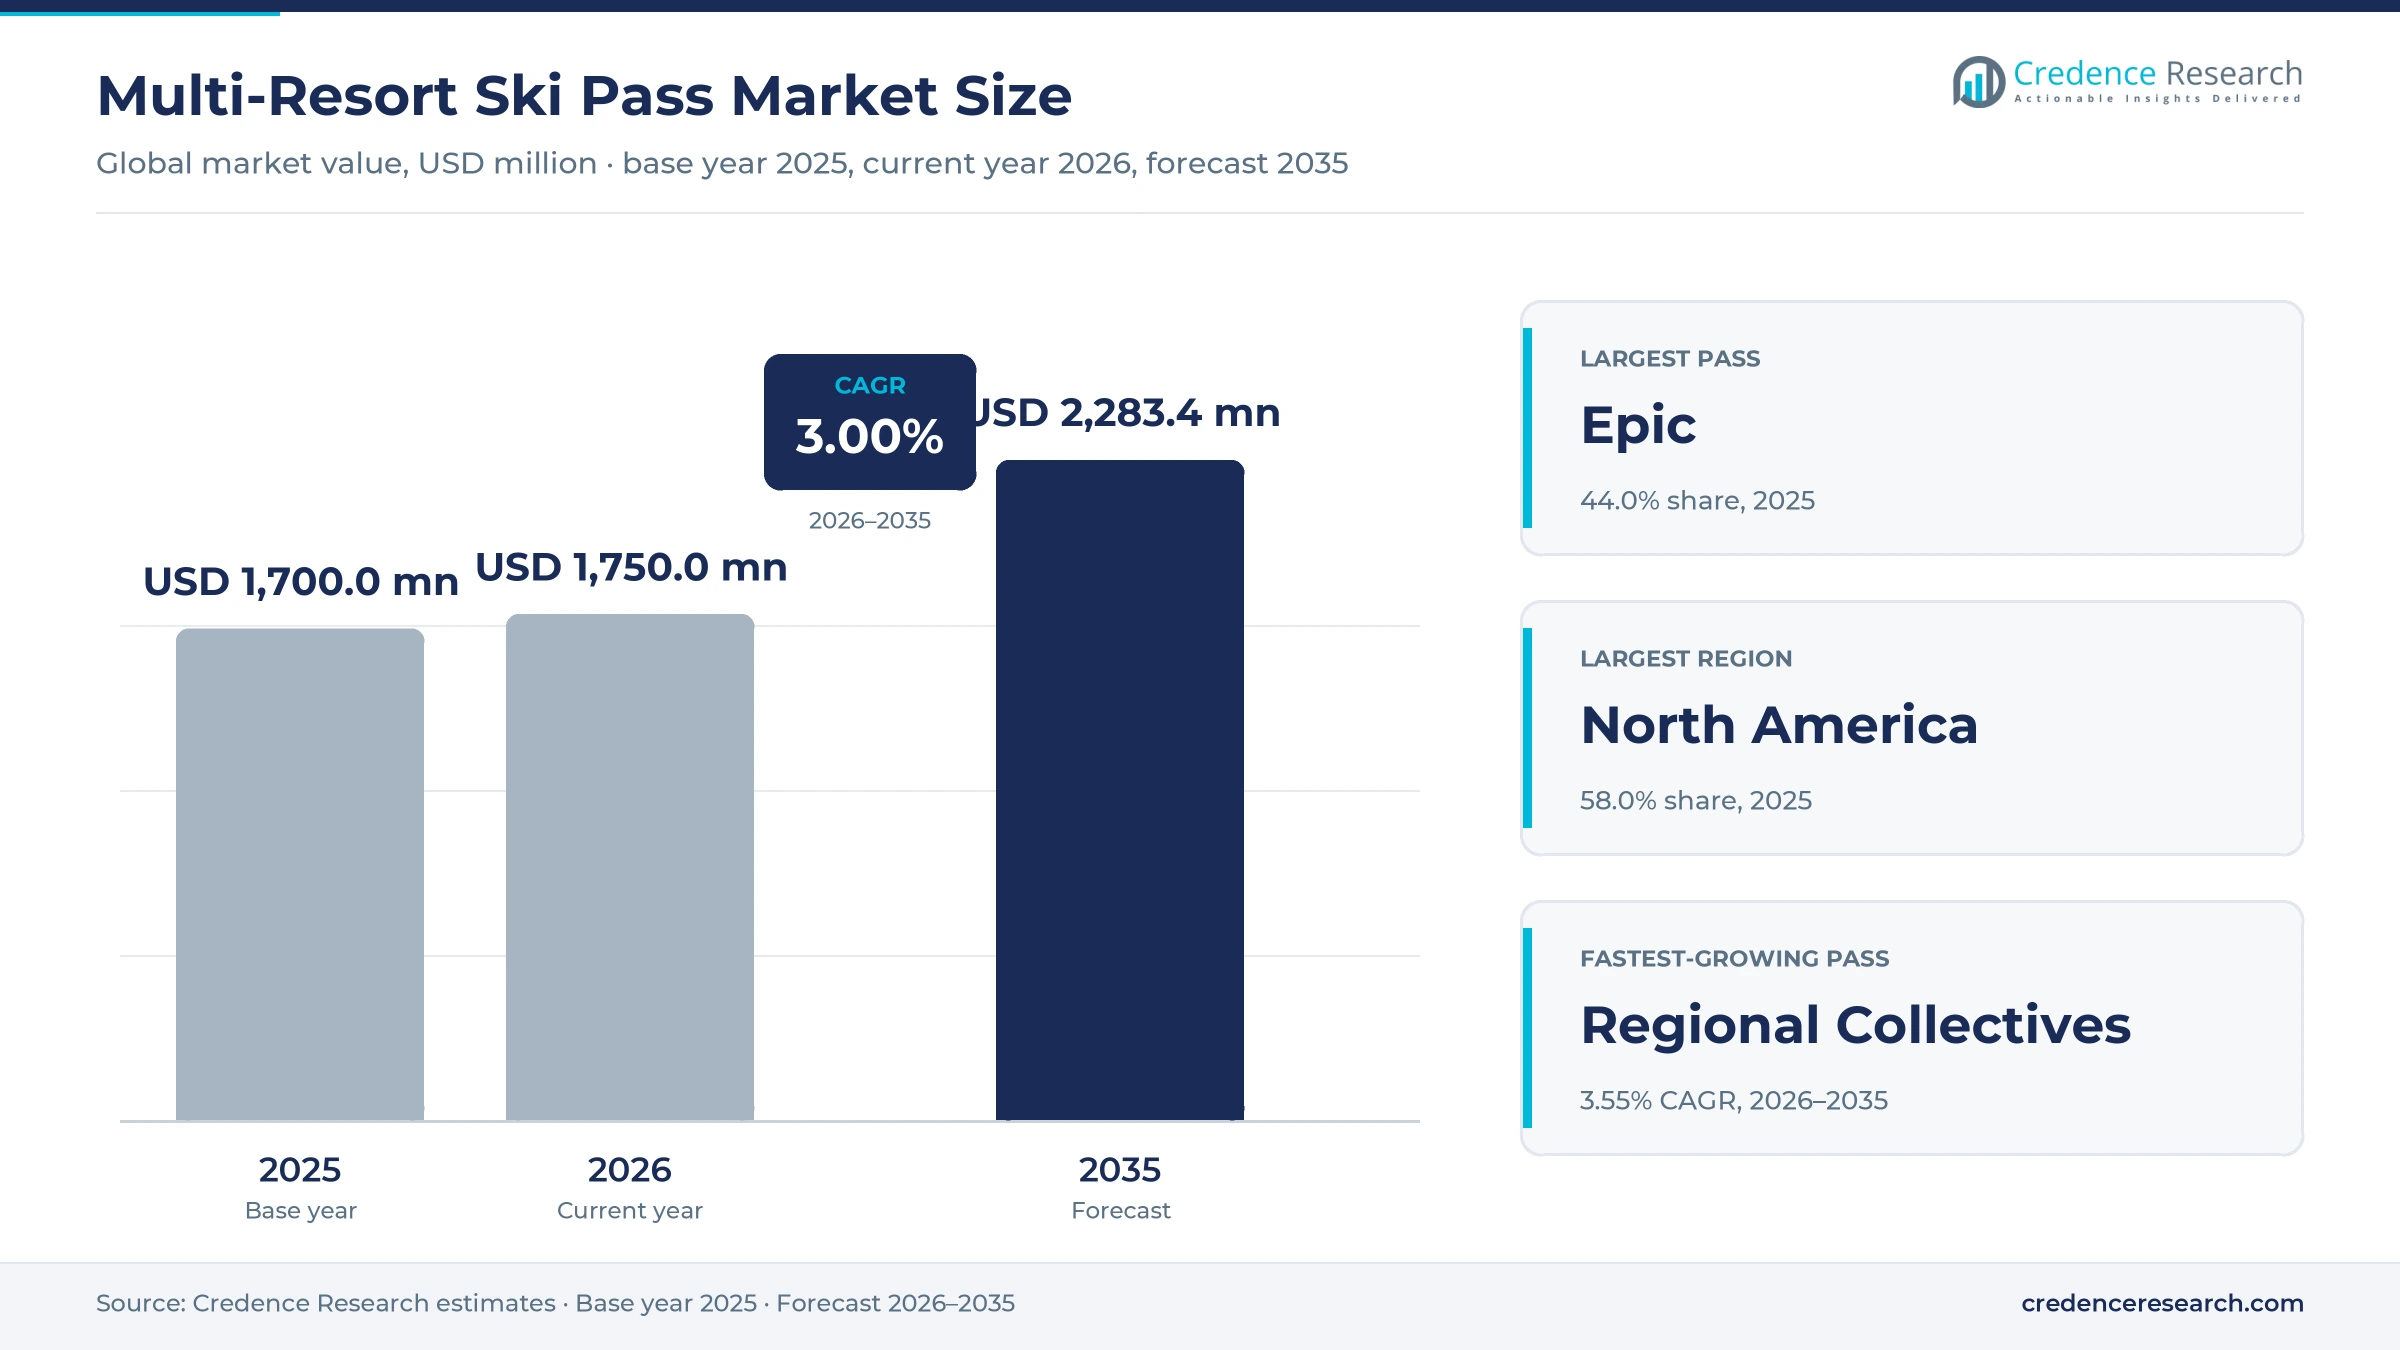
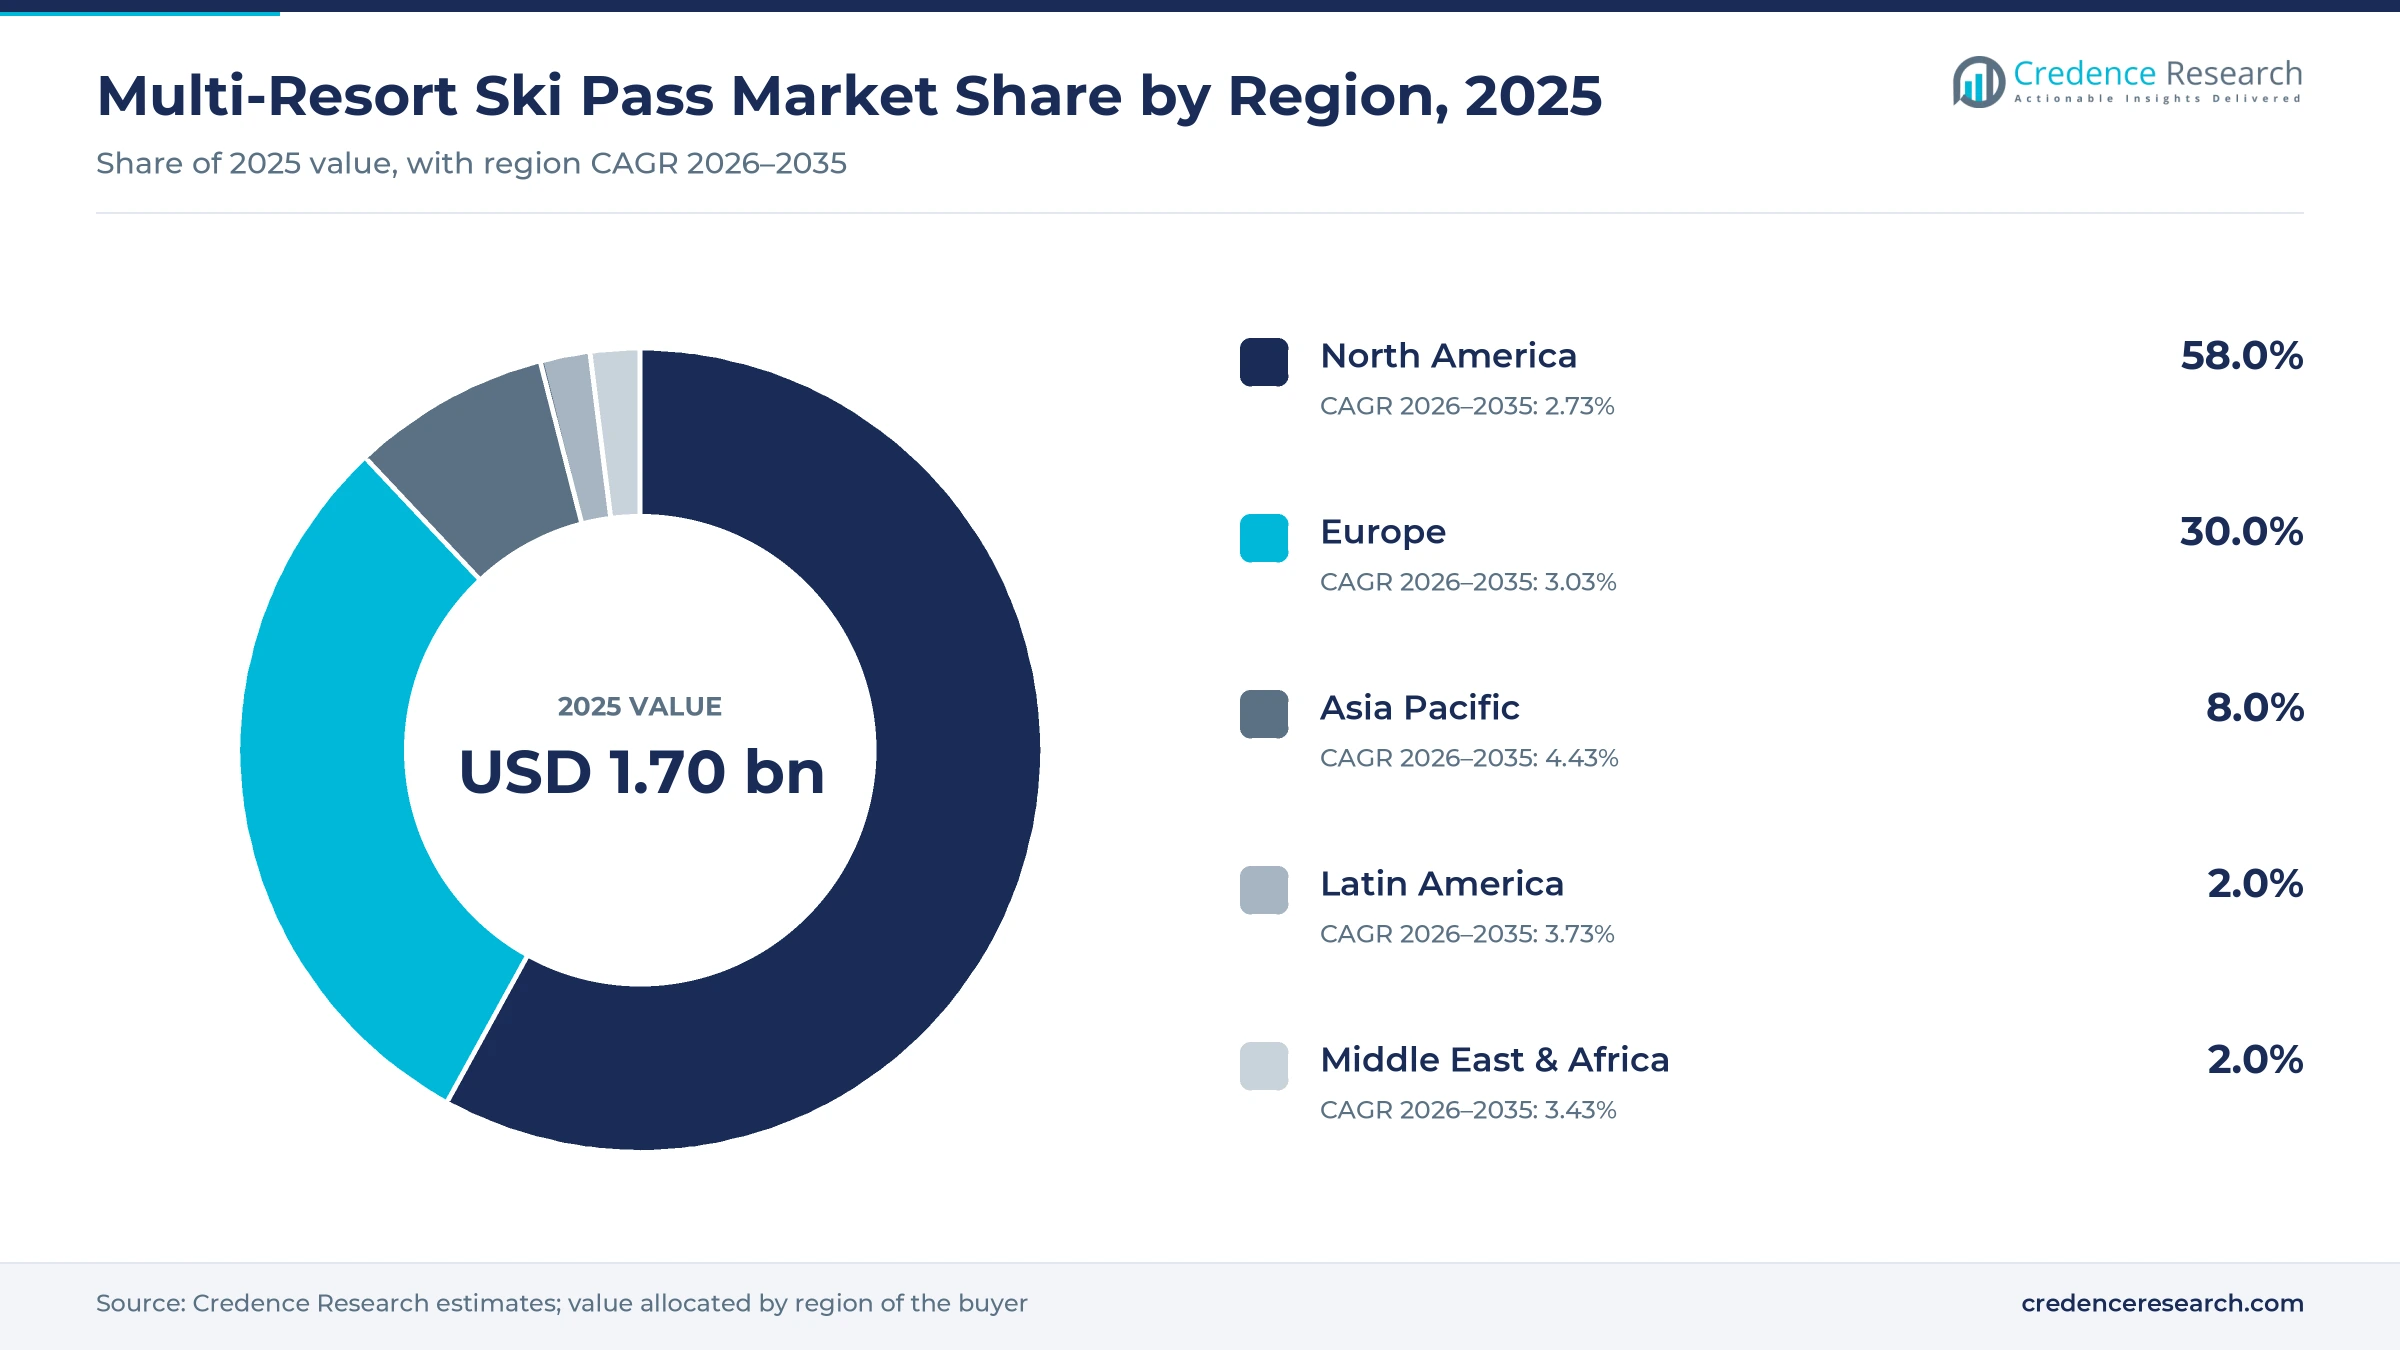
The global multi-resort ski pass market was valued at USD 1.70 billion in 2025 and is projected to increase from USD 1.75 billion in 2026 to USD 2.28 billion by 2035, registering a CAGR of 3.00% during 2026–2035. Demand comes from destination skiers and regional day-trippers who prefer one prepaid product for several mountains, and from operators that want cash before the snow falls. North America held the largest regional share, 58.0% in 2025, because Epic and Ikon started there and U.S. ski areas logged 61.5 million skier visits in 2024-25. Asia Pacific is the fastest-growing region at 4.43% a year, as Japan welcomed a record 42.7 million foreign visitors in 2025 and pass groups keep adding Japanese partner resorts. On the commercial side, lower-priced collectives such as Indy and the Swiss Magic Pass are widening their networks, while Ikon added a refundable option for 2026-27 after weak snow cut visits during the 2025/26 winter.
What does a buyer get with a multi-resort ski pass?
The market covers prepaid passes that give access to two or more independently branded ski resorts, sold as unlimited season passes, limited-day passes with blackout dates and day-count passes. Buyers purchase them online from pass operators, mostly between March and early December, often with renewal pricing and payment plans.
The scope excludes single-resort season passes, window lift tickets, lessons, rentals, lodging and food sold separately, even when holders receive discounts on them. The value chain runs from resort owners and partner resorts that agree on access days, through pass operators that market and price the products, to holders who plan trips around the network.
Multi-Resort Ski Pass Market Insights
- The market grows from USD 1.70 billion in 2025 to USD 2.28 billion by 2035 at a 3.00% CAGR, as operators widen networks and sell passes months before the season.
- North America held 58.0% of 2025 value, as season passes accounted for 49% of the 61.5 million U.S. skier visits in 2024-25.
- Epic led with 44.0% of 2025 value, because about 2.3 million guests committed to Vail Resorts advance products for 2025/26.
- Ikon reached 80 destinations on five continents for 2026-27 after adding Madarao in Japan and two Chinese resorts on Sept. 10, 2026.
- The Swiss Magic Pass sold a record 321,400 passes for 2025/26, up 63%, showing the pull of lower-priced regional collectives.
Epic leads while regional collectives grow fastest
Why does Epic lead multi-resort pass spending?
Based on pass, the market is categorized into Epic, Ikon and regional collectives. Epic led with 44.0% of 2025 value because Vail Resorts reported about 2.3 million guests committed to its advance products for 2025/26 across 42 owned resorts in North America, Australia and Europe, according to its December 2025 filing. Ikon follows with 80 destinations on five continents for 2026-27, as Alterra announced on Sept. 10, 2026. Regional Collectives grow fastest at 3.55% a year, as the Swiss Magic Pass sold a record 321,400 passes for 2025/26, up 63%, and Indy reached 271 resorts in August 2025.
How do adults, families and students buy passes?
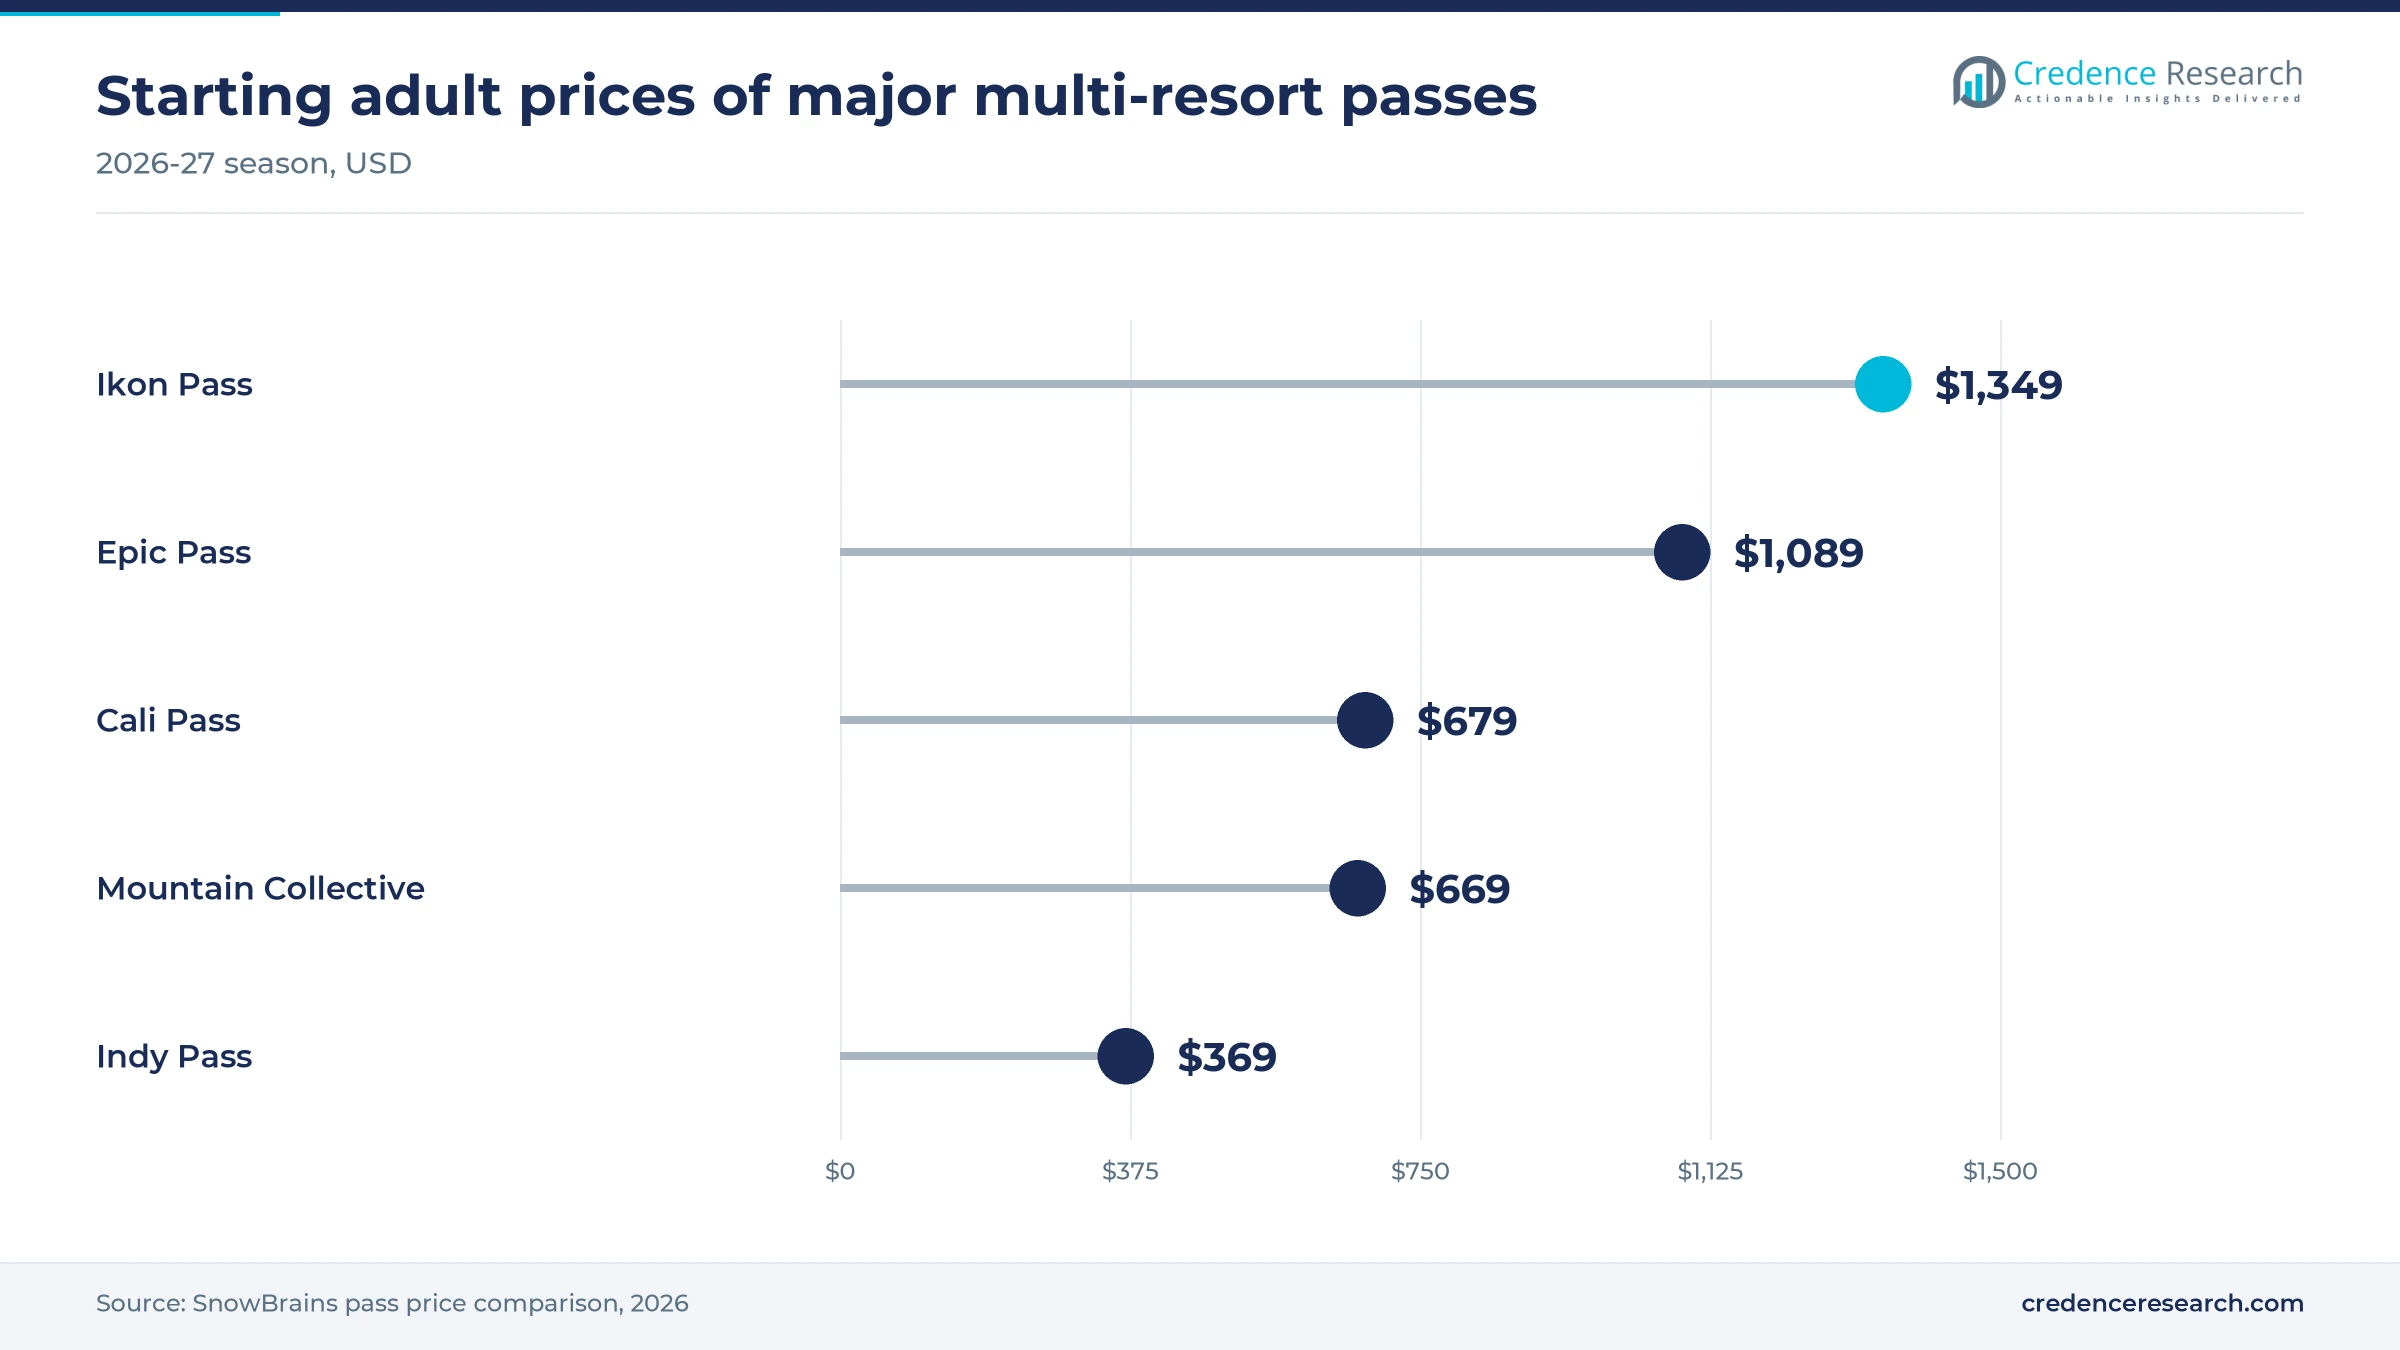
Based on customer, the market is categorized into adults, families and students. Adults led with 60.0% of 2025 value because the full adult Ikon Pass starts at $1,399 for 2026-27, according to the Steamboat Pilot, and the Epic Pass at an early-bird $1,089, according to SnowBrains, which makes the adult pass the largest purchase in most households. Families gain from child pricing such as the $585 Epic child pass and the expanded Ikon child discounts announced in March 2026. Students grow fastest at 3.90% a year, as Vail Resorts said in June 2026 that its new young adult passes were solidly outperforming other age groups.
Why do unlimited passes hold the largest share?
Based on access type, the market is categorized into unlimited passes, limited-day passes and day-count passes. Unlimited Passes led with 52.0% of 2025 value because frequent skiers in the Rockies and the Alps buy one product for the whole season, and Vail Resorts cited relative strength in unlimited passes in its Sept. 28, 2026 results. Limited-day products such as the Epic Local Pass, which launched at $809 for 2026/27, trade blackout dates for lower prices. Unlimited Passes also grow fastest at 3.21% a year, as Vail Resorts said in June 2026 that unlimited passes were outperforming its frequency products.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Pass | Epic | 44.0% | Regional Collectives | 3.55% |
| By Customer | Adults | 60.0% | Students | 3.90% |
| By Access Type | Unlimited Passes | 52.0% | Unlimited Passes | 3.21% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Wider networks and early cash keep passes selling
Operators widen reciprocal pass networks
Destination operators keep adding partner resorts so that one pass covers more trips, which raises the value buyers see in a single purchase. Indy Pass added 43 resorts for 2025/26, bringing its coalition to 271 resorts in 14 countries, according to its Aug. 28, 2025 announcement. Ikon added Courmayeur, Cervinia, La Thuile, Monterosa and Pila in the Aosta Valley of Italy in August 2025, as PlanetSKI reported. The Epic Pass now reaches 26 European resorts, including Les 3 Vallées and Ski Arlberg, according to OnTheSnow. In the Credence Research model this adds about 1.11 percentage points to annual growth to 2035. As a result, wider networks keep Epic and Ikon holders renewing even when they change destinations from year to year.
Preseason pass sales lock in early cash
Multi-resort memberships move a large part of lift spending into spring and fall, before snow falls, which gives operators cash for lifts, snowmaking and staff. Vail Resorts said in December 2025 that about 2.3 million guests had committed in advance and that these products would account for about 74% of its skier visits, excluding complimentary visits. Across the United States, season passes made up 49% of 2024-25 skier visits, according to the National Ski Areas Association. Indy capped public sales in early March 2025 after a record renewal period, as SAM Magazine reported. In the Credence Research model this adds about 0.90 percentage points to annual growth to 2035. Because cash arrives early, operators keep pricing passes to sell well before December.
Loyalty perks and tiers keep renewals high
Tiered prices and renewal benefits reward holders who return each year, which lowers churn and smooths volumes when snow is poor. Ikon introduced Renewal Rewards for 2026-27, letting returning holders choose monthly mountain credits or travel and gear benefits, according to TownLift. Epic early buyers for 2026-27 receive 10 Buddy Tickets and six Ski With a Friend tickets, as SnowBrains reported. Indy also set its flagship Indy+ Pass at $399 for 2026-27 and opened renewals at its lowest guaranteed price on Feb. 25, 2026, according to Business Wire. In the Credence Research model this adds about 0.54 percentage points to annual growth to 2035. In turn, renewal benefits support Unlimited Passes, which held 52.0% of 2025 value.
Asian ski travel pulls passes toward Japan
Japanese powder resorts are drawing more international skiers, and pass groups are adding Asian partners to capture those trips. Japan received a record 42.7 million foreign visitors in 2025, the first year above 40 million, according to figures from Tourism Minister Yasushi Kaneko reported by AGBrief. Ikon added seven Japanese resorts, including Shiga Kogen, Furano and Zao Onsen, for winter 2025/26, raising its Asian roster to 11 destinations, according to its Oct. 21, 2025 release. Epic partners include the Hakuba Valley resorts and Rusutsu, as OnTheSnow lists. Ikon then added Madarao in Japan and two Chinese resorts on Sept. 10, 2026. As a result, Asia Pacific posts the fastest regional growth in the forecast.
Budget collectives and app passes reshape buying
Budget regional passes rise against mega passes
Lower-priced regional collectives are winning skiers who find full mega passes too expensive for the days they ski. The Magic Pass sold a record 321,400 passes for 2025/26, up 63%, according to Swissinfo. Its network spans nearly 100 ski areas in Switzerland, France and Italy, SAM Magazine reported in September 2025. Indy starts at $369 for 2026-27, compared with $1,399 for the Ikon Pass, as the Steamboat Pilot reported, and an early-bird $1,089 for the Epic Pass, as SnowBrains reported. Snow Partners also sells the $199 Snow Triple Play across 15 ski areas in the U.S. Northeast and Eastern Canada. This shift explains why Regional Collectives are the fastest-growing pass group in the forecast.
Phone-based passes shift buying into apps
Mobile passes are moving purchase, entry and on-mountain spending into operator apps, which gives pass groups more data on each holder. Vail Resorts launched hands-free Mobile Pass and Mobile Lift Ticket access in the My Epic app for 2023/24, using low-energy Bluetooth so a phone can stay in a pocket, according to its March 2, 2023 release. Whistler Blackcomb followed with mobile passes for 2024/25, as Vail Resorts announced on Feb. 27, 2024. Ikon removed lift reservations at the four Aspen Snowmass mountains for 2026-27, according to TownLift, which simplifies access for holders. In turn, app data helps operators target day-count and add-on offers to holders who ski fewer days.
Beginner and young adult passes open new buyers
Entry-level and age-based products give operators a way to recruit skiers who later buy full passes. Indy launched its $189 Learn to Turn Pass, which bundles three lift tickets, lessons and rentals, at 30 resorts in August 2025, according to Indy Pass. More than 40 resorts took part in the 2025/26 Learn to Turn product, Indy said in February 2026. Ikon's Squad Pack lets five skiers aged 23 to 28 buy Base Passes at $750 each, about 20% off, as the Steamboat Pilot reported. Epic also prices ages 13 to 30 about 20% below the adult rate. As a result, Students grow fastest at 3.90% a year.
Southern Hemisphere passes open a second winter
Australian and South American resorts let pass groups sell a second winter to the same holders, which opens sales in the northern summer. Epic Australia Pass units rose about 26% through May 27, 2026, according to Vail Resorts' June 8, 2026 filing. The 2027 Epic Australia Pass launched on Aug. 12, 2026 at AUD 1,099 for adults, with unlimited days at Perisher, Falls Creek and Hotham and 2027/28 access to more than 85 resorts, as Mountainwatch reported. Indy added Corralco in Chile, its first Southern Hemisphere resort, for summer 2025, according to Indy Pass. In turn, these products help Latin America grow at 3.73% a year.
Snow, prices and staffing test pass loyalty
Poor snow years cut visits and renewals
Weak snow seasons reduce visits and make holders less likely to renew the following spring. Vail Resorts reported that fiscal 2026 skier visits fell 13.4%, with Rockies snowfall at or near historic lows and Australian snowfall about 57% below the 10-year average, according to its Sept. 28, 2026 filing. Its 2026/27 pass units were down about 12% through Sept. 18, 2026. Operators answer with refund options, such as the Ikon full refund for passes left unused by Jan. 15, 2027.
Rising pass prices test buyer tolerance
Annual price increases push some skiers toward cheaper regional passes or single-day tickets. Vail Resorts raised 2025/26 pass prices about 7%, and units fell about 2% through Dec. 5, 2025, according to its December 2025 filing. Alterra raised the 2026-27 Ikon Pass to $1,399, $70 or about 5% more than a year earlier, as the Steamboat Pilot reported. Because buyers compare totals across a family, each increase weighs on renewals, so operators now lean on young adult discounts and payment plans to hold their volumes.
Staffing disputes and crowding erode pass value
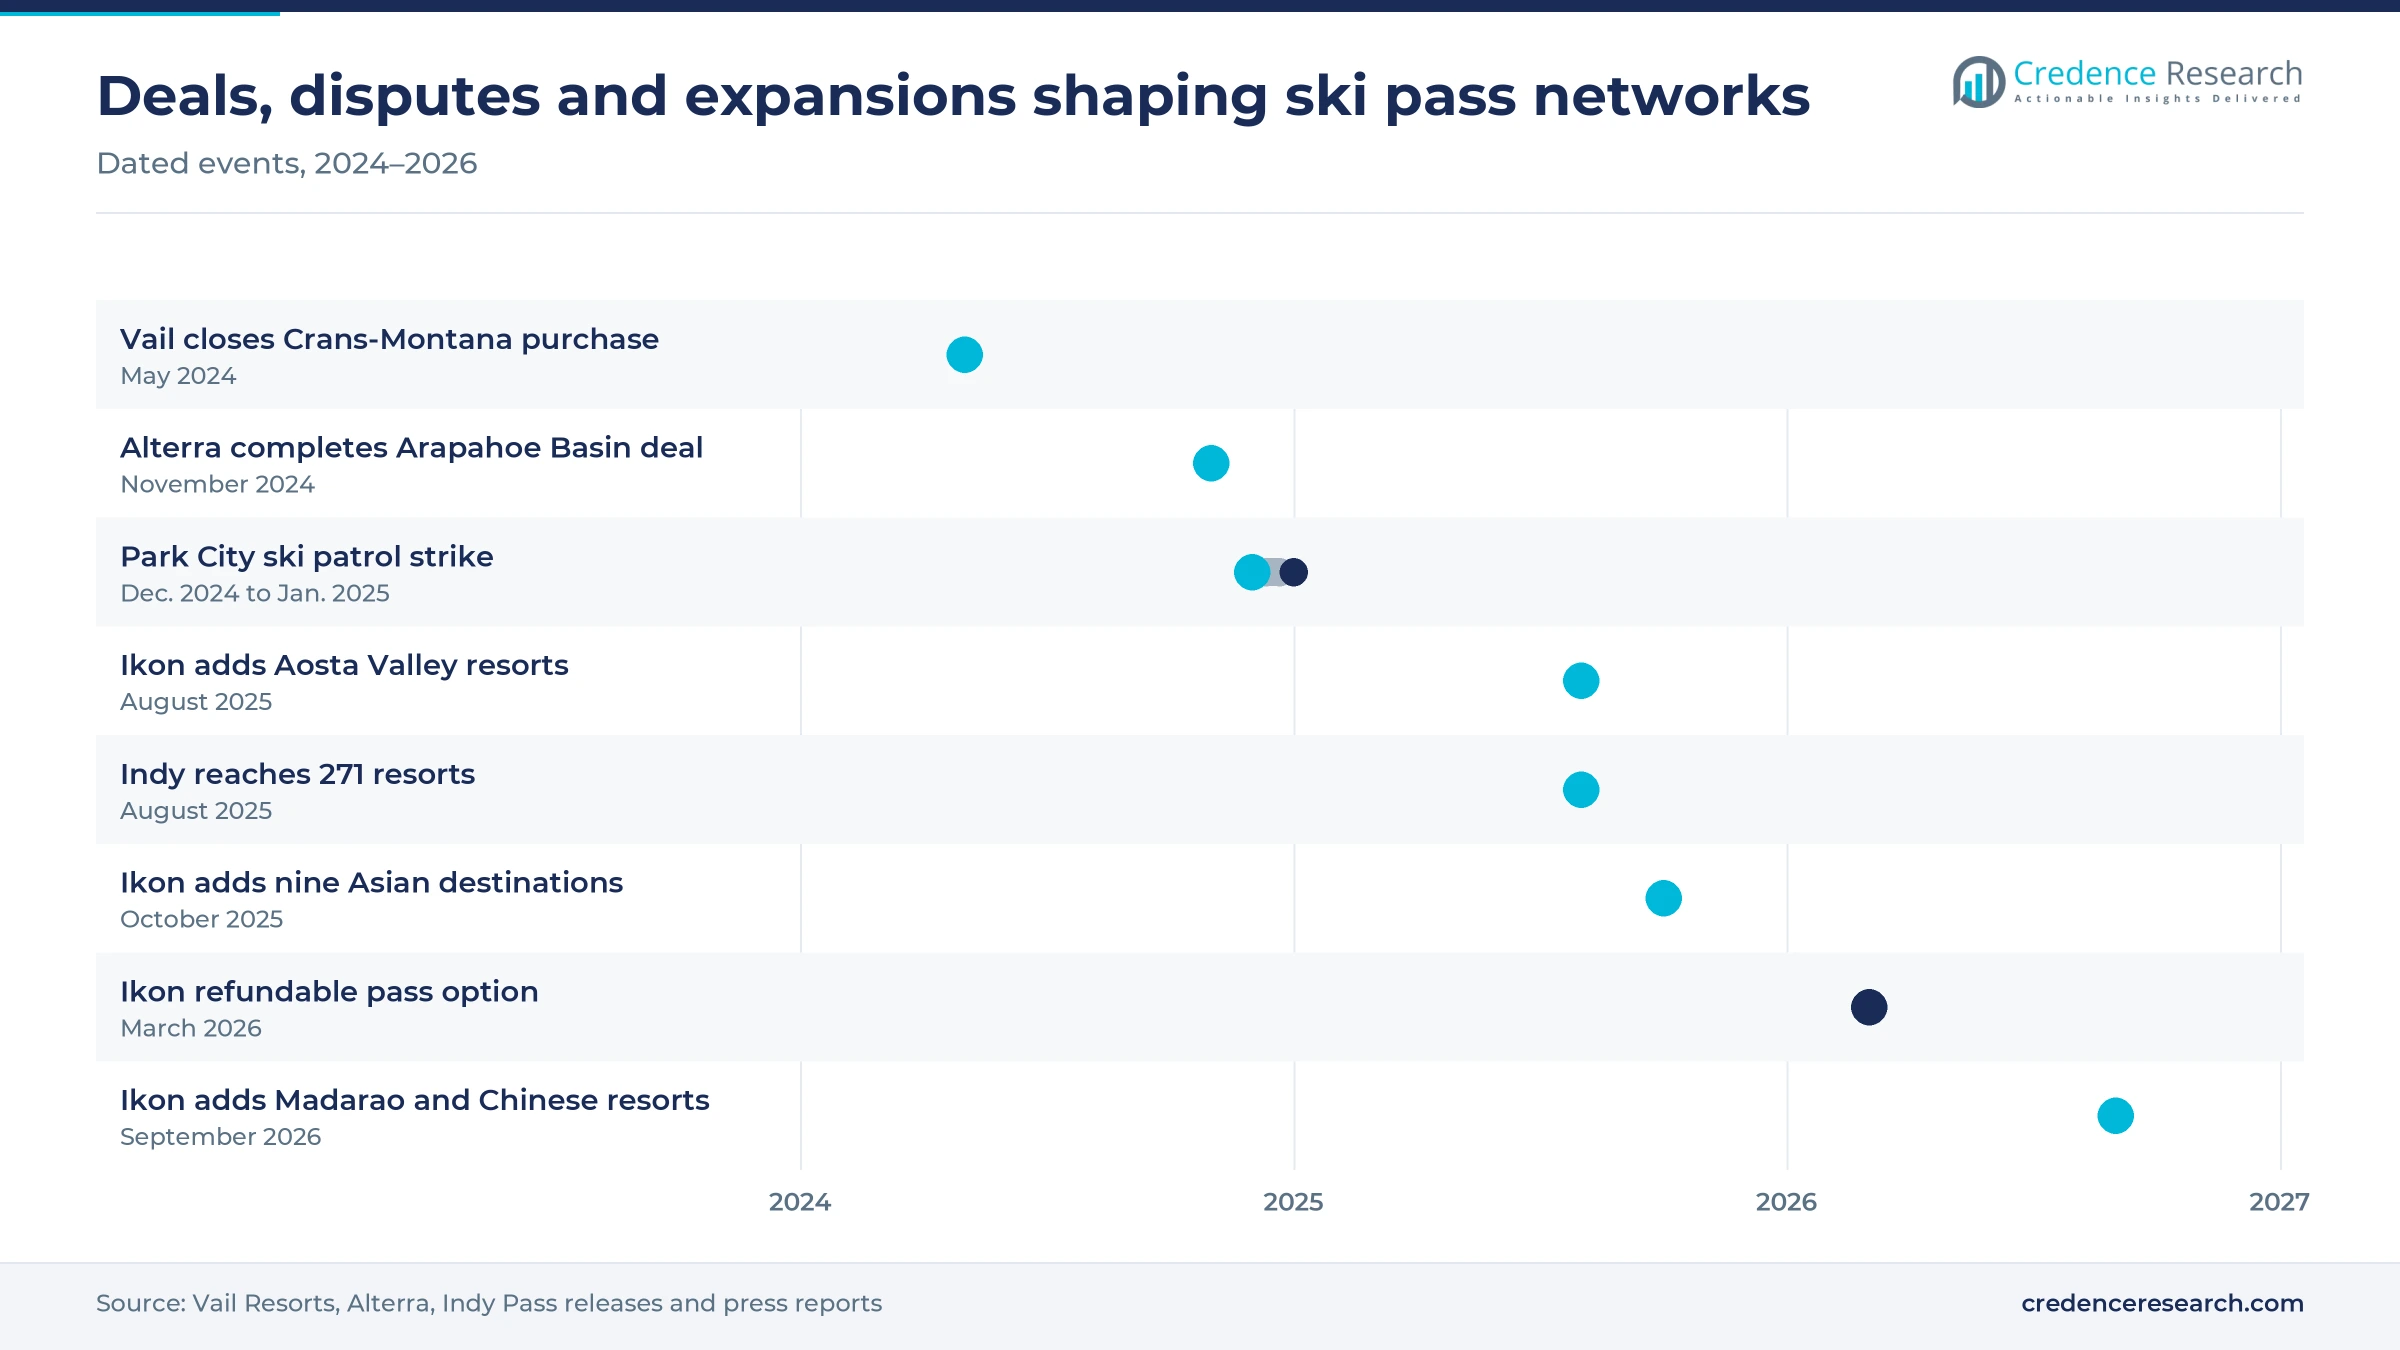
Labor disputes and crowded holiday periods weaken the value holders receive from an unlimited pass. Park City Mountain ski patrollers struck for 12 days from Dec. 27, 2024, leaving little more than a quarter of the terrain open during the holiday rush, according to The Colorado Sun. Vail Resorts then offered Park City pass holders a 50% credit per day skied in that window toward the next season's pass, KPCW reported in January 2025. Such credits protect loyalty but reduce the yield from each pass sold.
Capacity caps limit how far collectives can grow
Independent collectives limit sales to protect partner resorts from crowding, which caps how many passes they can sell. Indy sold its 2025/26 passes in limited quantities while supplies lasted when sales reopened on Aug. 28, 2025, according to Indy Pass. For 2026-27, its public sale began March 1, 2026 only after renewals and waitlist purchases, Business Wire reported. As a result, collective growth depends on adding resorts rather than on selling more passes at each one, which slows gains at popular partners.
North America leads as Asia Pacific grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 0.99 | 58.0% | 2.73% |
| Europe | 0.51 | 30.0% | 3.03% |
| Asia Pacific | 0.14 | 8.0% | 4.43% |
| Latin America | 0.03 | 2.0% | 3.73% |
| Middle East & Africa | 0.03 | 2.0% | 3.43% |
North America keeps the largest pass base
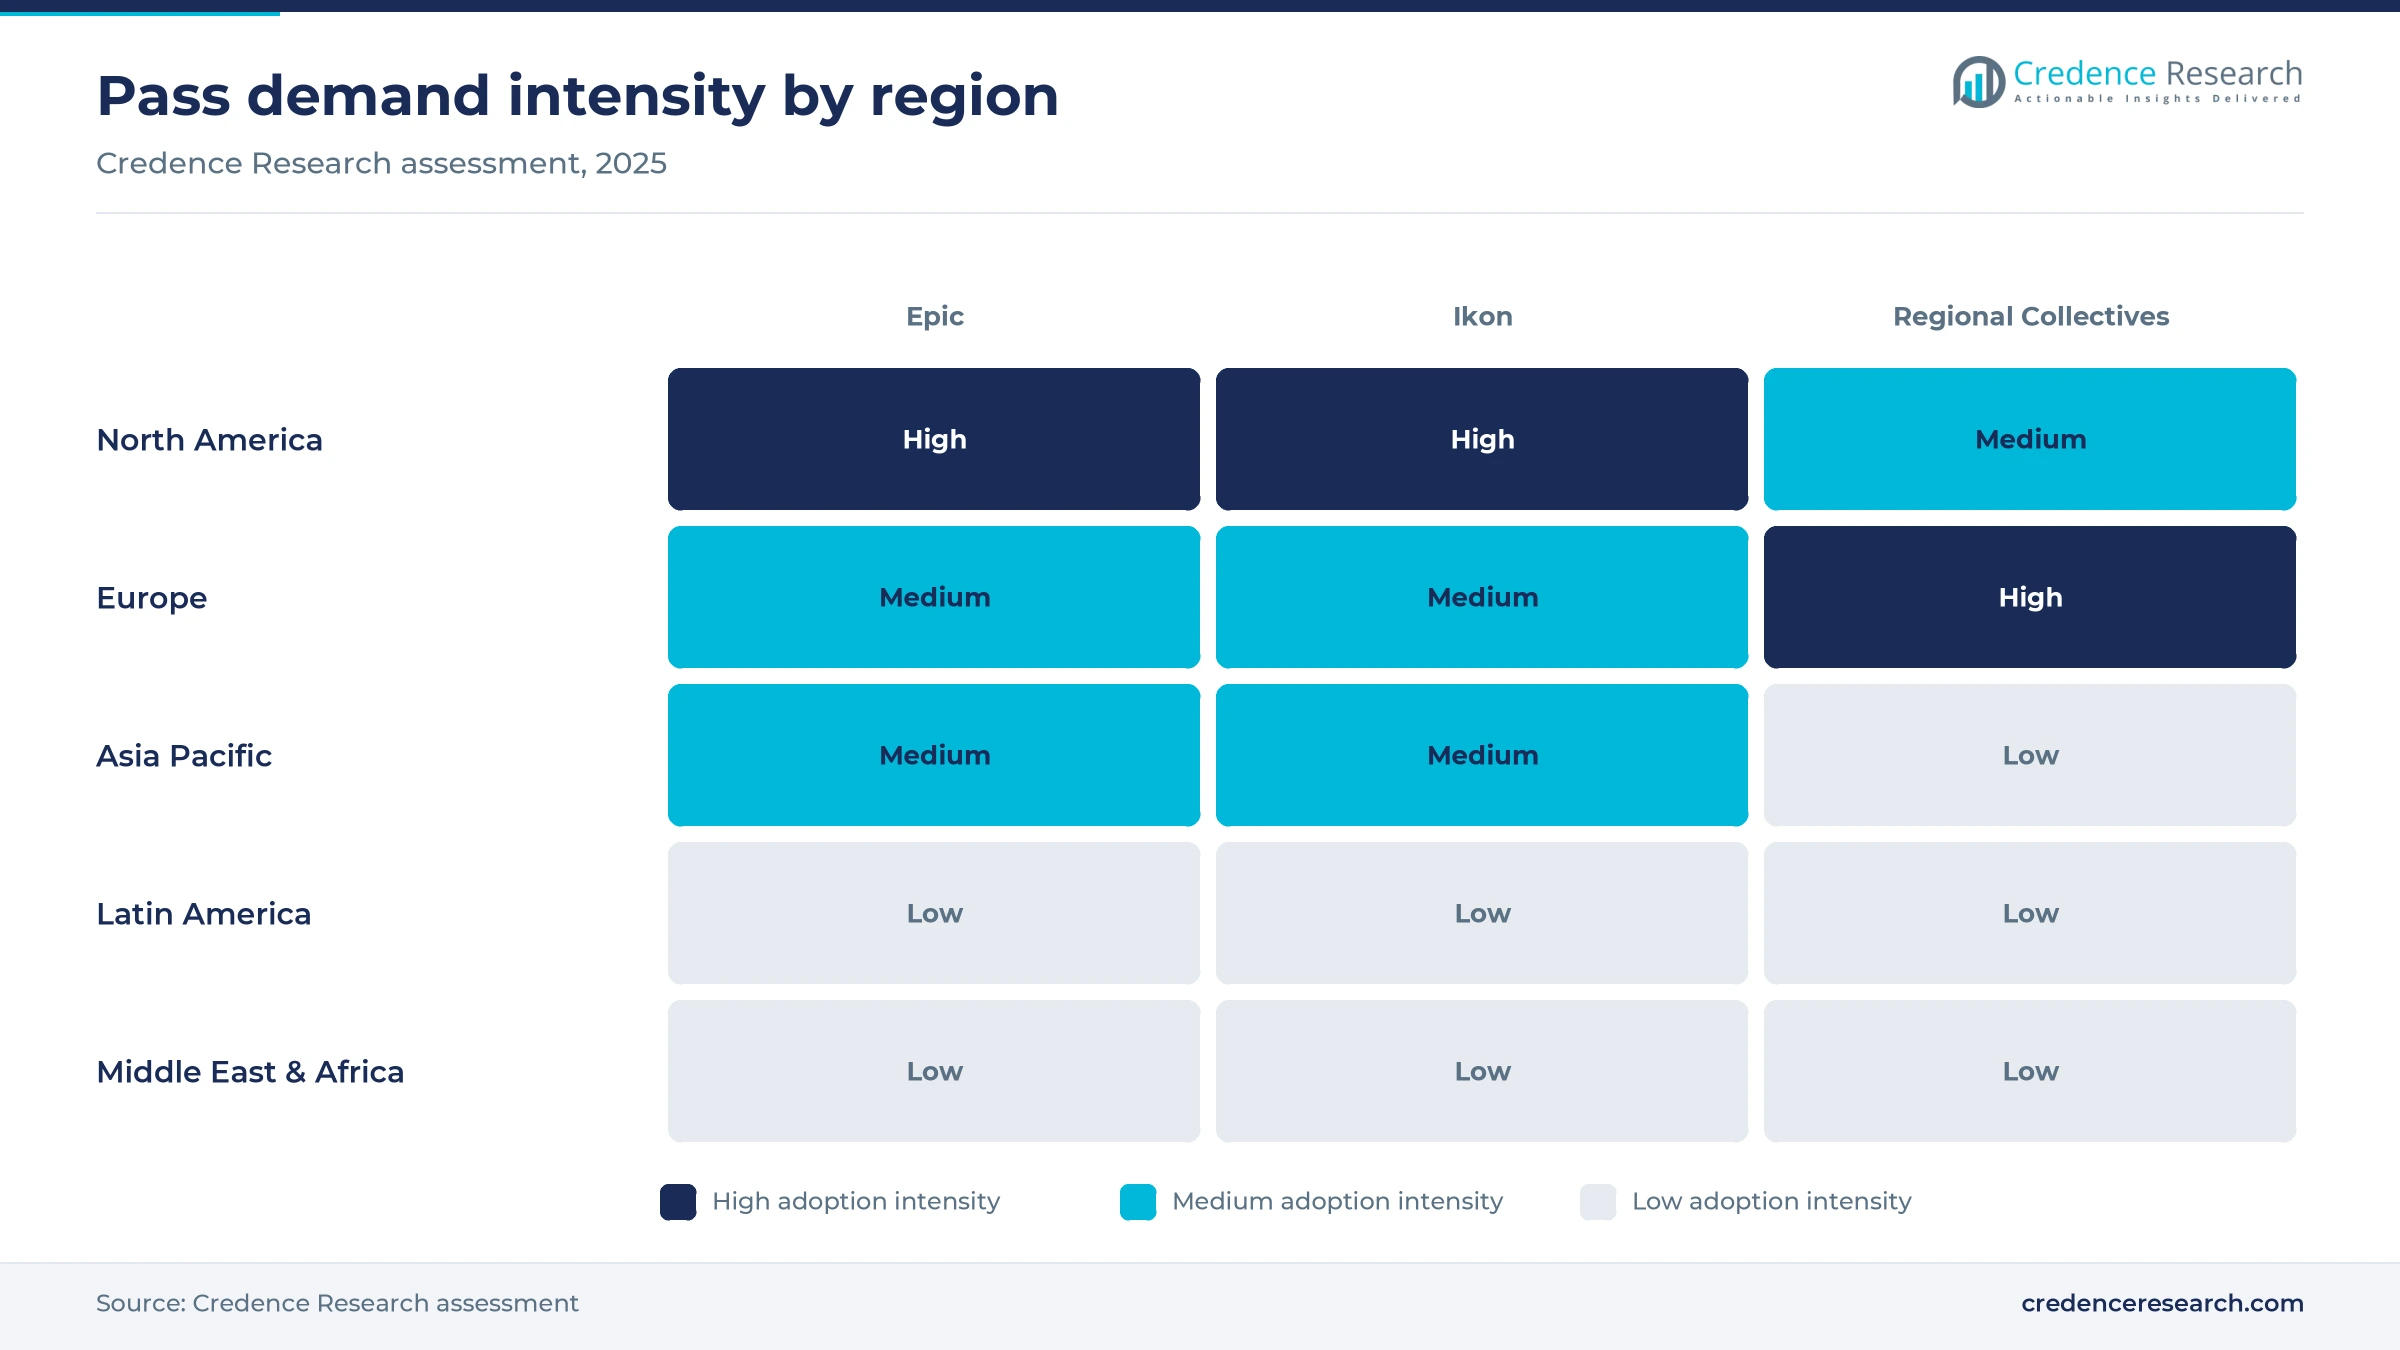
North America held 58.0% of 2025 value and grows at 2.73% a year, as Epic and Ikon both started in the Rockies and still sell most passes there. U.S. ski areas recorded 61.5 million skier visits in 2024-25, the second-best season on record, across 492 operating areas, and the Rocky Mountain region took 42.9% of visits, according to the National Ski Areas Association. Alterra completed its purchase of Arapahoe Basin in November 2024, and the area became unlimited on the Ikon Base Pass for 2026-27. Growth is slower because the holder base is already large.
Europe mixes mega passes with local collectives
Europe held 30.0% of 2025 value and grows at 3.03% a year, supported by both international mega passes and local collectives. Vail Resorts closed its purchase of Crans-Montana in Switzerland in May 2024, giving Epic Pass holders unlimited access there as at Andermatt-Sedrun. Ikon covers Chamonix, Zermatt, St. Moritz, Kitzbühel and Dolomiti Superski, while the Magic Pass adds Swiss, French and Italian areas each season. The full Ikon Pass gives 7 combined days across the five Aosta Valley resorts, which supports demand from Italian and French skiers. Indy added Les 7 Laux and Valmorel in France and Levi in Finland for 2026-27, according to Business Wire.
Asia Pacific grows fastest on Japan and Australia
Asia Pacific held 8.0% of 2025 value and grows fastest at 4.43% a year, led by Japan and Australia. Ikon listed 11 Asian destinations after its October 2025 expansion, and Epic partners with the Hakuba Valley resorts and Rusutsu in Japan. In Australia, Vail Resorts owns Perisher, Falls Creek and Hotham, and Epic Australia Pass units rose about 26% through May 2026. However, Australian snowfall about 57% below the 10-year average in mid-2026 shows how weather can slow the region in a single season.
Latin America builds on Chilean summer skiing
Latin America held 2.0% of 2025 value and grows at 3.73% a year from a small base in the Chilean and Argentine Andes. Indy added Corralco in Chile as its first Southern Hemisphere resort, open to its holders from June 2025. Valle Nevado, near Santiago, opened its 2025 season on June 13 as the first Chilean resort to start that winter, according to Snow Industry News. Those dates let North American holders ski during their own summer, which is the main appeal of pass access in the region.
Middle East & Africa relies on outbound skiers
Middle East & Africa held 2.0% of 2025 value and grows at 3.43% a year from a small base, because the region has few lift-served resorts of its own, and its largest planned venue slipped when Saudi Arabia and the Olympic Council of Asia agreed on Jan. 24, 2026 to postpone the Asian Winter Games at Trojena. The council then named Almaty as the 2029 host on Feb. 5, 2026, according to Reuters.
Resort deals and Asian partners expand access in 2024–2026
| Development | Status and market relevance |
|---|---|
| In May 2024, Vail Resorts closed its purchase of Crans-Montana Mountain Resort in Switzerland, its second owned Swiss resort. | Completed, unlimited Epic Pass access from 2024/25 |
| In November 2024, Alterra Mountain Company completed its purchase of Arapahoe Basin in Colorado. | Completed, unlimited on the Ikon Base Pass for 2026-27 |
| In August 2025, Indy Pass added 43 resorts and reopened sales with a 271-resort coalition in 14 countries. | Live, sales limited while supplies last |
| In October 2025, Ikon Pass added nine Asian destinations in Japan, China and South Korea for winter 2025/26. | Live, 11 Asian destinations on the pass |
| In September 2026, Ikon Pass added Madarao in Japan plus Beidahu and Lake Songhua in China for winter 2026/27. | Announced, 80 destinations across five continents |
Mobile passes, refunds and bundles change the product
- Mobile passes in the My Epic app use low-energy Bluetooth, so holders pass lift gates with the phone in a pocket.
- Refundable pass options from Ikon return the full price for a 2026-27 pass left unused by Jan. 15, 2027, or half after one use.
- Installment plans such as the three-payment, no-interest Indy plan spread the cost of a pass across the sales season.
- Bundled beginner products like the Indy Learn to Turn Pass combine three lift tickets, lessons and rentals for $189.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Network breadth and price tiers decide who wins
Competition turns on network breadth, price tiers and the share of days that holders can use without restrictions. Vail Resorts sells Epic passes built around 42 owned resorts, which lets it control lift capacity, pricing and on-mountain spending. Alterra Mountain Company runs Ikon as a mix of owned resorts and partners, with 80 destinations for 2026-27. Mountain Collective offers two no-blackout days at each of 27 destinations, and it overlaps heavily with the Ikon roster. Indy Pass groups more than 300 independent alpine and Nordic resorts and limits sales to protect them from crowding. In Europe, the Magic Pass cooperative competes on low prices and a fast-growing Swiss, French and Italian network. Pass operators also compete with tour packagers in winter adventure travel, where lodging and lift access are often sold together.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Vail Resorts (Epic) | Owner-operator | Epic Pass suite across 42 owned resorts plus partners |
| Alterra Mountain Company (Ikon) | Owner and alliance | Ikon Pass with 80 destinations for 2026-27 |
| Mountain Collective | Alliance pass | Two days at each of 27 destinations |
| Indy Pass | Independent collective | More than 300 alpine and Nordic resorts |
| Magic Pass | Regional cooperative | Swiss-led pass with a record 321,400 holders for 2025/26 |
Renewal rates will matter more than resort counts
Credence Research's view is that multi-resort ski pass renewal rates will matter more than resort counts over the forecast period. Networks already cover most destinations that holders want, so adding partners brings smaller gains each year. The 12% fall in Vail Resorts pass units through September 2026 shows how quickly a poor snow season feeds into the next sales cycle. Operators that offer refunds, young adult pricing and flexible day products will hold more holders through weak winters. Spending on boots, bindings and other equipment also rises with each extra day skied, so resorts value frequent holders most.
Model built from operator filings and resort data
The report uses 2025 as the base year and forecasts to 2035. Market values come from the Credence Research model, which links skier visits, pass holder counts and published pass prices, and regional and segment splits are Credence Research estimates. Inputs came from Vail Resorts filings with the U.S. Securities and Exchange Commission, National Ski Areas Association visit data, Japanese tourism statistics, pass operator announcements and trade press reports. No interviews or surveys were conducted by Credence Research for this edition.
Collectives and Asian partners carry growth to 2035
The market is set to grow from USD 1.75 billion in 2026 to USD 2.28 billion by 2035 at a 3.00% CAGR. Regional Collectives are forecast to grow at 3.55% a year in the multi-resort ski pass market, ahead of the two mega passes. North America will stay the largest region, but most new holders will come from regional collectives, Japanese partner resorts and Southern Hemisphere passes. Mega pass prices are likely to rise more slowly after the sales declines of 2025/26 and 2026/27, while refund and day-count options broaden. Operators will also bundle passes with lodging and flights as resorts compete for sports tourism spending in Japan and the Alps through the forecast period.
Frequently Asked Questions
How big is the multi-resort ski pass market?
Which pass leads the market?
Which pass type grows fastest?
Which region holds the largest share?
Which region grows fastest?
Which customer group grows fastest?
How did weather affect pass sales in 2026?
Who are the main companies in the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Pass
- 1.2.1 Epic
- 1.2.2 Ikon
- 1.2.3 Regional Collectives
- 1.3 By Customer
- 1.3.1 Adults
- 1.3.2 Families
- 1.3.3 Students
- 1.4 By Access Type
- 1.4.1 Unlimited Passes
- 1.4.2 Limited-Day Passes
- 1.4.3 Day-Count Passes
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 1.70 billion → 2035: USD 2.28 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Multi-Resort Ski Pass Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Multi-Resort Ski Pass Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Multi-Resort Ski Pass Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Multi-Resort Ski Pass Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Multi-Resort Ski Pass Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Multi-Resort Ski Pass Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Multi-Resort Ski Pass Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Multi-Resort Ski Pass Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 1.70 billion → 2035: USD 2.28 billion)
- 11.1.2 Historical Market Size, 2018-2025
- 11.1.3 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Multi-Resort Ski Pass Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Pass - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Base-Year Market Share, 2025
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Epic
- 12.3.6.2 Ikon
- 12.3.6.3 Regional Collectives
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Customer - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Base-Year Market Share, 2025
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Adults
- 12.4.6.2 Families
- 12.4.6.3 Students
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Access Type - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Base-Year Market Share, 2025
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Unlimited Passes
- 12.5.6.2 Limited-Day Passes
- 12.5.6.3 Day-Count Passes
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Multi-Resort Ski Pass End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Multi-Resort Ski Pass Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Multi-Resort Ski Pass Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2025-2035
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Multi-Resort Ski Pass Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Vail Resorts (Epic)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Alterra Mountain Company (Ikon)
- 18.4 Mountain Collective
- 18.5 Indy Pass
- 18.6 Magic Pass
- 18.7 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

