
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
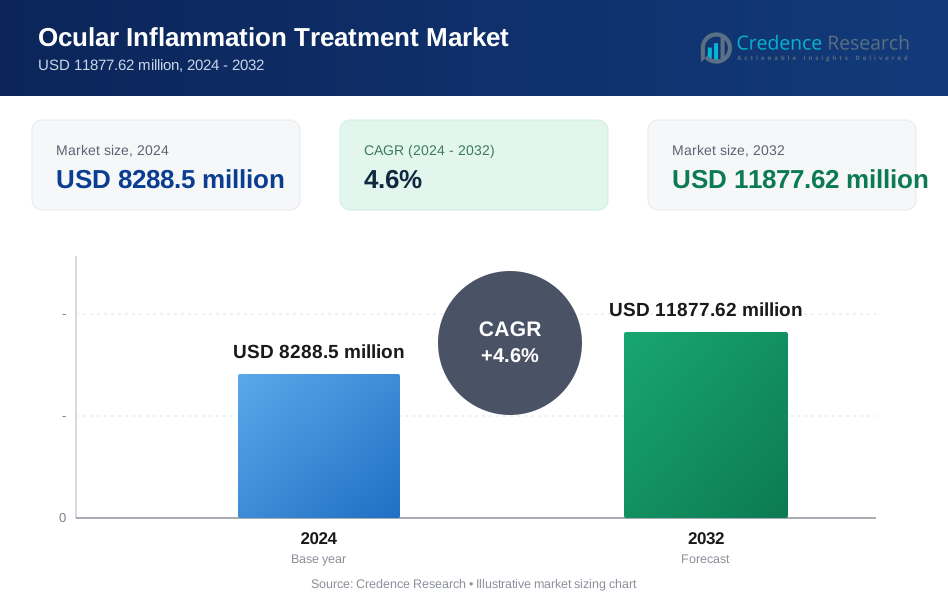
| Ocular Inflammation Treatment Market Size 2024 | USD 8288.5 million |
| Ocular Inflammation Treatment Market, CAGR | 4.6% |
| Ocular Inflammation Treatment Market Size 2032 | USD 11877.62 million |
Market Overview
The Global Ocular Inflammation Treatment Market is projected to grow from USD 8288.5 million in 2024 to USD 11877.62 million by 2032, expanding at a CAGR of 4.6% from 2024 to 2032.
The ocular inflammation treatment market is currently driven by rising prevalence of eye disorders, increasing awareness of ocular health, and advancements in drug formulations and delivery methods. The market is witnessing robust growth due to a surge in the geriatric population, which is more susceptible to conditions like uveitis and dry eye syndrome. Technological innovations, such as targeted biologics and personalized medicine, are enhancing treatment efficacy and patient outcomes. Additionally, rising investment in research and development, coupled with supportive regulatory frameworks, is accelerating market expansion. The growing demand for minimally invasive procedures and the availability of advanced diagnostic tools further bolster market growth, positioning it for continued advancement in the coming years.
Geographically, the ocular inflammation treatment market is experiencing significant growth across North America, Europe, and Asia-Pacific, each contributing uniquely to the sector's expansion. North America leads the market, driven by advanced healthcare infrastructure, high awareness levels, and a substantial patient population. The presence of key pharmaceutical companies and significant investment in research and development bolster this region's dominance. Europe follows closely, benefiting from a well-established healthcare system and increasing healthcare expenditure. In Asia-Pacific, rapid economic growth, expanding healthcare access, and rising awareness about ocular conditions are fueling market potential, with countries like China and India emerging as significant players. Key players in the market include Allergan, Novartis, and Roche, renowned for their innovative therapies and strong market presence. These companies drive competition through continuous product development and strategic partnerships. Emerging firms like Spark Therapeutics and Ocular Therapeutix are also making strides with novel treatment approaches, contributing to a dynamic and competitive landscape. Overall, the global market is marked by diverse regional dynamics and influential players committed to advancing ocular inflammation therapies.
Market Drivers
Rising Prevalence of Eye Disorders
The increasing incidence of ocular inflammatory conditions, such as uveitis and dry eye syndrome, significantly drives market growth. For instance, the global prevalence of dry eye disease is escalating due to environmental factors and an aging population, leading to higher demand for effective treatments. This growing patient population compels pharmaceutical companies to develop and deliver innovative therapies to address these widespread issues.
Technological Advancements
Innovations in drug development and delivery systems are pivotal in propelling the ocular inflammation treatment market. For instance, the advent of targeted biologics and advanced drug delivery platforms, such as sustained-release formulations and nanotechnology, enhances treatment precision and efficacy. These technological advancements not only improve patient outcomes but also create new opportunities for market expansion.
Increasing Healthcare Expenditure
Rising healthcare spending globally, particularly in emerging markets, fuels the demand for advanced ocular inflammation treatments. For instance, as countries like China and India invest more in their healthcare systems, they improve access to novel therapies and diagnostic tools, thereby driving market growth. This increased investment supports the development and adoption of new treatments, contributing to the overall expansion of the market.
Growing Awareness and Diagnosis
Enhanced awareness about ocular health and improvements in diagnostic capabilities contribute to market growth. For instance, increased public awareness campaigns and advancements in diagnostic technologies enable earlier and more accurate detection of ocular inflammatory conditions. This heightened awareness and better diagnostic tools lead to prompt treatment and a growing patient base, further stimulating market demand.
Market Trends
Shift Toward Personalized Medicine
The ocular inflammation treatment market is increasingly focusing on personalized medicine to improve therapeutic outcomes. For instance, advancements in genomics and biomarkers allow for tailored treatment plans that address individual patient profiles more precisely. This trend is driven by the recognition that personalized approaches can enhance efficacy and minimize side effects compared to one-size-fits-all solutions. Companies are investing in research to develop targeted therapies that align with specific genetic and molecular profiles of patients, which is anticipated to lead to more effective and individualized treatment options.
Integration of Digital Health Technologies
The integration of digital health technologies is revolutionizing the management of ocular inflammation. For instance, the use of mobile health applications and telemedicine platforms is growing, enabling remote monitoring and management of eye conditions. These technologies facilitate real-time data collection and patient engagement, leading to improved adherence to treatment regimens and timely interventions. Additionally, advancements in digital diagnostics, such as AI-driven imaging and monitoring tools, are enhancing the accuracy of disease assessment and treatment planning, reflecting a significant trend towards digitalization in ocular healthcare.
Market Challenges Analysis
High Costs of Advanced Therapies
One significant challenge in the ocular inflammation treatment market is the high cost associated with advanced therapies. Innovative treatments, such as biologics and targeted therapies, often come with substantial price tags, which can limit accessibility for a broad patient base. These high costs can lead to insurance coverage issues and financial barriers for patients, potentially restricting market growth and adoption of new treatments.
Regulatory and Approval Hurdles
Navigating the regulatory landscape for ocular inflammation treatments presents another challenge. The lengthy and complex approval processes required by regulatory agencies can delay the introduction of new therapies to the market. Stringent requirements for clinical trials and evidence of safety and efficacy add to the development timeline and costs, potentially slowing innovation and market entry for new products. This regulatory complexity can hinder timely access to novel treatments and impact overall market dynamics.
Market Segmentation Analysis
By Treatment Type:
- Corticosteroids: Corticosteroids hold a dominant position in the ocular inflammation treatment market due to their efficacy in rapidly reducing inflammation and controlling symptoms across various ocular conditions. They are commonly prescribed for anterior uveitis and episcleritis/scleritis, where inflammation control is critical. Despite their effectiveness, long-term use can lead to potential side effects, driving ongoing research into alternative treatments.
- Monoclonal Antibodies: Monoclonal antibodies are emerging as a significant segment in the market, particularly for conditions such as posterior uveitis and pan uveitis. These biologics target specific inflammatory pathways, offering a high level of precision in treatment. They are increasingly favored for their ability to address severe and chronic forms of inflammation with fewer systemic side effects compared to traditional therapies.
By Disease Type:
- Anterior Uveitis: Anterior uveitis, the most common form of uveitis, primarily affects the front part of the eye. Treatments often include corticosteroids and cycloplegic agents to manage inflammation and pain. The market for anterior uveitis is robust due to the condition’s high prevalence and the need for effective and prompt treatment options.
- Posterior Uveitis: Posterior uveitis, affecting the back of the eye, requires more specialized treatments such as monoclonal antibodies and immunosuppressants. This segment is growing as new therapies are developed to address the more severe and complex nature of posterior uveitis, which often leads to vision-threatening complications.
Segmentation
Based on Treatment Type
- Corticosteroids
- Antibiotics
- Monoclonal Antibodies
- Immunosppressant
- Cycloplegic Agents
- Antivirals
- Antifungal
- Analgesics
Based on Disease Type
- Anterior Uveitis
- Posterior Uveitis
- Pan Uveitis
- Intermediate Uveitis
- Episcleritis/Scleritis
Based on Mode of Administration
- Topical
- Injectable
- Oral
- Others
Based on Region
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis
North America
North America is the largest regional market for ocular inflammation treatments, commanding a significant share of approximately 45%. The region's dominance stems from its advanced healthcare infrastructure, high levels of awareness, and substantial investment in research and development. The presence of major pharmaceutical companies and the early adoption of innovative therapies further bolster its market leadership. The United States leads due to its well-established healthcare system and high prevalence of ocular conditions that require advanced treatments.
Europe
Europe holds a substantial share of around 30% in the global ocular inflammation treatment market. The region benefits from a robust healthcare framework, increasing healthcare expenditure, and growing patient awareness about ocular health. Western European countries such as Germany, France, and the United Kingdom are major contributors to this market, driven by their strong healthcare systems and high levels of medical research. Additionally, Eastern European countries are gradually expanding their market presence as healthcare access improves and awareness increases.
Asia-Pacific
The Asia-Pacific region is experiencing rapid growth and currently accounts for approximately 20% of the global market. This growth is driven by economic expansion, improving healthcare infrastructure, and increasing awareness of ocular health issues. Countries like China and India are major contributors, owing to their large patient populations and rising investment in healthcare. The region is witnessing a surge in demand for advanced treatments and diagnostic tools, which is propelling market growth. Emerging economies in Southeast Asia are also contributing to this upward trend as they enhance their healthcare systems.
Latin America
Latin America holds a smaller share of around 5% of the global ocular inflammation treatment market. However, the region is showing potential for growth due to improving healthcare access and rising awareness about ocular diseases. Countries such as Brazil and Mexico are leading this market segment, driven by increased healthcare investments and the expansion of medical services.
Middle East and Africa
The Middle East and Africa account for approximately 3% of the global market. This region is characterized by a growing healthcare sector, but it faces challenges such as varying levels of healthcare access and economic disparities. Despite these challenges, increasing investments in healthcare infrastructure and rising awareness about ocular conditions are expected to drive future market growth in this region.
Key Players
- Allergan (AbbVie Inc.)
- Novartis AG
- Roche Holding AG
- Regeneron Pharmaceuticals, Inc.
- Santen Pharmaceutical Co., Ltd.
- Valeant Pharmaceuticals International, Inc.
- Ocular Therapeutix, Inc.
- Bausch + Lomb (a division of Bausch Health Companies Inc.)
- Sun Pharmaceutical Industries Ltd.
- Pfizer Inc.
Competitive Analysis
The ocular inflammation treatment market is highly competitive, characterized by the presence of several leading pharmaceutical companies and innovative biotech firms. Major players like Allergan, Novartis, and Roche dominate the market with their extensive portfolios of established and emerging therapies. These companies leverage significant R&D investments and strong distribution networks to maintain market leadership. The competition is further intensified by the rapid pace of technological advancements and the introduction of novel treatments, such as monoclonal antibodies and targeted biologics, which are driving innovation. Additionally, emerging players like Ocular Therapeutix and Spark Therapeutics are challenging established firms with breakthrough therapies and novel drug delivery systems. Strategic collaborations, acquisitions, and partnerships are common as companies seek to enhance their market position and expand their product offerings. Overall, the competitive landscape is dynamic, with ongoing efforts to address unmet medical needs and capitalize on growing market opportunities.
Recent Developments
- In March 2023, Novartis received FDA approval for its new drug, Kymriah, for the treatment of refractory ocular inflammation. This approval marked a significant advancement in targeted biologic therapies for ocular conditions, highlighting the company's commitment to addressing complex inflammatory diseases.
- In May 2023, Allergan launched a new corticosteroid treatment, Durezol, with an extended-release formulation aimed at improving patient adherence and reducing dosing frequency. This development represents a key enhancement in managing acute ocular inflammation and addressing patient needs for more convenient treatment options.
- In August 2023, Ocular Therapeutix announced positive results from its Phase 3 clinical trials for a novel drug delivery system designed to treat dry eye disease. The innovative system aims to offer sustained relief and reduce the need for frequent eye drops, potentially transforming the management of ocular inflammation.
- In November 2023, Regeneron Pharmaceuticals expanded its portfolio with the introduction of a new monoclonal antibody specifically targeting inflammatory pathways in uveitis. This development underscores the growing focus on precision medicine and personalized treatment approaches in the ocular inflammation market.
Market Concentration & Characteristics
The ocular inflammation treatment market exhibits a moderate to high level of concentration, dominated by a few major pharmaceutical companies with extensive resources and established market presence. Key players such as Allergan, Novartis, and Roche hold substantial market shares due to their broad portfolios, significant R&D investments, and strong distribution networks. These companies focus on a range of treatment modalities, from corticosteroids and monoclonal antibodies to novel biologics. The market is characterized by intense competition driven by rapid technological advancements and a continual push for innovation in drug development. Additionally, there is a notable presence of specialized biotech firms that introduce cutting-edge therapies and drug delivery systems, contributing to a dynamic and evolving landscape. The industry also sees frequent strategic partnerships and acquisitions as companies aim to enhance their product offerings and address emerging treatment needs in ocular inflammation.
Report Coverage
The research report offers an in-depth analysis based on treatment types, Disease type, Mode of Administration and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Increased Adoption of Biologics: The market is expected to see continued growth in the adoption of biologic therapies, such as monoclonal antibodies, which offer targeted treatment for ocular inflammation and improved patient outcomes.
- Advancements in Drug Delivery Systems: Innovations in drug delivery, including sustained-release formulations and implantable devices, will likely enhance treatment efficacy and patient compliance by reducing the frequency of administration.
- Growth in Personalized Medicine: The shift toward personalized medicine will drive the development of tailored therapies based on genetic and molecular profiling, offering more precise and effective treatment options for ocular inflammation.
- Expansion in Emerging Markets: Increasing healthcare access and awareness in emerging markets, particularly in Asia-Pacific and Latin America, will lead to significant market expansion as these regions adopt advanced ocular treatments.
- Development of Novel Therapeutics: Ongoing research will likely yield new therapeutic agents, including small molecules and gene therapies, addressing previously unmet needs in the treatment of ocular inflammation.
- Integration of Digital Health Technologies: The incorporation of digital health technologies, such as telemedicine and AI-driven diagnostic tools, will improve disease management and patient engagement, potentially leading to better outcomes.
- Focus on Combination Therapies: The use of combination therapies, integrating different treatment modalities to address various aspects of ocular inflammation, will become more prevalent, offering enhanced efficacy and reduced side effects.
- Increased R&D Investment: Continued investment in research and development by pharmaceutical and biotech companies will drive innovation and the introduction of new, more effective treatments for ocular inflammation.
- Regulatory Advances: Evolving regulatory frameworks may facilitate faster approval processes for new therapies, accelerating the time-to-market for novel treatments and enhancing market dynamics.
- Emerging Biotech Startups: The rise of emerging biotech startups focusing on breakthrough therapies and innovative drug delivery systems will introduce new competition and opportunities, contributing to a dynamic and competitive market landscape.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Ocular Inflammation Treatment Market
What factors are driving the growth of the Ocular Inflammation Treatment Market?
What are the key segments within the Ocular Inflammation Treatment Market?
Who are the major players in the Ocular Inflammation Treatment Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Ocular Inflammation Treatment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Ocular Inflammation Treatment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 8288.5 million → 2032: USD 11877.62 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Ocular Inflammation Treatment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Ocular Inflammation Treatment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Ocular Inflammation Treatment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Ocular Inflammation Treatment Market Drivers
- 3.3 Ocular Inflammation Treatment Market Restraints & Challenges
- 3.4 Ocular Inflammation Treatment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Ocular Inflammation Treatment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Ocular Inflammation Treatment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Ocular Inflammation Treatment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Ocular Inflammation Treatment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Ocular Inflammation Treatment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Ocular Inflammation Treatment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Ocular Inflammation Treatment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Ocular Inflammation Treatment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Ocular Inflammation Treatment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Ocular Inflammation Treatment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Ocular Inflammation Treatment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Ocular Inflammation Treatment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Ocular Inflammation Treatment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Ocular Inflammation Treatment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Ocular Inflammation Treatment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Ocular Inflammation Treatment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Ocular Inflammation Treatment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Ocular Inflammation Treatment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Ocular Inflammation Treatment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
