
Market Overview:
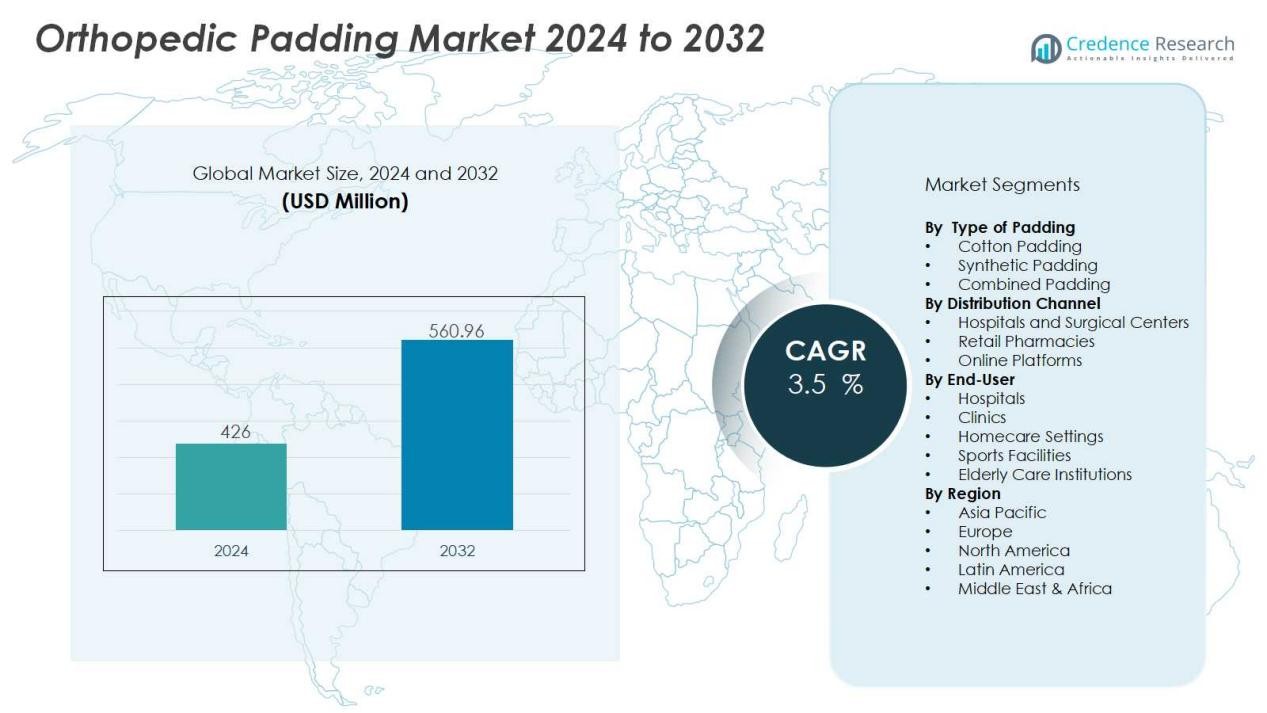
The orthopedic padding market size was valued at USD 426 million in 2024 and is anticipated to reach USD 560.96 million by 2032, at a CAGR of 3.5 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Orthopedic Padding Market Size 2024 | USD 426 Million |
| Orthopedic Padding Market, CAGR | 3.5 % |
| Orthopedic Padding Market Size 2032 | USD 560.96 Million |
Key drivers of the orthopedic padding market include the rising incidence of bone fractures, arthritis, and joint-related conditions, particularly among aging populations. Growing adoption of sports and fitness activities has led to a higher rate of injuries, which fuels demand for padding materials in rehabilitation and post-surgical care. Furthermore, hospitals and clinics are prioritizing advanced padding solutions that improve comfort, prevent skin complications, and enhance recovery outcomes, strengthening product adoption across healthcare systems.
Regionally, North America leads the orthopedic padding market due to its advanced healthcare infrastructure, high surgical volumes, and widespread use of orthopedic care products. Europe follows closely, supported by a growing elderly population and strong adoption of innovative healthcare solutions. Asia Pacific is anticipated to witness the fastest growth, driven by rising healthcare investments, expanding patient awareness, and increasing surgical interventions in countries such as China and India. Emerging markets in Latin America and the Middle East & Africa also present untapped opportunities, supported by improving medical access and infrastructure.
Market Insights:
- The orthopedic padding market was valued at USD 426 million in 2024 and is expected to reach USD 560.96 million by 2032, growing at a CAGR of 3.5%.
- Rising incidence of fractures, arthritis, and joint-related conditions among aging populations continues to drive market demand.
- Increasing sports and recreational injuries create consistent need for orthopedic padding in rehabilitation and post-surgical care.
- North America led with 38% share in 2024, supported by advanced healthcare infrastructure and high surgical volumes.
- Europe followed with 29% share, driven by an aging population, robust healthcare systems, and material innovation.
- Asia Pacific held 22% share in 2024 and is projected to grow fastest, supported by rising healthcare investments and surgical interventions.
- Latin America captured 6% share, while the Middle East & Africa accounted for 5%, both benefiting from expanding healthcare access and medical tourism.
Market Drivers:
Rising Incidence of Musculoskeletal Disorders and Injuries:
The orthopedic padding market is driven by the growing prevalence of fractures, arthritis, and joint-related conditions worldwide. An aging population with higher susceptibility to bone and joint issues further increases demand. Sports and recreational activities have also contributed to higher injury rates, creating consistent need for padding in rehabilitation and post-surgical care. It benefits from this trend as patients and healthcare providers prioritize supportive and protective materials.
- For instance, 3M Health Care offers synthetic cast padding that provides highly conformable and breathable support, with product lengths standardized at 3.658 meters to ensure effective coverage and comfort for patients during recovery.
Expanding Surgical Procedures and Post-Operative Care:
Orthopedic padding plays a vital role in surgical interventions by providing cushioning, stability, and protection. The rise in orthopedic surgeries, including joint replacements and trauma-related procedures, has fueled product demand. It ensures patient comfort, reduces pressure points, and minimizes skin complications during recovery. The increasing reliance on efficient post-operative care solutions strengthens its adoption across hospitals and clinics.
- For instance, Stryker's MAKO robotic surgery system was used in over 1.5 million procedures worldwide as of mid-2024, including total knee, partial knee, and total hip replacements, underscoring the growing integration of orthopedic technologies in surgical care
Advancements in Material Innovation and Product Development:
Continuous improvements in material science have enhanced the effectiveness and usability of orthopedic padding. Modern padding solutions are designed with breathable, hypoallergenic, and skin-friendly materials that improve patient outcomes. It is gaining traction due to innovations that focus on durability, flexibility, and comfort. The development of lightweight, cost-effective, and customizable products further expands their use in diverse orthopedic treatments.
Growing Healthcare Infrastructure and Awareness in Emerging Markets:
Expanding healthcare investments in Asia Pacific, Latin America, and the Middle East have opened new growth avenues. Rising awareness among patients regarding orthopedic support products strengthens their acceptance. It benefits from the increasing availability of advanced healthcare facilities and trained professionals in these regions. Government initiatives and private sector investment continue to support wider adoption of orthopedic padding solutions.
Market Trends:
Adoption of Advanced Materials and Patient-Centric Solutions:
The orthopedic padding market is witnessing strong demand for innovative materials that enhance patient comfort and treatment efficiency. Manufacturers are introducing breathable, lightweight, and hypoallergenic padding designed to prevent skin irritation and improve recovery. It is also experiencing a rise in demand for eco-friendly and sustainable materials, aligning with healthcare sustainability goals. Customizable padding solutions tailored to specific patient needs are gaining traction across hospitals and clinics. The integration of antimicrobial properties into products further improves patient safety and reduces infection risks. Growing awareness among patients and healthcare providers about these advanced solutions is reinforcing market adoption.
- For instance, Johnson & Johnson MedTech launched the VOLT™ Variable Angle Optimized Locking Tech Plating System in late 2024, enhancing fracture management solutions by improving stability and efficiency, while incorporating antimicrobial capabilities that help reduce infection risks during patient recovery.
Expansion of Outpatient Care and Home-Based Recovery Products:
Shifting care models toward outpatient procedures and home-based recovery are shaping new trends in the orthopedic padding market. It is benefiting from the growing availability of user-friendly products designed for use outside traditional hospital settings. The rise in e-commerce platforms and digital distribution channels has also expanded product accessibility to patients directly. Portable and cost-effective padding solutions are becoming more popular among individuals seeking convenience and faster recovery. Healthcare providers are increasingly recommending padding for preventive care in sports and elderly populations. These evolving trends are positioning orthopedic padding as a vital component of modern healthcare practices.
- For instance, in 2025, Johnson & Johnson MedTech launched the VOLT™ Variable Angle Optimized Locking Tech Plating System, which improves stability and efficiency in outpatient fracture management, highlighting the shift toward advanced, user-friendly products designed for non-hospital settings.
Market Challenges Analysis:
High Cost of Advanced Materials and Limited Reimbursement Policies:
The orthopedic padding market faces challenges due to the high cost of advanced materials used in premium products. While breathable and hypoallergenic padding improves patient comfort, it also raises production expenses, making such products less affordable in cost-sensitive regions. Limited reimbursement coverage for orthopedic support solutions restricts wider adoption, especially in developing markets. It struggles to balance the demand for innovation with price sensitivity among healthcare providers and patients. The lack of consistent insurance support often forces patients to choose lower-cost alternatives. This issue creates a barrier to market penetration and slows the adoption of advanced solutions.
Quality Variability and Lack of Standardization Across Regions:
Variability in product quality and lack of strict regulatory frameworks in some regions present another challenge for the orthopedic padding market. It is difficult for patients and providers to distinguish between high-quality and substandard options, leading to inconsistent treatment outcomes. Counterfeit and low-grade products in emerging markets further weaken trust and hinder adoption of reliable solutions. Limited awareness among patients about the importance of certified and tested padding adds to the problem. Healthcare facilities in underdeveloped regions also face constraints in sourcing high-standard products consistently. These gaps in regulation and quality control create hurdles for global market expansion.
Market Opportunities:
Rising Demand in Emerging Economies and Expanding Healthcare Access:
The orthopedic padding market holds strong opportunities in emerging economies with rapidly improving healthcare infrastructure. Growing investments in hospitals, rehabilitation centers, and trauma care facilities are creating wider demand for supportive care products. It can benefit from increasing government healthcare spending and private sector participation in countries such as India, China, and Brazil. Rising disposable incomes and improved patient awareness also support adoption of advanced padding solutions. Expanding insurance coverage in these regions is expected to further accelerate product accessibility. These factors position developing markets as high-growth zones for orthopedic padding adoption.
Technological Innovation and Expansion into Non-Traditional Applications:
Innovation in materials and design provides significant opportunities for the orthopedic padding market. It can leverage advancements in smart fabrics, antimicrobial coatings, and eco-friendly materials to attract new customers. The development of customizable and patient-specific padding solutions enhances recovery outcomes and strengthens brand competitiveness. Expansion into preventive care for athletes and elderly populations also opens new revenue streams. Growing use of e-commerce and digital health platforms broadens product visibility and patient access. These opportunities enable manufacturers to capture untapped potential and diversify their market presence.
Market Segmentation Analysis:
By Type of Padding:
The orthopedic padding market includes cotton, synthetic, and combined padding solutions. Cotton padding remains widely used due to its affordability, comfort, and breathability. Synthetic padding is gaining preference for its durability, water resistance, and ease of application in modern medical settings. Combined padding, which integrates cotton and synthetic layers, is emerging as a balanced option for strength and patient comfort. It is expected to see further demand with hospitals focusing on efficiency and patient safety.
- For Instance, Delta-Cast® Delta-Rol® is a synthetic cast padding that offers a breathable material with conformable stretch. The product, manufactured by Essity, is widely used in combination with other layers in orthopedic casting procedures.
By Distribution Channel:
Hospitals and surgical centers dominate distribution due to the consistent need for orthopedic padding in trauma and post-operative care. Retail pharmacies maintain strong sales supported by accessibility and patient familiarity with common padding products. Online platforms are growing rapidly, driven by the expansion of e-commerce and direct-to-patient supply models. It benefits from digital distribution that improves availability in both developed and emerging regions. Manufacturers are leveraging online channels to reach broader patient groups with customizable options.
- For example, in 2024, Essity's Health & Medical business area, which includes orthopedic padding brands, reported strong growth and higher market share, driven by a global focus on hygiene and health solutions and successful product innovation.
By End-User:
Hospitals remain the largest end-user segment, supported by high surgical volumes and advanced care facilities. Clinics account for a growing share, driven by rising outpatient procedures and rehabilitation services. Homecare settings are expanding as patients adopt self-care products for recovery and preventive use. It is seeing rising interest from sports facilities and elderly care institutions for non-surgical orthopedic support. This diversification across end users is strengthening overall market adoption.
Segmentations:
By Type of Padding:
- Cotton Padding
- Synthetic Padding
- Combined Padding
By Distribution Channel:
- Hospitals and Surgical Centers
- Retail Pharmacies
- Online Platforms
By End-User:
- Hospitals
- Clinics
- Homecare Settings
- Sports Facilities
- Elderly Care Institutions
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America and Europe:
North America held 38% market share in 2024, making it the leading region in the orthopedic padding market. Europe followed with 29% market share, supported by a robust healthcare system and aging demographics. It benefits from the high volume of orthopedic surgeries, advanced medical infrastructure, and strong insurance coverage in both regions. Growing demand for sports injury treatments in the United States and rising geriatric care needs in Europe strengthen product uptake. Innovation in materials and consistent regulatory oversight further enhance adoption. Manufacturers in these regions focus heavily on premium padding solutions that improve patient safety and comfort.
Asia Pacific:
Asia Pacific accounted for 22% market share in 2024 and is projected to expand at the fastest pace. The orthopedic padding market gains momentum from increasing healthcare investments in China, India, and Southeast Asia. It is driven by rising trauma cases, higher surgical volumes, and improving patient awareness in urban centers. Expanding private hospital networks and growing middle-class income levels also support wider adoption of orthopedic products. Government initiatives in healthcare modernization continue to boost opportunities for global manufacturers. Rising demand in sports medicine and rehabilitation further strengthens the region’s growth potential.
Latin America and Middle East & Africa:
Latin America captured 6% market share in 2024, while the Middle East & Africa held 5% market share. The orthopedic padding market sees growth potential in these regions due to improving healthcare access and infrastructure development. It benefits from increasing surgical interventions, particularly in trauma and joint replacement procedures. Expanding private sector investments and international collaborations are bringing modern orthopedic solutions to underserved markets. Rising medical tourism in countries such as Mexico and the UAE also creates new opportunities. Growing awareness of orthopedic care products is expected to steadily expand adoption in these emerging regions.
Key Player Analysis:
- 3M
- Ossur
- Derma Sciences
- GF Health Products
- Lohmann & Rauscher
- Paul Hartmann
- DeRoyal
- Medical Action Industries
- Alimed
- Briggs Medical
- Bioseal
- O&M Halyard
- Breg
- Creative Foam Corp
- Dynarex
Competitive Analysis:
The orthopedic padding market is highly competitive, shaped by global leaders and regional players. Key companies include 3M, Ossur, Derma Sciences, GF Health Products, Lohmann & Rauscher, Paul Hartmann, DeRoyal, Medical Action Industries, Alimed, and Briggs Medical. It is driven by continuous innovation in padding materials, product customization, and the ability to meet clinical standards. Companies focus on expanding product portfolios with breathable, hypoallergenic, and antimicrobial solutions to address rising patient needs. Strategic partnerships with healthcare providers and distributors help strengthen global reach and market presence. Price competitiveness and quality consistency remain critical factors in securing long-term contracts with hospitals and clinics. It continues to see strong investment in digital sales platforms, enhancing direct access to patients and caregivers worldwide.
Recent Developments:
- In February 2025, Össur launched the Navii microprocessor knee, which features a waterproof design and advanced gait algorithms that adjust to the user’s walking patterns.
- In September 2025, The CEO of 3M announced goals for achieving 25% margin expansion by 2027 and highlighted the company’s plan to launch 1,000 products by 2028, focusing on aerospace, automotive, and data center segments.
Report Coverage:
The research report offers an in-depth analysis based on Type of Padding, Distribution Channel, End-User and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- Growing demand for orthopedic padding will continue with rising cases of fractures, arthritis, and trauma.
- Healthcare providers will prioritize advanced materials that improve comfort, reduce skin complications, and enhance recovery outcomes.
- Manufacturers will expand portfolios with breathable, hypoallergenic, and antimicrobial padding solutions to meet patient needs.
- Digital distribution channels and e-commerce will strengthen direct access for patients seeking cost-effective options.
- Emerging economies will present significant growth opportunities driven by healthcare investments and expanding surgical volumes.
- Innovation in smart fabrics and eco-friendly materials will shape future product development and adoption.
- Home-based recovery and outpatient care trends will increase demand for portable and user-friendly padding products.
- Athletes and elderly populations will create new consumer segments for preventive and supportive orthopedic care.
- Regulatory frameworks and quality certifications will become key to building trust and ensuring product reliability.
- Collaborations between manufacturers and healthcare institutions will accelerate adoption and expand global reach.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Incidence of Musculoskeletal Disorders and Injuries
Increasing cases of bone fractures, arthritis, and joint-related conditions, especially among aging populations and active individuals, are driving demand for orthopedic padding in both acute and chronic care settings.
Expanding Surgical Procedures and Post-Operative Care
Growth in orthopedic surgeries, such as joint replacements and trauma interventions, is fueling the need for padding products that provide cushioning, stability, and protection during recovery, supporting better patient outcomes.
Advancements in Material Innovation and Product Development
Continuous improvements in padding materials - such as breathable, hypoallergenic, and antimicrobial options - are enhancing comfort and safety, encouraging healthcare providers to adopt advanced solutions.
Growing Healthcare Infrastructure and Awareness in Emerging Markets
Rising investments in healthcare facilities and increasing patient awareness in regions like Asia Pacific, Latin America, and the Middle East & Africa are expanding access to orthopedic care and driving market growth.
Shift Toward Outpatient and Home-Based Recovery
Trends toward outpatient procedures and home-based rehabilitation are increasing demand for user-friendly, portable orthopedic padding products, making them more accessible to a broader patient base.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the orthopedic padding market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the orthopedic padding market projected to grow between 2024 and 2032?
Which orthopedic padding market segment held the largest share in 2024?
What are the primary factors fueling the growth of the orthopedic padding market?
Who are the leading companies in the orthopedic padding market?
Which region commanded the largest share of the orthopedic padding market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Hospitals
- 1.2.2 Clinics
- 1.2.3 Homecare Settings
- 1.2.4 Sports Facilities
- 1.2.5 Elderly Care Institutions
- 1.3 By Type of Padding
- 1.3.1 Cotton Padding
- 1.3.2 Synthetic Padding
- 1.3.3 Combined Padding
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 426 million → 2032: USD 560.96 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Orthopedic Padding Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Orthopedic Padding Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Orthopedic Padding Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Orthopedic Padding Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Orthopedic Padding Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Orthopedic Padding Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Orthopedic Padding Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Orthopedic Padding Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 426 million → 2032: USD 560.96 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Orthopedic Padding Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Clinics
- 12.3.7.3 Homecare Settings
- 12.3.7.4 Sports Facilities
- 12.3.7.5 Elderly Care Institutions
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Type of Padding - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cotton Padding
- 12.4.7.2 Synthetic Padding
- 12.4.7.3 Combined Padding
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Orthopedic Padding End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Orthopedic Padding Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Orthopedic Padding Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Orthopedic Padding Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 3M
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Ossur
- 18.4 Derma Sciences
- 18.5 GF Health Products
- 18.6 Lohmann & Rauscher
- 18.7 Paul Hartmann
- 18.8 DeRoyal
- 18.9 Medical Action Industries
- 18.10 Alimed
- 18.11 Briggs Medical
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

