
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Periodontal Disease Market Size 2023 | USD 3,712.97 million |
| Periodontal Disease Market, CAGR | 5.76% |
| Periodontal Disease Market Size 2032 | USD 6,256.85 million |
Market Overview
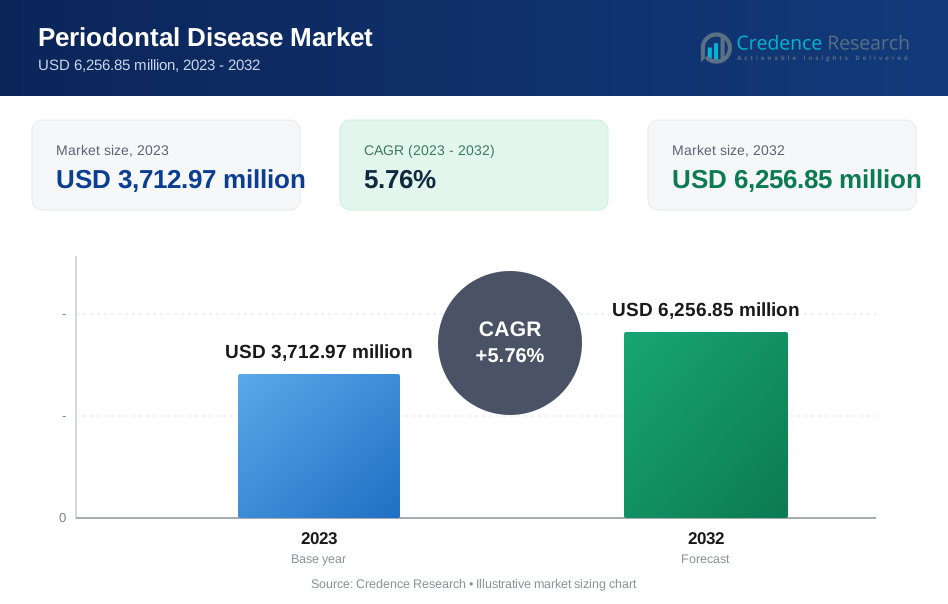
The global periodontal disease market is projected to grow from USD 3,712.97 million in 2023 to USD 6,256.85 million by 2032, with a compound annual growth rate (CAGR) of 5.76%.
The global periodontal disease market is driven by the increasing prevalence of periodontal conditions due to rising aging populations and growing awareness about oral health. Advancements in diagnostic technologies and minimally invasive treatment options are also contributing to market growth. Additionally, the rising adoption of preventive dental care and oral hygiene products is fueling demand for periodontal treatments. The market is further influenced by the growing focus on cosmetic dentistry, as people seek solutions for aesthetic concerns related to gum health. Trends such as the integration of AI in dental diagnostics and treatment planning, as well as the increasing use of laser therapy, are expected to enhance treatment outcomes and patient experience. Furthermore, the expanding availability of advanced periodontal care in emerging markets and the development of cost-effective treatment solutions will continue to support market expansion over the forecast period.
The global periodontal disease market exhibits significant geographical variation, with North America and Asia-Pacific emerging as key regions driving growth. In North America, advanced healthcare systems, high awareness levels, and strong demand for innovative treatments contribute to the region's dominance. Conversely, the Asia-Pacific market is growing rapidly due to improving healthcare access, increased awareness, and changing lifestyles, especially in developing countries. Key players in the global periodontal disease market include prominent pharmaceutical and dental care companies such as Bausch Health Companies Inc., Colgate-Palmolive Company, 3M, Sunstar Suisse S.A., and Mylan N.V. These companies offer a range of treatments, from non-surgical solutions like antibiotics to surgical interventions for chronic and aggressive periodontal conditions. The presence of these major players in both regions is essential to the expansion of periodontal disease management and treatment options worldwide, driving innovation and enhancing accessibility to advanced care.
Market Insights
- The global periodontal disease market was valued at USD 12.3 billion in 2023 and is projected to grow at a CAGR of 6.8% from 2024 to 2032.
- Increasing prevalence of periodontal diseases due to aging populations and lifestyle factors, such as smoking and poor oral hygiene, is driving market growth.
- Rising awareness about the link between oral health and overall health, supported by public health campaigns and social media, is boosting demand for treatments.
- Technological advancements, including laser therapy and advanced diagnostic tools, are enhancing treatment options and supporting market growth.
- High treatment costs and limited access to dental care in certain regions may hinder market expansion.
- North America holds a significant market share, driven by advanced healthcare systems and high treatment adoption rates.
- The Asia-Pacific region is experiencing rapid growth, driven by improving healthcare infrastructure and increasing awareness in emerging economies.
Market Drivers
Increasing Prevalence of Periodontal Disease
The global rise in the prevalence of periodontal disease can be attributed to various factors, including an aging population and unhealthy lifestyles. For instance, the World Health Organization (WHO) reports that severe periodontal disease affects a significant portion of the global population, particularly among older adults. As people age, weakened immune systems and decreased oral hygiene contribute to a higher incidence of periodontal conditions. Additionally, lifestyle factors such as smoking, excessive alcohol consumption, poor diet, and lack of proper oral care significantly increase the risk of developing periodontal disease. These combined factors are driving the demand for periodontal treatments worldwide.
Rising Awareness of Oral Health
Public health campaigns focused on the importance of oral hygiene and the connection between periodontal disease and systemic health are contributing to greater awareness. For instance, mass media campaigns have shown to improve oral health behaviors and knowledge, leading to increased dental visits. Social media and online resources further enhance public understanding, encouraging individuals to take preventive measures and seek timely treatment. The widespread dissemination of oral health information has empowered people to make informed decisions, which is fueling demand for dental care, including treatments for periodontal disease.
Technological Advancements
Innovations in dental technologies are playing a crucial role in driving market growth. For instance, the development of advanced treatment options like laser therapy, regenerative procedures, and minimally invasive techniques has made periodontal care more effective and less invasive. Additionally, the introduction of sophisticated diagnostic tools, such as intraoral cameras and digital X-rays, enables early detection and timely intervention, leading to better outcomes for patients. These technological advancements are enhancing treatment accessibility and improving patient satisfaction.
Growing Geriatric Population and Healthcare Expenditure
The increasing number of elderly individuals worldwide is another key driver for the periodontal disease market. Older adults are more susceptible to periodontal disease due to age-related changes in oral tissues and immune system decline. As the aging population grows, so do healthcare costs, including dental care. Government initiatives aimed at improving healthcare access and the growing availability of private insurance coverage for dental procedures further drive demand for periodontal treatments. Additionally, emerging research linking periodontal disease to systemic health conditions, such as heart disease and diabetes, is reinforcing the importance of preventive measures and treatment.
Market Trends
Rising Prevalence and Growing Awareness
The rising prevalence of periodontal disease is closely linked to an aging population and unhealthy lifestyle factors. As the global population ages, the incidence of periodontal disease increases due to age-related changes in immune function and oral health. For instance, studies show that approximately 70% of adults aged 65 and older have periodontal disease. Additionally, lifestyle factors such as smoking, excessive alcohol consumption, poor oral hygiene, and unhealthy diets significantly contribute to the development of periodontal conditions. The growing awareness of oral health, fueled by government initiatives and public health campaigns, is also a major factor. These campaigns emphasize the importance of oral hygiene and the connection between periodontal disease and systemic health conditions, such as diabetes and heart disease. Social media platforms further amplify these messages, enabling the widespread sharing of information and encouraging individuals to take a more proactive approach to dental care. This rising awareness is driving greater demand for preventive and treatment options for periodontal disease.
Technological Advancements and Growing Healthcare Demand
Technological advancements in dental diagnostics and treatments are significantly contributing to market growth. The development of advanced diagnostic tools, such as intraoral cameras and digital X-rays, allows for earlier detection and intervention, improving treatment outcomes and patient satisfaction. In addition, innovative treatment options, including laser therapy, regenerative procedures, and minimally invasive techniques, have revolutionized periodontal care, making it more effective and less invasive. This has driven an increase in demand for periodontal treatments. Moreover, the growing geriatric population, which is more susceptible to periodontal disease, further fuels the market. As older adults are at higher risk, the demand for treatments continues to rise. Along with this, the increasing healthcare expenditure is another important driver, with more people seeking dental services, including periodontal treatments. Rising insurance coverage for dental procedures also supports market growth, enabling greater access to necessary care. Finally, emerging research linking periodontal disease to systemic health conditions such as heart disease, diabetes, and respiratory infections reinforces the importance of preventive measures and timely treatment, further driving market expansion.
Market Challenges Analysis
Lack of Awareness and Limited Access to Dental Care
A significant challenge in combating periodontal disease is the lack of awareness, particularly in developing countries, where many people are unaware of the symptoms and long-term consequences of the disease. For instance, a study found that awareness about the link between periodontal disease and systemic health is very limited in both urban and rural populations in India. This lack of understanding leads to delays in diagnosis and treatment, allowing the condition to worsen. Inadequate oral hygiene practices, coupled with limited access to dental care, contribute further to the prevalence of periodontal disease. Many individuals in underserved regions face barriers such as insufficient access to dental professionals, either due to geographical constraints or socioeconomic factors. These challenges are compounded by a lack of education on the importance of oral health and preventive measures. Without proper preventive care and timely intervention, periodontal disease continues to be a major health issue, especially in areas where healthcare infrastructure is not fully developed.
High Cost of Treatment and Complex Regimens
The high cost of advanced periodontal treatments presents a significant barrier for many patients. Procedures such as dental implants, regenerative treatments, and other specialized therapies can be expensive, making them inaccessible to individuals, particularly in lower-income regions or those without comprehensive insurance coverage. Insurance plans vary widely in terms of coverage for periodontal treatments, further exacerbating disparities in access to care. Additionally, the complexity of periodontal disease treatment poses another challenge. Patients often require multiple visits and lengthy treatment regimens, which can be inconvenient and may affect patient compliance. The prolonged nature of treatment, combined with the need for ongoing care, can lead to suboptimal outcomes if patients fail to follow the prescribed regimen. Factors like poor patient adherence, underlying systemic health conditions, and inadequate treatment contribute to the recurrence of periodontal disease, making it a persistent challenge in dental healthcare.
Market Opportunities
Expanding Market for Preventive Care and Early Intervention
The growing global awareness of oral health presents significant opportunities for the periodontal disease market, especially in the area of preventive care and early intervention. Public health campaigns and increased access to online resources are educating people on the importance of maintaining oral hygiene and the link between periodontal disease and systemic health conditions like diabetes and heart disease. This heightened awareness is driving demand for preventive products, such as advanced toothbrushes, mouthwashes, and professional dental cleanings. Additionally, advancements in diagnostic tools, such as intraoral cameras and digital X-rays, offer opportunities for early detection, allowing healthcare providers to intervene before the disease reaches advanced stages. Early treatment can help mitigate the progression of periodontal disease, opening up opportunities for both traditional dental practices and innovative treatment solutions.
Technological Advancements and Emerging Markets
Technological innovations in dental care offer substantial opportunities for growth in the periodontal disease market. Laser therapies, regenerative treatments, and minimally invasive techniques are revolutionizing the way periodontal disease is managed, providing less invasive options with faster recovery times and improved outcomes. These innovations not only enhance patient satisfaction but also drive market demand for advanced treatments. Furthermore, emerging markets, particularly in regions with improving healthcare infrastructure, represent a growing opportunity for periodontal disease management. As access to dental care increases in these areas, the demand for both preventive and corrective treatments is expected to rise. The integration of insurance plans that cover periodontal treatments, along with government initiatives focused on expanding healthcare access, will further propel the market, making periodontal care more accessible to a broader population.
Market Segmentation Analysis:
By Type:
The global periodontal disease market is segmented by type, which includes Gingivitis, Chronic Periodontal Disease, Aggressive Periodontal Disease, Others, and Type 5. Gingivitis is the most common form of periodontal disease and is expected to dominate the market due to its high prevalence and ease of diagnosis. As an inflammatory condition, it primarily affects the gums and is typically reversible with proper treatment, driving demand for both preventive and therapeutic solutions. Chronic Periodontal Disease, often associated with aging and systemic health conditions, continues to see a rise in prevalence, fueling the demand for advanced treatments. Aggressive Periodontal Disease, characterized by rapid tissue destruction, represents a smaller yet significant segment, requiring aggressive intervention. The Others segment includes rare forms of periodontal disease, while Type 5 encompasses emerging classifications and conditions that are expected to evolve with further research.
By Application:
The market is also segmented by application into Non-surgical Treatment, Surgical Treatment, and other applications such as Application 3, Application 4, and Application 5. Non-surgical treatments are the most widely used approach due to their less invasive nature and effectiveness in managing early stages of periodontal disease. Techniques like scaling, root planing, and antimicrobial therapy drive this segment. Surgical treatments, however, are required for more advanced cases, involving procedures such as flap surgery and regenerative therapies. This segment is growing as the severity of periodontal diseases escalates. The Application 3, Application 4, and Application 5 segments represent specific innovations in treatment approaches or targeted applications, likely tied to new therapeutic methods or technologies under development. These segments are emerging as integral components in personalized and advanced treatment strategies, expanding the market's scope for addressing diverse periodontal conditions.
Segments:
Based on Type:
- Gingivitis
- Chronic Periodontal Disease
- Aggressive Periodontal Disease
- Others
- Type 5
Based on Application:
- Non-surgical Treatment
- Surgical Treatment
- Application 3
- Application 4
- Application 5
Based on Therapeutics:
- Systematic Antibiotics
- Local Antibiotics
- Therapeutics 3
- Therapeutics 4
- Therapeutics 5
Based on End Users:
- Hospitals
- Dental Clinic
- Dental Academics
- Research Institutes and Others
- End Users 5
Based on Distribution Channel:
- Distribution Channel 1
- Distribution Channel 2
- Distribution Channel 3
- Distribution Channel 4
- Distribution Channel 5
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America dominates the global periodontal disease market, holding a significant market share of over 40% in 2023. This region's leadership can be attributed to several factors, including advanced healthcare infrastructure, high awareness levels, and substantial investments in dental research and treatment. The growing prevalence of periodontal diseases, particularly chronic forms linked to lifestyle factors like smoking and poor oral hygiene, further supports market expansion. Additionally, the aging population in North America contributes to a higher demand for periodontal disease treatments, as older individuals are more prone to such conditions. The region is also characterized by high adoption of advanced diagnostic and treatment technologies, such as laser therapies, regenerative procedures, and minimally invasive surgical techniques. With an increasing number of dental clinics, hospitals, and specialized periodontal care centers, North America remains a key player in the periodontal disease market, and its growth is expected to continue due to strong healthcare spending and a well-established market for dental care services.
Asia-Pacific
The Asia-Pacific region is emerging as a significant growth area for the global periodontal disease market, with a market share of approximately 30% in 2023. This region's market is expected to grow at a faster rate compared to other regions, driven by the rising prevalence of periodontal diseases, particularly in developing countries like India and China. The growth in Asia-Pacific is fueled by improving healthcare access, increased awareness of oral health, and the adoption of advanced dental technologies. A large, aging population, combined with urbanization and changing lifestyles, has contributed to a higher incidence of periodontal diseases. Governments and health organizations in countries like Japan, China, and India are actively promoting oral hygiene practices, which is expected to boost demand for treatments and preventive measures. Additionally, with rising healthcare expenditures and expanding middle-class populations in countries like China and India, there is an increasing demand for both surgical and non-surgical treatments. As dental clinics and healthcare services continue to expand across the region, the Asia-Pacific market is poised for substantial growth in the coming years.
Key Player Analysis
- Bausch Health Companies Inc.
- Colgate-Palmolive Company
- Mylan N.V.
- Lyne Laboratories
- WOCKHARDT
- Xttrium Laboratories
- Sunstar Suisse S.A.
- 3M
- Izun Pharmaceuticals
- Tolmar Pharmaceuticals, Inc.
- Company 11
- Company 12
- Company 13
- Company 14
Competitive Analysis
The global periodontal disease market is highly competitive, with key players focusing on strategic partnerships, innovations, and regional expansions to maintain market share. Leading companies such as Bausch Health Companies Inc., Colgate-Palmolive Company, Mylan N.V., Lyne Laboratories, Wockhardt, Xttrium Laboratories, Sunstar Suisse S.A., 3M, Izun Pharmaceuticals, and Tolmar Pharmaceuticals, Inc. are making significant contributions to the market. Companies are focusing on innovation in both non-surgical and surgical treatments, aiming to improve patient outcomes and reduce the burden of periodontal diseases. Many players are investing in advanced diagnostic tools and therapeutic solutions, including laser therapies, regenerative procedures, and minimally invasive treatments. The competition is also driven by an increasing focus on expanding geographical presence, particularly in emerging regions where there is growing awareness about oral health and rising healthcare spending. Strategic collaborations, mergers, and acquisitions are being adopted to strengthen product portfolios and improve market positioning. Additionally, the market is witnessing significant investments in research and development, with players striving to introduce new treatments and products that cater to the evolving needs of patients. The integration of advanced technologies and the focus on cost-effective solutions further intensify competition in this dynamic market.
Recent Developments
- In September 2023, Bausch Health Companies Inc. and its oral health care division, OraPharma announced plans to team up with the League of United Latin American Citizens (LULAC), the biggest Hispanic group in the U.S. Their goal is to spread awareness about gum disease among Hispanic communities. This collaboration aims to help Hispanics better understand how to detect and treat gum disease.
- In June 2023, Eli Lilly and Company finalized an agreement to acquire DICE Therapeutics, Inc., a renowned biopharmaceutical firm recognized for its groundbreaking DELSCAPE technology platform. This platform is instrumental in creating novel oral therapeutic candidates, such as oral IL-17 inhibitors, which are presently in clinical development. These treatments are designed to target chronic immune-related diseases.
- In March 2023, Haleon initiated the #BetterOralCareNation campaign in Malaysia to enhance oral health practices across the country. The campaign seeks to raise awareness about the importance of oral hygiene and promote better oral care habits among Malaysians.
- In April 2023, Novo Nordisk collaborated with Aspect Biosystems, a company involved in bioprinting biomaterials, for the development of bioprinted tissue therapeutics for obesity and diabetes.
- In March 2022, Biocomposites signed an agreement with Zimmer Biomet to distribute the new genex Bone Graft Substitute. Genex Bone Graft Substitute is a biphasic composite of exceptional purity specifically formulated to balance osteoconductive scaffold strength and persistence in the body to enable the optimal remodeling of bone architecture.
- In February 2022, Envista Holding Corporation formed a strategic partnership with the Spanish Dental Service Organization- Vitaldent Group. This helps the company to become the preferred supplier of dental implants.
Market Concentration & Characteristics
The global periodontal disease market is characterized by moderate to high concentration, with a mix of established multinational companies and emerging players. The market is dominated by key companies that leverage advanced technologies, broad distribution networks, and extensive research and development (R&D) capabilities. These companies focus on offering a range of treatment options, from non-surgical therapies like scaling and root planing to innovative surgical procedures such as regenerative surgery and laser treatments. Market players emphasize providing effective, minimally invasive treatments that align with the growing demand for patient-centric solutions. The market is also influenced by a combination of factors such as an aging population, increased awareness of oral health, and advancements in dental technologies. In addition, the demand for affordable and accessible treatments is driving the growth of local players, particularly in emerging markets where healthcare infrastructure is expanding. As a result, the competitive landscape includes both global players with established reputations and regional companies aiming to tap into the increasing demand for periodontal disease treatments. Furthermore, companies are increasingly focused on collaboration and partnerships with dental professionals, hospitals, and research institutions to enhance product offerings and expand their market share.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Therapeutics, End Users, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The global periodontal disease market is expected to grow steadily due to increasing awareness of oral health and its link to systemic diseases.
- Advancements in diagnostic tools and treatment technologies, such as laser therapy and regenerative procedures, will drive market growth.
- The aging population will continue to be a major driver, as older individuals are more prone to periodontal disease.
- Non-surgical treatment options will see a rise in demand due to their convenience and less invasive nature.
- Market growth will be fueled by increasing healthcare expenditure and better insurance coverage for dental treatments.
- Emerging markets, particularly in Asia-Pacific and Latin America, will experience a surge in demand for affordable periodontal treatments.
- The rising popularity of dental tourism, driven by cost-effective treatment options, will contribute to market expansion.
- Increased focus on preventive care and early detection will help reduce the burden of periodontal disease globally.
- The development of targeted therapies and personalized treatments for periodontal disease will offer more effective management options.
- Collaboration between dental professionals and research institutions will foster innovation and improve the overall treatment landscape for periodontal disease.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Prevalence of Periodontal Disease
The global rise in periodontal disease, driven by aging populations and lifestyle factors such as smoking and poor oral hygiene, is leading to greater demand for both preventive and therapeutic solutions.
Rising Awareness of Oral Health
Public health campaigns and social media are boosting awareness of the link between oral and systemic health, encouraging more people to seek early diagnosis and treatment for periodontal conditions.
Technological Advancements in Diagnostics and Treatment
Innovations such as laser therapy, regenerative procedures, and advanced diagnostic tools are making periodontal care more effective, less invasive, and accessible, thereby expanding the market.
Growing Geriatric Population and Healthcare Expenditure
Older adults are more susceptible to periodontal disease, and as this demographic grows, so does the need for periodontal treatments, supported by increasing healthcare spending and insurance coverage.
Expansion in Emerging Markets
Improving healthcare infrastructure and rising awareness in Asia-Pacific and Latin America are opening new opportunities for market growth, especially as access to advanced dental care increases in these regions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Periodontal Disease Market?
What factors are driving the growth of the Global Periodontal Disease Market?
What are the key segments within the Global Periodontal Disease Market?
What are some challenges faced by the Global Periodontal Disease Market?
Who are the major players in the Global Periodontal Disease Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Gingivitis
- 1.2.2 Chronic Periodontal Disease
- 1.2.3 Aggressive Periodontal Disease
- 1.2.4 Others
- 1.2.5 Type 5
- 1.3 By End Users
- 1.3.1 Hospitals
- 1.3.2 Dental Clinic
- 1.3.3 Dental Academics
- 1.3.4 Research Institutes and Others
- 1.3.5 End Users 5
- 1.4 By Application
- 1.4.1 Non-surgical Treatment
- 1.4.2 Surgical Treatment
- 1.4.3 Application 3
- 1.4.4 Application 4
- 1.4.5 Application 5
- 1.5 By Therapeutics
- 1.5.1 Systematic Antibiotics
- 1.5.2 Local Antibiotics
- 1.5.3 Therapeutics 3
- 1.5.4 Therapeutics 4
- 1.5.5 Therapeutics 5
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 3,712.97 million → 2032: USD 6,256.85 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Periodontal Disease Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Periodontal Disease Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Periodontal Disease Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Periodontal Disease Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Periodontal Disease Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Periodontal Disease Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Periodontal Disease Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Periodontal Disease Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 3,712.97 million → 2032: USD 6,256.85 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Periodontal Disease Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Gingivitis
- 12.3.7.2 Chronic Periodontal Disease
- 12.3.7.3 Aggressive Periodontal Disease
- 12.3.7.4 Others
- 12.3.7.5 Type 5
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End Users - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals
- 12.4.7.2 Dental Clinic
- 12.4.7.3 Dental Academics
- 12.4.7.4 Research Institutes and Others
- 12.4.7.5 End Users 5
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Non-surgical Treatment
- 12.5.7.2 Surgical Treatment
- 12.5.7.3 Application 3
- 12.5.7.4 Application 4
- 12.5.7.5 Application 5
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Therapeutics - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Systematic Antibiotics
- 12.6.7.2 Local Antibiotics
- 12.6.7.3 Therapeutics 3
- 12.6.7.4 Therapeutics 4
- 12.6.7.5 Therapeutics 5
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Periodontal Disease End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Periodontal Disease Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Periodontal Disease Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Periodontal Disease Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Bausch Health Companies Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Colgate-Palmolive Company
- 18.4 3M
- 18.5 Sunstar Suisse S.A.
- 18.6 Mylan N.V.
- 18.7 WOCKHARDT
- 18.8 Xttrium Laboratories
- 18.9 Izun Pharmaceuticals
- 18.10 Tolmar Pharmaceuticals, Inc.
- 18.11 Lyne Laboratories
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

