
Market Overview:
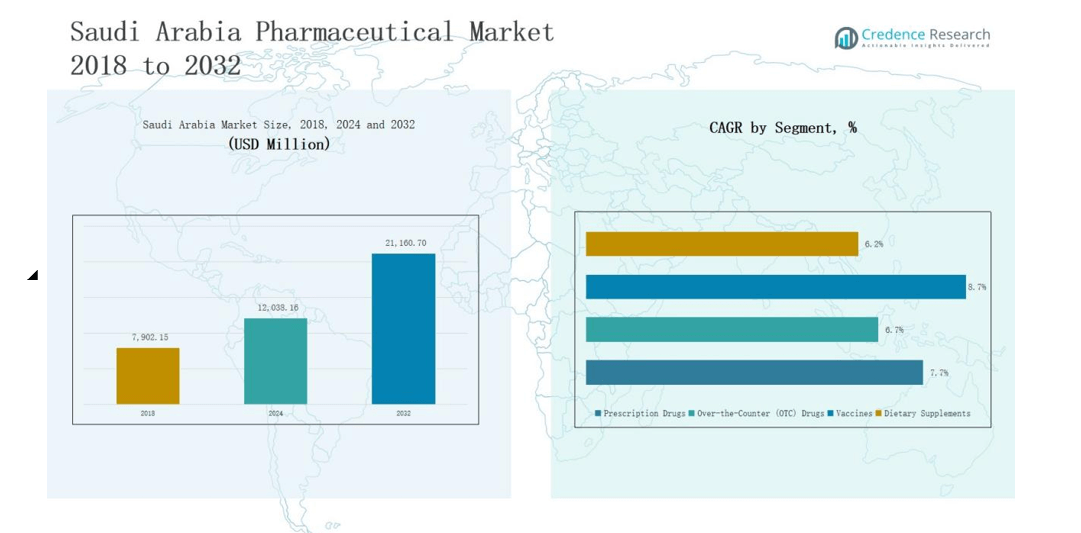
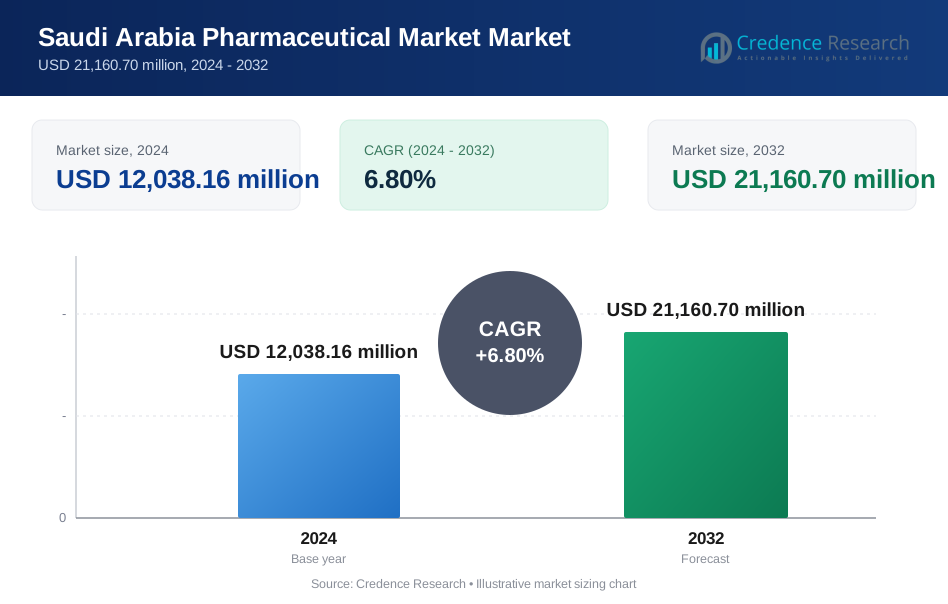
Saudi Arabia Pharmaceutical Market size was valued at USD 7,902.15 million in 2018 to USD 12,038.16 million in 2024 and is anticipated to reach USD 21,160.70 million by 2032, at a CAGR of 6.80% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Saudi Arabia Pharmaceutical Market Size 2024 | USD 12,038.16 million |
| Saudi Arabia Pharmaceutical Market, CAGR | 6.80% |
| Saudi Arabia Pharmaceutical Market Size 2032 | USD 21,160.70 million |
The Saudi Arabia Pharmaceutical Market is shaped by a mix of strong domestic manufacturers and multinational corporations. Leading local players such as Saudi Pharmaceutical Industries and Medical Appliances Corporation (SPIMACO), Tabuk Pharmaceuticals, Riyadh Pharma, and Al-Dawaa Pharmacies maintain a significant presence through generics, essential medicines, and extensive retail networks. Global leaders including Pfizer, Novartis, and GlaxoSmithKline (GSK) dominate advanced therapies, branded drugs, and specialty segments, leveraging innovation pipelines and strategic collaborations with regional firms. Among all regions, the Central Region emerged as the leader with 38% share in 2024, supported by Riyadh’s concentration of hospitals, research centers, and corporate headquarters that drive pharmaceutical demand. This combined competitive strength and regional dominance continue to underpin the market’s sustained growth trajectory.
Market Insights
- The Saudi Arabia Pharmaceutical Market grew from USD 7,902.15 million in 2018 to USD 12,038.16 million in 2024 and is forecasted to reach USD 21,160.70 million by 2032, reflecting steady expansion at a CAGR of 6.80%.
- Prescription drugs held 63% share in 2024, supported by chronic disease prevalence and government-backed healthcare reforms, while OTC drugs, vaccines, and dietary supplements captured 18%, 12%, and 7% respectively.
- Branded drugs led with 54% share in 2024, driven by physician preference and multinational innovation, whereas generics secured 36% and biosimilars gained 10% with increasing regulatory approvals.
- Oncology dominated with 29% share in 2024, followed by cardiology at 21% and diabetes at 17%, while neurology, respiratory, and other therapeutic areas accounted for the remaining 33% collectively.
- Regionally, the Central Region led with 38% share in 2024, followed by the Western Region at 27%, the Eastern Region at 22%, and the Southern Region at 13%, highlighting strong demand centers across the Kingdom.
Market Segment Insights
By Product Type
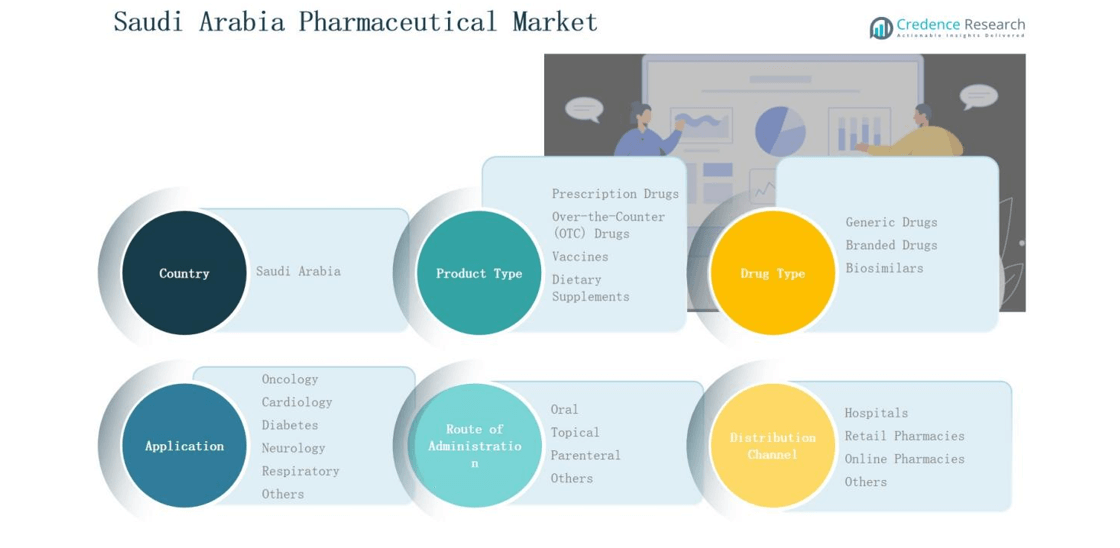
Prescription drugs dominated the Saudi Arabia pharmaceutical market with 63% share in 2024. Growth is driven by rising chronic disease prevalence, government support for advanced therapies, and increasing patient reliance on prescribed medication. Over-the-counter (OTC) drugs held 18% share, supported by demand for self-care and minor illness treatment. Vaccines accounted for 12% share, reflecting national immunization initiatives, while dietary supplements captured 7% share, fueled by growing consumer interest in preventive healthcare and wellness.
- For instance, AstraZeneca’s Tagrisso (osimertinib) has been adopted within the Saudi National Cancer Control Program to improve survival rates in lung cancer patients.
By Drug Type
Branded drugs led the market with 54% share in 2024, supported by strong physician preference, established trust, and innovative formulations from multinational companies. Generic drugs followed with 36% share, driven by affordability and government encouragement to reduce healthcare costs. Biosimilars, though emerging, held 10% share, gaining traction through regulatory approvals and wider adoption for biologic treatments.
- For instance, Teva Pharmaceuticals offers one of the largest generic portfolios globally, including generic versions of widely used drugs like atorvastatin for cholesterol management.
By Application
Oncology was the largest application segment, contributing 29% share in 2024, supported by increasing cancer incidence and the introduction of advanced targeted therapies. Cardiology followed with 21% share, reflecting high demand for cardiovascular treatments in an aging population. Diabetes accounted for 17% share, driven by one of the world’s highest regional prevalence rates. Neurology captured 12% share, supported by growing cases of neurological disorders. Respiratory drugs held 9% share, boosted by asthma and COPD cases, while other therapeutic areas combined contributed 12% share.
Market Overview
Rising Burden of Chronic Diseases
The increasing prevalence of chronic conditions such as diabetes, cardiovascular disorders, and cancer is a key growth driver for Saudi Arabia’s pharmaceutical market. With one of the highest global diabetes rates and rising obesity-linked complications, demand for advanced and continuous treatment is expanding. The government’s Vision 2030 healthcare reforms further accelerate pharmaceutical demand by improving access to diagnostics, specialized therapies, and patient-centric care. These factors strengthen reliance on prescription medicines and encourage multinational companies to expand therapeutic portfolios tailored to chronic disease management.
- For instance, in September 2021, AstraZeneca signed a Memorandum of Understanding (MoU) with the Saudi Ministry of Investment and the Ministry of National Guard Health Affairs in Riyadh.
Government Healthcare Investments and Reforms
Saudi Arabia’s strong investment in healthcare infrastructure under Vision 2030 plays a central role in market expansion. The government allocates substantial budgets to modernize hospitals, expand pharmaceutical distribution, and integrate advanced medical technologies. Regulatory bodies also accelerate drug approvals, encouraging faster access to innovative medicines. Furthermore, policies promoting local manufacturing and partnerships with global pharmaceutical leaders are increasing domestic production capacity. This combination of investments, policy support, and industry collaborations positions the country as a regional hub for pharmaceutical innovation and growth.
Expanding Local Manufacturing and Generic Adoption
The growing focus on local production of generics is driving cost efficiency and supply security in Saudi Arabia’s pharmaceutical sector. Domestic companies, supported by government incentives, are scaling up facilities to reduce reliance on imports and improve drug availability. Generics, known for affordability, are gaining wider acceptance among physicians and patients, particularly in managing chronic diseases. Increased manufacturing capabilities also open avenues for exporting regionally. This shift not only supports healthcare affordability but also strengthens the Kingdom’s pharmaceutical self-sufficiency in line with Vision 2030 goals.
- For instance, Jamjoom Pharma, headquartered in Jeddah, has increased local production of generic ophthalmology and dermatology drugs, which are now widely prescribed in government hospitals.
Key Trends & Opportunities
Digital Transformation and E-Pharmacies
Digital healthcare is rapidly transforming the Saudi pharmaceutical landscape. Online pharmacies and telemedicine platforms are expanding, offering convenient access to medicines and consultations. Consumers increasingly prefer e-pharmacies for prescription refills, OTC drugs, and dietary supplements due to convenience and home delivery. Government endorsement of digital healthcare systems under Vision 2030 further enhances trust in online distribution. This trend presents significant opportunities for pharmaceutical firms to invest in digital platforms, strengthen customer engagement, and capture growing demand for technology-driven healthcare solutions in the Kingdom.
- For instance, Al Nahdi Medical Company, a leading retail pharmacy chain in Saudi Arabia, has expanded its NahdiCare Clinics and digital pharmacy services, enabling patients to consult doctors virtually and order chronic medication refills directly via its online platform.
Rising Demand for Specialty and Biologic Drugs
The increasing adoption of specialty and biologic drugs represents a major opportunity in the Saudi market. High incidence of oncology, autoimmune, and neurological disorders is driving demand for innovative biologics and targeted therapies. Regulatory support for biosimilars further complements market expansion by offering cost-effective alternatives to high-priced biologics. Multinational firms are entering partnerships with Saudi companies to enhance access to advanced therapies. With healthcare reforms encouraging innovation, specialty drugs and biosimilars are set to gain a stronger foothold, improving patient outcomes and expanding revenue opportunities.
- For instance, Saudi Food and Drug Authority (SFDA) approvals of biosimilars like Amgen’s adalimumab biosimilar (Amgevita) have given patients with autoimmune disorders affordable treatment options.
Key Challenges
Pricing Pressure and Cost Containment Policies
Despite market growth, pricing pressure remains a critical challenge in Saudi Arabia’s pharmaceutical sector. The government actively regulates drug prices to maintain affordability and reduce healthcare spending. While beneficial for patients, these policies limit profit margins for manufacturers and distributors. Generic competition further intensifies pricing challenges, especially for multinational companies that depend on branded medicines. The focus on cost containment makes it essential for companies to balance innovation with affordability, often requiring partnerships or local manufacturing strategies to sustain long-term profitability.
Supply Chain and Import Dependency
A significant challenge for Saudi Arabia is its dependency on imports for many pharmaceutical products, particularly advanced biologics and specialty drugs. Global supply chain disruptions, such as those witnessed during the pandemic, highlight the risks of reliance on external suppliers. Delays in shipments and shortages can hinder patient access to critical medicines. Although local manufacturing is expanding, it is not yet sufficient to meet the entire demand. Addressing these vulnerabilities requires accelerated investment in domestic production and regional supply chain diversification.
Regulatory and Market Entry Barriers
Strict regulatory requirements and lengthy approval processes can act as barriers for pharmaceutical companies entering the Saudi market. While reforms are improving transparency, compliance with complex regulations remains time-consuming and resource-intensive. Multinational firms often face challenges aligning global practices with local standards, delaying product launches. Furthermore, competition from well-established domestic firms adds to the difficulty of market penetration. Overcoming these hurdles requires strategic partnerships, investment in regulatory expertise, and alignment with national healthcare priorities to ensure successful market entry and sustained growth.
Regional Analysis
Central Region
The Central Region accounted for 38% share of the Saudi Arabia Pharmaceutical Market in 2024, supported by the dominance of Riyadh as the capital and medical hub. Major hospitals, research centers, and corporate headquarters strengthen pharmaceutical consumption in this area. It benefits from government-driven healthcare reforms and strong investment in hospital infrastructure. The presence of multinational pharmaceutical firms and local players ensures widespread drug availability. Retail and hospital pharmacies remain the primary distribution channels. Demand for oncology and cardiology drugs is particularly strong in this region.
Western Region
The Western Region held 27% share of the Saudi Arabia Pharmaceutical Market in 2024. The cities of Jeddah and Makkah play a crucial role due to large populations and high medical tourism. Seasonal healthcare demand rises with millions of pilgrims traveling to the area each year, supporting increased pharmaceutical consumption. Hospitals and retail pharmacies remain vital in fulfilling demand. This region also records strong sales of OTC drugs and vaccines, driven by preventive healthcare practices. Pharmaceutical distributors continue to expand networks to cater to both residents and visiting populations.
Eastern Region
The Eastern Region contributed 22% share of the Saudi Arabia Pharmaceutical Market in 2024. Its significance comes from a concentration of expatriates and industrial hubs, which require advanced healthcare facilities. The region’s hospitals and clinics are highly equipped, driving demand for branded and specialty drugs. Chronic diseases such as diabetes and cardiovascular disorders remain key therapeutic focus areas. Retail and online pharmacies show steady growth as consumers increasingly seek convenient access to medicines. The region benefits from government-backed investment in healthcare to support its growing population.
Southern Region
The Southern Region represented 13% share of the Saudi Arabia Pharmaceutical Market in 2024. Pharmaceutical growth here is relatively moderate compared to other regions due to smaller urban populations and fewer large-scale hospitals. However, the government continues to invest in strengthening healthcare accessibility in rural and semi-urban areas. OTC drugs and dietary supplements see higher traction, as preventive health awareness spreads. Local pharmacies and hospital networks are expanding to improve drug penetration. It remains an emerging growth area with potential for further investment in infrastructure and distribution.
Market Segmentations:
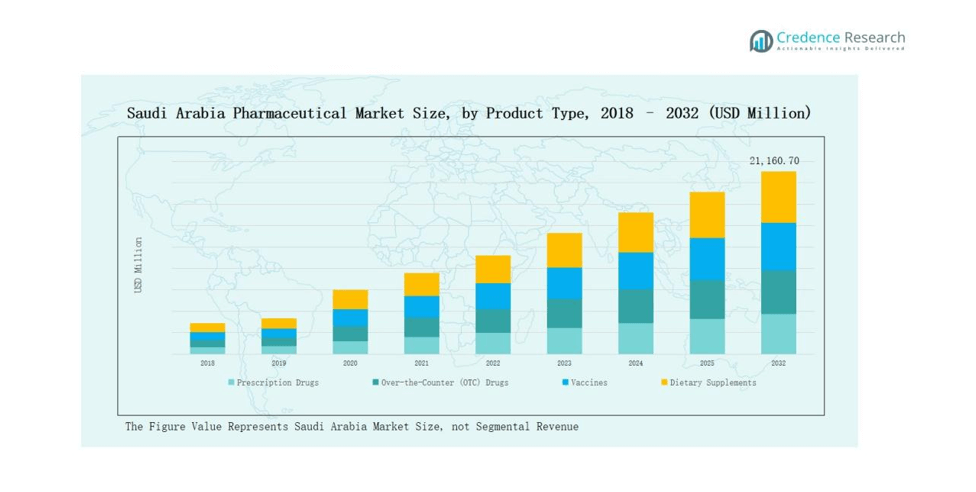
By Product Type
- Prescription Drugs
- Over-the-Counter (OTC) Drugs
- Vaccines
- Dietary Supplements
By Drug Type
- Generic Drugs
- Branded Drugs
- Biosimilars
By Application
- Oncology
- Cardiology
- Diabetes
- Neurology
- Respiratory
- Others
By Route of Administration
- Oral
- Topical
- Parenteral
- Others
By Distribution Channel
- Hospitals
- Retail Pharmacies
- Online Pharmacies
- Others
By Region
- Central region
- Western Region
- Eastern Region
- Southern Region
Competitive Landscape
The Saudi Arabia Pharmaceutical Market is highly competitive, with a mix of domestic firms and multinational corporations shaping industry dynamics. Local leaders such as SPIMACO, Tabuk Pharmaceuticals, and Riyadh Pharma maintain strong positions by producing generics and essential drugs aligned with national healthcare priorities. Multinational players including Pfizer, Novartis, and GSK dominate branded and specialty drug categories, leveraging global innovation pipelines and strategic partnerships. Al-Dawaa Pharmacies adds strength on the retail side, operating one of the largest pharmacy networks in the Kingdom. Companies compete through expansion of product portfolios, collaborations with government agencies, and investments in manufacturing to reduce import dependency. Growing interest in biosimilars and specialty therapies further intensifies competition, pushing firms to balance affordability with innovation. The market’s regulatory environment also encourages local–global partnerships, ensuring technology transfer and advanced product availability. Collectively, this diverse competitive base sustains growth and drives continuous advancement in the Kingdom’s pharmaceutical sector.
Key Players
- Saudi Pharmaceutical Industries and Medical Appliances Corporation (SPIMACO)
- Al-Dawaa Pharmacies
- Tabuk Pharmaceuticals
- Pfizer
- Riyadh Pharma
- Novartis
- GSK (GlaxoSmithKline)
Recent Developments
- In August 2025, Agios’ PYRUKYND® (mitapivat) received approval in Saudi Arabia for treating adult patients with thalassemia, expanding access to innovative rare disease therapies.
- In May 2025, Saudi Arabia’s Public Investment Fund (Lifera) partnered with Novo Nordisk to localize the production of insulin and GLP-1 medications, boosting domestic manufacturing capabilities.
- In December 2024, Bio-Thera Solutions partnered with Tabuk Pharmaceuticals to exclusively manufacture, distribute, and market the ustekinumab biosimilar BAT2206 in Saudi Arabia.
- In June 2025, King Faisal Specialist Hospital & Research Centre (KFSHRC) and Germfree Laboratories announced the establishment of the first Advanced Therapy Medicinal Product (ATMP) Manufacturing Campus in Riyadh.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Drug Type, Application, Route of Administartion, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for chronic disease therapies will continue to drive prescription drug growth.
- Government reforms will expand local pharmaceutical manufacturing capacity across key regions.
- Adoption of generics will rise as cost efficiency remains a priority in healthcare policy.
- Specialty and biologic drugs will gain traction with increasing cancer and autoimmune cases.
- Digital healthcare platforms will strengthen online pharmacy penetration and patient accessibility.
- Partnerships between global firms and local companies will expand innovation and technology transfer.
- Preventive healthcare will boost demand for vaccines and dietary supplements across demographics.
- Regulatory frameworks will become more transparent, supporting faster drug approvals and market entry.
- Distribution networks will strengthen with hospital and retail pharmacies expanding into underserved areas.
- Investments in research and clinical trials will position the Kingdom as a regional pharmaceutical hub.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Burden of Chronic Diseases
The high and increasing prevalence of chronic conditions such as diabetes, cardiovascular diseases, and cancer in Saudi Arabia is driving sustained demand for pharmaceuticals, particularly prescription and specialty drugs. This trend is further supported by government initiatives to improve chronic disease management and patient access to advanced therapies.
Government Healthcare Investments and Vision 2030 Reforms
Substantial government investment in healthcare infrastructure and reforms under Vision 2030 are modernizing hospitals, expanding pharmaceutical distribution, and accelerating drug approvals. These efforts are making innovative medicines more accessible and encouraging both local manufacturing and international partnerships.
Expansion of Local Manufacturing and Generic Adoption
Government incentives and policies are boosting domestic production of generic drugs, reducing reliance on imports and improving drug affordability. This shift supports healthcare cost containment and enhances the Kingdom’s pharmaceutical self-sufficiency, aligning with national strategic goals.
Digital Transformation and E-Pharmacy Growth
The rapid adoption of digital healthcare platforms, including online pharmacies and telemedicine, is increasing patient access to medicines and consultations. Government support for digital health under Vision 2030 is fostering trust in e-pharmacies and expanding the reach of pharmaceutical products across the country.
Rising Demand for Specialty and Biologic Drugs
Growing incidence of oncology, autoimmune, and neurological disorders is fueling demand for innovative biologics and specialty drugs. Regulatory support for biosimilars and partnerships between multinational and local firms are expanding access to advanced therapies and driving market growth in these high-value segments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Saudi Arabia pharmaceutical market?
What are the key drivers of growth in the Saudi Arabian pharmaceutical market?
How does the Saudi government support the pharmaceutical sector?
What is the position of Saudi Arabia in the GCC pharmaceutical market?
How does Saudi Arabia’s proximity to global pharmaceutical hubs affect its market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Drug Type
- 1.2.1 Branded Drugs
- 1.2.2 Generic Drugs
- 1.2.3 Biosimilars
- 1.3 By Application
- 1.3.1 Oncology
- 1.3.2 Cardiology
- 1.3.3 Diabetes
- 1.3.4 Neurology
- 1.3.5 Respiratory
- 1.3.6 Others
- 1.4 By Product Type
- 1.4.1 Prescription Drugs
- 1.4.2 Over-the-Counter (OTC) Drugs
- 1.4.3 Vaccines
- 1.4.4 Dietary Supplements
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 12,038.16 million → 2032: USD 21,160.70 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Saudi Arabia Pharmaceutical Market Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Saudi Arabia Pharmaceutical Market Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Saudi Arabia Pharmaceutical Market Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Saudi Arabia Pharmaceutical Market Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Saudi Arabia Pharmaceutical Market Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Saudi Arabia Pharmaceutical Market Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Saudi Arabia Pharmaceutical Market Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Saudi Arabia Pharmaceutical Market Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 12,038.16 million → 2032: USD 21,160.70 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Saudi Arabia Pharmaceutical Market Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Drug Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Branded Drugs
- 12.3.7.2 Generic Drugs
- 12.3.7.3 Biosimilars
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Oncology
- 12.4.7.2 Cardiology
- 12.4.7.3 Diabetes
- 12.4.7.4 Neurology
- 12.4.7.5 Respiratory
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Prescription Drugs
- 12.5.7.2 Over-the-Counter (OTC) Drugs
- 12.5.7.3 Vaccines
- 12.5.7.4 Dietary Supplements
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Saudi Arabia Pharmaceutical Market End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Saudi Arabia Pharmaceutical Market Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Saudi Arabia Pharmaceutical Market Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Saudi Arabia Pharmaceutical Market Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Saudi Pharmaceutical Industries and Medical Appliances Corporation (SPIMACO)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Al-Dawaa Pharmacies
- 18.4 Tabuk Pharmaceuticals
- 18.5 Pfizer
- 18.6 Riyadh Pharma
- 18.7 Novartis
- 18.8 GSK (GlaxoSmithKline)
- 18.9 AstraZeneca
- 18.10 Jamjoom Pharma
- 18.11 Teva Pharmaceuticals
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

