
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Canada Retail Pharmacy Market Size 2024 | SD 39,810.35 million |
| Canada Retail Pharmacy Market, CAGR | 3.08% |
| Canada Retail Pharmacy Market Size 2032 | USD 50,732.50 million |
Market Overview
The Canada Retail Pharmacy Market is projected to grow from USD 39,810.35 million in 2024 to an estimated USD 50,732.50 million by 2032, with a compound annual growth rate (CAGR) of 3.08% from 2025 to 2032. This growth is driven by factors such as an aging population, increasing prevalence of chronic diseases, and rising demand for healthcare services.
Key drivers of the market include the expanding geriatric population, which necessitates more frequent medication use, and the increasing incidence of chronic conditions like diabetes, hypertension, and arthritis. Additionally, advancements in digital health technologies, such as telepharmacy and online prescription services, are enhancing accessibility and convenience for consumers. The integration of these technologies is expected to further propel market growth by improving patient engagement and medication adherence.
Geographically, the retail pharmacy market is concentrated in urban centers across Canada, with provinces like Ontario and Quebec housing the majority of retail pharmacy outlets. Major players in the market include McKesson Canada, Shoppers Drug Mart (a subsidiary of Loblaw Companies), and Jean Coutu Group (operated by Metro Inc.). These companies dominate the market through extensive networks of retail locations and a broad range of pharmacy services, positioning them as key contributors to the sector's growth.
Market Insights
- The Canada Retail Pharmacy Market is projected to grow from USD 39,810.35 million in 2024 to USD 50,732.50 million by 2032, at a CAGR of 3.08% from 2025 to 2032.
- The Global Retail Pharmacy Market is expected to grow from USD 14,45,920.00 million in 2024 to USD 19,65,958.05 million by 2032, at a CAGR of 3.92% from 2025 to 2032.
- The increasing aging population is driving demand for prescription medications and healthcare services, contributing significantly to market growth.
- The rising prevalence of chronic diseases such as diabetes, hypertension, and arthritis is boosting the need for long-term medication management, expanding the retail pharmacy market.
- Advancements in telepharmacy and online prescription services are improving accessibility and convenience, leading to greater market adoption and growth.
- Ongoing regulatory changes and reimbursement pressures on pharmacies can limit profitability and operational flexibility, posing challenges to market players.
- Ontario and Quebec hold the largest market shares, driven by urbanization, population density, and high demand for pharmaceutical services in these provinces.
- Smaller provinces and rural areas are witnessing growth through digital solutions like mail-order and online pharmacies, which are enhancing accessibility and service delivery.
Report Scope
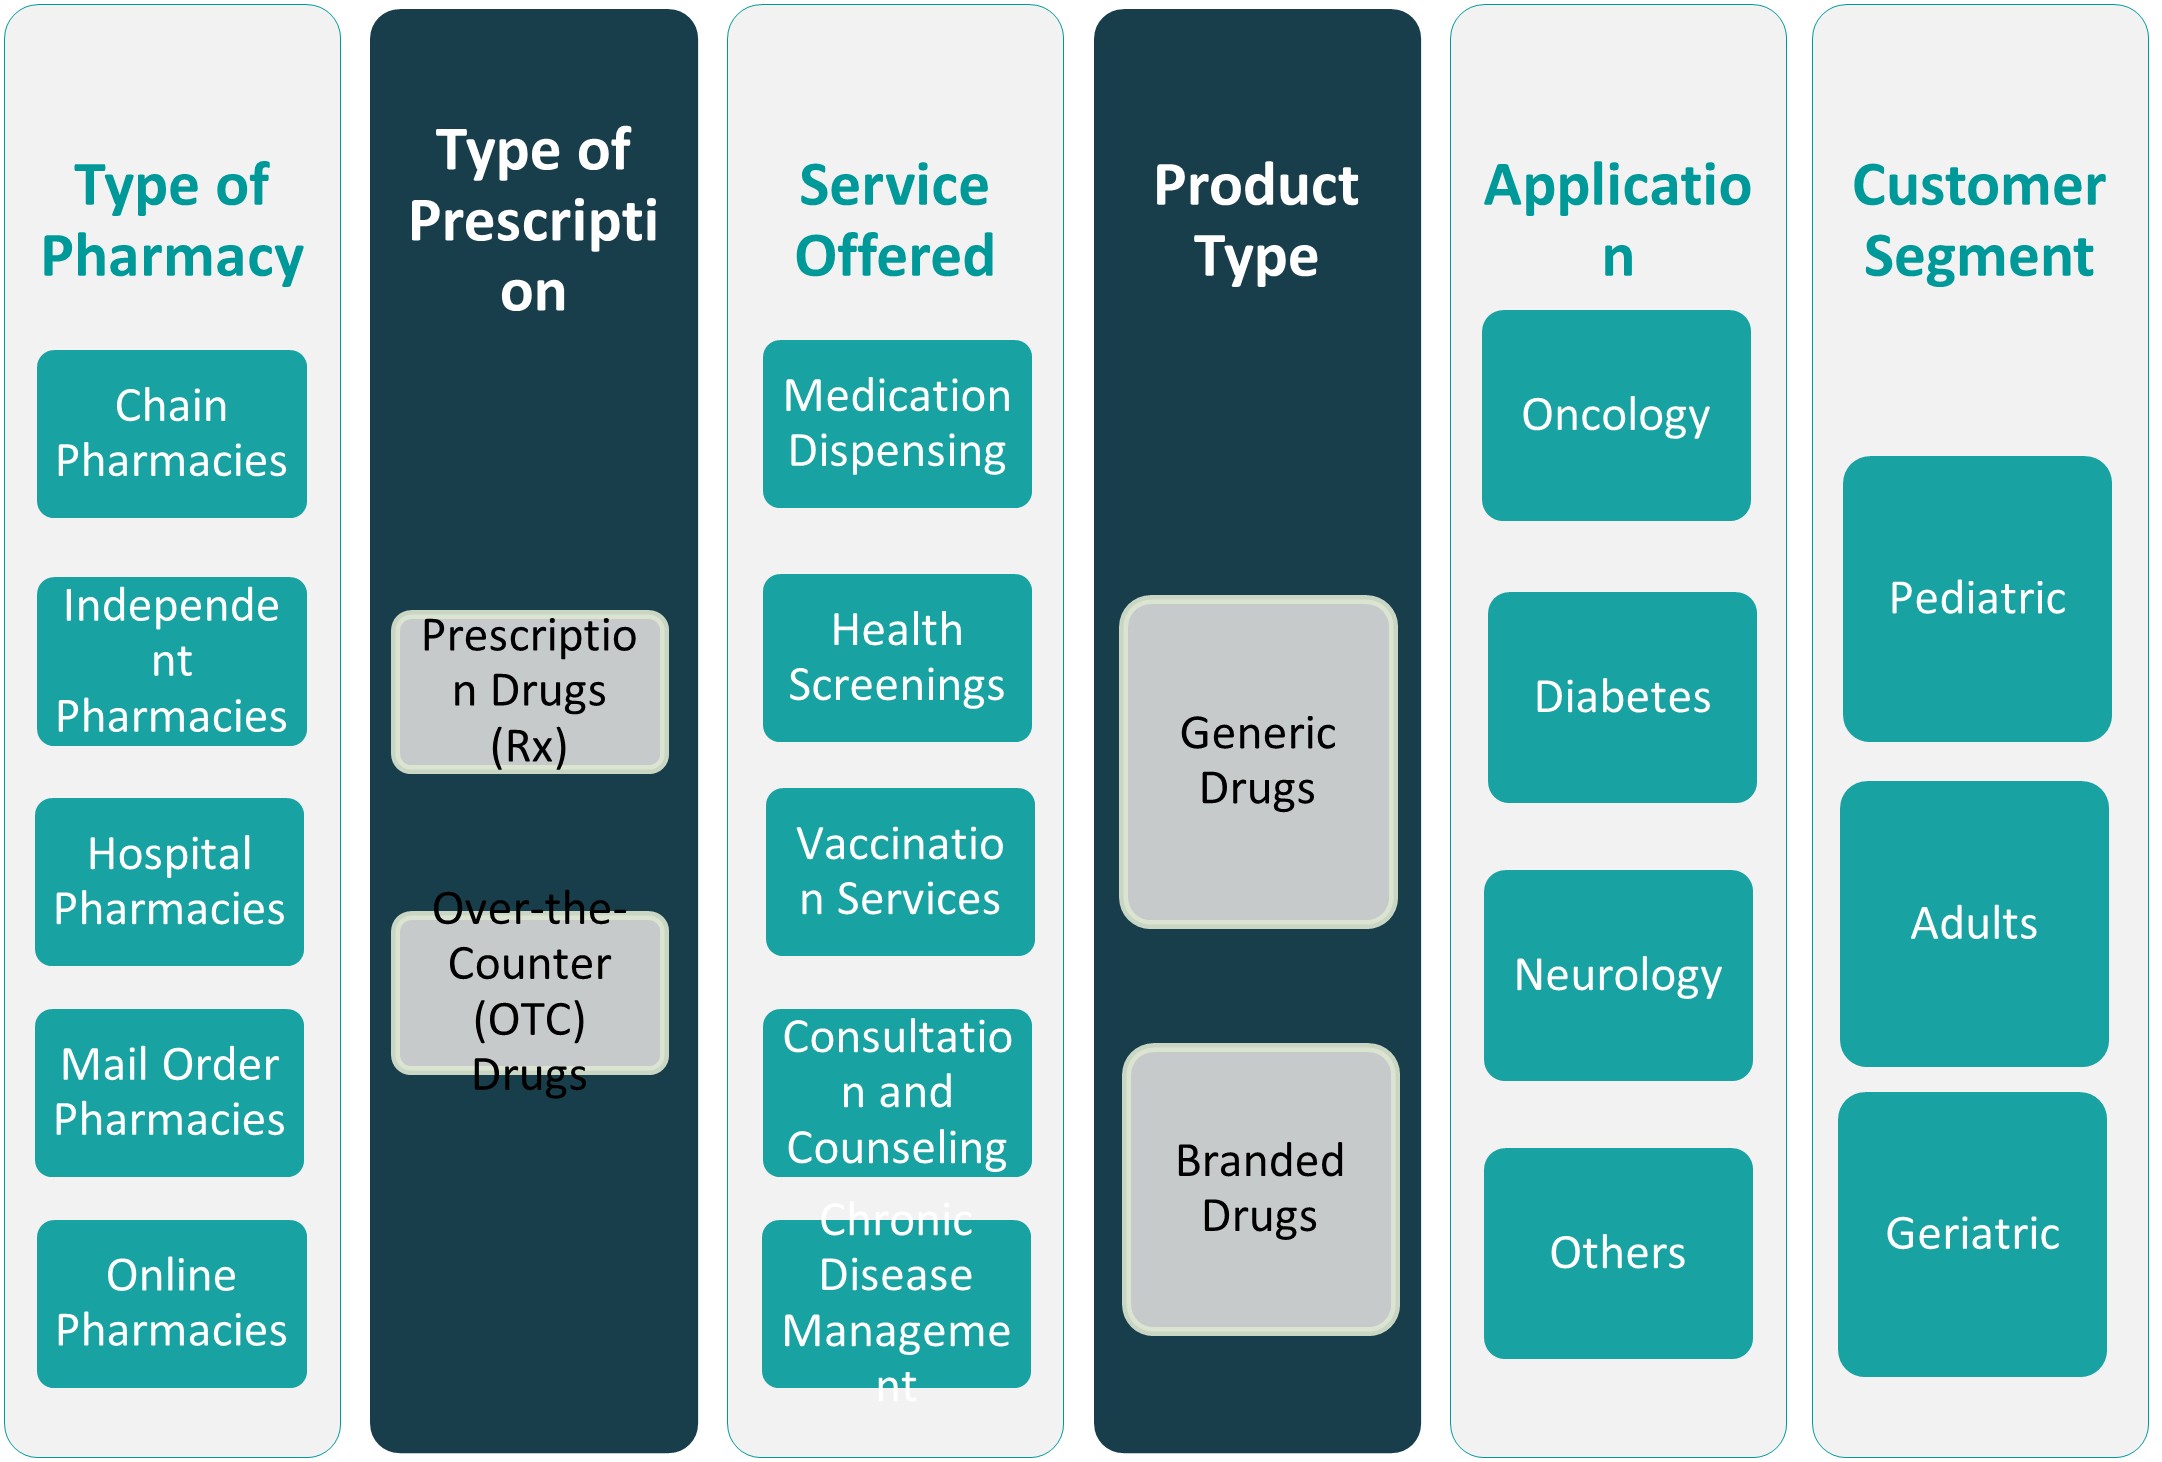
This report segments the Canada Retail Pharmacy Market as follows:
Market Drivers
Advancements in Digital Health Technologies
Digital health adoption is reshaping the Canada retail pharmacy sector as pharmacies combine e-prescriptions, online refills, app-based reminders, virtual pharmacist consultations and home delivery to make medication access more convenient and continuous. This is especially relevant in rural and mobility-constrained communities, where telepharmacy and electronic prescription workflows reduce travel needs while improving speed, traceability and patient safety. A strong supporting indicator is Canada Health Infoway’s PrescribeIT program, which connects prescribers directly with pharmacy management systems to transmit prescriptions electronically, helping reduce lost, fraudulent or misused prescriptions and strengthening medication-management workflows across the care pathway. Retail pharmacies are using these digital capabilities to improve refill adherence, automate reminders, manage inventory more efficiently and expand service reach beyond store walls. As Canadian consumers increasingly expect healthcare to operate with the same ease as retail banking or e-commerce, pharmacies that integrate mobile engagement, secure digital records and remote pharmacist access are better positioned to retain customers and become everyday health-management platforms.
Government Support for Healthcare Services
Government-backed healthcare programs and pharmacy-service policies continue to reinforce the Canada retail pharmacy sector by improving access to medicines, supporting pharmacist-led care and strengthening public confidence in community-based healthcare delivery. Provincial drug plans such as Ontario Drug Benefit and BC PharmaCare help eligible populations manage medication affordability, while public health programs create demand for vaccination, smoking cessation, wellness counselling and preventive products. A useful supporting benchmark comes from the Canadian Institute for Health Information, which reported 48,450 licensed pharmacists in Canada in 2024, including 29,399 employed in direct patient care, underscoring the depth of the professional workforce available to deliver government-enabled pharmacy services. This capacity allows pharmacies to participate more actively in publicly funded vaccination campaigns, minor ailment assessment, medication reviews and chronic-care support. By aligning reimbursement, professional scope and access objectives, governments are helping pharmacies move from a dispensing-first model toward a trusted front-line care model, which improves convenience for patients and relieves pressure on physicians, clinics and hospitals.
Aging Population and Increased Healthcare Needs
Canada’s aging population is intensifying demand for retail pharmacy services because older adults typically require more prescriptions, medication reviews, adherence support, vaccination access, mobility aids and counselling for complex therapy regimens. This demographic shift is already visible: Statistics Canada reported that about 7.6 million Canadians were aged 65 and older on July 1, 2023, representing 18.9 percent of the national population, and projected that seniors could account for 21.4 percent to 23.4 percent by 2030. For retail pharmacies, this creates recurring prescription traffic and stronger demand for services such as blister packaging, home delivery, medication synchronization, chronic pain support and pharmacist-led therapy optimization. The opportunity is not only transactional; older patients often value trusted, local advice and frequent interaction with healthcare professionals. Pharmacies that build geriatric-focused service models can improve safety around polypharmacy, support aging in place and strengthen loyalty among seniors and caregivers, making community pharmacies essential partners in Canada’s broader healthcare system.
Prevalence of Chronic Diseases
The rising burden of chronic illness is a major structural driver for the Canada retail pharmacy sector, as patients with diabetes, hypertension, cardiovascular conditions, respiratory diseases and arthritis rely on frequent prescription refills, monitoring tools, OTC support and pharmacist counselling. The Public Health Agency of Canada has reported that 3 in 5 Canadians aged 20 and older live with a chronic disease and 4 in 5 are at risk of developing one, highlighting the scale of ongoing medication and disease-management needs across the country. This creates a steady role for pharmacies in adherence improvement, medication therapy reviews, refill synchronization, blood pressure monitoring, diabetes education and vaccine promotion for vulnerable groups. As healthcare systems prioritize prevention and outpatient management, retail pharmacies are becoming practical extensions of chronic-care delivery because they are accessible, familiar and frequently visited. By expanding counselling, screening and digital adherence tools, pharmacies can help re
Market Trends
Increasing Role of Pharmacists in Chronic Disease Management
Pharmacists in Canada are increasingly recognized for their role in chronic disease management. As the prevalence of chronic conditions like diabetes, hypertension, and cardiovascular diseases rises, pharmacists are playing a critical role in managing these diseases by providing medication counseling, monitoring patient adherence, and offering lifestyle advice. Many retail pharmacies are expanding their services to include comprehensive medication therapy management (MTM), where pharmacists assess a patient's entire medication regimen and provide guidance on how to optimize treatment. This trend is driving greater collaboration between pharmacists, physicians, and other healthcare providers to ensure holistic care for patients. By enhancing their role in chronic disease management, pharmacists help improve patient outcomes and reduce the overall burden on the healthcare system, positioning retail pharmacies as essential players in the healthcare delivery model.
Emphasis on Sustainability and Eco-Friendly Practices
Sustainability has become an important trend in the Canadian retail pharmacy market, driven by both consumer demand and regulatory pressures. Pharmacies are increasingly adopting eco-friendly practices, from reducing plastic waste by offering reusable bags to implementing more energy-efficient store designs. Additionally, many retail pharmacies are shifting towards sustainable packaging for their OTC products and prescription medications. This move not only aligns with growing environmental concerns but also responds to the expectations of environmentally conscious consumers. Green initiatives, such as the recycling of pharmaceutical waste and the use of renewable energy sources in pharmacy operations, are becoming more prevalent. Furthermore, some pharmacies are expanding their product lines to include organic and eco-friendly health products, catering to consumers who prioritize sustainability in their purchasing decisions. This trend is expected to continue as both consumers and businesses embrace environmentally responsible practices.
Growth of Online Pharmacy Services
The Australian retail pharmacy market is increasingly witnessing a shift towards digital platforms. With the rise of e-commerce, more consumers are turning to online pharmacies for convenience, competitive pricing, and accessibility. For instance, during the COVID-19 pandemic, online pharmacy services in Australia saw a significant surge, with some platforms reporting a 200% increase in orders for prescription medications and health products. Retail pharmacies are responding by enhancing their digital infrastructure and offering services like e-prescriptions, online consultations, and automated prescription refills. Furthermore, the integration of mobile applications for managing medications, booking appointments, and tracking health metrics is further boosting the growth of online pharmacy services. This trend is expected to continue, with a rising number of pharmacies adopting e-commerce models to meet consumer demand for flexibility and convenience.
Expansion of Health and Wellness Offerings
The growing demand for health and wellness products is another prominent trend in Australia’s retail pharmacy market. Consumers are becoming increasingly health-conscious, seeking out products that contribute to long-term well-being and prevent the onset of chronic diseases. For example, sales of vitamins and supplements in Australian pharmacies increased by approximately 15% in the past year, reflecting the rising interest in preventive health solutions. Pharmacies are also incorporating fitness-related products like fitness trackers, sports nutrition, and personal care items into their offerings. The demand for holistic health solutions, which focus on both physical and mental well-being, is driving this expansion, and retail pharmacies are positioning themselves as one-stop shops for all health-related needs.
Market Challenges
Regulatory and Reimbursement Pressures
One of the key challenges facing the Australian retail pharmacy market is the intense price competition, particularly in an environment of rising operational costs and margin pressures. Pharmacies are faced with the challenge of maintaining profitability while offering competitive pricing to attract consumers. The growing popularity of online pharmacies has intensified price competition, as these platforms often provide lower prices and the convenience of home delivery. Traditional brick-and-mortar pharmacies are struggling to compete with these online services, especially in a market where consumers are increasingly price-sensitive and value-driven. Additionally, the Pharmaceutical Benefits Scheme (PBS) in Australia, which provides subsidized prices for certain prescription medications, creates pressure on pharmacies to adjust their pricing strategies while managing government regulations.
The pricing structure in the Australian retail pharmacy market is tightly regulated, and as a result, pharmacies have limited flexibility in setting prices for prescription drugs, which affects their profit margins. This challenge is compounded by increasing operational expenses, including rent, wages, and the cost of technology adoption. For instance, Australian pharmacies, on average, spend approximately $200,000 annually on wages, reflecting the high cost of retaining staff in the sector. These factors make it difficult for pharmacies to sustain high-profit margins. As a result, retail pharmacies are forced to find innovative ways to differentiate themselves, such as by offering additional services or expanding their product range, in order to maintain customer loyalty and competitiveness.
Competition from E-Pharmacies and Online Healthcare Platforms
The rise of e-pharmacies and online healthcare platforms represents another significant challenge for the Canada Retail Pharmacy Market. With the growing demand for convenience, many consumers are turning to online platforms to purchase medications and health products, bypassing traditional brick-and-mortar pharmacies. E-pharmacies offer the advantage of home delivery, competitive pricing, and 24/7 accessibility, making them a preferred choice for tech-savvy consumers, especially in urban areas where consumers have more access to digital health services. The COVID-19 pandemic accelerated this shift, as people became more accustomed to shopping for medications online and using telehealth services for consultations. While traditional retail pharmacies have adapted by establishing their own online services and expanding their digital presence, they continue to face stiff competition from e-pharmacies that often have lower overhead costs and more streamlined operations.
Furthermore, large online retailers like Amazon have entered the healthcare space, providing additional competition for local pharmacies. To stay competitive, traditional retail pharmacies must invest in digital technologies such as telepharmacy services, e-prescriptions, and user-friendly online platforms. Additionally, offering personalized services, such as medication therapy management and health consultations, can help retail pharmacies differentiate themselves. However, this requires significant investment and strategic planning, making it a challenge for smaller, independent pharmacies to keep pace with the digital transformation of the industry. The continued rise of online competitors poses a long-term challenge to traditional retail pharmacy models, compelling them to innovate or risk losing market share.
Market Opportunities
Expansion of Health and Wellness Services
One of the key market opportunities in the Canada Retail Pharmacy Market lies in the expansion of health and wellness services. As consumers become more health-conscious and proactive in managing their well-being, pharmacies have the opportunity to diversify their offerings beyond traditional prescription dispensing. Retail pharmacies can expand their role as healthcare hubs by offering services such as immunizations, cholesterol screenings, blood pressure monitoring, and chronic disease management programs. These services not only enhance customer engagement but also provide additional revenue streams. Moreover, pharmacies can cater to the growing demand for preventive care, which is becoming increasingly important as Canada's aging population seeks solutions to manage long-term health. The integration of wellness programs into pharmacy offerings can also strengthen customer loyalty, as patients often prefer pharmacies that provide a one-stop solution for both healthcare and personal well-being. By investing in wellness services, retail pharmacies can tap into the expanding demand for non-prescription health products, including vitamins, dietary supplements, and natural health remedies, further broadening their product portfolio.
Adoption of Digital Health Solutions
Another significant market opportunity for retail pharmacies in Canada is the adoption of digital health solutions. The increasing reliance on technology for healthcare management presents an opportunity for pharmacies to enhance service delivery through online platforms, telepharmacy, and digital prescription management. With more Canadians seeking convenient, accessible healthcare, retail pharmacies can offer home delivery services for medications, online prescription refills, and virtual consultations with pharmacists. Additionally, integrating technologies such as AI-driven medication reminders, health tracking apps, and e-prescriptions can improve patient adherence to prescribed treatments, driving long-term customer relationships. The rise of digital health also supports pharmacy business models in underserved areas, where access to physical stores may be limited. As the demand for digital health services continues to grow, retail pharmacies that embrace these technologies are well-positioned to capture market share and deliver enhanced, convenient healthcare services.
Market Segmentation Analysis
By Type of Pharmacy
The Canada Retail Pharmacy Market is segmented by the type of pharmacy, including chain pharmacies, independent pharmacies, hospital pharmacies, mail-order pharmacies, and online pharmacies. Chain pharmacies dominate the market, benefiting from established networks, brand recognition, and economies of scale. These pharmacies have widespread locations across urban and rural areas, which enables them to reach a broad customer base. Independent pharmacies, while smaller in scale, offer personalized services and cater to local communities, often fostering long-term relationships with their customers. Hospital pharmacies primarily serve in-patients and outpatients within the hospital setting but are also expanding their retail pharmacy services to patients who require chronic disease management and specialized medications. Mail-order pharmacies cater to customers who prefer home delivery of medications, particularly those with chronic conditions requiring regular prescriptions. Online pharmacies have gained significant traction due to the growing demand for convenience, with many Canadians opting for the ease of ordering medications and health products online. These pharmacies also allow consumers to access digital consultations and telepharmacy services, further fueling their market growth.
By Type of Prescription
The retail pharmacy market in Canada is further segmented based on the type of prescription, including prescription drugs (Rx) and over-the-counter (OTC) drugs. Prescription drugs are a significant segment, as they are often used to treat chronic conditions such as diabetes, hypertension, and heart disease, which require ongoing management. The demand for prescription drugs is driven by Canada's aging population and the increasing prevalence of chronic diseases. OTC drugs, on the other hand, are widely purchased by consumers for self-care and preventive healthcare. The rising trend of self-medication, coupled with growing awareness of health conditions, has boosted the demand for OTC drugs such as pain relievers, cold medications, and dietary supplements. Both segments are critical to the growth of retail pharmacies, with prescription drugs contributing significantly to revenue, while OTC drugs provide a substantial consumer base seeking convenience and ease of purchase.
Segments
Based on Type of Pharmacy
- Chain Pharmacies
- Independent Pharmacies
- Hospital Pharmacies
- Mail Order Pharmacies
- Online Pharmacies
Based on Type of prescription
- Prescription Drugs (Rx)
- Over-the-Counter (OTC) Drugs
Based on Service offered
- Medication Dispensing
- Health Screenings
- Vaccination Services
- Consultation and Counseling
- Chronic Disease Management
Based on Product Type
- Generic Drugs
- Branded Drugs
Based on Application
- Oncology
- Diabetes
- Neurology
- Other
Based on Customer
- Paediatric
- Adults
- Geriatric
Based on Region
- Ontario
- Quebec
- British Columbia
Regional Analysis
Ontario (38%)
Ontario holds the largest market share in the Canada Retail Pharmacy Market, contributing approximately 38% of the total market revenue. This is due to the province’s large population, urbanization, and healthcare infrastructure, which includes a significant number of retail pharmacy outlets. Ontario’s retail pharmacies benefit from a high demand for both prescription and over-the-counter (OTC) medications, bolstered by the province's aging population and the increasing prevalence of chronic diseases. The province also has a large proportion of consumers who seek health and wellness services, further expanding the market. With strong competition among chain pharmacies like Shoppers Drug Mart and Rexall, as well as independent pharmacies, Ontario remains a key player in driving overall market growth.
Quebec (27%)
Quebec follows closely, contributing approximately 27% to the total market. The province has a unique demographic makeup with a large French-speaking population, and retail pharmacies in Quebec cater to both the linguistic and healthcare needs of this diverse group. Quebec's healthcare system also promotes the use of generic drugs and preventive health services, which fuels demand for both prescription and OTC medications. The province’s pharmacies are increasingly adopting digital technologies, such as telepharmacy services, to enhance convenience for consumers, particularly in remote areas. Retail pharmacies in Quebec face competition from both national chains and regional players, which drives innovation and service quality.
Key players
- McKesson Canada
- Shoppers Drug Mart Corporation
- Costco Pharmacy
- Walmart Pharmacy
- Kroger Pharmacy
Competitive Analysis
The Canada Retail Pharmacy Market is highly competitive, with several key players vying for market share through diverse service offerings and strategic expansions. McKesson Canada stands as one of the leading players, offering a broad portfolio of prescription drugs and healthcare services across the country. Their extensive distribution network and focus on digital solutions for pharmacies help strengthen their market position. Shoppers Drug Mart Corporation, a subsidiary of Loblaw Companies, is another dominant player, recognized for its wide range of healthcare services and strong retail presence. Costco Pharmacy and Walmart Pharmacy are significant competitors, offering competitive pricing and leveraging their large retail networks to attract a wide customer base. Both have successfully integrated pharmacy services into their overall shopping experience, driving consumer traffic. Kroger Pharmacy, known for its strong brand in North America, is expanding its footprint in Canada, focusing on improving customer engagement through personalized pharmacy services. Together, these players are reshaping the Canadian pharmacy landscape through innovations in service delivery, product offerings, and customer experience.
Recent Developments
- In December 2025, LSL Pharma Group announced the acquisition of Juno OTC Inc., adding a portfolio of Health Canada-approved OTC drugs, natural health products, and medical devices and strengthening its position as a supplier to Canadian pharmacy banners.
- In January 2026, Synergy CHC expanded distribution of its FOCUSfactor functional beverage portfolio across Canada through Walmart Canada and McKesson Canada, building on its earlier supplement-SKU launch and broadening availability through pharmacy, mass, grocery, convenience, and wholesale channels.
- In February 2026, Loblaw Companies, parent of Shoppers Drug Mart and Pharmaprix, announced a 2026 expansion and renovation program across its Canadian retail network, including food and pharmacy operations, with plans to open new locations and renovate existing stores.
- In April 2026, Pharmacy Brands Canada launched OpenRx, a zero-fee model designed to give independent pharmacy owners access to national-scale purchasing power while allowing them to retain control of their businesses.
- In May 2026, Apotex launched Apo Semaglutide Injection, a generic equivalent of Ozempic, in Canada, with initial inventory shipping to wholesalers and expected availability on pharmacy shelves across the country within weeks.
Market Concentration and Characteristics
The Canada Retail Pharmacy Market is moderately concentrated, with several dominant players controlling a significant share of the market. Key players such as McKesson Canada, Shoppers Drug Mart, and Costco Pharmacy hold a substantial portion of the market, benefiting from their extensive networks, brand recognition, and competitive pricing strategies. These companies are able to leverage economies of scale, offering a wide range of products and services, from prescription medications to health screenings and vaccinations. Independent pharmacies, although smaller in scale, contribute to the market by providing personalized services and catering to local communities. The market is also characterized by a growing trend toward digital transformation, with many pharmacies adopting e-commerce platforms, telepharmacy services, and home delivery options to enhance convenience and accessibility. The increasing presence of online pharmacies and digital health services is further intensifying competition, driving innovation, and shaping the future landscape of the market.
Report Coverage
The research report offers an in-depth analysis based on Type of Pharmacy, Type of prescription, Service offered, Product Type, Application, Customer and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The adoption of digital health solutions, including online pharmacies and telepharmacy, will continue to expand. Consumers increasingly seek the convenience of onlineordering, prescription refills, and virtual consultations.
- Retail pharmacies will increasingly diversify their service offerings to include health screenings, immunizations, and chronic disease management. This shift will drive growth as pharmacies become more integrated into preventative healthcare.
- Canada's aging demographic will continue to contribute to the growing demand for prescription medications. Older adults are more likely to suffer from chronic conditions, necessitating long-term pharmaceutical care.
- As cost-conscious consumers and healthcare providers turn to generic drugs, their market share will rise. Generic medications provide an affordable alternative to branded drugs, helping to manage the increasing healthcare costs.
- The integration of AI-driven solutions for medication management and personalized services will enhance customer engagement. AI will improve prescription adherence and optimize inventory management in pharmacies.
- With a growing focus on health and wellness, pharmacies will expand their role in preventive care. Services such as vaccinations and health screenings will become more common, contributing to a broader customer base.
- Evolving regulatory policies related to drug pricing and healthcare services will impact retail pharmacies. Companies must adapt to new regulations around pricing, reimbursements, and service delivery to remain competitive.
- The rise of e-pharmacies will continue to pose a challenge to traditional retail pharmacies. With increasing consumer preference for convenience, established pharmacies must innovate to maintain market share.
- Ongoing reforms in healthcare insurance and drug coverage policies will directly affect consumer spending on pharmacy services. Retail pharmacies will need to adjust their offerings to align with changing reimbursement structures.
- As environmental concerns rise, pharmacies will focus on adopting sustainable practices. Green initiatives such as reducing plastic waste and using eco-friendly packaging will become essential to meet consumer expectations and regulatory demands.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Aging Population and Increased Healthcare Needs
Canada’s growing senior demographic is driving higher demand for prescription medications, medication reviews, and pharmacy-based health services. Older adults require more frequent and complex pharmaceutical care, making retail pharmacies essential for ongoing health management.
Prevalence of Chronic Diseases
The rising incidence of chronic conditions such as diabetes, hypertension, and arthritis is fueling demand for long-term medication management and pharmacist-led counseling. Retail pharmacies play a critical role in supporting adherence and providing disease management services.
Advancements in Digital Health Technologies
The adoption of telepharmacy, e-prescriptions, and online pharmacy platforms is improving accessibility and convenience for consumers, especially in rural and underserved areas. Digital solutions are expanding the reach of retail pharmacies and enhancing patient engagement.
Government Support for Pharmacy Services
Public healthcare programs and provincial drug plans are increasing access to medications and supporting pharmacist-led care, reinforcing the role of retail pharmacies in community health. Government initiatives also enable pharmacies to participate in vaccination campaigns and preventive health services.
Expansion of Health and Wellness Offerings
Retail pharmacies are diversifying into preventive care, health screenings, and wellness products to meet consumer demand for holistic health solutions. This expansion creates new revenue streams and strengthens customer loyalty by positioning pharmacies as comprehensive healthcare hubs.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size of the Canada Retail Pharmacy Market?
What factors are driving growth in the Canada Retail Pharmacy Market?
Who are the major players in the Canada Retail Pharmacy Market?
How is the shift towards digital health impacting the retail pharmacy market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Service Offered
- 1.2.1 Medication Dispensing
- 1.2.2 Health Screenings
- 1.2.3 Vaccination Services
- 1.2.4 Consultation and Counseling
- 1.2.5 Chronic Disease Management
- 1.3 By Type of Pharmacy
- 1.3.1 Chain Pharmacies
- 1.3.2 Independent Pharmacies
- 1.3.3 Hospital Pharmacies
- 1.3.4 Mail Order Pharmacies
- 1.3.5 Online Pharmacies
- 1.4 By Type of Prescription
- 1.4.1 Prescription Drugs (Rx)
- 1.4.2 Over-the-Counter (OTC) Drugs
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 39,810.35 million → 2024: USD 39,810.35 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2024
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2024
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Canada Retail Pharmacy Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Canada Retail Pharmacy Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2024
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2024
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Canada Retail Pharmacy Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2024
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Canada Retail Pharmacy Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Canada Retail Pharmacy Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Canada Retail Pharmacy Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Canada Retail Pharmacy Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Canada Retail Pharmacy Market Outlook, 2024-2024
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 39,810.35 million → 2024: USD 39,810.35 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2024
- 11.2.1 Revenue Forecast to 2024
- 11.2.2 Volume Forecast to 2024
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Canada Retail Pharmacy Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Service Offered - Market Size and Forecast, 2024-2024
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2024
- 12.3.4 Volume Forecast, 2024-2024
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Medication Dispensing
- 12.3.7.2 Health Screenings
- 12.3.7.3 Vaccination Services
- 12.3.7.4 Consultation and Counseling
- 12.3.7.5 Chronic Disease Management
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Type of Pharmacy - Market Size and Forecast, 2024-2024
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2024
- 12.4.4 Volume Forecast, 2024-2024
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Chain Pharmacies
- 12.4.7.2 Independent Pharmacies
- 12.4.7.3 Hospital Pharmacies
- 12.4.7.4 Mail Order Pharmacies
- 12.4.7.5 Online Pharmacies
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Type of Prescription - Market Size and Forecast, 2024-2024
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2024
- 12.5.4 Volume Forecast, 2024-2024
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Prescription Drugs (Rx)
- 12.5.7.2 Over-the-Counter (OTC) Drugs
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Canada Retail Pharmacy Geographic Market Outlook, 2024-2024
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2024
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Canada Retail Pharmacy Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2024
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Canada Retail Pharmacy Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2024
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 McKesson Canada
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Shoppers Drug Mart Corporation
- 17.4 Costco Pharmacy
- 17.5 Walmart Pharmacy
- 17.6 Jean Coutu Group (Metro Inc.)
- 17.7 Rexall Pharmacy Group
- 17.8 Pharmasave
- 17.9 London Drugs
- 17.10 Guardian and I.D.A. Pharmacies
- 17.11 Kroger Pharmacy
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

