
Market Overview:
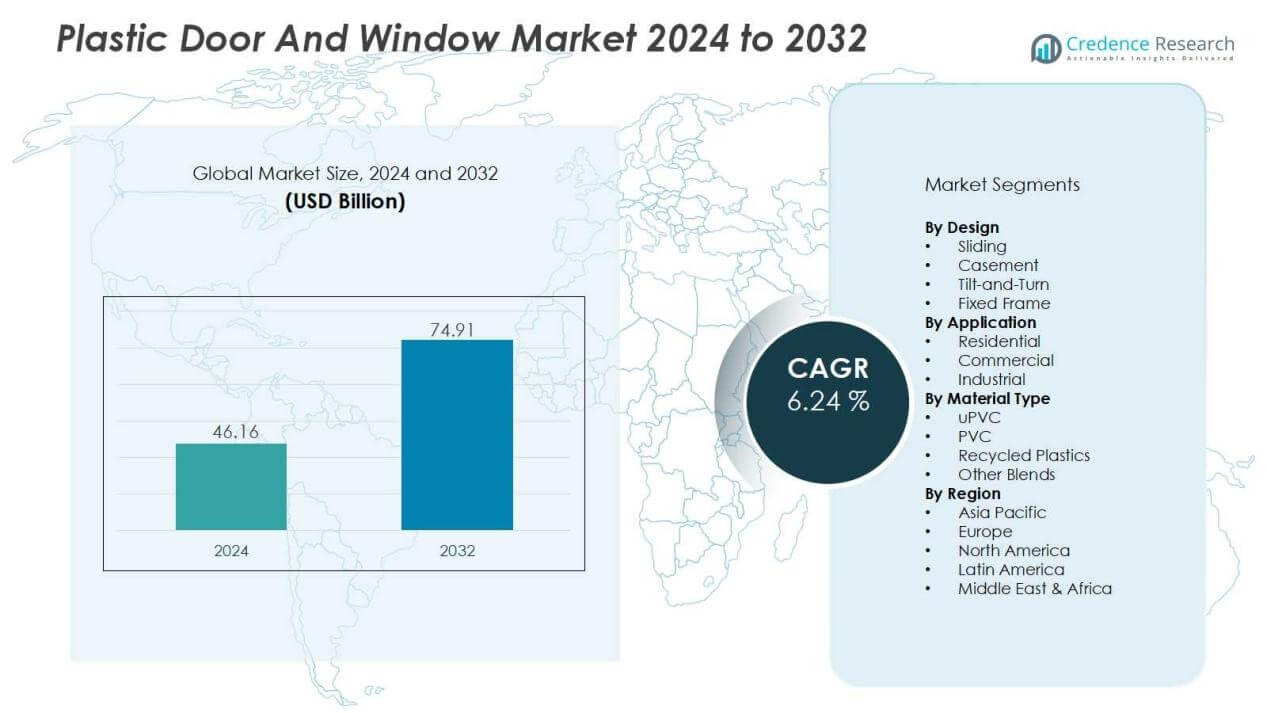
The plastic door and window market size was valued at USD 46.16 billion in 2024 and is anticipated to reach USD 74.91 billion by 2032, at a CAGR of 6.24% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Plastic Door And Window Market Size 2024 | USD 46.16 Billion |
| Plastic Door And Window Market, CAGR | 6.24% |
| Plastic Door And Window Market Size 2032 | USD 74.91 Billion |
Key drivers shaping the market include growing consumer demand for durable, low-maintenance solutions and rising awareness of energy-efficient construction materials. Plastic doors and windows offer superior thermal insulation and weather resistance, which enhances their appeal in both new construction and renovation projects. Expanding applications in smart homes, green buildings, and sustainable architecture further accelerate adoption. Manufacturers are investing in innovations such as recycled plastic frames and advanced glazing to align with environmental regulations and evolving consumer preferences.
Regionally, Asia Pacific dominates the plastic door and window market due to rapid urbanization, strong infrastructure investments, and expanding real estate activity in China and India. North America and Europe follow, supported by renovation trends, stringent energy codes, and growing replacement demand. The Middle East, Latin America, and Africa are emerging markets, fueled by rising construction projects and increasing acceptance of modern, cost-efficient building materials. This regional spread highlights the market’s global growth potential.
 Market Insights:
- The plastic door and window market was valued at USD 46.16 billion in 2024 and is projected to reach USD 74.91 billion by 2032, growing at a CAGR of 6.24%.
- Rising demand for energy-efficient construction drives adoption, as plastic doors and windows provide superior insulation and reduce energy loss.
- Durability and low maintenance strengthen consumer preference, with products outperforming wood and metal in longevity and weather resistance.
- Rapid urbanization and expanding real estate activity in China, India, and Southeast Asia boost large-scale adoption.
- Manufacturers focus on recycled plastics, advanced glazing, and customizable designs to meet sustainability goals and smart home integration needs.
- Challenges include fluctuating raw material costs, environmental concerns, and competition from substitutes such as aluminum and wood.
- Asia Pacific holds 45% market share, North America accounts for 22%, Europe 20%, and emerging regions including the Middle East, Latin America, and Africa collectively hold 13%.
Market Drivers:
Rising Demand for Energy-Efficient Construction Materials:
The plastic door and window market benefits from the growing emphasis on energy-efficient construction. It provides superior insulation properties that help reduce energy loss and improve indoor comfort. Builders and homeowners adopt these solutions to meet stricter building codes and lower utility costs. The rising awareness of sustainable living strengthens demand across residential and commercial spaces.
- For Instance, Aluplast's Energeto® uPVC windows, with 'foam inside' technology, can deliver a U-factor as low as 0.60 to 0.65 W/m²K depending on the specific configuration and glazing.
Durability and Low Maintenance Appeal:
Consumers value doors and windows that withstand harsh weather, resist corrosion, and require minimal upkeep. The plastic door and window market addresses this demand by offering products that outperform wood and metal in longevity. It reduces the need for frequent repairs or replacements, which appeals to both cost-sensitive and premium buyers. This reliability supports adoption in high-volume housing and institutional projects.
- For instance, REHAU Group, a global leader in uPVC window and door systems, is recognized for delivering products that combine durability and sustainability, maintaining excellent performance across multiple climates, with installations exceeding 30 years in service life without significant maintenance requirements.
Urbanization and Expanding Real Estate Sector:
Rapid urban growth and rising infrastructure investments stimulate adoption of plastic-based fixtures. The plastic door and window market gains momentum from increasing construction of residential complexes, commercial buildings, and smart homes. It supports large-scale developments where cost-effectiveness and quick installation matter. Growing disposable income in emerging economies drives further demand for modern, customizable options.
Innovation in Sustainable and Smart Solutions:
Manufacturers are focusing on recycled plastics, advanced glazing, and modern designs to meet evolving consumer expectations. The plastic door and window market benefits from innovations that align with green building standards. It also responds to the growing demand for smart home integration with enhanced security and design flexibility. This trend strengthens the market’s role in future-ready construction solutions.
Market Trends:
Growing Preference for Sustainable and Customized Solutions:
The plastic door and window market is witnessing a strong shift toward eco-friendly and customizable products. Consumers and builders demand recycled materials and low-emission options to align with green construction goals. It benefits from regulatory support promoting sustainable building materials, particularly in Europe and North America. Customization in color, finish, and design enhances the appeal of plastic doors and windows across residential and commercial projects. Rising adoption in smart city initiatives further accelerates market penetration. Product developers focus on creating versatile designs that meet both functional and aesthetic needs. This trend is shaping long-term growth and positioning the market as a key player in sustainable architecture.
- For instance, OKNOPLAST, a leading European window and door manufacturer, recycles 2,000 tons of PVC waste annually and has achieved a 50% reduction in gas consumption in their production process by using heat recovered from glass tempering furnaces.
Integration of Technology and Advanced Manufacturing:
The plastic door and window market is evolving with innovations in manufacturing processes and smart integration. Automated extrusion, precision molding, and advanced glazing techniques enable higher product quality and durability. It supports the adoption of energy-efficient models that improve insulation and reduce environmental impact. Smart technologies such as embedded sensors and security features are gaining traction, especially in urban developments. Digital platforms also support consumers in designing and customizing doors and windows before purchase. Rapid innovation fosters competitive differentiation among manufacturers and expands adoption in premium housing projects. This technology-driven shift is creating new opportunities for the industry worldwide.
- For Instance, aint-Gobain, a leader in smart glazing, markets smart glass under the SageGlass brand that actively controls light transmission while enhancing energy efficiency for buildings, and Saint-Gobain operates in over 75 countries, its SageGlass products are known to have been installed in buildings in more than 27 countries, and are sold to many more.
Market Challenges Analysis:
Fluctuating Raw Material Costs and Environmental Concerns:
The plastic door and window market faces significant pressure from volatility in raw material prices. Dependence on petroleum-based plastics makes it vulnerable to shifts in global crude oil costs. It also faces criticism for contributing to environmental pollution when recycling infrastructure is inadequate. Growing regulatory pressure to limit non-biodegradable plastics creates compliance challenges for manufacturers. Companies must invest in sustainable alternatives, which raises production costs and impacts profitability. These factors collectively hinder smooth market expansion across several regions.
Intense Competition and Quality Perception Issues:
The plastic door and window market also struggles with intense competition from substitutes such as aluminum, wood, and composite materials. It faces challenges in overcoming the perception of being less premium compared to traditional materials in certain markets. Price-sensitive consumers may choose low-cost options, which affects margins for quality-focused players. Regional fragmentation adds complexity, with local manufacturers offering cheaper alternatives. Compliance with international standards further requires continuous innovation and testing, which increases operating expenses. These challenges demand strategic positioning and differentiation to sustain growth.
Market Opportunities:
Rising Adoption in Green Building and Smart Infrastructure:
The plastic door and window market has strong opportunities driven by global demand for sustainable construction. Green building certifications encourage the use of energy-efficient and recyclable materials. It benefits from the shift toward low-carbon housing and commercial developments across urban centers. Integration into smart infrastructure projects offers additional growth potential, especially where durability and thermal performance are key. Expanding government support for eco-friendly materials further strengthens adoption. These factors open new revenue streams for manufacturers focusing on innovation and compliance.
Expanding Demand in Emerging Economies and Renovation Projects:
The plastic door and window market also gains opportunities from rapid urbanization and infrastructure growth in Asia-Pacific, Latin America, and the Middle East. Rising disposable income supports demand for affordable yet modern housing solutions. It benefits from the renovation wave in North America and Europe, where replacement demand for energy-efficient models is strong. Growing e-commerce channels expand reach, offering consumers more access to customizable designs. Local players can leverage cost advantages, while global companies can target premium markets with advanced products. These opportunities highlight strong prospects for growth across both developing and mature markets.
Market Segmentation Analysis:
By Material Type:
The plastic door and window market by material type is led by uPVC, known for its durability, insulation, and low maintenance. It dominates both residential and commercial adoption due to cost efficiency and weather resistance. PVC and other blends also hold demand, particularly in regions where affordability is a priority. Growing use of recycled plastics strengthens the segment with sustainability benefits. Manufacturers emphasize materials that align with green building standards to expand their presence.
- For instance, VEKA, a German company, is a pioneer of energy-saving uPVC profile systems used in over 40 countries, known for their durability and weatherproof features.
By Application:
In application terms, the plastic door and window market shows strong traction in residential construction, supported by urban housing and renovation projects. It also gains momentum in commercial spaces, including offices, retail complexes, and institutional buildings. Industrial applications contribute through demand for functional, cost-effective solutions. Builders prefer plastic doors and windows for energy efficiency, longevity, and flexible design options. Rising real estate projects in both developed and emerging markets reinforce growth in this segment.
- For instance, REHAU’s five-chamber uPVC window systems achieve a thermal transmittance (U-value) of 0.8 W/m²K when paired with 44 mm triple-glazed units, reducing heat loss and improving building comfort.
By Design:
By design, sliding doors and windows dominate due to space-saving benefits and aesthetic appeal. It supports modern urban housing where compact layouts require efficient solutions. Casement and tilt-and-turn designs maintain steady demand in premium housing and commercial projects. Fixed frame models find applications in large-scale buildings needing simple, durable solutions. The growing preference for customizable and contemporary styles drives innovation across this segment.
Segmentations:
By Material Type:
- uPVC
- PVC
- Recycled Plastics
- Other Blends
By Application:
- Residential
- Commercial
- Industrial
By Design:
- Sliding
- Casement
- Tilt-and-Turn
- Fixed Frame
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
Asia Pacific:
Asia Pacific holds 45% market share in the plastic door and window market, making it the leading region. Strong demand arises from rapid urbanization and large-scale housing projects in China, India, and Southeast Asia. It benefits from strong government support for infrastructure development and cost-effective construction materials. Rising disposable income and preference for modern housing solutions further boost adoption. Manufacturers focus on affordable, durable, and energy-efficient designs to meet regional needs. The expanding real estate and smart city initiatives create long-term opportunities for sustained growth.
North America and Europe:
North America holds 22% market share while Europe accounts for 20% in the plastic door and window market. Both regions benefit from renovation and replacement demand in residential and commercial properties. It gains strength from stringent energy efficiency regulations that encourage advanced glazing and insulated frames. Consumers in these markets also value aesthetics, customization, and durability, which strengthens premium product adoption. Growing awareness of sustainable materials enhances the role of plastic doors and windows in green building projects. Renovation cycles and strict regulatory standards continue to shape market momentum.
Middle East, Latin America, and Africa:
The Middle East, Latin America, and Africa collectively hold 13% market share in the plastic door and window market. Rising construction activity, infrastructure investments, and demand for affordable housing drive growth in these regions. It benefits from ongoing urbanization and the expansion of commercial developments such as offices and retail spaces. Governments support modern construction practices that include cost-efficient and durable materials. Local players expand their presence by offering low-cost options, while global companies explore premium segments. These emerging markets represent strong potential for future expansion and diversification.
Key Player Analysis:
- Veka
- Ply Gem Windows
- JELDWEN Windows Doors
- Atrium Windows Doors
- Weather Shield Windows Doors
- Champion Window Company
- Deceuninck
- profine Group
- REHAU
- MI Windows and Doors
- Marvin Windows and Doors
- Pella Corporation
- Andersen Corporation
- Kolbe Windows Doors
Competitive Analysis:
The plastic door and window market is highly competitive with strong participation from global and regional players. Key companies include Veka, Ply Gem Windows, JELDWEN Windows Doors, Atrium Windows Doors, Weather Shield Windows Doors, Champion Window Company, and Deceuninck. It is shaped by continuous innovation in design, energy efficiency, and sustainable material use. Companies focus on expanding product portfolios to meet the rising demand for customized and durable solutions. Strategic partnerships, distribution networks, and technological upgrades remain critical for market leadership. Competition is further intensified by local players offering cost-effective alternatives across emerging markets. Manufacturers that balance affordability, quality, and compliance with green building standards are better positioned to capture long-term growth.
Recent Developments:
- In July 2025, JELDWEN expanded its Cradle to Cradle certification portfolio to include more sustainable door products, reinforcing its commitment to environmental responsibility.
- In July 2025, Ply Gem Windows and Mastic Siding powered Habitat for Humanity's Builders Blitz 2025, reflecting community partnership and corporate responsibility efforts.
Report Coverage:
The research report offers an in-depth analysis based on Material Type, Application, Design and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The plastic door and window market will see strong adoption from rising demand for energy-efficient construction solutions.
- It will benefit from government incentives and building codes that promote sustainable and recyclable materials.
- Manufacturers will invest in advanced glazing technologies and smart features to meet modern housing needs.
- Urbanization in Asia Pacific will continue to drive large-scale demand for affordable and durable options.
- North America and Europe will remain key markets due to renovation cycles and replacement demand.
- It will expand in emerging economies where infrastructure development and disposable income are rising steadily.
- E-commerce platforms will enhance product reach, offering consumers access to customizable and innovative designs.
- Sustainability trends will push companies to focus on recycled plastics and low-carbon production methods.
- Global competition will intensify, with players differentiating through design, performance, and value-added services.
- The market will play a central role in future-ready construction, supported by smart city initiatives worldwide.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Emphasis on Energy-Efficient Construction
Plastic doors and windows offer superior thermal insulation, helping buildings meet stricter energy codes and reduce utility costs. This drives adoption in both new construction and renovation projects as energy efficiency becomes a top priority for builders and homeowners.
Durability and Low Maintenance
Plastic doors and windows outperform traditional wood and metal alternatives in terms of weather resistance, corrosion resistance, and longevity. Their low maintenance requirements appeal to cost-sensitive buyers and large-scale housing projects, supporting widespread market adoption.
Rapid Urbanization and Infrastructure Growth
Expanding urban populations, especially in Asia Pacific, are fueling large-scale residential and commercial construction. The need for affordable, quickly installed, and modern building materials positions plastic doors and windows as a preferred choice in these fast-growing markets.
Innovation in Sustainable and Smart Solutions
Manufacturers are investing in recycled plastics, advanced glazing, and smart integration to align with green building standards and evolving consumer preferences. These innovations enhance product appeal and compliance with environmental regulations, further accelerating market growth.
Renovation and Replacement Demand in Developed Markets
In North America and Europe, aging building stock and renovation cycles are driving replacement demand for energy-efficient and customizable plastic doors and windows, reinforcing steady market growth in mature regions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the plastic door and window market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the plastic door and window market projected to grow between 2024 and 2032?
Which plastic door and window market segment held the largest share in 2024?
What are the primary factors fueling the growth of the plastic door and window market?
Who are the leading companies in the plastic door and window market?
Which region commanded the largest share of the plastic door and window market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Design
- 1.2.1 Sliding
- 1.2.2 Casement
- 1.2.3 Tilt-and-Turn
- 1.2.4 Fixed Frame
- 1.3 By Application
- 1.3.1 Residential
- 1.3.2 Commercial
- 1.3.3 Industrial
- 1.4 By Material Type
- 1.4.1 uPVC
- 1.4.2 PVC
- 1.4.3 Recycled Plastics
- 1.4.4 Other Blends
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 46.16 billion → 2032: USD 74.91 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Plastic Door And Window Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Plastic Door And Window Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Plastic Door And Window Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Plastic Door And Window Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Plastic Door And Window Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Plastic Door And Window Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Plastic Door And Window Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Plastic Door And Window Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 46.16 billion → 2032: USD 74.91 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Plastic Door And Window Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Design - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Sliding
- 12.3.7.2 Casement
- 12.3.7.3 Tilt-and-Turn
- 12.3.7.4 Fixed Frame
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Residential
- 12.4.7.2 Commercial
- 12.4.7.3 Industrial
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 uPVC
- 12.5.7.2 PVC
- 12.5.7.3 Recycled Plastics
- 12.5.7.4 Other Blends
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Plastic Door And Window End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Plastic Door And Window Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Plastic Door And Window Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Plastic Door And Window Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Veka
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Ply Gem Windows
- 18.4 JELDWEN Windows Doors
- 18.5 Atrium Windows Doors
- 18.6 Weather Shield Windows Doors
- 18.7 Champion Window Company
- 18.8 Deceuninck
- 18.9 profine Group
- 18.10 REHAU
- 18.11 Pella Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

