
Market Overview:
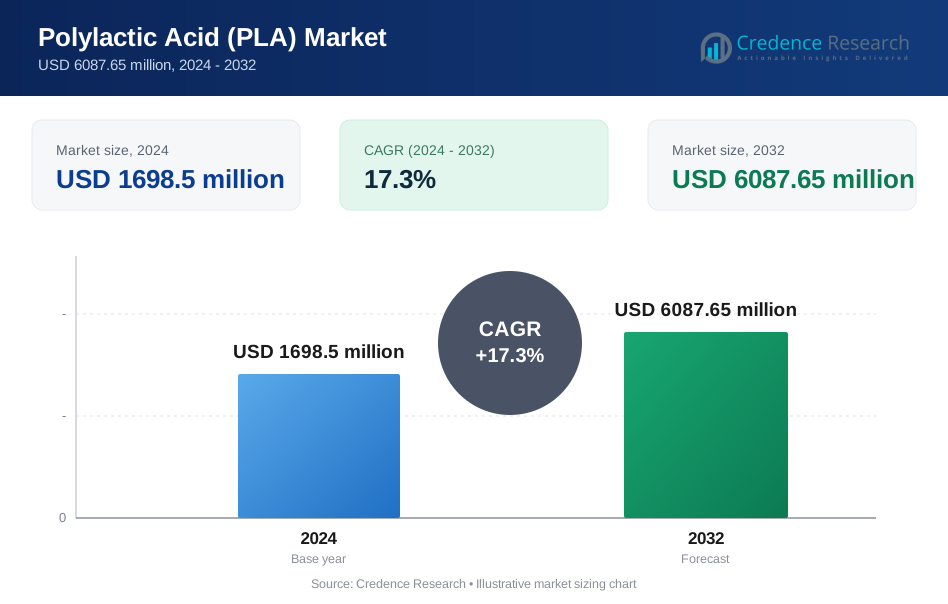
Polylactic Acid (PLA) Market was valued at USD 1698.5 million in 2024 and is anticipated to reach USD 6087.65 million by 2032, growing at a CAGR of 17.3 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Polylactic Acid (PLA) Market Size 2024 | USD 1698.5 Million |
| Polylactic Acid (PLA) Market, CAGR | 17.3 % |
| Polylactic Acid (PLA) Market Size 2032 | USD 6087.65 Million |
North America led the Polylactic Acid (PLA) Market in 2024 with about 37% share, supported by strong bioplastic adoption and robust corn-based feedstock supply. Key players including NatureWorks, Total Corbion PLA, BASF SE, Sulzer, COFCO Biochemical, FUTERRO S.A., Zhejiang Hisun Biomaterials, Nantong Jiuding Biological Engineering, Chongqing Bofei Biochemical Products, and UNITIKA LTD. expanded their presence through capacity upgrades, advanced fermentation technologies, and development of high-performance PLA grades. These companies focused on sustainable packaging demand, stronger regulatory support, and rising interest in circular biopolymer systems, which reinforced North America’s leadership and encouraged broader global deployment of PLA solutions.
Market Insights:
- The Polylactic Acid (PLA) Market was valued at USD 5 million in 2024 and is projected to reach USD 6087.65 million by 2032, growing at a CAGR of 17.3%
- Strong demand from sustainable packaging drives PLA adoption, with packaging holding about 58% share due to regulatory pressure on single-use plastics and rapid uptake in food service and retail.
- Trends highlight rising use of high-performance PLA grades in textiles, consumer goods, and biomedical applications, supported by advances in heat-resistant and durable formulations.
- Key players such as NatureWorks, Total Corbion PLA, BASF SE, COFCO Biochemical, FUTERRO S.A., and Zhejiang Hisun Biomaterials expand capacity and invest in bio-refineries, while competition remains shaped by cost pressure from petro-based plastics.
- North America led the market with 37% share in 2024, followed by Europe at 33% and Asia-Pacific at 25%, supported by strong packaging demand and abundant feedstock availability for corn-, sugarcane-, and cassava-based PLA.
Market Segmentation Analysis:
By Raw Material
Corn starch led the Polylactic Acid (PLA) Market in 2024 with an estimated 62% share. Producers favored corn feedstock due to strong global supply, established refining chains, and lower conversion costs. Rising demand for compostable plastics in food service and retail packaging also pushed corn-based PLA output. Sugarcane and cassava grades grew at a steady rate as Asian and Latin American suppliers expanded bio-based chemical capacity. Other niche raw materials saw limited use because feedstock availability and processing efficiency remained uneven across regions.
- For instance, one market‑analysis report estimated that corn‑based PLA accounted for about 65.5% of global PLA output in 2024 supported by corn’s abundant supply, high starch content, and established processing infrastructure.
By Application
Rigid thermoform dominated the Polylactic Acid (PLA) Market in 2024 with nearly 48% share. Packaging firms relied on PLA thermoformed trays, cups, and containers due to rising bans on single-use plastics and shifting consumer preference toward renewable materials. Film and sheets followed as demand increased in bags, wraps, and agricultural mulch applications. Bottles gained uptake in niche beverage and personal care formats. Other uses stayed modest because performance gaps in heat resistance and barrier strength restricted adoption in high-stress environments.
- For instance, another report notes that PLA-based films & sheets (flexible packaging) remain a significant portion of non-rigid PLA applications, complementing rigid thermoforms under the packaging umbrella.
By End-use
Packaging held the leading share in the Polylactic Acid (PLA) Market in 2024 with about 58%. Brand owners adopted PLA packaging to meet sustainability targets, reduce landfill waste, and comply with tightening regulations across Europe and North America. Agriculture saw growing PLA mulch and clips demand due to easier field disposal and lower soil impact. Automotive, electronics, and textiles used PLA in lightweight interior parts, casings, and fibers. Consumer goods and biomedical uses expanded as companies adopted biodegradable materials for cutlery, toys, implants, and controlled-release devices.
Key Growth Drivers:
Rising Global Demand for Sustainable Packaging
Growing restrictions on single-use plastics and rising demand for eco-friendly materials strongly push Polylactic Acid (PLA) adoption. Many countries enforce rules that require recyclable or compostable packaging, which places PLA in a favorable position due to its renewable feedstock and lower carbon footprint. Brands in food service, retail, and fast-moving consumer goods use PLA products to meet internal sustainability goals and avoid penalties linked to plastic waste. Strong interest from e-commerce packaging also lifts consumption as companies shift to lighter and greener materials. PLA producers expand capacity to meet supply shortages, especially in Asia and Europe. These combined forces create stable long-term demand for PLA packaging formats such as thermoformed trays, films, and disposable serviceware.
- For instance, in Europe the Single‑Use Plastics Directive (SUPD) has led several EU countries to ban disposable cutlery, plates, and polystyrene containers.
Expansion of Bio-Refineries and Feedstock Availability
Large investments in bio-refineries strengthen PLA supply by improving access to corn, sugarcane, and cassava feedstocks. Many producers upgrade fermentation and polymerization technology to reduce costs and improve conversion efficiency. Nations with strong agricultural output, such as the United States, Thailand, and Brazil, support PLA growth by offering stable crop supply and improving logistics for biopolymer manufacturing. Feedstock diversification also helps protect the market from price fluctuations in corn and sugar. Lower production costs encourage wider use of PLA in textiles, consumer goods, and agriculture. As capacity additions come online, market players secure long-term contracts with packaging, automotive, and electronics firms. These steps deepen PLA integration across multiple industries.
- For instance, TotalEnergies Corbion operates a PLA production facility in Thailand that uses sugarcane‑derived raw sugar from local mills leveraging tropical‑region agriculture to secure stable feedstock supply and reduce logistic emission burdens relative to imported starch.
R&D Progress in High-Performance PLA Grades
Research efforts improve PLA’s heat resistance, impact strength, and barrier properties, allowing wider use in demanding applications. Modified PLA blends replace traditional plastics in automotive panels, electronic casings, and premium rigid packaging. Advancements in crystallization control and compounding also create PLA materials suitable for hot-fill containers and microwave-safe products. Universities and chemical companies collaborate to develop next-generation PLA grades with longer life cycles and better recyclability. New processing technologies reduce energy use and enhance product consistency, supporting mass adoption. As high-performance variants enter the market, industries gain confidence in PLA’s ability to meet functional and regulatory needs, leading to broader commercial acceptance.
Key Trends & Opportunities:
Shift Toward Circular Bioplastics Systems
Circular economy programs accelerate opportunities for PLA through composting, chemical recycling, and controlled feedstock recovery. Governments invest in industrial composting networks to support wider disposal options for PLA-based products. Technology developers scale depolymerization systems that convert PLA waste back into lactic acid, creating a closed-loop supply chain. Retailers and food service brands adopt take-back programs that highlight the environmental benefits of biodegradable packaging. These changes increase PLA visibility and raise consumer acceptance.
- For instance, TotalEnergies Corbion recently announced a commercially viable process for producing 100% chemically recycled PLA from post‑consumer waste: used PLA is depolymerized back into its original monomer (lactide), which can then be repolymerized into new PLA resin with properties identical to virgin material.
Growing Use in High-Value Medical and Textile Applications
PLA gains momentum in biomedical devices and technical textiles due to better biocompatibility and improved fiber properties. Medical firms adopt PLA for sutures, tissue scaffolds, and drug-delivery systems. Textile producers use PLA fibers for lightweight clothing, hygiene products, and eco-friendly blends. Rising demand for sustainable materials in fashion and healthcare supports long-term opportunity creation.
- For instance, PLA is widely used in 3D‑printed medical devices: researchers have successfully created bone‑tissue scaffolds, drug‑eluting constructs, and biodegradable implants with PLA that support tissue regeneration and controlled release of active agents.
Key Challenges:
Competition from Lower-Cost Petrochemical Plastics
Traditional plastics such as PET, PP, and PS maintain strong cost advantages, especially in regions with low oil prices. Large converters hesitate to adopt PLA in high-volume applications due to higher material prices and performance gaps in heat stability. Limited global capacity also restricts scaling benefits. These cost pressures slow PLA penetration in mainstream packaging and consumer goods.
Inadequate Composting and Recycling Infrastructure
PLA adoption faces barriers in regions without industrial composting systems or proper sorting facilities. Many municipalities lack the ability to process PLA waste, which can undermine environmental claims and raise disposal costs for brands. Confusion among consumers about composting standards further limits PLA recovery rates. These gaps reduce PLA’s sustainability impact and challenge its long-term acceptance.
Regional Analysis:
North America
North America led the Polylactic Acid (PLA) Market in 2024 with about 37% share. Strong regulations on single-use plastics and rising adoption of compostable packaging supported PLA demand across food service, retail, and e-commerce sectors. The United States remained the largest consumer due to steady bioplastic investments and strong availability of corn-based feedstocks. Brands in consumer goods and healthcare also expanded PLA use in fibers, casings, and medical-grade materials. Increased focus on closed-loop systems and industrial composting programs further strengthened the region’s leadership in PLA production and consumption.
Europe
Europe held nearly 33% share of the global Polylactic Acid (PLA) Market in 2024. The European Union’s strict waste directives and plastic taxation drove strong demand for bio-based packaging. Countries such as Germany, France, and the Netherlands accelerated PLA adoption through advanced composting networks and sustainability-focused retail chains. Food packaging, cutlery, and films remained leading users, supported by expanding recycling and organic waste treatment capacity. Rising interest in textile-grade PLA and eco-friendly consumer products further boosted regional growth as brands aligned with circular economy goals.
Asia-Pacific
Asia-Pacific accounted for roughly 25% of the Polylactic Acid (PLA) Market in 2024 and recorded the fastest growth rate. China, Japan, Thailand, and South Korea expanded biopolymer production backed by strong government incentives and rising demand for greener packaging. Abundant sugarcane and cassava feedstock supply in Southeast Asia also increased PLA output. Expanding applications in textiles, automotive interiors, and electronics strengthened market penetration. E-commerce packaging and food delivery platforms further accelerated adoption, making Asia-Pacific a key future growth hub for PLA manufacturers.
Latin America
Latin America held close to 3% share of the Polylactic Acid (PLA) Market in 2024. Brazil led regional consumption due to large sugarcane reserves, strong bio-refinery activity, and growing interest in sustainable packaging. Food and beverage brands adopted PLA trays, bottles, and films to meet rising environmental commitments. Mexico and Chile also showed steady demand as retailers shifted toward compostable materials. Limited industrial composting infrastructure and higher import dependence outside Brazil kept adoption moderate, but ongoing investment in bio-based materials supports long-term opportunity.
Middle East & Africa
The Middle East & Africa region captured around 2% share of the Polylactic Acid (PLA) Market in 2024. Adoption grew slowly due to limited composting systems and higher prices compared to petrochemical plastics. However, rising sustainability programs in the UAE, Saudi Arabia, and South Africa supported niche demand in food packaging and consumer goods. Import-driven supply chains continued to dominate, though emerging bio-based project investments signaled long-term potential. Growing awareness of environmental waste issues and planned regulatory reforms are expected to lift regional PLA usage over the forecast period.
Market Segmentations:
By Raw Material
- Corn starch
- Sugarcane
- Cassava
- Others
By Application
- Rigid thermoform
- Film & sheets
- Bottles
- Others
By End-use
- Packaging
- Agriculture
- Automotive & transportation
- Electronics
- Textile
- Consumer goods
- Bio-medical
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape:
The Polylactic Acid (PLA) Market features leading players such as NatureWorks, Total Corbion PLA, BASF SE, Sulzer, COFCO Biochemical, FUTERRO S.A., Zhejiang Hisun Biomaterials, Nantong Jiuding Biological Engineering, Chongqing Bofei Biochemical Products, and UNITIKA LTD. These companies strengthen their positions by expanding biopolymer production, securing long-term feedstock contracts, and developing high-performance PLA grades with better heat resistance and mechanical strength. Many firms invest in large-scale bio-refineries to improve cost efficiency and meet rising demand from packaging, textiles, consumer goods, and automotive sectors. Strategic collaborations between technology providers and manufacturers support rapid adoption of chemical recycling and advanced fermentation technologies. European and Asian players focus on scaling circular systems, while North American producers leverage strong corn supply to maintain cost advantages. Continuous product innovation and capacity expansion remain central to competition, with sustainability commitments guiding long-term industry strategies.
Key Player Analysis:
- FUTERRO S.A.
- UNITIKA LTD.
- COFCO Biochemical
- BASF SE (Ludwigshafen, Germany)
- Chongqing Bofei Biochemical Products, Ltd.
- Nantong Jiuding Biological Engineering
- Sulzer (Winterthur, Switzerland)
- Zhejiang Hisun Biomaterials Co., Ltd
- Total Corbion PLA (Gorinchem, Netherlands)
- NatureWorks (Minnetonka, Minnesota, United States)
Recent Developments:
- In October 2025, FUTERRO S.A. continued its Europe expansion push, publishing updates on its European biorefinery programme and company roadmap for scaling PLA/lactic-acid production.
- In February 2025, COFCO Biochemical (COFCO Biotechnology) filed plans to relocate its 30,000 t/y lactide production project to Bengbu, Anhui province, a strategic move to address PLA supply-chain bottlenecks (lactide = key PLA intermediate).
Report Coverage:
The research report offers an in-depth analysis based on Raw material, Application, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- PLA demand will rise as global rules tighten on single-use plastics.
- Packaging firms will scale PLA use to meet sustainability targets.
- New high-heat and high-strength PLA grades will unlock advanced applications.
- Bio-refinery expansion will improve feedstock supply and reduce production costs.
- Chemical recycling and depolymerization will support circular PLA systems.
- Textile and fiber applications will grow with rising interest in eco-friendly materials.
- Automotive and electronics sectors will adopt PLA for lightweight parts and casings.
- Composting infrastructure improvements will increase end-of-life viability for PLA products.
- Asia-Pacific will become the fastest-growing region due to strong manufacturing capacity.
- Strategic partnerships among producers, converters, and brands will speed up PLA commercialization.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Polylactic Acid (PLA) Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is Polylactic Acid (PLA) Market projected to grow between 2024 and 2032?
Which Polylactic Acid (PLA) Market segment held the largest share in 2024?
What are the primary factors fueling the growth of Polylactic Acid (PLA) Market?
Who are the leading companies in Polylactic Acid (PLA) Market?
Which region commanded the largest share of Polylactic Acid (PLA) Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Polylactic Acid (PLA) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Polylactic Acid (PLA) Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1698.5 million → 2032: USD 6087.65 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Polylactic Acid (PLA) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Polylactic Acid (PLA) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Polylactic Acid (PLA) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Polylactic Acid (PLA) Market Drivers
- 3.3 Polylactic Acid (PLA) Market Restraints & Challenges
- 3.4 Polylactic Acid (PLA) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Polylactic Acid (PLA) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Polylactic Acid (PLA) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Polylactic Acid (PLA) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Polylactic Acid (PLA) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Polylactic Acid (PLA) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Polylactic Acid (PLA) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Polylactic Acid (PLA) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Polylactic Acid (PLA) Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Polylactic Acid (PLA) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Polylactic Acid (PLA) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Polylactic Acid (PLA) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Polylactic Acid (PLA) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Polylactic Acid (PLA) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Polylactic Acid (PLA) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Polylactic Acid (PLA) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Polylactic Acid (PLA) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Polylactic Acid (PLA) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Polylactic Acid (PLA) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Polylactic Acid (PLA) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
