
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Self-Ligating Brackets Market Size 2024 | USD 367.4 million |
| Self-Ligating Brackets Market , CAGR | 7.1% |
| Self-Ligating Brackets Market Size 2032 | USD 635.99 million |
Market Overview:
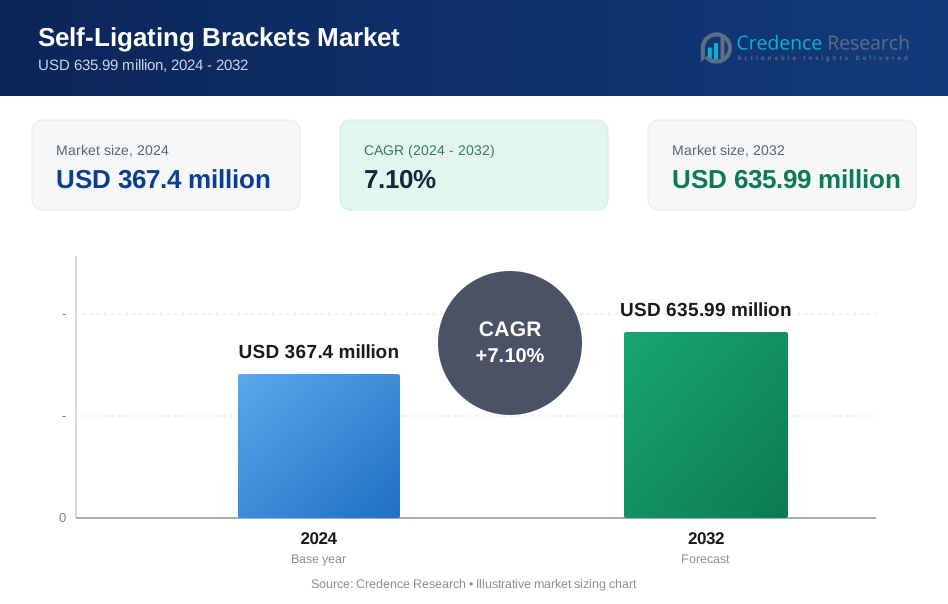
The self-ligating brackets market is poised to grow from USD 367.4 million in 2024 to USD 635.99 million by 2032, at a CAGR of 7.1% during the forecast period (2024-2032).
The increasing prevalence of malocclusion and rising awareness regarding orthodontic treatments are key factors driving the demand for self-ligating brackets. These brackets offer several advantages over conventional braces, such as reduced friction, shorter treatment duration, and enhanced patient comfort. Additionally, technological advancements in orthodontics, including the integration of artificial intelligence in treatment planning and the adoption of 3D printing for bracket manufacturing, are contributing to market expansion. The growing preference for minimally invasive dental procedures and the rising demand for aesthetic dental solutions further bolster market growth. An increasing number of orthodontists and dental clinics offering self-ligating bracket treatments, along with favourable reimbursement policies in certain regions, are also supporting market penetration.
North America holds a dominant share in the market due to its well-developed healthcare infrastructure, high orthodontic treatment rates, and significant investments in advanced dental technologies. The presence of key market players and increasing adoption of digital orthodontics further reinforce the region’s leadership. Meanwhile, the Asia-Pacific region is projected to witness the highest growth rate, driven by increasing disposable income, rising dental tourism, and a growing awareness of orthodontic treatments. Countries like China, India, and South Korea are experiencing significant market expansion due to improving healthcare access and an increasing number of dental clinics. Europe also holds a substantial market share, supported by well-established dental care services, high demand for cosmetic dentistry, and growing awareness about advanced orthodontic treatments. Additionally, Latin America and the Middle East & Africa regions are witnessing steady growth, supported by improving healthcare access and increasing investment in dental care infrastructure.
Market Insights:
- The self-ligating brackets market is projected to grow from USD 367.4 million in 2024 to USD 635.99 million by 2032, with a CAGR of 1%.
- Rising cases of dental malocclusions globally, affecting approximately 39% of the population, drive demand.
- Innovations like custom brackets and digital treatment planning enhance treatment accuracy and patient satisfaction.
- Growing popularity of clear and ceramic self-ligating brackets is boosting demand, especially among adults.
- High costs of advanced orthodontic solutions and limited accessibility in rural areas pose challenges.
- North America leads with a 35% market share, supported by advanced dental infrastructure and strong awareness.
- Asia-Pacific is the fastest-growing region due to increasing healthcare investments and expanding middle-class populations.
Market Drivers:
Increasing Demand for Aesthetic Dental Treatments
The self-ligating brackets market is witnessing significant growth due to the rising demand for aesthetic dental treatments. For instance, according to a survey by the American Association of Orthodontists, there has been a 20% increase in adults seeking orthodontic treatment over the past five years, driven by a desire for improved aesthetics. Self-ligating brackets, which are often less visible than traditional metal braces, cater to this demographic by offering a more discreet option for teeth alignment. This trend is particularly pronounced in regions with high disposable incomes, where patients are willing to invest in treatments that enhance their appearance without compromising comfort or efficiency.
Technological Advancements in Orthodontics
Technological advancements play a pivotal role in driving the self-ligating brackets market. For instance, companies like 3M Unitek and Dentsply Sirona have introduced innovative self-ligating systems that reduce treatment time and enhance patient comfort. These advancements include the development of brackets with lower friction, which allows for smoother tooth movement and potentially shorter treatment durations. A study published by the National Institute of Dental and Craniofacial Research highlighted that self-ligating brackets can reduce treatment time by up to 25% compared to conventional braces, making them an attractive option for both patients and orthodontists.
Growing Prevalence of Malocclusion
The prevalence of malocclusion, or misalignment of teeth, is another key driver for the self-ligating brackets market. For instance, data from the World Health Organisation indicates that approximately 50% to 75% of the global population has some form of malocclusion, necessitating orthodontic intervention. Self-ligating brackets provide an efficient solution for correcting these issues, with benefits like reduced need for adjustments and less discomfort during treatment. This has led to an increased adoption rate among orthodontists who are looking to offer treatments that are both effective and patient-friendly. A study among Zhuang children aged 7–8 years found a total prevalence of malocclusion of 58.5%, with the highest prevalence of anterior crossbite tendency.
Enhanced Patient Comfort and Reduced Appointment Frequency
Patient comfort and convenience are crucial factors influencing the choice of orthodontic treatments. For instance, a survey conducted by the British Orthodontic Society revealed that 70% of patients prefer treatments that require fewer office visits. Self-ligating brackets, with their design that minimises the need for frequent adjustments, align well with this preference. They not only reduce the number of appointments but also decrease the overall treatment time, which is a significant advantage in today's fast-paced lifestyle. This aspect of self-ligating brackets is particularly appealing to busy professionals and parents, further fuelling market growth. A study on patient satisfaction with orthodontic treatment found that 62.6% of patients were very satisfied regarding the behaviour of the orthodontist, indicating a high level of comfort and satisfaction with the treatment process.
Market Trends
Rising Demand for Aesthetic Orthodontic Solutions
The self-ligating brackets market is witnessing a significant trend towards aesthetic orthodontic solutions. Patients, particularly adults, are increasingly opting for discreet dental correction options to enhance their smiles without compromising on aesthetics. For instance, a 2024 survey by the American Association of Orthodontists revealed that over 65% of adults prioritise aesthetic over functional aspects when choosing orthodontic solutions. This trend is particularly strong in North America and Asia-Pacific, where aesthetic dentistry is rapidly expanding. Ceramic self-ligating brackets, which blend seamlessly with natural teeth, are gaining traction due to their enhanced visual appeal and functionality.
Advancements in Bracket Technology
Innovations in bracket design and materials are driving the self-ligating brackets market forward. Companies like 3M have introduced new self-ligating bracket systems featuring low-friction technology, which not only enhances patient comfort but also potentially reduces treatment time. For example, in 2023, 3M launched a new bracket system aimed at improving patient experience through advanced materials and design. These advancements are not only about aesthetics but also about improving the efficiency of orthodontic treatment, making self-ligating brackets a preferred choice among both orthodontists and patients.
Strategic Partnerships and Market Expansion
Key players in the self-ligating brackets market are engaging in strategic partnerships and acquisitions to expand their product offerings and global reach. For instance, in 2022, Align Technology acquired OrthoClear, a provider of self-ligating braces, to strengthen its position in the orthodontic market. Such strategic moves are aimed at integrating advanced technologies and expanding market presence, thereby driving growth in the self-ligating brackets sector.
Patient Comfort and Treatment Efficiency
The focus on patient comfort and treatment efficiency continues to be a pivotal trend in the self-ligating brackets market. Self-ligating brackets reduce the need for frequent adjustments, thereby decreasing chair time for patients. For instance, a study published in The Angle Orthodontist in 2024 highlighted that self-ligating brackets can shorten treatment times by 15-20% compared to traditional braces. This efficiency not only appeals to busy professionals but also reduces overall costs for patients, making these brackets a more economical option in the long term.
Market Challenges Analysis
High Cost of Dental Procedures
One of the primary restraints in the self-ligating brackets market is the high cost associated with dental procedures. The premium pricing of self-ligating brackets, particularly ceramic and active types, can deter widespread adoption, especially in price-sensitive regions. For instance, a 2024 survey by the American Dental Association (ADA) indicated that the average cost for self-ligating braces ranges from $3,000 to $7,000, significantly higher than traditional braces. This cost barrier can limit market growth, as many consumers, particularly in developing markets, may opt for more affordable alternatives like clear aligners or traditional braces. Regulatory challenges pose another significant obstacle to the self-ligating brackets market. The stringent regulations imposed by government authorities, such as the U.S. Food and Drug Administration (FDA), require extensive testing and approval processes for new orthodontic devices. These regulations ensure patient safety but can delay product launches and increase development costs.
Limited Reimbursement Policies
The lack of comprehensive reimbursement policies for orthodontic treatments, including self-ligating brackets, is a notable challenge. In many regions, orthodontic care is not fully covered by insurance, making it less accessible to a broader population. According to a 2024 report by the National Institute of Dental and Craniofacial Research (NIDCR), only 30% of orthodontic treatments are reimbursed by insurance, with self-ligating brackets often receiving even less coverage due to their higher cost. This financial burden can hinder market expansion, particularly in regions where out-of-pocket expenses are a significant deterrent.
Market Opportunities
The self-ligating brackets market offers substantial growth potential due to the rising prevalence of dental malocclusions and the growing demand for aesthetically appealing orthodontic solutions. With approximately 39% of the global population affected by malocclusions, there is a significant need for effective and patient-friendly treatment options. Self-ligating brackets, known for their reduced friction and faster treatment times, cater to these requirements, positioning themselves as a preferred choice for both orthodontists and patients. Moreover, the increasing emphasis on minimally invasive procedures is driving the adoption of these advanced systems. The introduction of clear and ceramic self-ligating brackets further amplifies their appeal among adults seeking discreet treatment solutions, presenting a lucrative opportunity for manufacturers to target this growing demographic.
Emerging economies present an untapped market for self-ligating brackets, supported by improving healthcare infrastructure and rising disposable incomes. Countries like India, China, and Brazil are witnessing significant investments in dental healthcare, with healthcare budgets growing at 7%-9% annually. Government programs aimed at expanding access to affordable healthcare are also creating a favourable environment for orthodontic treatments. Additionally, technological advancements, such as 3D printing and digital treatment planning, are making these brackets more accessible and efficient. Companies investing in innovation and strategic collaborations with dental clinics and institutions can capitalise on the growing demand in these regions. Collectively, the combination of increasing global dental awareness, technological progress, and regional expansion opportunities highlights the robust market potential for self-ligating brackets.
Market Segmentation Analysis:
By Type:
The market is categorised into passive, active, and interactive brackets. Passive self-ligating brackets dominate the segment due to their minimal friction and lower force requirements, making them ideal for initial alignment phases. Active brackets, which apply continuous pressure on the archwire, are gaining popularity for their efficiency in achieving precise dental movements. Interactive brackets, combining the benefits of passive and active systems, represent an emerging segment, offering orthodontists enhanced flexibility during treatments.
By Technology
The market is segmented into ceramic, metal, and hybrid brackets. Ceramic brackets are witnessing high demand, particularly among adult patients, due to their aesthetic appeal and ability to blend with natural tooth colour. Metal brackets remain the most widely used due to their durability and cost-effectiveness, making them suitable for a wide range of cases. Hybrid brackets, integrating ceramic and metal components, are gaining traction as they offer a balance between aesthetics and functionality.
By End User
The market includes dental clinics, hospitals, and academic institutions. Dental clinics hold the largest share, driven by the increasing number of orthodontic cases and the growing preference for personalised treatment plans. Hospitals account for a significant portion due to their ability to provide comprehensive orthodontic care. Academic institutions are also contributing to the segment, as they adopt advanced self-ligating systems for training and research purposes, fostering the market's growth.
Segmentations:
By Product:
- Active Self-Ligating Brackets
- Passive Self-Ligating Brackets
By Indication:
- Metal
- Ceramic
By End User:
- Hospitals
- Dental Clinics
- Group Dental Practices
- Academic & Research Institutions
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest market share in the self-ligating brackets market, accounting for 35% of the global revenue. The region's dominance is attributed to its advanced dental healthcare infrastructure and strong emphasis on aesthetic dental treatments. High disposable incomes and increasing awareness of orthodontic care among adults and adolescents have significantly driven adoption.
Europe
Europe accounts for 28% of the market share, driven by the rising prevalence of dental malocclusions and the region’s focus on innovative orthodontic technologies. Countries like Germany, the UK, and France are at the forefront of self-ligating bracket adoption, benefiting from robust healthcare infrastructure and high patient awareness of dental aesthetics. Additionally, dental tourism in Eastern Europe, particularly in Hungary and Poland, has boosted demand for advanced orthodontic solutions.
Asia-Pacific
The Asia-Pacific region is the fastest-growing market, capturing 22% of the global share. Growth in emerging economies such as India, China, and Japan is fuelled by rising healthcare investments and increasing awareness of orthodontic treatments. Additionally, healthcare expenditure in the region is growing at an annual rate of 7%-9%, further driving the expansion of orthodontic treatments and technologies.
Latin America and the Middle East & Africa
Latin America and the Middle East & Africa together account for the 15% market share, driven by improving healthcare awareness and access to orthodontic services. Similarly, the UAE and South Africa have seen substantial investments in healthcare infrastructure, creating favourable conditions for the adoption of advanced orthodontic technologies and fostering growth opportunities in these regions.
Key Player Analysis:
- 3M
- Ormco Corporation
- Dentsply Sirona
- American Orthodontics
- Henry Schein, Inc.
- G&H Orthodontics
- Rocky Mountain Orthodontics
- BioMers Pte Ltd
- GC Orthodontics
- TP Orthodontics
Competitive Analysis:
The self-ligating brackets market is characterised by intense competition among established players and emerging innovators striving to capture market share through product differentiation and technological advancements. Leading companies such as 3M, Ormco Corporation, and Dentsply Sirona dominate the market due to their extensive distribution networks, strong brand presence, and continuous investment in R&D. For instance, Ormco’s advanced Damon System brackets have gained significant traction, offering reduced treatment time and enhanced patient comfort. Emerging players, including BioMers Pte Ltd and G&H Orthodontics, are focusing on aesthetic and hybrid solutions to meet growing consumer preferences for discreet orthodontic treatments. Additionally, partnerships between manufacturers and dental clinics are driving market penetration, particularly in emerging economies. The market's competitive dynamics are further fuelled by the adoption of digital orthodontics, with companies integrating technologies such as 3D printing and AI-based treatment planning to gain a competitive edge.
Recent Developments:
- In March 2024, Ormco Corporation introduced the Damon Ultima System, a fully reengineered passive self-ligating bracket designed to virtually eliminate play for precise control of rotation, angulation, and torque.
- In January 2023, Dentsply Sirona launched the In-Ovation X self-ligating bracket system, featuring a low-profile design and an enclosed clip to mitigate calculus accumulation, enhancing patient comfort and treatment efficiency.
- In June 2022, American Orthodontics enhanced its Empower® Clear Brackets, incorporating a 20% thicker clip for increased wire seating force and reduced deformation, alongside a robust bracket body design for improved durability.
- In September 2022, 3M introduced the Clarity Ultra Self-Ligating Brackets, featuring a wide ceramic door to assist rotational control and a door mechanism tested to endure twice as many opening and closing cycles as typical treatment, ensuring reliability.
Market Concentration & Characteristics:
The self-ligating brackets market exhibits moderate market concentration, with a mix of established global players and emerging companies driving competition. Key manufacturers such as 3M, Ormco Corporation, and Dentsply Sirona dominate the landscape due to their extensive distribution networks, robust R&D capabilities, and diverse product portfolios catering to aesthetic and functional demands. The market is characterised by rapid technological advancements, including 3D printing, digital treatment planning, and the development of hybrid brackets that combine metal and ceramic components for enhanced performance and aesthetics. Additionally, the growing focus on minimally invasive orthodontic solutions and patient comfort has spurred innovation, with companies introducing brackets that reduce treatment time and improve hygiene. While developed regions like North America and Europe account for significant market share, emerging economies in Asia-Pacific are experiencing robust growth, driven by increasing healthcare investments and rising demand for advanced orthodontic treatments.
Report Coverage:
The research report offers an in-depth analysis based on product, indication, end user, and region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, a SWOT analysis, and current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market
Future Outlook
- The self-ligating brackets market is poised to benefit from ongoing advancements in orthodontic technologies, including digital treatment planning and 3D printing.
- Increasing demand for aesthetic orthodontic solutions will drive the adoption of ceramic and clear self-ligating brackets globally.
- Rising awareness of oral health and malocclusion treatments will expand the market's reach, particularly in emerging economies.
- The integration of artificial intelligence in orthodontic diagnostics and treatment customisation will enhance the efficiency and appeal of self-ligating systems.
- Emerging markets in Asia-Pacific and Latin America will witness robust growth due to improving healthcare infrastructure and rising disposable incomes.
- Partnerships between manufacturers and dental clinics are expected to increase, boosting accessibility to advanced orthodontic treatments.
- The trend of dental tourism, particularly in Europe and Southeast Asia, will create lucrative opportunities for market players.
- Innovations in bracket materials and designs will focus on improving patient comfort and reducing treatment time, strengthening market adoption.
- Increasing investments in orthodontic research and development will lead to the introduction of cost-effective solutions, widening the market's consumer base.
- Government healthcare initiatives and insurance coverage expansion will enhance the affordability and accessibility of orthodontic treatments globally.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Demand for Aesthetic Dental Treatments
A growing number of adults and image-conscious patients are seeking orthodontic solutions that are less visible and more comfortable, driving demand for self-ligating brackets, especially ceramic and clear variants that offer discreet treatment options.
Technological Advancements in Orthodontics
Innovations such as 3D printing, AI-driven treatment planning, and improved bracket designs are enhancing treatment efficiency, reducing chair time, and improving patient outcomes, making self-ligating brackets more attractive to both providers and patients.
Rising Prevalence of Malocclusion
With a significant portion of the global population affected by dental misalignment, the need for effective and patient-friendly orthodontic solutions like self-ligating brackets is increasing, especially as awareness and diagnosis rates rise.
Enhanced Patient Comfort and Reduced Appointment Frequency
Self-ligating brackets require fewer adjustments and office visits compared to traditional braces, appealing to busy patients and parents and contributing to higher satisfaction and adoption rates.
Expansion of Dental Infrastructure in Emerging Markets
Rapid improvements in healthcare infrastructure, rising disposable incomes, and government initiatives in regions like Asia-Pacific and Latin America are making advanced orthodontic treatments, including self-ligating brackets, more accessible and affordable.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the self-ligating brackets market?
What are some challenges faced by the self-ligating brackets market?
Who are the major players in the self-ligating brackets market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Active Self-Ligating Brackets
- 1.2.2 Passive Self-Ligating Brackets
- 1.2.3 Interactive Self-Ligating Brackets
- 1.3 By End User
- 1.3.1 Dental Clinics
- 1.3.2 Hospitals
- 1.3.3 Group Dental Practices
- 1.3.4 Academic & Research Institutions
- 1.4 By Material
- 1.4.1 Metal
- 1.4.2 Ceramic
- 1.4.3 Hybrid
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 367.4 million → 2032: USD 635.99 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Self-Ligating Brackets Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Self-Ligating Brackets Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Self-Ligating Brackets Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Self-Ligating Brackets Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Self-Ligating Brackets Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Self-Ligating Brackets Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Self-Ligating Brackets Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Self-Ligating Brackets Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 367.4 million → 2032: USD 635.99 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Self-Ligating Brackets Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Active Self-Ligating Brackets
- 12.3.7.2 Passive Self-Ligating Brackets
- 12.3.7.3 Interactive Self-Ligating Brackets
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Dental Clinics
- 12.4.7.2 Hospitals
- 12.4.7.3 Group Dental Practices
- 12.4.7.4 Academic & Research Institutions
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Metal
- 12.5.7.2 Ceramic
- 12.5.7.3 Hybrid
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Self-Ligating Brackets End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Self-Ligating Brackets Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Self-Ligating Brackets Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Self-Ligating Brackets Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 3M
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Ormco Corporation
- 18.4 Dentsply Sirona
- 18.5 American Orthodontics
- 18.6 Henry Schein, Inc.
- 18.7 G&H Orthodontics
- 18.8 Rocky Mountain Orthodontics
- 18.9 BioMers Pte Ltd
- 18.10 GC Orthodontics
- 18.11 TP Orthodontics
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

