
Japan prices the first iPSC products as clinics face review
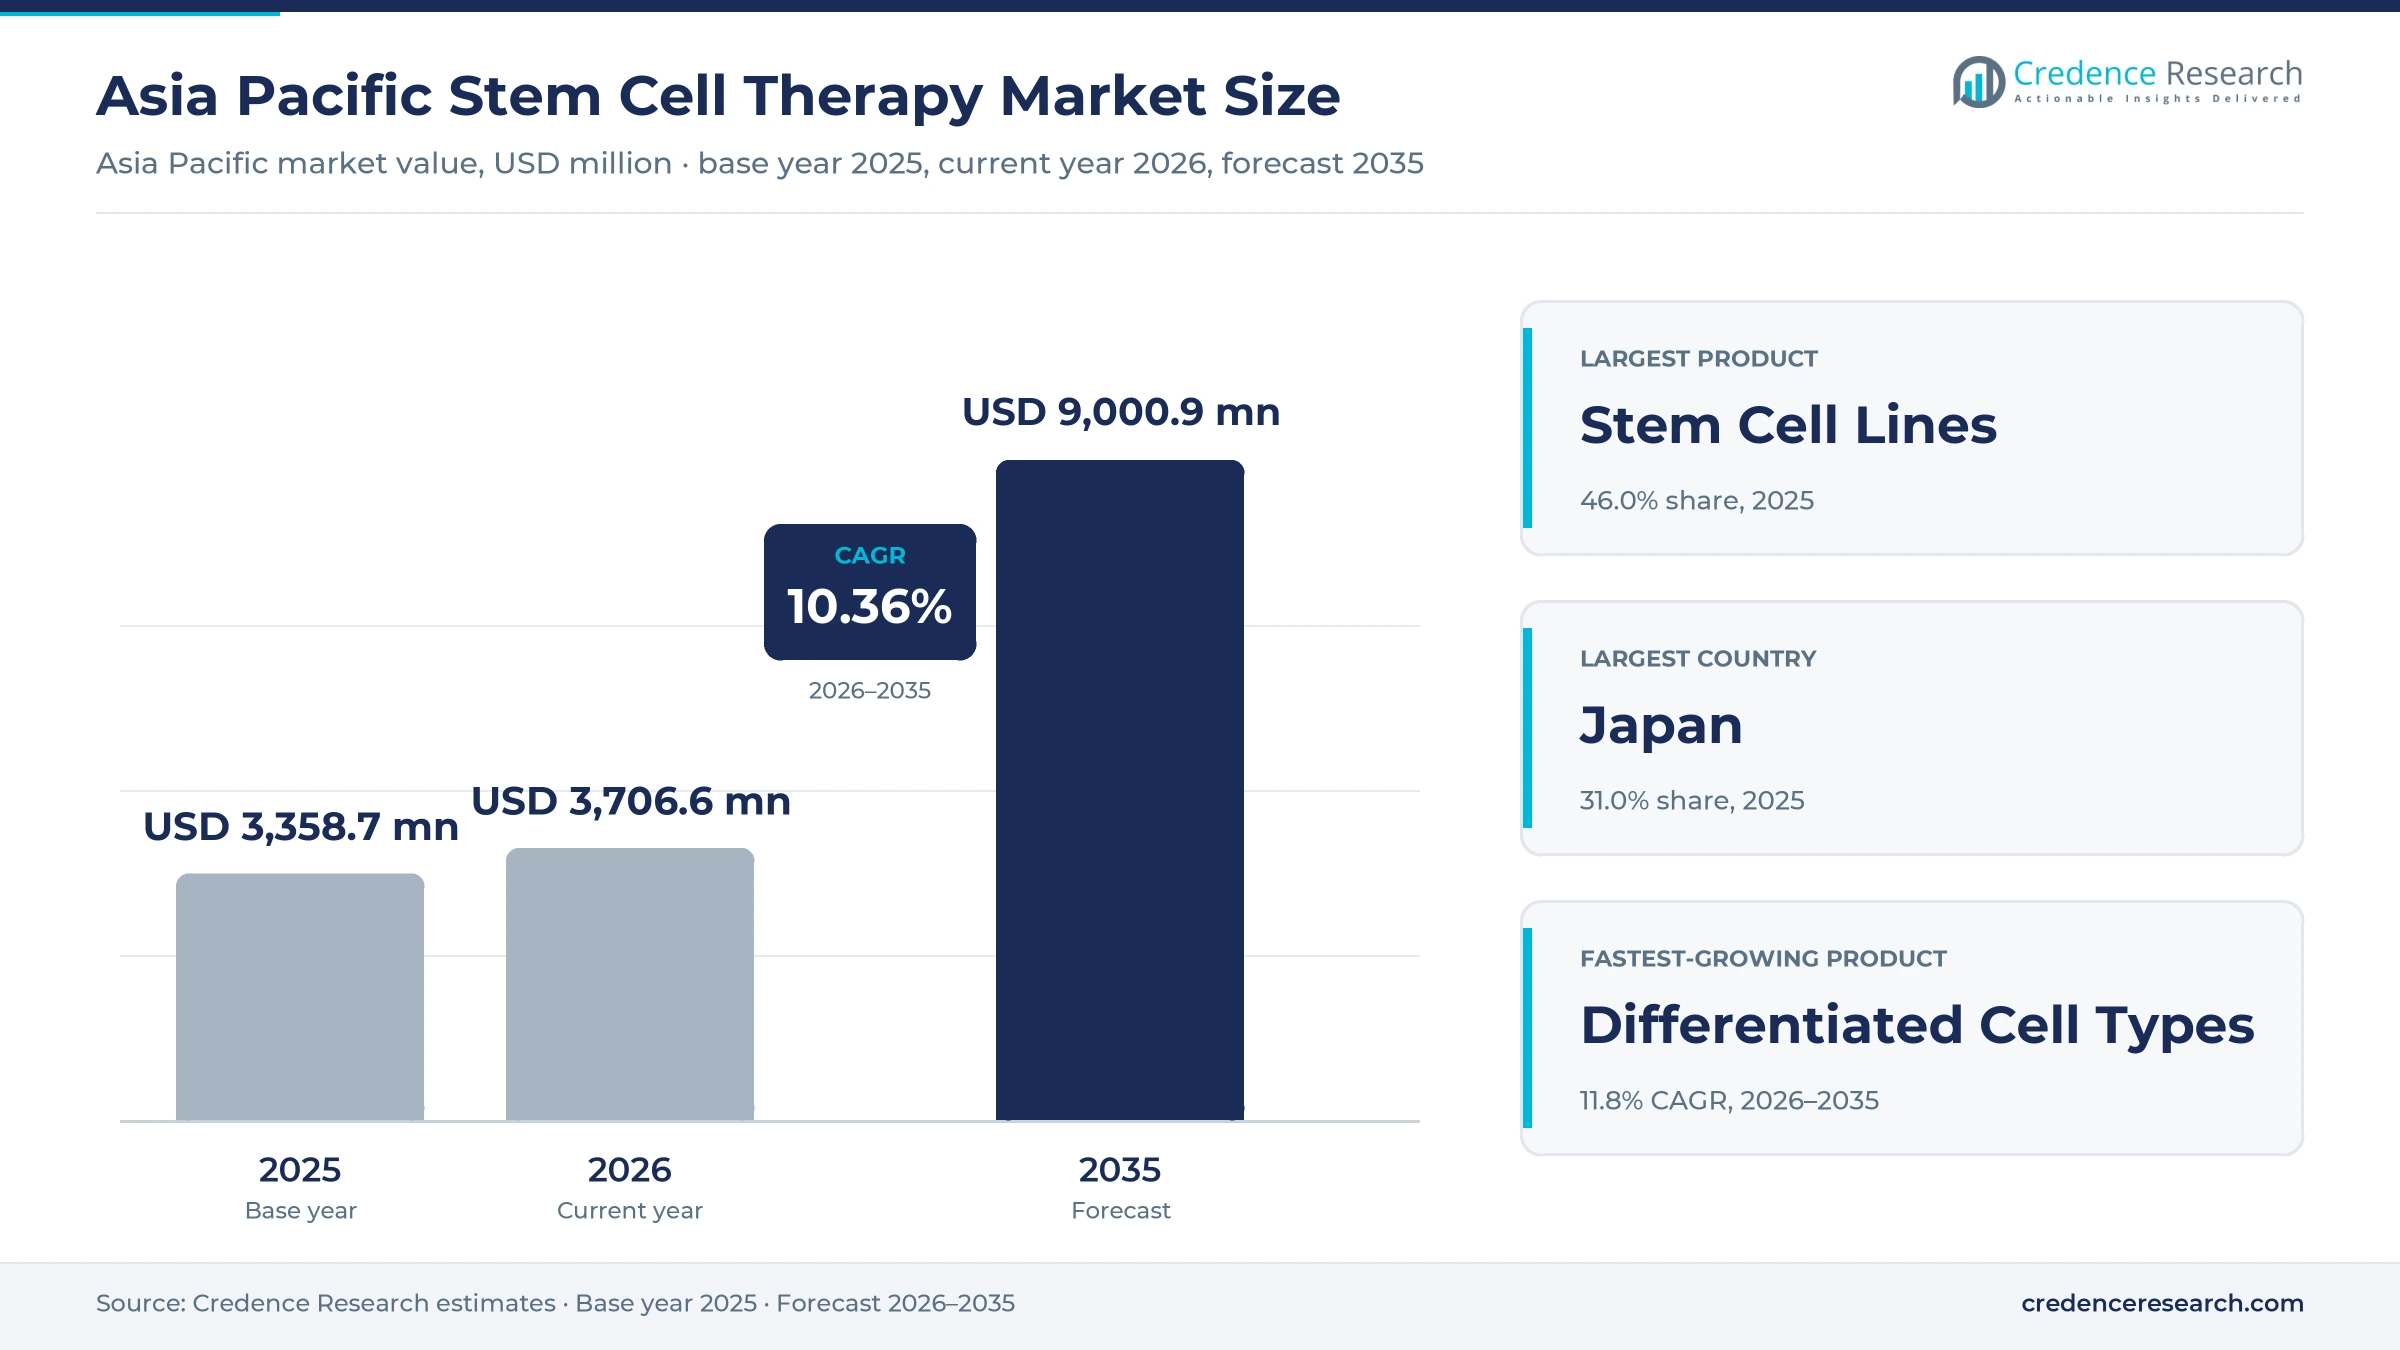
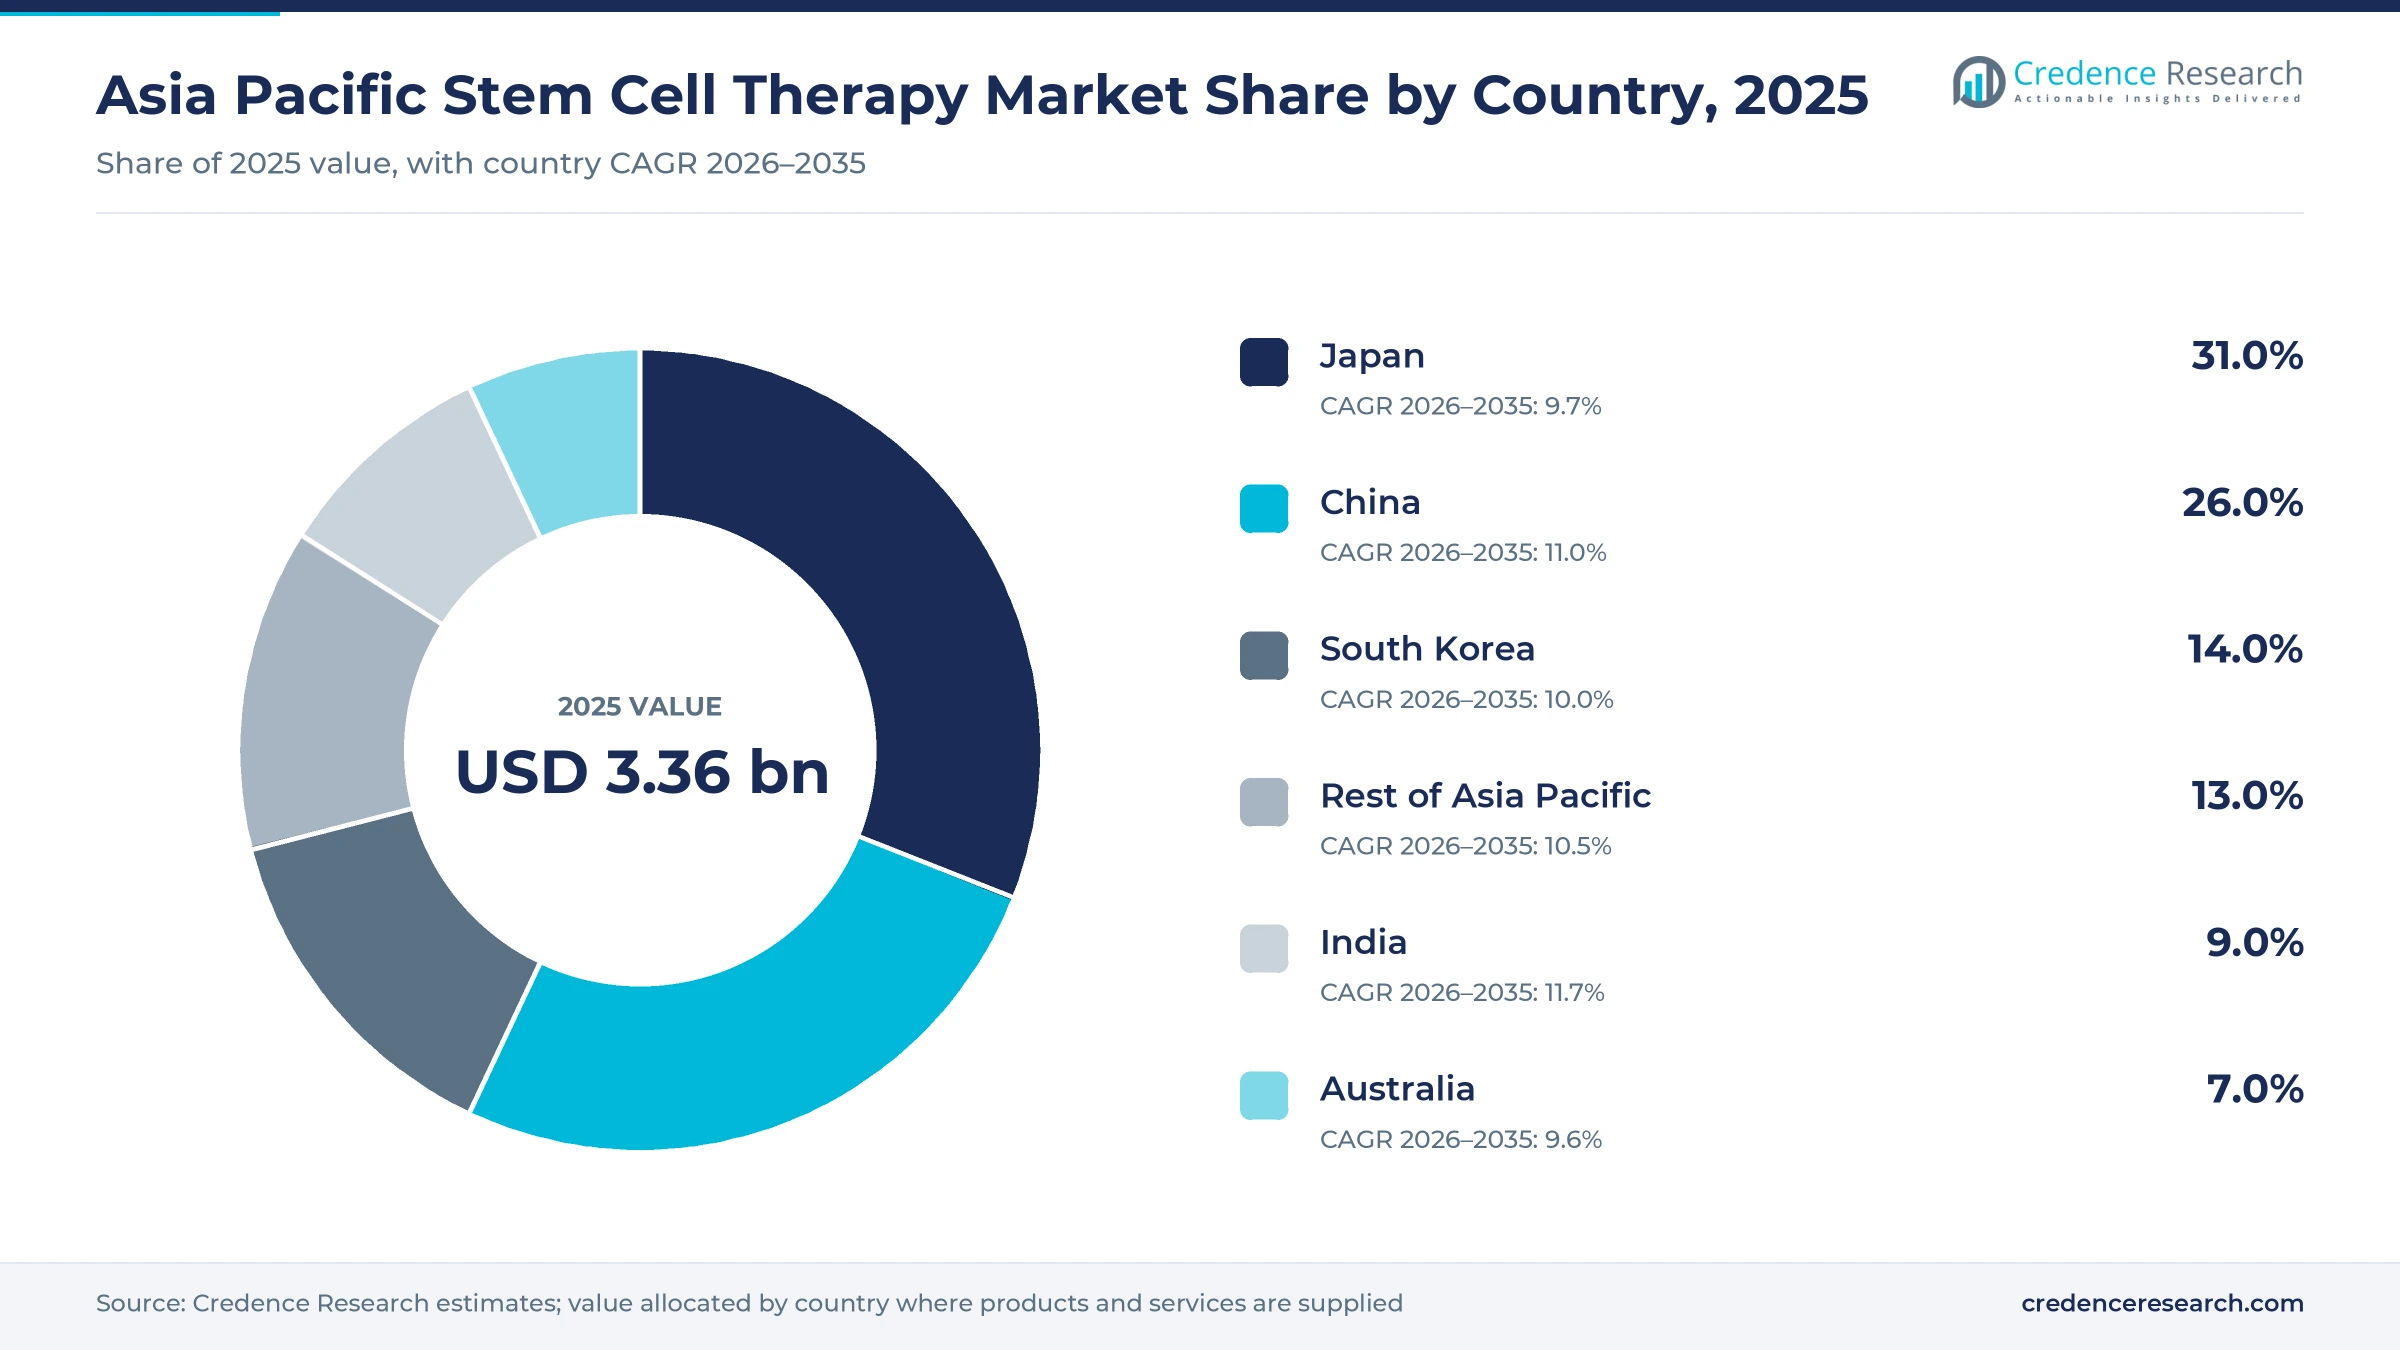
The Asia Pacific stem cell therapy market was valued at USD 3.36 billion in 2025 and is projected to increase from USD 3.71 billion in 2026 to USD 9.00 billion by 2035, registering a CAGR of 10.36% during 2026–2035. Demand comes from hospitals that transplant mesenchymal, cord blood and induced pluripotent stem cell products, from self-pay regenerative clinics, and from developers that buy cell lines, culture media and processing services. Japan held the largest country share, 31.0% in 2025, because insured mesenchymal products such as TEMCELL and the region's largest base of registered self-pay clinic treatments sit there, and the first iPSC-derived products entered national insurance in 2026. India is the fastest-growing country at 11.7% a year in Credence Research estimates, from a small base of approved products. Japan conditionally approved two such products in March 2026, Sumitomo Pharma's Parkinson's disease cells and Cuorips' heart muscle sheets, which set the first per-patient prices for this class.
Insured products and self-pay clinics both carry regional value
The market counts stem cell products used to treat patients in the region, whether they are approved medicines, conditionally approved regenerative products or cells processed for clinic treatments, together with the stem cell lines, culture media and acquisition, production and cryopreservation services that make them. Hospitals buy approved products at insured prices, while clinics charge patients directly.
Routine bone marrow harvests for transplant are counted only where the cells are processed or banked, and gene-modified T-cell products such as CAR-T therapies are excluded. Lines, media and processing services are counted only when sold to a third party, so inputs a product owner makes in-house are not counted twice. Value moves from cell banks and media suppliers through developers and their licensees to transplant centers, orthopedic hospitals and regenerative clinics.
Asia Pacific Stem Cell Therapy Market Insights
- The Asia Pacific stem cell therapy market rises from USD 3.36 billion in 2025 to USD 9.00 billion by 2035, a 10.36% CAGR during 2026–2035, as insured products replace clinic-only treatments.
- Japan held 31.0% of 2025 value, because insured mesenchymal products and the region's largest base of registered clinic treatments sit there.
- Stem Cell Lines led with 46.0% of 2025 value, because most mesenchymal products approved in Japan, China and India are expanded from banked donor cell lines.
- Japan conditionally approved the first two products made from induced pluripotent stem cells on March 6, 2026, with full approval tied to seven years of efficacy data.
- Medipost's Cartistem met all endpoints in its Japanese Phase 3 trial in May 2026, setting up a target of Japanese approval by the end of 2027.
MSC lines lead while iPSC-derived cells grow fastest
Banked MSC lines lead while iPSC-derived cells grow fastest
Based on product, the market is categorized into stem cell lines, culture media and differentiated cell types. Stem Cell Lines led with 46.0% of 2025 value because most approved mesenchymal products in the region are expanded from banked donor lines, and JCR Pharmaceuticals has sold TEMCELL, made from such lines, in Japan since Feb. 24, 2016. Differentiated Cell Types grow fastest at 11.8% a year, as Japan placed Sumitomo Pharma's dopaminergic progenitor cells under national insurance on May 20, 2026, according to Insurance Business Asia. Culture media suppliers gain from both, because every lot needs defined growth media.
Cell production leads while cryopreservation grows fastest
Based on technology, the market is categorized into cell acquisition, cell production and cryopreservation. Cell Production led with 42.0% of 2025 value because expansion under good manufacturing practice is the costliest step, and a single clinical-grade line takes more than a year to make in South Korea, The Korea Times reported in June 2026. Cryopreservation grows fastest at 11.2% a year, as banks ship frozen lines, and the National Stem Cell Bank opened applications on June 30, 2026, for four vials of its KNIH01 clinical-grade line. Frozen stocks also link the market to cord blood banking services.
Regenerative medicine leads while drug discovery grows fastest
Based on application, the market is categorized into regenerative medicine, drug discovery and development, and others. Regenerative Medicine led with 72.5% of 2025 value because every insured product in the region treats tissue damage, and SanBio launched AKUUGO for traumatic brain injury in Japan on May 21, 2026, the company said. Drug Discovery and Development grows fastest at 11.4% a year, as South Korea's National Stem Cell Bank distributed 139 lines to 52 research institutions in 2025, more than double its earlier annual average, with universities taking 67% of demand.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product | Stem Cell Lines | 46.0% | Differentiated Cell Types | 11.8% |
| By Technology | Cell Production | 42.0% | Cryopreservation | 11.2% |
| By Application | Regenerative Medicine | 72.5% | Drug Discovery and Development | 11.4% |
Japanese insurance prices anchor regional price points
Approved stem cell products in Asia Pacific are priced per patient or per bag under national insurance, while self-pay clinics set their own fees. Japan's iPSC-derived products now list above ¥50 million per patient, reflecting autologous or small-batch manufacture and tiny cohorts. Allogeneic mesenchymal products sold from banked lines cost far less per course, which lets them reach more patients. Manufacturing inputs also carry high fixed costs, so developers with a single product earn margins only once cohorts grow. Credence Research expects price cuts at full approval, once larger data sets arrive.
| Product or input | Typical price or fee | Basis |
|---|---|---|
| AKUUGO for traumatic brain injury | ¥72,716,528 national insurance price | SanBio notice, June 2026 |
| Amchepry for Parkinson's disease | ¥55.3 million per patient | Insurance Business Asia, May 2026 |
| RiHEART heart muscle sheet | ¥53.2 million official price | Jiji Press, July 2026 |
| HeartSheet, withdrawn in 2024 | About ¥14.76 million per treatment | PubMed Central review, 2025 |
| TEMCELL HS Inj. for acute GVHD | ¥868,680 per bag of 72 million cells | Mesoblast release, February 2016 |
| Clinical-grade iPSC line in South Korea | More than 800 million won per line | The Korea Times, June 2026 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Insured prices, ageing and new approval routes lift use
Insurance prices for iPSC products set a revenue path
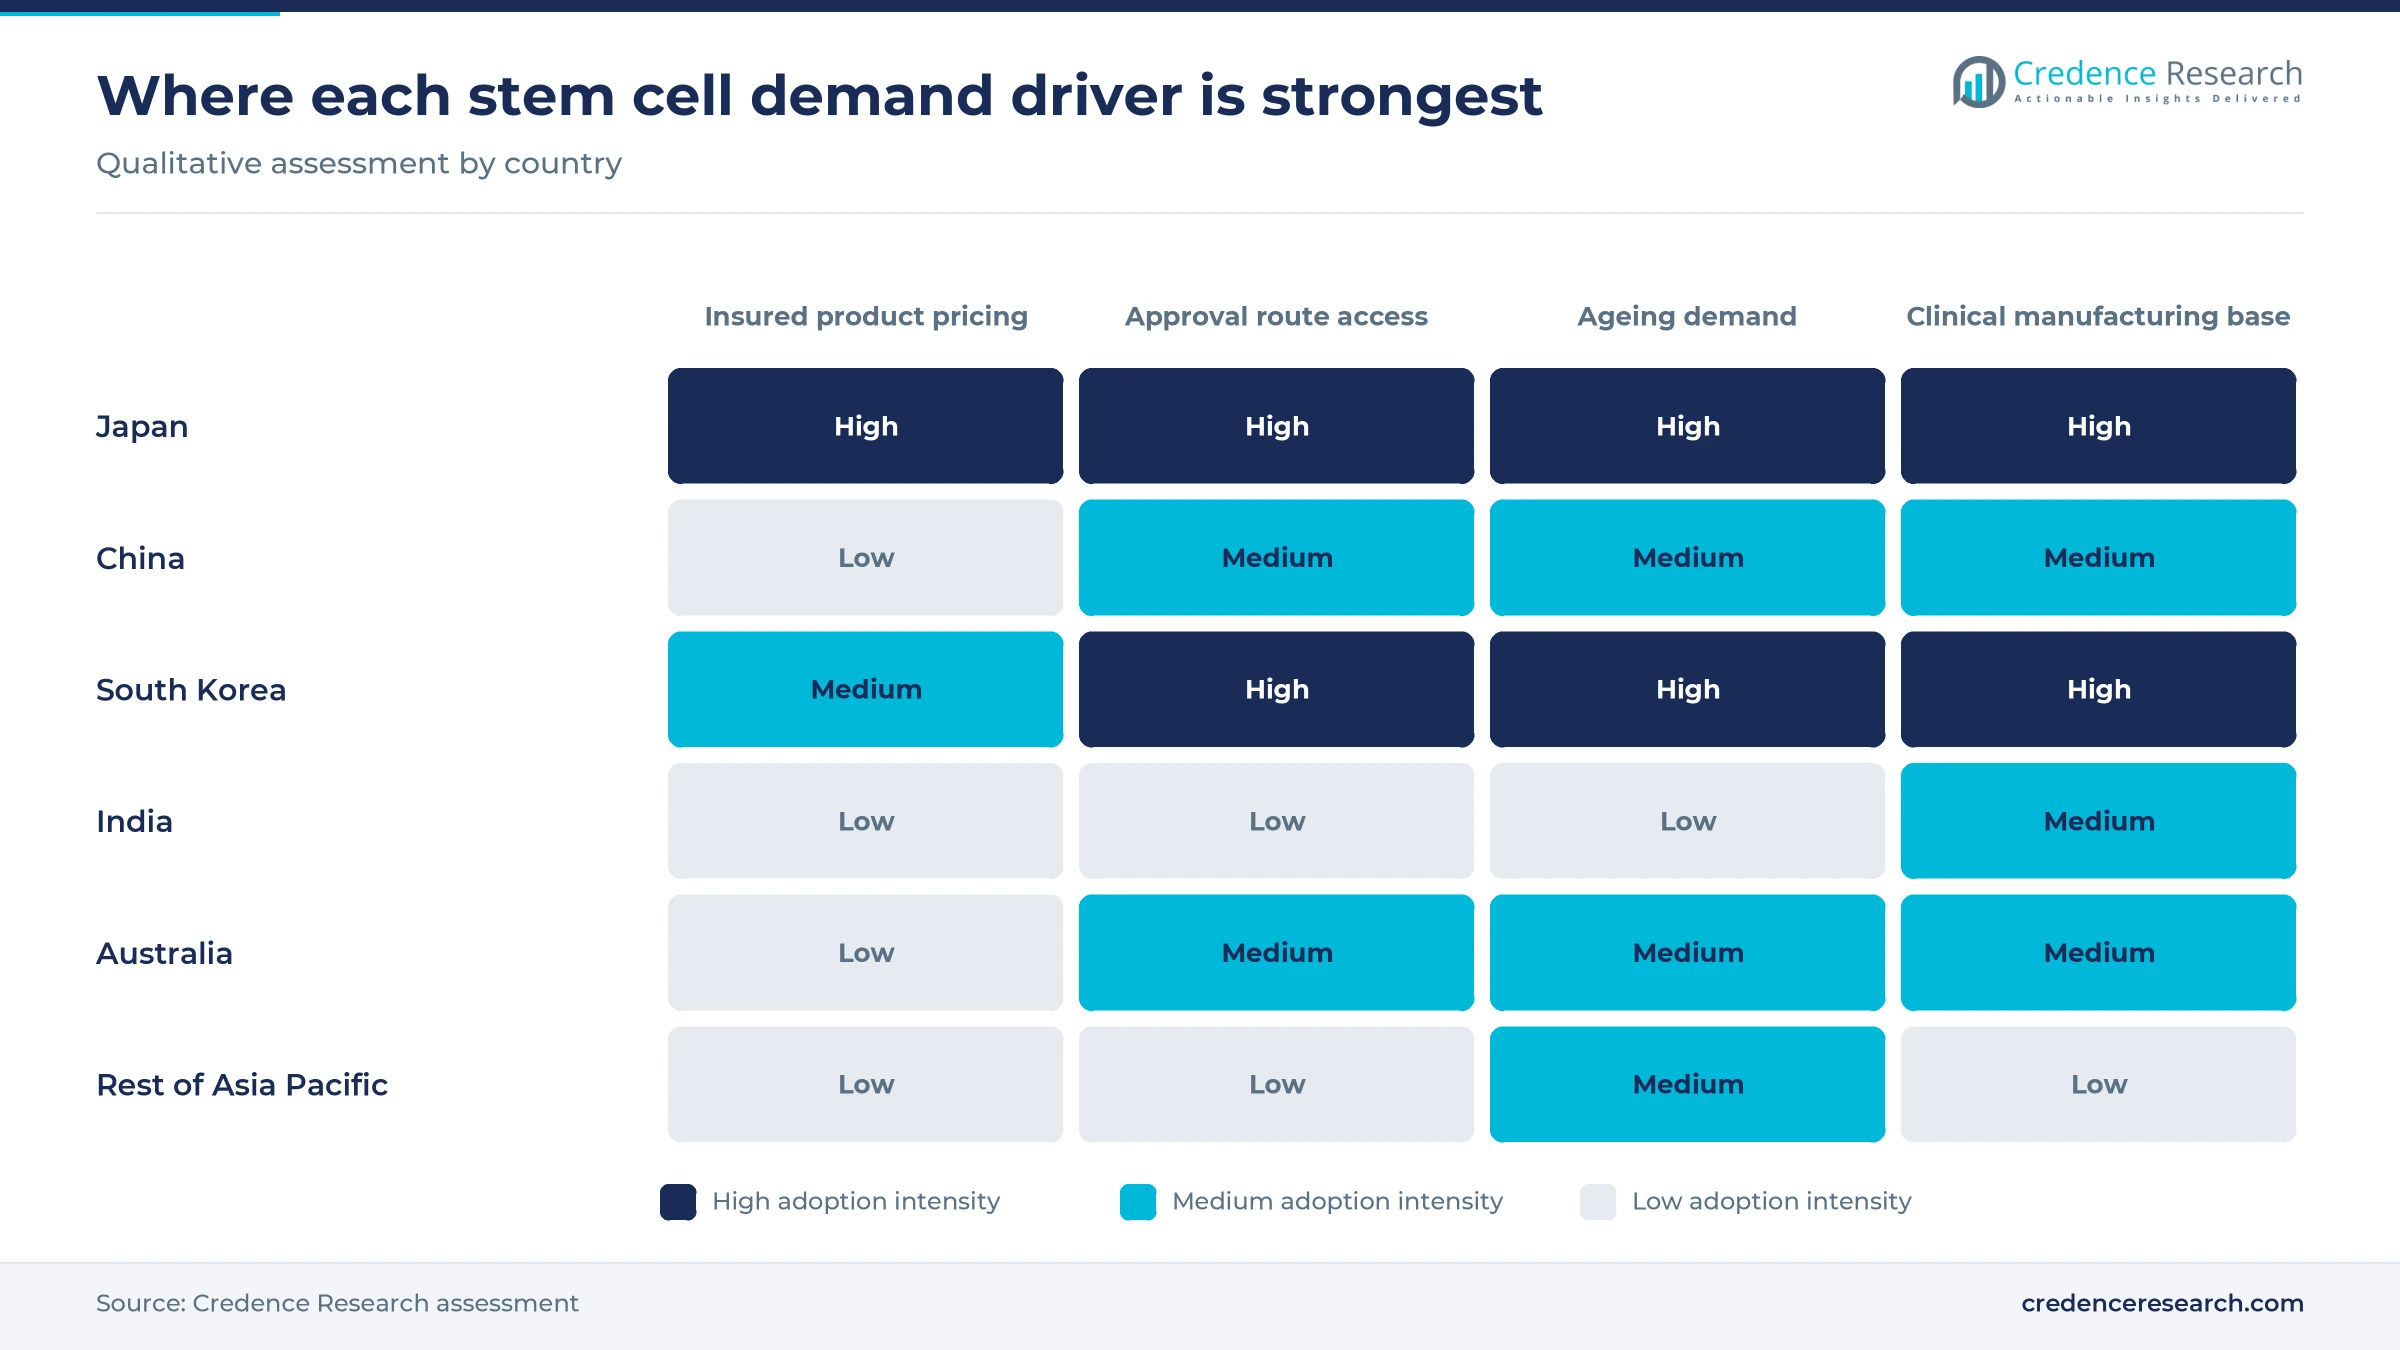
Japan's decision to reimburse the first products made from induced pluripotent stem cells gives developers a defined price for each patient, which turns clinical programs into revenue lines. Amchepry, Sumitomo Pharma's cell product for Parkinson's disease, entered national insurance at ¥55.3 million per patient, according to Insurance Business Asia. Cuorips' RiHEART heart muscle sheet followed on Sept. 1, 2026, at an official price of ¥53.2 million, Jiji Press reported. SanBio also put AKUUGO on sale in May 2026, after the health ministry lifted its shipment restriction in December 2025. These listings favor developers that can price per patient, while transplant hospitals gain new procedures that carry an insured fee.
Older populations widen the pool of degenerative cases
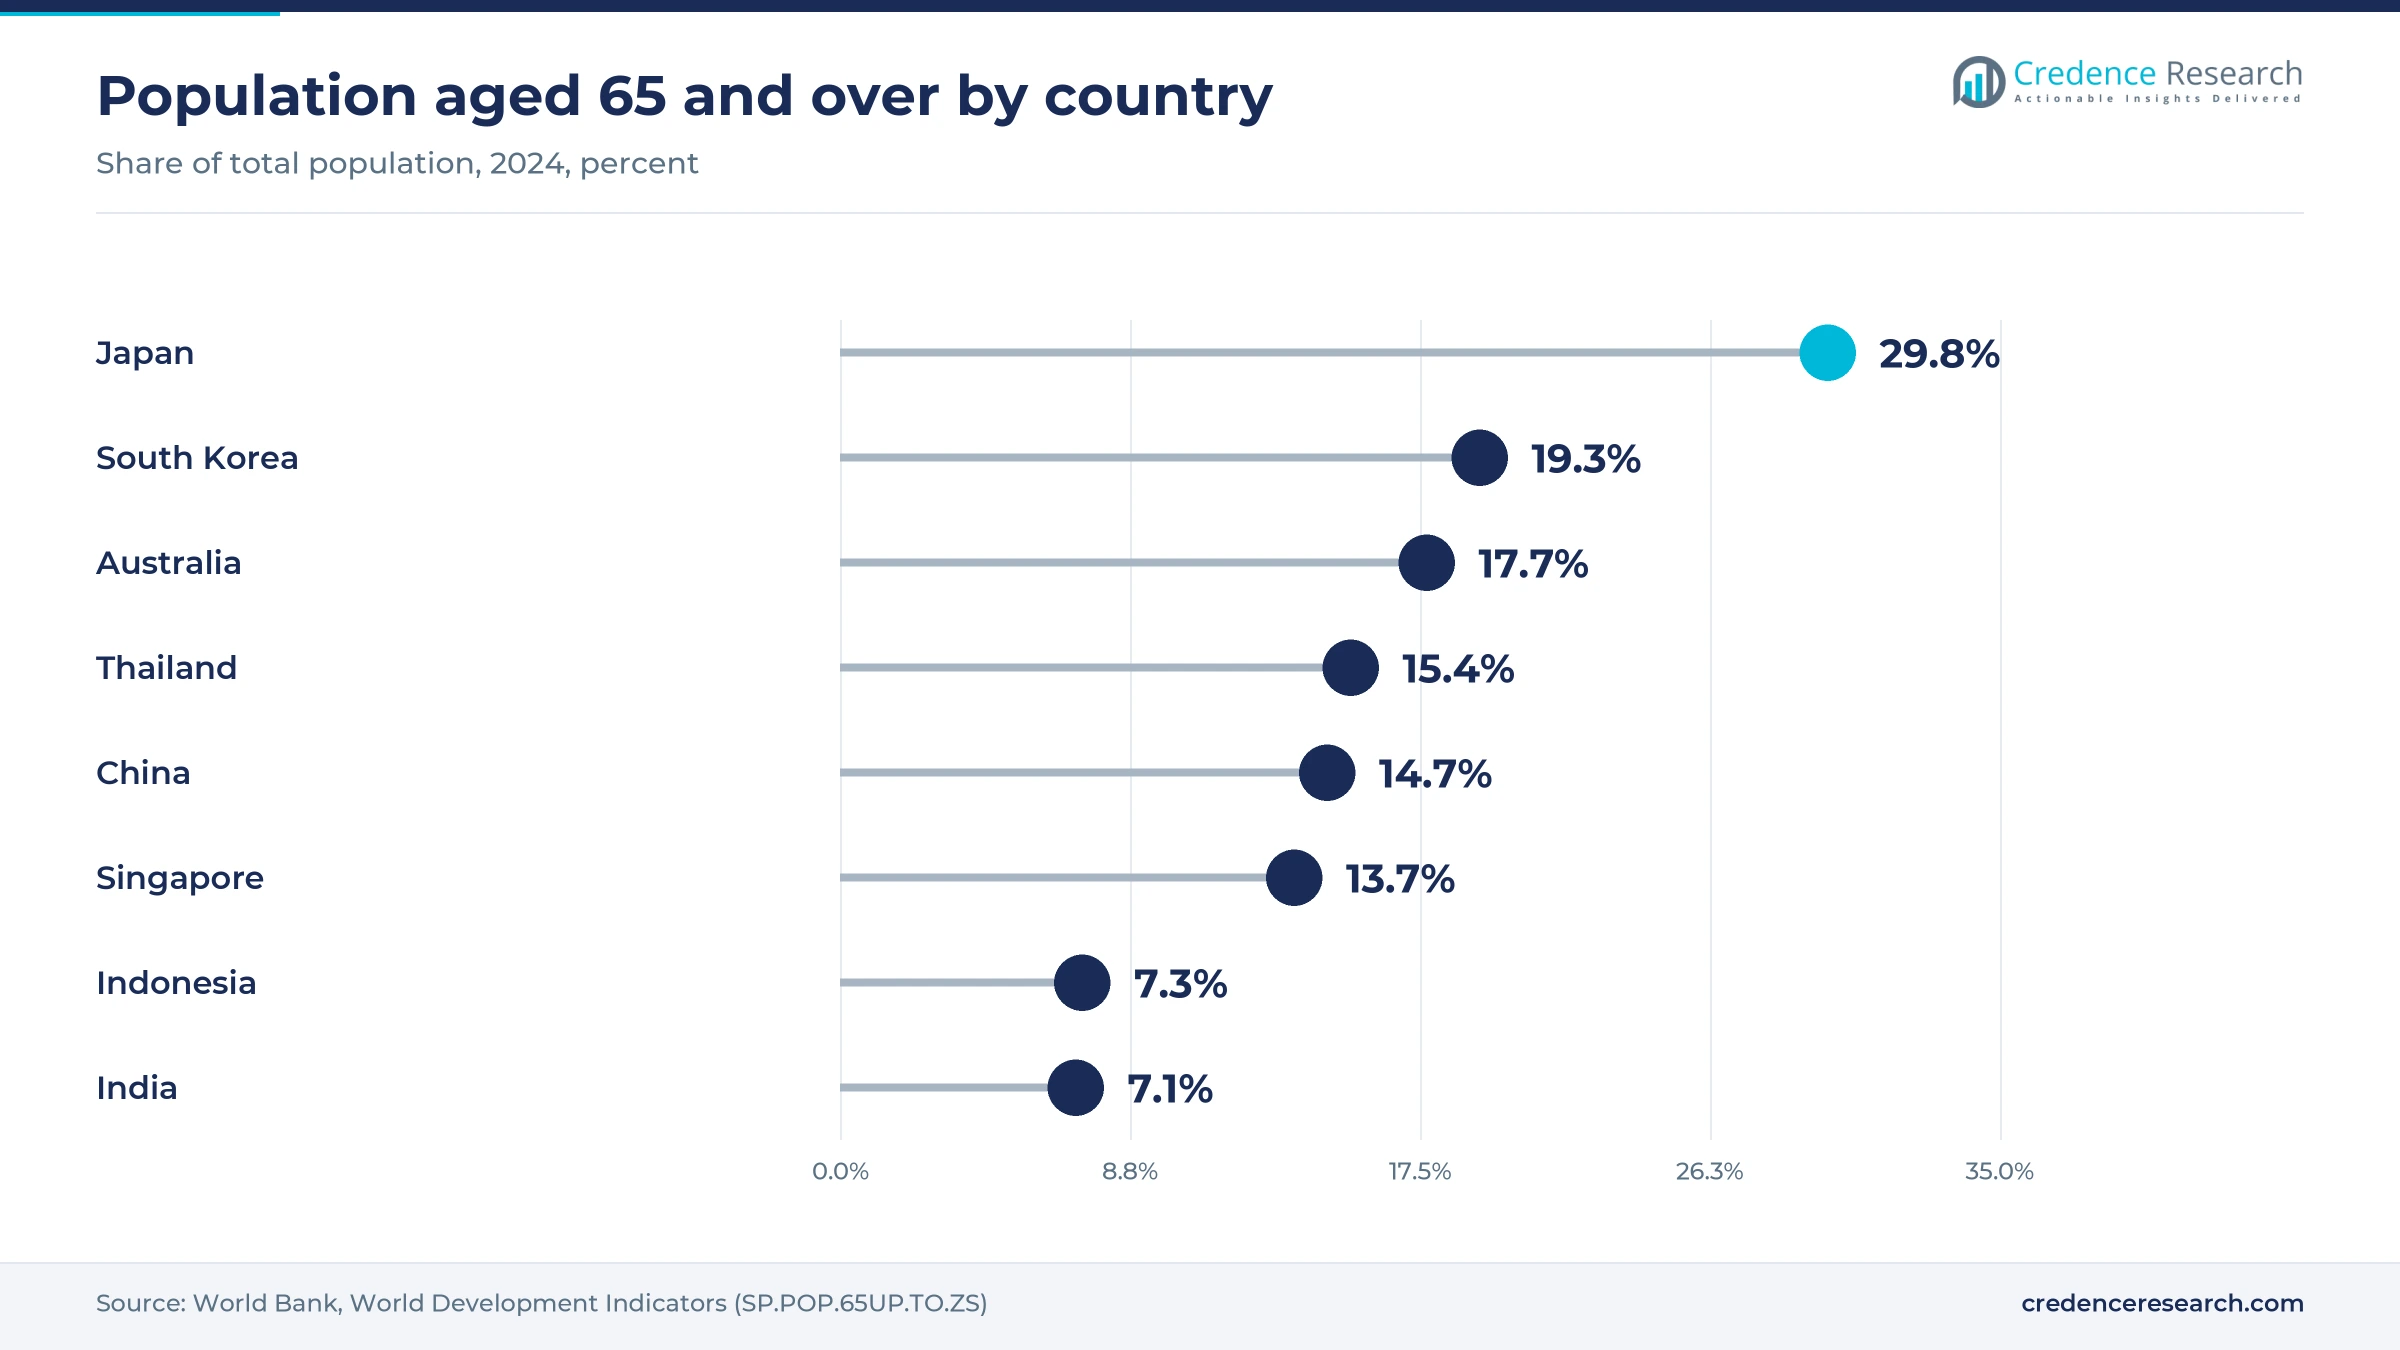
Ageing raises the number of patients with the degenerative conditions that current products target, from knee cartilage loss to Parkinson's disease and heart failure. People aged 65 and over made up 29.8% of Japan's population and 19.3% of South Korea's in 2024, World Bank data show. Medipost's Japanese Phase 3 trial of Cartistem enrolled 130 people with knee cartilage damage, which shows how developers size demand around older orthopedic patients. Japan therefore carries the highest degenerative demand per head in Asia Pacific. India, where people aged 65 and over make up about 7.1% of the population, offers a younger profile, so its demand leans toward blood disorders rather than degenerative disease.
New approval routes in Korea and China admit products
Regulators in South Korea and China opened routes that let stem cell products reach patients before full approval, which pulls hospital demand forward. South Korea began a treatment system on Feb. 21, 2025, under which designated hospitals may use technologies that passed medium- or high-risk clinical research for serious, rare and intractable diseases, Asia Economy reported. China's drug regulator approved Platinumlife's amimestrocel, an umbilical cord mesenchymal product for steroid-refractory acute graft-versus-host disease in patients aged 14 and older, with conditions, the NMPA said. The Korean system cleared its first plan in April 2026 for VaizenCell's VT-EBV-N, an immune cell product, so the stem cell benefit is still ahead. Designated hospitals and developers with Phase 2 data gain first.
Public and donor funding builds clinical-grade supply
Clinical-grade manufacturing capacity is expanding through public and philanthropic money, which lowers the entry cost for smaller developers. The CiRA Foundation's Yanai facility in Kyoto received approval on May 29, 2025, to manufacture cells for clinical research, the foundation said. About ¥1.5 billion of a ¥4.5 billion private donation paid for the facility, which aims to supply patient-specific cells to companies at fair prices. South Korea's National Institute of Health assembled the country's first clinical-grade iPSC line for public distribution in March 2026, The Korea Times reported, giving developers a starting line without their own derivation work. Developers that rent capacity through contract manufacturing in Japan avoid that outlay, which favors asset-light startups.
Hospital supply replaces clinic use as Japan tightens rules
Japan's iPSC products shift from trials into hospitals
Developers in Japan are shifting from clinical research to commercial supply, as the first iPSC-derived products enter hospital use under conditional terms. The health ministry conditionally approved Amchepry and RiHEART on March 6, 2026, as the world's first practical iPS cell-derived medical products, and full approval depends on efficacy data collected over seven years, Jiji Press reported. The companies set initial targets of 35 Parkinson's patients and 75 ischemic cardiomyopathy patients. A patient was treated with RiHEART in September 2026, Ajinomoto said in October 2026, noting that its StemFit medium is used to make the sheets. Small cohorts keep early sales modest, yet transplant centers and cell processing suppliers gain repeat procedures and a template for later iPSC programs.
Japan shifts clinic oversight toward scientific review
Japanese regulators are shifting oversight of self-pay regenerative treatments toward scientific review, adding compliance costs for private clinics. An amendment to the Act on the Safety of Regenerative Medicine took effect on May 31, 2025, requiring review committees to assess scientific validity and adding in vivo gene therapy to the highest risk class, BioPharma APAC reported. A health ministry working group began discussing validity checks for self-pay treatments on July 1, 2026, and the ministry asked providers, committees and manufacturers to run self-inspections on July 31, 2026. At the 2015 baseline, private practice held 1,794 of 1,831 low-risk plans, which shows how much clinic volume sits in this tier. Clinics selling treatments with weak supporting evidence are the most exposed.
Japan opens a filing route for Korean cartilage products
Japan offers Korean developers a second approval route for products that already sell at home, which widens their addressable orthopedic market. Medipost said on May 14, 2026, that Cartistem met all primary and secondary endpoints in its Japanese Phase 3 trial against a hyaluronic acid control, with 59 patients treated and 61 in the control arm. The company plans to file for approval in Japan later in 2026 and targets approval by the end of 2027, with Teikoku Seiyaku holding exclusive distribution rights. South Korea's regulator approved Cartistem for knee cartilage defects in January 2012, according to Daily Pharm. Japanese orthopedic hospitals treating older patients are the target customer group, and a distributor with hospital reach shortens the path from approval to first sales.
Graft-versus-host disease offers an off-the-shelf opening
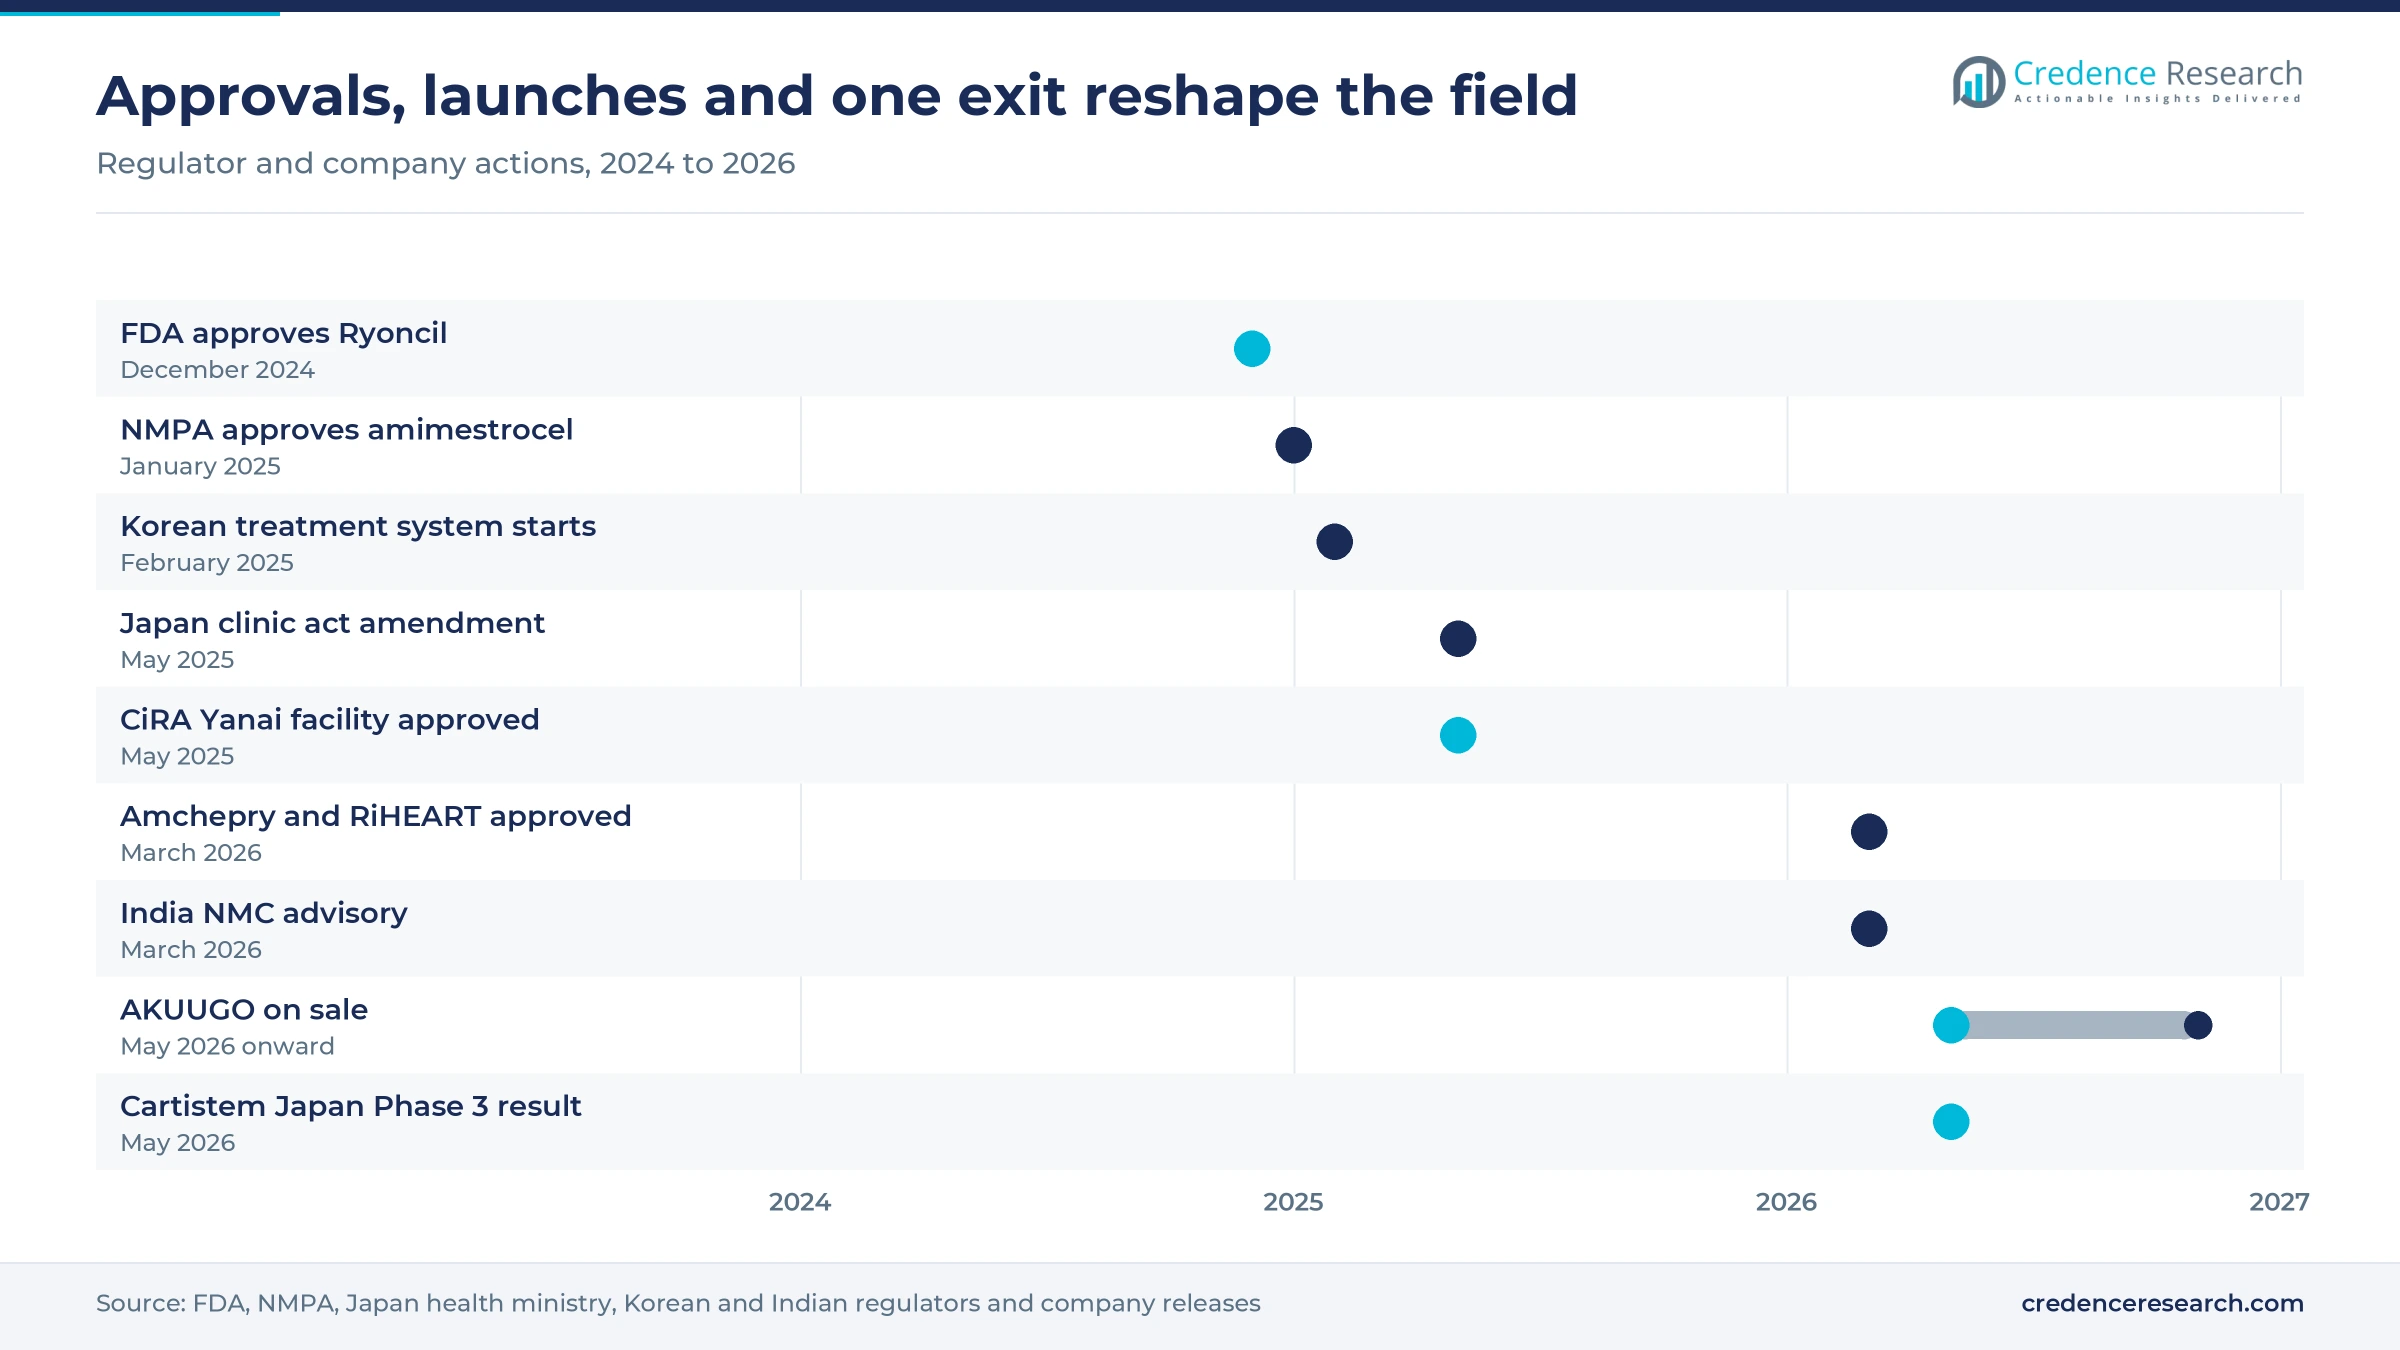
Steroid-refractory acute graft-versus-host disease after bone marrow transplant is an opening for allogeneic products that can be stocked frozen and shipped on demand. The U.S. Food and Drug Administration approved Mesoblast's Ryoncil on Dec. 18, 2024, as the first FDA-approved mesenchymal stromal cell therapy, for children aged two months and older, the agency said. JCR Pharmaceuticals, Mesoblast's licensee in Japan, already sells TEMCELL for the same condition in children and adults, and the Chinese approval noted above targets it too. Every allogeneic hematopoietic transplant program creates candidates, so transplant centers in China and India are the next customer group.
Withdrawals, India limits and mixed trials slow adoption
Conditional approvals can be withdrawn after launch
Conditional approval in Japan does not guarantee a lasting market, because products must later prove benefit. Terumo's HeartSheet, conditionally approved in September 2015, failed the criteria for regular approval on July 19, 2024, and sales stopped the next day, a 2025 review in PubMed Central found. Its post-marketing data compared 49 treated patients with 102 controls. Developers relying on small conditional cohorts, including the new iPSC products, face the same test.
India limits routine use to listed conditions
India restricts routine stem cell treatment to a notified list, which shuts private clinics out of many indications. The National Medical Commission said on March 25, 2026, that mesenchymal stem cell therapy is not approved for any condition and that autism treatment is allowed only in approved trials. A health ministry advisory reported in September 2026 treats unauthorized use and advertising as commercial misconduct. Private clinics selling orthopedic and neurological injections are the most exposed group.
Mixed late-stage evidence slows full approvals
Mixed results from late-stage trials delay full approvals and limit exports for rare-disease products. CorestemChemon's Neuronata-R Phase 3 trial in ALS did not reach statistical significance across all patients, meeting its primary endpoint only in slow progressors, the company said in July 2026. The U.S. Food and Drug Administration then asked for a new confirmatory Phase 3b study before any licence filing, Money Today reported on Nov. 16, 2026. Developers that depend on a single indication in their pipeline are the most exposed.
Clinical-grade facilities cost more than small developers can fund
Building a compliant cell manufacturing facility costs 3 billion to 15 billion won, according to South Korea's National Stem Cell Bank as reported by The Korea Times in June 2026, which keeps early developers dependent on shared or contract capacity. Startups without public funding or a licensing partner are most exposed, because a single clinical-grade line also takes more than a year to make. Developers that cannot secure capacity face delayed trials, which slows regional iPSC demand while only two iPSC products held insurance listings in 2026.
Japan leads on insured products while India grows fastest
| Country | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Japan | 1.04 | 31.0% | 9.7% |
| China | 0.87 | 26.0% | 11.0% |
| South Korea | 0.47 | 14.0% | 10.0% |
| Rest of Asia Pacific | 0.44 | 13.0% | 10.5% |
| India | 0.30 | 9.0% | 11.7% |
| Australia | 0.24 | 7.0% | 9.6% |
Japan leads on insured iPSC and MSC products
Japan held 31.0% of 2025 value and grows at 9.7% a year through 2035. It is the only country in the region where iPSC-derived products carry insured prices, with Amchepry and RiHEART priced above ¥50 million per patient from 2026, while SanBio's AKUUGO launched in May 2026 at the higher national insurance price shown in the pricing table. TEMCELL, the HeartSheet record and the 2025 clinic rules described above show that the country also has the deepest regulatory history. Self-pay clinic volumes are not published, which is an evidence gap in the estimate.
China builds a commercial category from one approval
China held a 26.0% share of 2025 value and grows at 11.0% a year. The conditional approval of amimestrocel, which the NMPA announced in January 2025, created the first commercial mesenchymal product on the mainland, where hospitals had used stem cells mainly through registered clinical research. People aged 65 and over made up 14.7% of the population in 2024, a large absolute base for orthopedic and neurological use. Credence Research found no public price for amimestrocel, which is an evidence gap.
South Korea holds four approved stem cell products
South Korea held 14.0% of 2025 value and grows at 10.0% a year. The country approved four stem cell products between 2011 and 2014, starting with Hearticellgram-AMI in 2011, and none after 2014, Daily Pharm reported in June 2022. More than 400 patients in South Korea have received Neuronata-R, CorestemChemon said in July 2026. The 2025 treatment system and clinical-grade line supply give hospitals new routes, although few stem cell plans have cleared yet.
India grows fastest from a small approved base
India held a 9.0% share of 2025 value and is the fastest-growing country at 11.7% a year. Stempeutics received approval from the Drug Controller General of India to launch Stempeucel for critical limb ischemia caused by Buerger's disease or atherosclerotic peripheral arterial disease, European Pharmaceutical Review reported. Growth comes from transplant centers and approved products, because the 2026 advisories noted above push unapproved clinic use out of the market.
Australia relies on transplant centers and research buyers
Australia held a 7.0% share of 2025 value and grows at 9.6% a year. People aged 65 and over made up 17.7% of Australians in 2024, which sustains orthopedic and graft-versus-host demand at hospital transplant units. Allogeneic mesenchymal products such as the Ryoncil approval noted above show the kind of off-the-shelf product that Australian transplant centers could adopt. Credence Research did not verify current Australian product registrations in this run, which is an evidence gap, so the estimate rests on transplant and research spending.
Southeast Asia and other markets stay early stage
The rest of Asia Pacific held 13.0% of 2025 value and grows at 10.5% a year. Thailand and Singapore had 65-plus shares of 15.4% and 13.7% in 2024, which points to rising degenerative demand in Thailand, Malaysia and Vietnam as well. Credence Research found no locally approved stem cell product in Vietnam, Malaysia, Thailand or other Southeast Asian markets during this review, which is an evidence gap, so value here rests mainly on transplant centers, research buyers and patients traveling to Japan or South Korea.
Approvals, launches and one exit reshape the field
| Development | Status and market relevance |
|---|---|
| In January 2025, China's NMPA conditionally approved Platinumlife's amimestrocel for steroid-refractory acute graft-versus-host disease. | Conditional approval; first mesenchymal product on the mainland. |
| In May 2025, the CiRA Foundation's Yanai facility in Kyoto received approval to manufacture cells for clinical research. | Manufacturing approval; it gives smaller developers access to clinical-grade iPSC supply. |
| In December 2025, Japan's health ministry lifted the shipment restriction on SanBio's AKUUGO, which launched in May 2026. | Approval change completed; commercial launch in May 2026. |
| In March 2026, Japan conditionally approved Sumitomo Pharma's Amchepry and Cuorips' RiHEART. | Conditional, time-limited approval; insurance coverage followed in May and September 2026. |
| In May 2026, Medipost reported that Cartistem met all endpoints in its Japanese Phase 3 trial. | Testing milestone; a Japanese filing is planned later in 2026. |
Dopaminergic grafts, cell sheets and defined media
- Dopaminergic progenitor grafts replace lost neurons in Parkinson's disease, with Amchepry transplanting 5 million to 10 million cells into the brain.
- Cell sheet engineering lets RiHEART deliver heart muscle cells as a patch of 4 to 5 cm and 0.1 mm thick.
- Banked allogeneic mesenchymal lines allow one donor source to supply many patients, holding the cost per course far below autologous products.
- Defined xeno-free culture media such as StemFit AK03N remove animal and human raw materials, which supports traceability for clinical manufacture.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Single-product owners compete through licensees
Competition in the Asia Pacific stem cell therapy market runs product by product, because each approved therapy has one owner and a narrow indication. Sumitomo Pharma and Cuorips hold the first insured iPSC products in Japan, and SanBio holds the only brain injury product. JCR Pharmaceuticals sells TEMCELL under license from Mesoblast, which also owns Ryoncil in the United States. Medipost sells Cartistem in South Korea and has picked Teikoku Seiyaku for Japan, while CorestemChemon defends Neuronata-R with Korean real-world data. Platinumlife holds the first Chinese approval and Stempeutics the leading Indian product. Ajinomoto supplies media to developers, and its role grows as products scale. Companies compete on confirmatory data, insurance pricing, manufacturing approval and hospital access, and many also position products within broader regenerative medicine portfolios.
How is the supply side organized?
The supply side serving Asia Pacific patients runs in three distinct tiers. Product owners such as Sumitomo Pharma, Cuorips, SanBio, Medipost, CorestemChemon, Platinumlife and Stempeutics each hold one or two approved products, so concentration is high within an indication but low across the region. Licensees and distributors such as JCR Pharmaceuticals and Teikoku Seiyaku carry hospital access. Input suppliers, led by media makers such as Ajinomoto and public banks, sell to every developer that builds iPSC platforms. Entry barriers sit in manufacturing approval and confirmatory data, and margins sit with owners of insured products.
Product owners, licensees and input suppliers buyers shortlist
| Company | Type | Role in the market |
|---|---|---|
| Sumitomo Pharma Co., Ltd. | Product owner | Sells Amchepry, iPSC-derived dopaminergic cells for Parkinson's disease, in Japan |
| JCR Pharmaceuticals Co., Ltd. | Licensee and manufacturer | Sells TEMCELL mesenchymal cells for acute graft-versus-host disease in Japan |
| Mesoblast Limited | Product owner | Owns remestemcel-L, licensed to JCR in Japan and approved as Ryoncil in the U.S. |
| SanBio Co., Ltd. | Product owner | Sells AKUUGO cell product for traumatic brain injury in Japan since May 2026 |
| Cuorips Inc. | Product owner | Sells RiHEART iPSC-derived heart muscle sheets for ischemic cardiomyopathy in Japan |
| Medipost Co., Ltd. | Product owner | Sells Cartistem cord blood cells for knee cartilage in South Korea; Japan filing planned |
| CorestemChemon Inc. | Product owner | Sells Neuronata-R autologous bone marrow cells for ALS in South Korea |
| Platinumlife Biotechnology (Beijing) Co., Ltd. | Product owner | Holds China's first approved umbilical cord mesenchymal product, amimestrocel |
| Stempeutics Research Pvt. Ltd. | Product owner | Sells Stempeucel pooled mesenchymal cells for critical limb ischemia in India |
| Ajinomoto Co., Inc. | Input supplier | Supplies StemFit iPSC culture media used to make RiHEART |
Confirmatory data will decide who keeps market access
Credence Research's view is that confirmatory evidence, rather than the number of new approvals, will decide which owners keep access to Asia Pacific patients by 2035. Japan's insured iPSC prices create a clear revenue path, but HeartSheet showed that conditional approval can end abruptly. Allogeneic mesenchymal products from banked lines should widen access fastest in China, South Korea and India, while clinic rules in Japan and India move volume toward approved products. Owners with confirmatory data and a strong licensee are best placed.
Estimates rest on product prices and approval records
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. The 2025 value brings the earlier Credence Research estimate for 2023 forward at its own growth rate and was checked against published product prices, approval records, clinic plan counts and manufacturing costs. Market values come from the Credence Research model, and the country, product, technology and application splits are Credence Research estimates informed by public data. Sources include health ministries and drug regulators in Japan, China, South Korea, India and the United States, the World Bank, company announcements and reputable trade press. No interviews or surveys were used to build these estimates.
Insured iPSC products and transplant demand to 2035
Credence Research expects stem cell therapy value in the region to reach USD 9.00 billion by 2035 as insured products widen and transplant centers adopt off-the-shelf cells. India should keep the fastest pace from a small base, while Japan remains the largest source of value through 2026–2035. iPSC-derived products gain share as cohorts grow beyond their first patients, and mesenchymal lines keep the volume lead. The main risks are failed confirmatory trials, stricter clinic rules and high manufacturing costs, while new Chinese and Korean approvals offer upside.
Confirmatory data and clinic rules set the range
The range to 2035 depends on whether conditional products pass confirmatory review and on how far clinic rules in Japan and India shrink self-pay volume. Full approvals for the iPSC products and a Japanese approval for Cartistem would lift value, while further withdrawals or stricter clinic rules would hold growth below the base case. China's pace of new mesenchymal approvals is the largest swing factor outside Japan.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 7.9% | USD 7.32 billion | Conditional products fail confirmation and clinic rules cut self-pay volume sharply |
| Base | 10.36% | USD 9.00 billion | Current products keep access and a few new approvals arrive each year |
| Upside | 12.4% | USD 10.58 billion | China and South Korea approve several new mesenchymal products before 2030 |
Frequently Asked Questions
How big is the Asia Pacific stem cell therapy market?
Which country leads the market?
How does South Korea compare in stem cell therapy?
What is the position of China?
How much do iPSC therapies cost in Japan?
Is stem cell therapy available in Southeast Asia?
What are the main challenges?
Who are the main companies in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Stem Cell Lines
- 1.2.2 Culture Media
- 1.2.3 Differentiated Cell Types
- 1.3 By Technology
- 1.3.1 Cell Acquisition
- 1.3.2 Cell Production
- 1.3.3 Cryopreservation
- 1.4 By Application
- 1.4.1 Regenerative Medicine
- 1.4.2 Drug Discovery and Development
- 1.4.3 Others
- 1.5 By Country
- 1.5.1 Japan
- 1.5.2 China
- 1.5.3 South Korea
- 1.5.4 India
- 1.5.5 Australia
- 1.5.6 Rest of Asia Pacific
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 3.36 billion → 2035: USD 9.00 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Asia Pacific Stem Cell Therapy Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Asia Pacific Stem Cell Therapy Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Asia Pacific Stem Cell Therapy Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Asia Pacific Stem Cell Therapy Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Asia Pacific Stem Cell Therapy Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Asia Pacific Stem Cell Therapy Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Asia Pacific Stem Cell Therapy Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Asia Pacific Stem Cell Therapy Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 3.36 billion → 2035: USD 9.00 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Asia Pacific Stem Cell Therapy Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Stem Cell Lines
- 12.3.7.2 Culture Media
- 12.3.7.3 Differentiated Cell Types
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cell Acquisition
- 12.4.7.2 Cell Production
- 12.4.7.3 Cryopreservation
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Regenerative Medicine
- 12.5.7.2 Drug Discovery and Development
- 12.5.7.3 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Country - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Japan
- 12.6.7.2 China
- 12.6.7.3 South Korea
- 12.6.7.4 India
- 12.6.7.5 Australia
- 12.6.7.6 Rest of Asia Pacific
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Asia Pacific Stem Cell Therapy End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Asia Pacific Stem Cell Therapy Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Country-Level Shares, 2025
- 14.2 Country Market Size Comparison, 2025
- 14.3 Country Market Forecasts, 2025-2035
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Asia Pacific Stem Cell Therapy Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Asia Pacific Stem Cell Therapy Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Sumitomo Pharma Co., Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 JCR Pharmaceuticals Co., Ltd.
- 18.4 Mesoblast Limited
- 18.5 SanBio Co., Ltd.
- 18.6 Cuorips Inc.
- 18.7 Medipost Co., Ltd.
- 18.8 CorestemChemon Inc.
- 18.9 Platinumlife Biotechnology (Beijing) Co., Ltd.
- 18.10 Stempeutics Research Pvt. Ltd.
- 18.11 Ajinomoto Co., Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

