
Market Overview:
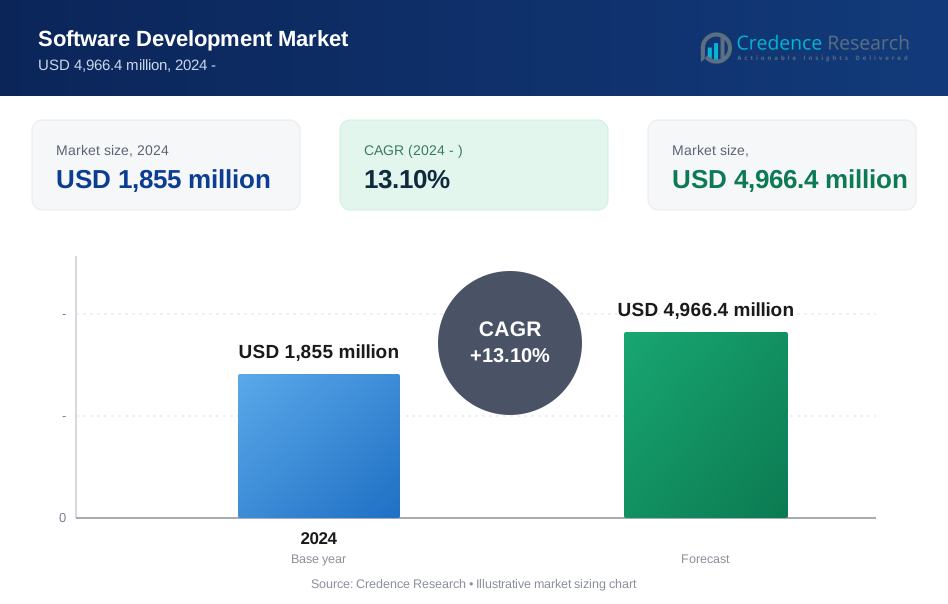
The Software Development Market size was valued at USD 1855 million in 2024 and is anticipated to reach USD 4966.4 million by 2032, at a CAGR of 13.1 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Software Development Market Size 2024 | USD 1855 Million |
| Software Development Market, CAGR | 13.1 % |
| Software Development Market Size 2032 | USD 4966.4 Million |
Key drivers fueling market expansion include the rising need for business agility, enhanced productivity, and competitive differentiation. Organizations are adopting customized software applications to streamline workflows, facilitate remote work, and support complex decision-making processes. The proliferation of mobile devices and the widespread use of SaaS (Software as a Service) models have transformed software delivery and consumption patterns. In addition, the growing emphasis on cybersecurity, regulatory compliance, and data privacy is prompting companies to invest in secure and scalable software architectures. Strategic collaborations, mergers, and acquisitions among technology vendors are further stimulating innovation and enabling faster go-to-market capabilities.
Regionally, North America dominates the Software Development Market, attributed to the presence of major technology companies, advanced IT infrastructure, and strong investment in research and development. The United States leads in software innovation and digital adoption, followed by Canada’s robust enterprise technology sector. Europe holds a substantial market share, supported by stringent data regulations, digital skills development, and government initiatives promoting industry 4.0 transformation. Asia-Pacific is witnessing the fastest growth, with countries like China, India, and Japan leveraging large developer talent pools and expanding digital ecosystems to support domestic and international demand. Latin America and the Middle East & Africa are emerging as attractive markets, driven by growing digitalization and increasing technology investments.
Market Insights:
- The Software Development Market is expected to reach USD 4,966.4 million by 2032, driven by digital transformation and business process optimization.
- Organizations adopt customized software, cloud applications, and SaaS models to boost agility, productivity, and operational efficiency.
- Artificial intelligence and automation drive demand for advanced software, enhancing decision-making, workflow automation, and customer engagement.
- Heightened focus on cybersecurity and regulatory compliance leads companies to invest in secure, scalable architectures and robust risk mitigation.
- Talent shortages and skills gaps in cloud, AI, and cybersecurity continue to challenge market expansion and delay project timelines.
- North America commands 43% of the market, led by the U.S. and Canada, due to strong digital infrastructure and continuous software innovation.
- Asia-Pacific holds a 28% market share and leads in growth, fueled by a large developer base, rapid digital adoption, and government digital initiatives.
Market Drivers:
Digital Transformation and Business Process Optimization:
The accelerating shift toward digital transformation stands as a primary driver in the Software Development Market. Enterprises are prioritizing investments in advanced digital tools and platforms to streamline business operations, automate repetitive tasks, and improve overall efficiency. Cloud-based applications, AI-driven analytics, and mobile-first strategies are enabling companies to adapt to evolving market needs with speed and flexibility. The increasing pressure to reduce operational costs and boost productivity has encouraged organizations to embrace customized software solutions. These efforts are redefining traditional business models and facilitating the transition to data-driven decision-making. The market continues to see demand for scalable, agile software products that support long-term growth.
- For Instance, Microsoft Toshiba deployed Microsoft 365 Copilot to 10,000 employees, resulting in confirmed savings of 5.6 hours per employee each month due to optimized workflows and AI-powered process improvements.
Growing Adoption of Cloud and SaaS Solutions:
The widespread adoption of cloud computing and Software as a Service (SaaS) models is reshaping the Software Development Market. Organizations value the flexibility, cost-effectiveness, and rapid deployment capabilities offered by cloud-native applications. It enables seamless integration, secure access, and real-time collaboration across distributed teams. Businesses are leveraging SaaS for functions such as customer relationship management, enterprise resource planning, and cybersecurity, driving demand for new software development projects. The scalability of cloud infrastructure allows companies to adjust resources based on user demand, fostering innovation and experimentation. This dynamic has prompted both established enterprises and startups to accelerate digital initiatives.
- For Instance, Salesforce customers automate 1.3 trillion business processes each month using Salesforce Flow, saving 109 billion hours of manual work every month.
Expansion of Artificial Intelligence and Automation Technologies:
Artificial intelligence and automation technologies are significantly influencing software development trends. AI-driven applications are powering enhanced customer experiences, predictive analytics, and personalized services across industries. Automation tools are reducing manual workload and streamlining complex workflows, leading to faster product delivery and improved quality assurance. The Software Development Market benefits from the integration of machine learning algorithms, robotic process automation, and natural language processing into modern applications. Organizations recognize the value of embedding intelligence into their digital platforms, creating a strong incentive for continuous software innovation. This evolution fuels ongoing investment in research, talent acquisition, and development capabilities.
Increasing Emphasis on Cybersecurity and Regulatory Compliance:
Heightened concerns about data privacy, cybersecurity threats, and stringent regulatory requirements are shaping software development priorities. Companies must comply with global data protection standards such as GDPR, HIPAA, and CCPA, which require secure software architecture and transparent data practices. It compels technology providers to embed advanced security features into their products and ensure robust vulnerability management. The Software Development Market is witnessing a surge in demand for secure coding practices, automated compliance checks, and real-time threat monitoring. Businesses are prioritizing risk mitigation strategies to safeguard critical information and maintain customer trust. This environment supports the growth of specialized cybersecurity and compliance-focused software solutions.
Market Trends:
Rapid Expansion of Low-Code and No-Code Development Platforms:
Low-code and no-code development platforms are reshaping the Software Development Market by democratizing application creation. These platforms enable non-technical users and citizen developers to design, build, and deploy software solutions with minimal coding expertise. Enterprises are adopting low-code tools to accelerate digital transformation, reduce development cycles, and address resource constraints in IT departments. It empowers organizations to respond quickly to market changes and customer demands while minimizing reliance on traditional software engineering teams. Low-code adoption also enhances collaboration between business units and IT, allowing for faster innovation and prototyping. The trend supports cost-effective scaling of digital solutions across large and small enterprises.
- For instance, Appian guarantees that an organization’s first project will go live within 8 weeks of starting development, showcasing rapid deployment timelines for enterprise-grade applications using its low-code platform.
Widespread Adoption of Agile and DevOps Methodologies:
Agile and DevOps practices are becoming standard in software development, driving faster time-to-market and higher product quality. Organizations are shifting from rigid, traditional project management frameworks to flexible, iterative approaches that emphasize collaboration, continuous integration, and frequent delivery. The Software Development Market benefits from the widespread implementation of automated testing, deployment pipelines, and feedback loops that improve code quality and user satisfaction. It creates an environment where teams can adapt to user feedback, address issues promptly, and implement updates rapidly. The focus on continuous improvement and cross-functional teamwork strengthens software resilience and performance. Adoption of Agile and DevOps practices is fueling a culture of innovation and responsiveness throughout the industry.
- For instance, Spotify: Squads at Spotify are typically composed of 6 to 12 members, each empowered to deliver new features independently, minimizing dependencies and accelerating feature releases.
Market Challenges Analysis:
Talent Shortage and Skills Gap:
The global shortage of skilled software developers presents a significant challenge for the Software Development Market. Companies face persistent difficulty recruiting and retaining talent with expertise in cloud computing, AI, cybersecurity, and advanced programming languages. It drives up labor costs and delays project timelines, impacting competitiveness and innovation. The rapid evolution of technologies often leaves skill sets outdated, requiring ongoing investment in training and upskilling. Competition among employers for top developers further intensifies workforce shortages. Organizations must adapt by fostering continuous learning environments and leveraging automation to address resource constraints.
Rising Complexity in Security and Compliance:
Increasing regulatory demands and evolving cyber threats create complex barriers for software providers. The Software Development Market must comply with stringent global standards while responding to sophisticated attacks on data and infrastructure. It challenges companies to integrate robust security measures into every phase of the development lifecycle. The pace of digital transformation can expose vulnerabilities, making proactive risk management essential. Keeping up with shifting compliance rules across regions requires significant investment in technology and process redesign. Failure to address these challenges can undermine customer trust and damage brand reputation.
Market Opportunities:
Expansion in Emerging Markets and Industry Verticals:
Rising digital adoption across emerging markets presents strong growth opportunities for the Software Development Market. Rapid urbanization, increasing smartphone penetration, and expanding internet infrastructure drive demand for customized software solutions in sectors such as healthcare, finance, retail, and logistics. It enables providers to introduce localized products tailored to unique business needs and regulatory requirements. Governments and enterprises in these regions are investing heavily in digital transformation, creating new avenues for partnerships and innovation. The push toward smart cities and digital government services further accelerates the need for advanced software applications. This trend positions software vendors to capture untapped market segments and diversify their global presence.
Growth in Artificial Intelligence and Automation Applications:
The rising adoption of artificial intelligence and automation offers lucrative opportunities for software developers. Organizations seek intelligent platforms to automate repetitive tasks, improve decision-making, and personalize customer experiences. The Software Development Market benefits from the integration of machine learning, predictive analytics, and natural language processing in both enterprise and consumer-facing applications. It drives demand for new frameworks and tools that simplify AI deployment and management. Sectors such as manufacturing, healthcare, and financial services stand to gain significant efficiency improvements through AI-powered software. This opportunity fuels continued investment in research, collaboration, and advanced technology development.
Market Segmentation Analysis:
By Type:
The Software Development Market covers application software, system software, and customized solutions, with demand for tailored applications and vertical-specific platforms driving growth. Organizations require specialized software to address unique operational requirements, support digital transformation, and gain competitive advantage.
- For instance, Atlassian’s Jira application software is now used by approximately 300,000 customers globally, including 85% of Fortune 500 companies, with over 90% of its customer base having migrated to the cloud as of 2025.
By Deployment Mode:
The market splits into on-premise, cloud-based, and hybrid solutions. Cloud-based deployment leads market growth, favored for its scalability, cost-effectiveness, and support for remote and distributed workforces. Hybrid models attract enterprises seeking flexibility and robust data control, while on-premise options remain essential in sectors with stringent security or compliance mandates.
By Enterprise Size:
The market segments into small and medium-sized enterprises (SMEs) and large enterprises. SMEs are rapidly increasing their investment in software solutions to enhance agility, automate core processes, and access emerging digital channels. Large enterprises continue to allocate significant budgets for advanced software, integrating analytics, AI, and cybersecurity features to manage complex global operations. The Software Development Market, through these segments, adapts to evolving customer needs and drives digital innovation across all organizational sizes and industry verticals.
- For instance, Holded, a management software company for SMEs, acquired over 10,000 users within its first year of launch, demonstrating rapid adoption of integrated ERP platforms that automate accounting, billing, and inventory processes for small businesses.
Segmentations:
By Type:
- Application Software
- System Software
- Customized Solutions
- Middleware
- Open Source Software
By Deployment Mode:
- Cloud-Based
- On-Premise
- Hybrid
By Enterprise Size:
- Small Enterprises
- Medium Enterprises
- Large Enterprises
By Industry Vertical:
- Banking, Financial Services, and Insurance (BFSI)
- Healthcare and Life Sciences
- Retail and E-commerce
- Manufacturing
- IT & Telecom
- Government
- Education
- Transportation and Logistics
- Energy and Utilities
- Others
By Regional:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America:
North America accounts for 43% of the global Software Development Market in 2025, maintaining its leadership position. It benefits from highly developed IT infrastructure, strong R&D investment, and a mature digital ecosystem. The United States leads with continuous software innovation, high adoption of emerging technologies, and the presence of major players like Microsoft, IBM, and Oracle. Canada contributes through its growing enterprise sector and support for digital modernization. Businesses in the region integrate cloud computing, AI, and cybersecurity, fueling demand for advanced software solutions. The Software Development Market thrives on agile methodologies and DevOps adoption, accelerating application deployment. Startups and established vendors compete vigorously, keeping the market dynamic.
Europe:
Europe holds 24% of the Software Development Market, driven by strong digital infrastructure and regulatory focus. It shows robust adoption of automation, IoT, and AI across sectors. GDPR and other data protection laws compel providers to deliver secure, compliant architectures. Enterprises in Germany, the UK, and France invest significantly in IT modernization and Industry 4.0 transition. Collaboration between governments, research institutions, and private firms nurtures innovation and digital skills development. The Software Development Market adopts open-source frameworks and interoperability standards to meet regional diversity. Agile delivery models and cybersecurity practices gain prominence amid complex compliance requirements.
Asia-Pacific:
Asia-Pacific captures 28% of the Software Development Market in 2025 and reports the fastest growth. It boasts a large developer population, expanding digital ecosystems, and rising tech investments. China, India, and Japan lead regional expansion, backed by government digital initiatives and startup activity. Businesses focus on cloud infrastructure, enterprise mobility, and automation to stay competitive. The Software Development Market draws multinational vendors seeking scalable talent and cost efficiencies. Mobile-first cultures and youthful demographics support rapid uptake of innovative applications. Regional policy support for smart cities, fintech, and digital services strengthens market expansion.
Key Player Analysis:
- Microsoft
- Tata Consultancy Services Limited
- Thoughtworks, Inc.
- Brainvire Infotech Inc.
- Capgemini
- Cognizant
- Infopulse
- Infosys Ltd.
- Tietoevry
- Trigent Software, Inc.
Competitive Analysis:
The Software Development Market features intense competition among established technology leaders and specialized service providers. Key players such as Microsoft, Tata Consultancy Services Limited, Thoughtworks, Inc., and Brainvire Infotech Inc. shape the competitive landscape by offering comprehensive software solutions, consulting, and digital transformation services. It rewards firms with deep technical expertise, innovation capacity, and robust client relationships. Market participants focus on continuous product enhancement, strategic alliances, and expansion into emerging industry verticals. Customization, scalability, and security remain critical differentiators as businesses demand solutions tailored to specific operational needs. Rapid adoption of new technologies such as AI, cloud, and DevOps drives further competition, compelling companies to invest in talent and R&D. The Software Development Market remains dynamic, with startups and global corporations competing for market share across diverse regions and industry segments.
Recent Developments:
- In March 2025, Tata Consultancy Services Limited acquired Darshita Southern India Happy Homes for ₹2,250 crore to expand its delivery center infrastructure.
- In December 2024, Capgemini announced the acquisition of Syniti, a US-based enterprise data management software and services provider.
- August 2024, Infopulse, as part of Tietoevry Create, joined the AI-RAN Alliance to advance the use of artificial intelligence in Radio Access Networks, collaborating with global business leaders and academic institutions.
Market Concentration & Characteristics:
The Software Development Market exhibits moderate to high market concentration, dominated by leading global technology firms such as Microsoft, IBM, Oracle, SAP, and Amazon Web Services, alongside a dynamic ecosystem of specialized vendors and startups. It features rapid innovation cycles, a strong focus on research and development, and high barriers to entry driven by capital requirements and technical expertise. The market supports a wide range of delivery models, including on-premise, cloud, and hybrid solutions, catering to diverse enterprise and consumer needs. Intense competition fosters continuous advancement in product features, user experience, and integration capabilities, while client demand for customization, scalability, and security drives differentiation among market participants.
Report Coverage:
The research report offers an in-depth analysis based on Type, Deployment Mode, Enterprise Size, Industry Vertical and Regional. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Developers will embrace AI-powered coding assistants to accelerate development and reduce manual errors.
- Organizations will adopt low-code and no-code platforms to speed application delivery and empower business users.
- Enterprises will shift more workloads to multi-cloud and hybrid-cloud environments, boosting demand for interoperable software.
- Security-by-design will become standard practice, with real-time threat detection embedded throughout the development lifecycle.
- Edge computing trends will drive demand for lightweight, decentralized software tailored to IoT devices.
- Continuous integration and continuous deployment (CI/CD) pipelines will gain wider adoption, improving release frequency and reliability.
- Demand for digital twins and virtual simulation software will grow in manufacturing, healthcare, and smart infrastructure.
- Software vendors will focus on modular and API-first architectures to support seamless integration across ecosystems.
- Increased regulatory scrutiny on data privacy and localization will require software providers to build region-specific compliance capabilities.
- Democratizing software development will open new market segments, as citizen development tools reduce dependency on traditional IT resources.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Digital Transformation and Business Process Optimization
Organizations are investing in advanced digital tools and platforms to streamline operations, automate tasks, and improve efficiency. This shift is driving demand for customized software solutions that enable agility and data-driven decision-making.
Growing Adoption of Cloud and SaaS Solutions
The flexibility, scalability, and cost-effectiveness of cloud-based and SaaS models are prompting businesses to migrate from legacy systems. This trend accelerates software development projects focused on cloud-native and integrated applications.
Expansion of Artificial Intelligence and Automation Technologies
AI and automation are being embedded into software to enhance customer experiences, automate workflows, and provide predictive analytics. This drives ongoing investment in new software development to support intelligent, adaptive business processes.
Increasing Emphasis on Cybersecurity and Regulatory Compliance
With rising cyber threats and stricter data regulations, companies are prioritizing secure software architectures and compliance features. This is fueling demand for software solutions that integrate advanced security and automated compliance checks.
Rapid Expansion of Low-Code and No-Code Development Platforms
Low-code and no-code platforms are democratizing software creation, enabling faster application delivery and empowering non-technical users. This trend addresses IT resource constraints and accelerates digital transformation across industries.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Software Development Market?
What factors are driving the growth of the Software Development Market?
What are the key segments within the Software Development Market?
What are some challenges faced by the Software Development Market?
Who are the major players in the Software Development Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Application Software
- 1.2.2 System Software
- 1.2.3 Customized Solutions
- 1.2.4 Middleware
- 1.2.5 Open Source Software
- 1.3 By Deployment Mode
- 1.3.1 Cloud-Based
- 1.3.2 On-Premise
- 1.3.3 Hybrid
- 1.4 By Enterprise Size
- 1.4.1 Small Enterprises
- 1.4.2 Medium Enterprises
- 1.4.3 Large Enterprises
- 1.5 By Industry Vertical
- 1.5.1 Banking, Financial Services, and Insurance (BFSI)
- 1.5.2 Healthcare and Life Sciences
- 1.5.3 Retail and E-commerce
- 1.5.4 Manufacturing
- 1.5.5 IT & Telecom
- 1.5.6 Government
- 1.5.7 Education
- 1.5.8 Transportation and Logistics
- 1.5.9 Energy and Utilities
- 1.5.10 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,855 million → 2032: USD 4,966.4 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Software Development Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Software Development Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Software Development Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Software Development Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Software Development Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Software Development Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Software Development Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Software Development Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,855 million → 2032: USD 4,966.4 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Software Development Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Application Software
- 12.3.6.2 System Software
- 12.3.6.3 Customized Solutions
- 12.3.6.4 Middleware
- 12.3.6.5 Open Source Software
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Deployment Mode - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Cloud-Based
- 12.4.6.2 On-Premise
- 12.4.6.3 Hybrid
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Enterprise Size - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Small Enterprises
- 12.5.6.2 Medium Enterprises
- 12.5.6.3 Large Enterprises
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Industry Vertical - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Banking, Financial Services, and Insurance (BFSI)
- 12.6.6.2 Healthcare and Life Sciences
- 12.6.6.3 Retail and E-commerce
- 12.6.6.4 Manufacturing
- 12.6.6.5 IT & Telecom
- 12.6.6.6 Government
- 12.6.6.7 Education
- 12.6.6.8 Transportation and Logistics
- 12.6.6.9 Energy and Utilities
- 12.6.6.10 Others
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Software Development End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Software Development Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Software Development Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Software Development Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Microsoft
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Tata Consultancy Services Limited
- 18.4 Thoughtworks, Inc.
- 18.5 Brainvire Infotech Inc.
- 18.6 Capgemini
- 18.7 Cognizant
- 18.8 Infopulse
- 18.9 Infosys Ltd.
- 18.10 Tietoevry
- 18.11 Trigent Software, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

