
Market Overview
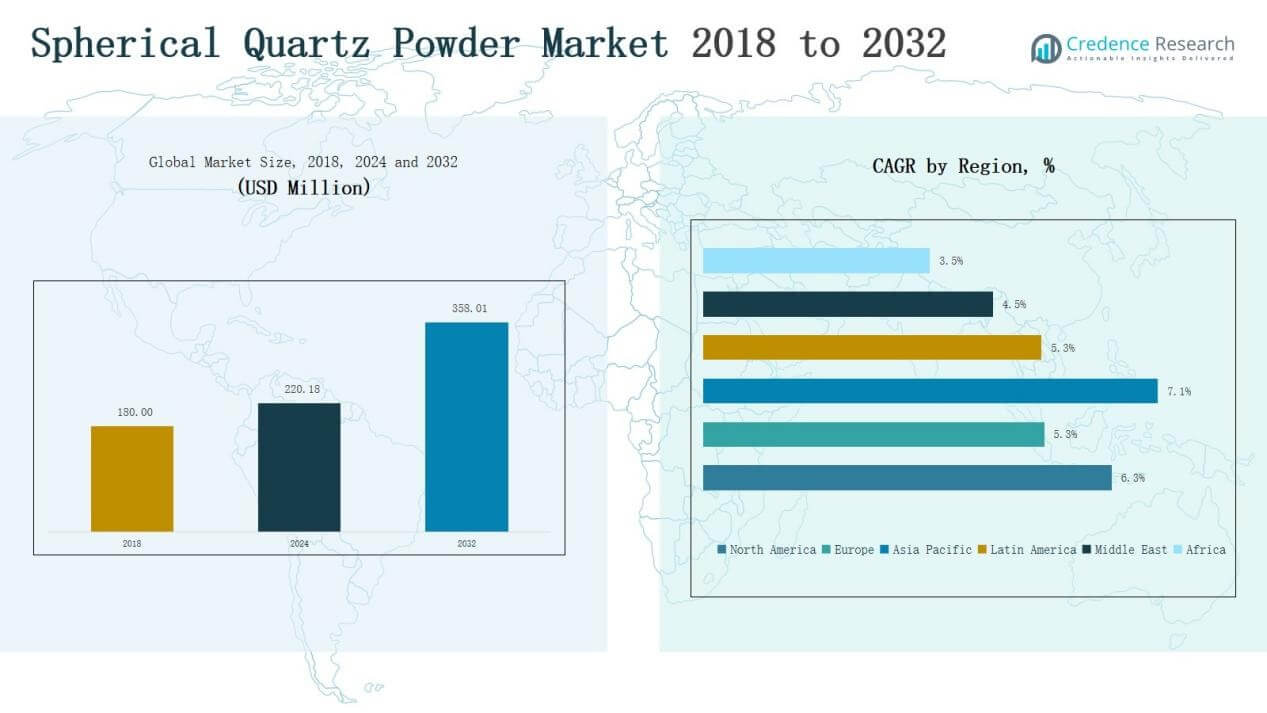
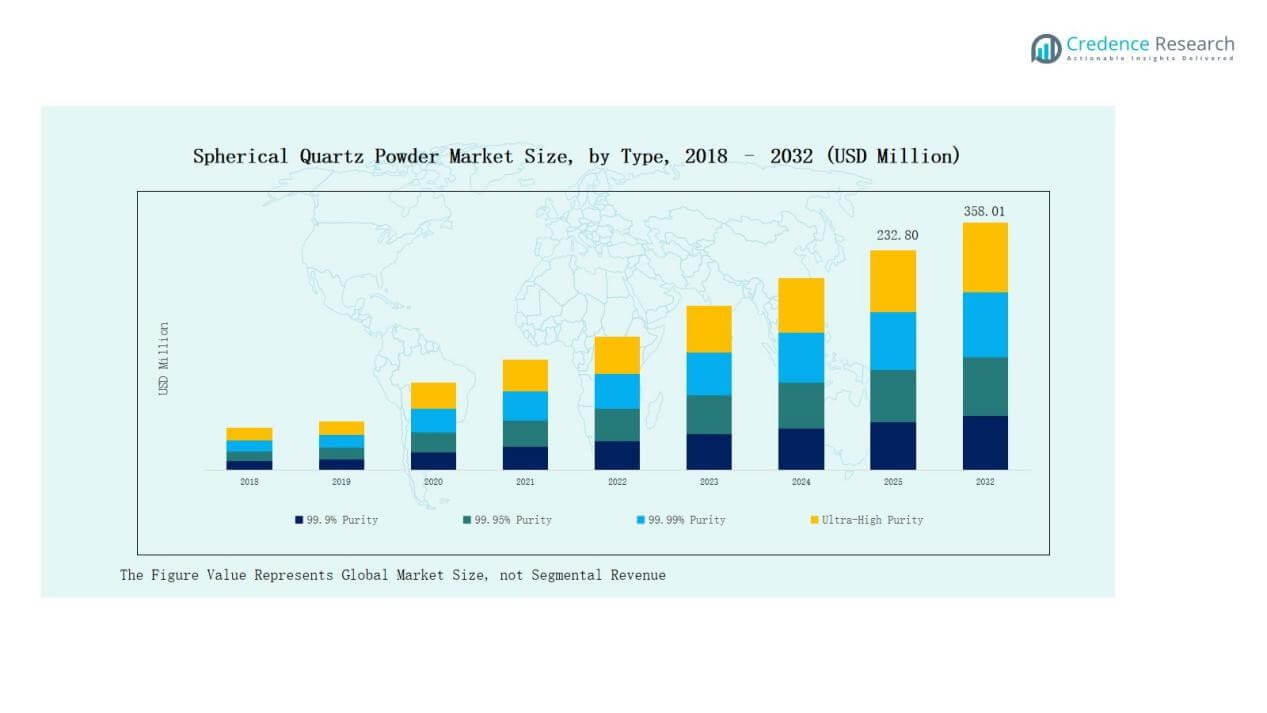
The Spherical Quartz Powder Market size was valued at USD 180.00 million in 2018, reached USD 220.18 million in 2024, and is anticipated to reach USD 358.01 million by 2032, growing at a CAGR of 6.34% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Spherical Quartz Powder Market Size 2024 | USD 220.18 Million |
| Spherical Quartz Powder Market, CAGR | 6.34% |
| Spherical Quartz Powder Market Size 2032 | USD 358.01 Million |
The Spherical Quartz Powder Market is characterized by the presence of prominent global and regional players focusing on purity levels, technological advancements, and application-specific solutions. Leading companies include SINOENERGY Group, ALPA Powder Technology, Sinonine, Micron, Denka, Tatsumori, Shin-Etsu Chemical, Tanki New Materials, Tongrun Nano Technology, NOVORAY, Admatechs, FUSO Chemical, Sibelco, Nippon Chemical, and Pacific Quartz, all of which compete through product innovation, high-purity offerings, and strong supply networks. Regionally, Asia Pacific dominated the market in 2024 with a 49% share, supported by robust semiconductor manufacturing, rapid electronics adoption, and expanding automotive and industrial applications.
 Market Insights
- The Spherical Quartz Powder Market grew from USD 180.00 million in 2018 to USD 220.18 million in 2024 and is projected at USD 358.01 million by 2032, expanding at a 34% CAGR.
- The 99% purity type segment led with a 38% share in 2024, supported by demand in semiconductor and electronics manufacturing requiring superior chemical stability and minimal impurities.
- By application, semiconductor packaging dominated with 41% share in 2024, driven by rising chip production, miniaturization trends, and growing use in fan-out and wafer-level packaging.
- The semiconductor and electronics industry held 47% share in 2024, with growth driven by digitalization, 5G deployment, and consumer electronics demand, while automotive and aerospace added steady contributions.
- Asia Pacific commanded 49% share in 2024, valued at USD 103.23 million, supported by semiconductor hubs in China, Japan, South Korea, and India, making it the fastest-growing region globally.
Market Segment Insights
By Type
The 99.99% purity segment dominated the market in 2024 with a 38% revenue share, driven by its widespread use in high-end semiconductor and electronics manufacturing. Its superior chemical stability, low thermal expansion, and minimal impurities make it ideal for advanced integrated circuit packaging. Rising demand for high-performance chips in 5G, AI, and cloud computing continues to strengthen this segment. Ultra-high purity grades are also gaining traction, fueled by growth in aerospace and optical applications requiring extreme material reliability.
For instance, Merck KGaA introduced new electronic-grade specialty materials designed for AI-driven chip manufacturing processes.
By Application
Semiconductor packaging led the market in 2024 with a 41% share, supported by surging chip production and miniaturization trends. Spherical quartz powder ensures uniform filling, low shrinkage, and thermal conductivity in encapsulation materials, enabling higher device performance. The growing adoption of advanced packaging techniques, including fan-out and wafer-level processes, boosts demand. Electronics and optical components followed closely, driven by consumer devices and communication systems. Expanding use in coatings, adhesives, and emerging 3D printing applications is broadening growth opportunities across industries.
For instance, Kyocera developed a new optical substrate using fine spherical silica powder, enhancing reliability in 5G components and fueling its use in high-speed communication devices.
By End-Use Industry
The semiconductor and electronics segment accounted for the largest share at 47% in 2024, owing to rising investments in chip manufacturing and next-generation technologies. Spherical quartz powder plays a vital role in insulation, encapsulation, and precision component manufacturing. Rapid digitalization, 5G deployment, and demand for consumer electronics fuel this dominance. The automotive and aerospace industries also contribute significantly, leveraging quartz powder in advanced sensors and lightweight components. Industrial manufacturing and telecommunications add steady demand across specialized technical applications.
Key Growth Drivers
Rising Demand from Semiconductor Packaging
Semiconductor packaging remains the largest demand driver, with spherical quartz powder widely used in encapsulants and fillers. Its properties-low thermal expansion, high purity, and strong insulation-support high-performance chips. The boom in consumer electronics, 5G networks, and AI-driven applications amplifies demand. Increasing wafer-level and fan-out packaging adoption also boosts consumption. Leading semiconductor hubs in Asia-Pacific and North America continue to expand capacity, further solidifying the importance of quartz powder as a strategic material for advanced chip manufacturing processes.
For instance, TSMC announced plans to expand its advanced packaging facility in Chiayi, Taiwan, investing $2.9 billion to enhance capacity for wafer-level system-on-integrated-chips (SoIC).
Advancements in Electronics and Optical Applications
Electronics and optical component producers increasingly favor spherical quartz powder for its clarity, durability, and thermal stability. Its applications range from LEDs and displays to precision optical lenses. The rapid growth in smartphones, IoT devices, and connected consumer electronics creates sustained demand. In optics, high-purity quartz supports the performance of photonics and laser systems. With industries moving toward miniaturization and energy-efficient solutions, the reliability of quartz powder ensures its continued integration into new product designs, strengthening market growth globally.
For instance, Jiangsu Shengtian New Material Co., Ltd from China manufactures high-purity spherical silica powder used in optical lenses and photonics due to its excellent fluidity and small surface area.
Expansion of Aerospace and Automotive Industries
The aerospace and automotive sectors are steadily increasing adoption of spherical quartz powder in high-performance components. Its role in lightweight composites, thermal coatings, and advanced sensors enhances efficiency and safety. Automotive electrification, autonomous driving technologies, and in-flight communication systems demand advanced materials with superior heat resistance and stability. Quartz powder’s unique characteristics meet these needs effectively. Continuous investment in electric vehicles and aerospace innovation provides long-term growth opportunities, positioning quartz powder as a vital input for critical applications.
 Key Trends & Opportunities
Shift Toward Ultra-High Purity Grades
An increasing trend toward ultra-high purity quartz powder is evident, especially for semiconductors and aerospace. With rising miniaturization and stringent reliability requirements, manufacturers prefer 99.99% purity and above. These grades ensure minimal contamination, stable performance, and compatibility with advanced fabrication processes. The opportunity lies in scaling production technologies to consistently deliver such high-purity products. Companies investing in purification and precision processing techniques are well-positioned to capture market share as industries shift toward ultra-reliable, next-generation material solutions.
For instance, in aerospace, ultra-high purity quartz is essential for producing optical fibers used in communication systems on aircraft, where impurities could compromise signal clarity and safety.
Emerging Use in 3D Printing Materials
3D printing presents a growing opportunity for spherical quartz powder as industries explore new material applications. Its flowability, thermal resistance, and ability to enhance composite structures make it valuable for additive manufacturing. Aerospace, automotive, and industrial sectors are experimenting with quartz-based powders for high-strength, heat-resistant prototypes and components. As adoption of additive manufacturing broadens, demand for specialized powders is expected to accelerate. This trend creates a new growth pathway for suppliers diversifying beyond traditional electronics and semiconductor markets.
For instance, TRUNNANO, a reputable supplier, offers spherical quartz powder with a mass fraction of up to 90.5% in resin composites, enhancing thermal stability and matching the thermal expansion of monocrystalline silicon for electronic components.
Key Challenges
High Production and Processing Costs
Producing high-purity spherical quartz powder involves advanced purification, energy-intensive processes, and strict quality control. These steps significantly raise production costs, making the material more expensive than substitutes. Price sensitivity in downstream industries, especially automotive and consumer electronics, often limits widespread adoption. Small and mid-tier manufacturers face difficulties competing with global players that achieve economies of scale. Managing production costs while maintaining required purity levels is a critical challenge, slowing adoption in cost-conscious markets despite growing technical demand.
Environmental and Regulatory Constraints
The extraction and processing of quartz powder raise environmental concerns, including dust emissions, energy usage, and waste management. Governments are enforcing stricter environmental regulations and occupational safety standards for quartz mining and handling. Compliance increases operational costs for manufacturers. In some regions, tightening regulations restrict quartz production capacity, creating supply chain risks. Companies must invest in cleaner production technologies and ensure compliance, but these measures add cost and complexity. Failure to adapt may result in supply disruptions and penalties.
Supply Chain Dependence and Raw Material Availability
The market faces risks from raw material supply dependence, particularly in regions with limited quartz mining resources. A few countries dominate the supply of high-purity quartz, creating potential vulnerabilities from trade restrictions, geopolitical tensions, or export bans. Transportation delays and rising logistics costs also add pressure to global supply chains. As demand rises from electronics and aerospace, ensuring consistent and secure raw material access becomes a major challenge. Diversifying sourcing and building resilient supply chains are critical priorities.
Regional Analysis
North America
North America accounted for a 24% market share in 2024, valued at USD 53.19 million, up from USD 44.28 million in 2018. By 2032, the market is projected to reach USD 86.32 million, growing at a CAGR of 6.3%. Growth is driven by strong semiconductor and electronics manufacturing in the U.S., coupled with increasing adoption in aerospace and automotive industries. Expanding investments in advanced packaging technologies and defense applications further strengthen demand. The region benefits from a robust industrial base and technological innovations, positioning it as a key growth hub within the global spherical quartz powder market.
Europe
Europe captured a 18% share of the global market in 2024, generating USD 40.13 million, compared to USD 34.65 million in 2018. By 2032, the market is forecasted to reach USD 60.24 million, reflecting a CAGR of 5.3%. Growth is supported by advancements in electronics, automotive components, and optical industries. Germany, France, and the UK lead demand with strong semiconductor supply chains and industrial manufacturing. Regulatory emphasis on high-quality materials and energy-efficient technologies drives adoption. Despite moderate growth, Europe remains a significant contributor to global demand, supported by established manufacturing clusters and steady end-user industry expansion.
Asia Pacific
Asia Pacific dominated the global spherical quartz powder market with a 49% share in 2024, valued at USD 103.23 million, up from USD 82.44 million in 2018. The market is anticipated to reach USD 177.32 million by 2032, registering the fastest growth with a CAGR of 7.1%. China, Japan, South Korea, and India drive demand, supported by strong semiconductor manufacturing, rapid electronics adoption, and expanding automotive production. The region’s role as a global hub for chip fabrication and industrial innovation solidifies its dominance. Favorable government policies and rising investments in advanced technologies continue to accelerate regional market expansion.
 Market Segmentations:
By Type
- 9% Purity
- 95% Purity
- 99% Purity
- Ultra-High Purity
By Application
- Semiconductor Packaging
- Electronics
- Optical Components
- Coatings
- Adhesives & Sealants
- 3D Printing Materials
- Others
By End-Use Industry
- Semiconductor & Electronics
- Automotive
- Aerospace
- Telecommunications
- Industrial Manufacturing
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The spherical quartz powder market is moderately consolidated, with a mix of global leaders and regional specialists competing on purity levels, product innovation, and application-specific solutions. Key players such as SINOENERGY Group, ALPA Powder Technology, Shin-Etsu Chemical, Denka, Tatsumori, Admatechs, NOVORAY, FUSO Chemical, and Sibelco dominate through advanced manufacturing technologies and established supply networks. These companies focus on developing ultra-high purity grades to meet stringent requirements of the semiconductor and electronics sectors, which remain the largest demand drivers. Partnerships with downstream industries, capacity expansions, and investments in precision processing strengthen market positions. Smaller regional firms, including Tongrun Nano Technology and Tanki New Materials, compete through customization and cost-effective offerings, particularly in emerging markets. Competition is also shaped by environmental compliance and supply chain security, pushing manufacturers to adopt sustainable processes. Overall, innovation, purity assurance, and strategic alliances are critical factors determining competitive advantage in this evolving market.
Key Players
- SINOENERGY Group
- ALPA Powder Technology
- Sinonine
- Micron
- Denka
- Tatsumori
- Shin-Etsu Chemical
- Tanki New Materials
- Tongrun Nano Technology
- NOVORAY
- Admatechs
- FUSO Chemical
- Sibelco
- Nippon Chemical
- Pacific Quartz
Recent Developments
- In July 2025, Cabot Corporation launched LITX® 95F conductive carbon for energy storage systems, highlighting its focus on advanced materials innovation.
- In January 2025, Wacker Chemie AG opened new specialty silicone production facilities in Japan and South Korea, strengthening its high-purity chemicals presence.
- In July 2025, Wacker Chemie AG commissioned the Etching Line Next for ultra-pure semiconductor silicon production, reinforcing its capabilities in high-purity material processing.
- In October 2024, Momentive Technologies acquired Sibelco’s spherical alumina and spherical silica businesses in South Korea, strengthening its advanced materials portfolio.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End Use Industry and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand from semiconductor packaging will continue to dominate due to advanced chip designs.
- Adoption of ultra-high purity quartz powder will rise in electronics and aerospace applications.
- Expansion of 5G networks and AI-driven technologies will increase material requirements.
- Growing use of spherical quartz powder in optical components will support precision manufacturing.
- Automotive electrification will drive adoption in sensors, coatings, and advanced components.
- Emerging applications in 3D printing will create new growth opportunities.
- Industrial manufacturing will expand usage in adhesives, sealants, and coatings.
- Sustainability practices in production will gain importance due to regulatory pressures.
- Asia Pacific will maintain its leadership with strong semiconductor and electronics industries.
- Strategic collaborations among suppliers and end users will accelerate product innovation.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Spherical Quartz Powder Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Spherical Quartz Powder Market projected to grow between 2025 and 2032?
Which Spherical Quartz Powder Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Spherical Quartz Powder Market?
Who are the leading companies in the Spherical Quartz Powder Market?
Which region commanded the largest share of the Spherical Quartz Powder Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 220.18 million → 2032: USD 358.01 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Spherical Quartz Powder Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Spherical Quartz Powder Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Spherical Quartz Powder Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Spherical Quartz Powder Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Spherical Quartz Powder Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Spherical Quartz Powder Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Spherical Quartz Powder Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Spherical Quartz Powder Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 220.18 million → 2032: USD 358.01 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Spherical Quartz Powder Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Spherical Quartz Powder Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Spherical Quartz Powder Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Spherical Quartz Powder Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
