
Market Overview:
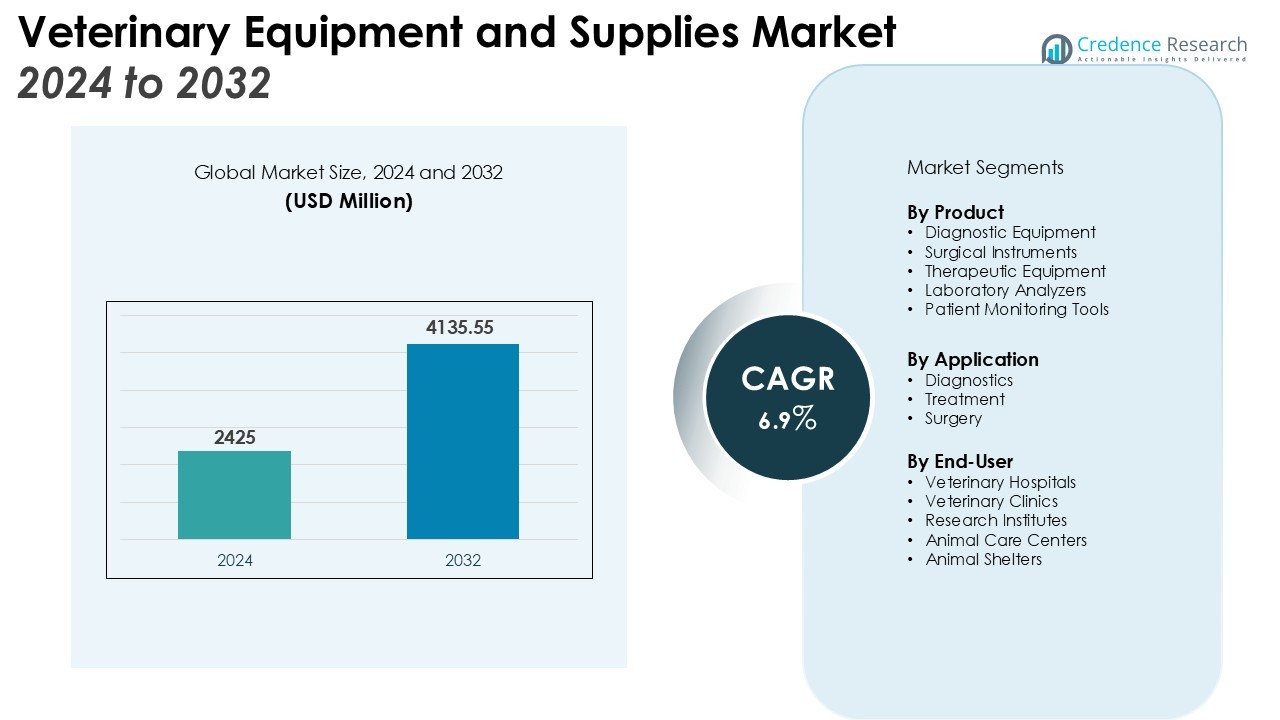
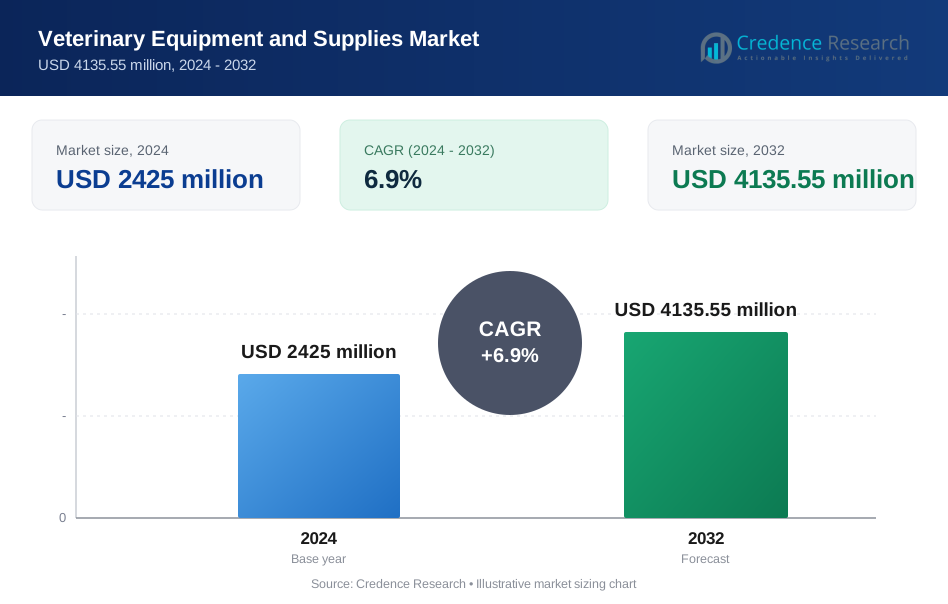
The Veterinary Equipment and Supplies Market size was valued at USD 2425 million in 2024 and is anticipated to reach USD 4135.55 million by 2032, at a CAGR of 6.9% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Veterinary Equipment and Supplies Market Size 2024 | USD 2425 Million |
| Veterinary Equipment and Supplies Market, CAGR | 6.9% |
| Veterinary Equipment and Supplies Market Size 2032 | USD 4135.55 Million |
Key drivers of the market include the growing pet population globally, particularly in developed regions, which fuels the demand for veterinary services and equipment. The continuous technological advancements in veterinary diagnostics and treatment, such as the development of digital imaging systems, surgical instruments, and monitoring equipment, further support market growth. Additionally, the growing awareness of animal health and welfare, coupled with an increasing number of veterinary clinics and animal hospitals, is contributing to the rising demand for veterinary equipment and supplies. The increasing trend of pet adoption, particularly in emerging markets, also plays a significant role in expanding the market.
Regionally, North America holds the largest market share due to the high pet ownership rates and well-established healthcare infrastructure. Europe follows closely, supported by rising investments in animal healthcare and a growing focus on pet wellness. The Asia-Pacific region is expected to witness the highest growth, driven by expanding veterinary services, rising disposable income, and growing awareness about animal health in emerging economies like China and India. The surge in government initiatives to improve veterinary care standards in these regions further accelerates market expansion.
Market Insights:
- The Veterinary Equipment and Supplies Market is expected to grow at a CAGR of 6.9%, reaching USD 4135.55 million by 2032, driven by an increasing demand for veterinary services and equipment globally.
- Advancements in diagnostic tools, surgical instruments, and digital imaging systems are improving the quality and efficiency of veterinary care, thereby expanding the market.
- Rising pet ownership, particularly in developed countries and emerging markets, is significantly boosting demand for veterinary services and the equipment required for animal health management.
- A global focus on animal health and welfare is driving pet owners to invest in higher-quality veterinary services, benefiting the market for sophisticated veterinary equipment.
- North America dominates the market with a 43% share, driven by high pet ownership rates, advanced healthcare infrastructure, and a focus on preventive care. Europe follows with a 27% market share, while the Asia-Pacific region is expected to experience the highest growth.
- The growing number of veterinary clinics, hospitals, and specialized treatment centers worldwide is fueling the demand for advanced equipment and supplies, particularly in emerging markets.
- The high cost of advanced equipment, such as digital imaging and surgical tools, poses a challenge for veterinary practices, particularly in emerging markets, limiting the widespread adoption of cutting-edge technologies.
Market Drivers:
Increasing Pet Ownership and Adoption Rates
The rising pet ownership across the globe, particularly in developed countries, significantly boosts the demand for veterinary services and equipment. The growing awareness of the benefits of pet care and the increasing trend of pet adoption contribute to the expanding market. Veterinary Equipment and Supplies Market benefits from a higher volume of pet healthcare requirements, leading to a greater need for advanced diagnostic and treatment tools in veterinary clinics.
- For instance, Zoetis has invested nearly $1 million annually in partnership with Adopt a Pet, which has facilitated over 223,000 pet adoptions through more than 17,000 animal shelters and rescues, directly enhancing access to veterinary care.
Technological Advancements in Veterinary Care
Ongoing advancements in veterinary diagnostics and treatment technologies play a critical role in market growth. New innovations such as digital imaging systems, advanced surgical instruments, and patient monitoring equipment improve the quality and efficiency of veterinary care. These developments help to diagnose and treat a wide range of diseases and conditions, increasing the demand for modern veterinary equipment.
- For instance, IDEXX Laboratories' ImageVue DR30 digital imaging system reduces radiation dose to 18.6 milliroentgens from 246.3 milliroentgens typical of computed radiography, delivering superior image contrast and sharpness while ensuring safer diagnostics for both pets and veterinary staff.
Rising Animal Health Awareness
There is a growing global focus on animal welfare and health, driving the demand for quality veterinary services and equipment. Pet owners are becoming more proactive in maintaining their animals' health, fueling the need for sophisticated equipment. Veterinary Equipment and Supplies Market is benefiting from this heightened awareness, with pet owners willing to invest in better healthcare options for their animals.
Expansion of Veterinary Clinics and Hospitals
The increasing number of veterinary clinics, hospitals, and specialized treatment centers worldwide supports the demand for veterinary equipment and supplies. These facilities require a wide range of tools and equipment for everyday operations and complex procedures. The growth in veterinary infrastructure, particularly in emerging economies, further drives market expansion, as more facilities adopt advanced technology for improved pet healthcare services.
Market Trends:
Growth in Preventive Veterinary Care
The Veterinary Equipment and Supplies Market is experiencing a shift toward preventive care as pet owners increasingly prioritize routine check-ups and early detection of health issues. This trend is driving demand for diagnostic equipment, such as blood analyzers and imaging devices, designed for routine health assessments. Early detection of diseases such as cancer, diabetes, and kidney disease is leading to better treatment outcomes and reducing overall healthcare costs. The focus on preventive care is particularly prominent in developed regions, where pet owners are more educated on the importance of regular veterinary visits. Veterinary clinics are incorporating advanced diagnostic tools to meet the growing demand for preventive healthcare solutions.
- For instance, IDEXX Laboratories placed over 300 IDEXX inVue Dx™ Cellular Analyzers in Q1 2025 during the transition from a controlled rollout to broad market availability.
Integration of Advanced Technologies
The Veterinary Equipment and Supplies Market is also witnessing an increasing integration of advanced technologies like artificial intelligence (AI) and telemedicine in veterinary care. AI-powered tools are enhancing diagnostic accuracy, while telemedicine allows pet owners to access veterinary consultations remotely. These technological advancements improve both the accessibility and efficiency of veterinary services. Veterinary clinics are adopting these tools to streamline operations, reduce costs, and provide better care. This shift toward digital solutions is particularly evident in emerging markets, where technological adoption is growing rapidly, thus expanding the reach and capabilities of veterinary practices. These trends are contributing to the accelerated growth of the veterinary equipment and supplies market.
- For instance, Vetology’s AI diagnostic platform generates detailed radiology reports for veterinary X-rays within 5 to 10 minutes of image upload, improving diagnostic efficiency by increasing reports processed per hour from 6.5 to 8, which can reduce a 40-case workday by up to 3 hours, thus streamlining veterinary diagnostics effectively.
Market Challenges Analysis:
High Cost of Advanced Equipment
One of the major challenges faced by the Veterinary Equipment and Supplies Market is the high cost of advanced veterinary equipment. Sophisticated tools, such as digital imaging systems and surgical instruments, require significant investment from veterinary clinics and hospitals. Smaller practices or those in emerging markets may find it difficult to afford such high-end equipment, limiting their ability to provide advanced care. This price barrier restricts the widespread adoption of innovative technologies, despite their potential to improve diagnostic accuracy and treatment outcomes. The cost factor also impacts the market’s growth in price-sensitive regions where cost-effective solutions are preferred.
Regulatory and Compliance Issues
The veterinary equipment market faces regulatory hurdles and compliance requirements that can delay product launches and innovation. Stringent regulations regarding the safety, quality, and performance standards of veterinary devices create a complex environment for manufacturers. Compliance with local and international regulatory bodies can lead to long approval timelines, increasing costs and delaying market entry. These regulations can also create challenges for smaller manufacturers, limiting competition and innovation within the Veterinary Equipment and Supplies Market. Adhering to these standards while maintaining profitability remains a significant challenge for companies in this space.
Market Opportunities:
Expanding Pet Care Market
The growing pet care market presents significant opportunities for the Veterinary Equipment and Supplies Market. As pet ownership continues to rise globally, the demand for veterinary services, including routine check-ups and emergency care, increases. This expanding market offers opportunities for manufacturers to innovate and develop specialized equipment tailored to the needs of pet owners. Veterinary practices are seeking to upgrade their equipment to provide better diagnostic and treatment options, driving the demand for advanced technologies. The rise in disposable income, particularly in emerging markets, is also contributing to the growth of this opportunity, making it an attractive sector for investment.
Advancements in Telemedicine and AI Integration
Telemedicine and AI integration provide substantial opportunities within the Veterinary Equipment and Supplies Market. As veterinary practices adopt digital solutions for remote consultations, diagnostic tools powered by AI can enhance diagnostic accuracy and streamline treatment plans. This technology expansion presents an opportunity for equipment suppliers to offer cutting-edge solutions designed for telemedicine and AI applications. Veterinary clinics and hospitals can leverage these technologies to improve operational efficiency and patient outcomes. With the growing trend of digital transformation in veterinary care, this represents a key opportunity for market players to capitalize on these emerging trends.
Market Segmentation Analysis:
By Product
The Veterinary Equipment and Supplies Market is primarily driven by diagnostic equipment, including imaging systems, laboratory analyzers, and patient monitoring tools. These products dominate the market due to the increasing demand for accurate diagnostics and early disease detection. Surgical instruments and therapeutic equipment also contribute significantly, as veterinary procedures become more advanced, catering to complex surgeries and treatments.
- For instance, IDEXX Laboratories has revolutionized veterinary diagnostics with its AI-powered SediVue Dx, which completes urine sediment analysis in under three minutes, enhancing diagnostic efficiency and accuracy.
By Application
The market is segmented into diagnostics, treatment, and surgery. Diagnostics hold the largest share, driven by the growing emphasis on early disease detection and the need for accurate, real-time results. Treatment and surgery applications are also expanding, with innovations in minimally invasive procedures and specialized instruments improving patient outcomes and operational efficiency.
- For instance, Siemens Healthineers leverages AI-powered diagnostic solutions that help radiologists reduce interpretation time while maintaining accuracy, addressing workloads of over 100 studies per day and cutting diagnostic errors significantly.
By End-User
Veterinary hospitals and clinics lead the market, accounting for a substantial share. These facilities require a wide range of equipment for both routine care and complex procedures. The increasing number of pet owners and the expansion of veterinary services in emerging economies contribute to the demand. Other end-users, such as research institutes and animal care centers, are also key segments, with growing investments in animal health and wellness.
Segmentations:
By Product
- Diagnostic Equipment
- Surgical Instruments
- Therapeutic Equipment
- Laboratory Analyzers
- Patient Monitoring Tools
By Application
- Diagnostics
- Treatment
- Surgery
By End-User
- Veterinary Hospitals
- Veterinary Clinics
- Research Institutes
- Animal Care Centers
- Animal Shelters
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North American Veterinary Equipment and Supplies Market holds the largest market share of 43%. High pet ownership rates and a well-established healthcare infrastructure contribute to this dominant position. The U.S. leads the market, with increasing demand for both basic and advanced veterinary equipment. The region’s focus on preventive care and the rising prevalence of pet diseases support continued market growth. The presence of key industry players in North America fosters innovation, ensuring steady market expansion.
Europe
The European Veterinary Equipment and Supplies Market holds a share of 27%. Rising investments in animal healthcare and growing pet ownership drive market demand. Countries like Germany and the UK have seen an increase in the adoption of advanced veterinary equipment, fueled by the rising focus on preventive care and animal welfare. The growing pet insurance market also supports veterinary service accessibility, further boosting the demand for medical supplies and equipment. Government initiatives contribute to a favorable regulatory environment, accelerating market growth.
Asia-Pacific
The Asia-Pacific Veterinary Equipment and Supplies Market accounts for a share of 20%. The region is experiencing rapid growth, driven by rising disposable incomes, changing lifestyles, and increasing pet ownership, particularly in emerging economies like China and India. Awareness regarding animal health and the expansion of veterinary services significantly contribute to this growth. As the region’s veterinary infrastructure improves, the demand for advanced diagnostic and treatment tools is expected to rise, offering substantial opportunities for manufacturers.
Key Player Analysis:
- Covetrus, Inc.
- B. Braun Melsungen AG
- DRE Veterinary
- Vetland Medical Sales and Services
- Shenzhen Mindray Bio-Medical Electronics Co., Ltd.
- Smith’s Medical,Inc.
- Midmark Corporation
- Jorgensen Labs.
- Nonin Medical, Inc.
- Digicare Biomedical
Competitive Analysis:
The Veterinary Equipment and Supplies Market is highly competitive, with key players focusing on technological innovation and expanding their product portfolios to meet growing demand. Leading companies such as Philips Healthcare, IDEXX Laboratories, and Thermo Fisher Scientific dominate the market with their advanced diagnostic equipment, surgical instruments, and monitoring systems. These companies invest heavily in research and development to introduce new technologies that improve diagnostic accuracy and treatment efficiency. Regional players, particularly in North America and Europe, are gaining market share by offering high-quality products and robust customer service. The market is also seeing increased collaboration between veterinary clinics and equipment suppliers, driving the adoption of advanced technologies. While large players maintain a stronghold, emerging companies in Asia-Pacific are contributing to market growth by offering cost-effective solutions, expanding their footprint in developing regions where veterinary services are rapidly increasing.
Recent Developments:
- In April 2025, B. Braun Medical Inc. announced the U.S. FDA approval of Piperacillin and Tazobactam for Injection and Sodium Chloride Injection in the DUPLEX Drug Delivery System, a ready-to-activate two-compartment container system to improve efficiency and safety in antibiotic administration.
- In April 2025, B. Braun launched the EZCOVER® Probe Cover Set in the U.S., designed to enhance safety and efficiency in ultrasound-guided peripheral nerve block procedures by reducing infection transmission risks.
Market Concentration & Characteristics:
The Veterinary Equipment and Supplies Market is moderately concentrated, with several large players dominating the market. Key companies, such as Philips Healthcare, IDEXX Laboratories, and Thermo Fisher Scientific, hold significant market shares through their extensive product offerings and strong global presence. These players focus on technological innovation and high-quality solutions to maintain competitive advantage. However, the market also features a growing number of regional and smaller players that cater to emerging markets with cost-effective products. This mix of established companies and newer entrants creates a competitive landscape where product differentiation, quality, and customer service are crucial for success. The market is characterized by rapid technological advancements, an increasing emphasis on animal welfare, and expanding veterinary services globally, which continuously shape the strategies of key players in the industry.
Report Coverage:
The research report offers an in-depth analysis based on Product, Application, End-User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Veterinary Equipment and Supplies Market will continue to grow due to rising pet ownership globally and increasing demand for advanced veterinary care.
- Technological advancements in diagnostic tools, surgical instruments, and patient monitoring devices will play a pivotal role in market expansion.
- Rising awareness about animal health and wellness will drive the adoption of more sophisticated veterinary equipment.
- The growing trend of preventive healthcare in pets will result in higher demand for routine diagnostics and check-ups.
- Emerging markets in Asia-Pacific, particularly China and India, will experience the highest growth as disposable income and pet adoption rates rise.
- Government initiatives and regulatory support will further improve veterinary care standards, accelerating market growth.
- The increasing focus on animal welfare will drive investments in high-quality veterinary equipment and supplies.
- More veterinary clinics and hospitals will adopt advanced technologies, increasing demand for specialized equipment.
- Integration of artificial intelligence (AI) and telemedicine in veterinary care will create new opportunities for the market.
- The rise of veterinary e-commerce platforms will offer more accessible purchasing options for veterinary supplies, expanding the customer bases.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Veterinary Equipment and Supplies, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Veterinary Equipment and Supplies market projected to grow between 2024 and 2032?
Which Veterinary Equipment and Supplies market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Veterinary Equipment and Supplies market?
Who are the leading companies in the Veterinary Equipment and Supplies market?
Which region commanded the largest share of the Veterinary Equipment and Supplies market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Veterinary Equipment and Supplies Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Veterinary Equipment and Supplies Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2425 million → 2032: USD 4135.55 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Veterinary Equipment and Supplies Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Veterinary Equipment and Supplies Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Veterinary Equipment and Supplies Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Veterinary Equipment and Supplies Market Drivers
- 3.3 Veterinary Equipment and Supplies Market Restraints & Challenges
- 3.4 Veterinary Equipment and Supplies Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Veterinary Equipment and Supplies Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Veterinary Equipment and Supplies Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Veterinary Equipment and Supplies category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Veterinary Equipment and Supplies Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Veterinary Equipment and Supplies Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Veterinary Equipment and Supplies market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Veterinary Equipment and Supplies Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Veterinary Equipment and Supplies Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Veterinary Equipment and Supplies Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Veterinary Equipment and Supplies (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Veterinary Equipment and Supplies Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Veterinary Equipment and Supplies Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Veterinary Equipment and Supplies Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Veterinary Equipment and Supplies Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Veterinary Equipment and Supplies Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Veterinary Equipment and Supplies Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Veterinary Equipment and Supplies Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Veterinary Equipment and Supplies Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Veterinary Equipment and Supplies Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
