
Aging populations and biosimilars reshape bone care
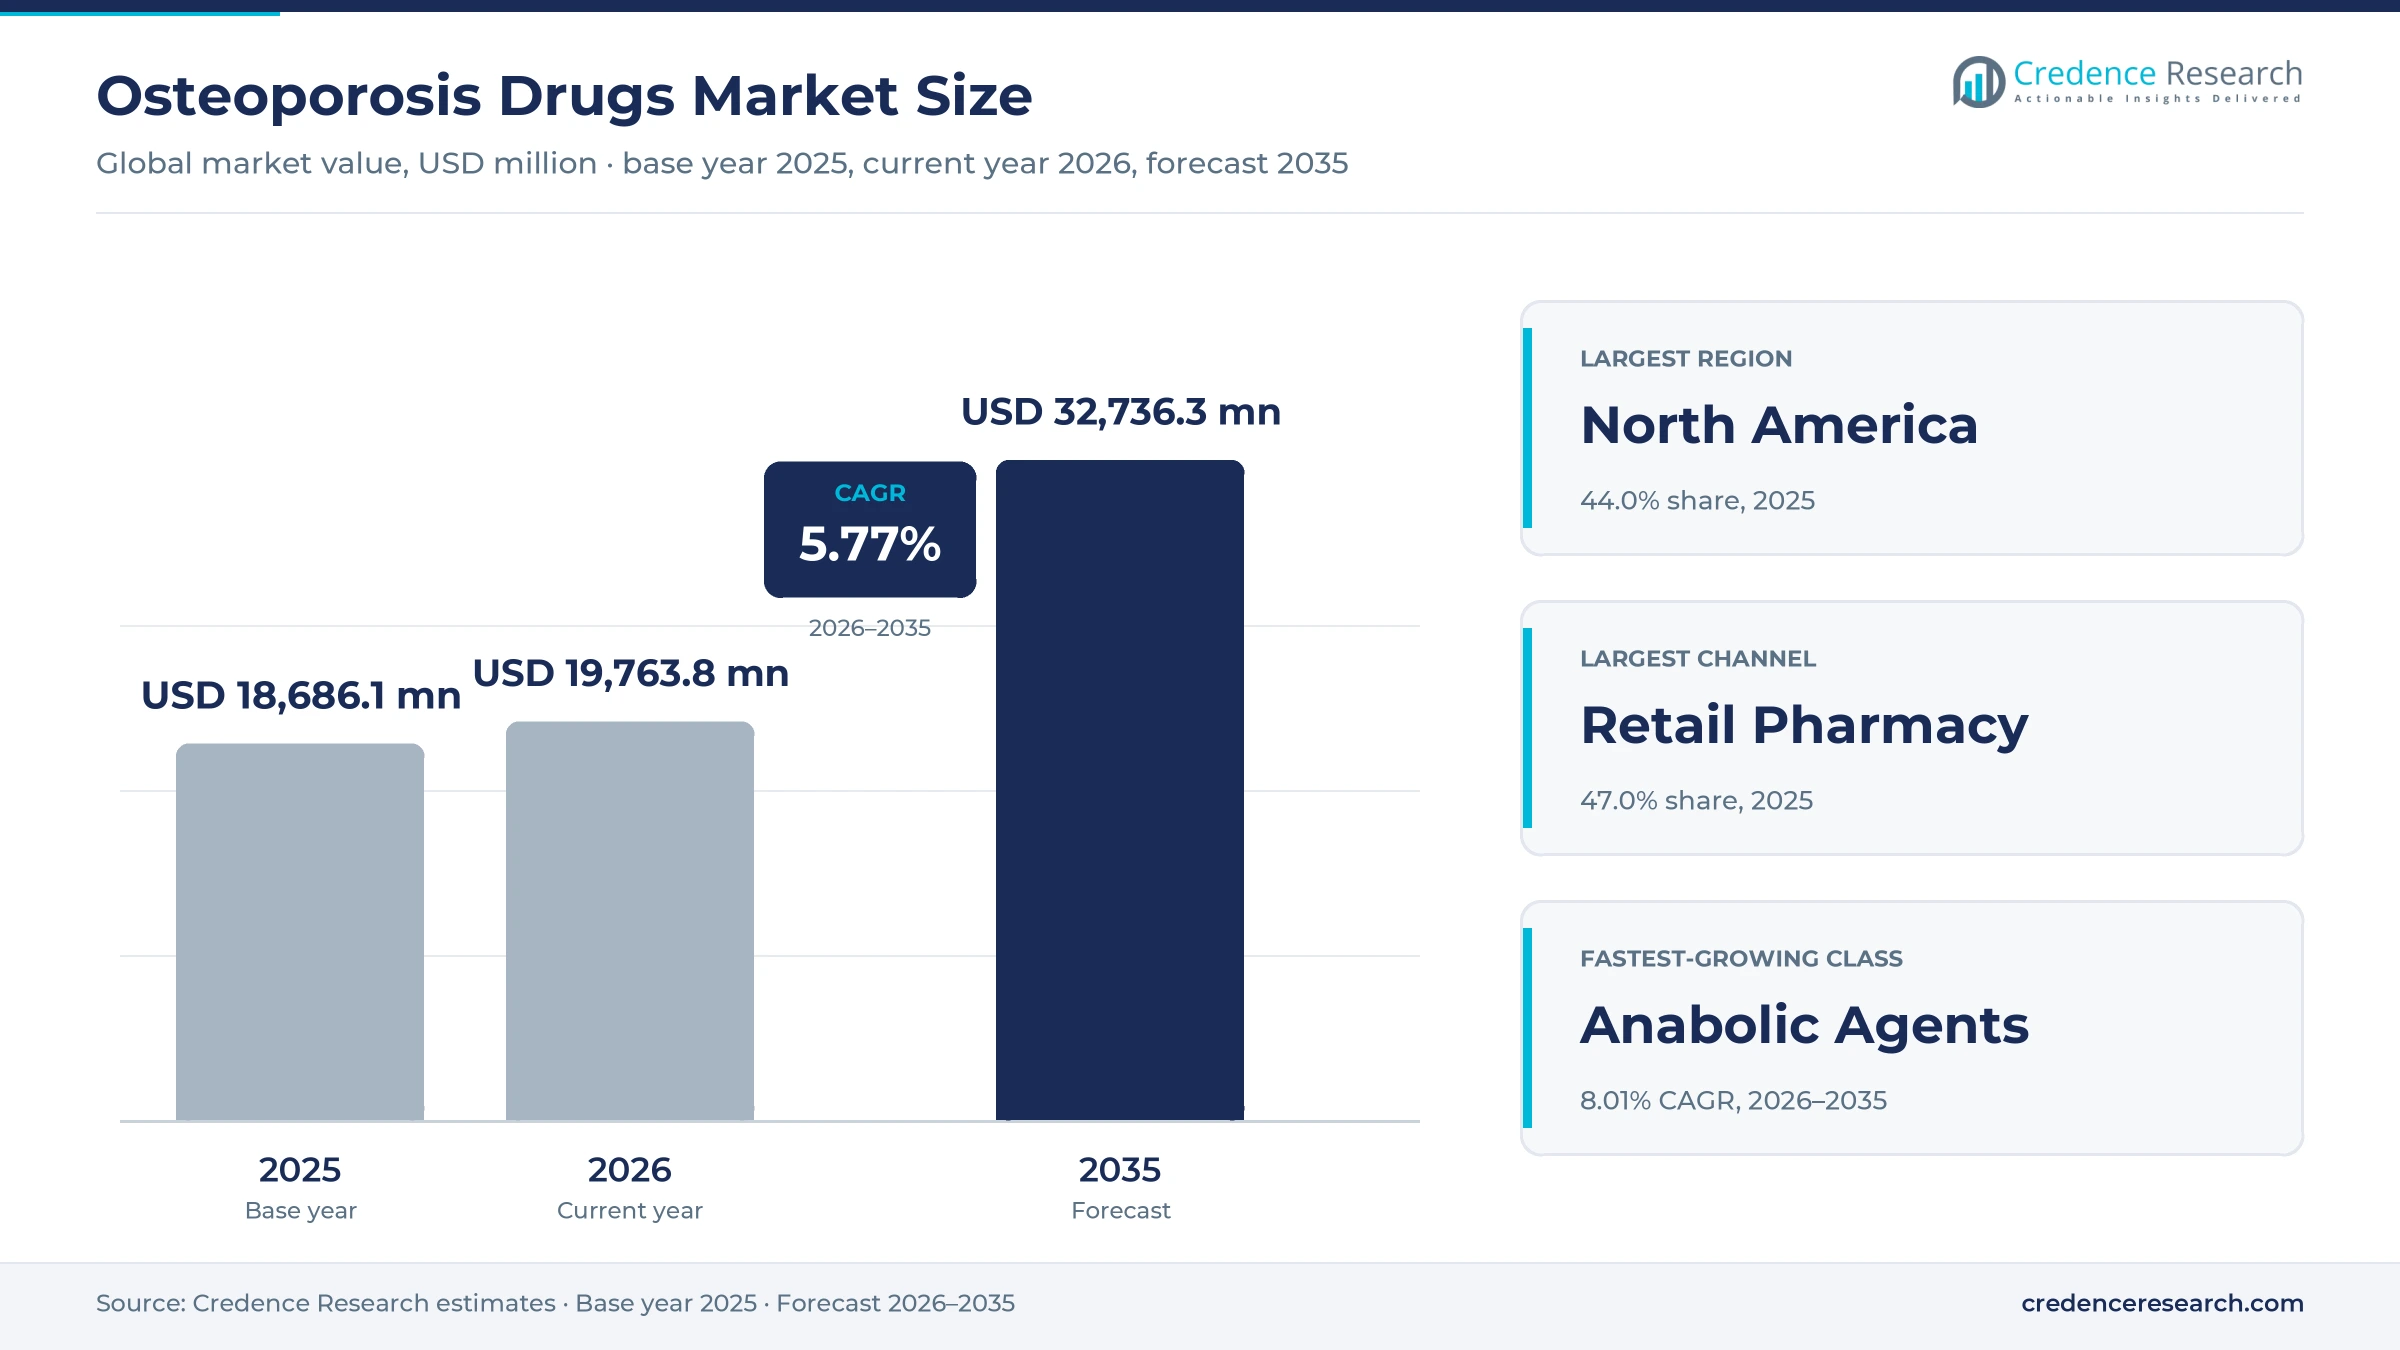
The global osteoporosis drugs market was valued at USD 18.69 billion in 2025 and is projected to increase from USD 19.76 billion in 2026 to USD 32.74 billion by 2035, registering a CAGR of 5.77% during 2026–2035. Demand comes from aging populations, a large pool of untreated postmenopausal women and wider use of bone-building medicines after a first fracture. North America held the largest regional share, 44.0% in 2025, because U.S. insurers cover injectable antibodies and anabolic agents for many older adults. Asia Pacific is the fastest-growing region at 7.17% a year, as Japan, China and South Korea manage some of the fastest-aging populations in the world. The commercial picture changed in March 2024, when the FDA approved the first interchangeable denosumab biosimilars. As a result, lower-priced versions of the leading injectable now compete for patients in the United States and Europe.
Which bone loss medicines and settings does this analysis cover?
The analysis counts prescription medicines used to prevent and treat primary and secondary bone loss, including bisphosphonates, denosumab, selective estrogen receptor modulators, teriparatide, abaloparatide, romosozumab, hormonal therapy and prescribed calcium and vitamin D. Values reflect manufacturer selling prices after typical discounts, and patients obtain most products through retail and hospital pharmacies.
Bone density scanners, fracture surgery implants and dietary supplements bought without a prescription sit outside this scope. The value chain runs from originator, generic and biosimilar manufacturers through wholesalers and pharmacy benefit managers to hospital, retail and online pharmacies, which dispense medicines prescribed by endocrinologists, rheumatologists, gynecologists and primary care doctors.
Osteoporosis Drugs Market Insights
- The osteoporosis drugs market grows from USD 18.69 billion in 2025 to USD 32.74 billion by 2035, a 5.77% CAGR as aging populations and anabolic therapy uptake lift spending.
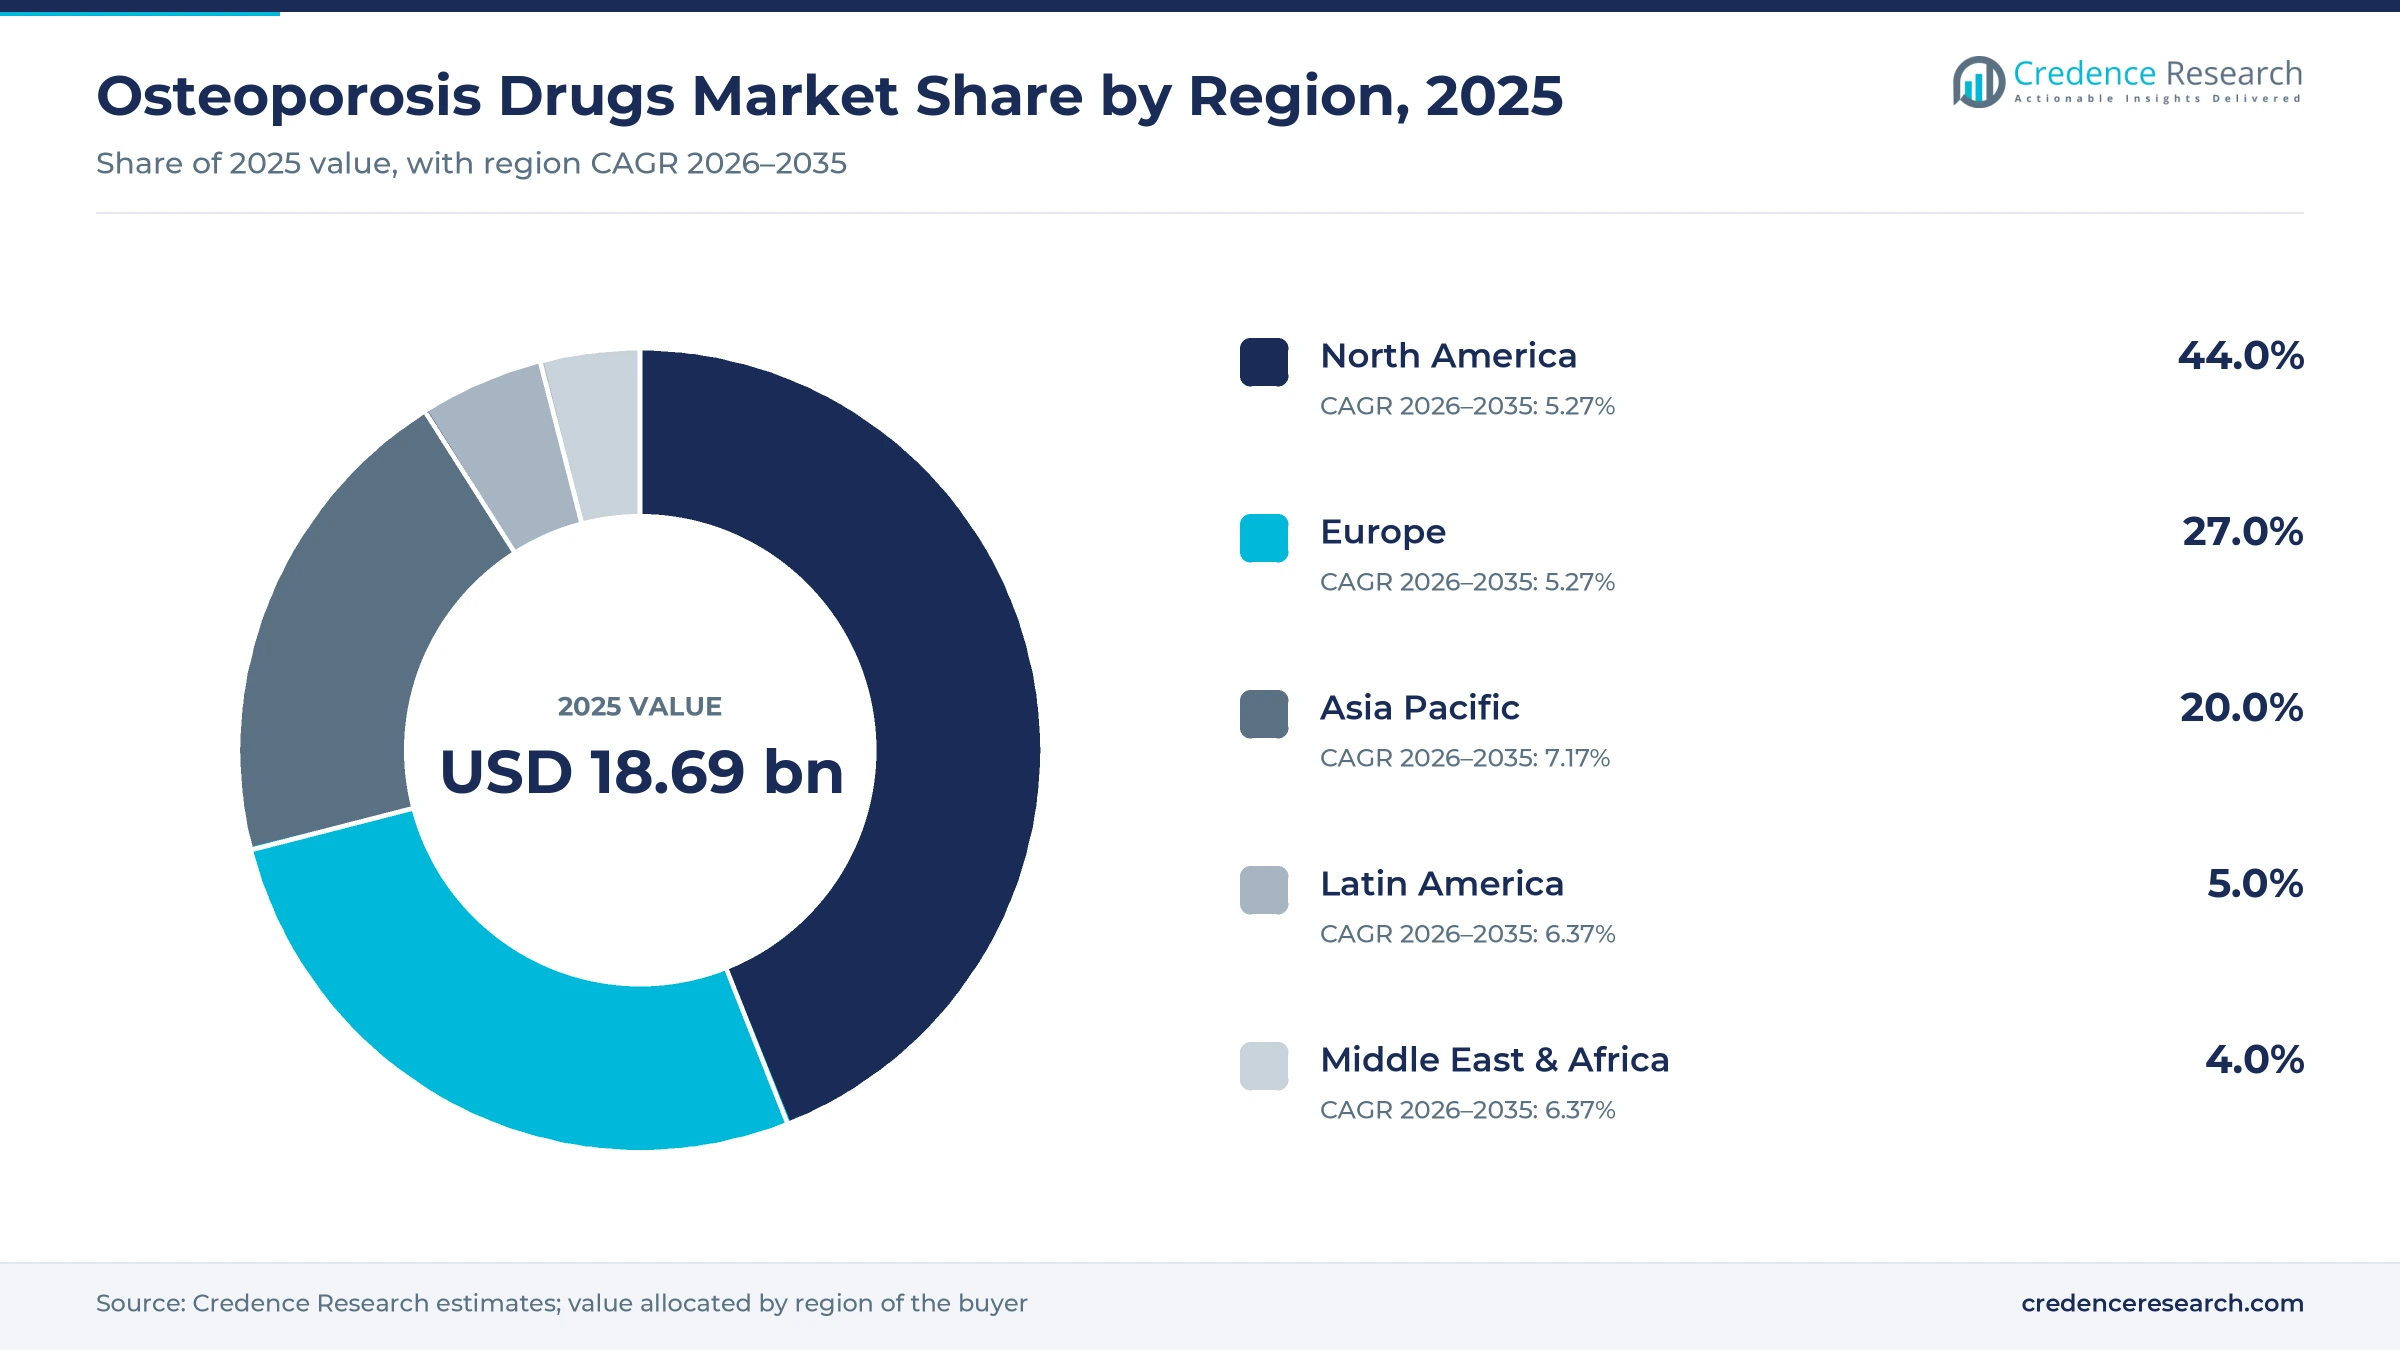
- North America held 44.0% of global bone loss therapy value in 2025, supported by broad insurance coverage for injectable medicines.
- Other drug classes, led by denosumab, held 34.0% of 2025 value, while anabolic agents grow fastest at 8.01% a year.
- In March 2024, the FDA approved Jubbonti and Wyost from Sandoz as the first interchangeable denosumab biosimilars covering all reference indications.
- In September 2025, the FDA approved Biocon Biologics denosumab biosimilars, described as the sixth set of such products cleared in the United States.
Denosumab-led classes lead as anabolic agents gain
Why does primary bone loss hold most of the value?
Based on type, the market is categorized into primary osteoporosis and secondary osteoporosis. Primary Osteoporosis led with a 78.0% share of 2025 value, because postmenopausal and age-related bone loss account for most diagnosed patients. Secondary Osteoporosis grows fastest at 6.47% a year, as doctors treat more bone loss linked to long-term steroid use, cancer hormone therapy and chronic kidney or inflammatory disease.
Which medicine classes capture most of the value?
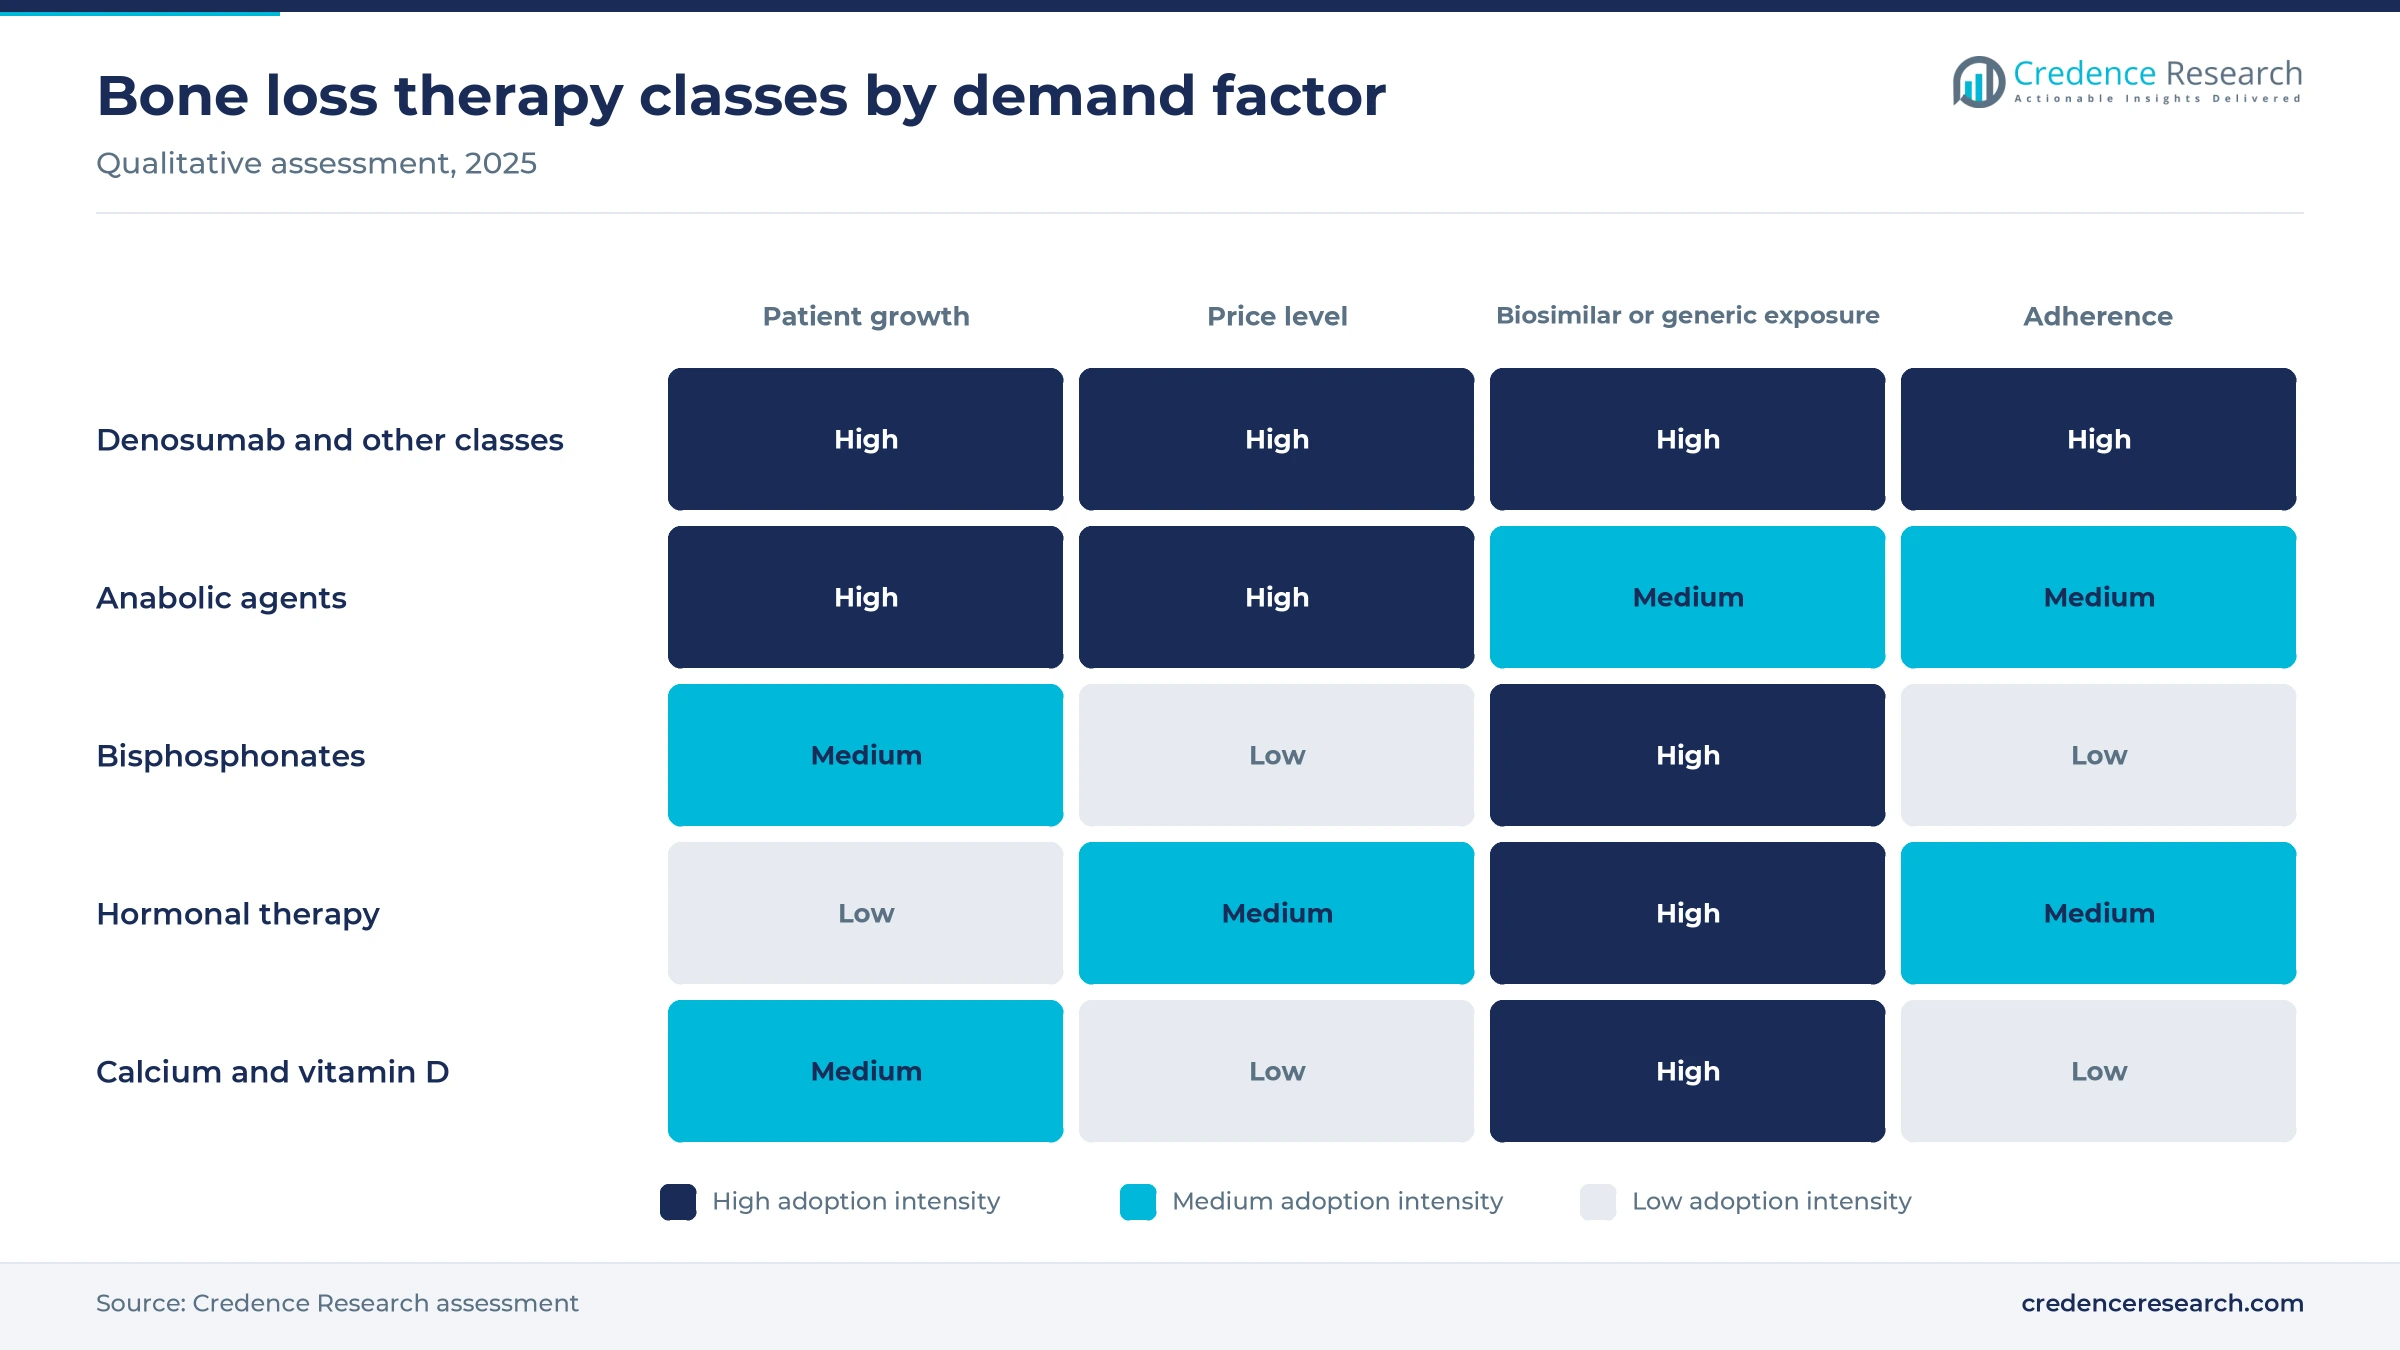
Based on drug class, the market is categorized into bisphosphonates, anabolic agents, calcium and vitamin D supplements, hormonal therapy and other drug classes. Other Drug Classes led with a 34.0% share of 2025 value, because denosumab injections every six months carry high prices. Anabolic Agents grow fastest at 8.01% a year, as doctors use bone-building medicines first for very high-risk patients. Generic bisphosphonates keep large prescription volumes at relatively low prices.
Why are online pharmacies gaining share?
Based on distribution channel, the market is categorized into hospital pharmacy, retail pharmacy, online pharmacy and others. Retail Pharmacy led with a 47.0% share of 2025 value, because most patients refill oral tablets and supplements close to home. Online Pharmacy grows fastest at 7.99% a year, as online pharmacies make monthly refills easier for older adults with limited mobility.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Type | Primary Osteoporosis | 78.0% | Secondary Osteoporosis | 6.47% |
| By Drug Class | Other Drug Classes | 34.0% | Anabolic Agents | 8.01% |
| By Distribution Channel | Retail Pharmacy | 47.0% | Online Pharmacy | 7.99% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Fracture burden and aging lift treatment demand
How does population aging sustain demand for bone therapy?
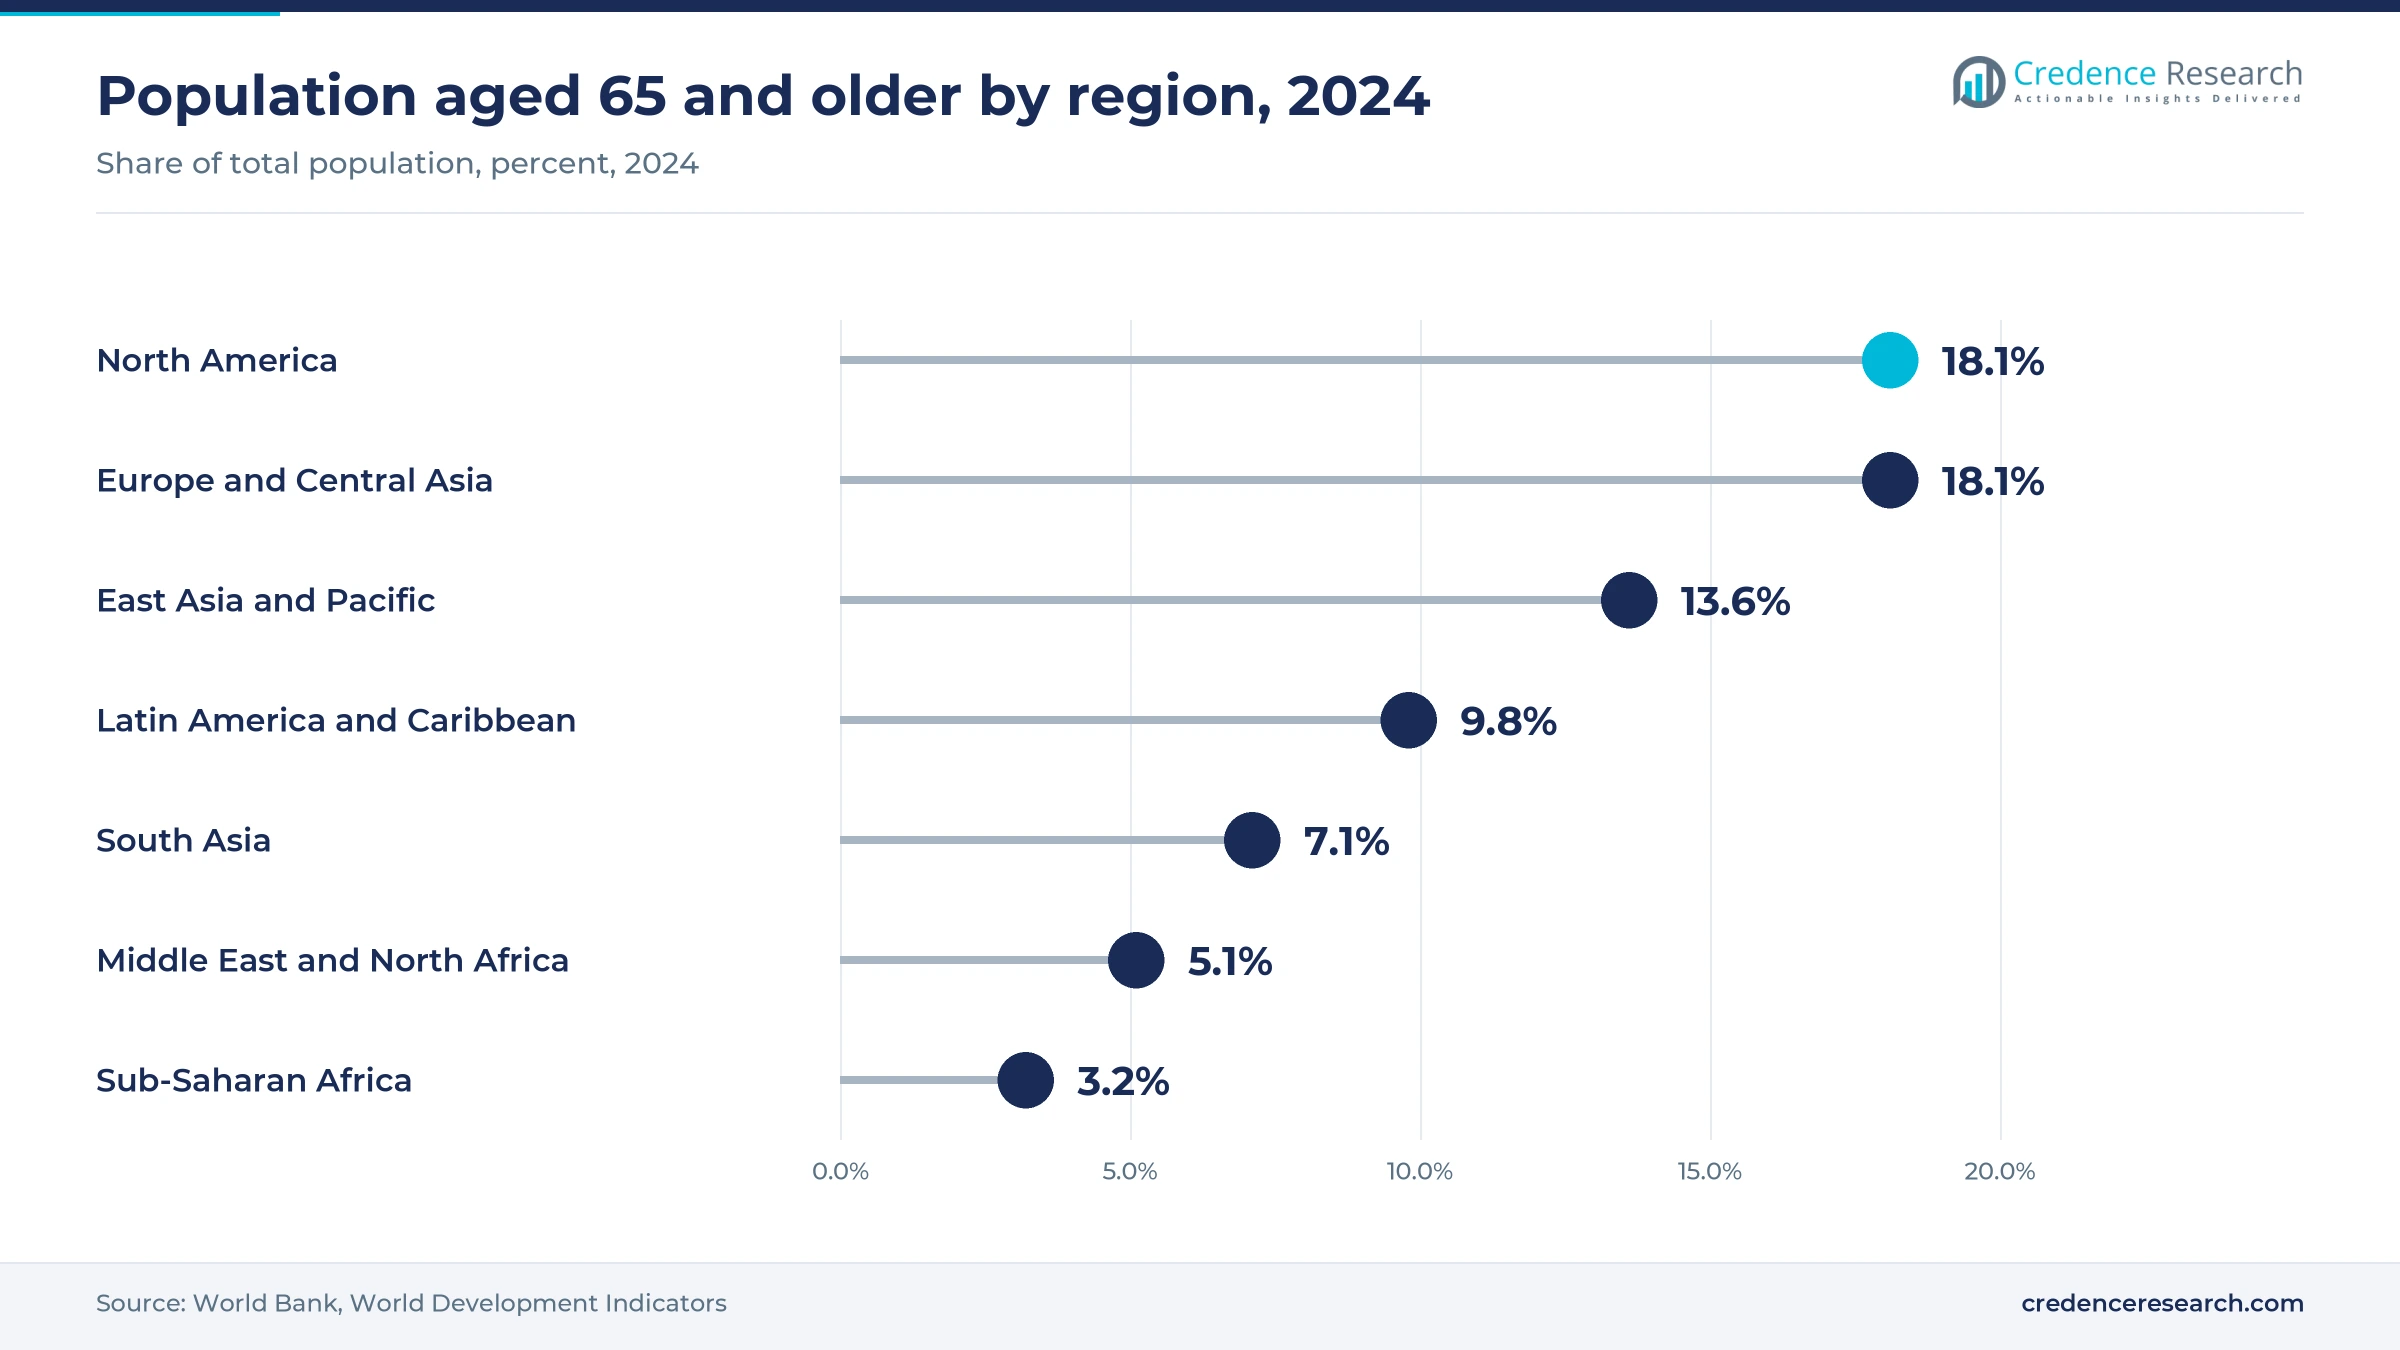
Population aging sustains demand, because bone density falls with age and fracture risk rises sharply after 60. The World Health Organization projects that 1 in 6 people worldwide will be aged 60 years or over by 2030. The agency also expects the number of people aged 60 and older to reach 2.1 billion by 2050. In addition, the number of people aged 80 or older is expected to triple between 2020 and 2050 to 426 million. World Bank data show that people aged 65 and older made up about 18.1% of the North American population in 2024. As a result, the pool of patients who need long-term bone therapy keeps growing in every region through 2035.
Why does the rising fracture burden push treatment demand?
The rising fracture burden pushes treatment demand, because each fragility fracture signals a need for medicine to prevent the next one. The International Osteoporosis Foundation reports that 1 in 3 women and 1 in 5 men over 50 will experience an osteoporotic fracture in their lifetime. The foundation estimates that up to 37 million fragility fractures occur each year in people over 55, about 70 every minute. It also projects that hip fracture numbers will nearly double between 2018 and 2050. In turn, health systems face strong pressure to treat patients after a first fracture rather than wait for repeat events that cost far more to manage.
How do high repeat fracture rates favor bone-building agents?
High repeat fracture rates favor bone-building agents, because patients who have already broken a bone face the highest near-term risk. The International Osteoporosis Foundation notes that a prior fracture raises the risk of another fracture by 86%. After a hip fracture, about 1 in three patients has a second hip fracture, on average within about 1.5 years. These patients often need faster gains in bone density than weekly or monthly oral tablets can deliver. As a result, anabolic agents grow at 8.01% a year, the fastest pace among drug classes, as specialists use teriparatide, abaloparatide and romosozumab for very high-risk patients.
Why do denosumab biosimilars widen access to injectable therapy?
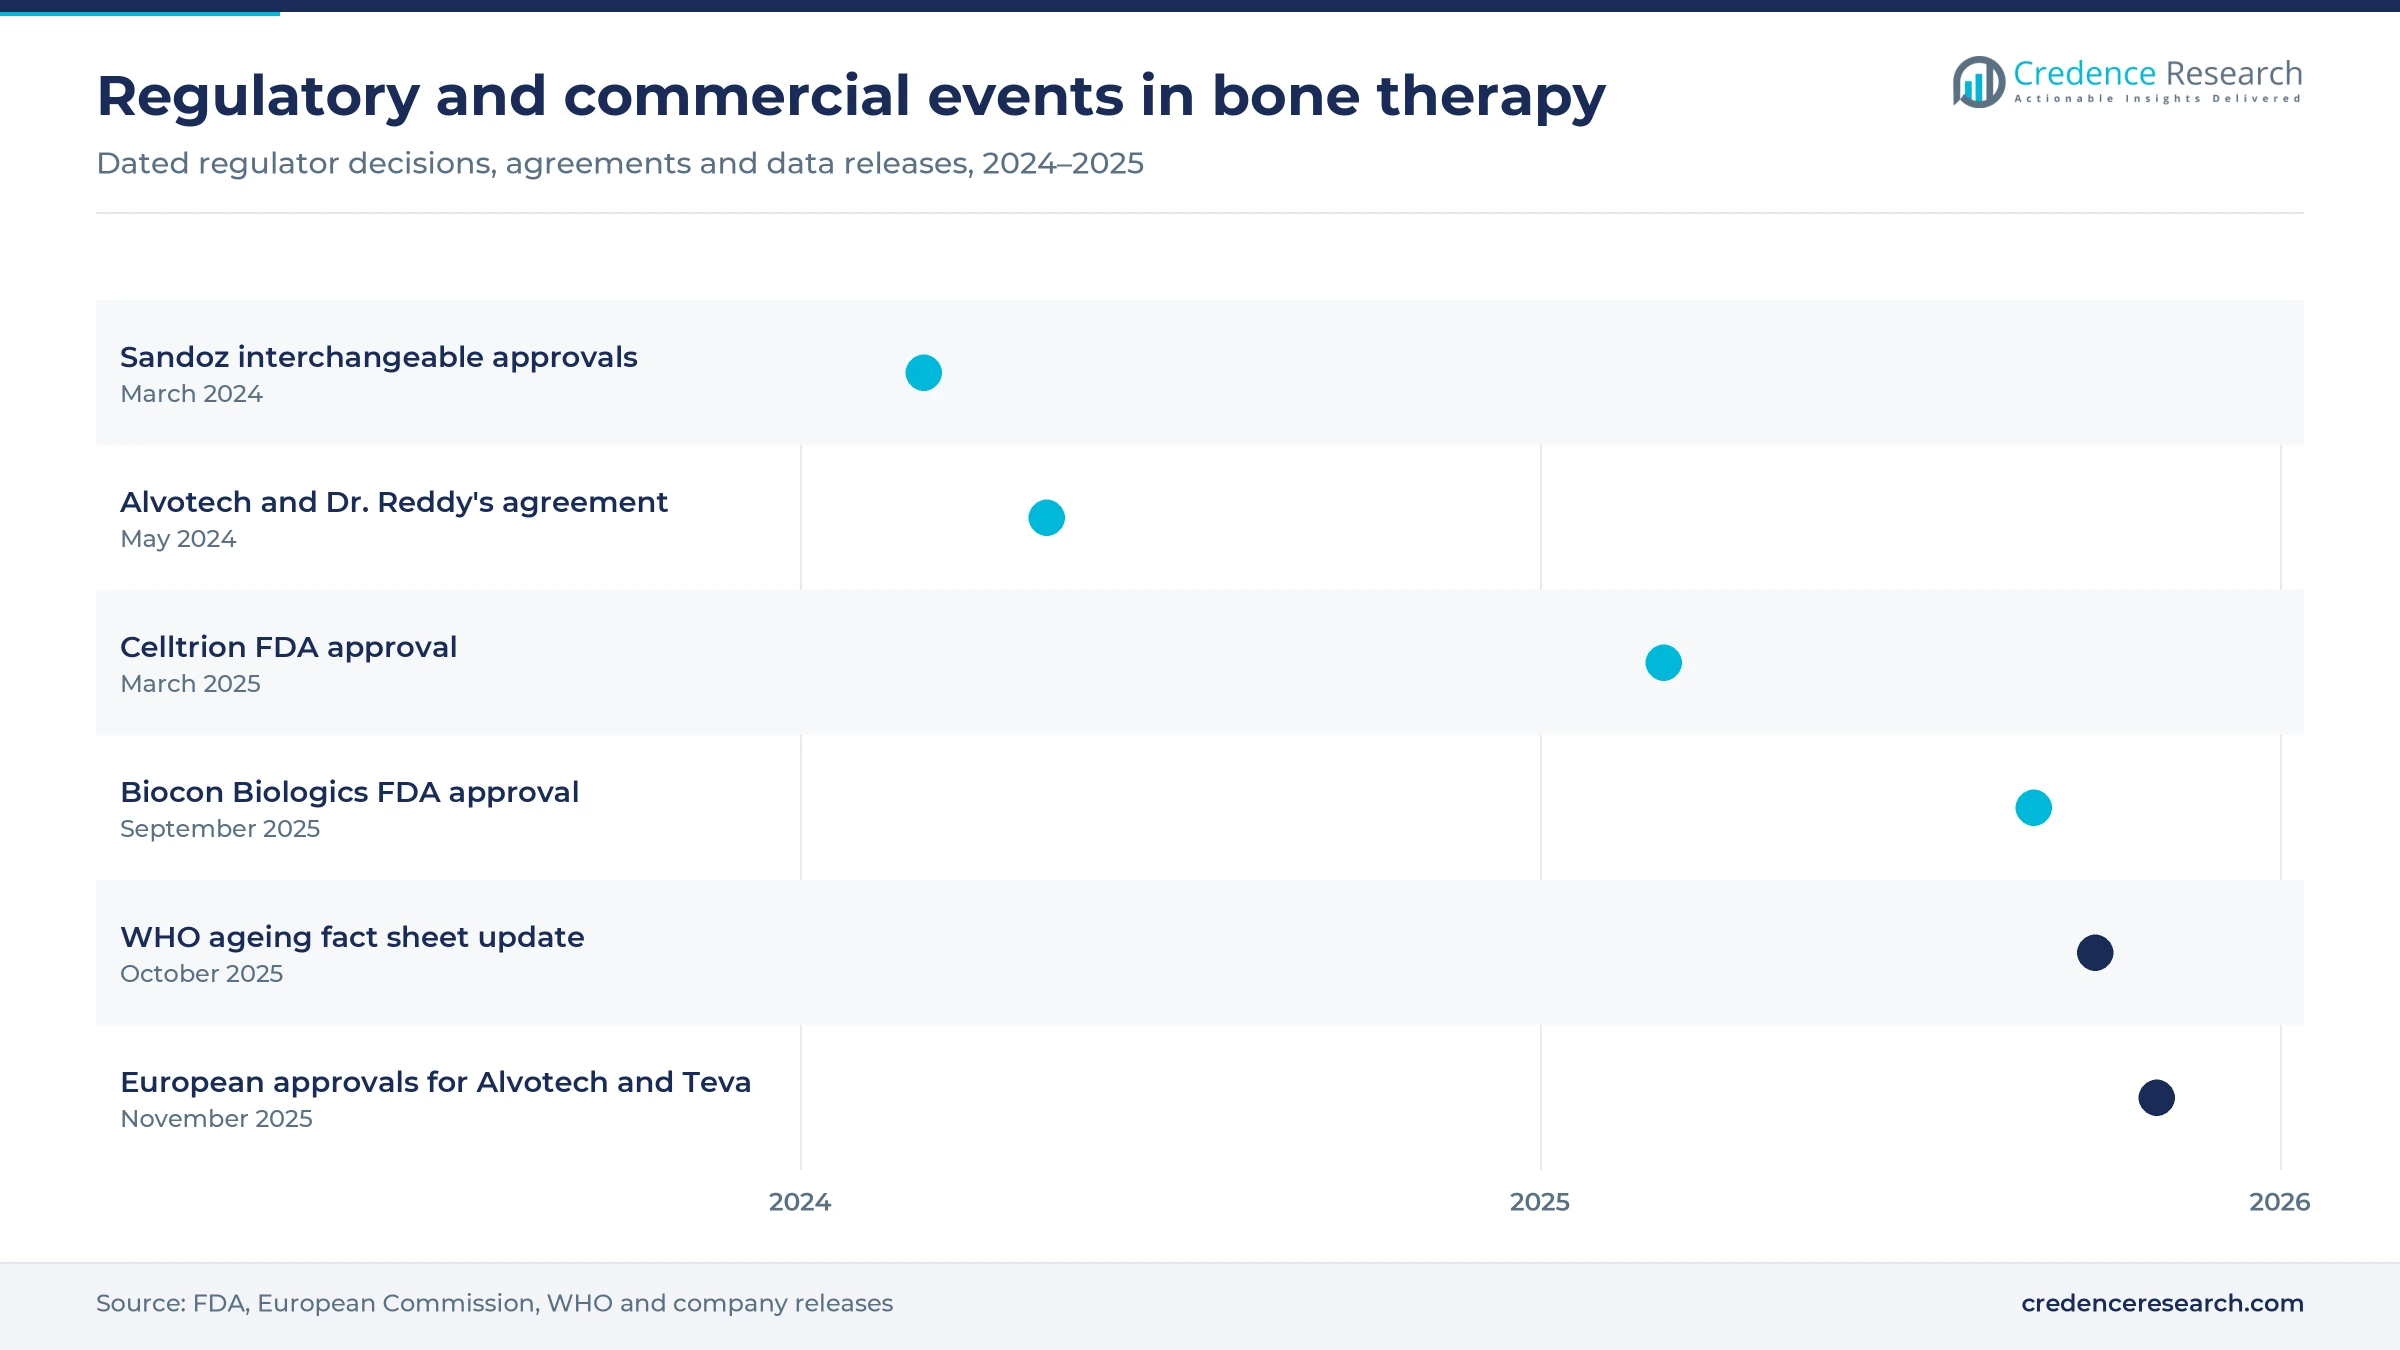
Denosumab biosimilars widen access to injectable therapy, because lower prices let payers cover more patients who cannot take bisphosphonates. In March 2024, the FDA approved Jubbonti and Wyost from Sandoz as the first interchangeable denosumab biosimilars covering all reference indications. In March 2025, the FDA approved Stoboclo and Osenvelt from Celltrion, which planned a U.S. launch in June under a settlement with Amgen. In September 2025, the FDA approved Biocon Biologics products, described as the sixth set of denosumab biosimilars cleared in the country. In turn, more patients can start and stay on twice-yearly injections at a lower cost per dose.
Biosimilar entry and bone-building therapy shift care
How is biosimilar competition shifting the injectable segment?
Biosimilar competition is shifting the injectable segment, because several manufacturers now sell versions of the leading antibody across major markets, and biosimilars now shape payer contracts. In May 2024, Alvotech and Dr. Reddy's agreed to commercialize AVT03, a denosumab biosimilar candidate, with Dr. Reddy's holding exclusive U.S. rights. In November 2025, the European Commission approved AVT03 from Alvotech and the Ponlimsi and Degevma biosimilars from Teva. These approvals followed the first interchangeable U.S. approvals for Sandoz in March 2024. As a result, the other drug classes segment, which held 34.0% of 2025 value, faces price erosion even as volumes grow. Companies with low-cost production can gain share in national tenders and payer contracts.
Why is bone-building therapy rising in high-risk care?
Bone-building therapy is rising in high-risk care, because specialists increasingly start these patients on anabolic agents before moving to antiresorptive medicines. Teriparatide and abaloparatide stimulate new bone formation through daily injections, while romosozumab is given monthly for one year. The International Osteoporosis Foundation reports that a prior fracture raises the risk of another by 86%, which supports faster-acting therapy after a break. After a hip fracture, about 1 in three patients has another hip fracture, often within about 1.5 years. Up to 37 million fragility fractures occur each year in people over 55. In turn, fracture liaison services and specialist clinics are becoming more important prescribers, because they identify the patients who qualify for these medicines.
Can closing the treatment gap open new demand in Europe?
Closing the treatment gap gives manufacturers a clear opening in Europe, because many eligible women still receive no medicine. The International Osteoporosis Foundation estimates that the average treatment gap across EU27 countries, Switzerland and the United Kingdom reached 71% in 2019. The same data put the number of untreated eligible women at about 15 million. The foundation also counts about 32 million people aged 50 or older with the disease in that group of countries. Europe already held 27.0% of 2025 value, so even modest gains in diagnosis add large volumes. As a result, companies that support screening and fracture liaison programs can win new long-term patients.
Where can fast-aging Asian markets add value?
Fast-aging Asian markets give manufacturers room to add value, because older populations in the region are growing quickly from a lower treatment base. World Bank data show that people aged 65 and older made up about 13.6% of the East Asia and Pacific population in 2024. The World Health Organization expects the number of people aged 80 or older worldwide to triple between 2020 and 2050, reaching 426 million. Asia Pacific is the fastest-growing region in this report as a result. In turn, local generic producers and biosimilar makers have room to supply lower-priced bisphosphonates and antibodies across China, India and Southeast Asia, where many patients pay out of pocket.
Low treatment rates and price erosion limit value
How does underdiagnosis keep many patients untreated?
Underdiagnosis keeps many patients untreated, because bone loss causes no symptoms until a fracture occurs. Many older adults never receive a bone density scan, especially in rural areas and low-income countries. Men are screened far less often than women, even though they account for about a quarter of hip fractures over 50. As a result, a large share of potential demand remains outside the prescription market, and screening programs remain the main lever for change.
Why does poor adherence limit the value of oral tablets?
Poor adherence limits the value of oral tablets, because weekly or monthly bisphosphonates require strict fasting and upright posture after each dose. Many patients stop treatment within the first year because of stomach side effects or worry about rare jaw and thigh bone problems. Doctors must then restart therapy or switch patients to injections. In turn, pharmacist follow-up and longer-acting injectable options are becoming important tools for keeping patients on therapy.
How does biosimilar entry erode prices for originators?
Biosimilar entry erodes prices for originators, because payers can now choose among several interchangeable versions of denosumab. Biocon Biologics received the sixth set of U.S. denosumab biosimilar approvals in September 2025, and more approvals followed in Europe. Originators therefore face falling net prices on their largest injectable brands. As a result, value growth in the other drug classes segment trails volume growth, even as more patients start treatment.
Why do safety concerns slow uptake of some therapies?
Safety concerns slow uptake of some therapies, because several medicines carry warnings that limit their use. Romosozumab carries a boxed warning on heart attack, stroke and cardiovascular death risk, which excludes some older patients with cardiovascular disease. Its label also limits treatment to 12 monthly doses, after which patients need a follow-on antiresorptive medicine. In turn, doctors must plan long treatment sequences carefully, which adds visits and slows decisions for many patients.
North America leads as Asia Pacific gains pace
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 8.22 | 44.0% | 5.27% |
| Europe | 5.05 | 27.0% | 5.27% |
| Asia Pacific | 3.74 | 20.0% | 7.17% |
| Latin America | 0.93 | 5.0% | 6.37% |
| Middle East & Africa | 0.75 | 4.0% | 6.37% |
Why does North America hold the largest regional share?
North America held a 44.0% share of 2025 value and grows at 5.27% a year through 2035. The United States drives this position, because Medicare and commercial insurers cover injectable antibodies and anabolic agents. People aged 65 and older made up about 18.1% of the regional population in 2024, according to World Bank data. Denosumab biosimilar launches since 2025 lower costs per patient and widen access.
What shapes demand across Europe?
Europe held a 27.0% share of 2025 value and grows at 5.27% a year through 2035. Germany, France, the United Kingdom, Italy and Spain account for most spending, because national health systems reimburse bone therapy under defined criteria. The 71% treatment gap reported for 2019 leaves room for growth. However, early biosimilar adoption and tender pricing keep value growth below the global average.
How fast is Asia Pacific adding patients?
Asia Pacific held a 20.0% share of 2025 value and is the fastest-growing region at 7.17% a year. Japan has one of the oldest populations in the world and broad use of anabolic agents. China and South Korea are expanding bone density screening for older women. In turn, generic producers in India supply low-cost bisphosphonates and supplements across the region.
Where is Latin America adding demand?
Latin America held a 5.0% share of 2025 value and grows at 6.37% a year through 2035. Brazil and Mexico lead regional spending, because private insurers and specialist clinics adopt injectable therapy in major cities. Public systems still depend mainly on generic bisphosphonates and prescribed vitamin D therapy with calcium.
What limits growth in the Middle East and Africa?
The Middle East and Africa held a 4.0% share of 2025 value and grows at 6.37% a year through 2035. Gulf states fund branded specialist care, while much of Africa relies on low-cost oral tablets. Younger populations and limited screening keep treatment rates low outside major cities and private hospitals.
Denosumab biosimilar approvals since 2024
| Development | Status and market relevance |
|---|---|
| In March 2024, the FDA approved Jubbonti and Wyost from Sandoz as the first interchangeable denosumab biosimilars. | Approved; covers all indications of the reference products |
| In May 2024, Alvotech and Dr. Reddy's Laboratories Ltd. agreed to commercialize the AVT03 denosumab biosimilar candidate. | Agreement; Dr. Reddy's holds exclusive U.S. rights and shared rights in Europe and the U.K. |
| In March 2025, the FDA approved Stoboclo and Osenvelt from Celltrion as denosumab biosimilars. | Approved; U.S. launch planned under a settlement with Amgen |
| In September 2025, the FDA approved Bosaya and Aukelso from Biocon Biologics as denosumab biosimilars. | Approved; described as the sixth set of U.S. denosumab biosimilars |
| In November 2025, the European Commission approved denosumab biosimilars from Alvotech and Teva Pharmaceutical Industries Ltd. | Approved; adds lower-priced injectable options across Europe |
Antibodies and bone-building agents lead innovation
- RANKL monoclonal antibodies block bone breakdown for six months after one injection, which suits patients who cannot take oral tablets.
- Parathyroid hormone analogs stimulate new bone formation through daily injections, which rebuilds density faster after a fracture.
- Sclerostin inhibitors both build bone and slow its breakdown with monthly dosing over one year, which supports very high-risk patients.
- Intravenous bisphosphonates deliver a full year of protection in one infusion, which removes the strict fasting rules of oral tablets.
- Prefilled pens and syringes let patients inject at home, which cuts clinic visits and supports long treatment courses.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Originators and biosimilar makers compete on access
Competition is led by originators with injectable and anabolic portfolios, strong specialist sales teams and payer contracts. Amgen Inc. competes with denosumab and romosozumab, while Eli Lilly and Company remains associated with teriparatide and raloxifene. Novartis AG, Sanofi and Bristol-Myers Squibb Company hold positions in older bisphosphonates and supportive care, while Pfizer Inc. offers hormone replacement therapy for postmenopausal women. Teva Pharmaceutical Industries Ltd., Mylan, Dr. Reddy's Laboratories Ltd. and Cipla Limited compete through generic tablets, injectables and biosimilars, with Teva and Dr. Reddy's adding denosumab biosimilars. Horizon Therapeutics, acquired by Amgen in October 2023, brings rare inflammatory disease experience. As a result, competition centers on fracture reduction data, dosing convenience, biosimilar pricing and payer access rather than list price alone.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Amgen Inc. | Originator | Denosumab and romosozumab injectables |
| Eli Lilly and Company | Originator | Teriparatide and raloxifene |
| Novartis AG | Originator | Zoledronic acid infusion |
| Pfizer Inc. | Originator | Hormonal therapy for postmenopausal women |
| Sanofi | Originator | Established bone health brands |
| Bristol-Myers Squibb Company | Originator | Diversified specialty portfolio |
| Teva Pharmaceutical Industries Ltd. | Generics and biosimilars | Ponlimsi and Degevma denosumab biosimilars |
| Mylan | Generics | Generic bisphosphonates |
| Dr. Reddy's Laboratories Ltd. | Generics and biosimilars | U.S. rights to the AVT03 denosumab biosimilar |
| Cipla Limited | Generics | Low-cost tablets for emerging markets |
| Horizon Therapeutics | Specialty pharmaceutical | Rare disease portfolio within Amgen |
Anabolic uptake and biosimilars set the pace
Credence Research's view is that anabolic uptake and biosimilar pricing will set the pace of growth through 2035. The overall market grows at 5.77% a year, supported by aging populations, high repeat fracture rates and a large untreated pool. Anabolic agents grow faster than any other class as specialists treat very high-risk patients first. Biosimilars lower denosumab prices, but they also widen access for many insured patients. Companies that combine strong fracture data, convenient dosing and broad payer access will capture the most new patients.
How Credence Research sized bone therapy spending
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. Market values come from the Credence Research model, which builds spending by type, drug class, distribution channel and region. Regional and segment splits are Credence Research estimates informed by World Health Organization and World Bank data, International Osteoporosis Foundation statistics, regulator decisions and company press releases. No primary interviews or surveys were used in preparing this edition of the report.
Bone loss therapy spending outlook to 2035
By 2035, the osteoporosis drugs market is projected to reach USD 32.74 billion, with growth led by anabolic agents, denosumab biosimilars and wider treatment after first fractures. Primary bone loss remains the largest type, while secondary bone loss gains ground as more cancer and steroid patients receive protection. North America keeps the highest spending per patient, while Asia Pacific adds the most new patients. Online pharmacies take a larger share of refills for older adults at home. As a result, advantage will depend on fracture data, dosing convenience and payer access.
Frequently Asked Questions
How big is the global osteoporosis drugs market?
Which drug class leads bone loss therapy spending?
Which region leads osteoporosis drug demand?
Why is secondary bone loss treatment growing faster?
How do online pharmacies affect bone therapy sales?
What recent approvals affect osteoporosis drugs?
Who are the leading osteoporosis drug companies?
What restrains growth in osteoporosis drugs?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Primary Osteoporosis
- 1.2.2 Secondary Osteoporosis
- 1.3 By Drug Class
- 1.3.1 Bisphosphonates
- 1.3.2 Anabolic Agents
- 1.3.3 Calcium and Vitamin D Supplements
- 1.3.4 Hormonal Therapy
- 1.3.5 Other Drug Classes
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 18.69 billion → 2035: USD 32.74 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Osteoporosis Drugs Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Osteoporosis Drugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Osteoporosis Drugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Osteoporosis Drugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Osteoporosis Drugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Osteoporosis Drugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Osteoporosis Drugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Osteoporosis Drugs Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 18.69 billion → 2035: USD 32.74 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Osteoporosis Drugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Primary Osteoporosis
- 12.3.7.2 Secondary Osteoporosis
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Drug Class - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Bisphosphonates
- 12.4.7.2 Anabolic Agents
- 12.4.7.3 Calcium and Vitamin D Supplements
- 12.4.7.4 Hormonal Therapy
- 12.4.7.5 Other Drug Classes
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Osteoporosis Drugs Geographic Market Outlook, 2025-2035
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2035
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Osteoporosis Drugs Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Osteoporosis Drugs Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Amgen Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Bristol-Myers Squibb Company
- 17.4 Eli Lilly and Company
- 17.5 Novartis AG
- 17.6 Pfizer Inc.
- 17.7 Sanofi
- 17.8 Teva Pharmaceutical Industries Ltd.
- 17.9 Horizon Therapeutics
- 17.10 Mylan
- 17.11 Dr. Reddy's Laboratories Ltd.
- 17.12 Cipla Limited
- 17.13 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

