EQT agrees €10.8 billion all-cash takeover of QIAGEN, plans NYSE and Frankfurt delisting
QIAGEN N.V. has agreed to be taken private by the EQT XI fund in an all-cash deal worth about 10.8 billion euros, the two sides said late Wednesday, Oct. 21, from Venlo, Netherlands, and Amsterdam. Crown NL Bidco B.V., the bidding vehicle, will offer 46.50 euros per share to every QIAGEN shareholder. Both QIAGEN boards approved the agreement unanimously, and the company expects to leave the New York and Frankfurt stock exchanges once the offer closes, which is targeted for mid-2027.
Key developments
- EQT Private Equity will launch a voluntary public tender offer at 46.50 euros per share in cash, valuing QIAGEN at about 10.8 billion euros (about $12.1 billion) in enterprise value, including about $1.1 billion of net debt.
- The price is a 40.3% premium to QIAGEN's XETRA close of 33.15 euros on July 8, 2026, the last trading day before reports of private equity interest, and 46.9% above the three-month volume-weighted average of 31.66 euros.
- Luxinva S.A., a unit of the Abu Dhabi Investment Authority, and CPP Investment Board Europe Inc., a unit of CPP Investments, will hold indirect stakes as co-investors.
- The offer needs at least 50% plus one share of QIAGEN's capital, shareholder approval of post-closing measures at an extraordinary general meeting, and merger control and foreign investment clearances. It carries no financing condition.
- QIAGEN suspended its full-year 2026 outlook while the deal is pending and reported preliminary third-quarter net sales of $548 million and adjusted diluted earnings of $0.65 per share.
Company background
QIAGEN is a Netherlands-based holding company whose products extract and analyze molecular information from biological samples. The company describes its portfolio as Sample to Insight solutions, a chain that runs from sample preparation kits and assays to bioinformatics software and laboratory automation. Its customers fall into two broad groups: Life Sciences, which covers academic labs, pharmaceutical research and industrial uses such as forensics, and Molecular Diagnostics, which serves clinical healthcare.
The company reports more than 500,000 customers and about 5,400 employees across more than 35 locations as of Sept. 30, 2026. Its shares trade on the New York Stock Exchange under QGEN and on the Frankfurt Prime Standard under QIA.
The agreement follows what QIAGEN called a comprehensive strategic review that included talks with both strategic and financial parties. The company set July 8 as the unaffected reference date because market reports about private equity takeover interest began circulating after that session.
Industry implications
The deal moves one of the best-known names in sample preparation and molecular testing out of public markets. Chief Executive Jonathan M. Pratt said private ownership would let the company move faster and with greater freedom to back its most attractive opportunities. That argument points to longer investment horizons for research and development, automation platforms and software, areas where quarterly reporting can weigh on spending decisions.
The announcement also lands during a busy stretch for health care dealmaking. Merck KGaA agreed this month to buy RNA drug developer Silence Therapeutics, Cencora agreed on Oct. 21 to acquire American Oncology Network, and Abbott said the same day that it plans to separate its nutrition business. Taken together, the moves show large owners reshaping portfolios around businesses they believe they can run better under a different structure.
For laboratories and hospitals that rely on QIAGEN consumables and instruments, little should change in the near term. QIAGEN said it will operate independently under current management until closing and will keep its name and brand afterward.
Competitive and supply chain implications
Under the business combination agreement, EQT committed to support QIAGEN's strategy, key brands, operational footprint, research and development, employee arrangements and culture, along with prudent financing. The release did not give specific pledges on headquarters location or job numbers, so customers and staff will watch the offer document for more detail.
The financing structure matters for suppliers and partners. EQT has committed equity and debt financing large enough to cover the full consideration and transaction costs, with Morgan Stanley, Jefferies, Deutsche Bank, SMBC, Credit Agricole and UniCredit acting as debt arrangers. A leveraged balance sheet typically sharpens focus on cash generation, procurement terms and the efficiency of manufacturing sites that produce kits and reagents for global distribution.
Rival life science tool and diagnostics makers will look for any change in QIAGEN's pricing, product priorities or partnership strategy once it no longer reports publicly each quarter. EQT's healthcare team says it has invested more than 30 billion euros across more than 210 healthcare companies, which gives it a broad base for potential add-on deals.
Regional implications
The transaction spans three regulatory systems. Germany's financial regulator BaFin must approve the offer document before the acceptance period begins, and the U.S. tender offer and Schedule TO filing with the Securities and Exchange Commission will start on the same day. Merger control and foreign investment reviews will add further jurisdictions.
In Europe, the deal removes a Frankfurt-listed life science company from the public market, and the dual listing in New York will end as well. Participation by sovereign and pension investors from Abu Dhabi and Canada reflects the role long-term capital pools now play in large European take-private deals, and foreign investment reviews will assess that ownership.
Credence Research analysis
The structure of this offer is as notable as the price. QIAGEN's boards will implement post-closing measures if at least 80% of votes cast at the extraordinary meeting support them, but may still proceed below that level if they judge it in the company's interest and shareholder support remains substantial. Shareholders who do not tender would receive a cash distribution equal to the offer price, less withholding taxes, which could leave them with less than tendering investors. That design gives EQT a clear route to full ownership and gives holdouts a reason to tender.
The decision to suspend full-year guidance, announced alongside preliminary third-quarter results that gave no growth comparison, suggests management sees more room to reshape the business privately than as a listed company. The key questions are whether EQT funds new automation and digital products at the pace Pratt described, and how the debt load shapes spending on research, manufacturing and acquisitions over the next several years.
What comes next
- BaFin review and publication of the offer document, which opens the acceptance period and the parallel U.S. tender offer.
- A formal reasoned statement from the QIAGEN boards recommending that shareholders tender, after the offer document is published.
- An extraordinary general meeting during the initial acceptance period to vote on post-closing measures.
- Merger control and foreign investment clearances, with closing expected in mid-2027.
- A possible interim dividend of up to $0.47 per share if closing has not occurred within 10 months because of pending regulatory approvals, without reducing the offer price.
Sources
- QIAGEN and EQT Private Equity announce agreement on a recommended voluntary all-cash public takeover offer (Business Wire)
- QIAGEN N.V. ad hoc announcement: business combination agreement, preliminary Q3 2026 results and outlook suspension
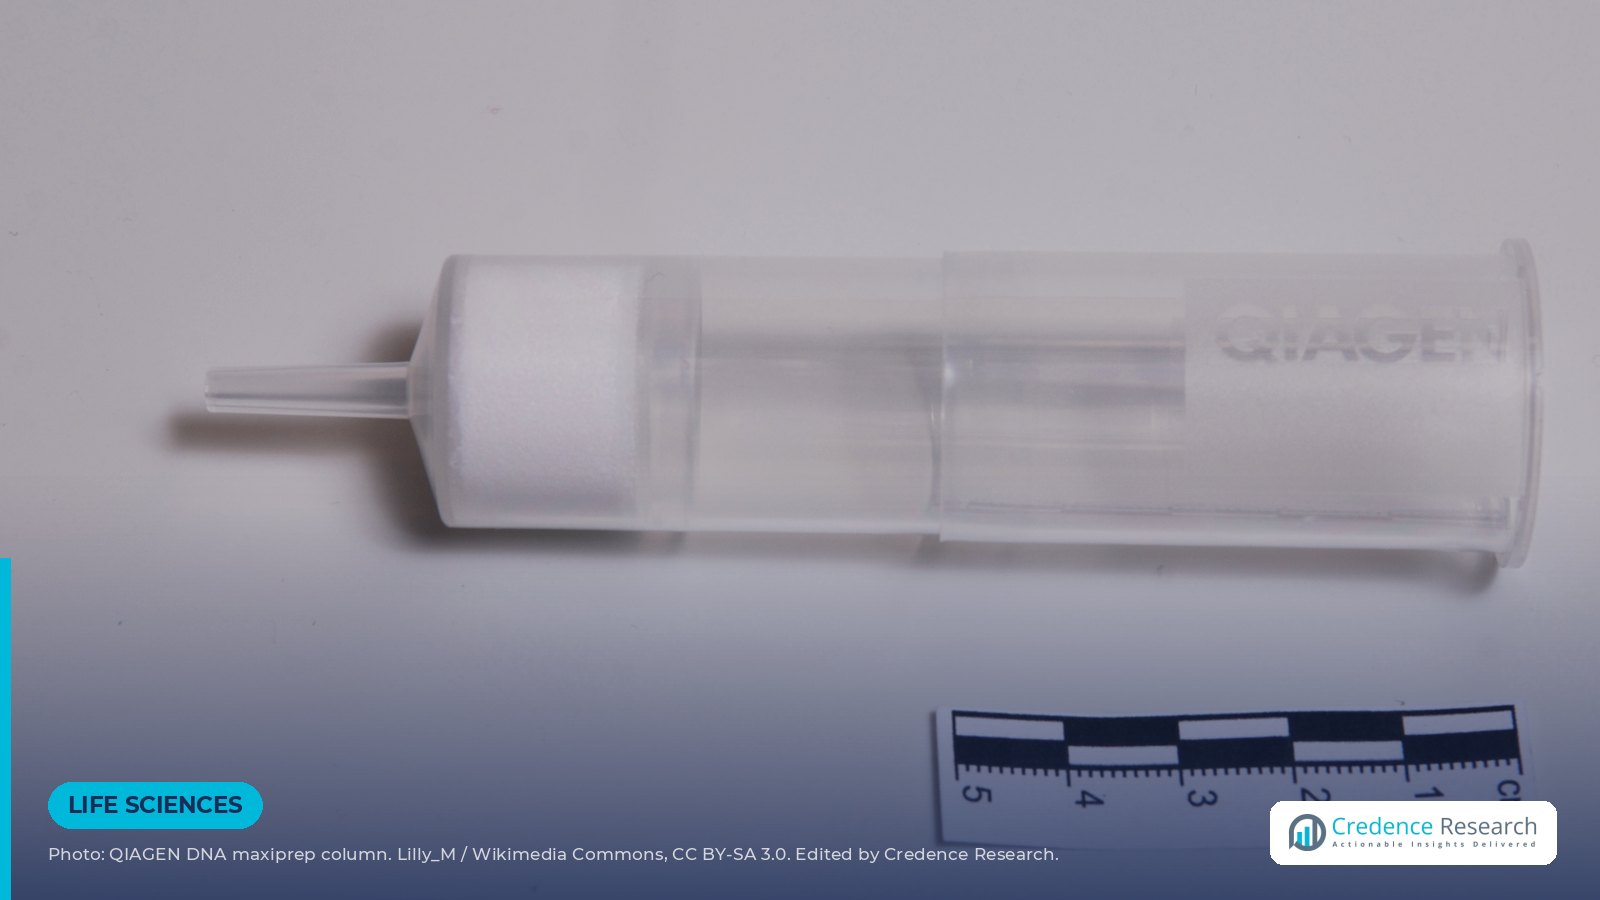
Image: A QIAGEN DNA maxiprep purification column, by Lilly_M via Wikimedia Commons, CC BY-SA 3.0. Cropped and edited by Credence Research.

About the Author

Senior News Editor at Credence Research Inc