
Axial Flux Motor Market Overview
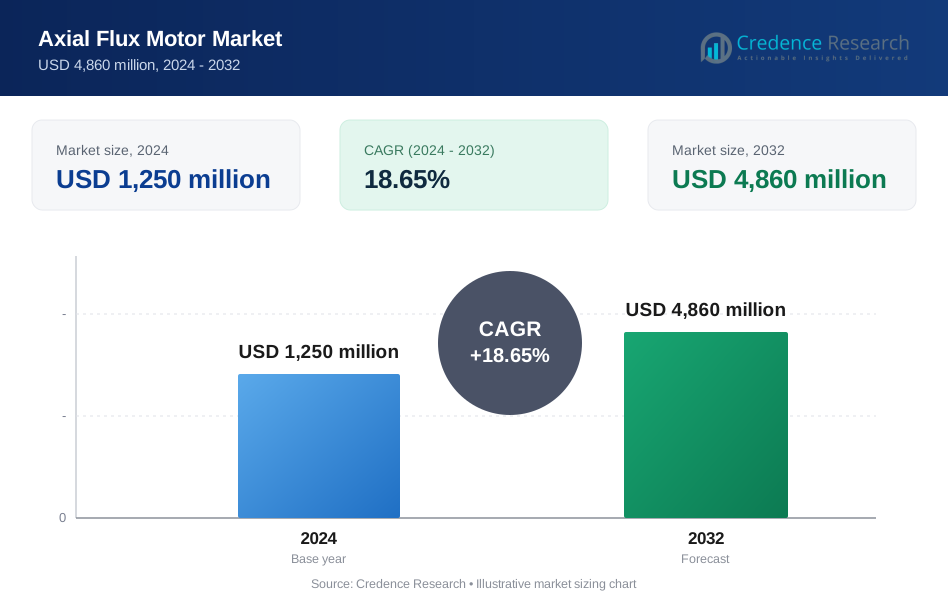
Axial Flux Motor Market size was valued at USD 1501.72 million in 2025 and is anticipated to reach USD 4,970.69 million by 2032, at a CAGR of 18.65% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2021-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Axial Flux Motor Market Size 2025 | USD 1501.72 million |
| Axial Flux Motor Market, CAGR | 18.65% |
| Axial Flux Motor Market Size 2032 | USD 4,970.69 million |
The Axial Flux Motor Market is experiencing rapid growth, primarily driven by increasing adoption in electric vehicles (EVs), where demand for lightweight, compact, and highly efficient motor solutions continues to surge. The market benefits from advancements in automotive electrification, as OEMs prioritize next-generation propulsion technologies to meet stringent emissions regulations and enhance vehicle performance. Growing investments in research and development, alongside supportive government policies promoting clean energy, are accelerating innovation and product commercialization. Additionally, the expanding use of axial flux motors in industrial automation and renewable energy systems further propels market growth. Key trends shaping the industry include the integration of advanced materials to improve power density, the development of modular motor designs for flexible applications, and the emergence of smart manufacturing practices. These factors collectively contribute to a robust market outlook, fostering continuous innovation and positioning axial flux motors as a pivotal component in modern electrification strategies.
The Axial Flux Motor Market demonstrates strong geographical diversity, with significant growth observed across Asia Pacific, Europe, and North America. Asia Pacific leads the market, driven by rapid advancements in electric vehicle manufacturing and a robust supply chain network, particularly in China and Japan. Europe stands out for its pioneering approach to automotive electrification and regulatory focus on sustainable mobility, fostering widespread adoption of high-efficiency motor technologies. North America’s market expansion is fueled by investments in advanced manufacturing and increasing demand for electric mobility solutions. Among the prominent players shaping the Axial Flux Motor Market are Magnax bvba, known for its innovative high-performance motors; YASA Limited, recognized for supplying advanced axial flux technology to automotive OEMs; and Nidec Corporation, a global leader in electric motor manufacturing. These companies, along with others such as Saietta Group, continue to drive innovation and competition across key regions.
Axial Flux Motor Market Insights
- The Axial Flux Motor Market is projected to grow from USD 1501.72 million in 2025 to USD 4,970.69 million by 2032, at a CAGR of 18.65%.
- Rising adoption of electric vehicles and increased focus on lightweight, high-efficiency propulsion systems drive market expansion, especially among OEMs aiming to meet emission and energy targets.
- Key market trends include rapid advancements in motor materials, increasing integration of digital technologies for predictive maintenance, and growing use in diverse applications such as industrial machinery, marine propulsion, and aerospace.
- Competitive dynamics are shaped by leading players like Magnax bvba, YASA Limited, and Nidec Corporation, who invest in R&D and strategic partnerships to deliver next-generation, high-performance axial flux motors.
- The market faces restraints such as complex manufacturing processes, high production costs, and dependence on rare earth materials, which can affect scalability and supply chain stability.
- Regional analysis shows robust demand in Asia Pacific due to automotive manufacturing growth, while Europe benefits from regulatory push for electrification and North America sees steady uptake in electric mobility and industrial automation.
- The market is evolving through increased collaborations between automotive OEMs and technology innovators, supporting customization, higher efficiency, and the expansion of axial flux motor applications across emerging end-user industries.
Axial Flux Motor Market Drivers
Rising Adoption of Electric Vehicles Boosts Market Expansion
The rapid shift toward electric mobility significantly drives the Axial Flux Motor Market. Electric vehicle manufacturers increasingly seek compact and lightweight motor solutions to improve range, performance, and energy efficiency. Axial flux motors deliver higher power density and improved torque compared to conventional radial flux motors, making them a preferred choice in EV propulsion systems. OEMs leverage these advantages to meet stringent emissions regulations and address consumer demand for advanced electric vehicles. Government incentives and stricter regulatory frameworks worldwide encourage automotive electrification, amplifying the need for next-generation electric drivetrains. The growing penetration of electric cars, buses, and commercial vehicles worldwide further propels the market forward.
- For instance, the International Energy Agency (IEA) projects that electric vehicles will account for 25% of all new car sales by 2025, reinforcing demand for advanced motor technologies.
Technological Innovations Accelerate Market Growth
Ongoing research and development efforts underpin strong momentum in the Axial Flux Motor Market. Manufacturers focus on enhancing motor efficiency, reducing weight, and optimizing thermal management. Advanced materials, such as high-performance magnets and specialized laminations, help improve power output and reliability. The emergence of modular and scalable motor designs offers flexibility for integration across various mobility and industrial platforms. Collaboration between automotive OEMs, technology firms, and component suppliers accelerates the commercialization of cutting-edge axial flux motor solutions. Continuous improvements in design and engineering drive adoption across emerging applications and industries.
- For instance, modular and scalable axial flux motor designs are enabling flexible integration across mobility and industrial platforms.
Expanding Applications Beyond Automotive Segment
The Axial Flux Motor Market continues to diversify, with applications growing beyond automotive. Industries such as aerospace, renewable energy, and industrial automation adopt axial flux motors for their compact form factor and superior efficiency. Electric aircraft and drones utilize these motors to achieve lighter weights and higher performance standards. Renewable energy systems, including wind and hydroelectric generators, benefit from the motors’ high efficiency and power density. Industrial automation sectors leverage axial flux motors to streamline operations and reduce energy consumption. It maintains robust demand due to its versatility across multiple high-growth end-user segments.
Supportive Policy Environment and Sustainability Initiatives
A favorable policy landscape contributes to the strong growth trajectory of the Axial Flux Motor Market. Governments worldwide implement regulations promoting clean energy adoption and carbon emission reduction, incentivizing industries to transition to electric solutions. Funding for research and pilot projects helps accelerate product innovation and market entry. Energy efficiency standards and sustainability targets encourage businesses to integrate advanced motor technologies into their operations. Public and private sector collaboration fosters a climate of innovation and adoption. The emphasis on sustainable practices and environmental stewardship continues to reinforce market expansion and long-term viability.
Axial Flux Motor Market Trends
Integration of Advanced Materials and Design Innovations Enhances Performance
Continuous advancements in materials science and engineering shape the current trends in the Axial Flux Motor Market. Manufacturers are investing in lightweight, high-strength composites and rare earth magnets to improve power density and efficiency. It benefits from innovative cooling systems and thermal management solutions, which enhance reliability and prolong operational life. Motor designers prioritize modularity, enabling easier customization and integration across diverse platforms. Advances in computer-aided design and simulation tools allow for optimized motor architectures. These trends collectively enable superior performance and adaptability to emerging mobility and industrial applications.
Growth in Electric Mobility Drives Market Diversification
The transition to electric mobility drives significant diversification within the Axial Flux Motor Market. It sees robust demand from electric vehicle manufacturers seeking efficient propulsion solutions for cars, motorcycles, commercial vehicles, and specialty transportation. Axial flux motors’ compact design and high torque output align well with evolving vehicle architectures. The expansion into electric two-wheelers, buses, and off-road vehicles underscores the versatility of these motors. Battery technology advancements and falling costs further support broader market penetration. Stakeholders are keenly focused on addressing integration challenges to maximize the potential of axial flux motor adoption in mobility applications.
- For instance, the rising demand for electric vehicles (EVs) is fueling the adoption of axial flux motors due to their compact design and high torque output.
Digitalization and Smart Manufacturing Accelerate Market Evolution
The adoption of digital technologies and smart manufacturing practices is a defining trend in the Axial Flux Motor Market. It leverages automation, IoT-enabled monitoring, and predictive maintenance to enhance operational efficiency. Data-driven insights support quality control, streamline production processes, and reduce downtime. The integration of Industry 4.0 principles accelerates product innovation cycles and shortens time-to-market. Manufacturers utilize advanced analytics to forecast demand and optimize supply chains. These trends position the market for sustained growth and competitiveness in a rapidly evolving industrial landscape.
- For instance, Industry 4.0 principles, including automation and IoT-enabled monitoring, are being integrated into axial flux motor production to enhance efficiency.
Emphasis on Sustainability and Circular Economy Initiatives
Heightened awareness of environmental impact and resource sustainability influences trends in the Axial Flux Motor Market. It responds to market demand for energy-efficient, recyclable, and low-carbon solutions across end-user industries. Stakeholders are prioritizing the use of eco-friendly materials and energy-saving production processes. Lifecycle analysis and circular economy principles guide product development and waste reduction strategies. Regulatory pressure and consumer preference for sustainable products encourage continuous improvements in environmental performance. The commitment to sustainability is now a key differentiator among leading market participants.
Axial Flux Motor Market Challenges Analysis
Supply Chain Constraints and Raw Material Volatility
Volatility in raw material prices and supply chain disruptions pose significant obstacles for the Axial Flux Motor Market. It depends on the steady supply of rare earth elements and high-grade materials, which are subject to fluctuating prices and geopolitical uncertainties. Disruptions in global logistics or restrictions on material exports can impact production schedules and profit margins. Manufacturers face pressure to secure long-term contracts and diversify sourcing strategies to mitigate these risks. Compliance with environmental regulations and sustainability standards introduces further complexity. Addressing these supply chain challenges is critical for market stability and future growth.
- For instance, the industry relies on rare earth elements, which are subject to fluctuating prices and geopolitical uncertainties, impacting production schedules and profit margins.
Complex Manufacturing Processes and High Production Costs
The Axial Flux Motor Market faces challenges related to complex manufacturing processes and high production costs. The intricate design of axial flux motors demands precise engineering, specialized materials, and advanced assembly techniques. It often requires high-performance magnets and sophisticated cooling systems, contributing to elevated production expenses. Manufacturers must invest heavily in research and development to overcome technical barriers and ensure consistent product quality. Limited availability of skilled labor and advanced manufacturing infrastructure can slow scalability. High initial costs present a hurdle for new market entrants and limit adoption among cost-sensitive customers.
Axial Flux Motor Market Opportunities
Expansion into New Mobility and Industrial Applications
The Axial Flux Motor Market holds significant opportunities through expansion into new mobility and industrial applications. Its unique advantages compact size, high torque, and superior power density enable it to address the evolving needs of electric aircraft, drones, and marine propulsion systems. The growing electrification of construction and agricultural equipment creates new pathways for adoption in off-highway vehicles. The shift toward smart factories and automated systems in manufacturing industries further opens up demand for highly efficient, space-saving motors. Strategic partnerships with OEMs and technology innovators facilitate the integration of axial flux motors into next-generation platforms. Successful market players will focus on custom solutions to capitalize on diverse application requirements.
Innovation in Sustainable Materials and Circular Economy Solutions
Advancements in sustainable materials and circular economy initiatives present long-term growth prospects for the Axial Flux Motor Market. It stands to benefit from the development of eco-friendly components and recycling technologies that reduce environmental impact. Stakeholders investing in green manufacturing processes and closed-loop supply chains will position themselves as leaders in responsible production. Increased regulatory support and consumer demand for low-carbon solutions create a favorable environment for innovative product launches. Collaborative research with material scientists and industry consortia will help accelerate the transition to sustainable axial flux motor designs. Companies that align with global sustainability trends are likely to gain competitive advantage and unlock new revenue streams.
Market Segmentation Analysis:
By Cooling Process:
By cooling process, the market features two main segments: air cooling and liquid cooling. Air-cooled axial flux motors offer simplicity and cost-effectiveness, making them suitable for smaller vehicles and applications where thermal demands remain moderate. It finds substantial adoption in electric passenger cars and light industrial equipment. Liquid-cooled motors, on the other hand, excel in high-performance and heavy-duty applications due to superior heat dissipation and the ability to sustain peak output over extended periods. This segment supports sectors such as commercial vehicles, industrial machinery, and electric propulsion systems for marine and aerospace.
By Power:
Segmenting the Axial Flux Motor Market by power output reveals a wide spectrum of deployment opportunities. The 1kW–15kW range targets light electric vehicles, two-wheelers, and compact robotics, offering energy efficiency and design flexibility. The 15kW–80kW segment addresses the needs of mainstream electric passenger vehicles and some commercial platforms, combining balanced performance with reasonable weight and size. Motors in the 80kW–160kW bracket are prevalent in high-end electric cars, buses, and specialized industrial equipment, supporting applications that demand elevated torque and sustained reliability. Units rated above 160kW are engineered for premium electric vehicles, heavy commercial fleets, and high-power industrial and marine propulsion, where uncompromising performance and durability are critical.
By Motor Efficiency:
Motor efficiency is another key dimension in the Axial Flux Motor Market, segmented into LE1, LE2, LE3, and LE4 classes. LE1 and LE2 motors typically serve applications with standard efficiency requirements, offering a cost-effective balance of output and energy use. LE3 and LE4 motors represent advanced, high-efficiency models that cater to sectors where reducing operational costs and meeting stringent regulatory standards are essential. These premium efficiency classes align with global trends toward sustainability and support end users focused on lowering energy consumption and emissions. The breadth and depth of these segments underscore the market’s adaptability to customer demands and the continual push for innovation within the axial flux motor industry.
Segments:
Based on Cooling Process:
- Air Cooling
- Liquid Cooling
Based on Power:
- 1kW–15kW
- 15kW–80kW
- 80kW–160kW
- Above 160kW
Based on Motor Efficiency:
- LE1
- LE2
- LE3
- LE4
Based on Application:
- Electric Passenger Vehicles
- Commercial Vehicles
- Industrial Machinery
- Elevators
- Robotics Actuators and Propulsion Systems
- Aircrafts & Electric Glider Planes
- Yachts & Electric Boats
- Electric Drones
- Others
Based on End-User Industry:
- General Manufacturing
- Power
- Construction
- Automotive
- Aerospace
- Marine
- Agriculture
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
Asia Pacific
As of 2024, Asia Pacific holds the largest market share, accounting for approximately 38% of the global Axial Flux Motor Market. The region’s dominance is driven by its strong automotive manufacturing ecosystem, particularly in China, Japan, and South Korea, where electric vehicle production and component innovation remain a priority. Robust government incentives supporting EV adoption and significant investments in industrial automation have fueled market expansion. China leads the charge with its ambitious new energy vehicle targets and world-class battery manufacturing capabilities. The region also benefits from a growing renewable energy sector, where axial flux motors are increasingly utilized in wind and solar applications. Rapid urbanization and infrastructure development continue to boost demand for advanced, high-efficiency motors across diverse end-user industries.
Europe
Europe represents the second-largest regional market, capturing approximately 29% of the global market share. The region stands out for its pioneering role in sustainable mobility, stringent emissions regulations, and focus on electrification. Leading automotive manufacturers across Germany, France, the UK, and Nordic countries actively integrate axial flux motors into their latest EV platforms. The presence of prominent motor technology innovators and specialized suppliers further accelerates product development and commercialization. Europe’s robust aerospace, marine, and industrial automation sectors present lucrative opportunities for high-performance axial flux motor applications. Continued regulatory pressure to reduce carbon emissions and improve energy efficiency propels investments in next-generation electric propulsion technologies. Government-backed research initiatives and strategic industry partnerships drive continuous advancements and reinforce Europe’s leadership in high-efficiency motor deployment.
North America
North America accounts for approximately 22% of the global Axial Flux Motor Market. The United States leads regional growth, propelled by strong demand for electric mobility, increasing investment in advanced manufacturing, and a vibrant start-up ecosystem focused on electrification. The market benefits from substantial R&D funding, the presence of leading EV brands, and expanding applications in aerospace, defense, and off-highway vehicles. Regulatory support for clean energy, tax incentives for electric vehicle adoption, and growing interest in sustainable industrial operations foster steady market growth. North America’s focus on smart infrastructure and IoT-driven manufacturing environments also amplifies demand for compact, high-efficiency motors. Collaboration between technology firms, automakers, and research institutes is advancing the integration of axial flux motor solutions into a broader range of high-value applications.
Rest of the World
Rest of the World, including regions such as Latin America, the Middle East, and Africa, holds a collective market share of approximately 11%. While adoption remains in earlier stages compared to mature markets, these regions display growing interest in electric mobility and renewable energy integration. Governments are increasingly investing in clean transportation infrastructure and energy-efficient technologies to address urbanization challenges and environmental concerns. The expansion of local manufacturing capabilities and strategic alliances with global technology leaders present long-term growth opportunities. Key focus areas include electric buses, light commercial vehicles, and distributed energy generation systems, where axial flux motors’ efficiency and versatility deliver competitive advantages. As market awareness and regulatory support continue to strengthen, the Rest of the World is expected to witness steady progress and rising contribution to the global axial flux motor market in the coming years.
Key Player Analysis
Magnax BV Nidec Corporation Schaeffler AG NTN Corporation Phi-Power Lucchi R. S.r.l. Evans Electric YASA Limited Evolito Ltd. OthersCompetitive Analysis
The competitive landscape of the Axial Flux Motor Market is shaped by technological innovation, strategic alliances, and a strong emphasis on research and development. Leading players such as Magnax bvba, YASA Limited, Nidec Corporation, Schaeffler Group, Saietta Group, NTN Corporation, Phi-Power, Lucchi R. S.r.l., and ZIEHL-ABEGG drive the market forward with proprietary motor designs and advanced engineering capabilities. These companies focus on improving power density, efficiency, and scalability to meet the evolving demands of electric vehicles, industrial automation, and renewable energy applications. The market witnesses frequent collaborations between technology providers and automotive OEMs to accelerate integration of next-generation axial flux motors into mainstream electric mobility platforms. Strategic partnerships, global supply chain optimization, and targeted expansion into high-growth regions further reinforce the competitive positions of market participants. Continuous technological advancement and responsiveness to customer-specific requirements remain critical factors for maintaining leadership and achieving long-term market growth.
Recent Developments
- In August 2022, Magnax, technology leader in axial flux electric motors, has closed a €20m funding round and adds two new investors: BIG Capital, who led the round, and SFPIM. With yokeless axial flux technology at its core, Magnax’s mission is to accelerate the innovation of EV powertrains and aerospace propulsion systems.
- In August 2023, Electric truck OEM Tresa Motors unveils its axial flux motor platform. Tresa Motors, an original equipment manufacturer (OEM) for electric trucks based in India, introduced its platform, the FLUX 350, featuring a Permanent Magnet Synchronous Axial Flux Motor.
- In November 2022, Naxatra lab, has launched their axial flux powertrain for electric vehicles. This cutting-edge technology promises enhanced efficiency and performance in electric vehicle drive systems.
Market Concentration & Characteristics
The Axial Flux Motor Market exhibits a moderate to high level of concentration, with a handful of established companies commanding a significant share of global revenues. It is characterized by intensive research and development, proprietary technologies, and high barriers to entry due to complex manufacturing requirements and specialized engineering expertise. Market participants focus on continuous product innovation, targeting improvements in power density, energy efficiency, and design flexibility to address the needs of diverse end-use industries. The market values strong intellectual property portfolios and emphasizes collaboration with automotive OEMs, technology firms, and industrial partners. It responds quickly to regulatory changes and advances in electrification, particularly in the automotive, aerospace, and industrial sectors. The Axial Flux Motor Market is marked by a dynamic interplay of innovation, strategic alliances, and regional expansion, ensuring sustained competitiveness and growth opportunities for leading players.
Report Coverage
The research report offers an in-depth analysis based on Cooling Process, Power, Motor Efficiency, Application, End-User Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is projected to experience significant growth, driven by increasing demand across various industries.
- Electric vehicles will continue to be a primary application area, with axial flux motors offering advantages in power density and efficiency.
- Advancements in manufacturing techniques are expected to reduce production costs, making axial flux motors more accessible.
- The aerospace sector is anticipated to adopt axial flux motors for electric propulsion systems, contributing to market expansion.
- Industrial automation will benefit from the compact design of axial flux motors, facilitating integration into various machinery.
- Marine applications are likely to see increased use of axial flux motors, aligning with the push for sustainable maritime solutions.
- The development of rare-earth-free axial flux motors will address supply chain concerns and promote environmental sustainability.
- Collaborations between motor manufacturers and OEMs are expected to accelerate the adoption of axial flux technology.
- Regulatory support for clean energy initiatives will further drive the implementation of axial flux motors in multiple sectors.
- Continuous innovation and research will expand the application range of axial flux motors, solidifying their role in future technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Surging Electric Vehicle Adoption
The rapid growth of the electric vehicle (EV) market is fueling demand for axial flux motors, which offer superior power density, compactness, and efficiency compared to traditional motors. OEMs are increasingly integrating these motors to meet stringent emissions regulations and consumer expectations for high-performance EVs.
Technological Advancements in Motor Design
Continuous innovation in materials, cooling systems, and modular architectures is enhancing the performance and reliability of axial flux motors. These advancements enable broader application across automotive, industrial, and aerospace sectors, supporting market expansion.
Supportive Government Policies and Sustainability Initiatives
Global regulatory frameworks promoting clean energy and carbon reduction are incentivizing the adoption of advanced electric propulsion technologies, including axial flux motors. Subsidies, tax incentives, and R&D funding are accelerating commercialization and market penetration.
Expansion into New Industrial and Mobility Applications
Beyond automotive, axial flux motors are increasingly used in aerospace, marine, robotics, and renewable energy systems due to their lightweight design and high efficiency. This diversification is opening new revenue streams and driving overall market growth.
Smart Manufacturing and Digitalization
The integration of Industry 4.0 principles, such as automation, IoT-enabled monitoring, and predictive maintenance, is improving production efficiency and product quality for axial flux motors. These digital advancements are reducing costs and enabling faster time-to-market.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Axial Flux Motor Market?
What factors are driving the growth of the Axial Flux Motor Market?
What are some challenges faced by the Axial Flux Motor Market?
Who are the major players in the Axial Flux Motor Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Power
- 1.2.1 1kW–15kW
- 1.2.2 15kW–80kW
- 1.2.3 80kW–160kW
- 1.2.4 Above 160kW
- 1.3 By Application
- 1.3.1 Electric Passenger Vehicles
- 1.3.2 Commercial Vehicles
- 1.3.3 Industrial Machinery
- 1.3.4 Aircrafts & Electric Glider Planes
- 1.3.5 Yachts & Electric Boats
- 1.3.6 Electric Drones
- 1.3.7 Robotics Actuators and Propulsion Systems
- 1.3.8 Others
- 1.4 By Cooling Process
- 1.4.1 Air Cooling
- 1.4.2 Liquid Cooling
- 1.5 By Motor Efficiency
- 1.5.1 LE1
- 1.5.2 LE2
- 1.5.3 LE3
- 1.5.4 LE4
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,250 million → 2032: USD 4,860 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Axial Flux Motor Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Axial Flux Motor Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Axial Flux Motor Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Axial Flux Motor Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Axial Flux Motor Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Axial Flux Motor Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Axial Flux Motor Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Axial Flux Motor Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,250 million → 2032: USD 4,860 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Axial Flux Motor Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Power - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 1kW–15kW
- 12.3.7.2 15kW–80kW
- 12.3.7.3 80kW–160kW
- 12.3.7.4 Above 160kW
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Electric Passenger Vehicles
- 12.4.7.2 Commercial Vehicles
- 12.4.7.3 Industrial Machinery
- 12.4.7.4 Aircrafts & Electric Glider Planes
- 12.4.7.5 Yachts & Electric Boats
- 12.4.7.6 Electric Drones
- 12.4.7.7 Robotics Actuators and Propulsion Systems
- 12.4.7.8 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Cooling Process - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Air Cooling
- 12.5.7.2 Liquid Cooling
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Motor Efficiency - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 LE1
- 12.6.7.2 LE2
- 12.6.7.3 LE3
- 12.6.7.4 LE4
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Axial Flux Motor End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Axial Flux Motor Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Axial Flux Motor Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Axial Flux Motor Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Magnax BV
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Nidec Corporation
- 18.4 YASA Limited
- 18.5 Schaeffler AG
- 18.6 NTN Corporation
- 18.7 Saietta Group
- 18.8 Phi-Power
- 18.9 Lucchi R. S.r.l.
- 18.10 Evans Electric
- 18.11 Evolito Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

