
Market Overview
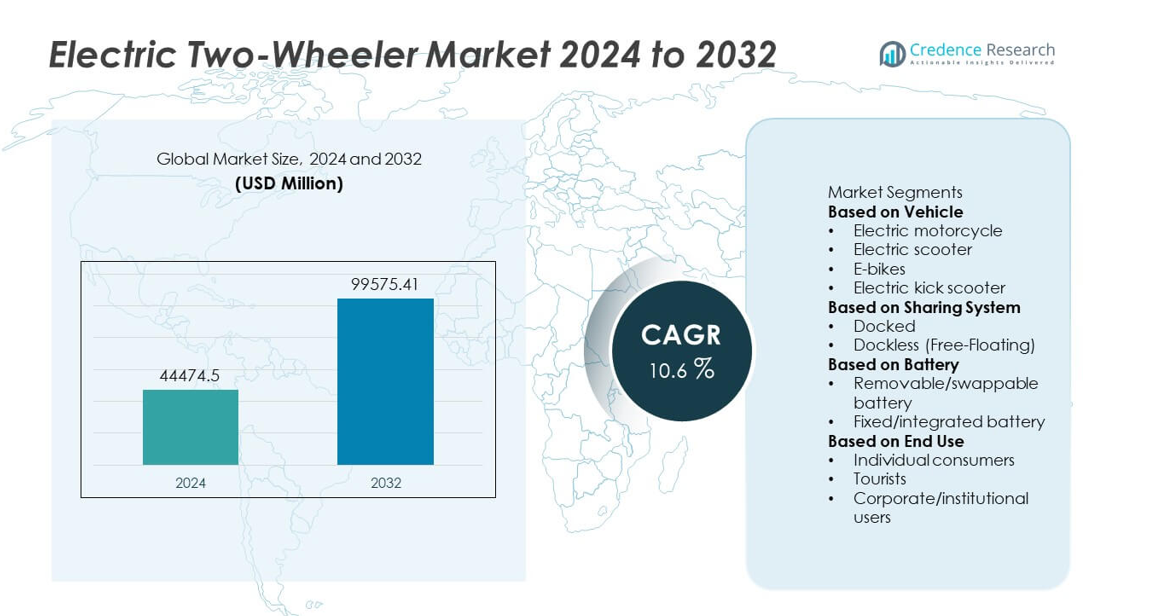
The Electric Two-Wheeler Market was valued at USD 44,474.5 million in 2024 and is projected to reach USD 99,575.41 million by 2032, growing at a CAGR of 10.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electric Two-Wheeler Market Size 2024 | USD 44,474.5 million |
| Electric Two-Wheeler Market , CAGR | 10.6% |
| Electric Two-Wheeler Market Size 2032 | USD 99,575.41 million |
The Electric Two-Wheeler Market is led by key players such as Yulu, Bolt, TIER Mobility, GrabWheels, Bird.co, Voi Technology, Lime Micromobility, Helbiz, Revel, and Dott. These companies are driving innovation through smart connectivity, battery-swapping solutions, and app-based micro-mobility services. Continuous expansion of shared electric scooter and e-bike fleets in major cities supports rapid market penetration. Asia-Pacific emerged as the leading region, holding a 69% market share in 2024, driven by strong local manufacturing and government incentives. Europe followed with 17%, supported by strict emission targets, while North America accounted for 9%, propelled by growing adoption in shared mobility and urban transport solutions.
Market Insights
- The Electric Two-Wheeler Market was valued at USD 44,474.5 million in 2024 and is projected to reach USD 99,575.41 million by 2032, growing at a CAGR of 10.6% during the forecast period.
- Growth is driven by government incentives, rising fuel prices, and increasing adoption of cost-effective, emission-free transport for urban commuting and delivery applications.
- Market trends focus on battery-swapping technology, connected mobility, and the rise of shared e-scooter and e-bike platforms to enhance convenience and reduce operating costs.
- Leading players such as Yulu, Lime Micromobility, TIER Mobility, and Bird.co are investing in smart mobility platforms, lightweight vehicle designs, and regional fleet expansion strategies.
- Asia-Pacific dominates the market with a 69% share, followed by Europe with 17% and North America with 9%, while electric scooters lead the vehicle segment with a 55% share due to their strong urban mobility demand.
Market Segmentation Analysis:
By Vehicle
The electric scooter segment dominated the Electric Two-Wheeler Market in 2024 with a 55% market share. Its leadership is supported by growing adoption for short-distance urban commuting and delivery services. Electric scooters offer cost efficiency, compact design, and low maintenance, appealing to both individual users and fleet operators. Manufacturers such as Yadea, Hero Electric, and Niu Technologies are expanding smart and connected scooter models with advanced lithium-ion batteries. Increasing demand for eco-friendly personal transport and rapid expansion of city-based e-mobility programs continue to strengthen this segment’s dominance.
- For instance, Yadea's KS6 Pro electric scooter is powered by a 500 W brushless motor paired with a 15 Ah lithium battery, offering a range of up to 55 km per charge and a top speed of up to 30 km/h. The model integrates an intelligent control system and a triple braking system (disc, drum, and regenerative electric), which aids in energy recovery during daily commutes.
By Sharing System
The dockless (free-floating) segment held a 62% market share in 2024, driven by its flexibility and convenience for users. This system allows riders to pick up and drop vehicles anywhere within service zones, enhancing accessibility. Major cities across Europe, Asia, and North America are adopting dockless models to support sustainable urban transport. Technology integration, including GPS tracking and mobile app-based rentals, further boosts adoption. Operators like Lime and Bird are scaling fleet size and geographic coverage, making dockless sharing a preferred model for micro-mobility expansion.
- For instance, Lime Micromobility operates a global fleet of e-scooters and e-bikes that exceeded 270,000 vehicles in early 2025, deploying them across its network of over 280 cities. Its vehicles are equipped with IoT modules for real-time fleet tracking, with many featuring swappable batteries to reduce downtime.
By Battery
The removable or swappable battery segment accounted for a 57% market share in 2024. Its popularity is due to the convenience of quick battery replacement and minimal downtime for riders. This technology supports better energy management and allows fleet operators to optimize vehicle availability. Companies such as Gogoro and Ather Energy are developing large-scale battery-swapping networks to enhance accessibility. The flexibility and cost-effectiveness of removable systems make them ideal for both personal and commercial applications, driving widespread adoption in densely populated urban areas worldwide.
Key Growth Drivers
Government Incentives and Emission Regulations
Supportive government policies and emission control regulations are major drivers for the electric two-wheeler market. Subsidies, tax exemptions, and purchase incentives encourage consumers to shift from fuel-powered to electric vehicles. Countries across Asia and Europe are setting stricter emission targets, boosting EV adoption. Urban areas are also introducing low-emission zones, accelerating the replacement of conventional scooters and bikes. These initiatives reduce ownership costs and promote local manufacturing, strengthening electric mobility ecosystems and driving strong adoption across commuter and delivery segments.
- For instance, India's government provided Yulu with support to expand its electric fleet under local manufacturing incentives. Yulu's stated goal is to deploy 100,000 electric vehicles by 2025. Its Miracle GR scooter is powered by a lithium-ion battery, achieving a significant range per charge while contributing to zero tailpipe emissions in urban areas.
Technological Advancements in Battery and Charging Systems
Advancements in lithium-ion and solid-state batteries are transforming the performance and reliability of electric two-wheelers. Improved energy density, faster charging, and enhanced battery life have made electric models more practical for daily commuting. Manufacturers are integrating regenerative braking and smart energy management systems to improve efficiency. Fast-charging and swappable battery technologies are reducing range anxiety and downtime. Continuous R&D investment in compact and lightweight battery solutions continues to strengthen vehicle performance, driving consumer confidence and large-scale adoption worldwide.
- For instance, Gogoro developed its swappable battery network with over 2,500 GoStations supporting 540,000 daily battery swaps across Taiwan. Each smart lithium-ion pack stores 1.7 kWh of energy and completes a full swap in less than 6 seconds, enabling seamless power continuity for shared e-scooter fleets operated by partners like Yamaha and Hero MotoCorp.
Rising Urbanization and Growing Demand for Affordable Mobility
Increasing urban population density and traffic congestion are pushing demand for compact and affordable mobility solutions. Electric two-wheelers offer cost-effective alternatives to cars and public transport for short-distance travel. Their low maintenance, reduced fuel dependency, and eco-friendly operation appeal to both individuals and commercial users. The rapid growth of e-commerce and last-mile delivery services further supports fleet electrification. With improving infrastructure and digital ride-sharing platforms, electric two-wheelers are becoming a practical choice for urban transportation in emerging and developed markets.
Key Trends & Opportunities
Expansion of Shared Mobility and Micro-Mobility Services
The rise of shared mobility platforms is driving demand for electric scooters and bikes in urban areas. Companies are investing in large-scale e-fleet deployments to offer affordable, app-based rentals. Dockless systems and smart GPS tracking have made shared electric vehicles more convenient for daily use. Governments are supporting these initiatives as part of sustainable city mobility programs. The growing preference for flexible, short-distance travel options creates opportunities for manufacturers and operators to collaborate on connected, low-emission transport solutions.
- For instance, Third Lane Mobility Inc., the parent company of Bird and Spin, operates a micromobility fleet that serves cities and university campuses across North America, Europe, and the Middle East.
Integration of Smart and Connected Technologies
Electric two-wheelers are rapidly integrating digital technologies such as IoT, telematics, and AI-driven systems. These features enable real-time tracking, remote diagnostics, and predictive maintenance. Manufacturers are adding smartphone connectivity, GPS navigation, and digital dashboards to enhance rider experience. Connected features also help fleet operators optimize usage and monitor performance. This trend supports data-driven mobility solutions and improves operational efficiency. As consumer expectations shift toward convenience and intelligence, connected electric two-wheelers will become standard across both personal and commercial markets.
- For instance, Voi Technology introduced its Voiager 5 e-scooter equipped with an IoT system capable of transmitting location and performance data. The V5 includes a high-precision GPS antenna for sub-meter accuracy to assist with parking, improving safety and enabling predictive maintenance through data analysis. Rider engagement is enhanced via its connected mobile platform, which uses a QR code for unlocking and other features.
Key Challenges
High Initial Cost and Battery Replacement Expense
Despite operational savings, electric two-wheelers still face challenges from high upfront costs. Batteries represent a major portion of vehicle price, limiting affordability for mass consumers. The expense of battery replacement after a few years of usage further impacts total ownership cost. Although declining battery prices are improving accessibility, cost competitiveness with petrol-based models remains a concern in developing regions. Financial support, leasing programs, and battery-as-a-service models will be essential to overcome this challenge and increase market penetration.
Limited Charging Infrastructure and Range Constraints
stations, creating inconvenience for riders. Range limitations also discourage potential buyers, particularly in areas with poor grid support. Manufacturers and energy providers are now collaborating to expand charging networks and deploy compact home chargers. Overcoming infrastructure barriers through public-private partnerships and standardized charging systems will be critical for enabling consistent, large-scale market growth.
Regional Analysis
Asia-Pacific
Asia-Pacific held the largest market share of 69% in 2024, driven by high adoption in China, India, and Southeast Asia. Strong government incentives, urban congestion, and rising fuel costs have accelerated the shift toward electric mobility. China leads the market with large-scale production and domestic consumption supported by companies such as Yadea, AIMA, and Niu Technologies. India and Indonesia are expanding manufacturing capabilities and EV infrastructure under national electrification programs. Affordable pricing, battery-swapping networks, and growing e-commerce delivery demand continue to strengthen Asia-Pacific’s leadership in the global electric two-wheeler market.
Europe
Europe captured a 17% market share in 2024, supported by stringent emission regulations and growing urban sustainability initiatives. Countries like Germany, France, and the Netherlands are promoting electric mobility through subsidies and charging infrastructure investments. The rising popularity of e-bikes and shared electric scooters in metropolitan areas has fueled demand. Manufacturers are focusing on performance, design, and integration of connected technologies to appeal to eco-conscious consumers. Strong environmental policies and expansion of smart mobility services will continue to support Europe’s role as a fast-growing region in the electric two-wheeler market.
North America
North America accounted for a 9% market share in 2024, driven by increasing adoption in the U.S. and Canada. The market benefits from rising fuel costs, government rebates, and the growth of last-mile delivery services. Electric bikes and scooters are gaining traction in urban centers as cities promote clean and compact transport options. Companies like Bird, Lime, and Harley-Davidson’s LiveWire are expanding product portfolios to capture consumer and commercial segments. Investments in charging infrastructure and strong regulatory backing will further enhance regional growth over the forecast period.
Latin America
Latin America held a 3% market share in 2024, led by emerging adoption in Brazil, Mexico, and Colombia. Economic focus on affordable and sustainable transport options is driving interest in electric scooters and e-bikes. Local governments are introducing pilot projects and incentive schemes to promote electric mobility in urban areas. Manufacturers are partnering with regional distributors to establish assembly units and charging networks. Although adoption is at an early stage, growing environmental awareness and urban delivery demand indicate significant potential for market expansion in the coming years.
Middle East & Africa
The Middle East and Africa accounted for a 2% market share in 2024, reflecting early-stage adoption supported by government sustainability programs. The UAE, Saudi Arabia, and South Africa are investing in electric mobility as part of long-term carbon reduction strategies. Growing urbanization and tourism-related transport demand are creating opportunities for electric scooter deployment. However, limited charging infrastructure and high import costs remain challenges. With planned EV infrastructure investments and supportive policies, the region is expected to witness steady growth in electric two-wheeler adoption during the forecast period.
Market Segmentations:
By Vehicle
- Electric motorcycle
- Electric scooter
- E-bikes
- Electric kick scooter
By Sharing System
- Docked
- Dockless (Free-Floating)
By Battery
- Removable/swappable battery
- Fixed/integrated battery
By End Use
- Individual consumers
- Tourists
- Corporate/institutional users
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Electric Two-Wheeler Market includes major players such as Yulu, Bolt, TIER Mobility, GrabWheels, Bird.co, Voi Technology, Lime Micromobility, Helbiz, Revel, and Dott. These companies focus on expanding product portfolios, improving battery technology, and developing sustainable shared mobility solutions. Strategic collaborations with city authorities and energy providers are strengthening their market presence across urban regions. Many players are integrating IoT-based fleet management, smart connectivity, and AI-driven analytics to enhance operational efficiency. Regional startups are emphasizing affordability and localized production to gain market traction. Meanwhile, established companies are investing in fast-charging and swappable battery systems to reduce downtime and improve user convenience. The increasing focus on micro-mobility, digital platforms, and environmentally responsible transport solutions continues to intensify competition in the global electric two-wheeler market.
Key Player Analysis
Recent Developments
- In April 2025, Lime entered an exclusive agreement with Redwood Materials (founded by ex-Tesla CTO JB Straubel) to recycle lithium-ion batteries from its shared e-bikes and scooters in the U.S., Germany, and the Netherlands. Lime sends end-of-life batteries (5–7 years old, ~500 charge cycles) to Redwood’s Nevada facility.
- In 2025, Yulu expanded its presence in the quick-commerce segment via its Yulu Dex low-speed electric scooter line, emphasizing delivery use cases under 25 km/h.
- In August 2024, Lime officially entered the Japanese market with its e-scooter service in Tokyo, marking its first expansion into East Asia. The launch, which began on August 19, 2024, introduces 200 Gen4.1 and Gen4.1 Seated e-scooters across six wards: Shibuya, Shinjuku, Meguro, Setagaya, Toshima, and Nakano.
- In 2024, Yulu turned EBITDA positive and announced plans to deploy 100,000 electric vehicles by 2025, scaling its shared mobility footprint.
- In 2024, TIER Mobility and Dott finalized their merger, retiring the TIER brand and operating all scooters and e-bikes under the Dott platform in 427 cities
Report Coverage
The research report offers an in-depth analysis based on Vehicle, Sharing System, Battery, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The electric two-wheeler market will expand rapidly as urban areas adopt clean mobility.
- Battery technology improvements will enhance range, performance, and charging efficiency.
- Shared mobility and rental platforms will continue driving large-scale adoption in cities.
- Manufacturers will focus on lightweight designs and modular battery architectures for better efficiency.
- Public and private investments in charging networks will strengthen operational convenience.
- Partnerships between automakers and energy firms will accelerate battery-swapping infrastructure development.
- Government policies and emission targets will remain key growth enablers worldwide.
- Connected technologies will enhance vehicle monitoring, fleet management, and user experience.
- Emerging markets will see increased adoption due to affordable pricing and local manufacturing initiatives.
- Sustainability goals and digital innovation will shape the next phase of electric two-wheeler transformation.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Government Incentives and Emission Regulations
Supportive policies, subsidies, and emission control regulations are encouraging consumers and fleet operators to shift from fuel-powered to electric two-wheelers. These measures reduce ownership costs and promote local manufacturing, accelerating adoption in both commuter and delivery segments.
Technological Advancements in Battery and Charging Systems
Improvements in lithium-ion and solid-state batteries, along with the rise of swappable and fast-charging solutions, are making electric two-wheelers more practical and reliable for daily use. Enhanced energy density and reduced charging times address range anxiety and operational downtime.
Expansion of Shared Mobility and Micro-Mobility Services
The proliferation of app-based rental platforms and large-scale e-fleet deployments in urban areas is driving rapid market penetration. Dockless systems and smart connectivity make electric two-wheelers more accessible and convenient for short-distance travel.
Rising Urbanization and Demand for Affordable Mobility
Increasing urban population density and traffic congestion are pushing demand for compact, cost-effective transport solutions. Electric two-wheelers offer a practical alternative for personal and commercial users, especially for last-mile delivery and daily commuting.
Integration of Smart and Connected Technologies
The adoption of IoT, telematics, and AI-driven systems enables real-time tracking, predictive maintenance, and enhanced user experience. These connected features improve operational efficiency for fleet operators and appeal to tech-savvy consumers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the Global Electric Two Wheelers Market in 2023 and 2032?
What factors are driving the growth of the electric two-wheelers market?
How are government policies contributing to market growth?
Which region dominates the Global Electric Two Wheelers Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Battery
- 1.2.1 Removable/swappable battery
- 1.2.2 Fixed/integrated battery
- 1.3 By End Use
- 1.3.1 Individual consumers
- 1.3.2 Tourists
- 1.3.3 Corporate/institutional users
- 1.4 By Vehicle
- 1.4.1 Electric motorcycle
- 1.4.2 Electric scooter
- 1.4.3 E-bikes
- 1.4.4 Electric kick scooter
- 1.5 By Sharing System
- 1.5.1 Docked
- 1.5.2 Dockless (Free-Floating)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 44,474.5 million → 2032: USD 99,575.41 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Electric Two-wheelers Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Electric Two-wheelers Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Electric Two-wheelers Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Electric Two-wheelers Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Electric Two-wheelers Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Electric Two-wheelers Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Electric Two-wheelers Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Electric Two-wheelers Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 44,474.5 million → 2032: USD 99,575.41 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Electric Two-wheelers Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Battery - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Removable/swappable battery
- 12.3.7.2 Fixed/integrated battery
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End Use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Individual consumers
- 12.4.7.2 Tourists
- 12.4.7.3 Corporate/institutional users
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Vehicle - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Electric motorcycle
- 12.5.7.2 Electric scooter
- 12.5.7.3 E-bikes
- 12.5.7.4 Electric kick scooter
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Sharing System - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Docked
- 12.6.7.2 Dockless (Free-Floating)
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Electric Two-wheelers End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Electric Two-wheelers Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Electric Two-wheelers Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Electric Two-wheelers Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Yulu
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Bolt
- 18.4 TIER Mobility
- 18.5 GrabWheels
- 18.6 Bird.co
- 18.7 Voi Technology
- 18.8 Lime Micromobility
- 18.9 Helbiz
- 18.10 Revel
- 18.11 Dott
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

