
Market Overview:
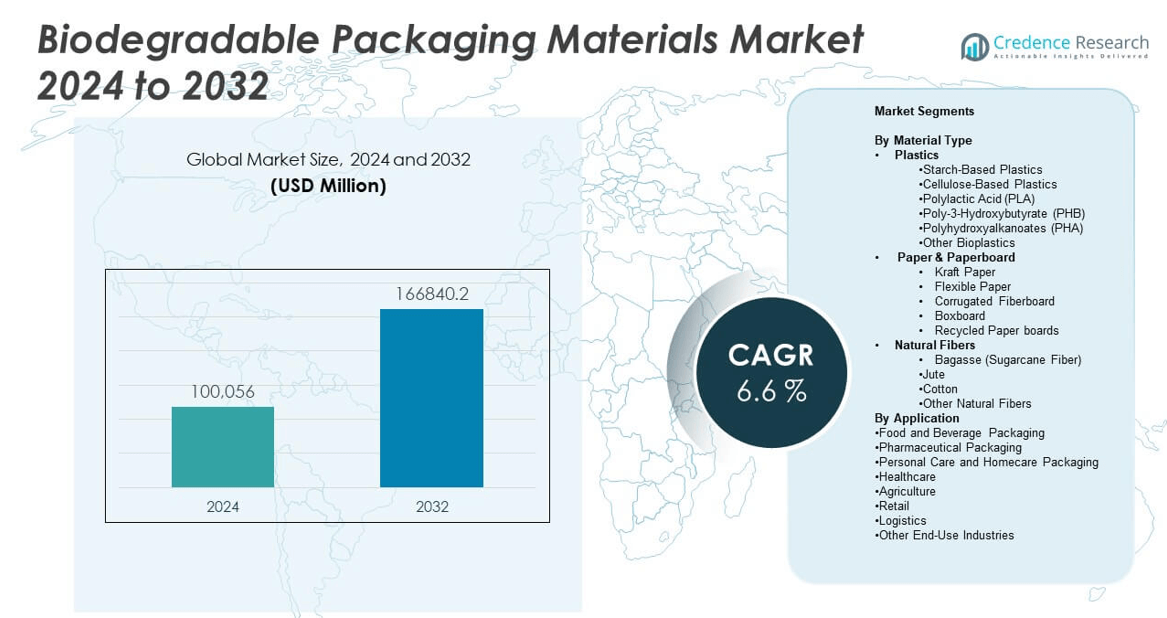
The Biodegradable Packaging Materials Market is projected to grow from USD 100,056 million in 2024 to an estimated USD 166,840.2 million by 2032, with a compound annual growth rate (CAGR) of 6.6% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Biodegradable Packaging Materials Market Size 2024 | USD 100,056 million |
| Biodegradable Packaging Materials Market, CAGR | 6.6% |
| Biodegradable Packaging Materials Market Size 2032 | USD 166,840.2 million |
This market is experiencing strong momentum as consumer awareness about environmental sustainability intensifies and governments impose stricter regulations on single-use plastics. Manufacturers are adopting biodegradable alternatives made from materials such as starch, polylactic acid (PLA), and cellulose, which break down naturally without leaving harmful residues. The increasing demand for eco-friendly packaging in the food and beverage, personal care, and healthcare sectors is further propelling market growth. Technological advancements in compostable and water-soluble films are also opening new opportunities for application across multiple industries.
Geographically, Europe leads the market due to stringent environmental policies and widespread adoption of green packaging solutions. North America follows closely, driven by corporate sustainability goals and consumer preference for environmentally responsible products. The Asia Pacific region is emerging rapidly, supported by rising environmental awareness, expanding e-commerce, and proactive government initiatives in countries like China, India, and South Korea. Latin America and the Middle East are witnessing gradual adoption, primarily led by multinational brands and evolving packaging standards.
Market Insights:
- The Biodegradable Packaging Materials Market was valued at USD 100,056 million in 2024 and is projected to reach USD 166,840.2 million by 2032, growing at a CAGR of 6.6%.
- Growing bans on single-use plastics and strict global regulations are accelerating the shift toward biodegradable alternatives.
- Rising consumer demand for eco-friendly packaging is driving innovation in compostable films and bio-based polymers.
- High production costs and limited industrial composting infrastructure continue to restrain market scalability.
- Europe holds the largest market share at 34%, driven by regulatory enforcement and mature recycling systems.
- Asia Pacific is witnessing the fastest growth due to expanding urbanization and national plastic reduction policies.
- North America maintains strong momentum, supported by ESG-driven corporate initiatives and sustainable packaging mandates.
Market Drivers:
Rising Global Regulatory Pressures on Conventional Plastic Waste Management
Governments across key regions are implementing strict regulations against conventional plastic usage. These policies include bans on single-use plastics and mandates for compostable packaging in consumer products. The shift has created high demand for biodegradable alternatives. The Biodegradable Packaging Materials Market benefits from regulatory alignment with environmental goals. Brands are adapting packaging formats to comply with evolving legislation. Regulatory bodies in Europe and North America are enforcing eco-compliance certifications. These legal frameworks are accelerating transitions to bio-based packaging. Companies face significant penalties for non-compliance, prompting proactive material sourcing. Regulations continue to reshape packaging development and procurement strategies.
- For example, in the United States, California’s SB 54 bill requires packaging producers to achieve a 25% reduction in single-use plastics and 100% compostability or recyclability in all packaging by 2032.
Growing Consumer Awareness of Environmental Sustainability and Waste Reduction
Eco-conscious consumer behavior is driving demand for biodegradable packaging across retail sectors. Buyers are prioritizing brands that demonstrate commitment to environmental responsibility. The Biodegradable Packaging Materials Market is gaining traction from consumers seeking alternatives to plastic waste. Lifestyle changes and ethical purchasing are reinforcing the shift to compostable materials. Packaging has become a key factor in consumer decision-making. Industries are responding by rebranding and relabeling packaging with sustainability credentials. Public discourse on plastic pollution strengthens support for green materials. Social media campaigns and advocacy groups are influencing consumer expectations. Packaging that communicates biodegradability now holds commercial advantage.
Increased Adoption in the Food and Beverage Sector Due to Compostable Compliance
Food and beverage manufacturers are under pressure to meet both safety and environmental standards. Biodegradable packaging offers a balance between shelf life, hygiene, and sustainability. The Biodegradable Packaging Materials Market has seen significant demand from this segment. Compostable containers, films, and wraps are replacing traditional plastic counterparts. Regulatory guidance encourages compostable solutions for single-serve and ready-to-eat packaging. Brands are aligning with zero-waste movements to enhance market positioning. Certified compostable materials attract eco-conscious consumers in the food sector. Supply chains are adjusting to incorporate plant-based polymers for mass production. Food service providers are investing in compostable packaging to meet green targets.
- For instance, Magical Mushroom Company’s mycelium-based packaging is made from 100% mushroom root (mycelium) combined with agricultural waste such as hemp or sawdust. The packaging is custom-molded and produced in about seven days. It fully decomposes in home compost conditions within approximately 40 to 45 days and is certified for industrial compostability under recognized standards, including EN 13432.
Technological Advancements Enhancing Material Performance and Application Range
Innovation in material science is enabling the development of high-performance biodegradable solutions. New blends offer strength, flexibility, and durability equivalent to conventional plastic. The Biodegradable Packaging Materials Market is evolving with enhanced mechanical and barrier properties. Manufacturers are integrating additives that accelerate decomposition without compromising function. Advancements allow broader applications across industrial, healthcare, and electronics packaging. High-speed production compatibility has improved market feasibility for large-scale deployment. Research institutions and startups are collaborating to enhance material properties. Funding for R&D in biopolymers is expanding the innovation pipeline. Technology is making biodegradable options more competitive with petroleum-based packaging.
Market Trends:
Shift Toward Bio-Based Multilayer Films and Coatings for Functional Packaging
The market is observing growing adoption of bio-based multilayer films in flexible packaging. These films combine compostability with high-performance barriers against moisture and oxygen. The Biodegradable Packaging Materials Market is seeing a shift toward coated paper and PLA blends. Bio-based coatings are replacing petroleum-based laminates in foodservice and pharmaceutical packaging. Manufacturers are creating hybrid structures that support recyclability and biodegradability. These innovations address both functional and environmental demands. Brand owners seek sustainable films that maintain printability and sealing strength. Regulatory incentives for mono-material solutions further promote multilayer biodegradable films. Product launches emphasize recyclability, compostability, and renewable content.
- For example, Earthfirst Films launched its Earthfirst Compostable Laminations in November 2024 engineered to deliver moisture and oxygen barrier properties matching those of conventional plastics, now available as regenerative, high-performance pre-laminations suitable for digital printing.
Expansion of E-Commerce Accelerating Demand for Sustainable Secondary Packaging
The e-commerce sector is pushing demand for biodegradable cushioning, mailers, and shipping bags. Retailers are seeking sustainable solutions for secondary packaging amid consumer pressure. The Biodegradable Packaging Materials Market is adapting to online retail's high-volume, protective packaging needs. Corrugated boxes, molded pulp inserts, and starch-based peanuts are gaining traction. Brands aim to improve the sustainability of their unboxing experience. Environmentally-friendly void fills and outer wrappings enhance corporate ESG compliance. Product returns and reshipments require resilient yet biodegradable options. Logistics partners are optimizing packaging for sustainability in transit. Consumer satisfaction increasingly depends on the ecological profile of delivery packaging.
Brand Differentiation Through Visual Communication of Compostability Claims
Design and labeling of biodegradable packaging now emphasize compostability credentials. Brands use icons, certifications, and printed messages to highlight environmental compliance. The Biodegradable Packaging Materials Market is seeing increased demand for clearly marked eco-packaging. Packaging serves not just a protective function but also a branding and messaging tool. Transparent claims are key to building trust among sustainability-focused buyers. On-pack information about disposal methods is becoming standard practice. Third-party certifications like OK Compost and ASTM D6400 are used prominently. Retailers prefer SKUs that visually communicate sustainable attributes. This trend influences packaging procurement and shelf placement decisions.
Growing Use of Agricultural and Marine Waste Feedstocks for Packaging Material
Manufacturers are exploring non-food biomass sources such as seaweed, bagasse, and corn husks. These feedstocks reduce competition with food supply and offer local sourcing benefits. The Biodegradable Packaging Materials Market is seeing innovation in waste-derived polymer development. Startups are commercializing cellulose-based materials from agro-industrial byproducts. Algae-based films are gaining traction for their fast biodegradation and low footprint. Regional governments support waste valorization initiatives through grants and subsidies. These feedstocks align with circular economy goals and carbon neutrality targets. Low-waste input materials improve lifecycle assessments and reduce environmental burden. Industry partnerships are scaling pilot programs into commercial packaging lines.
- For example, Sway’s seaweed-based bags, commercialized in October 2024, are notable for composting fully in 12 weeks and offering a 40% lower cradle-to-gate carbon footprint compared to fossil-based LDPE.
Market Challenges Analysis:
Limited Commercial Infrastructure for Biodegradable Waste Processing and Collection
One of the main challenges is the absence of robust composting and collection infrastructure. Biodegradable packaging often ends up in landfills, where degradation slows significantly. The Biodegradable Packaging Materials Market faces limitations in post-use material recovery. Municipal waste systems in many regions lack segregation for compostable materials. This infrastructure gap undermines the effectiveness of biodegradable solutions. Consumer confusion about disposal methods leads to contamination of recycling streams. Without widespread industrial composting facilities, end-of-life benefits remain underutilized. Brands face reputational risks if biodegradability claims do not translate into real-world impact. Solving the waste processing bottleneck requires cross-sector collaboration and public investment.
High Costs and Supply Chain Complexity Compared to Conventional Plastic
The cost of biodegradable packaging remains a barrier for widespread adoption. Raw materials like PLA and PHA are more expensive than fossil-based polymers. The Biodegradable Packaging Materials Market must navigate pricing challenges across supply chains. Specialized machinery, certifications, and production processes increase operational expenses. Smaller manufacturers face entry barriers due to high capital requirements. Procurement teams often prioritize affordability over sustainability. Scaling production to reduce unit costs requires significant investment. Price-sensitive sectors hesitate to switch due to marginal cost differences. Aligning cost competitiveness with performance remains a critical hurdle for market expansion.
Market Opportunities:
Rising Corporate Sustainability Targets Driving Investment in Eco-Packaging
Global corporations are prioritizing carbon-neutral goals and ESG reporting. These mandates are creating demand for certified biodegradable packaging at scale. The Biodegradable Packaging Materials Market is positioned to support these sustainability roadmaps. Procurement strategies are shifting toward verified compostable and renewable solutions. Companies view packaging transformation as a key pillar of climate responsibility. Long-term vendor contracts are opening for certified biodegradable suppliers. Industry awards and certifications offer competitive differentiation. Internal product development teams are collaborating with packaging innovators.
Untapped Potential in Emerging Economies with Regulatory Tailwinds
Developing nations are beginning to implement plastic bans and packaging reforms. These shifts open new markets for biodegradable formats in retail and food sectors. The Biodegradable Packaging Materials Market can grow by localizing production in these economies. Low-cost raw materials and growing middle-class awareness fuel potential. Governments offer tax incentives and pilot zones for sustainable packaging ventures. Regional packaging converters seek partnerships with bio-based resin suppliers. Adoption is accelerating in Asia, Latin America, and Africa, supported by urbanization trends.
Market Segmentation Analysis:
The Biodegradable Packaging Materials Market is segmented
By material type into plastics, paper & paperboard, and natural fibers. Plastics hold a dominant share due to the wide use of starch-based plastics, cellulose-based plastics, PLA, PHB, and PHA in flexible packaging applications. PLA and starch-based variants are widely adopted in foodservice and retail due to their compostability and printability. Paper & paperboard, including kraft paper, flexible paper, corrugated fiberboard, boxboard, and recycled paperboards, continue to grow steadily in both primary and secondary packaging due to recyclability and consumer preference for plastic-free formats. Natural fibers such as bagasse, jute, and cotton are gaining traction in niche applications where biodegradability and strength are essential, particularly in rigid and molded formats.
- For instance, NatureWorks LLCis a global leader in PLA (polylactic acid) bioplastics, marketed under the Ingeo™ brand. In 2024, Ingeo™ grades 2003D and 4043D were adopted widely in flexible film and thermoformed packaging for foodservice brands.
By application, food and beverage packaging remains the largest segment due to regulatory mandates and demand for sustainable foodservice materials. Pharmaceutical and healthcare packaging are adopting biodegradable materials to meet clean-label and disposal requirements. Personal care and homecare brands are turning to bioplastics and fiber-based formats for sustainable branding. Agriculture and logistics segments are integrating biodegradable films and molded packaging for crop protection and shipping stability. Retail packaging continues to evolve with eco-friendly alternatives to attract environmentally conscious consumers. It enables a wide variety of industries to meet sustainability goals through certified compostable and recyclable solutions.
- For example, Amcor has launched AmSky™, a recyclable blister pack for pharmaceuticals, replacing PVC with a polyolefin-based structure compatible with current recycling streams.
Segmentation:
By Material Type
- Plastics
- Starch-Based Plastics
- Cellulose-Based Plastics
- Polylactic Acid (PLA)
- Poly-3-Hydroxybutyrate (PHB)
- Polyhydroxyalkanoates (PHA)
- Other Bioplastics
- Paper & Paperboard
- Kraft Paper
- Flexible Paper
- Corrugated Fiberboard
- Boxboard
- Recycled Paper boards
- Natural Fibers
- Bagasse (Sugarcane Fiber)
- Jute
- Cotton
- Other Natural Fibers
By Application
- Food and Beverage Packaging
- Pharmaceutical Packaging
- Personal Care and Homecare Packaging
- Healthcare
- Agriculture
- Retail
- Logistics
- Other End-Use Industries
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Europe holds the largest share of the Biodegradable Packaging Materials Market at 34% in 2024. Strong regulatory enforcement of single-use plastic bans and widespread adoption of compostable solutions drive regional growth. Countries such as Germany, France, and the Netherlands have set ambitious waste reduction targets, encouraging industries to shift toward bio-based packaging. Leading packaging manufacturers in Europe continue to invest in R&D for certified compostable materials. Consumer preference for eco-labeled products strengthens demand across sectors, particularly in food and personal care. Government incentives and well-established waste management infrastructure support sustained market expansion.
North America accounts for 28% of the Biodegradable Packaging Materials Market, led by the U.S. and Canada. Rising awareness of environmental sustainability and increasing adoption of corporate ESG goals fuel packaging transformation. Brands are integrating biodegradable options into e-commerce, retail, and food distribution. The region benefits from rapid material innovation and growing startup activity in bioplastics. Public pressure on brands to eliminate plastic waste accelerates investment in alternative packaging. Municipalities and states have introduced local bans and composting mandates that further reinforce adoption.
Asia Pacific represents 24% of the market share and is the fastest-growing region. It offers significant potential due to rising population, expanding urbanization, and evolving regulatory landscapes. China, India, and South Korea are advancing national plastic reduction policies, creating space for biodegradable packaging adoption. Local manufacturers are scaling production of PLA, starch-based, and cellulose materials to meet demand. E-commerce and food delivery services in the region are integrating sustainable packaging into operations. The Biodegradable Packaging Materials Market in Asia Pacific is benefiting from strong domestic demand and increased export opportunities for compostable goods.
Key Player Analysis:
- Mondi Group
- Smurfit Kappa Group
- Tetra Pak International S.A.
- Sealed Air Corporation
- International Paper Company
- BASF SE
- Stora Enso
- WestRock Company
- DS Smith
- Huhtamaki Oyj
- NatureWorks LLC
- Novamont S.p.A.
- Be Green Packaging LLC
- Eco-Products, Inc.
- Kruger Inc.
- Reynolds Group Holding Limited
- Clearwater Paper Corporation
- Sonoco Products Company
- Berry Global Group
- Ball Corporation
- Vegware Ltd.
Competitive Analysis:
The Biodegradable Packaging Materials Market features strong competition among multinational corporations and regional specialists. Companies compete on material innovation, regulatory compliance, and end-user customization. It continues to see high R&D investment aimed at enhancing performance, shelf life, and printability of biodegradable formats. Strategic mergers and partnerships with biotech startups are expanding market reach. Players focus on product certifications such as EN 13432 and ASTM D6400 to gain credibility. Rising private-label packaging demand pushes firms to offer cost-effective solutions. Market leaders benefit from economies of scale and established supply chains. Competitive advantage lies in the ability to deliver certified, scalable, and sustainable packaging alternatives across industries.
Recent Developments:
- In June 2025, Mondi Group made headlines in the biodegradable packaging materials market by launching the re/cycle PaperPlus Bag Advanced. This innovative high-barrier paper bag significantly reduces plastic content, provides robust moisture protection for humidity-sensitive products, and supports recyclability, making it an ideal choice for the construction sector and powdery goods.
- In May 2024, Sealed Air Corporation released the Liquibox® Universal Self-Sealing Cap, a hygienic, recycle-ready fitment for professional dairy dispensing systems. The product is designed to reduce food waste, enhance hygiene, and extend freshness in commercial milk dispensing applications, underlining Sealed Air’s progress in advancing recyclable packaging innovations.
- In June 2024, Tetra Pak International S.A. entered a new strategic partnership with China’s Yili Group to advance innovation in dairy packaging. The collaboration focuses on R&D in equipment, new materials, quality control, and the sustainable development of dairy packaging, addressing growing consumer demands for greener solutions.
Market Concentration & Characteristics:
The Biodegradable Packaging Materials Market shows moderate concentration with a mix of global leaders and emerging regional players. It is characterized by rapid innovation in materials science and strong alignment with regulatory shifts toward sustainability. The market favors companies with integrated supply chains, advanced R&D capabilities, and proven compliance with compostability standards. Product differentiation relies on functional performance, material sourcing transparency, and environmental certifications. It continues to evolve toward application-specific designs for food, beverage, and personal care packaging. The market encourages cross-sector collaboration between packaging firms, biopolymer producers, and waste management operators.
Report Coverage:
The research report offers an in-depth analysis based on material type and application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for biodegradable packaging will continue to rise due to global regulatory pressure on plastic reduction.
- Consumer preference for sustainable products will drive brand investment in compostable packaging solutions.
- Technological advancements in bio-based materials will expand application across diverse industries.
- Increased availability of composting infrastructure will enhance end-of-life effectiveness for biodegradable products.
- E-commerce growth will boost the need for sustainable secondary and protective packaging formats.
- Emerging markets in Asia and Latin America will become key growth areas due to policy reforms and urbanization.
- Food and beverage companies will lead adoption through eco-certified, functional packaging innovations.
- Strategic partnerships between packaging producers and biopolymer suppliers will support scalability.
- Retailers will prioritize biodegradable alternatives to meet internal sustainability goals and reduce waste footprint.
- Continued R&D investments will improve cost-efficiency, barrier properties, and shelf stability of biodegradable packaging.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Global Regulations on Single-Use Plastics
Governments worldwide are implementing bans and restrictions on conventional plastics, mandating the use of compostable and biodegradable packaging. This regulatory pressure is compelling manufacturers and brands to adopt biodegradable materials to ensure compliance and avoid penalties.
Rising Consumer Awareness and Preference for Sustainability
Consumers are increasingly prioritizing eco-friendly packaging, driving brands to invest in biodegradable solutions that align with environmental values. This shift in consumer behavior is influencing purchasing decisions and encouraging companies to differentiate through sustainable packaging.
Technological Advancements in Biodegradable Materials
Innovations in material science, such as improved compostable films and bio-based polymers, are enhancing the performance, durability, and application range of biodegradable packaging. These advancements make biodegradable options more competitive with traditional plastics and expand their use across industries.
Expansion of E-Commerce and Demand for Sustainable Secondary Packaging
The growth of online retail is increasing the need for protective, sustainable packaging solutions. Biodegradable mailers, cushioning, and shipping materials are being adopted to meet both consumer expectations and corporate ESG goals in the e-commerce sector.
Corporate Sustainability Initiatives and ESG Reporting
Large corporations are setting ambitious sustainability targets, including carbon neutrality and waste reduction, which drive investment in certified biodegradable packaging. These initiatives are reshaping procurement strategies and accelerating the transition to eco-friendly packaging formats.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Biodegradable Packaging Materials Market?
What are the key segments within the Biodegradable Packaging Materials Market?
What are some challenges faced by the Biodegradable Packaging Materials Market?
Who are the major players in the Biodegradable Packaging Materials Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Food and Beverage Packaging
- 1.2.2 Pharmaceutical Packaging
- 1.2.3 Personal Care and Homecare Packaging
- 1.2.4 Healthcare
- 1.2.5 Agriculture
- 1.2.6 Retail
- 1.2.7 Logistics
- 1.2.8 Other End-Use Industries
- 1.3 By Material Type
- 1.3.1 Plastics (Starch-Based, Cellulose-Based, PLA, PHB, PHA, Other Bioplastics)
- 1.3.2 Paper & Paperboard (Kraft Paper, Flexible Paper, Corrugated Fiberboard, Boxboard, Recycled Paper Boards)
- 1.3.3 Natural Fibers (Bagasse, Jute, Cotton, Other Natural Fibers)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 100,056 million → 2032: USD 166,840.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Biodegradable Packaging Materials Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Biodegradable Packaging Materials Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Biodegradable Packaging Materials Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Biodegradable Packaging Materials Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Biodegradable Packaging Materials Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Biodegradable Packaging Materials Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Biodegradable Packaging Materials Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Biodegradable Packaging Materials Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 100,056 million → 2032: USD 166,840.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Biodegradable Packaging Materials Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Food and Beverage Packaging
- 12.3.7.2 Pharmaceutical Packaging
- 12.3.7.3 Personal Care and Homecare Packaging
- 12.3.7.4 Healthcare
- 12.3.7.5 Agriculture
- 12.3.7.6 Retail
- 12.3.7.7 Logistics
- 12.3.7.8 Other End-Use Industries
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Plastics (Starch-Based, Cellulose-Based, PLA, PHB, PHA, Other Bioplastics)
- 12.4.7.2 Paper & Paperboard (Kraft Paper, Flexible Paper, Corrugated Fiberboard, Boxboard, Recycled Paper Boards)
- 12.4.7.3 Natural Fibers (Bagasse, Jute, Cotton, Other Natural Fibers)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Biodegradable Packaging Materials End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Biodegradable Packaging Materials Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Biodegradable Packaging Materials Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Biodegradable Packaging Materials Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Mondi Group
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Smurfit Kappa Group
- 18.4 Tetra Pak International S.A.
- 18.5 Sealed Air Corporation
- 18.6 International Paper Company
- 18.7 BASF SE
- 18.8 Stora Enso
- 18.9 WestRock Company
- 18.10 DS Smith
- 18.11 Huhtamaki Oyj
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

