
Market Overview
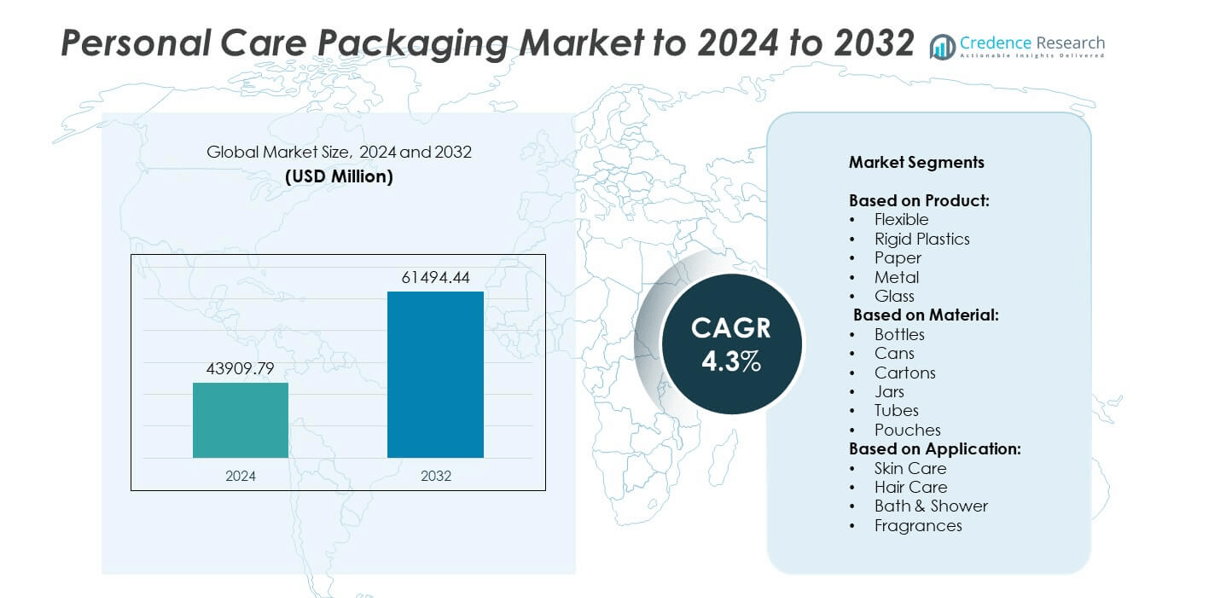
Personal Care Packaging market size was valued USD 43909.79 million in 2024 and is anticipated to reach USD 61494.44 million by 2032, at a CAGR of 4.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Personal Care Packaging Market Size 2024 | USD 43909.79 million |
| Personal Care Packaging Market, CAGR | 4.3% |
| Personal Care Packaging Market Size 2032 | USD 61494.44 million |
The personal care packaging market is shaped by key players including Aptar, Ardagh Group S.A., ITC, Amcor, WestRock Company, Crown, Berry Global, Albea Group, Sonoco Products Company, Mondi, Ampac Holding, and Amcor plc. These companies focus on sustainable materials, lightweight designs, and innovative formats to meet growing consumer demand and regulatory requirements. Strategic collaborations, capacity expansions, and digital printing technologies are widely adopted to strengthen market position and improve brand engagement. North America leads the market with over 32% share in 2024, supported by high consumption of premium personal care products and early adoption of eco-friendly packaging solutions.
Market Insights
- The personal care packaging market was valued at USD 43909.79 million in 2024 and is projected to reach USD 61494.44 million by 2032, growing at a CAGR of 4.3%.
- Rising demand for sustainable and recyclable packaging materials, along with increased personal grooming awareness, is driving strong market growth across all product categories.
- Flexible packaging holds over 40% share as the dominant segment, while bottles lead material use, supported by the popularity of shampoos, lotions, and body wash products.
- The market is competitive, with players focusing on innovation, lightweight designs, and refillable solutions to gain share, supported by strategic mergers, partnerships, and capacity expansions.
- North America leads with over 32% share, followed by Europe at 28% and Asia Pacific at 26%, with strong growth potential in developing economies due to rising disposable incomes and expanding e-commerce channels boosting packaging demand.
Market Segmentation Analysis:
By Product
Flexible packaging led the personal care packaging market in 2024, holding over 40% share due to its lightweight nature, cost-effectiveness, and ability to offer diverse design formats. Its convenience for single-use and travel-size products supports strong demand, particularly in emerging economies. Growth is driven by rising consumer preference for easy-to-use packaging solutions, eco-friendly materials, and reduced transportation costs. Brands are adopting recyclable flexible films to align with sustainability goals. Rigid plastics followed, supported by high durability and suitability for premium product packaging like creams and lotions.
- For instance, Manjushree Technopack has over 275,000 metric tons per annum converting capacity across its plastics preforms, bottles, containers, films, and recycled resins segments.
By Material
Bottles dominated the personal care packaging market with more than 35% share in 2024, supported by their wide use in shampoos, conditioners, lotions, and body washes. Their ability to provide strong barrier protection, easy dispensing, and branding flexibility drives adoption across mass and premium categories. PET and HDPE bottles remain preferred due to recyclability and cost efficiency. Tubes and pouches are also witnessing rapid growth as brands focus on space-saving, lightweight options for e-commerce and sustainable refill packs, meeting growing demand for eco-conscious and convenient packaging.
- For instance, ALPLA has an installed and projected recycling capacity of 290,000 tonnes of recycled PET and 99,000 tonnes of recycled HDPE, bringing its total capacity to 389,000 tonnes of post-consumer recycled material as of mid-2025.
By Application
Skin care accounted for the largest share of the personal care packaging market, holding over 30% share in 2024, driven by rising demand for moisturizers, serums, and sunscreen products. Growth is supported by increasing focus on personal grooming, anti-aging products, and premiumization in urban markets. Packaging innovations like airless pumps and UV-protected bottles enhance product shelf life and consumer appeal. Hair care and bath & shower segments are also expanding steadily, fueled by growth in hygiene awareness and demand for natural and organic formulations.
Market Overview
Rising Demand for Sustainable Packaging
Sustainability is the key growth driver in the personal care packaging market, with consumers favoring eco-friendly materials such as recyclable plastics, paper-based packs, and biodegradable solutions. Brands are investing in closed-loop recycling systems and lightweight packaging to reduce carbon footprint. This shift is supported by stricter regulations like the EU Packaging and Packaging Waste Directive and increasing corporate commitments to achieve net-zero goals. Demand for refillable containers, compostable pouches, and recycled PET bottles is rapidly growing, making sustainability the most influential factor shaping packaging innovations.
- For instance, Amcor operates its Flexibles segment and Rigid Packaging segment in various locations worldwide. In its fiscal year 2024, Amcor reported operating out of 212 locations across 40 countries to produce a range of flexible packaging and rigid plastic containers for markets including food, personal care, and home care.
Growing Personal Grooming and Hygiene Awareness
Increased focus on self-care and hygiene is fueling demand for personal care products, driving packaging consumption. Rising disposable incomes, urbanization, and social media influence are encouraging premium product purchases, which require aesthetically appealing packaging. Categories like skin care, hair care, and bath products are witnessing double-digit growth, supported by rising product launches. Packaging manufacturers are responding with advanced formats like airless pumps, tamper-evident closures, and attractive labeling to cater to this demand. This driver significantly boosts packaging volumes across both mass-market and luxury segments.
- For instance, L’Oréal has expanded its refillable packaging options by a factor of 17 times over the past five years.
Expansion of E-commerce and Direct-to-Consumer Channels
The surge in online beauty and personal care product sales is driving demand for protective and compact packaging formats. E-commerce requires packaging that ensures product safety, tamper resistance, and minimal shipping costs. Companies are adopting lightweight materials, secondary protective packaging, and personalized designs to improve the unboxing experience and enhance brand loyalty. Subscription boxes and sample-size packaging are also gaining traction. This channel expansion is encouraging manufacturers to innovate with durable, sustainable, and space-efficient solutions that balance cost efficiency with visual appeal.
Key Trends & Opportunities
Shift Toward Premium and Smart Packaging
Premiumization in personal care is creating opportunities for high-quality packaging with advanced features. Smart packaging solutions like QR codes, NFC tags, and augmented reality integration are improving brand engagement and traceability. Glass and metal packaging are gaining traction for luxury skin care and fragrances, offering a premium look and superior product protection. Companies are also focusing on visually appealing designs and customization options to strengthen brand identity and attract younger consumers. This trend is reshaping the competitive landscape toward innovative, tech-enabled packaging solutions.
- For instance, Impinj shipped its 100 billionth RAIN RFID tag chip in March 2024, marking a company milestone for total cumulative shipments over its history.
Adoption of Refillable and Reusable Packaging Models
Refillable packaging formats are emerging as a strong opportunity, aligning with sustainability goals and reducing single-use plastic waste. Major brands are launching refill stations, pouch refills, and reusable containers to appeal to environmentally conscious consumers. This model reduces packaging waste while encouraging repeat purchases. Brands like Unilever and L’Oréal are actively piloting refillable product ranges in global markets. Growing consumer acceptance and supportive regulations are likely to accelerate this shift, opening a long-term opportunity for packaging suppliers offering durable and compatible refill systems.
- For instance, The Body Shop installed refill stations in 800 stores worldwide by 2023.
Key Challenges
Volatility in Raw Material Prices
Fluctuating prices of key raw materials such as PET, HDPE, aluminum, and paperboard pose challenges to packaging manufacturers. Price volatility impacts profit margins and makes cost forecasting difficult. Rising energy costs and supply chain disruptions further add to production expenses. Companies must balance between cost efficiency and maintaining sustainable practices, often leading to margin pressure. Strategic sourcing, adoption of recycled materials, and supplier partnerships are becoming necessary to mitigate risks and ensure business continuity in a competitive market.
Regulatory Compliance and Recycling Infrastructure Gaps
Strict regulations on plastic usage, extended producer responsibility (EPR) policies, and packaging waste management requirements are challenging for market players. Many regions still lack adequate recycling infrastructure, making compliance expensive and complex. Companies must invest in sustainable material development and closed-loop systems to meet evolving standards. Failure to comply may result in penalties and reputational risks. Collaboration with recycling firms and governments is crucial to create efficient collection and recycling systems, ensuring compliance while addressing growing consumer expectations for eco-friendly packaging.
Regional Analysis
North America
North America accounted for over 32% share of the personal care packaging market in 2024, making it the leading region. The market benefits from strong demand for premium skin care, hair care, and fragrance products supported by high disposable incomes and consumer focus on grooming. The presence of major global packaging manufacturers and personal care brands encourages innovation in sustainable and refillable formats. Growth in e-commerce channels has boosted the need for durable and protective packaging solutions. The United States dominates the regional market, supported by advanced production capabilities and early adoption of eco-friendly packaging initiatives.
Europe
Europe captured nearly 28% share of the personal care packaging market in 2024, driven by strict environmental regulations and rising consumer awareness about sustainability. Demand for recyclable and paper-based packaging is high, especially in countries like Germany, France, and the U.K. The premium segment for fragrances and luxury skin care is fueling growth in glass and metal packaging formats. Brands are investing in closed-loop recycling systems and refill programs to meet circular economy goals. Increasing online sales and strong innovation capabilities across the region are further supporting the adoption of modern and visually appealing packaging solutions.
Asia Pacific
Asia Pacific represented around 26% of the personal care packaging market in 2024, driven by a growing middle-class population and rapid urbanization. Rising disposable incomes in China, India, and Southeast Asian countries are boosting demand for affordable and attractive packaging solutions. Flexible packaging formats dominate due to cost efficiency and convenience. Regional manufacturers are adopting recyclable materials and lightweight designs to meet sustainability expectations. The region is witnessing rapid e-commerce growth, pushing demand for compact and protective packaging formats. Expanding domestic production and the presence of both local and global brands are further strengthening market opportunities.
Latin America
Latin America held close to 8% share of the personal care packaging market in 2024, with Brazil and Mexico leading regional consumption. Growth is supported by increasing awareness of personal grooming and the adoption of affordable packaging solutions such as flexible pouches and plastic bottles. Economic recovery and rising disposable incomes are boosting demand across skin care and hair care segments. Packaging suppliers are gradually transitioning toward recyclable and lightweight materials to meet global sustainability standards. Investments in local manufacturing and distribution networks are improving product availability and reducing reliance on imported packaging formats.
Middle East & Africa
Middle East & Africa accounted for nearly 6% share of the personal care packaging market in 2024, with demand supported by the rising popularity of fragrances, cosmetics, and luxury personal care products. The region is experiencing growth in modern retail and e-commerce platforms, increasing the need for attractive and protective packaging. Glass and metal formats are preferred for premium products, while flexible packaging is growing in mass-market segments. Local production capabilities are expanding, supported by investments in sustainable packaging technologies. The market is expected to grow steadily as consumer spending on grooming and beauty products continues to rise.
Market Segmentations:
By Product:
- Flexible
- Rigid Plastics
- Paper
- Metal
- Glass
By Material:
- Bottles
- Cans
- Cartons
- Jars
- Tubes
- Pouches
By Application:
- Skin Care
- Hair Care
- Bath & Shower
- Fragrances
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the personal care packaging market features leading players such as Aptar, Ardagh Group S.A., ITC, Amcor, WestRock Company, Crown, Berry Global, Albea Group, Sonoco Products Company, Mondi, Ampac Holding, and Amcor plc. The market is highly competitive with companies focusing on innovation, sustainable materials, and cost-efficient solutions to gain a competitive edge. Many players are investing in lightweight, recyclable, and refillable packaging formats to meet rising consumer demand for eco-friendly products. Strategic partnerships, mergers, and capacity expansions are common to strengthen regional presence and improve production capabilities. Digital printing technologies and smart packaging solutions are increasingly adopted to enhance brand visibility and consumer engagement. The market also sees a focus on meeting e-commerce requirements through protective and compact designs, ensuring safe product delivery. Sustainability goals and regulatory compliance continue to shape competition, driving investment in advanced material research and closed-loop recycling initiatives.
Key Player Analysis
- Aptar
- Ardagh Group S.A.
- ITC
- WestRock Company
- Crown
- Berry Global
- Albea Group
- Sonoco Products Company
- Mondi
- Ampac Holding
- Amcor plc
Recent Developments
- In 2025, Aptar company introduced full-plastic dispensing systems like the Advance Collection, made entirely from polyolefins (PP and PE), making them compatible with common plastic recycling streams.
- In 2025, Bery Global showcased its expanded Exclusive Stick and Refill range. This product line, which includes new travel-friendly sizes, was developed to meet the growing consumer demand for refillable and convenient packaging for deodorants and skincare products.
- In 2023, Amcor joined a strategic alliance with Mars, Delterra, and Procter & Gamble to invest in a circular plastics economy in developing regions. This upstream initiative aims to improve recycling infrastructure and address plastic pollution
Report Coverage
The research report offers an in-depth analysis based on Product, Material, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will see steady growth driven by rising demand for sustainable packaging solutions.
- Brands will focus on recyclable, biodegradable, and refillable formats to meet consumer expectations.
- E-commerce expansion will drive demand for durable and protective packaging formats.
- Premium packaging designs will gain traction in luxury skin care and fragrance segments.
- Smart packaging with QR codes and digital engagement features will become more common.
- Flexible packaging will remain dominant due to its lightweight and cost-efficient nature.
- Manufacturers will invest in advanced materials to meet global sustainability regulations.
- Emerging markets in Asia Pacific will offer strong growth opportunities for packaging suppliers.
- Collaboration between brands and recyclers will improve circular economy adoption.
- Technological innovations in digital printing and automation will enhance packaging customization.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Personal Care Packaging Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Personal Care Packaging Market projected to grow between 2025 and 2032?
Which Personal Care Packaging Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Personal Care Packaging Market?
Who are the leading companies in the Personal Care Packaging Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Personal Care Packaging Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Personal Care Packaging Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 43909.79 million → 2032: USD 61494.44 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Personal Care Packaging Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Personal Care Packaging Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Personal Care Packaging Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Personal Care Packaging Market Drivers
- 3.3 Personal Care Packaging Market Restraints & Challenges
- 3.4 Personal Care Packaging Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Personal Care Packaging Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Personal Care Packaging Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Personal Care Packaging category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Personal Care Packaging Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Personal Care Packaging Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Personal Care Packaging market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Personal Care Packaging Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Personal Care Packaging Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Personal Care Packaging Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Personal Care Packaging (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Personal Care Packaging Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Personal Care Packaging Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Personal Care Packaging Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Personal Care Packaging Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Personal Care Packaging Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Personal Care Packaging Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Personal Care Packaging Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Personal Care Packaging Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Personal Care Packaging Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
