
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Bod Incubator Market Size 2024 | USD 350.65 million |
| Bod Incubator Market, CAGR | 6.34% |
| Bod Incubator Market Size 2032 | USD 593.95 million |
Market Overview:
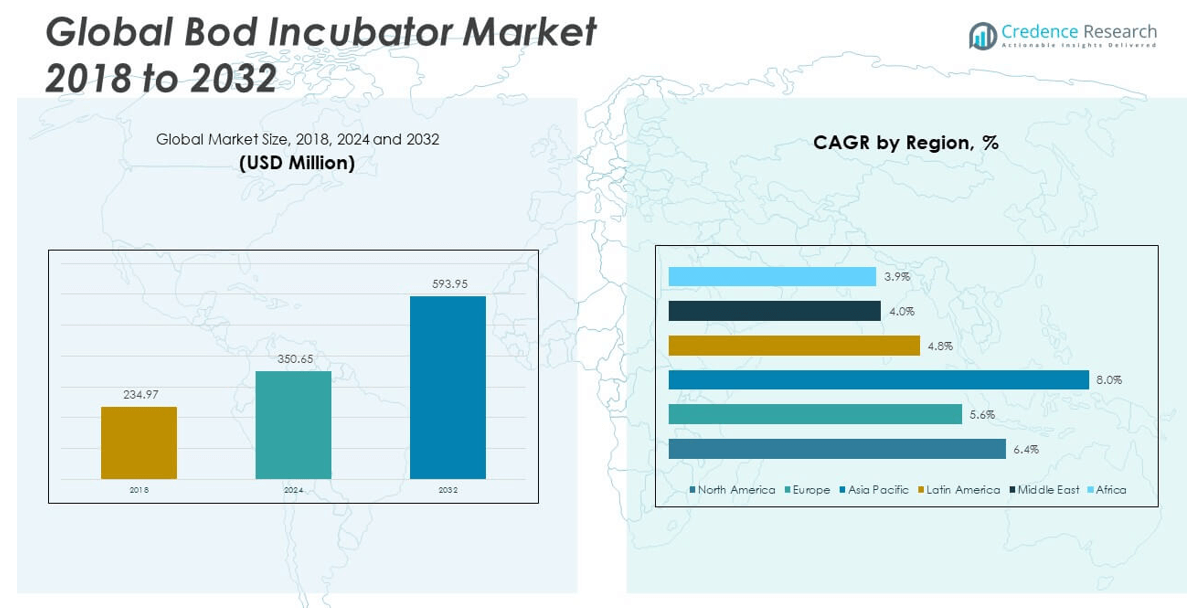
The Global Bio-Oxygen Demand (BOD) Incubator Market size was valued at USD 234.97 million in 2018 to USD 350.65 million in 2024 and is anticipated to reach USD 593.95 million by 2032, at a CAGR of 6.34% during the forecast period.
The growth of the Global BOD Incubator Market is primarily driven by stringent environmental regulations and increasing compliance requirements for wastewater treatment across various industries. Regulatory authorities, including the U.S. Environmental Protection Agency (EPA), the European Environment Agency, and similar bodies in emerging markets, are enforcing tighter discharge standards, prompting industries to adopt reliable BOD monitoring tools. This regulatory push is further amplified by rising environmental awareness among corporations and consumers, which is compelling companies to invest in advanced analytical instruments to monitor water quality. Moreover, technological innovations have significantly enhanced the functionality of BOD incubators. Modern devices now feature energy-efficient systems, programmable digital controls, data logging capabilities, and remote monitoring, which help laboratories and treatment facilities achieve higher accuracy and automation. The demand for compact, user-friendly, and low-maintenance units is also gaining traction.
North America currently holds the largest share of the global BOD incubator market, accounting for a significant portion of revenue due to well-established environmental policies and advanced infrastructure for water treatment and research. The United States leads the region in terms of demand, driven by strict EPA mandates and strong investments in environmental testing technologies. Europe follows as the second-largest market, supported by the European Union’s Water Framework Directive and robust industrial activity that necessitates routine BOD monitoring. Countries such as Germany, the U.K., and France represent key contributors to the region's growth. Meanwhile, the Asia-Pacific region is emerging as the fastest-growing market, with expanding wastewater treatment initiatives in countries like China, India, and Japan. Rapid urbanization, industrialization, and heightened environmental awareness in these countries are creating substantial opportunities for BOD incubator adoption. Additionally, growing public infrastructure investments in Southeast Asia are supporting market expansion. In contrast, Latin America, the Middle East, and Africa are still in the early stages of adoption.
Market Insights:
- The Global BOD Incubator Market reached USD 350.65 million in 2024 and is projected to grow at a CAGR of 6.34%, reaching USD 593.95 million by 2032, driven by increasing environmental regulation compliance.
- Stricter environmental discharge standards enforced by agencies like the EPA and EEA are compelling industries to adopt advanced BOD incubators for wastewater quality monitoring.
- Technological innovations in BOD incubators, such as digital controls, data logging, and remote monitoring, are enhancing efficiency and expanding their application across research and industrial labs.
- Sustainability initiatives and eco-focused regulations are boosting market demand, with institutions prioritizing water quality testing to align with global environmental goals.
- High equipment costs and budget limitations continue to challenge adoption in developing regions, where affordability remains a critical barrier to market expansion.
- Asia Pacific is the fastest-growing region, driven by rapid industrialization, urbanization, and investment in water infrastructure across China, India, and Southeast Asia.
- North America holds the largest market share, led by the U.S., due to well-established environmental policies and strong investments in testing and compliance technologies.
Market Drivers:
Stringent Environmental Regulations and Policy Compliance Requirements
Environmental regulations across developed and emerging economies continue to play a central role in propelling demand for BOD incubators. Regulatory bodies such as the U.S. Environmental Protection Agency (EPA), the European Environment Agency, and regional water management authorities mandate the regular testing of biochemical oxygen demand in industrial and municipal wastewater. These regulations aim to reduce environmental pollution and ensure the safe disposal of effluents. Industries including pharmaceuticals, food and beverages, chemicals, and pulp and paper are legally obligated to monitor water quality before discharge. The Global BOD Incubator Market benefits directly from this compliance-driven demand, as BOD incubators are a standard requirement for accurate and reproducible testing. It is expected that ongoing updates to environmental guidelines will reinforce the need for advanced incubation technologies across both public and private sectors.
- For example, Thermo Fisher Scientific’s Heratherm refrigerated incubators are explicitly designed to meet U.S. EPA Method 5210B for BOD testing, offering temperature uniformity of ±0.2°C at 20°C, which ensures compliance with stringent environmental standards.
Rising Industrialization and Wastewater Generation
Accelerating industrialization across Asia-Pacific, Latin America, and parts of Africa is contributing to increased volumes of industrial wastewater. With more manufacturing units and processing facilities operating globally, the need for effective wastewater management tools is growing rapidly. Industries are adopting advanced monitoring systems to meet both operational and regulatory demands. BOD incubators are essential tools for determining organic pollution levels and validating the efficiency of water treatment processes. The Global BOD Incubator Market is responding to this demand by offering products that cater to high-throughput laboratories and decentralized testing environments. It is poised for strong growth in regions where industrial output is rising and infrastructure development is prioritizing water sustainability.
Technological Advancements and Automation in Laboratory Equipment
Modern laboratories are transitioning toward digitally integrated and automated systems to enhance efficiency and precision. This shift is driving innovation in BOD incubator design and functionality. Features such as programmable temperature settings, digital display interfaces, built-in data logging, and remote monitoring capabilities are now standard in many new models. These innovations enable laboratories to reduce manual errors, improve workflow, and maintain regulatory documentation with ease. The Global BOD Incubator Market benefits from this evolution, with manufacturers introducing compact, energy-efficient, and multi-functional units to address varied customer needs. It is evolving rapidly to align with the broader trend of smart lab solutions and data-driven environmental monitoring.
- For example, modern BOD incubators commonly incorporate touchscreen digital controls, programmable temperature cycling, and USB/RS‑232 data capabilities. These features truly automate routine testing, reduce manual logging, and improve compliance with regulatory and quality standards.
Growing Focus on Sustainable Water Management Practices
The growing global emphasis on sustainability and environmental stewardship is encouraging public and private organizations to implement effective water management practices. This includes continuous monitoring of water quality indicators such as BOD to support eco-friendly operations and responsible resource use. Institutions engaged in water treatment, research, and policy implementation increasingly depend on accurate testing to support informed decision-making. The Global BOD Incubator Market is gaining traction in response to this emphasis on sustainable development and corporate responsibility. It supports long-term initiatives aimed at pollution control, resource conservation, and ecological balance. It continues to expand as sustainability becomes a core component of operational strategy across sectors.
Market Trends:
Integration of Smart Monitoring and IoT Capabilities
The adoption of Internet of Things (IoT) technologies in laboratory equipment is reshaping the operational landscape of BOD incubators. Laboratories are increasingly demanding devices that offer real-time data tracking, remote accessibility, and predictive maintenance alerts. Smart BOD incubators integrated with sensors and cloud connectivity are enabling seamless monitoring and control, even from off-site locations. These systems improve operational reliability and minimize downtime by notifying users of deviations from set parameters. The Global BOD Incubator Market is experiencing a shift toward such intelligent, connected solutions that align with modern digital infrastructure. It is expected to see rising investment in smart features that enhance user convenience and ensure data integrity in regulated environments.
- For instance, iGene Labserve’s BOD Incubator features a computerized PID temperature controller with real-time digital display of both set and process values, ensuring precise temperature regulation within a range of 5°C to 60°C. The unit is equipped with high/low temperature alarms and supports remote monitoring capabilities, allowing for data tracking and alert notifications if the temperature deviates from set parameters.
Customization and Modular Design Preferences Among End Users
Laboratories are moving away from one-size-fits-all equipment in favor of customizable, modular solutions. End users now seek BOD incubators that can be tailored to fit specific applications, sample volumes, or spatial constraints. This trend is particularly strong in contract testing labs, academic research centers, and mobile field units. Manufacturers are responding with modular units that allow flexibility in configuration, expandability, and ease of integration into existing laboratory setups. The Global BOD Incubator Market is adjusting to this trend by offering a wider range of models that cater to niche applications without compromising performance. It is aligning product development strategies with customer demand for adaptability and space efficiency.
- For example, Labman Automation, for example, provides incubators that can be tailored for specific rack and bottle sizes, supporting up to 500 bottles in a single unit. Their systems can be configured as standalone units or as integrated modules within larger robotic workflows, such as enclosing the entire BOD robot inside the incubator for continuous, unattended operation over weekends.
Increased Demand from Academic and Research Institutions
There is growing demand for BOD incubators from universities, technical institutes, and research organizations focused on environmental science, water management, and microbiological analysis. These institutions require cost-effective, reliable incubators for conducting studies on pollution control, water quality assessment, and biological treatment processes. The trend is fueled by global funding initiatives aimed at strengthening scientific research on climate change, sustainable water use, and ecosystem restoration. The Global BOD Incubator Market is expanding in this segment, supported by government-backed education and research programs. It is seeing increased procurement from public-sector laboratories and grant-funded projects, especially in developing regions where environmental education is being prioritized.
Focus on User-Centric Features and Ergonomic Enhancements
Laboratory professionals are placing higher value on ease of use, safety, and ergonomic design in laboratory equipment. The market is seeing a shift toward BOD incubators that feature user-friendly interfaces, low-noise operation, improved thermal insulation, and enhanced safety mechanisms. Touchscreen controls, intuitive menus, and quick calibration settings are becoming standard to reduce the learning curve for new users. The Global BOD Incubator Market is evolving to incorporate these human-centered design elements, improving overall user satisfaction and productivity. It is supporting the growing demand for equipment that delivers operational simplicity without sacrificing technical sophistication.
Market Challenges Analysis:
High Equipment Cost and Budget Constraints in Developing Regions
One of the primary challenges limiting the adoption of BOD incubators is the high upfront cost associated with advanced models. Many small laboratories and environmental testing facilities in developing countries operate on limited budgets, which restricts their ability to invest in sophisticated equipment. Cost-sensitive markets often prioritize basic operational needs over technologically enhanced features, slowing the market penetration of digital and automated BOD incubators. The Global BOD Incubator Market faces difficulty in scaling across price-sensitive sectors where demand exists but purchasing power remains low. It requires manufacturers to balance innovation with affordability to reach broader user bases. Lack of financing options or public procurement delays also hinder large-scale implementation in academic and public-sector laboratories.
Maintenance Complexity and Operational Skill Gaps
Another persistent issue in the market involves maintenance and the technical skill required to operate modern BOD incubators efficiently. Advanced models often integrate features like programmable controls, real-time monitoring, and automated calibration that require trained personnel. In regions lacking adequate technical support or training infrastructure, users may struggle to operate and maintain these units effectively. The Global BOD Incubator Market encounters adoption resistance in such environments, where reliability concerns emerge due to improper handling or calibration errors. It also faces service-related challenges, especially in rural or remote areas where timely technical assistance is unavailable. Building support networks and investing in user training will be essential to overcome this operational barrier.
Market Opportunities:
Expansion Potential in Untapped Emerging Markets
The growing need for effective water monitoring solutions in emerging economies presents a significant opportunity for manufacturers. Governments in regions such as Southeast Asia, Africa, and Latin America are investing in environmental infrastructure and pollution control programs. These initiatives are opening new avenues for the adoption of BOD incubators across municipal treatment facilities and industrial zones. The Global BOD Incubator Market can capitalize on this demand by offering cost-effective models tailored to the requirements of resource-limited settings. It can further strengthen market presence by collaborating with local distributors and regulatory bodies to increase awareness and accessibility. Strengthening public procurement frameworks and capacity-building programs will also support expansion in these regions.
Rising Demand for Portable and Field-Friendly Devices
There is growing interest in compact, lightweight BOD incubators suitable for field use, especially for remote environmental testing and mobile laboratories. Environmental researchers, NGOs, and emergency response units require portable solutions that offer reliable performance outside of controlled lab environments. The Global BOD Incubator Market is well-positioned to explore this niche by developing rugged, energy-efficient models that maintain accurate incubation conditions in varied settings. It can also explore opportunities in disaster response, water quality surveillance, and remote ecosystem studies. Product innovations focused on portability, battery operation, and wireless connectivity will further support growth in this specialized segment.
Market Segmentation Analysis:
The Global BOD Incubator Market is segmented
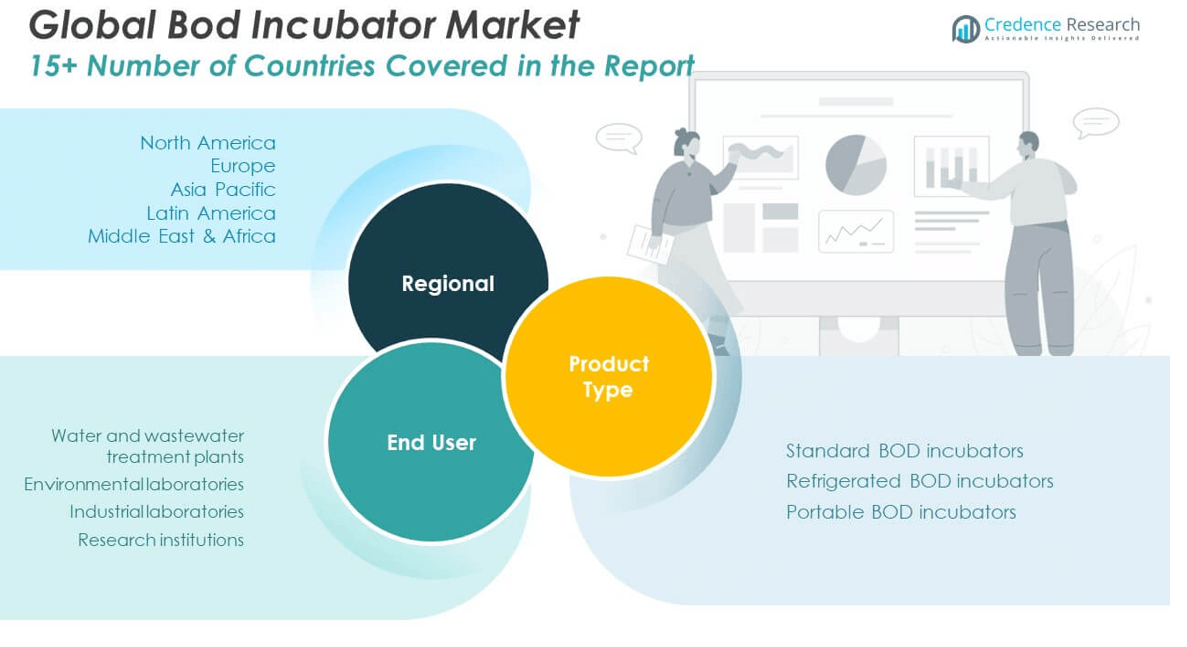
By product type into standard BOD incubators, refrigerated BOD incubators, and portable BOD incubators. Standard BOD incubators hold the largest share due to their widespread use in regulated laboratory environments and compatibility with basic water quality testing procedures. Refrigerated BOD incubators are gaining traction in advanced testing facilities where precise temperature control is essential, particularly in applications involving microbial growth and long-duration studies. Portable BOD incubators are emerging as a niche yet growing segment, driven by demand for mobile testing units and field-based environmental monitoring.
- For example, the SHEL LAB Low-Temperature BOD Incubator is widely used in regulated laboratory environments for standard BOD testing. It provides a temperature range from -10°C to 45°C, with temperature uniformity of ±0.5°C at 20°C, and accommodates up to 34 standard BOD bottles.
By end user, the market is categorized into water and wastewater treatment plants, environmental laboratories, industrial laboratories, and research institutions. Water and wastewater treatment plants represent the dominant end-user segment, driven by regulatory compliance requirements for effluent testing. Environmental laboratories also contribute significantly to demand, especially in government and private monitoring programs. Industrial laboratories use BOD incubators to evaluate process water and discharge standards, while research institutions rely on them for academic and environmental studies. The Global BOD Incubator Market reflects varied demand across segments, shaped by compliance needs, technological integration, and institutional capacity.
- For instance, BOD incubators are essential in wastewater treatment plants for regulatory effluent testing. For instance, facilities utilize standard and refrigerated BOD incubators to process large sample volumes, often analyzing hundreds of samples per week.
Segmentation:
By Product Type:
- Standard BOD Incubators
- Refrigerated BOD Incubators
- Portable BOD Incubators
By End User:
- Water and Wastewater Treatment Plants
- Environmental Laboratories
- Industrial Laboratories
- Research Institutions
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America BOD Incubator Market size was valued at USD 98.30 million in 2018 to USD 145.10 million in 2024 and is anticipated to reach USD 246.50 million by 2032, at a CAGR of 6.4% during the forecast period. North America holds the largest share of the Global BOD Incubator Market, accounting for nearly 45% of the total market value. The region’s dominance is driven by stringent environmental regulations, advanced infrastructure, and high adoption of laboratory automation across wastewater treatment and research institutions. The United States remains the core revenue generator due to EPA mandates and consistent investment in environmental monitoring technologies. Demand is reinforced by a strong presence of accredited testing laboratories, government-funded research centers, and industrial facilities required to meet discharge standards. The market continues to expand with innovations in smart incubators and increasing preference for energy-efficient models. It is supported by robust supply chains, skilled workforce, and public-private environmental initiatives.
Europe
The Europe BOD Incubator Market size was valued at USD 67.75 million in 2018 to USD 97.52 million in 2024 and is anticipated to reach USD 155.68 million by 2032, at a CAGR of 5.6% during the forecast period. Europe captures approximately 30% share of the Global BOD Incubator Market, reflecting high environmental compliance requirements and advanced laboratory standards. Countries such as Germany, France, and the U.K. are major contributors due to their industrial activity and adherence to EU environmental directives. The market benefits from well-funded research institutions and frequent product upgrades that align with strict performance and energy-use standards. Demand is further supported by public sector testing laboratories and university-based water quality research programs. Growing investments in smart cities and wastewater recycling projects are creating new applications for BOD incubators. It continues to evolve as manufacturers focus on customization and integration with digital platforms.
Asia Pacific
The Asia Pacific BOD Incubator Market size was valued at USD 46.61 million in 2018 to USD 75.21 million in 2024 and is anticipated to reach USD 143.81 million by 2032, at a CAGR of 8.0% during the forecast period. Asia Pacific holds a 20% share of the Global BOD Incubator Market and is the fastest-growing regional segment. Countries such as China, India, and Japan are witnessing increased demand due to rapid industrialization, urban expansion, and growing environmental awareness. Government-led investments in wastewater treatment infrastructure and sustainable development programs are fueling adoption. The region's expanding network of testing laboratories, academic institutions, and industrial clusters is driving uptake of automated and energy-efficient incubators. Rising public concern over pollution and stricter compliance norms are accelerating product deployment. It is emerging as a strategic region for global manufacturers seeking high-growth opportunities.
Latin America
The Latin America BOD Incubator Market size was valued at USD 11.33 million in 2018 to USD 16.71 million in 2024 and is anticipated to reach USD 25.12 million by 2032, at a CAGR of 4.8% during the forecast period. Latin America accounts for nearly 6% of the Global BOD Incubator Market, with Brazil and Mexico leading in terms of revenue and unit installations. Growing environmental oversight, urban water infrastructure projects, and industrial development are creating steady demand. The market is supported by increasing investments in environmental monitoring and laboratory modernization programs. However, limited public funding and technical training gaps remain barriers in certain areas. International collaborations and grants are helping to strengthen regional testing capabilities. It is projected to grow steadily as regulatory frameworks and compliance enforcement improve.
Middle East
The Middle East BOD Incubator Market size was valued at USD 6.43 million in 2018 to USD 8.74 million in 2024 and is anticipated to reach USD 12.44 million by 2032, at a CAGR of 4.0% during the forecast period. The region represents around 4% of the Global BOD Incubator Market and shows moderate but consistent growth. Gulf countries such as the UAE and Saudi Arabia are investing in environmental testing as part of broader water sustainability and smart city strategies. Water scarcity issues are pushing governments to enhance wastewater treatment and recycling infrastructure. The market is expanding across public utilities, environmental agencies, and industrial parks. Challenges include reliance on imported equipment and limited domestic manufacturing capacity. It offers growth potential as environmental awareness rises and private laboratories increase procurement.
Africa
The Africa BOD Incubator Market size was valued at USD 4.56 million in 2018 to USD 7.37 million in 2024 and is anticipated to reach USD 10.41 million by 2032, at a CAGR of 3.9% during the forecast period. Africa holds just under 3% share of the Global BOD Incubator Market, with demand concentrated in countries such as South Africa, Egypt, and Kenya. Adoption is being driven by rising focus on water sanitation, environmental conservation, and public health. Several international organizations and government agencies are supporting infrastructure development and laboratory upgrades across the region. Despite growth opportunities, budget constraints, lack of technical expertise, and limited supplier networks hinder broader adoption. The market is slowly expanding as awareness of water quality testing grows among municipalities and environmental regulators. It is expected to progress gradually with support from international aid and capacity-building initiatives.
Key Player Analysis:
- Thermo Fisher Scientific
- Panasonic Biomedical
- Binder GmbH
- Memmert GmbH + Co. KG
- Sheldon Manufacturing, Inc.
- JEIO Tech Co., Ltd.
- Eppendorf AG
- REMI Elektrotechnik Limited
- Ohmkar Equipments
- HAMCO
Competitive Analysis:
The Global BOD Incubator Market is moderately consolidated, with a mix of established players and regional manufacturers competing on product quality, technology integration, and pricing. Key companies focus on offering energy-efficient, compact, and digitally controlled incubators to meet rising demand across environmental, industrial, and academic sectors. It is witnessing increased competition from emerging players in Asia-Pacific who offer cost-effective solutions tailored to budget-sensitive markets. Leading companies are investing in R&D to enhance precision, automation, and IoT compatibility in their product lines. Strategic partnerships, product launches, and distributor expansions are common approaches to strengthen market presence. The Global BOD Incubator Market is also experiencing competitive pressure from manufacturers offering multifunctional laboratory equipment with incubation capabilities. It remains driven by innovation, brand reliability, and compliance with global laboratory standards.
Recent Developments:
- In June 2024, Thermo Fisher Scientific introduced the Heracell VIOS 250i AxD CO₂ Incubators, designed for integration into automated and modular laboratories. This launch is confirmed by multiple reputable industry news outlets and official press releases.
Market Concentration & Characteristics:
The Global BOD Incubator Market exhibits moderate market concentration, with a core group of international players dominating global sales, while regional manufacturers cater to localized demand. It is characterized by a steady pace of innovation, a strong focus on regulatory compliance, and growing demand for digital, energy-efficient, and user-friendly systems. The market caters to diverse end users including wastewater treatment facilities, research institutions, and environmental monitoring agencies. Product differentiation often revolves around automation, temperature uniformity, capacity range, and integrated data management. It reflects a balance between premium-quality units from established brands and affordable alternatives from emerging suppliers. Market dynamics vary across regions based on infrastructure maturity, environmental enforcement, and budget availability.
Report Coverage:
The research report offers an in-depth analysis based on Product Type and End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand will rise due to increasing global focus on wastewater quality and environmental sustainability.
- Smart incubators with IoT connectivity and remote monitoring will gain wider adoption in modern laboratories.
- Asia Pacific will become a primary growth engine, supported by rapid industrialization and infrastructure investment.
- Product innovation will focus on compact, energy-efficient, and user-friendly designs to meet evolving user needs.
- Government-led environmental programs will drive procurement across public utilities and research institutions.
- Academic and research funding will support uptake in universities and environmental science departments.
- Growing awareness of waterborne diseases will increase BOD testing in public health applications.
- Manufacturers will expand global footprint through partnerships, local assembly, and regional distribution networks.
- Portable and field-deployable incubators will see growing demand from mobile testing units and NGOs.
- Compliance with global laboratory standards will remain critical for product acceptance and market expansion.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Environmental Regulations and Policy Compliance
Increasingly strict discharge standards from agencies like the EPA and EEA require industries to regularly monitor biochemical oxygen demand in wastewater, directly driving the adoption of BOD incubators for compliance and reporting.
Rising Industrialization and Wastewater Generation
Rapid industrial growth, especially in Asia Pacific and Latin America, is leading to higher volumes of industrial wastewater, necessitating reliable BOD testing equipment to ensure effective treatment and regulatory adherence.
Technological Advancements and Automation
Modern BOD incubators now feature digital controls, data logging, and remote monitoring, which improve accuracy, reduce manual labor, and support automated laboratory workflows, making them more attractive to both industrial and research users.
Growing Focus on Sustainable Water Management
Global emphasis on sustainability and water resource management is prompting both public and private sectors to invest in advanced BOD incubators for continuous water quality monitoring and eco-friendly operations.
Expansion of Research and Academic Funding
Increased funding for environmental science, water management, and microbiological research is boosting demand for BOD incubators in universities and research institutions, especially in developing regions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global BOD Incubator Market?
What are the key segments within the Global BOD Incubator Market?
What are some challenges faced by the Global BOD Incubator Market?
Who are the major players in the Global BOD Incubator Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Water and Wastewater Treatment Plants
- 1.2.2 Environmental Laboratories
- 1.2.3 Industrial Laboratories
- 1.2.4 Research Institutions
- 1.3 By Product Type
- 1.3.1 Standard BOD Incubators
- 1.3.2 Refrigerated BOD Incubators
- 1.3.3 Portable BOD Incubators
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 350.65 million → 2032: USD 593.95 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global BOD Incubator Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global BOD Incubator Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global BOD Incubator Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global BOD Incubator Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global BOD Incubator Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global BOD Incubator Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global BOD Incubator Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global BOD Incubator Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 350.65 million → 2032: USD 593.95 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global BOD Incubator Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Water and Wastewater Treatment Plants
- 12.3.7.2 Environmental Laboratories
- 12.3.7.3 Industrial Laboratories
- 12.3.7.4 Research Institutions
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Standard BOD Incubators
- 12.4.7.2 Refrigerated BOD Incubators
- 12.4.7.3 Portable BOD Incubators
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global BOD Incubator End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global BOD Incubator Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global BOD Incubator Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global BOD Incubator Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Thermo Fisher Scientific
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Panasonic Biomedical
- 18.4 Binder GmbH
- 18.5 Memmert GmbH + Co. KG
- 18.6 Sheldon Manufacturing, Inc.
- 18.7 JEIO Tech Co., Ltd.
- 18.8 Eppendorf AG
- 18.9 REMI Elektrotechnik Limited
- 18.10 Ohmkar Equipments
- 18.11 HAMCO
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

